
 Flour Substitutes Market | 2026-2036
Flour Substitutes Market Size, Share, and Industry Trends Forecast 2026-2036
Flour Substitutes Market Foresight
Non-GMO Project verification is collapsing as a baseline qualification for retail shelf placement in North American flour substitutes, forcing suppliers to pursue additional certifications. ADM leverages its integrated oilseed processing network to secure consistent almond and coconut flour supply chains. Cargill competes through specialty starch blending capabilities that improve the functional performance of gluten-free formulations. Bunge anchors its position in South American cassava flour through direct farmer partnerships and regional milling infrastructure.
Flour substitutes encompass milled products derived from non-cereal sources such as nuts, legumes, tubers, and pseudocereals, typically processed to particle sizes between 80 and 200 microns and formulated to replicate the protein-starch matrix of wheat flour in baked applications. Almond flour retains higher fat content and requires modified hydration ratios, while chickpea flour delivers superior protein binding for vegan applications. Gluten-free baking commands the largest volume share among applications, though diabetic food products represent the fastest-expanding margin pool as glycemic indexing becomes standard formulation practice. Stand-up pouches dominate retail packaging due to oxygen barrier properties that extend shelf stability of high-lipid flours.
FDA gluten-free labeling rules and USDA organic certification requirements shape product formulation and marketing claims in the United States, while EU Regulation 1169/2011 mandates allergen disclosure that affects nut-based flour distribution across European markets. EFSA novel food assessments create entry barriers for emerging tuber and legume varieties not historically consumed in Europe. Stakeholders must monitor evolving glycemic index classification standards and their impending incorporation into front-of-pack labeling schemes.
Market Dynamics
The EU Green Deal's farm-to-fork sustainability targets are forcing raw material sourcing reconfigurations across alternative flour supply chains, compressing supplier margins while accelerating ingredient substitution rates in commercial baking.
Growth Catalysts
- Gluten-free labeling mandates:FDA gluten-free rules in the United States compel reformulation across commercial food manufacturing, expanding addressable volume for certified alternative flour suppliers.
- Diabetic food formulation standards:Glycemic indexing is becoming standard practice in bakery applications, pulling demand toward low-carb almond and coconut flour variants.
- Germany's dietary pivot:European consumers in Germany are shifting toward allergen-free diets, concentrating regional demand for nut-based and legume flour substitutes.
Market Restraints
- Input cost volatility:Almond flour production faces almond price swings tied to California water allocation cycles and pollinator colony collapse pressures.
- Supply concentration risk:Cassava flour sourcing clusters in Brazilian and Thai processing infrastructure, exposing buyers to regional weather disruptions and port congestion.
- Novel food entry barriers:EFSA novel food assessments block European distribution of emerging tuber and legume varieties without historical consumption records.
Strategic Opportunities
- Underpenetrated diabetic segments:Glycemic-indexed bakery products in France and Italy remain below saturation, creating white space for chickpea and lupin flour formulations.
- Sustainability-linked procurement:EU Green Deal carbon accounting requirements favor suppliers with verified regenerative agriculture partnerships in almond and coconut cultivation.
- Direct-to-bakery channels:Artisan and industrial bakeries are bypassing traditional distributors for bulk flour substitute contracts with regional millers.
Industry Challenges
- Formulation skill scarcity:Gluten-free baking requires modified hydration ratios and protein-starch matrix engineering that conventional milling technicians rarely possess.
- Certification timeline compression:Non-GMO Project verification collapse as a baseline qualification forces simultaneous pursuit of organic, regenerative, and carbon-neutral certifications.
- Legacy equipment incompatibility:High-lipid almond flour causes caking and flow issues in wheat-calibrated pneumatic conveying systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flour Substitutes Market |
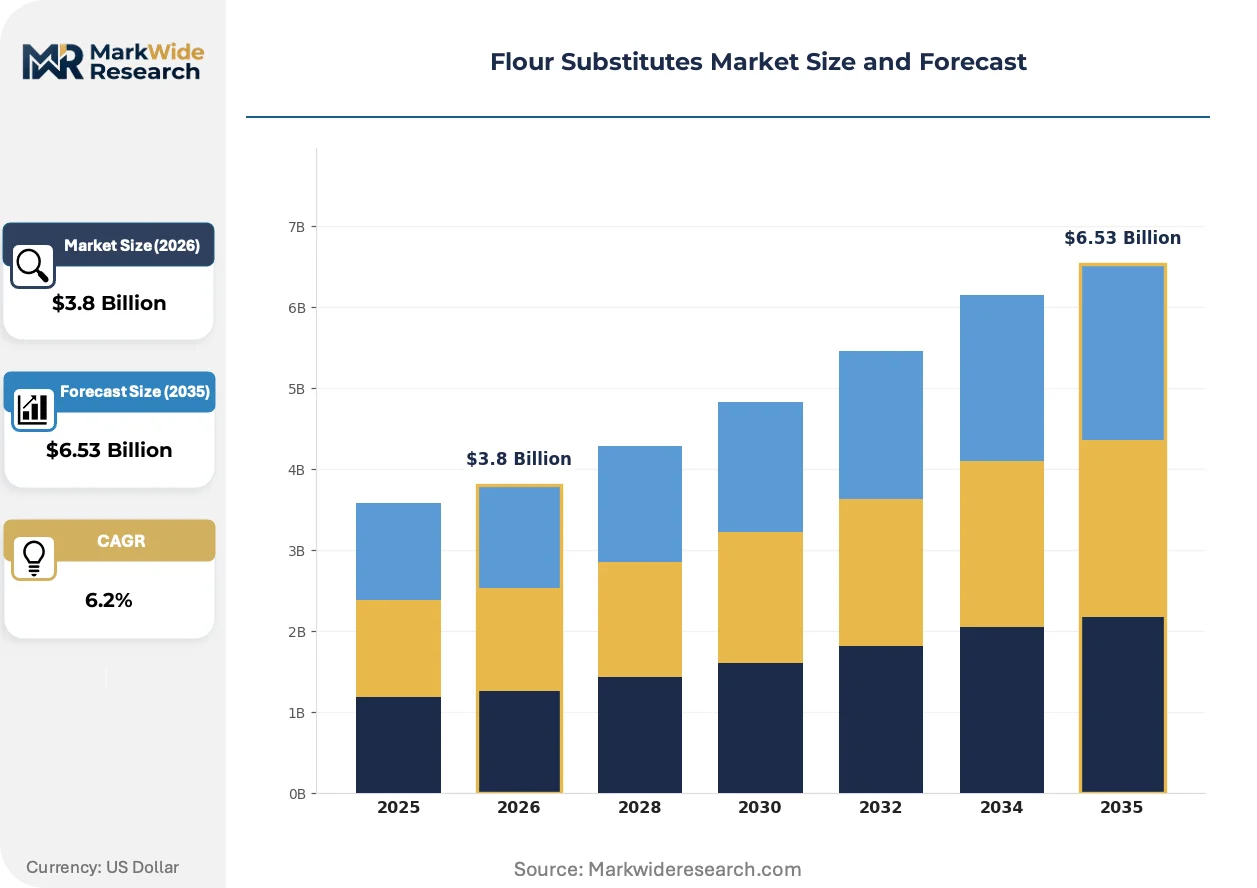
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.53 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
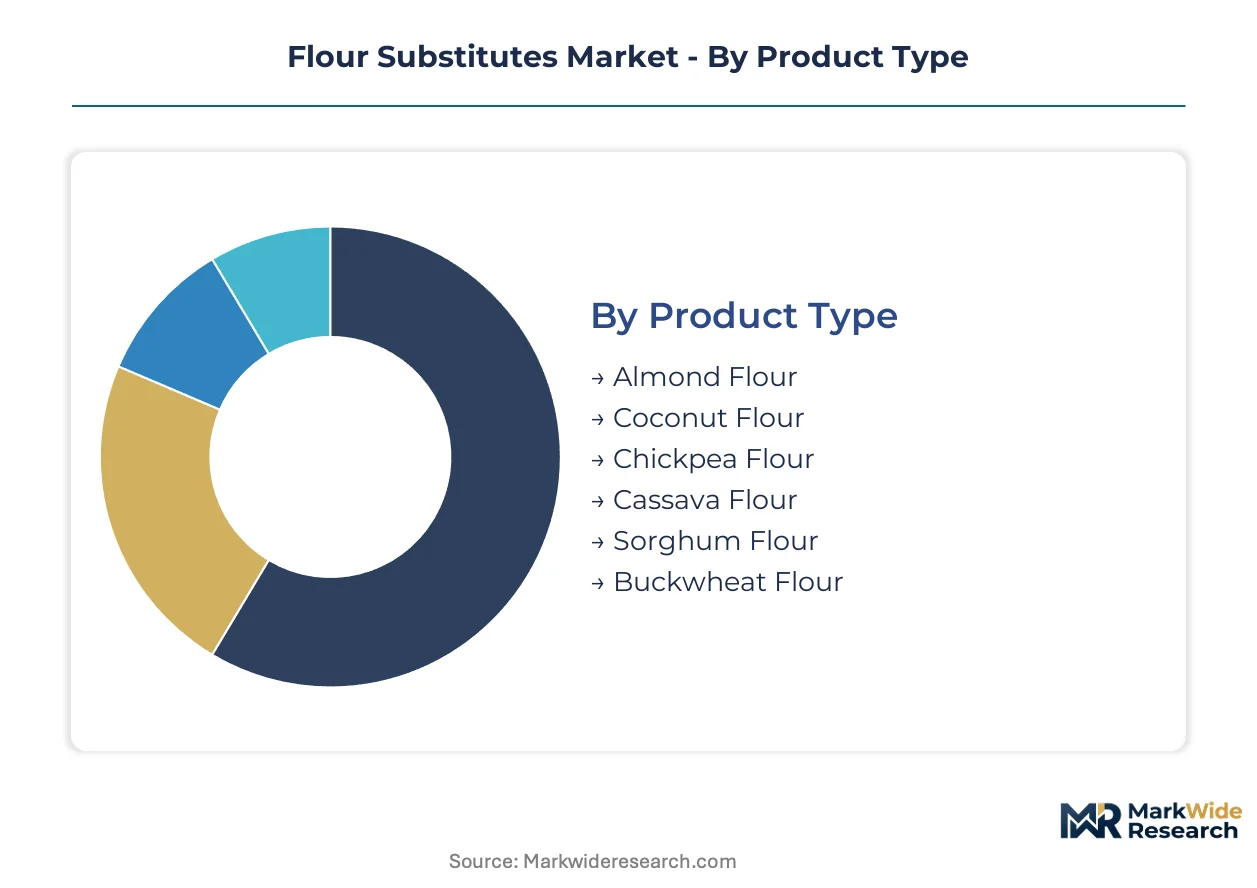
| Segmentation | Product Type: Almond Flour, Coconut Flour, Chickpea Flour, Cassava Flour, Sorghum Flour, Buckwheat Flour Application: Gluten-Free Baking, Vegan Cooking, Low-Carb Diets, Paleo Recipes, Diabetic Food Products, Snacks Production Packaging Type: Stand-Up Pouches, Resealable Bags, Bulk Packaging, Paper Bags, Plastic Containers, Box Packs End User: Retail Consumers, Food Service Providers, Health Food Stores, Specialty Bakeries, Online Retailers, Nutritionists |
| Companies Covered | ADM, Cargill, Bunge, Louis Dreyfus, COFCO Group, Wilmar International, Jinshahe Group, GoodMills Group, Carolina Innovative Food Ingredients, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flour Substitutes Market Shifts & Advancements
Particle size engineering and oxygen barrier packaging are converging to extend shelf stability of high-fat flours, while regulatory front-of-pack labeling schemes accelerate formulation transparency requirements.
Precision milling technology is miniaturizing. Advanced impact milling systems now achieve 80-200 micron particle distributions previously requiring industrial-scale ball mills. Mid-size specialty flour producers in the Netherlands and Spain are adopting these compact units to serve regional bakery co-operatives. This equipment downsizing is miniaturizing minimum viable production scale, enabling fragmented supply bases to challenge integrated oilseed processors on freshness and customization.
REACH chemical safety registrations are tightening contaminant thresholds for imported nut flours entering European markets. The European Chemicals Agency is expanding residue testing protocols to cover mycotoxin and pesticide carryover from non-EU cultivation zones. Almond and coconut flour imports from South Asian and Latin American origins face extended customs clearance timelines, pushing importers toward pre-certified supplier networks.
Buyer consolidation among contract bakery manufacturers is compressing supplier qualification cycles. Large commercial baking groups in Germany and Poland now demand simultaneous organic certification, carbon footprint disclosure, and allergen-free facility audits before contract award. Smaller regional millers are responding by forming certification consortiums to spread compliance costs across multiple alternative flour product lines.
Flour Substitutes Market Segmentation
Flour substitutes require precise technical matching between ingredient functionality and end-use specifications. Regulatory frameworks governing allergen disclosure and glycemic indexing create divergent compliance burdens across segment combinations.
Product Type:
FDA gluten-free labeling rules and EU Regulation 1169/2011 impose distinct formulation constraints on nut-derived versus tuber-derived alternatives, reshaping supplier certification priorities.
- Almond Flour:Milled blanched almonds retain 50-60% fat content and particle sizes of 80-120 microns, demanding modified hydration ratios in commercial baking. Demand concentrates in German retail channels where low-carb diet adherence is accelerating, though California water allocation cycles create input cost volatility that compresses margins.
- Coconut Flour:Defatted coconut meat yields high-fiber, low-carbohydrate flour with exceptional liquid absorption capacity requiring recipe reformulation. Specialty bakeries in Poland and the Netherlands are standardizing this ingredient for glycemic-indexed products, pulled by diabetic food formulation standards.
- Chickpea Flour:Ground desi or kabuli chickpeas deliver 20-25% protein binding superior to cereal alternatives for vegan applications. Food service providers in France are adopting this for allergen-free menu engineering.
- Cassava Flour:Finely milled Manihot esculenta tuber provides neutral flavor and tapioca-like starch behavior. Brazilian and Thai processing infrastructure concentrates supply, exposing buyers to regional weather disruptions.
- Sorghum Flour:Milled Sorghum bicolor grain offers gluten-free functionality with slower starch gelatinization. Health food stores in Spain are expanding shelf placement for ancient grain positioning.
- Buckwheat Flour:Ground Fagopyrum esculentum pseudocereal delivers complete protein and rutin antioxidant content. Paleo recipe developers favor this for its non-grain botanical classification.
Established volume favors almond flour; emerging adoption favors chickpea flour.
Application:
Commercial food manufacturing commands bulk procurement scale while artisan channels prioritize customization flexibility, fragmenting supplier qualification requirements.
- Gluten-Free Baking:Reformulated bread, pastry, and confectionery applications requiring protein-starch matrix engineering to replicate wheat gluten networks. Commercial bakery groups in Germany now demand simultaneous organic certification and allergen-free facility audits, compressing supplier timelines.
- Vegan Cooking:Plant-based formulations leveraging legume and nut flours for binding, structure, and protein fortification. Chickpea flour dominates this segment in Netherlands food service channels where binding performance is critical.
- Low-Carb Diets:Ketogenic and reduced-carbohydrate lifestyle products emphasizing net carbohydrate minimization. Almond and coconut flour variants are gaining share fastest in Italian retail as glycemic indexing becomes standard practice.
- Paleo Recipes:Grain-free formulations mimicking pre-agricultural dietary patterns. Buckwheat and cassava flour feature prominently despite botanical technicalities around pseudocereal classification.
- Diabetic Food Products:Glycemic-indexed bakery items formulated for blood glucose management. France and Italy remain below saturation, creating white space for chickpea and lupin flour formulations.
- Snacks Production:Extruded and baked savory applications including crackers, chips, and crisp formulations. Snack manufacturers in Poland are bypassing traditional distributors for bulk contracts with regional millers.
Gluten-free baking anchors procurement volume; diabetic food products show the steepest expansion trajectory.
Packaging Type:
Oxygen barrier properties determine shelf stability for high-lipid flours, while bulk formats serve contract manufacturing scale economies.
- Stand-Up Pouches:Multi-layer laminated structures with metallized or EVOH barrier layers extending shelf life of almond and coconut flours. Retail consumers in Germany favor this format for pantry storage convenience and resealability.
- Resealable Bags:Zipper-equipped polyethylene or polypropylene constructions for repeated access. Health food stores specify this for premium positioning of specialty flours.
- Bulk Packaging:Super sacks and fiber drums serving industrial bakery and contract manufacturing procurement. Direct-to-bakery channels favor this for cost efficiency.
- Paper Bags:Kraft multi-wall constructions with polyethylene liners for moderate barrier protection. Sustainability-linked procurement under EU Green Deal carbon accounting favors this format.
- Plastic Containers:Rigid PET or HDPE canisters with desiccant inserts for maximum moisture protection. Online retailers specify this for shipping durability.
- Box Packs:Corrugated enclosures with inner bag-in-box configurations for food service distribution. Specialty bakeries in Spain prefer this for kitchen organization.
Stand-up pouches dominate retail velocity; bulk packaging commands manufacturing procurement.
End User:
Channel consolidation among contract bakery manufacturers is compressing supplier qualification cycles while fragmenting regional demand.
- Retail Consumers:Individual households purchasing through supermarkets, hypermarkets, and natural food stores. German consumers shifting toward allergen-free diets are concentrating regional demand for nut-based substitutes.
- Food Service Providers:Restaurants, cafes, and institutional catering operations reformulating menus for dietary accommodation. Vegan cooking applications in Netherlands food service are standardizing chickpea flour procurement.
- Health Food Stores:Specialty retailers curating organic, non-GMO, and functional ingredient assortments. Certification consortiums among smaller regional millers are spreading compliance costs across product lines.
- Specialty Bakeries:Artisan and industrial operations producing gluten-free, diabetic-friendly, or allergen-free baked goods. Precision milling technology miniaturization is enabling fragmented supply bases to challenge integrated processors.
- Online Retailers:E-commerce platforms and direct-to-consumer subscription services. Oxygen barrier packaging specifications are critical for last-mile delivery integrity.
- Nutritionists:Dietary professionals recommending specific flour substitutes for clinical or wellness protocols. Glycemic index classification standards are impending incorporation into front-of-pack labeling schemes they monitor.
Food service providers drive formulation standardization; specialty bakeries demand customization flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal farm-to-fork targets are redirecting raw material flows toward regenerative agriculture partnerships in almond and coconut cultivation zones. National allergen disclosure mandates are reshaping distribution pathways for nut-based substitutes across major consumption markets.
United States
California's drought-driven water allocation cycles are compressing almond flour margins while FDA gluten-free labeling rules compel commercial bakery reformulation. The state's Central Valley processing clusters now prioritize integrated oilseed networks over spot-market sourcing. Los Angeles and San Francisco Bay Area food manufacturers are bypassing traditional distributors for direct regional miller contracts.
Germany
Low-carb and allergen-free dietary shifts are concentrating European demand for nut-based flour substitutes in German retail channels. EU Regulation 1169/2011 mandates strict allergen disclosure that affects nut flour labeling and shelf placement protocols. Berlin and Munich specialty bakeries are standardizing chickpea and lupin flour procurement for glycemic-indexed product lines.
Brazil
Cassava flour processing infrastructure clusters in São Paulo state and Minas Gerais, exposing buyers to regional weather disruption risks. Direct farmer partnerships are emerging as the dominant supply security mechanism for South American tuber-derived alternatives. Port congestion at Santos is extending lead times for European-bound shipments.
France
Diabetic food products remain below saturation, creating formulation white space for chickpea and lupin flour variants in glycemic-indexed bakery applications. EFSA novel food assessments block distribution of emerging tuber varieties without historical European consumption records. Lyon and Paris industrial baking groups now demand simultaneous organic certification and carbon footprint disclosure before contract award.
Netherlands
Specialty bakeries and food service providers are adopting coconut flour for glycemic-indexed products, pulled by diabetic formulation standards. Precision milling technology miniaturization is enabling fragmented regional millers to challenge integrated processors on freshness. Rotterdam logistics hubs are prioritizing pre-certified supplier networks to navigate REACH chemical safety registration delays for imported nut flours.
Flour Substitutes Market Competitive Landscape
Player mix skews toward integrated agricultural conglomerates with captive oilseed processing networks and regional specialty millers with certification consortium arrangements. The competitive structure splits between scale-driven commodity processors controlling upstream supply and agile mid-size operators exploiting equipment downsizing trends. Three archetypes dominate: diversified agribusiness giants with global sourcing infrastructure, regional miller cooperatives pooling compliance costs, and niche ingredient blenders focused on functional performance engineering. Dominant competitive moves include backward integration into farmer partnerships and geographic expansion through pre-certified supplier network establishment.
Among integrated agribusiness operators, ADM leverages its North American oilseed processing footprint while Cargill competes through specialty starch blending capabilities. Bunge anchors South American cassava flour positioning through Brazilian infrastructure. These three exemplify the scale-driven archetype where upstream supply control and multi-regional milling assets create defensive positioning against input cost volatility and certification timeline compression.
| Leading Market Players |
|---|
| ADM |
| Cargill |
| Bunge |
| Louis Dreyfus |
| COFCO Group |
| Wilmar International |
| Jinshahe Group |
| GoodMills Group |
| Carolina Innovative Food Ingredients |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts with Brazilian cassava processors and California almond cooperatives lock in supply access while providing price visibility against water allocation volatility and pollinator colony collapse pressures. These structures compress spot-market exposure for industrial bakery buyers while transferring agricultural risk upstream to growers.
Pricing Analysis
Certification level (USDA organic, Non-GMO Project, EU organic) creates the primary spread between premium and standard tiers, with regenerative agriculture verification commanding additional margin. Pricing stratifies across organic-certified, conventional allergen-free, and bulk commodity tiers, with almond flour facing cost compression from California drought-driven input volatility. Industrial bakery groups exhibit highest price sensitivity due to volume scale and contract concentration, while specialty health food stores accept premium positioning for multi-certification assortments.
Supply Chain Analysis
Brazil and Thailand anchor global cassava flour processing, while the United States and Spain concentrate almond and specialty milling infrastructure respectively. Raw material flows draw from California almond orchards, Brazilian Manihot esculenta cultivation zones, and South Asian coconut copra processing. Single-source vulnerability runs through Santos port congestion and Central Valley water allocation cycles. Distribution runs through integrated oilseed processors for bulk manufacturing and regional miller cooperatives for artisan bakery channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires substitution defense against emerging precision-fermented protein flours and cellular agriculture-derived binding agents that threaten nut and legume flour positioning in vegan applications.
For Market Incumbents: Compound certification advantages by stacking organic, regenerative, and carbon-neutral credentials before EU Green Deal carbon accounting mandates harden entry barriers. Deepen upstream control over almond cultivation through direct farmer partnerships in California and Spain, insulating against water allocation volatility that threatens margin stability in core product lines.
For New Entrants and Emerging Players: Anchor in underpenetrated diabetic food segments across France and Italy where glycemic-indexed bakery products remain below saturation and incumbent certification burdens are lighter. Target chickpea and lupin flour formulations for this white space, leveraging food service channel bypass strategies that avoid consolidated retail slotting fee structures.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among regional miller cooperatives with certification consortium arrangements and direct-to-bakery contract structures. Acquisition targets should demonstrate validated regenerative agriculture partnerships and pre-certified EU import pathways, with EFSA novel food assessment timelines serving as the critical inflection signal for emerging tuber variety commercialization potential.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Farmer Partnerships | Secures almond and cassava supply against California water volatility and Brazilian weather disruption. |
| Certification Consortium Formation | Spreads EU organic and carbon footprint compliance costs across fragmented regional miller networks. |
| Precision Milling Technology Adoption | Enables mid-size Dutch and Spanish producers to challenge integrated processors on freshness customization. |
| Direct-to-Bakery Channel Expansion | Bypasses consolidated distributor structures that compress margins for industrial bakery contract manufacturers. |
| Regenerative Agriculture Verification | Aligns supplier positioning with EU Green Deal farm-to-fork carbon accounting requirements. |
Research Methodology
Desk research of FDA gluten-free labeling guidance documents, EFSA novel food assessment records, and EU Regulation 1169/2011 implementation reports preceded structured interviews with commercial bakery procurement directors, specialty flour miller operations managers, and food service menu development executives. Primary fieldwork combined with secondary validation through USDA organic certification databases, REACH chemical safety registration filings, and trade flow customs data. Bottom-up volume modeling triangulated against top-down value projections across ingredient category and application segment combinations.
Variance decomposition across product type, application, packaging format, and end-user channel dimensions shaped the analytical framework over the projection horizon. CAGRs derived from historical volume trajectories adjusted for regulatory catalyst timing and substitution elasticity parameters. Forecast inputs incorporated almond price volatility indices tied to California water allocation cycles and pollinator colony health metrics.
Decision-makers should treat outputs as directional under assumptions of sustained EU Green Deal implementation and stable FDA gluten-free enforcement; material deviation in regulatory timelines or agricultural input costs would warrant model refresh. Recalibration cycles align with material shifts in EFSA novel food assessment throughput and EU carbon border adjustment mechanism activation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
Asia-Pacific Meat Substitutes Market
Alternative Food Sources
Precision Fermentation Market
Alternative Food Sources
North America Fat Replacers Market
Alternative Food Sources
Spirulina Market
Alternative Food Sources
Africa Potato Protein Market
Alternative Food Sources
Africa Protein Market
Alternative Food Sources
Global Algae Market
Alternative Food Sources
Mushroom Protein Market
Alternative Food Sources
Quinoa Protein Market
Alternative Food Sources
Mock Meat Market
Alternative Food Sources
Edible Packaging Market
Alternative Food Sources
Asia-Pacific Fat Replacers Market
Alternative Food Sources
Vegan Ham Market
Alternative Food Sources
Mycoprotein Products Market
Alternative Food Sources
Middle East and Africa Edible Insects Market
Alternative Food Sources
Artificial Meat Market