
 Edible Oils and Fats Market | 2026-2036
Edible Oils and Fats Market Size, Share, and Industry Trends Forecast 2026-2036
Edible Oils and Fats Market Analysis
Capital-intensity divergence between integrated plantation processors and merchant refiners is redrawing competitive boundaries in edible oils. Wilmar International Limited leverages its crushing and refining network across origination hubs to sustain margin capture from seed to shelf. Cargill Incorporated competes through its global logistics infrastructure and risk-management platforms. Bunge Limited anchors its position in oilseed processing scale across the Americas and European port complexes.
Edible oils and fats comprise triglyceride-based lipid products refined for human consumption, typically characterized by smoke points above 160°C and fatty-acid profiles tailored to thermal stability or nutritional labeling requirements. The category serves food manufacturing, foodservice frying, and retail cooking applications where oxidation resistance and flavor neutrality determine formulation selection. Palm oil and sunflower oil command divergent margin structures, with palm oil volumes dominating industrial bakery and confectionery while olive oil occupies premium retail positioning in Mediterranean and North American markets. Vegetable-sourced segments lead volume throughput, though blended formulations are gaining traction as processors optimize cost-performance ratios for institutional buyers.
The EU Deforestation Regulation and FDA food-labeling requirements are tightening chain-of-custody documentation, forcing traders to restructure procurement systems or face market-access barriers. Indonesia's Ministry of Trade and Malaysia's Malaysian Sustainable Palm Oil certification framework are imposing parallel sustainability verification protocols on export-bound volumes. Stakeholders must monitor regulatory fragmentation between deforestation-linked trade restrictions and national biofuel blending mandates that compete for the same oil feedstocks.
Market Dynamics
The EU Deforestation Regulation is forcing commodity traders to reconstruct procurement networks, diverting capital toward traceability infrastructure and certified supply bases while compressing margins for non-compliant originators.
Growth Catalysts
- Malaysian Sustainable Palm Oil certification:Export-bound processors are accelerating compliance investments to secure preferential access into European food manufacturing channels. This creates tiered market access based on sustainability verification.
- Indonesia's biofuel blending mandates:Domestic diversion of palm oil feedstocks into B35 and B40 programs is tightening exportable surplus, elevating price premiums for compliant international volumes.
- Foodservice frying applications:Southeast Asian quick-service restaurant chains are expanding palm olein procurement for high-heat stability requirements in centralized kitchen operations.
Market Restraints
- El Niño-induced yield volatility:Indonesian and Malaysian fresh fruit bunch production faces recurring moisture stress cycles that disrupt crushing schedules and elevate raw material cost bases.
- EU Deforestation Regulation traceability costs:Smallholder-dominated supply bases in Kalimantan and Sumatra lack geolocation documentation infrastructure, excluding volumes from premium market access.
- High-oleic sunflower oil substitution:Ukrainian and Argentine seed oils are capturing reformulation interest in European bakery applications where oxidative stability requirements overlap with palm functionality.
Strategic Opportunities
- India's packaged food sector:Urban retail chains in Mumbai and Delhi are expanding private-label edible oil portfolios, creating demand for toll-refined, branded formulations with regional taste profiles.
- Cellular lipid fermentation:Precision fermentation platforms are converging with lipid modification biochemistry to produce customized triglyceride structures for confectionery fat replacement.
- China's national nutrition labeling standards:Trans-fat disclosure mandates are accelerating interest in interesterified palm-based alternatives for industrial baking applications.
Industry Challenges
- Geospatial certification timelines:Smallholder mapping and polygon verification under EU Deforestation Regulation protocols require 18-24 month implementation cycles that outpace contract renewal windows.
- Refinery reconfiguration capex:Interestification and fractionation capacity upgrades for specialty fat production demand capital commitments that strain mid-scale processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Edible Oils and Fats Market |
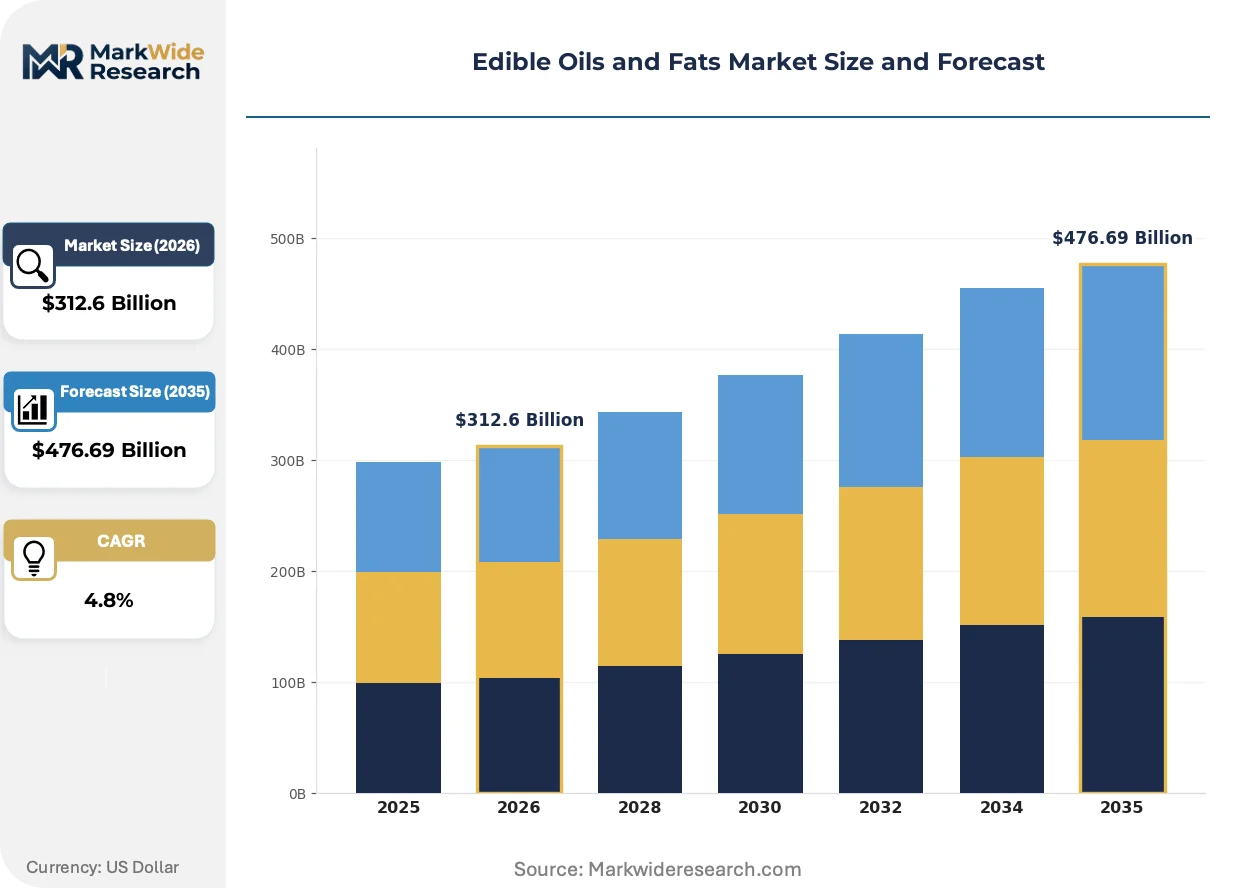
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $476.69 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cooking Oil, Olive Oil, Palm Oil, Sunflower Oil Source: Vegetable, Animal, Synthetic, Blended Packaging Type: Bottles, Tetra Packs, Cans, Pouches Distribution Channel: Supermarkets, Online Retailers, Grocery Stores, Wholesale |
| Companies Covered | Bunge Limited, United Plantations Berhad, Wilmar International Limited, Musim Mas Group, Fuji Oil Holdings Inc., Cargill Incorporated, Associated British Foods plc, IOI Corporation Berhad, Archer Daniels Midland Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Edible Oils and Fats Market Emerging Trajectories
Enzymatic interesterification is reconfiguring formulation economics across industrial bakery and confectionery, displacing traditional chemical processes while enabling cleaner-label positioning in premium retail channels.
Enzymatic interesterification employs lipase biocatalysts to redistribute fatty acids across triglyceride backbones without generating trans-isomers. European margarine manufacturers are adopting this technology at commercial scale for croissant and puff-pastry applications. This biocatalytic approach is supplanting sodium methoxide-based chemical interesterification in mid-premium product tiers where label simplicity commands retail price premiums.
The EU Deforestation Regulation mandates geolocation traceability to plantation level for all deforestation-risk commodities entering European markets. Food manufacturers must restructure supplier qualification systems to capture polygon coordinates and harvest dates. Palm-derived ingredient suppliers serving Unilever and Nestlé procurement networks are most affected, accelerating satellite-verification partnerships with Jakarta-based agritech platforms.
Centralized procurement consolidation is compressing supplier negotiation cycles across Southeast Asian food manufacturing. Indonesian instant noodle producers are consolidating palm olein purchasing through integrated trading desks, displacing fragmented spot-market buying. This concentration is most visible in Surabaya and Medan industrial zones where plantation-affiliated processors negotiate direct supply agreements with factory gate delivery terms.
Edible Oils and Fats Market Segmentation
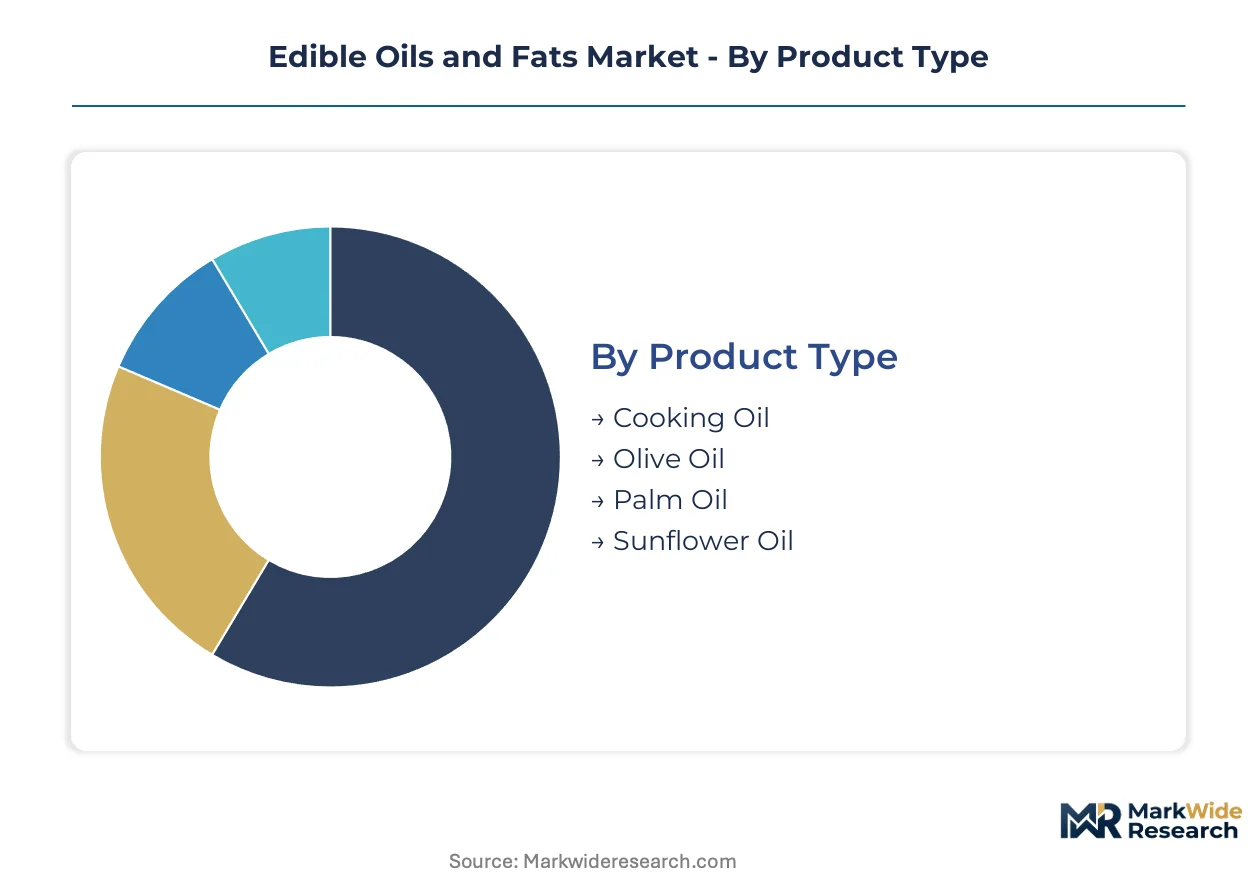
Segmentation in edible oils and fats reveals how formulation chemistry, sourcing provenance, and packaging economics intersect with channel access. Buyers sort across these dimensions based on thermal performance requirements, sustainability verification needs, and scale economics in institutional procurement.
Product Type:
Palm oil and olive oil command divergent channel strategies—commodity bulk flows through wholesale and food manufacturing, while premium retail positioning dominates olive oil shelf placement in European and North American supermarkets.
- Cooking Oil:Blended vegetable formulations optimized for smoke point stability above 200°C serve institutional frying operations across Southeast Asian foodservice chains. Demand concentrates in Indonesian quick-service restaurant central kitchens where high-heat stability requirements override cost minimization.
- Olive Oil:Monounsaturated fatty acid profiles exceeding 70% oleic acid content deliver oxidative stability for Mediterranean diet positioning. Italian and Spanish bottlers dominate premium retail channels in Germany and France where EFSA health claim authorizations support price premiums.
- Palm Oil:Fractionated palm olein and stearin serve industrial bakery and confectionery applications through B2B bulk delivery.
- Sunflower Oil:High-oleic variants from Ukrainian and Argentine crushing capture reformulation interest in European margarine production.
Palm oil dominates installed base by volume throughput. Olive oil is where expansion concentrates in premium retail margin capture.
Source:
Cost tier stratification separates commodity vegetable oils from synthetic lipid alternatives, with blended formulations occupying the mid-market optimization space for institutional buyers.
- Vegetable:Triglyceride structures from soybean, rapeseed, and palm mesocarp constitute the volume foundation. Malaysian and Indonesian plantation processors control upstream supply through integrated crushing and refining networks serving global food manufacturers.
- Animal:Tallow and lard fractions retain niche demand in traditional baking applications and pet food formulations where saturated fat functionality matches processing requirements.
- Synthetic:Interestified and hydrogenated fat alternatives face declining formulation share under trans-fat disclosure mandates.
- Blended:Custom fatty acid profiles combine palm olein with sunflower or canola oils to hit cost-performance targets for private-label retail programs.
Vegetable sourcing anchors supply security calculations for multinational procurement desks. Blended formulations are climbing the fastest as toll refiners optimize for regional taste preferences.
Packaging Type:
Volume scale and margin structure diverge sharply between commodity bulk and branded retail formats, with pouch economics disrupting traditional bottle penetration in emerging markets.
- Bottles:PET and glass containers dominate premium retail positioning in urban Indian and Chinese supermarkets where brand visibility commands shelf space allocation.
- Tetra Packs:Aseptic carton technology extends shelf life for olive and specialty oils in European retail channels.
- Cans:Metal packaging preserves oxidative stability for industrial bakery and frying oil deliveries.
- Pouches:Flexible laminate structures reduce unit economics for price-sensitive rural penetration in Indonesian and Nigerian markets.
Bottles retain installed base dominance in organized retail. Pouch formats are gaining share fastest through modern trade expansion in secondary cities.
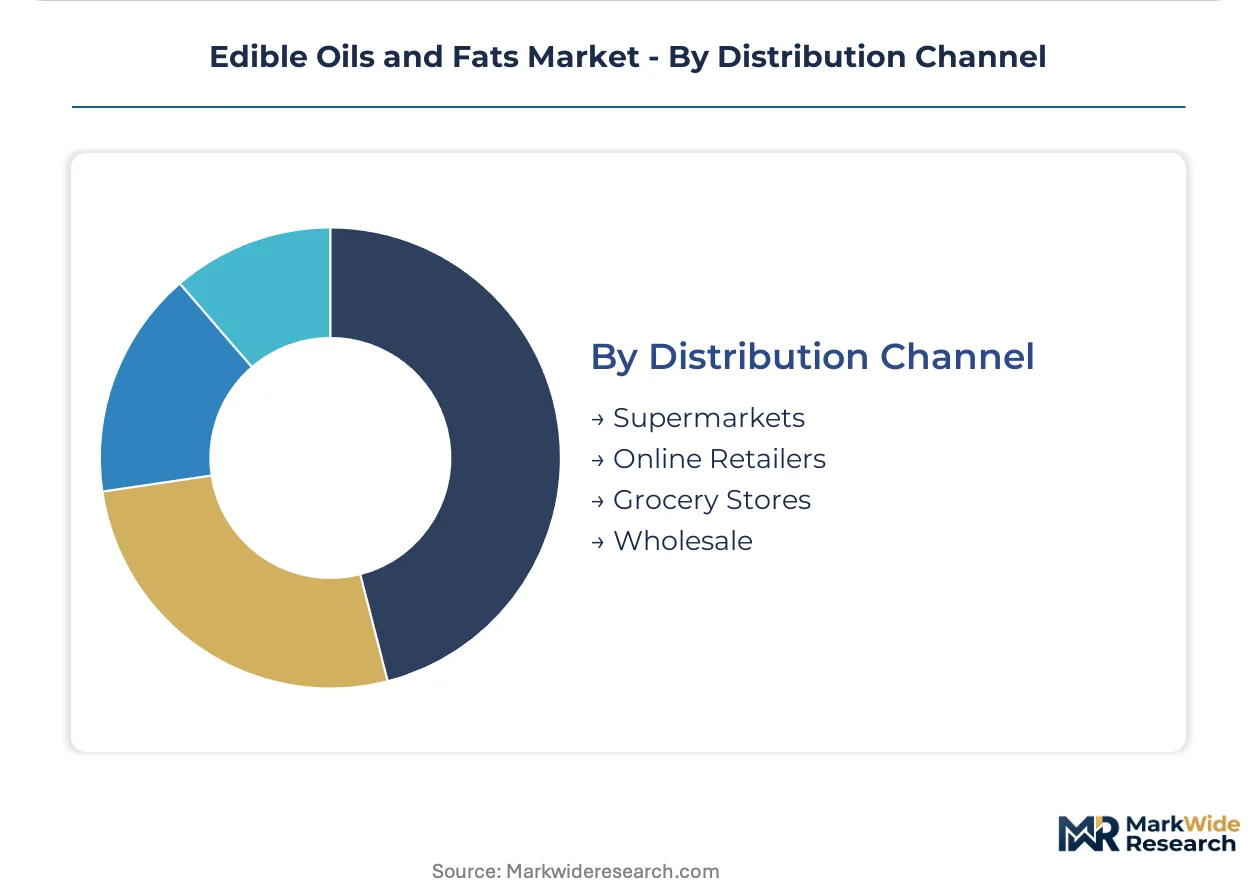
Distribution Channel:
Customer type and purchase frequency determine channel economics, with wholesale and grocery fragmentation yielding to supermarket consolidation and digital platform penetration.
- Supermarkets:Hypermarket and supermarket chains in São Paulo, Jakarta, and Mumbai consolidate edible oil procurement through centralized category management. Private-label programs capture volume through direct processor agreements that bypass traditional distributor margins.
- Online Retailers:E-commerce platforms in Chinese tier-1 cities and Indian metro markets aggregate niche and imported oil demand.
- Grocery Stores:Traditional trade fragmentation persists in African and South Asian markets where credit relationships and proximity determine purchase behavior.
- Wholesale:Institutional buyers in food manufacturing and foodservice negotiate direct supply agreements with plantation-gate processors.
Wholesale channels dominate volume throughput in industrial applications. Online retail represents the steepest expansion trajectory as urban consumers shift toward subscription-based replenishment models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across consuming regions. Indonesian and Nigerian buyers prioritize unit economics in flexible pouch formats. German and Japanese purchasers absorb premiums for traceability-certified and single-origin specialty oils.
Indonesia
Domestic biofuel blending mandates under B35 and B40 programs divert palm oil feedstocks from export channels. The Ministry of Trade enforces export licensing restrictions during peak harvest periods. Crushing and refining clusters in Medan and Surabaya industrial zones negotiate direct factory-gate supply agreements with instant noodle manufacturers.
Malaysia
Malaysian Sustainable Palm Oil certification unlocks preferential access to European food manufacturing procurement networks. The national certification framework mandates geolocation documentation for plantation-level traceability. Port Klang and Pasir Gudang processing complexes expand fractionation capacity for industrial bakery and confectionery exports.
India
Urban retail chains in Mumbai and Delhi expand private-label edible oil portfolios requiring toll-refined formulations. FSSAI trans-fat disclosure mandates accelerate interest in interesterified palm-based alternatives for industrial baking. Gujarat and Maharashtra refining clusters optimize for regional taste preferences in blended vegetable oil production.
Germany
EFSA health claim authorizations for olive oil support premium retail positioning in supermarket channels. The EU Deforestation Regulation forces restructuring of supplier qualification systems to capture polygon coordinates. Hamburg port complexes serve as distribution hubs for Mediterranean-origin specialty oils into Central European manufacturing.
China
National nutrition labeling standards mandate trans-fat disclosure for packaged food products. SAMR enforcement of dual carbon goals pressures processors toward cleaner production technologies. Yangtze River Delta refining clusters in Shanghai and Jiangsu provinces upgrade interesterification capacity for bakery fat replacement applications.
Edible Oils and Fats Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in edible oils and fats. Plantation-affiliated processors with captive crushing and refining networks command upstream margin capture. Merchant refiners lacking origination assets compete on toll-processing efficiency and formulation customization. Geographic expansion through direct supply agreements and certification compliance investments constitute the dominant competitive moves.
Within the integrated plantation processor archetype, Wilmar International Limited and IOI Corporation Berhad exemplify upstream-to-downstream control structures. Cargill Incorporated occupies a position among global merchant traders leveraging logistics infrastructure across multiple origination hubs. United Plantations Berhad represents the specialized plantation operator tier with concentrated Malaysian asset bases.
| Leading Market Players |
|---|
| Bunge Limited |
| United Plantations Berhad |
| Wilmar International Limited |
| Musim Mas Group |
| Fuji Oil Holdings Inc. |
| Cargill Incorporated |
| Associated British Foods plc |
| IOI Corporation Berhad |
| Archer Daniels Midland Company |
| Others |
Supply Flow & Price Mechanics
High-oleic sunflower oil substitution for palm fractions in European bakery reformulation simultaneously redraws sourcing geography toward Ukrainian and Argentine crushing corridors and compresses commodity palm olein price premiums. This displacement dynamic forces integrated plantation processors to defend margin capture through certification-tiered pricing rather than volume leverage alone.
Pricing Analysis
After-sales formulation services and technical support contracts drive lifetime value for industrial bakery and confectionery accounts more than upfront commodity premiums. Three-tier pricing structure across MSPO-certified premium, conventional standard, and spot-market economy levels segments buyer access based on geolocation documentation completeness. Pricing pressure stems from Indonesian biofuel blending mandates diverting exportable surplus and elevating raw material cost bases. Smallholder-dependent spot buyers in Kalimantan and Sumatra exhibit highest price sensitivity while European food manufacturers absorb certification premiums for deforestation-free supply security.
Supply Chain Analysis
Inventory cycles extending 18-24 months for EU Deforestation Regulation polygon verification create lead-time mismatches with annual contract renewal windows. Supply concentrates in Indonesia and Malaysia for upstream fresh fruit bunch production, with India and China anchoring downstream refining and formulation. Crude palm oil, palm kernel expeller, and specialty olein fractions constitute core input dependencies. Single-source vulnerability to El Niño-induced moisture stress in Southeast Asian plantation belts threatens crushing schedule continuity. Distribution runs through plantation-gate direct supply agreements with food manufacturers, bypassing traditional trader intermediaries in Surabaya and Medan industrial zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Edible oils and fats represent an early-cycle expansion story as cellular lipid fermentation and enzymatic interesterification open formulation frontiers beyond conventional triglyceride sourcing. India's packaged food sector penetration and China's trans-fat reformulation mandates provide dual tailwinds for technology-advantaged processors.
For Market Incumbents: Secure MSPO and EU Deforestation Regulation compliance infrastructure ahead of contract renewal cycles to lock in European food manufacturing procurement networks. Defend margin position through backward integration into plantation-gate crushing capacity in Kalimantan and Sumatra rather than merchant refining exposure. Cellular lipid fermentation platforms threaten long-term commodity volume assumptions, requiring R&D allocation toward biocatalytic fat modification capabilities. For New Entrants and Emerging Players: Anchor in India's toll-refining white space where urban retail chains seek private-label formulations with regional taste customization. Target Surabaya and Medan industrial corridors for direct factory-gate supply agreements displacing fragmented spot-market buying. Pursue enzymatic interesterification technology licensing as the go-to-market angle for cleaner-label positioning in premium European bakery channels. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed merchant refiners lacking origination infrastructure and facing margin compression from integrated plantation processors. Five-to-ten year viability hinges on certification compliance completion and specialty fat formulation capabilities rather than commodity throughput scale. Watch for EU Deforestation Regulation enforcement acceleration as the inflection signal separating compliant premium-tier access from excluded economy-tier volumes.| Strategic Initiative | Industry Significance |
|---|---|
| MSPO Certification Completion | Unlocks preferential European food manufacturing procurement access against non-compliant competitors. |
| Enzymatic Interesterification Scale-Up | Enables trans-fat-free bakery fat production under China's SAMR labeling mandates. |
| Plantation-Gate Crushing Expansion | Captures upstream margin in Medan and Surabaya industrial corridors for instant noodle supply. |
| Cellular Lipid Fermentation Partnership | Positions for confectionery fat replacement beyond conventional palm fraction limitations. |
| Direct Supply Agreement Consolidation | Displaces trader intermediaries through factory-gate delivery terms with Indonesian food manufacturers. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with plantation operations managers, edible oil procurement leads at multinational food manufacturers, toll-refining technical directors, and sustainability certification auditors. Secondary validation drew from Malaysian Palm Oil Board production statistics, Indonesian Ministry of Trade export licensing records, EU Deforestation Regulation implementation guidance, FAO oilseed trade databases, and SEC filings of listed plantation processors. Bottom-up volume modeling across crushing, refining, and formulation tiers triangulated against top-down market sizing from customs and trade flow data.
Across the analysis window, the forecasting framework modeled volume and value trajectories through segmentation by product type (cooking oil, olive oil, palm oil, sunflower oil), source origin (vegetable, animal, synthetic, blended), packaging format (bottles, pouches, cans, Tetra Packs), and distribution channel (supermarkets, online retail, grocery stores, wholesale). CAGRs were derived from regression analysis against biofuel blending mandate intensity, sustainability certification penetration rates, and foodservice frying application expansion. Industry-specific inputs included El Niño cycle probability distributions and EU Deforestation Regulation compliance timeline assumptions.
Material uncertainties — regulatory enforcement acceleration, biotechnology substitution curves, and plantation yield volatility — sit outside the modeled envelope and could revise trajectory assumptions substantially. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Virgin Coconut Oil Market
Ingredients
Mediterranean Marine Ingredients for Pet Health Market
Ingredients
Bouillon Cubes Market
Ingredients
Textured Milk Protein Market
Ingredients
Food Grade L-Arabinose Market
Ingredients
North America Phytosterols Market
Ingredients
Edible Animal Fat Market
Ingredients
Europe Sodium Reduction Ingredient Market
Ingredients
Global Fresh Compressed Yeast Market
Ingredients
Vegetable Fats Market
Ingredients
Glucose (Dextrose) Market
Ingredients
Agarwood Oil Market
Ingredients
United Kingdom Gelatin Market
Ingredients
Global Protein Hydrolysate Ingredients Market
Ingredients
United Kingdom Protein Market
Ingredients
Germany Gelatin Market