
 Europe Upcycled Food Products Market | 2026-2036
Europe Upcycled Food Products Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Upcycled Food Products Market Analytics
Precision fermentation and enzymatic recovery is fragmenting traditional ingredient supply chains across European food manufacturing. REMA 1000 leverages private-label upcycled snack lines to anchor shelf space in Nordic retail. Tesco competes through dedicated upcycled product bays in its largest UK superstores. Rebread specializes in spent-grain flour applications, positioning its bakery network as a closed-loop model for brewers.
Europe upcycled food products are edible goods manufactured from surplus, by-product, or cosmetically imperfect raw materials that would otherwise enter waste streams, typically processed through dehydration, milling, or fermentation to achieve food-grade safety and nutritional parity. These products serve industrial buyers seeking cost-stable ingredient inputs and consumers pursuing verifiable waste reduction in their purchasing. Snack Bars currently occupy the largest share of product type revenue, though Beverages demonstrate the fastest velocity as upcycled fruit pulp enters functional drink formulations. The Ingredients segment sustains the deepest margin pools, where B2B supply contracts lock in multi-year offtake agreements with food manufacturers.
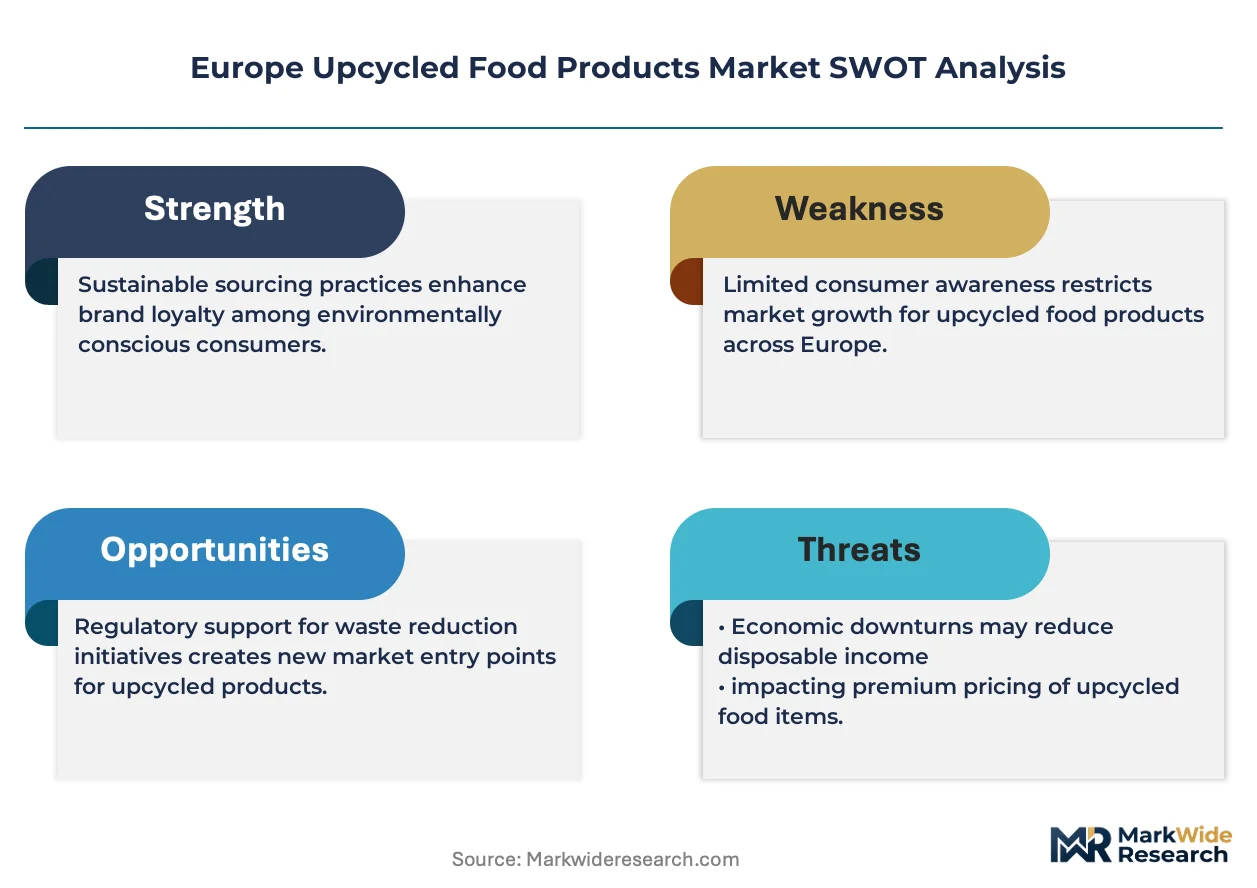
The EU Green Deal's food waste hierarchy, EFSA novel food guidance, and national extended producer responsibility schemes collectively shape formulation standards and market access across member states. REACH compliance requirements for upcycled ingredient traceability add certification costs that favor scaled operators over artisan entrants. Stakeholders must monitor how the EU AI Act's transparency mandates affect automated sorting technologies that classify food waste streams for human-grade recovery.
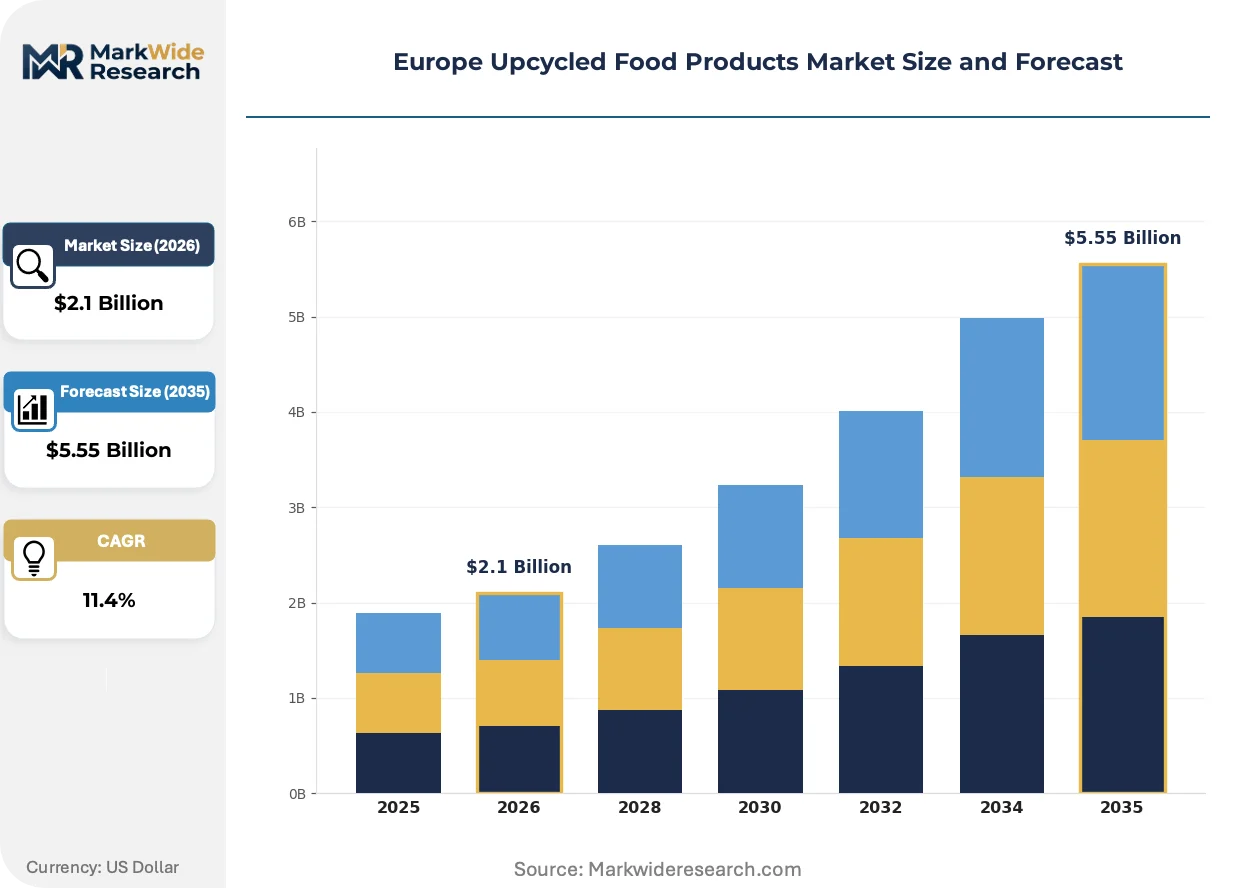
Market Dynamics
Precision fermentation and enzymatic recovery systems are fragmenting traditional ingredient supply chains across European food manufacturing, forcing processors to rebuild procurement relationships around waste-stream partnerships rather than commodity spot markets.
Growth Catalysts
- EU Green Deal food waste hierarchy:Mandatory reduction targets for member states create legal pull-through for upcycled ingredient procurement in industrial bakeries and ready-meal manufacturing.
- Spent grain valorization:Breweries in Bavaria and Bohemia are installing on-site dehydration units to supply flour mills with stable-volume by-product streams.
- Netherlands circular food clusters:Physical co-location of ingredient innovators with retail buyers in Wageningen and Rotterdam accelerates commercialization timelines for novel upcycled formulations.
Market Restraints
- REACH compliance costs:Traceability documentation for novel upcycled inputs adds certification overhead that disadvantages small-scale artisan entrants against scaled operators.
- Input supply fragmentation:Seasonal variability in fruit pulp and vegetable trim availability from agricultural processors creates volume planning uncertainty for beverage manufacturers.
- EFSA novel food guidance:Extended safety assessment timelines for fermentation-derived ingredients delay market entry by eighteen to thirty-six months versus conventional alternatives.
Strategic Opportunities
- Poland and Romania food processing:Underdeveloped waste valorization infrastructure in these member states offers first-mover positioning for dehydration equipment suppliers.
- Extended producer responsibility schemes:France's mandatory food waste reporting for large retailers creates compliance-driven demand for verified upcycled ingredient sourcing.
- AI-act automated sorting:Transparency mandates for machine-learning waste classification systems will favor vendors with interpretable algorithms in German and Dutch municipal contracts.
Industry Challenges
- Food-grade safety certification:Retrofitting existing dehydration lines to meet EFSA microbial standards requires capital outlays that strain mid-tier processor balance sheets.
- Cross-border waste transport:Divergent national interpretations of EU waste framework regulations create customs friction for ingredients moving between member states.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Upcycled Food Products Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $5.55 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Snack Bars, Flour, Beverages, Ingredients End User: Retail, Foodservice, Online Consumers, Distributors Packaging Type: Bottles, Pouches, Boxes, Jars Distribution Channel: Supermarkets, Health Food Stores, E-commerce, Farmers' Markets |
| Companies Covered | REMA 1000, RIND Snacks, Rohlik Group, Rootly, Trashy Chips, ALDI Nord Group, Rebread, Oisix ra Daichi, Tesco, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Upcycled Food Products Market Evolving Landscape
Active restructuring of supply relationships around waste-stream partnerships is compressing traditional commodity procurement cycles and enabling new margin pools for processors with captive access to by-product flows.
Enzymatic protein recovery from brewer's spent grain is migrating from pilot-scale demonstration to commercial deployment across Nordic and German malt houses. Industrial bakeries in Copenhagen and Hamburg are locking in multi-year offtake agreements for these flours at price premiums to conventional wheat. The technology is migrating from specialty craft applications to mainstream bread and snack manufacturing, displacing commodity gluten imports in formulations where functional protein content matters.
EFSA's evolving novel food guidance for fermentation-derived ingredients is forcing manufacturers to front-load toxicology studies before pilot production. Industrial biotechnology firms in the Netherlands and Denmark are building dedicated regulatory affairs functions to navigate pre-market authorization timelines. Beverage applications face the steepest compliance burden, as upcycled fruit pulp concentrates fall under stricter additive classifications than their fresh-pressed equivalents.
Foodservice procurement teams are unbundling sustainability verification from traditional quality audits, creating standalone supplier scorecards for waste-reduction metrics. Contract caterers operating across German federal government buildings and French corporate campuses now require documented upcycled ingredient percentages in RFP responses. This pattern is most visible in the Netherlands, where Sodexo and Compass Group have established dedicated upcycled product SKUs for their Benelux operations.
Europe Upcycled Food Products Market Segmentation
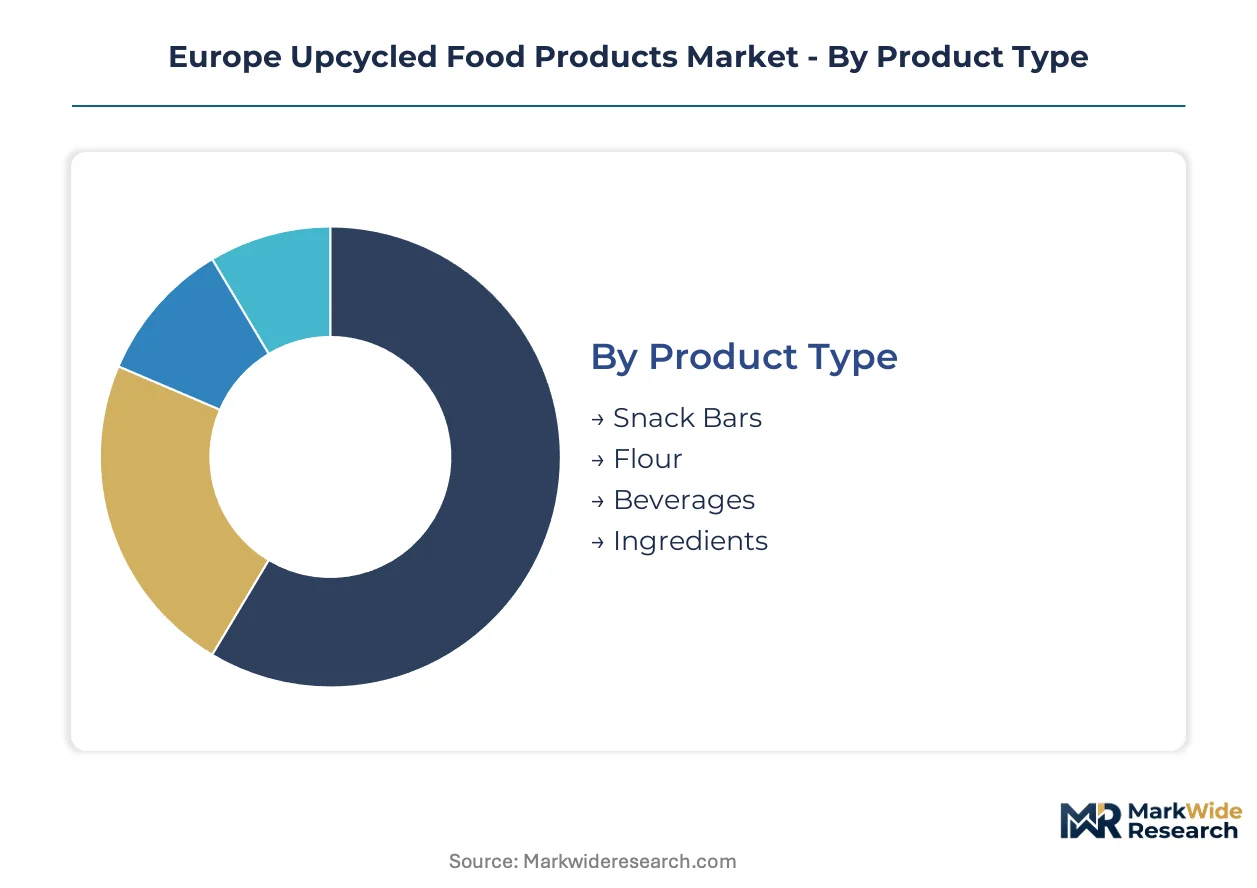
Segmentation in the Europe upcycled food products market reveals how waste-stream partnerships and regulatory compliance requirements reshape procurement decisions across distinct buyer categories. Understanding these divides exposes where margin pools concentrate and which channels face the steepest certification barriers.
Product Type:
After-sales technical support intensity varies sharply across product formats, with ingredient buyers demanding ongoing regulatory documentation while beverage brands prioritize formulation troubleshooting.
- Snack Bars:Compressed formats combining upcycled fruit pulp, spent grain flour, and nut by-products into shelf-stable nutrition products. German and Dutch retail buyers dominate procurement volumes, driven by private-label expansion at REMA 1000 and dedicated bay allocations at Tesco UK superstores. Snack bars hold the largest share; momentum sits with functional beverage applications.
- Flour:Milled outputs from brewer's spent grain, vegetable trim dehydration, and bread waste reprocessing achieve protein parity with conventional wheat. Copenhagen and Hamburg industrial bakeries lock in multi-year offtake agreements at price premiums to commodity imports. Flour holds the largest share; beverage formulations gain share fastest.
- Beverages:Functional drinks incorporating upcycled fruit pulp concentrates and vegetable juice by-products. EFSA novel food guidance imposes eighteen-to-thirty-six-month safety assessment delays versus fresh-pressed equivalents.
- Ingredients:B2B dehydrated powders, protein isolates, and fermentation-derived inputs supplying food manufacturers. REACH traceability documentation favors scaled operators with dedicated regulatory affairs functions.
Ingredient supply contracts sustain the deepest margin pools through multi-year offtake agreements, while beverage applications face the steepest compliance burden under evolving EFSA guidance.
End User:
Cost tier stratification separates premium sustainability-verified buyers from price-sensitive mass-market channels, with compliance-driven procurement concentrated in French and Dutch institutional foodservice.
- Retail:Supermarket chains and health food stores stocking packaged upcycled goods for household consumers. Netherlands circular food clusters in Wageningen accelerate product commercialization timelines for retail buyers.
- Foodservice:Contract caterers and restaurant operators incorporating upcycled ingredients into prepared meals. Sodexo and Compass Group Benelux operations mandate documented upcycled percentages in supplier RFP responses.
- Online Consumers:Direct-to-purchaser channels bypassing traditional retail markup structures. Subscription models concentrate in Nordic urban markets with established sustainability literacy.
- Distributors:Wholesale intermediaries consolidating fragmented artisan production for regional retail penetration. Cross-border waste transport friction disadvantages smaller distributors operating across divergent national regulatory interpretations.
Foodservice procurement teams unbundle sustainability verification from quality audits, creating standalone supplier scorecards that reshape competitive positioning for waste-reduction metrics.
Packaging Type:
Volume throughput constraints favor flexible formats for ingredient shipping while rigid containers dominate retail-facing beverage applications requiring shelf differentiation.
- Bottles:Glass and PET containers for liquid upcycled beverages and condiments. German municipal recycling systems impose extended producer responsibility fees that elevate total cost of ownership.
- Pouches:Flexible laminated films for dehydrated powders, snack bars, and concentrated ingredients. Reduced shipping weight appeals to e-commerce fulfillment operators managing last-mile cost structures.
- Boxes:Corrugated and rigid paperboard for multi-unit retail packaging and subscription deliveries. UK supermarkets prioritize shelf-ready formats minimizing in-store labor.
- Jars:Glass containers for spreads, fermented pastes, and premium ingredient presentations. French retail buyers associate jar formats with artisan credibility and transparency signaling.
Pouch formats expand most quickly in ingredient and e-commerce channels; bottles retain dominance in retail beverage placement.
Distribution Channel:
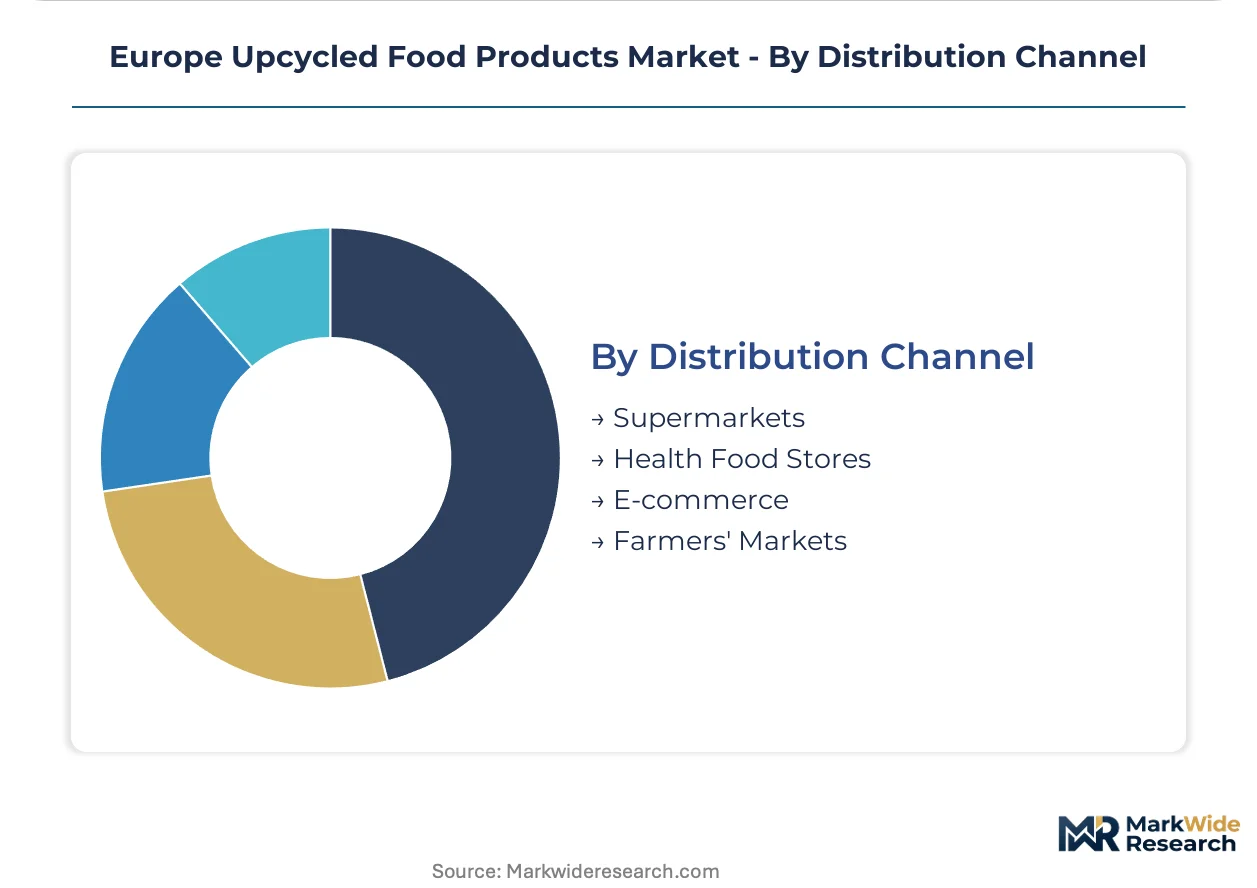
Geographic concentration of circular food clusters in the Netherlands and Bavaria creates procurement gravity that favors regional superstore buyers over dispersed farmers' market vendors.
- Supermarkets:Large-format retail operators with dedicated shelf space and private-label development capabilities. Tesco UK deploys dedicated upcycled product bays in largest superstores to anchor category visibility.
- Health Food Stores:Specialized retailers targeting sustainability-motivated consumers with premium positioning. Certification requirements for organic and waste-reduction claims create vendor qualification barriers.
- E-commerce:Direct-to-consumer platforms and third-party marketplace aggregators. AI Act transparency mandates for automated sorting technologies will shape fulfillment center vendor selection in German and Dutch contracts.
- Farmers' Markets:Direct producer-to-consumer venues for local and artisan upcycled goods. Seasonal input variability from agricultural processors limits consistent product availability for market vendors.
Supermarkets capture the largest transaction volumes; e-commerce channels climb fastest as fulfillment infrastructure matures for temperature-stable upcycled goods.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial bakeries and contract caterers concentrate procurement power in Northern European markets, while Mediterranean food processors lag in waste valorization infrastructure. Retail channel control sits with Dutch and German operators who dictate supplier certification requirements.
Germany
Bavarian malt houses deploy commercial-scale enzymatic protein recovery systems for brewer's spent grain, supplying Copenhagen and Hamburg industrial bakeries with multi-year offtake contracts. The country's extended producer responsibility schemes mandate food waste reporting for large retailers, creating compliance-driven demand for verified upcycled ingredients. Berlin-Brandenburg clusters host precision fermentation startups navigating EFSA novel food authorization timelines.
Netherlands
Wageningen and Rotterdam circular food clusters physically co-locate ingredient innovators with retail buyers, compressing commercialization timelines for novel formulations. REACH compliance documentation for upcycled ingredient traceability favors scaled operators with dedicated regulatory affairs functions. Randstad-based contract caterers Sodexo and Compass Group mandate documented upcycled percentages in supplier RFP responses.
France
Paris-based foodservice operators expand menu applications for upcycled ingredients across corporate campus and federal government building contracts. The country's mandatory food waste reporting for large retailers creates compliance-driven procurement pull-through. Île-de-France industrial bakeries lock in price premiums for spent-grain flours displacing commodity gluten imports.
United Kingdom
Tesco deploys dedicated upcycled product bays in largest superstores to anchor category visibility for household consumers. London/Southeast health food stores concentrate sustainability-motivated demand with premium positioning and organic certification requirements. UK supermarkets prioritize shelf-ready packaging formats minimizing in-store labor for multi-unit retail deliveries.
Poland
Underdeveloped waste valorization infrastructure across food processing regions offers first-mover positioning for dehydration equipment suppliers. Warsaw-based distributors consolidate fragmented artisan production for regional retail penetration. Divergent national interpretations of EU waste framework regulations create customs friction limiting cross-border ingredient flows.
Europe Upcycled Food Products Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. Retail operators with private-label capabilities and dedicated shelf space allocations hold procurement leverage over ingredient suppliers. Three archetypes dominate: supermarket chains with category-management functions, circular-economy ingredient technology firms, and foodservice procurement platforms with sustainability scorecards. Competitive moves concentrate on strategic partnerships linking waste-stream generators to processors, and portfolio diversification into functional beverage applications.
Among Nordic retail operators, REMA 1000 anchors private-label upcycled snack line development, while Tesco occupies a position within UK supermarket category management. Rebread exemplifies the closed-loop ingredient technology archetype, representing brewer-bakery partnership models. These three entities sit within distinct competitive vectors—retail channel control, geographic market anchoring, and circular supply chain integration—without overlapping strategic positioning.
| Leading Market Players |
|---|
| REMA 1000 |
| RIND Snacks |
| Rohlik Group |
| Rootly |
| Trashy Chips |
| ALDI Nord Group |
| Rebread |
| Oisix ra Daichi |
| Tesco |
| Others |
Value Network & Pricing Analysis
REACH traceability documentation costs for upcycled ingredient certification determine both three-tier pricing spreads across premium-mid-economy levels and the geographic clustering of supply relationships around scaled operators with dedicated regulatory affairs functions. EFSA novel food assessment timelines compress margin structures for fermentation-derived inputs while concentrating procurement power with Dutch and German buyers who dictate compliance standards.
Pricing Analysis
Multi-year offtake agreements with wheat futures indexation dominate the flour segment, locking Copenhagen and Hamburg industrial bakeries into cost-plus structures that stabilize input expenses against commodity volatility. Price differentiation separates EFSA-authorized fermentation ingredients from conventional alternatives, with certification grade and volume scale as primary tiering mechanisms. Pricing pressure stems from REACH compliance overhead that disadvantages artisan processors against scaled competitors. Mass-market retail channels exhibit highest price sensitivity, while foodservice procurement teams prioritize verified waste-reduction metrics over unit cost.
Supply Chain Analysis
Contract-manufacturing concentration sits with Bavarian malt houses and Wageningen-based precision fermentation facilities that hold commercial-scale enzymatic recovery capacity. Supply draws from Netherlands circular food clusters, German brewer dehydration units, and Polish equipment assembly operations. Raw material dependencies center on brewer's spent grain streams, fruit pulp concentrates from agricultural processors, and vegetable trim volumes from ready-meal manufacturers. Single-source vulnerability runs through seasonal variability in agricultural by-product availability. Distribution runs through supermarket private-label channels and foodservice procurement platforms with sustainability scorecards.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a substitution defense against conventional commodity ingredients, with precision fermentation-derived proteins threatening to displace upcycled by-product formulations if EFSA authorization timelines compress.
For Market Incumbents: Insulate market position through backward integration into brewer dehydration infrastructure and captive supply of spent-grain streams across Bavaria and Bohemia. Prioritize certification investment in REACH traceability documentation to maintain procurement leverage against artisan competitors. Channel control through dedicated retail bay allocations at Tesco and REMA 1000 anchors category visibility against private-label encroachment. For New Entrants and Emerging Players: Build out white-space positioning in Poland and Romania where waste valorization infrastructure remains underdeveloped and first-mover equipment supply contracts face limited competition. Target dehydration technology deployment for fruit pulp and vegetable trim applications where input supply fragmentation creates planning uncertainty for incumbent beverage manufacturers. Go-to-market angle centers on municipal contract partnerships leveraging EU AI Act transparency mandates for automated sorting systems. For Investors and Strategic Acquirers: The market sits at a regulatory consolidation phase that favors scaled operators with dedicated EFSA regulatory affairs functions and multi-year offtake contract portfolios. Long-term viability over the next decade hinges on circular food cluster proximity and waste-stream partnership density rather than brand equity. Acquisition target archetype: ingredient technology firms with captive brewer relationships and novel food authorization pipelines. Signal to watch: compression in EFSA safety assessment timelines for fermentation-derived ingredients as indicator of competitive barrier erosion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dehydration Infrastructure | Bavarian malt houses secure captive spent-grain supply, displacing commodity spot market dependency. |
| Multi-Year Offtake Agreement Expansion | Copenhagen and Hamburg industrial bakeries lock price premiums against wheat futures volatility. |
| EFSA Novel Food Authorization Investment | Dutch biotechnology firms front-load toxicology studies to compress eighteen-to-thirty-six-month entry delays. |
| Circular Food Cluster Geographic Expansion | Wageningen-Rotterdam co-location model migrates to Berlin-Brandenburg precision fermentation startups. |
| AI-Act Compliant Sorting Technology Deployment | German and Dutch municipal contracts favor interpretable algorithms for waste classification systems. |
Research Methodology
The analysis maps snack bar, flour, beverage, and ingredient sub-sectors, each validated through foodservice procurement directors, retail category managers, brewery operations heads, and precision fermentation R&D leads. Primary interviews with these stakeholders combined secondary validation from EFSA novel food submission databases, EU Green Deal implementation reports, REACH registration dossiers, and supermarket private-label expansion announcements. Bottom-up volume modeling across waste-stream availability and top-down value triangulation against circular economy investment flows anchored the approach.
The assumption-set held fixed EU Green Deal food waste hierarchy enforcement and EFSA guidance timelines while varying precision fermentation cost curves and AI Act implementation pacing across the projection horizon. Segmentation dimensions modeled include product format, end-user procurement channel, packaging type, and distribution channel complexity alongside regional regulatory cluster differentiation. CAGRs derived from waste-stream partnership formation rates and retail shelf-space allocation velocity. Industry-specific inputs incorporated brewer spent-grain dehydration capacity expansion and contract caterer sustainability scorecard adoption curves.
The forecast holds incumbent behavior within observed patterns; aggressive moves by precision fermentation startups with compressed EFSA timelines would shift outcomes toward protein ingredient substitution. Quarterly review of novel food authorization submission volumes and circular cluster investment announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
Vegetable Waste Products Market
Alternative Food Sources
Hemp-Based Products Market
Alternative Food Sources
North America Fat Replacers Market
Alternative Food Sources
Monoprotein Market
Alternative Food Sources
Asia-Pacific Meat Substitutes Market
Alternative Food Sources
Algae Oil Market
Alternative Food Sources
North America Precision Fermentation Market
Alternative Food Sources
Food Cultures Market
Alternative Food Sources
Fish Meal Alternative Market
Alternative Food Sources
Organic Gluten Substitutes Market
Alternative Food Sources
Vegan Casing Market
Alternative Food Sources
Gluten-Free Meat Substitutes Market
Alternative Food Sources
Asia-Pacific Meal Replacement Products Market
Alternative Food Sources
Vegan Caviar Market
Alternative Food Sources
Egg Substitutes Market
Alternative Food Sources
Low Carbs Vegan Food Market