
 Corn-Based Protein Market | 2026-2036
Corn-Based Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Corn-Based Protein Market Outlook
Direct procurement between corn processors and food manufacturers is rewriting traditional ingredient distribution. Cargill leverages its North American grain origination network to secure supply chain control from farm to formulation. Roquette differentiates through European pea-corn hybrid protein research, while Tate & Lyle anchors beverage applications with specialty hydrolysate expertise.
Corn-based protein comprises concentrated or isolated zein and glutelin fractions extracted from maize through wet milling or enzymatic hydrolysis, yielding products with protein content ranging from 50% to 90% depending on refinement grade. These ingredients serve as functional emulsifiers, texturizers, and nutritional fortifiers across human food and animal nutrition systems. Concentrate and isolate grades command the deepest margin pools due to their functional performance in meat analogues and sports beverages. Powder form dominates manufacturing logistics, though liquid hydrolysates are gaining traction in ready-to-drink nutritional applications where rapid absorption matters.
EMA food additive safety assessments, FDA GRAS notifications, and EU Green Deal agricultural sustainability criteria collectively shape product approval timelines and sourcing requirements for corn protein suppliers. REACH chemical registration and CSRD corporate disclosure rules add compliance layers for European market entry. Stakeholders must monitor evolving carbon accounting standards for crop-derived ingredients as procurement teams embed Scope 3 emissions thresholds into supplier qualification protocols.
Market Dynamics
The EU Green Deal is compressing approval timelines for crop-derived ingredients while livestock producers in Brazil accelerate feed formulation shifts away from soy dependency. Wet milling capacity expansion and enzymatic hydrolysis patents are redrawing competitive boundaries between concentrate and isolate grades.
Growth Catalysts
- EU Green Deal agricultural sustainability criteria:Procurement teams embed Scope 3 emissions thresholds into supplier qualification protocols, favoring corn protein with verified carbon accounting over soy alternatives.
- Brazilian livestock sector:Feed ration reformulation away from soy isolates toward corn-derived concentrates is creating concentrated demand pull from integrated poultry and swine operations.
- Enzymatic hydrolysis advancement:Second-generation fractionation methods yield higher-purity zein isolates with improved emulsification performance in meat analogues.
Market Restraints
- Maize price volatility:Input cost swings from drought cycles in US Corn Belt and Argentine Pampas compress margin predictability for wet millers.
- REACH chemical registration:European market entry requires multi-year substance dossier preparation, delaying commercialization for novel hydrolysate variants.
- Pea protein substitution:Roquette and European competitors advance pea-corn hybrid research, threatening pure-play corn isolate positioning in beverage applications.
Strategic Opportunities
- CSRD corporate disclosure rules:Mandatory sustainability reporting across EU-listed food manufacturers creates certified-ingredient premiums for suppliers with verified supply chain transparency.
- Ready-to-drink nutritional applications:Liquid hydrolysate formats with rapid absorption profiles capture share from powder concentrates in sports nutrition channels.
- India feed sector:Underpenetrated corn protein adoption in poultry and aquaculture rations offers first-mover positioning as FSSAI establishes novel protein ingredient standards.
Industry Challenges
- Carbon accounting skill scarcity:Procurement teams lack trained lifecycle assessment specialists to verify supplier Scope 3 claims against EU Green Deal benchmarks.
- GRAS notification timelines:FDA safety assessments for novel zein isolate applications extend 18-24 months, blocking formulation trials for US beverage launches.
- Legacy wet milling retrofit costs:Capacity expansion for isolate-grade production demands capital-intensive equipment upgrades at existing North American processing facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Corn-Based Protein Market |
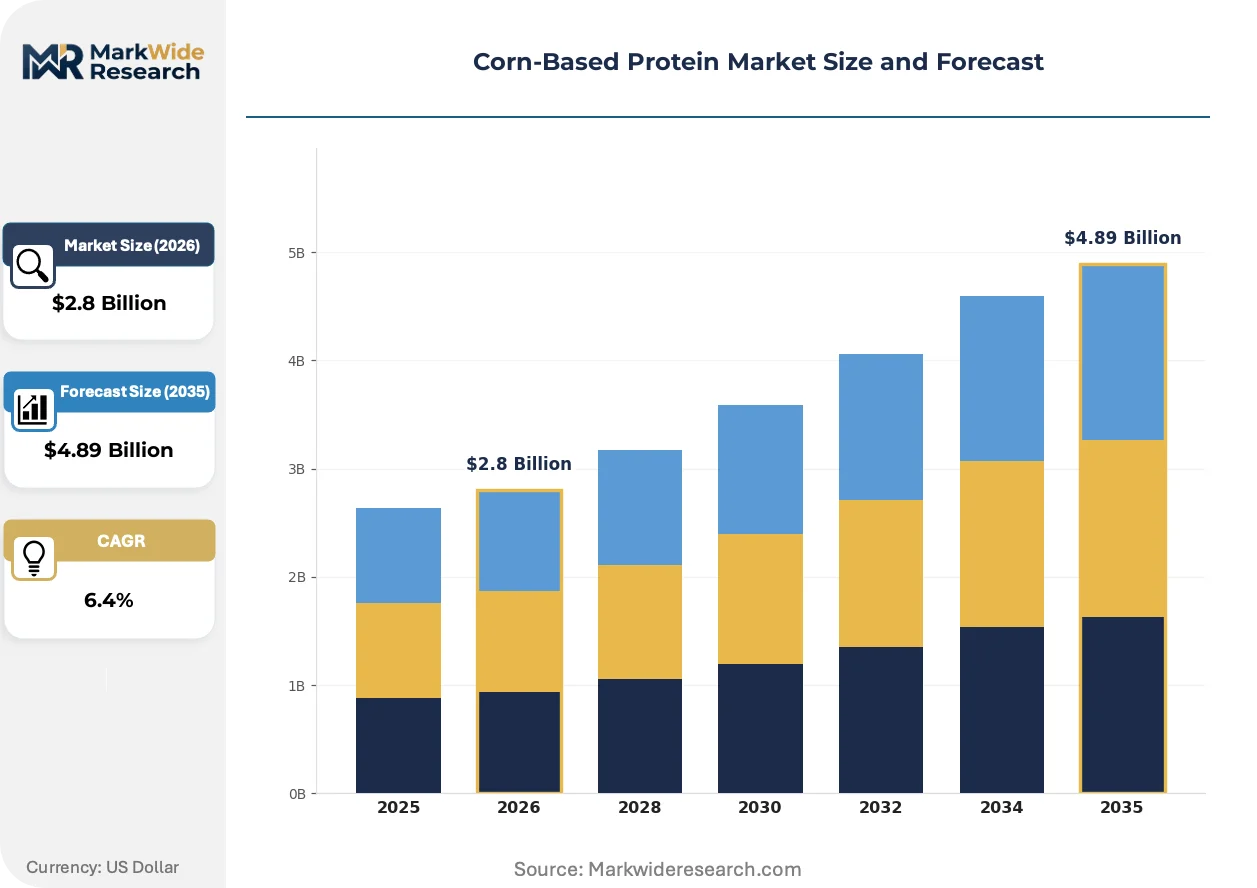
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Isolate, Concentrate, Hydrolysate, Textured Application: Food & Beverage, Animal Feed, Nutritional Supplements, Bakery Products End User: Health Conscious Consumers, Sports Nutritionists, Food Manufacturers, Livestock Producers Form: Powder, Granule, Liquid, Flake |
| Companies Covered | Ingredion Incorporated, Bunge Limited, Cargill, HEBEI BIOCON FEED ADDITIVES, Prorich Agro, Tate & Lyle, Glanbia Nutritionals, Nutrigo Feeds, Roquette, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Corn-Based Protein Market Strategic Shifts
Digital twin modeling of enzymatic fractionation is compressing R&D cycles for novel protein grades. Patent filings cluster around hybrid extraction methods and functional property enhancement for alternative protein applications.
Membrane filtration cascades paired with AI-driven process control are virtualizing traditional wet milling optimization. Specialty ingredient divisions at Tate & Lyle adopt these systems to reduce batch-to-batch variability in hydrolysate molecular weight profiles. The technology is virtualizing quality assurance overhead while accelerating customer-specific formulation development timelines.
REACH substance registration deadlines under ECHA jurisdiction are forcing early-stage corn protein suppliers to consolidate European market entry strategies. The regulation mandates full toxicological dossiers for enzymatic hydrolysates classified as novel chemical entities. Small-scale North American processors are responding through partnership structures with established EU registrants rather than independent filing.
Sports nutritionists now specify certified carbon footprint data as a primary selection criterion alongside functional performance. Direct procurement contracts between Brazilian livestock integrators and Argentine wet millers are displacing traditional distributor intermediaries. This pattern is most visible in São Paulo state poultry operations where feed cost transparency has become a competitive weapon.
Corn-Based Protein Market Segmentation
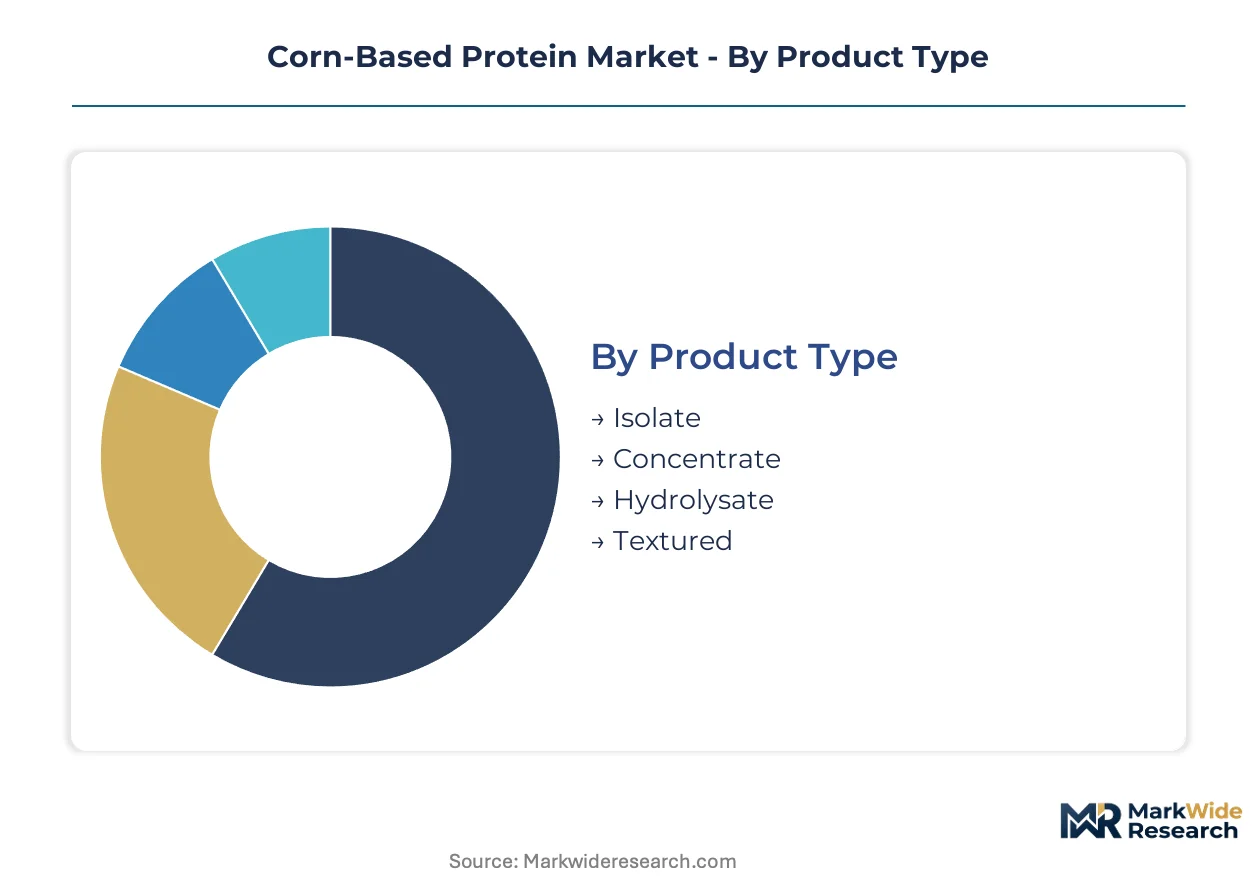
Corn-based protein segmentation reveals how extraction technology and formulation requirements split manufacturing investment and customer procurement priorities. Each dimension carries distinct margin structures and technical service demands that reshape supplier competitive positioning.
Product Type:
After-sales service intensity varies sharply across extraction grades, with isolate and hydrolysate users demanding ongoing technical support for emulsion stability and shelf-life optimization that concentrate buyers rarely require.
- Isolate:Zein and glutelin fractions refined to 80-90% protein content through multi-stage membrane filtration. Sports nutritionists in Brazil specify isolates for rapid-absorption beverage formulations where solubility performance determines procurement contracts.
- Concentrate:Intermediate refinement yielding 50-70% protein with retained fiber and lipid fractions. Livestock producers across São Paulo state favor concentrates for cost-optimized poultry feed rations where amino acid density balances against formulation economics.
- Hydrolysate:Enzymatically predigested proteins for clinical and senior nutrition applications requiring minimal digestive effort.
- Textured:Extruded protein structures mimicking meat fiber organization for plant-based analogues.
By volume, Concentrate leads. By growth pace, Hydrolysate is expanding most quickly.
Application:
Application segmentation tracks how functional requirements diverge between human consumption systems and animal nutrition, with regulatory pathways and certification demands creating distinct commercial entry barriers.
- Food & Beverage:Emulsification and texturizing applications in meat alternatives and dairy substitutes. EU Green Deal carbon accounting requirements are embedding Scope 3 verification into procurement specifications for beverage manufacturers.
- Animal Feed:Poultry, swine, and aquaculture rations where corn protein displaces soy isolates. Brazilian integrated operations are consolidating direct procurement relationships with Argentine wet millers to secure supply transparency.
- Nutritional Supplements:Protein fortification in powders, bars, and clinical nutrition products.
- Bakery Products:Dough conditioning and protein enrichment in commercial baking applications.
Animal Feed commands the largest volume position. Food & Beverage exhibits the steepest expansion trajectory as meat analogue formulations accelerate.
End User:
End user segmentation exposes how procurement sophistication and technical specification authority concentrate among professional formulators rather than retail consumers.
- Health Conscious Consumers:Retail purchasers of protein-fortified foods and supplements with limited technical specification involvement.
- Sports Nutritionists:Professional formulators specifying certified carbon footprint data alongside functional performance metrics in beverage development.
- Food Manufacturers:Industrial procurement teams embedding CSRD-aligned sustainability reporting requirements into supplier qualification protocols.
- Livestock Producers:Integrated poultry and swine operations in Brazil reformulating feed rations away from soy dependency toward corn-derived concentrates.
Food Manufacturers represent the dominant volume segment. Sports Nutritionists are gaining share fastest as certified-ingredient premiums expand.
Form:
Form segmentation reflects manufacturing logistics constraints and absorption kinetics that differentiate powder handling efficiency from liquid formulation flexibility.
- Powder:Dominant format for manufacturing logistics with established handling infrastructure and extended shelf stability. Tate & Lyle specialty divisions optimize molecular weight profiles for beverage solubility performance.
- Liquid:Hydrolysate formats with rapid absorption profiles capturing share in ready-to-drink sports nutrition channels where enzymatic predigestion accelerates amino acid availability.
- Granule:Intermediate particle size for controlled-release applications and specialized feed pelleting.
- Flake:Textured structures for meat analogue fiber simulation and visual appearance matching.
Powder maintains volume leadership. Liquid formats are climbing the fastest as beverage manufacturers prioritize rapid-absorption positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power tilts toward Argentine wet millers supplying Brazilian livestock integrators, while US Corn Belt processors absorb drought-driven input volatility without equivalent pass-through mechanisms.
United States
Drought cycles across Iowa and Illinois compress margin predictability for wet millers supplying beverage manufacturers. FDA GRAS notification timelines extend 18-24 months for novel zein isolate applications, delaying formulation trials. Processing clusters in Decatur, Illinois and Blair, Nebraska anchor concentrate production for domestic meat analogue developers.
Brazil
São Paulo state poultry operations reformulate feed rations away from soy dependency toward corn-derived concentrates. ANVISA novel ingredient pathways remain underdeveloped for hydrolysate registration, favoring concentrate imports from Argentine suppliers. Integrated swine operations in Santa Catarina consolidate direct procurement relationships with Paraná-based processors.
Germany
REACH substance registration deadlines under ECHA jurisdiction force early-stage suppliers to consolidate European market entry strategies. CSRD corporate disclosure rules mandate sustainability reporting across listed food manufacturers, creating certified-ingredient premiums. Hamburg and Frankfurt processing hubs specialize in beverage-grade hydrolysate refinement for sports nutrition channels.
Argentina
Pampas drought cycles alternate with surplus harvests, generating supply volatility that Buenos Aires-based exporters manage through forward contracting. The country's national agricultural regulator maintains phytosanitary certification reciprocity with Brazilian import authorities. Rosario port clusters concentrate wet milling capacity serving São Paulo feed sector demand.
India
Poultry and aquaculture rations remain underpenetrated for corn protein adoption as FSSAI establishes novel protein ingredient standards. The PLI scheme for food processing incentivizes wet milling capacity expansion in Gujarat and Maharashtra. Anand and Pune industrial corridors attract multinational ingredient suppliers positioning for first-mover advantage.
Corn-Based Protein Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream. The vendor base arranges into three tiers: multinational grain processors with captive origination networks, European specialty ingredient divisions with hybrid protein research capabilities, and regional feed additive suppliers serving livestock integrators through direct procurement contracts. Two dominant competitive moves define current positioning: backward integration into farm-level grain origination, and enzymatic hydrolysis patent filings around zein isolate fractionation.
Among North American grain processors, Cargill and Ingredion occupy positions as platform integrators with supply chain control from farm to formulation. Tate & Lyle exemplifies the specialty hydrolysate archetype through beverage application expertise. Roquette represents the hybrid research vector with European pea-corn protein development.
| Leading Market Players |
|---|
| Ingredion Incorporated |
| Bunge Limited |
| Cargill |
| HEBEI BIOCON FEED ADDITIVES |
| Prorich Agro |
| Tate & Lyle |
| Glanbia Nutritionals |
| Nutrigo Feeds |
| Roquette |
| Others |
Value Chain & Pricing Dynamics
Rosario port clusters concentrate Argentine wet milling capacity serving São Paulo feed sector demand, creating asymmetric pricing power where drought-driven input volatility in the Pampas transmits unevenly to Brazilian livestock integrators. Argentine exporters leverage forward contracting to capture margin premiums during surplus harvests, while US Corn Belt processors absorb climate-driven cost swings without equivalent pass-through mechanisms.
Pricing Analysis
Configured-to-order pricing for beverage-grade hydrolysates commands substantial premiums over standard concentrate grades for livestock feed. Three-tier pricing structure across premium, standard, and economy levels separates certified carbon-accounting isolates from commodity concentrates and unverified imports. Price differentiation hinges on EU Green Deal Scope 3 verification and enzymatic refinement grade. Pricing pressure stems from pea-corn hybrid substitution threats in European beverage applications. Livestock producers in São Paulo state exhibit highest price sensitivity, while sports nutritionists in Germany show lowest sensitivity due to certified-ingredient procurement mandates.
Supply Chain Analysis
REACH substance registration under ECHA jurisdiction restricts novel hydrolysate flows into European markets, forcing North American processors into partnership structures with established EU registrants. Supply concentrates in Argentina, the United States, and Brazil, with Rosario, Decatur, and São Paulo anchoring respective processing hubs. Raw material flows draw from Pampas and Corn Belt maize belts, with enzyme inputs for hydrolysis sourced from specialty biochemical suppliers. Single-source vulnerability concentrates in Argentine export corridors exposed to Pampas drought cycles. Distribution runs through direct procurement contracts between wet millers and integrated livestock operations, displacing traditional ingredient distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Corn-based protein sits in early-cycle expansion as Brazilian livestock producers accelerate feed reformulation away from soy dependency, creating concentrated demand pull from integrated poultry and swine operations.
For Market Incumbents: Pre-empt pea-corn hybrid substitution threats by accelerating enzymatic hydrolysis patent filings around zein isolate fractionation. Secure backward integration into farm-level grain origination networks to control input cost volatility. Defend margin pools in beverage applications through CSRD-aligned carbon accounting certification investments. For New Entrants and Emerging Players: Establish a beachhead in India's underpenetrated poultry and aquaculture feed sector as FSSAI establishes novel protein ingredient standards. Target liquid hydrolysate formats for ready-to-drink sports nutrition channels where rapid-absorption positioning commands premium pricing. Pursue partnership structures with established EU registrants to bypass REACH substance registration barriers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specialty hydrolysate suppliers with beverage-application technical service contracts. Long-term viability favors processors with enzymatic fractionation capabilities and verified Scope 3 carbon accounting systems. Monitor Brazilian direct procurement contract volumes as inflection indicator for structural demand shift away from soy protein.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Hydrolysis Patent Expansion | Secures intellectual property moats around zein isolate fractionation for meat analogue applications. |
| Backward Integration into Grain Origination | Cargill-style farm-to-formulation control mitigates Pampas and Corn Belt drought exposure. |
| CSRD-Aligned Certification Investment | Captures certified-ingredient premiums from EU-listed food manufacturers under mandatory disclosure rules. |
| Direct Procurement Contract Structures | Displaces distributor intermediaries in São Paulo poultry operations seeking feed cost transparency. |
| Liquid Hydrolysate Format Development | Targets ready-to-drink sports nutrition channels where rapid absorption drives procurement decisions. |
Study Parameters
Initial hypotheses were tested against primary input from wet milling operations managers, sports nutrition formulation directors, livestock procurement leads, and EU regulatory affairs specialists and refined through secondary validation. Primary fieldwork combined structured interviews with Argentine export coordinators and Brazilian feed formulators. Secondary sources included EMA food additive safety assessments, FDA GRAS notification filings, EU Green Deal agricultural sustainability criteria documentation, and ANVISA novel ingredient pathway records. Bottom-up volume modeling from extraction grade and application segments was triangulated against top-down macroeconomic demand projections.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled encompassed extraction grade tier, end-use application, formulation requirement, and regional regulatory cluster. CAGRs were synthesized from historical volume trajectories, capacity expansion announcements, and adoption curve positioning. Industry-specific forecast inputs included enzymatic hydrolysis patent filing velocity and CSRD corporate disclosure implementation timelines.
Stress conditions across Pampas drought frequency, maize price volatility bands, and REACH registration delay scenarios were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding EU Green Deal enforcement intensity and Brazilian livestock sector consolidation pace. Material shifts in FDA GRAS notification timelines or FSSAI novel protein standard finalization would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
North America Edible Insects Market
Alternative Food Sources
North America Meat Substitutes Market
Alternative Food Sources
Insect-Based Pet Food Market
Alternative Food Sources
United States Hemp Protein Market
Alternative Food Sources
Global Algal Oil Market
Alternative Food Sources
Plant-Based Squalene Market
Alternative Food Sources
Mushroom Protein Market
Alternative Food Sources
Fat Substitutes Market
Alternative Food Sources
Gluten-Free Meat Substitutes Market
Alternative Food Sources
Fungal Protein Market
Alternative Food Sources
Vegan Eggs Market
Alternative Food Sources
North America Fat Replacers Market
Alternative Food Sources
Edible Insects Market
Alternative Food Sources
Global Meal Replacement Shakes Market
Alternative Food Sources
Monoprotein Market
Alternative Food Sources
Flour Substitutes Market