
 Gluten Replacer Market | 2026-2036
Gluten Replacer Market Size, Share, and Industry Trends Forecast 2026-2036
Gluten Replacer Market Analytics
Ingredient sourcing and finished-formulation services is rewriting margin distribution across the gluten replacer value chain. Kerry leverages its integrated taste-and-nutrition platform to anchor premium positioning in bakery applications. Ingredion sustains scale advantages through its specialty starch portfolio, while ADM competes via vertical control over plant-protein supply chains.
Gluten replacers comprise functional ingredients—starches, proteins, hydrocolloids, and fibers—that replicate the viscoelastic properties of wheat gluten in dough systems, typically achieving comparable extensibility at inclusion rates between five and fifteen percent depending on the base matrix. Their primary commercial purpose is enabling palatable, structurally stable baked goods, snacks, and pasta formulations for gluten-intolerant consumers and clean-label seekers. Starch-based replacers dominate current volume due to cost parity and processing familiarity, though protein-based alternatives capture disproportionate margin in premium positioning. Fiber-based ingredients represent the fastest-expanding category as manufacturers pursue dual claims around digestive health and gluten-free status.
FDA gluten-free labeling rules and the EU's FIC Regulation establish strict thresholds and disclosure requirements that directly determine which formulations qualify for shelf placement in regulated markets. EFSA safety assessments and Health Canada gluten-free standards further constrain ingredient selection and supplier qualification protocols. Stakeholders must monitor evolving definitions of "gluten-free" and "very low gluten" across jurisdictions, as regulatory divergence threatens to fragment formulation strategies and complicate cross-border product lines.
Market Dynamics
Protein-based and starch-based ingredient sourcing is rewriting margin distribution across the gluten replacer value chain as bakery manufacturers accelerate clean-label reformulation amid tightening food-labeling requirements.
Growth Catalysts
- FDA gluten-free standards:Strict thresholds and disclosure requirements in the United States are forcing bakery manufacturers to reformulate with qualified gluten replacers to maintain shelf placement in regulated retail channels.
- Fiber-based ingredients:Manufacturers pursuing dual claims around digestive health and gluten-free status are driving fastest-expanding category adoption across premium positioning segments.
- Germany:Clean-label product lines in this market command premium positioning, concentrating demand for protein-based alternatives with superior viscoelastic performance in dough systems.
Market Restraints
- Input cost volatility:Specialty starches and plant proteins face agricultural commodity price swings that compress formulation margins for mid-tier bakery producers.
- Supply concentration risk:Premium hydrocolloid sourcing clusters with limited qualified suppliers in select European processing hubs, creating qualification bottlenecks.
- Technical limitation:Achieving comparable extensibility across diverse base matrices requires customized inclusion rates between five and fifteen percent, complicating scale economics.
Strategic Opportunities
- EU FIC Regulation:Evolving definitions of "very low gluten" versus "gluten-free" create formulation service opportunities for suppliers with regulatory navigation capabilities.
- Pasta applications:Structural stability requirements in extruded products represent an underpenetrated application segment for advanced protein-based replacer systems.
- Direct-to-manufacturer platforms:Ingredient sourcing and finished-formulation services are consolidating through digital procurement channels that bypass traditional distribution layers.
Industry Challenges
- Rheology expertise gap:Formulation science talent with deep viscoelastic property knowledge remains scarce relative to accelerating clean-label reformulation timelines.
- Cross-border qualification:Divergent EFSA safety assessments and Health Canada gluten-free standards fragment supplier qualification protocols for multi-jurisdiction product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gluten Replacer Market |
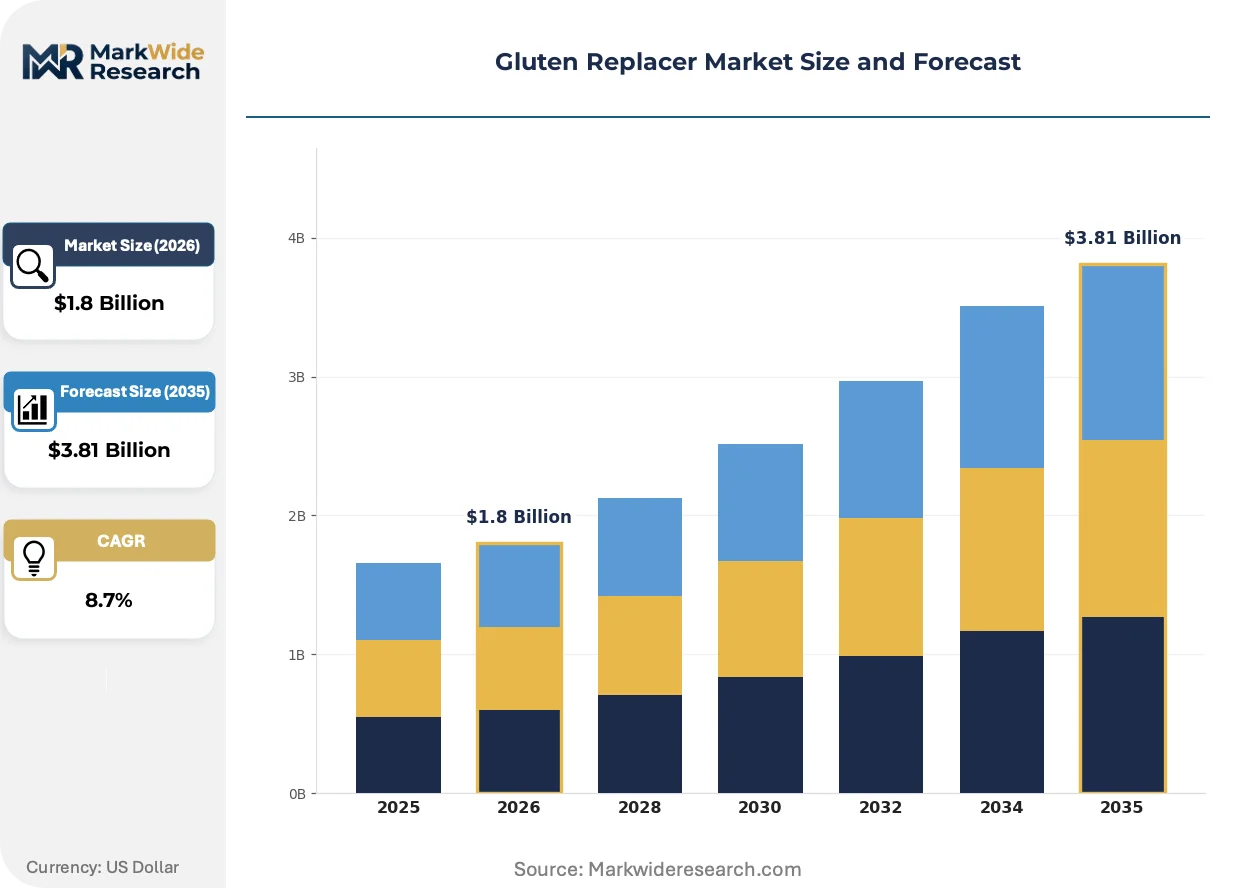
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Starch-based, Protein-based, Fiber-based, Other Ingredient Source: Plant-based, Animal-based, Synthetic, Others Application: Baked Goods, Snacks, Pasta, Dairy Alternatives Distribution Channel: Retail, E-commerce, Food Service, Direct Sales |
| Companies Covered | Kerry, Ingredion, ADM, Cargill, Tate & Lyle, CP Kelco, Roquette, Glanbia, Puris, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gluten Replacer Market Evolving Landscape
Computational modeling of dough microstructure is virtualizing traditional empirical formulation development, compressing R&D cycles while regulatory divergence across jurisdictions forces adaptive compliance architectures.
Enzymatic modification of plant proteins is virtualizing the functional performance gap between animal-derived and plant-based gluten replacers. Large-scale bakery manufacturers in Italy and the United States are adopting these systems at accelerated pilot-to-production timelines. The technology is virtualizing premium-tier margin capture previously reserved for specialized hydrocolloid blends.
REACH substance restrictions and evolving EFSA safety assessments are reshaping hydrocolloid eligibility lists for European bakery applications. Industrial consequence includes forced reformulation of legacy stabilizer systems and accelerated supplier requalification. Premium snack and frozen dough segments in Germany and France are responding with captive sourcing agreements to secure compliant ingredient pipelines.
Buyer concentration among contract manufacturers is compressing switching cycles and unbundling after-sales technical service from ingredient supply agreements. Regional bakery cooperatives in Italy are consolidating procurement through shared formulation laboratories that internalize rheology expertise. This pattern is most visible in Mediterranean markets where mid-tier producers lack in-house R&D scale.
Gluten Replacer Market Segmentation
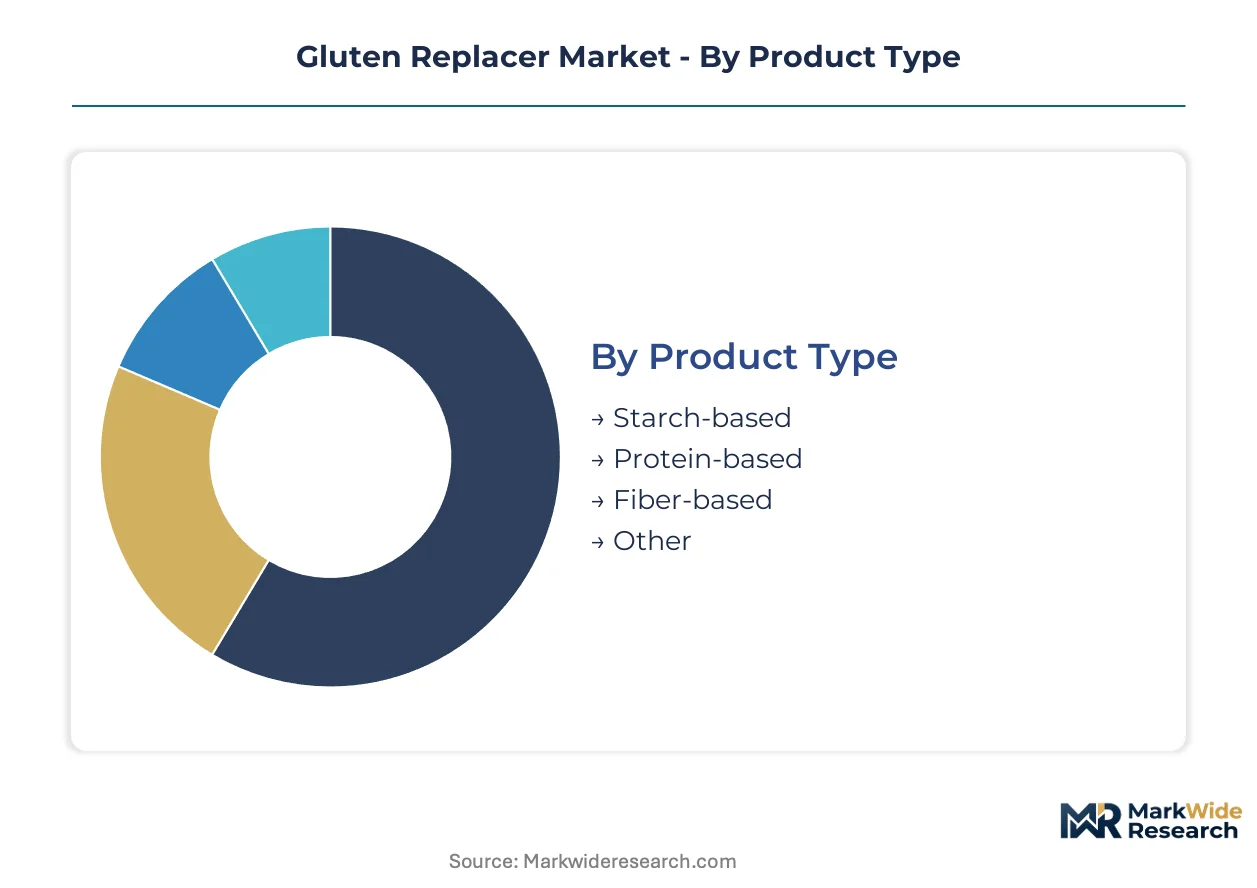
Gluten replacer manufacturers structure product portfolios around rheological performance requirements and clean-label positioning tiers. Segmentation choices directly determine margin capture, technical service intensity, and regulatory qualification burdens across bakery, snack, and pasta applications.
Product Type:
After-sales technical service intensity varies sharply across product categories, with protein-based systems demanding sustained formulation support while starch-based alternatives rely on established processing familiarity.
- Starch-based:Modified tapioca, potato, and rice starches provide cost-effective viscosity building and moisture retention in dough matrices. Demand concentrates among mid-tier bakery producers in Italy seeking processing parity with wheat flour without premium ingredient costs. These systems dominate current volume due to supply chain maturity and equipment compatibility.
- Protein-based:Pea, rice, and wheat-free oat proteins replicate gluten's viscoelastic network through film-forming and gelling functionality. Clean-label positioning in Germany and France commands premium pricing, with manufacturers pursuing dual protein content and gluten-free claims driving fastest category expansion.
- Fiber-based:Soluble fibers from chicory, psyllium, and citrus peel enhance water binding and digestive health positioning. Premium snack applications in the United States favor these systems for dual-functionality claims.
- Other:Hydrocolloid blends and enzymatic systems address specialized extrusion and frozen dough stability requirements.
Starch-based replacers hold the largest share; momentum sits with protein-based alternatives.
Ingredient Source:
Cost tier stratification separates commodity plant inputs from qualified animal-derived and precision-fermented synthetic alternatives.
- Plant-based:Pea, rice, fava bean, and cassava proteins plus root and tuber starches constitute the dominant sourcing category. Supply security concerns are accelerating captive cultivation agreements in North American and European processing corridors.
- Animal-based:Egg white proteins and dairy-derived ingredients serve niche premium applications requiring superior foaming and emulsification performance. Limited adoption reflects vegan positioning conflicts and allergen labeling complexity.
- Synthetic:Precision-fermented proteins and chemically modified starches offer batch-to-batch consistency unavailable in agricultural supply chains. Regulatory navigation requirements constrain deployment to manufacturers with dedicated compliance infrastructure.
- Others:Algae-derived and microbial fermentation products occupy emerging positioning for novel protein claims.
Plant-based sourcing commands volume leadership; synthetic alternatives are climbing the fastest on consistency premiums.
Application:
Volume concentration patterns favor baked goods while pasta and dairy alternatives present underpenetrated expansion vectors.
- Baked Goods:Bread, cakes, cookies, and pastries require tailored replacer systems matching specific crumb structure and shelf-life targets. Germany and Italy concentrate reformulation investment as legacy wheat-dependent producers face clean-label deadline pressure.
- Snacks:Extruded and sheeted snack products demand thermal stability and expansion control distinct from baked applications. Premium positioning in the United States favors fiber-based systems with digestive health dual claims.
- Pasta:Durum wheat replacement in extruded noodles presents technical barriers around cooking loss and texture retention that protein-heavy formulations are beginning to address.
- Dairy Alternatives:Cheese analogs and fermented plant-based products utilize gluten replacers for melt and stretch functionality, though this remains a peripheral application.
Baked goods hold the largest share; pasta applications show steepest expansion trajectory on structural performance gaps.
Distribution Channel:
Customer type segmentation separates formulation-naive buyers requiring bundled technical service from sophisticated manufacturers seeking ingredient-only supply.
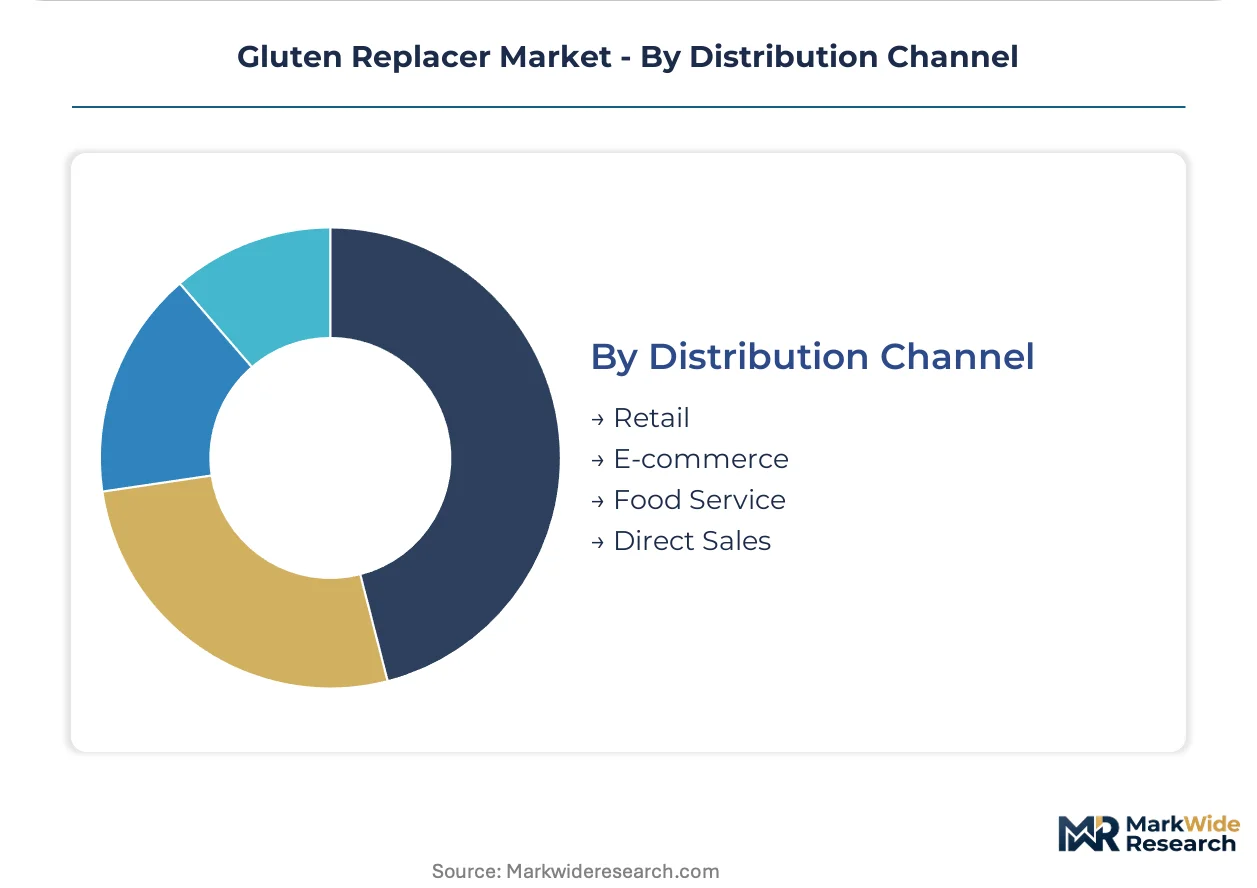
- Retail:Packaged consumer goods manufacturers purchase through distributor networks with attached application laboratories. Regional bakery cooperatives in Italy consolidate procurement through shared technical facilities.
- E-commerce:Digital procurement platforms bypass traditional distribution layers for mid-tier producers with in-house formulation capability.
- Food Service:Commercial bakery and restaurant chain operators demand consistent performance across dispersed production locations, favoring qualified supplier relationships over price optimization.
- Direct Sales:Large-scale manufacturers negotiate captive supply agreements with integrated taste-and-nutrition platforms for proprietary formulation access.
Retail channels hold the largest share; direct sales are gaining share fastest on consolidation among contract manufacturers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across major markets. Germany and Italy prioritize protein-based replacers for premium clean-label positioning, while the United States concentrates demand in fiber-enhanced systems for dual health claims. Starch-based alternatives retain volume leadership in cost-sensitive segments across all three markets.
United States
FDA gluten-free labeling standards drive reformulation investment among packaged goods manufacturers. The agency's strict thresholds force bakery producers to requalify supplier networks and ingredient sourcing. Chicago and Minneapolis processing corridors concentrate contract manufacturing capacity for national retail brands.
Germany
Clean-label bakery lines command premium shelf positioning, accelerating protein-based replacer adoption for viscoelastic performance. REACH substance restrictions and EFSA safety assessments reshape hydrocolloid eligibility lists. Munich and Stuttgart industrial clusters anchor captive sourcing agreements for compliant ingredient pipelines.
Italy
Legacy wheat-dependent pasta and bakery producers face deadline pressure for gluten-free line extensions. EU FIC Regulation disclosure requirements determine shelf placement eligibility across retail channels. Bologna and Parma food technology hubs consolidate shared formulation laboratories for mid-tier cooperative producers.
France
Premium snack and frozen dough segments favor fiber-based systems with digestive health dual claims. EFSA evolving definitions of "very low gluten" versus "gluten-free" complicate cross-border formulation strategies. Lyon and Rennes processing centers internalize rheology expertise through regional technical service partnerships.
Canada
Health Canada gluten-free standards constrain ingredient selection protocols for multi-jurisdiction product lines. Cross-border qualification requirements fragment supplier approval timelines for North American integrated manufacturers. Toronto and Montreal corridor concentrates specialty starch processing for bakery and snack applications.
Gluten Replacer Market Competitive Landscape
Capability concentration sits with integrated taste-and-nutrition platforms; scale advantage sits with commodity starch and protein processors. The market structures around three tiers: global ingredient conglomerates with captive supply chains, mid-cap specialty formulators with regional technical service depth, and emerging precision-fermentation players targeting batch-to-batch consistency premiums. Dominant competitive moves include backward integration into plant-protein cultivation and acquisition of formulation science talent pools.
Within the integrated platform tier, Kerry and ADM occupy positions spanning ingredient sourcing through finished-formulation services. Ingredion exemplifies the scale-driven specialty starch archetype with established processing familiarity advantages. Roquette represents the plant-protein vertical, anchoring European supply security through regional processing corridor presence.
| Leading Market Players |
|---|
| Kerry |
| Ingredion |
| ADM |
| Cargill |
| Tate & Lyle |
| CP Kelco |
| Roquette |
| Glanbia |
| Puris |
| Others |
Value Network & Pricing Analysis
Munich and Stuttgart industrial clusters anchor captive sourcing agreements for compliant ingredient pipelines, translating regional processing concentration into asymmetric pricing power for protein-based replacer suppliers. FDA gluten-free standards and REACH substance restrictions force mid-tier bakery producers to absorb premium qualification costs or exit regulated retail channels.
Pricing Analysis
Long-term offtake agreements dominate procurement between large-scale manufacturers and integrated taste-and-nutrition platforms, insulating premium tiers from agricultural commodity volatility while spot-market exposure concentrates in starch-based alternatives. Price differentiation hinges on certification grade against FDA and EFSA thresholds plus after-sales technical service bundling. Cost compression in mid-tier formulations is intensifying because input cost volatility in specialty starches and plant proteins squeezes margin recovery. Contract manufacturers exhibit lowest price sensitivity due to pass-through mechanisms, whereas regional bakery cooperatives in Italy face acute budget constraints.
Supply Chain Analysis
Contract manufacturing capacity clusters with Kerry, ADM, and Ingredion in North American and European processing corridors, with secondary concentration among Italian and German shared formulation laboratories. Raw material dependencies center on pea and rice protein isolates, modified tapioca and potato starches, and chicory-derived soluble fibers. Single-source vulnerability in premium hydrocolloid sourcing from limited European processing hubs creates qualification bottlenecks during regulatory transition periods. Distribution runs through direct sales channels for large-scale manufacturers and digital procurement platforms for mid-tier producers with in-house formulation capability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enzymatic modification of plant proteins is disrupting premium-tier margin capture, creating acceleration windows for stakeholders who secure formulation science talent and regulatory navigation capabilities ahead of clean-label deadline pressure.
For Market Incumbents: Harden supply security through backward integration into plant-protein cultivation in North American processing corridors, and anchor premium positioning by acquiring formulation laboratories with deep rheology expertise. Emerging precision-fermentation players threaten batch-to-batch consistency premiums, making talent retention in dough microstructure modeling a critical defensive lever. For New Entrants and Emerging Players: Pursue pasta applications as the most penetrable segment, where structural stability requirements in extruded products remain underaddressed by incumbent protein-heavy formulations. Target mid-tier bakery cooperatives in Italy through shared formulation laboratory partnerships, leveraging regulatory navigation capabilities as the primary go-to-market angle against integrated platform incumbents. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-complexity play because evolving definitions of "gluten-free" versus "very low gluten" across FDA, EFSA, and Health Canada jurisdictions fragment formulation strategies and reward suppliers with dedicated compliance infrastructure. Acquisition targets should emphasize mid-cap specialty formulators with regional technical service depth and captive sourcing agreements. Monitor EFSA safety assessment updates as the signal to watch for forced reformulation waves that reshape hydrocolloid eligibility lists.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plant-Protein Cultivation | Secures supply continuity for pea and rice protein isolates amid agricultural commodity volatility. |
| Acquisition of Formulation Science Talent Pools | Addresses rheology expertise gaps that constrain clean-label reformulation timelines for bakery manufacturers. |
| Regulatory Navigation Service Development | Captures margin from divergent FDA, EFSA, and Health Canada gluten-free standard compliance requirements. |
| Shared Formulation Laboratory Partnerships | Consolidates procurement for Italian regional bakery cooperatives lacking in-house R&D scale. |
| Precision-Fermentation Capacity Buildout | Delivers batch-to-batch consistency unavailable in agricultural supply chains for synthetic protein alternatives. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with bakery R&D directors, procurement leads at contract manufacturers, regulatory affairs specialists, and plant-protein sourcing managers; and secondary validation through FDA gluten-free labeling filings, EFSA safety assessment databases, EU FIC Regulation disclosure records, and customs trade data for specialty starch and protein isolate flows. Bottom-up volume modeling triangulated against top-down value estimates from integrated taste-and-nutrition platform disclosures.
Forecast inputs across the analysis window incorporated product type segmentation by rheological performance tier, ingredient source stratification between plant-based and synthetic alternatives, application concentration in baked goods versus pasta expansion vectors, and distribution channel evolution toward direct sales consolidation. CAGRs were derived from regression analysis against clean-label reformulation investment cycles and regulatory deadline schedules, with cross-validation against historical adoption curves for protein-based replacer systems.
Macroeconomic conditions sit as an overlay; deviation in agricultural commodity price indices and transatlantic logistics costs would shift the trajectory for mid-tier producer margin recovery. Quarterly review of EFSA safety assessment update schedules and FDA gluten-free standard enforcement patterns is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
North America Precision Fermentation Market
Alternative Food Sources
Global Konjac Glucomannan Market
Alternative Food Sources
Carragean Alternatives Market
Alternative Food Sources
Fish Meal Alternative Market
Alternative Food Sources
North America Insect Protein Market
Alternative Food Sources
North America Fat Replacers Market
Alternative Food Sources
Hemp-Based Products Market
Alternative Food Sources
Europe Algae Protein Market
Alternative Food Sources
Global Algal Oil Market
Alternative Food Sources
Bagasse Disposable Cutlery Market
Alternative Food Sources
Asia-Pacific Meal Replacement Products Market
Alternative Food Sources
Flaxseed Based Egg Replacement Market
Alternative Food Sources
Algal Protein Market
Alternative Food Sources
Emergency Food Market
Alternative Food Sources
Products from Food Waste Market
Alternative Food Sources
Asia-Pacific Fat Replacers Market