
 Marine Hyaluronic Ingredients Market | 2026-2036
Marine Hyaluronic Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Hyaluronic Ingredients Market Analytics
Buyer concentration among contract manufacturers is decoupling from traditional pharmaceutical offtake as cosmetics brands build direct sourcing relationships with marine extract suppliers. Croda International Plc leverages its lipid chemistry heritage to secure long-term algae cultivation partnerships. Shiseido Company, Limited anchors its marine biotechnology program through proprietary fermentation protocols in Yokohama. BASF SE competes by extending its biopolymer portfolio into cold-process marine derivatives for clean-label formulators.
Marine hyaluronic ingredients comprise glycosaminoglycan fractions extracted from fish cartilage, seaweed matrices, or mollusk connective tissue, typically yielding molecular weights from 50 kDa to 2,000 kDa depending on enzymatic hydrolysis conditions; these biopolymers function primarily as humectants and tissue-support matrices in topical and ingestible applications. Powder formats dominate current bulk shipments due to stability advantages in ambient storage, while gel preparations capture expanding margin pools in medical-grade dermatology applications. Algae-derived sources are gaining fastest traction among nutraceutical compounders seeking vegan positioning, though fish-derived fractions retain cost advantages for high-molecular-weight pharmaceutical grades.
REACH registration requirements in Europe and ECHA guidance on marine biopolymer hazard classification are elevating documentation burdens for importers, while FDA oversight of cosmetic ingredient safety through MoCRA provisions is reshaping U.S. market access protocols. Korea's MFDS has tightened microbial specification limits for marine-derived cosmetic actives, pressuring smaller suppliers toward certified contract manufacturing. Stakeholders must monitor regulatory divergence between cosmetic and pharmaceutical classification pathways as jurisdictions refine biopolymer sourcing disclosure mandates.
Market Dynamics
Direct sourcing relationships between cosmetics brands and marine extract suppliers are bypassing traditional pharmaceutical distributors, compressing intermediary margins while concentrating procurement power among vertically integrated formulators in East Asian coastal zones.
Growth Catalysts
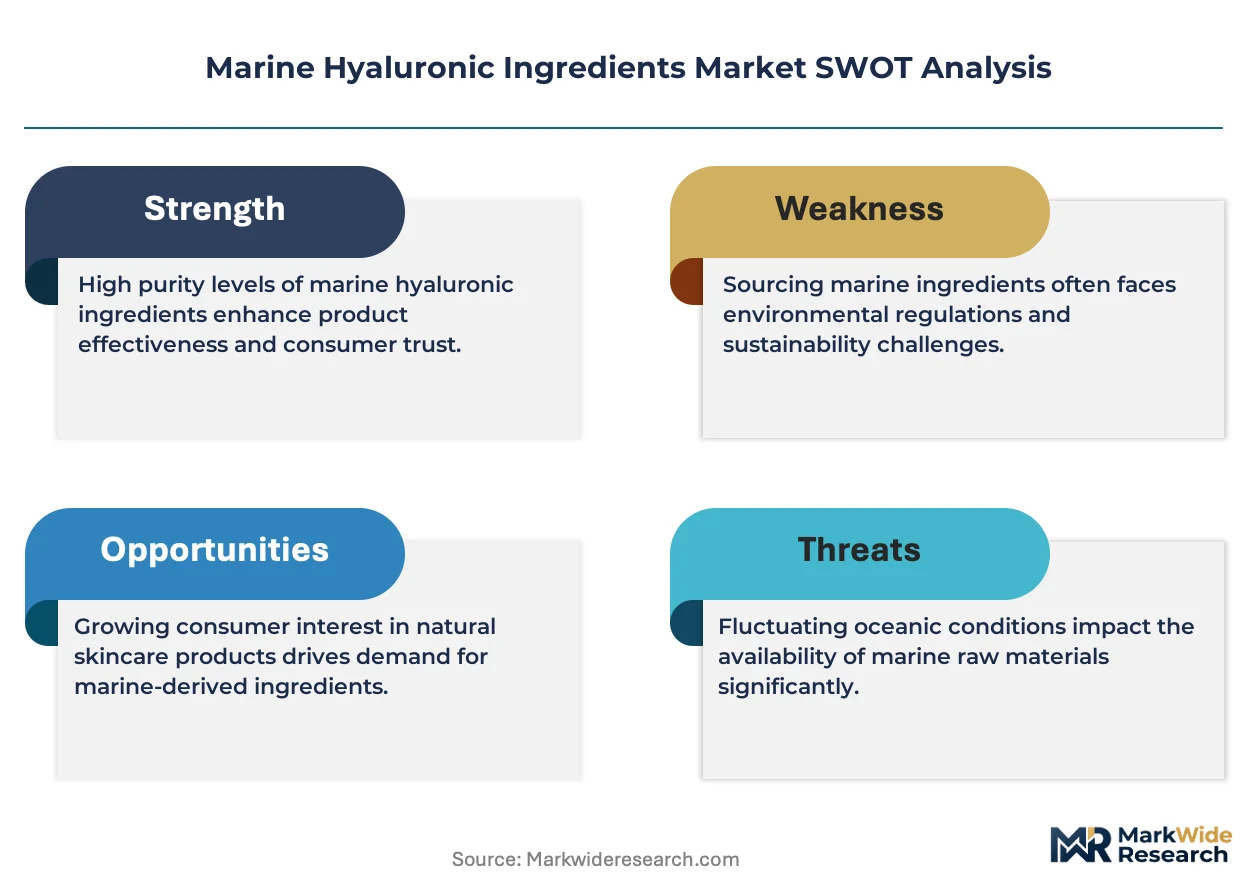
- REACH registration tiers:ECHA's refined biopolymer classification protocols are filtering out low-purity suppliers, creating premium positioning for compliant producers serving European cosmetic compounders.
- Algae fermentation scale-up:Photosynthetic cultivation systems in Qingdao and Busan are yielding vegan-certified hyaluronic acid fractions that nutraceutical brands are specifying for clean-label positioning.
- MFDS microbial standards:Korea's tightened specification limits for marine-derived cosmetic actives are accelerating consolidation toward certified contract manufacturers with in-house testing capabilities.
Market Restraints
- Fish cartilage supply volatility:Wild catch quotas in North Atlantic fisheries are constraining raw material availability for high-molecular-weight pharmaceutical grades.
- East Asian processing concentration:Over 60% of enzymatic hydrolysis capacity sits within 200 kilometers of Busan and Qingdao, exposing buyers to port congestion and regional climate disruption.
- Enzymatic hydrolysis yield ceilings:Current batch processing protocols cap molecular weight precision at 50 kDa increments, limiting customization for medical-grade dermatology applications.
Strategic Opportunities
- Indian pharmaceutical formulation:CDSCO's accelerated approval pathways for biopolymer excipients are opening access to generic injectable manufacturers in Hyderabad and Ahmedabad.
- MoCRA compliance services:FDA's cosmetic ingredient safety disclosure mandates are creating advisory revenue streams for laboratories capable of marine biopolymer toxicology documentation.
- Cold-process gel stabilization:Converging advances in lipid encapsulation and ambient-temperature crosslinking are enabling clean-label medical-grade preparations without thermal degradation.
Industry Challenges
- Fermentation protocol standardization:ISO quality benchmarks for marine-derived hyaluronic acid lack harmonized test methods, forcing suppliers to maintain multiple certification tracks for different export markets.
- Specialized enzymology talent:Shortages of process engineers with dual expertise in marine biochemistry and GMP manufacturing are extending facility commissioning timelines by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Hyaluronic Ingredients Market |
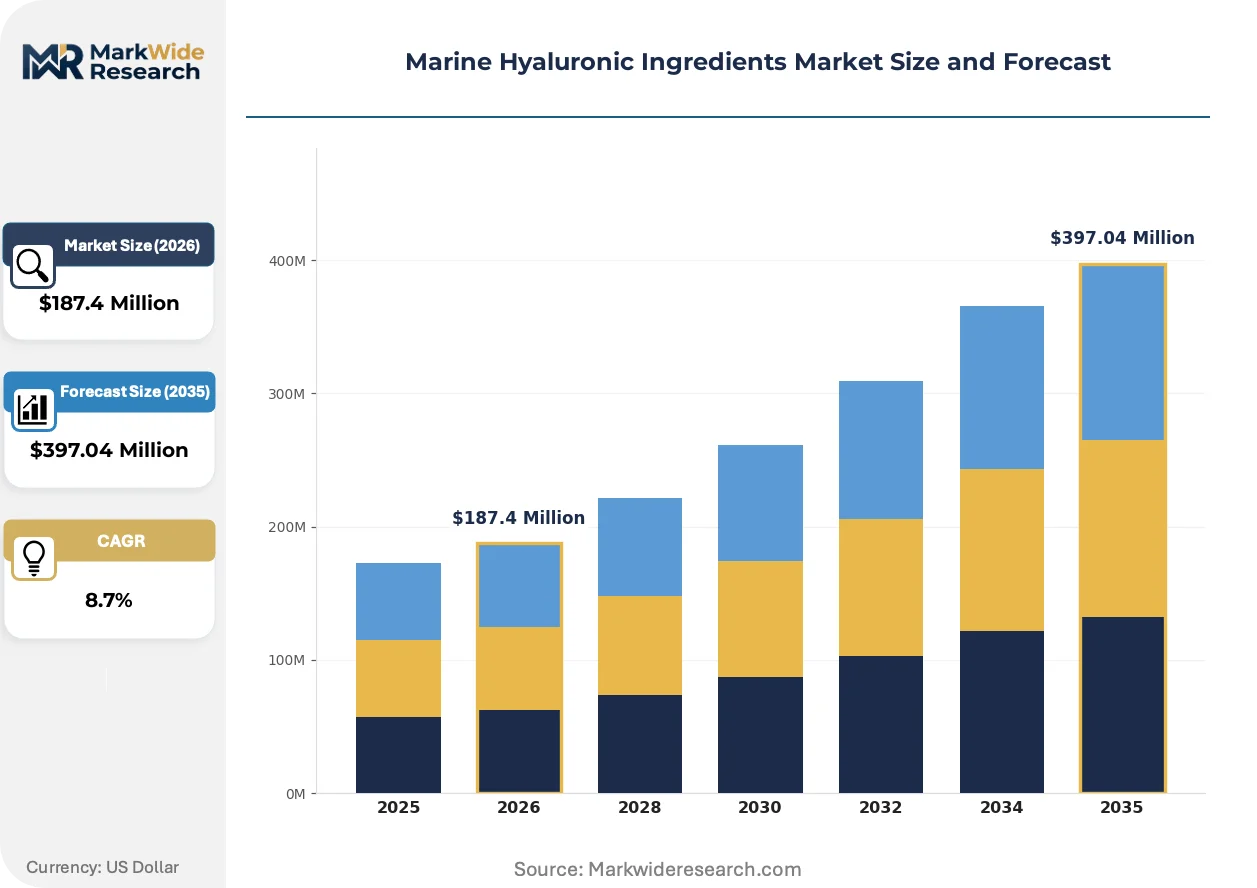
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Gel, Granule Application: Dermatology, Cosmetics, Nutraceuticals, Pharmaceuticals End User: Contract Manufacturers, Retailers, Wholesalers, Healthcare Providers Source: Fish, Seaweed, Shellfish, Algae |
| Companies Covered | L'Oréal, Estée Lauder Companies, Shiseido Company, Limited, Croda International Plc, BASF SE, Bloomage Biotechnology Corporation Limited, Merz Pharma GmbH & Co. KGaA, LG Household & Health Care Ltd., Seppic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Hyaluronic Ingredients Market Evolving Landscape
Biotechnology advances in enzymatic specificity and algae strain optimization are compressing production cycles while regulatory disclosure mandates are reshaping supplier qualification protocols across cosmetic and pharmaceutical channels.
Precision enzymatic hydrolysis is rewriting molecular weight customization capabilities for marine hyaluronic suppliers. Cosmetic formulators in Seoul and Tokyo are specifying narrow 100-300 kDa ranges for premium serum applications. This specificity is compressing commodity powder margins while expanding contract manufacturing premiums for validated batch documentation.
REACH Article 33 disclosure requirements for biopolymer hazard classification are elevating documentation burdens for European importers. ECHA guidance on marine-derived substance categorization is forcing suppliers to retrofit toxicology dossiers. Medical-grade dermatology segments are responding by consolidating procurement among REACH-registered producers with established safety data packages.
Direct platform contracting between cosmetics brands and marine extract cultivators is displacing traditional pharmaceutical distributor networks. Premium skincare lines in South Korea are negotiating multi-year offtake agreements with Busan-based algae processors. This channel compression is most visible in East Asian markets where vertical integration yields faster batch traceability than layered distribution.
Marine Hyaluronic Ingredients Market Segmentation
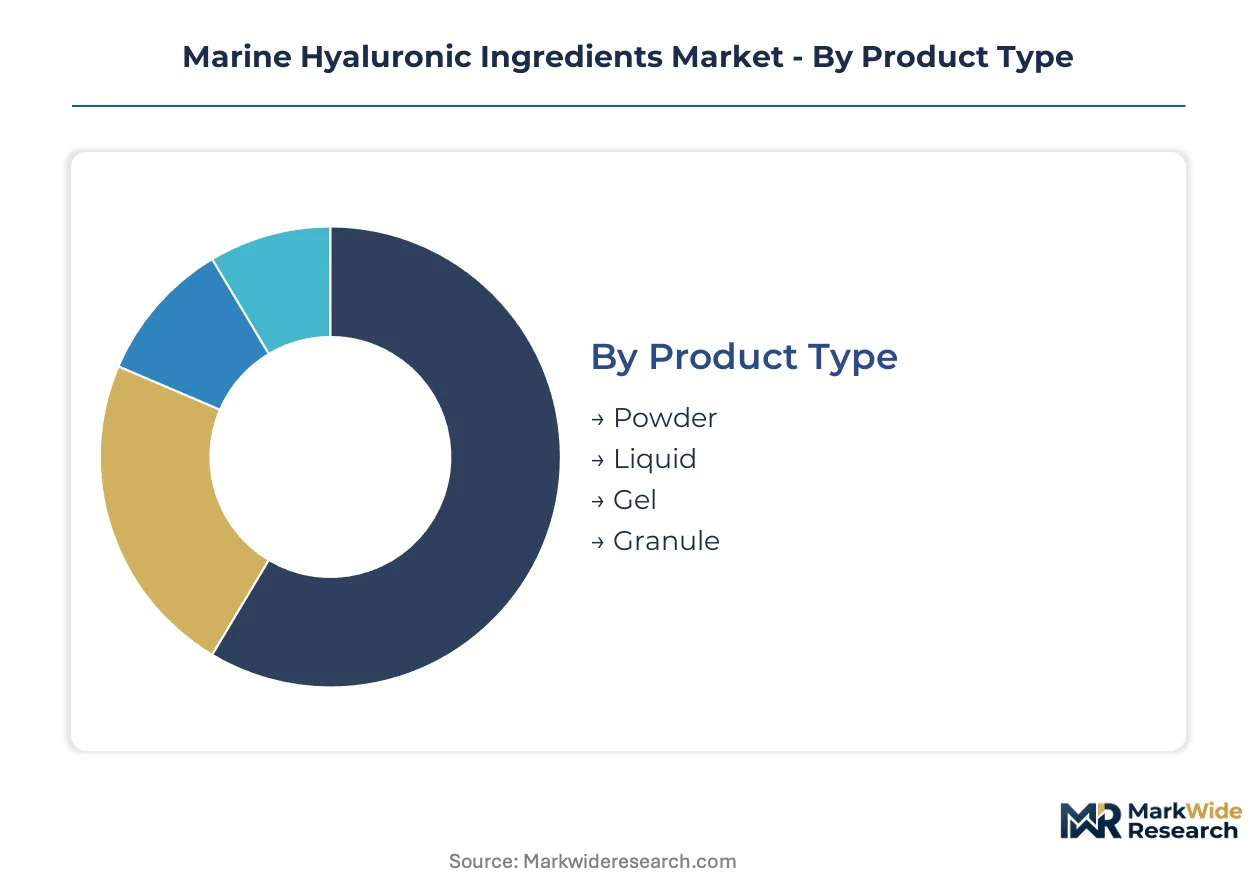
Marine hyaluronic ingredients fragment across four distinct taxonomies that determine pricing power, regulatory pathway, and customer access. Product format dictates stability economics and shipping logistics. Application verticals separate pharmaceutical-grade purity requirements from cosmetic flexibility. Source origin anchors vegan positioning against cost-competitive fish derivatives. End-user channel structure is compressing as brands bypass distributors for direct cultivation contracts.
Product Type:
Powder and liquid formats concentrate enzymatic hydrolysis capacity around Busan and Qingdao processing clusters, while gel and granule derivatives command premium positioning through specialized stabilization protocols.
- Powder:Spray-dried glycosaminoglycan fractions with 18-24 month ambient stability dominate bulk pharmaceutical procurement. Demand concentrates among Japanese and Korean injectable manufacturers seeking validated cold-chain alternatives.
- Liquid:Buffered aqueous solutions with preservative systems serve cosmetic compounders requiring direct formulation integration. South Korean serum manufacturers in Seoul and Incheon specify narrow viscosity ranges for premium skincare lines.
- Gel:Crosslinked preparations for medical-grade dermatology applications requiring sustained tissue residence.
- Granule:Free-flowing agglomerates for nutraceutical encapsulation and tablet compression processes.
Powder absorbs the bulk of installed capacity; gel is expanding most quickly.
Application:
Cosmetics and dermatology applications concentrate procurement power among vertically integrated East Asian formulators, while nutraceuticals and pharmaceuticals face divergent purity documentation burdens.
- Cosmetics:Topical humectant formulations spanning serums, creams, and masks leverage molecular weight customization for texture engineering. Premium skincare brands in Seoul negotiate direct offtake agreements with Busan-based algae processors, bypassing traditional distributor networks.
- Dermatology:Injectable and implantable tissue-support matrices demand validated endotoxin documentation and batch-to-batch molecular weight precision. Medical-grade specifications in Japan and South Korea require PMDA and MFDS facility inspections respectively.
- Nutraceuticals:Ingestible joint health and skin hydration supplements favor algae-derived vegan positioning for clean-label differentiation.
- Pharmaceuticals:Excipient and active pharmaceutical ingredient grades for ophthalmic and arthritic indications requiring full toxicology dossiers.
Cosmetics absorbs the bulk of installed capacity; nutraceuticals is climbing the fastest.
End User:
Contract manufacturers capture volume concentration through certified GMP facilities, while retailer and wholesaler channels face margin compression from direct brand-procurement relationships.
- Contract Manufacturers:Toll production facilities with in-house enzymatic hydrolysis and ISO quality certification serve multiple cosmetic and pharmaceutical brands. Korean and Chinese certified contractors are consolidating market access as MFDS and NMPA tighten facility inspection protocols.
- Retailers:Direct-to-consumer channels for finished nutraceutical and cosmetic products, increasingly bypassed by brand-owned e-commerce.
- Wholesalers:Traditional pharmaceutical and cosmetic ingredient distributors facing displacement from platform contracting.
- Healthcare Providers:Hospital and clinic procurement of medical-grade dermatology preparations for professional administration.
Contract manufacturers absorb the bulk of installed capacity; healthcare providers is gaining share fastest.
Source:
Fish-derived fractions retain cost advantages for high-molecular-weight pharmaceutical grades, while algae cultivation scales to challenge vegan-certified positioning in nutraceutical channels.
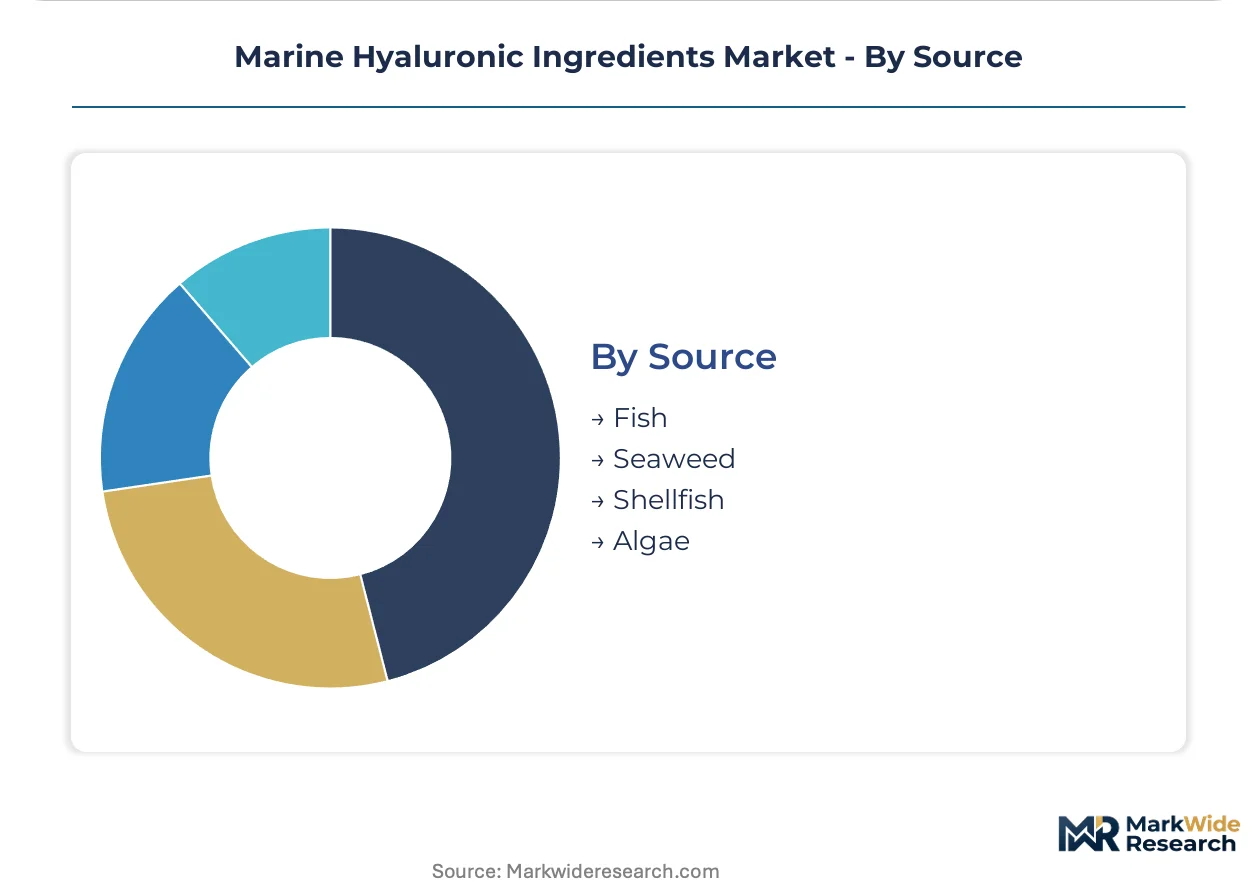
- Fish:Cartilage and connective tissue extraction from North Atlantic and Pacific fisheries yields cost-competitive high-molecular-weight fractions. Wild catch quotas constrain raw material availability for pharmaceutical-grade production.
- Algae:Photosynthetic and fermentation-based cultivation in Qingdao and Busan coastal zones delivers vegan-certified hyaluronic acid for clean-label nutraceutical positioning. Strain optimization programs are compressing production cycles.
- Seaweed:Brown and red macroalgae matrices requiring specialized enzymatic liberation protocols for glycosaminoglycan recovery.
- Shellfish:Mollusk connective tissue extraction with niche positioning in marine collagen co-product streams.
Fish absorbs the bulk of installed capacity; algae is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cosmetics brands in South Korea and Japan are consolidating direct procurement relationships with coastal marine extract processors, while regulatory divergence between ECHA and FDA frameworks is fragmenting supplier qualification protocols across export markets.
South Korea
Seoul-based premium skincare manufacturers are negotiating multi-year offtake agreements with Busan algae processors for vegan-certified hyaluronic acid fractions. MFDS tightened microbial specification limits for marine-derived cosmetic actives in 2023, pressuring smaller suppliers toward certified contract manufacturers with in-house testing capabilities. The Busan-Ulsan coastal corridor hosts over 60% of East Asian enzymatic hydrolysis capacity.
Japan
Shiseido and domestic cosmetics compounders anchor demand for high-molecular-weight pharmaceutical grades requiring PMDA facility inspections. METI biopolymer quality guidelines are converging with ISO benchmarks, elevating documentation burdens for imported raw materials. Yokohama fermentation facilities are scaling proprietary marine biotechnology protocols for medical-grade dermatology applications.
China
Qingdao photosynthetic cultivation systems are yielding algae-derived hyaluronic acid for nutraceutical clean-label positioning. NMPA tightened facility inspection protocols for cosmetic ingredient manufacturers, accelerating consolidation toward GMP-certified toll producers. The Shandong Peninsula processing cluster is expanding cold-chain logistics for temperature-sensitive gel preparations.
Germany
BASF SE and specialty chemical compounders are extending biopolymer portfolios into cold-process marine derivatives for REACH-compliant European formulators. ECHA guidance on marine-derived substance hazard classification is forcing suppliers to retrofit toxicology dossiers for Article 33 disclosure compliance. The Rhine-Ruhr industrial corridor maintains enzymology talent pools for precision hydrolysis process engineering.
United States
FDA MoCRA cosmetic ingredient safety disclosure mandates are reshaping market access protocols for marine biopolymer importers. Clean-label formulators in California and New York are specifying algae-derived vegan positioning for premium skincare lines. Third-party toxicology documentation services are emerging as advisory revenue streams for laboratories capable of marine biopolymer safety assessment.
Marine Hyaluronic Ingredients Market Competitive Landscape
East Asian producers anchor volume supply through coastal fermentation and enzymatic hydrolysis infrastructure; European specialty chemical houses hold premium positioning through REACH-registered safety dossiers and lipid chemistry integration. The vendor base stratifies across three archetypes: vertically integrated cosmetics brands with captive biotechnology programs, toll manufacturers with certified GMP capacity, and diversified chemical conglomerates extending biopolymer portfolios. Dominant competitive moves include direct platform contracting between brands and cultivators, plus cold-process stabilization technology licensing for medical-grade gel applications.
Among Japanese and Korean cosmetics conglomerates, Shiseido Company, Limited and LG Household & Health Care Ltd. exemplify the vertically integrated archetype through proprietary marine biotechnology programs and direct sourcing relationships with coastal processors. European specialty chemical representation includes Croda International Plc and BASF SE, which occupy positions bridging lipid chemistry heritage with biopolymer portfolio extension for compliant formulators. Bloomage Biotechnology Corporation Limited represents the Chinese fermentation scale-up specialist segment, with Qingdao-based photosynthetic cultivation systems serving nutraceutical clean-label demand.
| Leading Market Players |
|---|
| L'Oréal |
| Estée Lauder Companies |
| Shiseido Company, Limited |
| Croda International Plc |
| BASF SE |
| Bloomage Biotechnology Corporation Limited |
| Merz Pharma GmbH & Co. KGaA |
| LG Household & Health Care Ltd. |
| Seppic |
| Others |
Value Network & Pricing Analysis
Sovereign-backed producers in China's Shandong Peninsula and family-owned mid-caps along South Korea's Busan-Ulsan corridor anchor supply discipline through multi-year offtake contracts with Seoul-based cosmetics brands. This ownership pattern concentrates pricing power among vertically integrated formulators while compressing spot-market margins for unaffiliated traders.
Pricing Analysis
Volume concentrates in commodity powder grades while margin pools shift toward medical-grade gel preparations with validated endotoxin documentation. Three-tier pricing structure across premium, standard, and economy levels separates REACH-registered pharmaceutical grades from cosmetic-tier powders and uncertified bulk feedstock. Cost compression in standard-grade powders is intensifying because Busan-based algae processors are scaling photosynthetic cultivation capacity. Contract manufacturers exhibit the highest price sensitivity due to thin toll-processing margins, while dermatology clinics purchasing medical-grade preparations show minimal elasticity.
Supply Chain Analysis
Single-source vulnerability sits with enzymatic hydrolysis capacity concentrated within 200 kilometers of Busan and Qingdao. Raw material flows draw from North Atlantic fish cartilage fisheries, Qingdao algae cultivation ponds, and Shandong seaweed processing cooperatives. Supply chain risk centers on port congestion exposure at Busan container terminals during typhoon season. Distribution runs through certified GMP toll manufacturers serving multiple cosmetic and pharmaceutical brands, with direct platform contracting displacing traditional pharmaceutical distributors for premium skincare lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where ECHA REACH registration tiers and Korea MFDS microbial standards erect barrier-to-entry moats favoring incumbent producers with established toxicology dossiers and in-house testing capabilities.
For Market Incumbents: To counter margin compression from Qingdao algae processors scaling vegan-certified production, incumbent suppliers should deepen backward integration into proprietary fermentation protocols and expand cold-process gel stabilization licensing for medical-grade dermatology applications. Securing multi-year offtake agreements with Seoul premium skincare brands locks in volume before channel compression accelerates. For New Entrants and Emerging Players: Contract manufacturers in India present the most penetrable entry point, where CDSCO accelerated approval pathways for biopolymer excipients in Hyderabad and Ahmedabad remain underdeveloped relative to East Asian certification density. New entrants should anchor initial positioning through MoCRA compliance advisory services for U.S. cosmetic ingredient importers lacking marine biopolymer toxicology documentation capabilities. For Investors and Strategic Acquirers: Distressed-cycle entries favor certified GMP toll manufacturers in South Korea facing MFDS facility inspection cost burdens, where consolidation toward scaled operators creates acquisition targets with embedded customer relationships across Japanese and Korean cosmetics conglomerates. The signal to watch is regulatory divergence between ECHA and FDA disclosure mandates, which could bifurcate supplier qualification protocols and strand non-compliant assets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Algae Cultivation | Qingdao and Busan coastal processors secure captive vegan-certified feedstock for clean-label nutraceutical positioning. |
| Cold-Process Gel Stabilization Licensing | Lipid encapsulation advances enable medical-grade dermatology preparations without thermal degradation of glycosaminoglycan fractions. |
| REACH-Registered Safety Dossier Investment | ECHA Article 33 compliance creates premium positioning for European cosmetic compounders filtering out low-purity suppliers. |
| Direct Platform Contracting with Brands | Seoul skincare manufacturers bypass pharmaceutical distributors to negotiate multi-year offtake agreements with Busan processors. |
| MoCRA Compliance Advisory Services | FDA cosmetic ingredient safety mandates generate laboratory revenue streams for marine biopolymer toxicology documentation. |
Research Methodology
Document review covered regulatory filings with ECHA and FDA, trade customs data for glycosaminoglycan imports, and MFDS facility inspection records, complemented by interviews with marine biotechnology R&D directors, cosmetic formulation chemists at Seoul and Tokyo headquarters, contract manufacturing procurement leads in Busan and Qingdao, and dermatology clinic purchasing administrators. Secondary sources included REACH registration databases, CDSCO biopolymer excipient approval trackers, and PMDA medical-grade substance safety assessments. Bottom-up volume estimates from enzymatic hydrolysis capacity installations were cross-referenced against top-down demand aggregation from cosmetics brand procurement disclosures.
Cross-referencing historical batch production records against expert panel input from algae cultivation specialists and precision enzymology engineers informed the analytical framework. Segmentation dimensions modeled spanned product format, application vertical, source origin, and molecular weight tier alongside regional regulatory cluster differentiation. CAGRs were derived through iterative reconciliation of supply-side capacity expansion timelines with demand-side brand formulation pipeline visibility, incorporating strain optimization yield improvements and cold-chain logistics cost trajectories as industry-specific forecast inputs.
Caveats apply where wild catch quota reductions in North Atlantic fisheries, ECHA reclassification of marine-derived biopolymers, or MFDS microbial specification tightening could materially shift the outlook for high-molecular-weight pharmaceutical grade availability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Rice Bran Oil Market
Ingredients
Corn Oil Cake Market
Ingredients
Beetroot Powder Market
Ingredients
Potato Protein Market
Ingredients
Omega-3 Encapsulation Market
Ingredients
APAC Savoury Ingredients Market
Ingredients
Plant Based Premix Market
Ingredients
Refined Coconut Oil Market
Ingredients
Rapid-Set Gelatin Market
Ingredients
North America Whey Protein Ingredients Market
Ingredients
Ingredients Market
Ingredients
Edible Fiber Market
Ingredients
Vegetable Powder Market
Ingredients
United States Whey Protein Ingredients Market
Ingredients
North America Cocoa Products Market
Ingredients
Alcohol Ingredients Market