
 Sugar Alternative Market | 2026-2036
Sugar Alternative Market Size, Share, and Industry Trends Forecast 2026-2036
Sugar Alternative Market Outlook
Food-grade certification upgrades toward non-GMO and organic specifications is unwinding legacy commodity positioning across the sugar alternative supply base. Cargill, Incorporated leverages its integrated stevia supply chain from Latin American cultivation through extraction to secure consistent botanical purity. Tate & Lyle PLC anchors its competitive stance through specialized expertise in rare sugar enzymatic conversion, particularly allulose production. Roquette Frères differentiates via deep specialization in polyol manufacturing, controlling fermentation-derived erythritol capacity at scale.
Sugar alternatives encompass non-nutritive and low-caloric sweetening compounds—steviol glycosides, sugar alcohols, and rare sugars—typically manufactured through botanical extraction, enzymatic biotransformation, or catalytic hydrogenation processes, formulated to replicate sucrose sensory profiles while reducing glycemic impact in finished foods and beverages. Stevia-derived sweeteners lead product type value contribution due to concentrated potency and expanding GRAS-affirmed applications, while erythritol occupies the fastest-expanding position driven by cooling-effect compatibility in confectionery and beverage systems. Application segmentation shows beverages commanding the largest volume absorption as carbonated soft drink and ready-to-drink tea manufacturers execute portfolio-wide sugar reduction commitments.
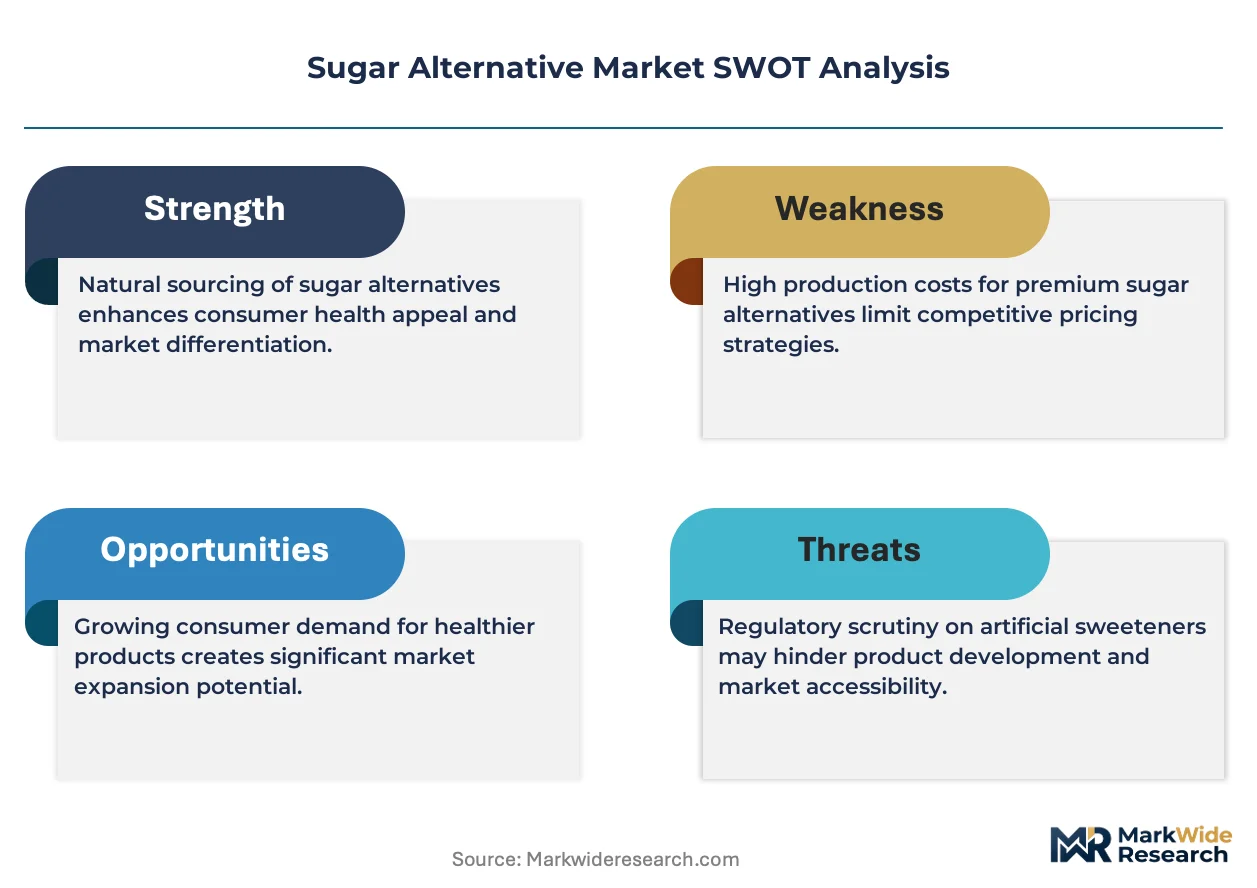
The FDA's Nutrition Facts label overhaul mandating added sugars disclosure has reshaped procurement priorities for food manufacturers seeking compliant reformulation pathways, while the USDA's BioPreferred program and EPA sustainability guidelines increasingly influence supplier qualification criteria for botanical-derived alternatives. EFSA's ongoing evaluations of novel sweetener safety profiles and purity specifications continue to modulate market access conditions for European-bound ingredients. Stakeholders must monitor evolving regulatory thresholds for acceptable daily intake revisions and emerging front-of-pack labeling schemes that directly reward deeper sugar substitution.
Market Dynamics
Beverage manufacturers' portfolio-wide sugar reduction commitments are compressing procurement timelines and forcing rapid reformulation cycles across the supply base. The FDA's added sugars disclosure mandate has transformed label compliance from a secondary consideration into a primary procurement filter.
Growth Catalysts
- US FDA Labeling Mandate:The Nutrition Facts overhaul requiring added sugars disclosure is accelerating clean-label ingredient substitution across carbonated soft drink and ready-to-drink tea portfolios.
- Stevia Extraction Refinement:Advances in steviol glycoside purification are expanding GRAS-affirmed applications into bakery and dairy systems previously resistant to botanical sweeteners.
- Beverage Industry Consolidation:Multi-brand beverage conglomerates are deploying unified sugar reduction specifications across regional product lines, creating concentrated demand pull for high-volume alternative suppliers.
Market Restraints
- Raw Material Concentration:Stevia leaf cultivation concentrates in Paraguay and China, exposing processors to climate volatility and geopolitical friction in concentrated supply corridors.
- Enzymatic Production Costs:Rare sugar manufacturing via enzymatic biotransformation requires specialized fermentation capacity with high capital intensity and lengthy qualification periods.
- Aftertaste Engineering Limitations:Lingering bitter or metallic off-notes in high-potency sweeteners restrict substitution rates in delicate flavor systems like flavored waters and premium juices.
Strategic Opportunities
- Allulose Regulatory Expansion:EFSA's ongoing novel food evaluations create pathway for European market entry if safety dossiers achieve favorable determinations.
- Confectionery Cooling Effect:Erythritol's endothermic dissolution properties align with sugar-free chocolate and mint category expansion where texture and mouthfeel differentiation command premium positioning.
- Direct-to-Manufacturer Platforms:Digital ingredient marketplaces are compressing procurement layers between botanical extractors and mid-size food manufacturers previously dependent on distributor networks.
Industry Challenges
- Cross-Functional Formulation Expertise:Shortage of professionals combining food science, regulatory affairs, and sensory evaluation skills slows reformulation velocity for mid-tier manufacturers.
- Organic Certification Backlogs:USDA National Organic Program accreditation timelines for new stevia processing facilities extend months beyond conventional certification, delaying premium product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sugar Alternative Market |
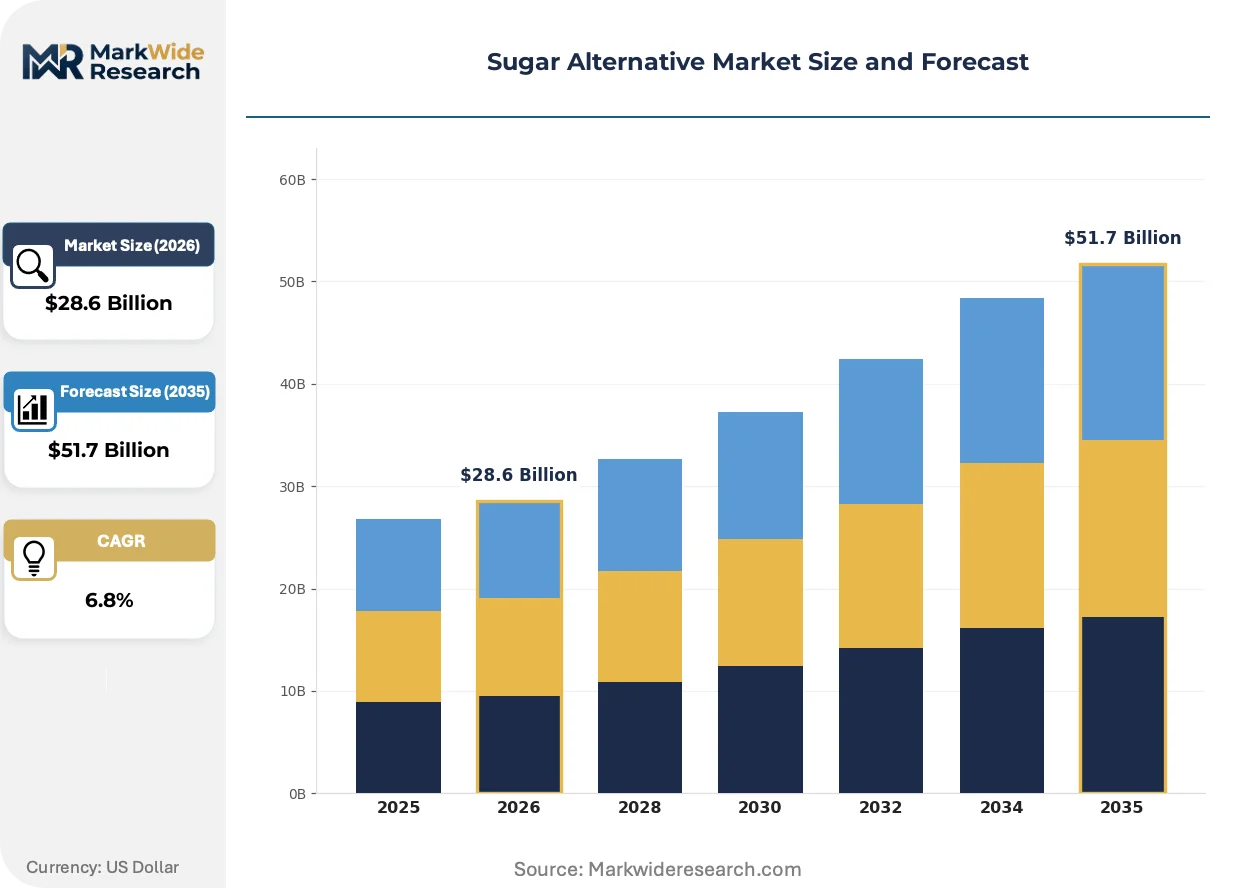
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stevia, Erythritol, Xylitol, Agave Syrup Application: Beverages, Bakery, Dairy Products, Confectionery Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Wholesale End User: Food Manufacturers, Restaurants, Individual Consumers, Nutraceuticals |
| Companies Covered | Cargill, Incorporated, Archer Daniels Midland Company, Ingredion Incorporated, Tate & Lyle PLC, International Flavors & Fragrances Inc., Roquette Frères, Ajinomoto Co., Inc., DuPont de Nemours, Inc., Celanese Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sugar Alternative Market Strategic Shifts
Biotechnological production methods are displacing traditional extraction and chemical synthesis across the sweetener supply base. Fermentation-derived molecules now achieve parity with botanical extracts on cost and purity metrics.
Precision fermentation for rare sugar production is supplanting catalytic hydrogenation in commercial allulose manufacturing. Ingredient suppliers in South Korea and Japan are scaling enzymatic cell factories to meet beverage industry volume commitments. This biotechnology transition is compressing capital requirements for new market entrants while eroding cost advantages of legacy chemical processors.
EFSA's systematic re-evaluation of sweetener additive specifications is tightening purity thresholds for European-bound ingredients. The regulatory recalibration is forcing extractors to upgrade chromatographic separation capabilities and expand contaminant testing protocols. Botanical-derived suppliers serving EU markets are responding by integrating in-house analytical laboratories previously outsourced to third-party certifiers.
Retail buyer consolidation is compressing supplier negotiation leverage and accelerating long-term contracting preferences. Supermarket private-label expansion in North America and Western Europe is displacing branded ingredient specifications with house-standard sweetness profiles. This procurement centralization is most visible in Germany and the United Kingdom, where discounter chains now dictate formulation parameters across multiple processed food categories.
Sugar Alternative Market Segmentation
Sugar alternative procurement patterns diverge sharply across formulation requirements, distribution pathways, and end-user sophistication. Segment-specific regulatory exposure and sensory performance thresholds create distinct competitive battlegrounds for suppliers.
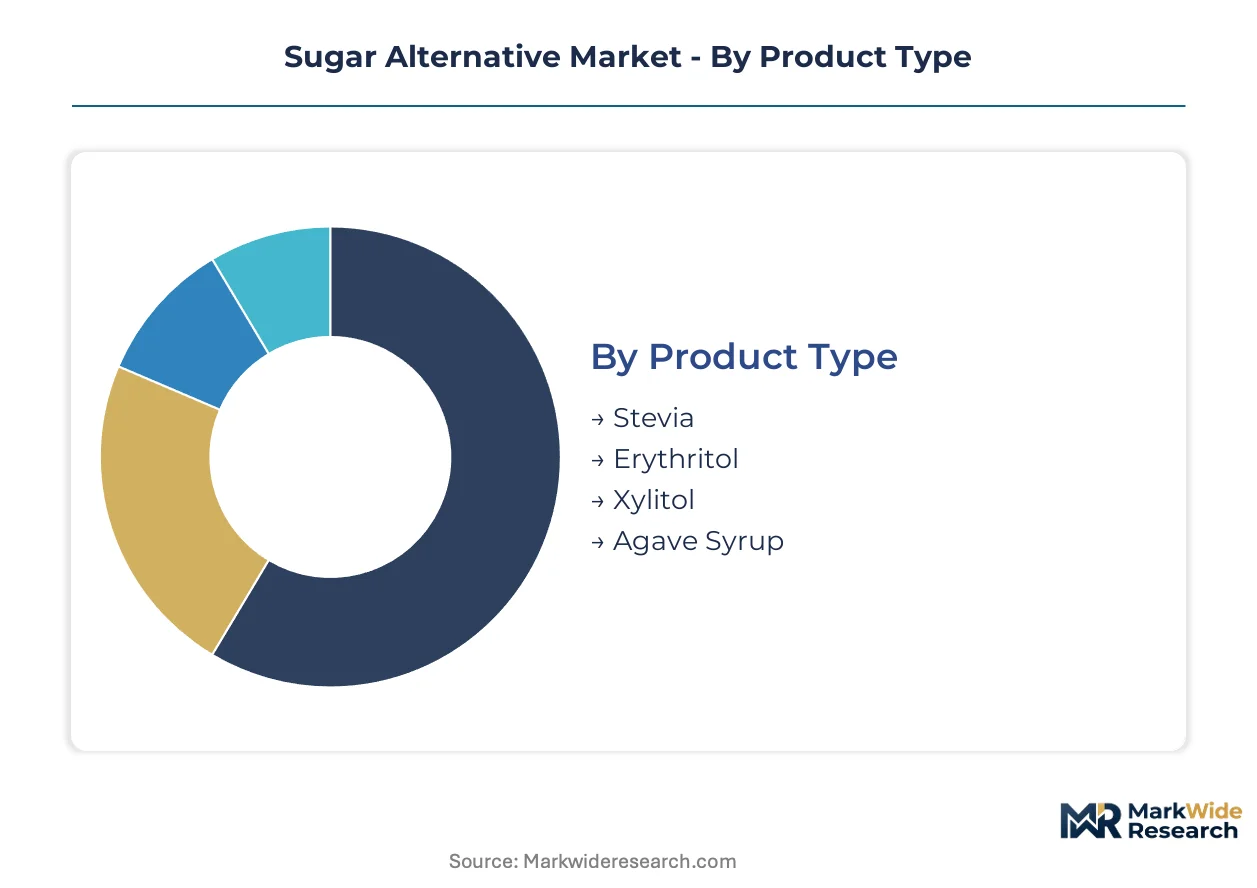
Product Type:
Stevia cultivation concentrates in Paraguay and China for export processing, while erythritol fermentation capacity clusters in domestic US and European manufacturing hubs.
- Stevia:Steviol glycoside extracts deliver high-potency sweetness at 200-400x sucrose equivalence. GRAS-affirmed Reb M and Reb D variants command premium positioning in US beverage reformulations where clean-label positioning drives procurement decisions.
- Erythritol:Fermentation-derived sugar alcohol provides 60-80% sucrose sweetness with negligible caloric contribution and pronounced cooling effect. Confectionery applications in sugar-free chocolate and mint categories absorb expanding volumes as texture engineering improves.
- Xylitol:Birch-derived and corn-cob sourced polyol maintains dental health positioning in chewing gum and oral care adjacent markets.
- Agave Syrup:Blue agave nectar from Jalisco, Mexico serves organic and natural-positioned product lines with lower glycemic index claims.
Stevia holds the largest share; momentum sits with erythritol.
Application:
Cost tier stratification separates premium positioned applications from commodity reformulation targets.
- Beverages:Carbonated soft drinks and ready-to-drink tea systems absorb the highest absolute volumes as PepsiCo and Coca-Cola execute portfolio-wide sugar reduction commitments. The FDA's added sugars disclosure mandate accelerates high-potency sweetener adoption in this category.
- Confectionery:Sugar-free chocolate, hard candies, and chewing gum leverage erythritol's endothermic dissolution for texture differentiation. Cooling-effect compatibility commands premium positioning in mint and chocolate combinations.
- Bakery:Maillard reaction limitations and moisture retention challenges restrict substitution rates in yeast-leavened and chemically aerated systems.
- Dairy Products:Flavored yogurt and ice cream applications require careful bulking agent coordination to maintain mouthfeel and freezing point depression.
Beverages dominate volume absorption; confectionery is climbing the fastest on cooling-effect premiums.
Distribution Channel:
Customer type fragmentation splits procurement between industrial-scale ingredient sourcing and fragmented retail access.
- Wholesale:Direct manufacturer-to-processor contracting captures bulk volumes for reformulation pipelines, bypassing distributor markups.
- Supermarkets:Retail shelf presence for consumer-packaged stevia and erythritol table-top sweeteners concentrates in Walmart, Kroger, and Aldi private-label expansion.
- Online Retail:Amazon and direct-to-consumer platforms serve specialty diet segments and small-batch food producers.
- Health Food Stores:Whole Foods and regional co-ops maintain organic and non-GMO certification premiums for agave and specialty stevia extracts.
Wholesale commands industrial volume; online retail gains share fastest on mid-tier manufacturer access.
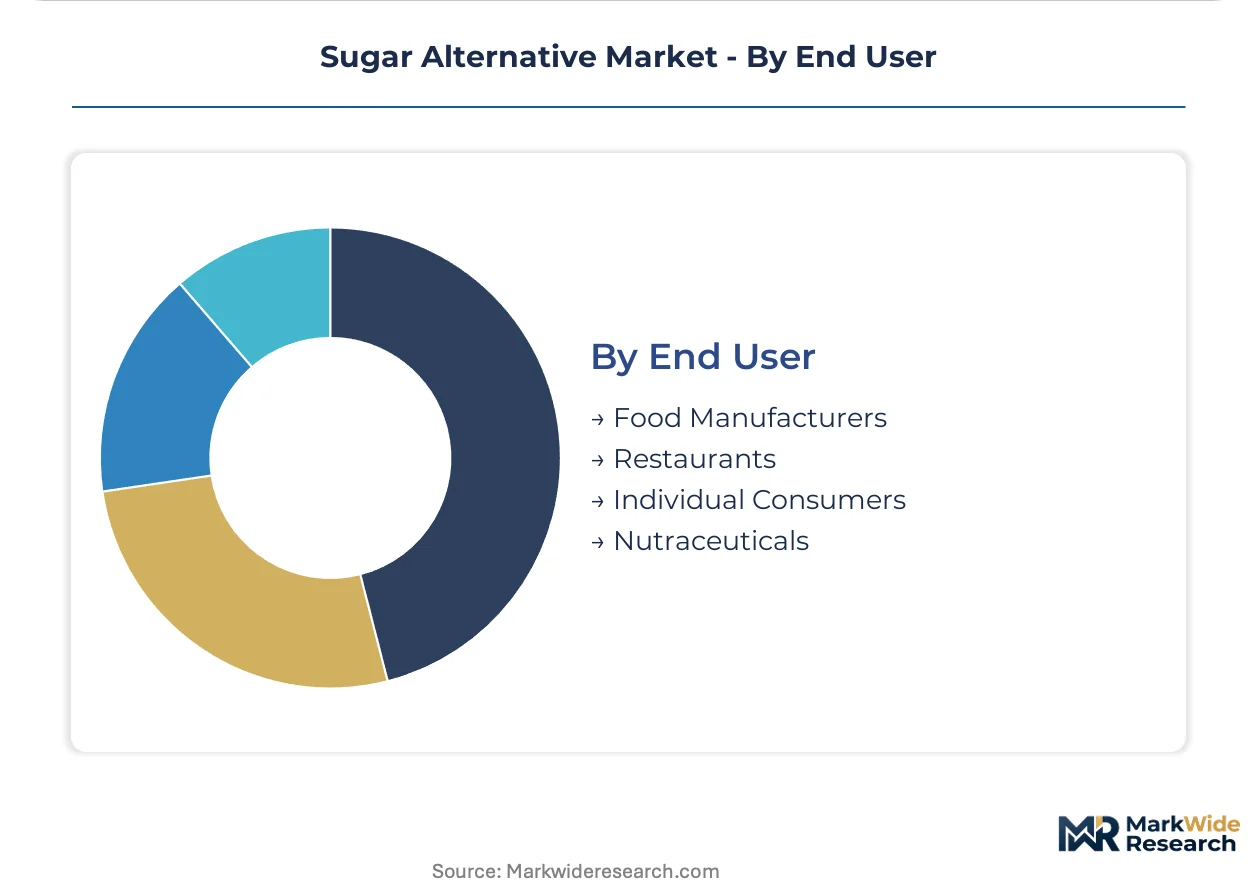
End User:
Supply concentration varies between captive formulation teams and dispersed foodservice operators.
- Food Manufacturers:Nestlé, Unilever, and General Mills maintain dedicated sugar reduction R&D functions with direct supplier relationships.
- Restaurants:Chain operators like Starbucks and Panera Bread deploy standardized beverage syrup specifications across franchise networks.
- Individual Consumers:Keto and diabetic diet adherents drive table-top sweetener purchases through retail and subscription channels.
- Nutraceuticals:Protein powder and meal replacement formulators integrate low-glycemic sweeteners for metabolic health positioning.
Food manufacturers represent the largest procurement base; nutraceuticals is expanding most quickly on functional positioning convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stevia leaf cultivation clusters in Paraguay and China, while erythritol fermentation capacity concentrates in domestic US and European manufacturing hubs. This geographic split between raw material sourcing and downstream processing shapes procurement risk profiles across the supply base.
United States
Beverage manufacturers' portfolio-wide sugar reduction commitments are driving concentrated demand pull from PepsiCo and Coca-Cola reformulation pipelines. The FDA's Nutrition Facts label overhaul mandating added sugars disclosure has transformed procurement priorities toward clean-label alternatives. Chicago and Atlanta anchor beverage industry R&D clusters where high-volume sweetener specifications are negotiated.
China
Domestic stevia leaf processing and erythritol fermentation capacity serve both export markets and growing local sugar reduction demand. The National Health Commission's dietary guidelines emphasizing reduced sugar intake are accelerating reformulation in domestic beverage and dairy sectors. Shandong Province hosts concentrated fermentation-derived polyol manufacturing infrastructure serving global supply chains.
Germany
EFSA's systematic re-evaluation of sweetener additive specifications is tightening purity thresholds for European-bound ingredients. The EU Green Deal's sustainability criteria are increasingly filtering supplier qualification for botanical-derived alternatives. Hamburg and Frankfurt clusters integrate chromatographic separation capabilities for upgraded contaminant testing protocols.
Japan
Enzymatic cell factory technology for rare sugar production is scaling to meet beverage industry volume commitments. METI's support for biotechnology transitions is compressing capital requirements for precision fermentation entrants. The Osaka-Nagoya corridor anchors specialized allulose manufacturing capacity leveraging enzymatic biotransformation expertise.
Brazil
Blue agave nectar cultivation in Jalisco-adjacent supply relationships serves organic and natural-positioned product lines. ANVISA's evolving food additive regulations are modulating market access conditions for imported high-potency sweeteners. São Paulo's food manufacturing corridor concentrates procurement decision-making for South American reformulation pipelines.
Sugar Alternative Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the sugar alternative supply base. The market structure consolidates around integrated agricultural processors, specialized biotech fermenters, and diversified ingredient conglomerates. Three strategic archetypes dominate: stevia cultivators with Latin American upstream control, rare sugar enzymatic specialists, and polyol manufacturers with fermentation scale. Competitive moves center on backward integration into botanical supply and capacity expansion in enzymatic production.
Among diversified agricultural processors, Cargill, Incorporated and Archer Daniels Midland Company occupy positions representing integrated supply chain control from cultivation through extraction. Tate & Lyle PLC exemplifies the specialized enzymatic conversion archetype, while Roquette Frères anchors the fermentation-derived polyol tier. These three players illustrate how geographic origin and corporate structure map to distinct competitive positioning within the alternative sweetener ecosystem.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| Archer Daniels Midland Company |
| Ingredion Incorporated |
| Tate & Lyle PLC |
| International Flavors & Fragrances Inc. |
| Roquette Frères |
| Ajinomoto Co., Inc. |
| DuPont de Nemours, Inc. |
| Celanese Corporation |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between Paraguayan stevia cultivators and US beverage manufacturers lock in both supply access and price visibility across volatile harvest cycles. These arrangements insulate processors from spot-market fluctuations while committing buyers to minimum volume thresholds that sustain cultivation infrastructure.
Pricing Analysis
The FDA's added sugars disclosure mandate dictates the pricing tier structure across the sugar alternative supply base. Three-tier pricing structure across premium, standard, and economy levels separates certified organic stevia extracts from conventional Reb A grades and commodity polyol blends. Cost compression in standard-tier erythritol is intensifying because Chinese fermentation capacity expansion outpaces demand absorption. Food manufacturers with reformulation pipelines represent the most price-sensitive buyers, while premium beverage brands absorb organic certification premiums with minimal negotiation leverage.
Supply Chain Analysis
Container availability constraints on the Shanghai-Los Angeles trade lane disrupt just-in-time delivery schedules for Chinese erythritol shipments. Stevia leaf supply concentrates in Paraguay and China, while fermentation-derived polyol manufacturing clusters in domestic US and Shandong Province facilities. Raw material dependencies span stevia leaf biomass, corn-derived dextrose feedstock, and enzymatic conversion catalysts. Single-source vulnerability in Paraguayan leaf supply exposes processors to climate-induced crop failures. Distribution runs through direct manufacturer-to-processor contracting for industrial volumes, bypassing distributor markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical formulation services represent a service-attach opportunity expanding faster than commodity ingredient sales, as beverage manufacturers outsource reformulation expertise to meet compressed procurement timelines.
For Market Incumbents: Shield margin position by deepening backward integration into Paraguayan stevia cultivation and accelerating in-house chromatographic purification capacity. Precision fermentation entrants threaten cost structures in rare sugar segments. Capacity addition in enzymatic allulose production anchors defensive positioning. For New Entrants and Emerging Players: Differentiate on certified organic supply chain transparency to capture reformulation contracts from mid-tier manufacturers facing USDA National Organic Program backlog delays. The most penetrable segment sits with private-label confectionery producers seeking cooling-effect alternatives. Direct-to-manufacturer digital platforms compress procurement layers. For Investors and Strategic Acquirers: Specialized enzymatic conversion technology holders with pilot-scale allulose capacity offer asymmetric upside if EFSA novel food determinations unlock European market access. Long-term viability hinges on biotechnology transitions displacing legacy chemical synthesis. Watch EFSA safety dossier timelines as inflection indicators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivation | Cargill's Paraguayan stevia estates secure consistent botanical purity against climate volatility. |
| Precision Fermentation Scale-Up | Tate & Lyle's enzymatic cell factories compress capital requirements for rare sugar manufacturing. |
| Chromatographic Separation Upgrade | Roquette's Hamburg facility meets EFSA tightening purity thresholds for European-bound erythritol. |
| Direct-to-Manufacturer Platform Launch | Digital marketplaces bypass distributor markups for mid-tier food manufacturer access. |
| Organic Certification Investment | USDA National Organic Program accreditation extends premium positioning in clean-label segments. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA GRAS notifications, EFSA additive evaluations, and trade customs data. Conversations with beverage formulation directors, stevia extraction plant managers, and retail category buyers inform supply-side and demand-side calibration. SEC filings from Cargill, Tate & Lyle, and Roquette anchor financial trajectory validation. Bottom-up volume modeling triangulates against top-down market sizing.
Segmentation dimensions modeled include product type, application category, distribution channel, and end-user sophistication across the projection horizon. CAGRs derive from regression analysis of historical volume trajectories and elasticity estimates against regulatory trigger events. Forecast inputs incorporate beverage industry sugar reduction commitment timelines and EFSA novel food evaluation schedules.
Material uncertainties — EFSA allulose safety determinations, Paraguayan harvest volatility, and enzymatic production cost curves — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory pathway continuity and biotechnology adoption rates. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
Dunaliella Salina Market
Alternative Food Sources
Meat Alternative Market
Alternative Food Sources
Global Algae Market
Alternative Food Sources
Middle East and Africa Edible Insects Market
Alternative Food Sources
Egg Substitutes Market
Alternative Food Sources
Global Meal Replacement Market
Alternative Food Sources
Carragean Alternatives Market
Alternative Food Sources
Microalgae Based Products Market
Alternative Food Sources
Vegan Casing Market
Alternative Food Sources
Vegan Ham Market
Alternative Food Sources
Fungal Protein Market
Alternative Food Sources
Fat Substitutes Market
Alternative Food Sources
Vegan Egg Substitute Market
Alternative Food Sources
Asia-Pacific Fat Replacers Market
Alternative Food Sources
Fish Oil Alternatives Market
Alternative Food Sources
Seaweed Protein Market