
 Vegan Alternatives Market | 2026-2036
Vegan Alternatives Market Size, Share, and Industry Trends Forecast 2026-2036
Vegan Alternatives Market Insights
Ingredient licensing and brand collaboration revenue is rewriting how value flows between technology holders and finished goods manufacturers. Beyond Meat leverages its extrusion technology portfolio to anchor premium positioning in foodservice channels. Impossible Foods sustains R&D intensity through heme protein innovation, while Oatly Group dominates oat-based dairy alternatives across European retail.
Vegan alternatives comprise formulated food products derived from plant proteins, starches, oils, and hydrocolloids designed to replicate the sensory and nutritional profiles of animal-derived foods, typically achieving protein content between 15-25% in meat analogues through high-moisture extrusion or shear-cell processing. These products serve industrial food manufacturers and foodservice operators seeking to reduce ingredient cost volatility and meet procurement sustainability targets. Dairy alternatives lead current revenue pools given established oat and soy milk infrastructure, while meat substitutes represent the fastest-expanding category as extrusion scale-up reduces unit costs. Flexitarians now constitute the largest customer type by volume, shifting margin concentration away from niche vegan positioning toward mass-market formulation and pricing.
The FDA governs allergen labeling and novel ingredient approvals such as soy leghemoglobin, while the EU Green Deal and EFSA nutrition claims regulation shape permissible marketing language and carbon accounting disclosures across European supply chains. These frameworks elevate compliance costs for entrants but reinforce established players with dedicated regulatory affairs capacity. Stakeholders must monitor evolving protein fractionation technologies and shifting procurement standards from quick-service restaurant chains to anticipate where formulation premiums will compress or expand.
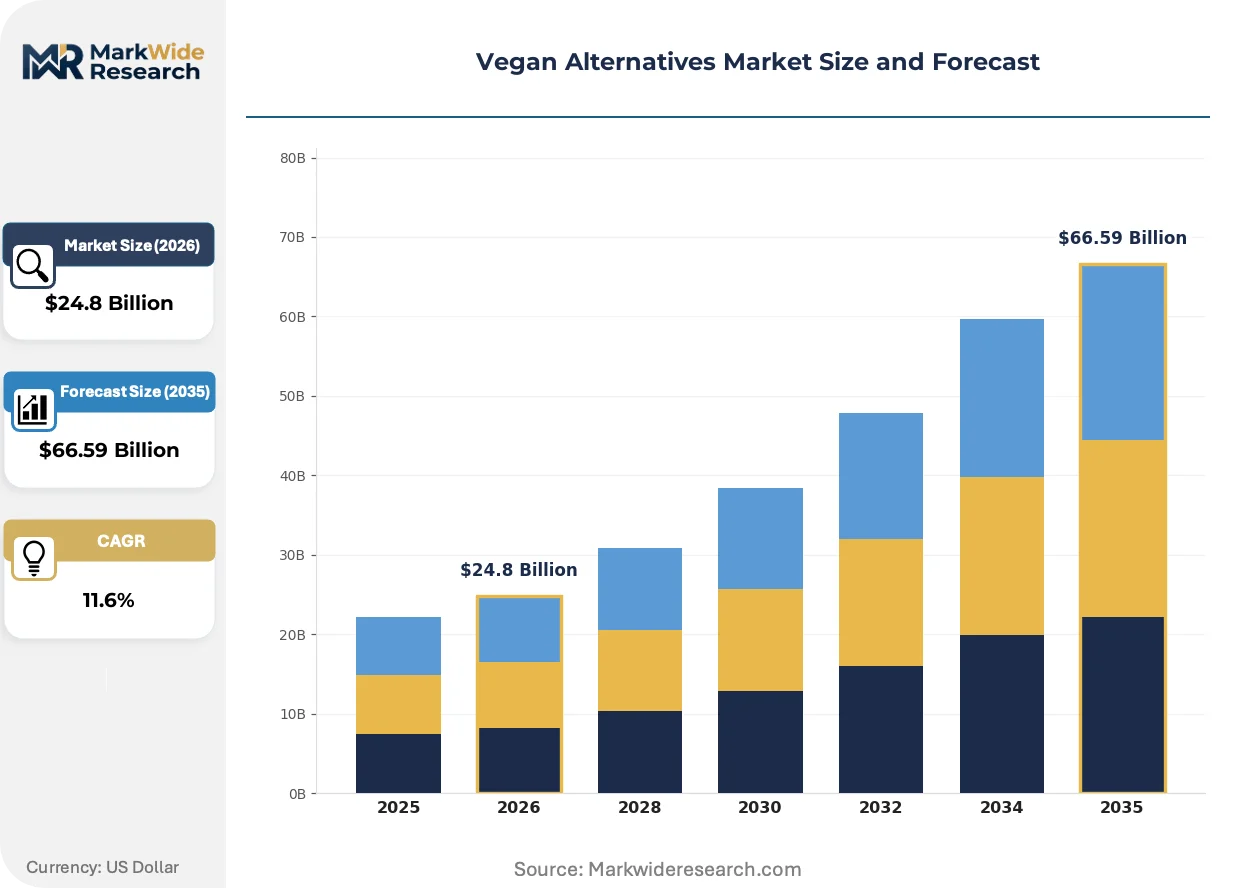
Market Dynamics
High-moisture extrusion scale-up is compressing unit economics for meat analogues while EU Green Deal carbon-accounting mandates force reformulation transparency across European supply chains.
Growth Catalysts
- EU Green Deal carbon disclosures:Mandatory Scope 3 reporting accelerates manufacturer investment in oat and pea protein fractionation to secure lower-emission ingredient credentials.
- Quick-service restaurant procurement mandates:Chains across Germany, the United Kingdom, and the United States now require plant-based options, creating guaranteed offtake volumes for extruded protein suppliers.
- Shear-cell processing maturation:This continuous-flow technology reduces energy intensity versus batch extrusion, enabling mid-scale food manufacturers to enter meat analogue production.
Market Restraints
- Pea protein concentrate supply concentration:Processing capacity clusters in Canada and northern France, exposing formulators to input cost volatility during crop shortfalls.
- Soy leghemoglobin novel-food approval timelines:EFSA's extended safety evaluation periods delay EU market entry for heme-containing products already cleared by FDA.
- Animal dairy price competitiveness:Subsidized conventional milk in the United States and EU member states narrows the retail price gap oat-based alternatives must bridge.
Strategic Opportunities
- Precision fermentation lipid production:Cultivated fat technologies from companies like those in Singapore and Israel promise to close the sensory gap in plant-based meats without agricultural land use.
- Indian foodservice penetration:Urban quick-service chains in Mumbai and Bangalore show accelerating trial rates for dairy alternatives among lactose-intolerant populations.
- Brazilian ANVISA novel protein pathways:Streamlined regulatory frameworks for fungal and algal proteins create first-mover advantages for ingredient suppliers targeting Latin American formulation houses.
Industry Challenges
- Extrusion technician scarcity:High-moisture extrusion operation requires specialized rheology and thermal processing expertise that food science programs have not scaled to match equipment deployment.
- Clean-label certification complexity:Multiple competing standards from V-Label, Vegan Society, and national kosher authorities create labeling compliance overhead for multi-market products.
- Legacy dairy equipment retrofit costs:Converting UHT milk lines for oat or almond base processing demands capital outlays that strain mid-tier dairy alternative entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegan Alternatives Market |
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $66.59 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Meat Substitutes, Dairy Alternatives, Egg Replacements, Plant-Based Snacks Customer Type: Health-Conscious Consumers, Vegans, Flexitarians, Food Enthusiasts Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Restaurants Application: Household Consumption, Food Services, Meal Kits, Bakery Products |
| Companies Covered | Beyond Meat, Impossible Foods, Danone, Nestlé, Hain Celestial Group, Amy's Kitchen, Oatly Group, Conagra Brands, Vitasoy International Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegan Alternatives Market Trends and Innovations
Formulation science is converging with bioprocessing advances to erode the sensory and nutritional gaps between plant-derived and animal-derived foods. Three developments dominate this transition.
Fermentation-derived proteins from biomass and precision platforms are hybridizing with conventional extrusion processes. Food manufacturers in the Netherlands and Denmark blend fungal mycelium with pea isolate to achieve fibrous textures without capital-intensive shear-cell investments. This hybrid approach compresses R&D timelines while maintaining clean-label positioning.
EFSA's 2023 guidance on nutrition and health claims for plant-based alternatives tightens permissible protein quality comparisons. Manufacturers must now substantiate PDCAAS or DIAAS scores rather than relying on crude protein content. This regulatory shift most impacts sports nutrition and infant formula segments, where German and French authorities have initiated enforcement actions against unsubstantiated equivalence claims.
Foodservice procurement is consolidating around direct supplier relationships that bypass traditional distribution intermediaries. Large contract caterers in the United Kingdom and United States now source extruded protein directly from technology holders, capturing margin and securing formulation exclusivity. This disintermediation pressures legacy foodservice distributors to develop private-label analogue capabilities or cede share in institutional channels.
Vegan Alternatives Market Segmentation
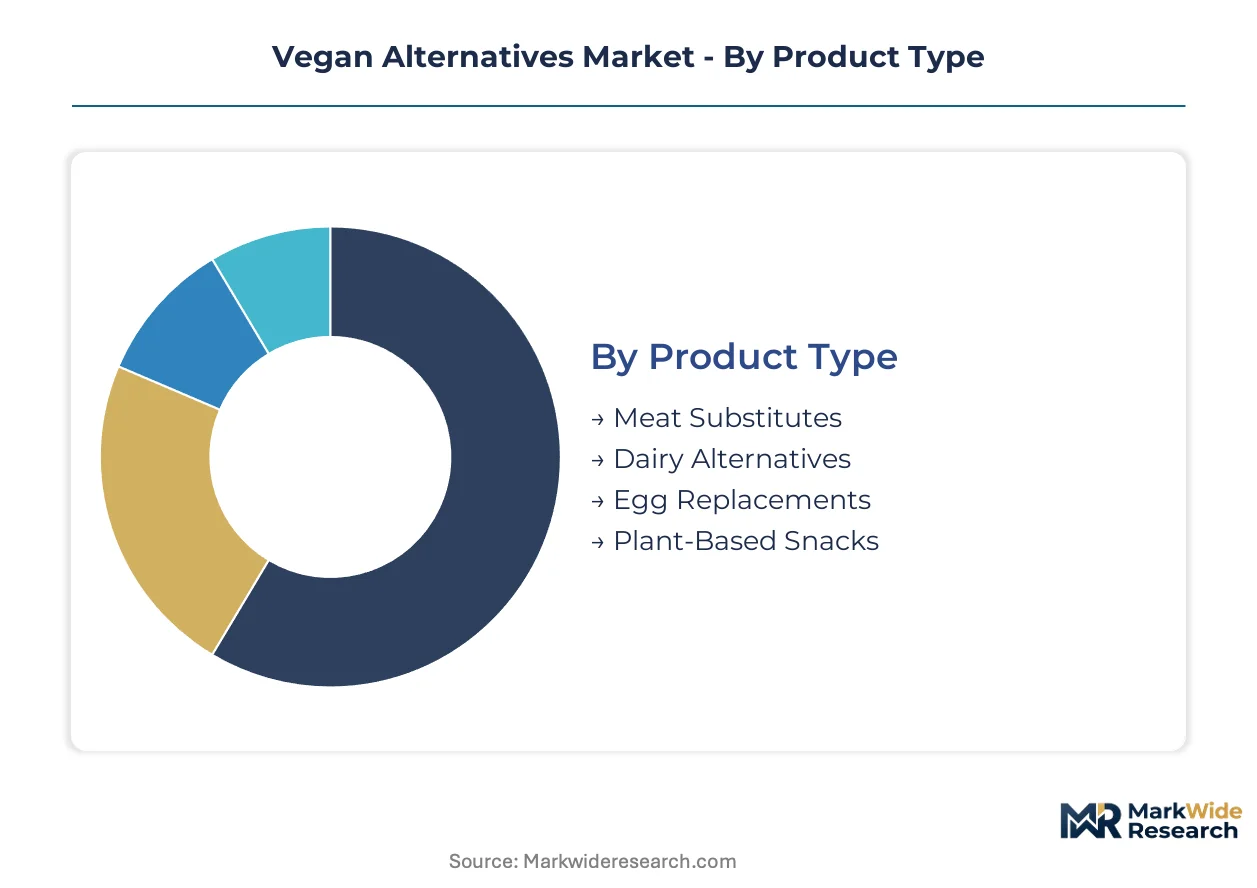
Segmentation in vegan alternatives reveals how formulation complexity, procurement standards, and channel economics fragment value capture across distinct customer journeys and use cases. Understanding these divides clarifies where technology premiums hold and where scale economies compress margins.
Product Type:
Cost tier differentiation separates commodity-adjacent categories from precision-formulated segments requiring capital-intensive processing infrastructure.
- Meat Substitutes:High-moisture extrusion and shear-cell processing create fibrous protein matrices from pea, soy, and wheat gluten isolates. Quick-service restaurant procurement mandates in Germany, the United Kingdom, and the United States concentrate demand for standardized patty and nugget formats, though extrusion technician scarcity constrains mid-scale manufacturer expansion.
- Dairy Alternatives:Oat, almond, and soy base formulations leverage established UHT infrastructure with enzyme-assisted starch hydrolysis for sweetness and mouthfeel. Retail distribution in Sweden and the Netherlands anchors volume, while legacy dairy equipment retrofit costs strain entrants converting conventional milk lines.
- Egg Replacements:Mung bean protein isolates and chickpea aquafaba emulsifiers replicate binding and foaming functions in bakery and sauce applications.
- Plant-Based Snacks:Extruded protein crisps and fermented nut cheeses occupy impulse-purchase channels with shorter ingredient decks.
Dairy alternatives command the established base. The steepest expansion runs through meat substitutes.
Customer Type:
Application intensity varies sharply across commitment levels to plant-based diets, with consequential differences in price elasticity and certification requirements.
- Flexitarians:This majority-volume segment purchases plant-based options intermittently without dietary exclusivity, driving mass-market formulation and pricing. German and British retail data show flexitarian households treat meat analogues as protein rotation rather than replacement, compressing premium positioning.
- Health-Conscious Consumers:Clean-label demands and protein quality scoring (PDCAAS/DIAAS) guide purchase decisions, particularly in sports nutrition and fortified dairy alternatives. EFSA's tightened nutrition claims enforcement in France and Germany elevates substantiation costs for brands targeting this segment.
- Vegans:Ethical consistency requirements sustain demand for third-party certifications from V-Label and Vegan Society, creating compliance overhead.
- Food Enthusiasts:Novel ingredient trial and gastronomic experimentation drive early adoption of fermentation-derived and hybrid protein formats.
Flexitarians anchor volume concentration. Health-conscious consumers are climbing the fastest on reformulation investment.
Distribution Channel:
Margin structure and supplier relationships diverge between consolidated retail and fragmented foodservice pathways.
- Supermarkets:Centralized category management and private-label development in Tesco, Carrefour, and Kroger networks concentrate pricing power. Shelf-space allocation for meat analogues now competes directly with conventional proteins in German and American stores.
- Restaurants:Direct supplier relationships bypass traditional distribution, with contract caterers in the United Kingdom and United States sourcing extruded proteins from technology holders for formulation exclusivity.
- Online Retail:Subscription models and direct-to-consumer shipping enable niche and refrigerated formats with limited retail penetration.
- Specialty Stores:Independent natural products retailers sustain artisan and import-positioned brands with higher service intensity.
Supermarkets hold the volume base. Restaurants are gaining share fastest on procurement consolidation.
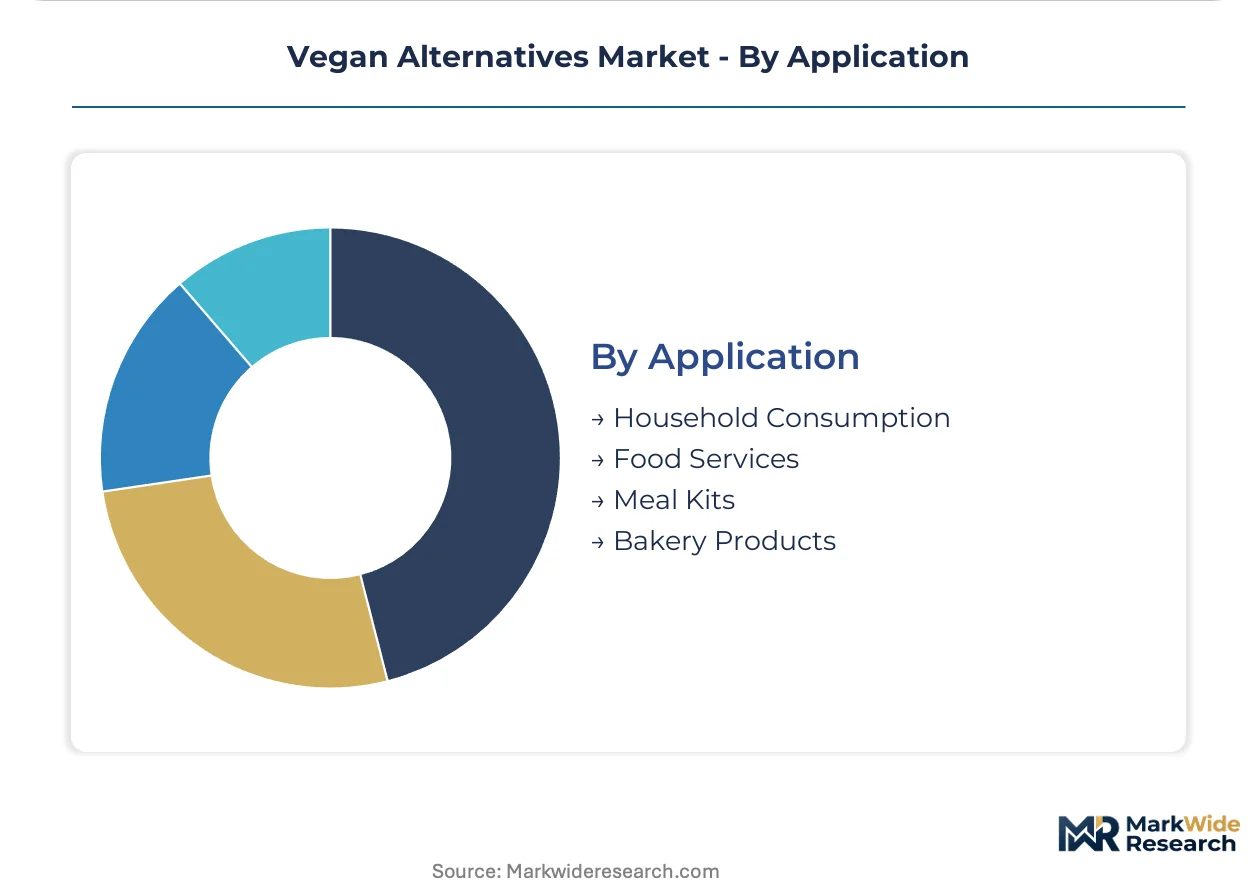
Application:
Volume scale and specification stringency separate consumer-direct formats from industrial ingredient supply.
- Food Services:Institutional procurement from quick-service chains, contract caterers, and hospitality groups demands consistent portion control and extended hold times. Direct supplier relationships in the United Kingdom and Germany capture margin through formulation exclusivity agreements.
- Household Consumption:Retail-packaged formats for home preparation emphasize convenience and sensory familiarity, with oat milk and plant-based mince dominating repeat purchase patterns.
- Meal Kits:Pre-portioned ingredients with recipe integration require specialized packaging and shorter shelf-life logistics.
- Bakery Products:Egg replacement functionality in industrial bread and pastry production demands specific protein binding and emulsification performance.
Food services anchor the commercial base. Household consumption is expanding most quickly on retail distribution maturation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies. German and Dutch consumers accept oat milk premiums, while US buyers remain sensitive to meat analogue pricing gaps against subsidized beef.
United States
Quick-service restaurant procurement mandates from chains in Texas and California drive extruded protein demand. FDA labeling guidelines for soy leghemoglobin and allergen disclosure create compliance thresholds for entrants. Chicago and Los Angeles anchor foodservice innovation clusters where contract caterers source directly from technology holders.
Germany
Flexitarian households in Berlin and Munich treat plant-based proteins as dietary rotation staples, sustaining volume despite economic headwinds. EU Green Deal carbon-accounting rules force Scope 3 disclosure across retail supply chains. The Rhine-Ruhr corridor concentrates extrusion equipment manufacturing and pea protein formulation R&D.
United Kingdom
Tesco and Sainsbury's centralized category management squeezes private-label margins while expanding shelf space for meat analogues. EFSA nutrition claims enforcement tightens protein quality substantiation requirements. London's contract catering sector pioneers direct supplier relationships that bypass traditional distribution intermediaries.
Sweden
Oat milk penetration reaches saturation in Stockholm and Gothenburg households, shifting growth toward fermented dairy alternatives. National carbon labeling mandates accelerate manufacturer investment in domestic oat fractionation. The Skåne region hosts precision fermentation startups targeting lipid production for meat analogue applications.
India
Urban quick-service chains in Mumbai and Bangalore show accelerating trial rates for dairy alternatives among lactose-intolerant populations. FSSAI novel protein approval pathways remain less defined than Western equivalents, delaying multinational entry. The National Capital Region emerges as a testbed for mung bean protein isolate production targeting egg replacement applications.
Vegan Alternatives Market Competitive Landscape
Capability concentration sits with technology holders commanding extrusion and fermentation IP; scale advantage sits with diversified food conglomerates with existing retail distribution and UHT infrastructure. The market structures around three archetypes: protein technology specialists, legacy dairy and meat processors pivoting portfolios, and private-label manufacturers serving retailer specifications. Competitive moves cluster on strategic partnerships for ingredient supply and capacity expansion in high-moisture extrusion lines.
Within the technology specialist tier, Beyond Meat and Impossible Foods exemplify contrasting platform strategies—extrusion portfolio licensing versus heme protein innovation—while Oatly Group anchors oat-based dairy scale across European retail. These entities occupy positions that downstream food manufacturers and foodservice operators must navigate when securing formulation exclusivity or ingredient cost stability.
| Leading Market Players |
|---|
| Beyond Meat |
| Impossible Foods |
| Danone |
| Nestlé |
| Hain Celestial Group |
| Amy's Kitchen |
| Oatly Group |
| Conagra Brands |
| Vitasoy International Holdings |
| Others |
Pricing and Supply Chain Analysis
Rotterdam-Antwerp barge freight corridors for pea protein concentrate exhibit volatile cost dynamics that amplify margin compression for mid-scale extrusion operators while enabling tiered price positioning between commodity oat bases and precision-formulated meat analogues.
Pricing Analysis
After-sales formulation support and co-development contracts with quick-service chains drive lifetime value capture for technology holders. Three-tier pricing structure across premium extruded proteins, standard oat-based dairy, and economy reconstituted isolates stratifies the market. Price differentiation rests on certification grade—EU Green Deal carbon disclosure compliance versus conventional labeling—and volume scale commitments from institutional buyers. Cost compression in standard-tier meat analogues is intensifying because subsidized conventional dairy narrows retail price gaps. Flexitarian households show highest price sensitivity, while foodservice procurement teams prioritize sensory performance over unit cost.
Supply Chain Analysis
Tariff exposure between Canada and the European Union dominates supply chain risk planning for pea protein formulators. Ingredient sourcing concentrates in Canada, northern France, and the Netherlands for fractionation capacity. Raw material dependencies include yellow pea, oat groats, and mung bean isolates. Single-source vulnerability in high-moisture extrusion equipment from German and Italian manufacturers creates procurement bottlenecks. Distribution runs through direct supplier relationships with contract caterers and foodservice operators, bypassing legacy wholesale intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment—established players with dedicated EFSA and FDA compliance capacity capture premium positioning while entrants face extended novel-food approval timelines.
For Market Incumbents: Insulate formulation exclusivity through captive pea protein fractionation in the Rhine-Ruhr corridor and accelerated shear-cell processing deployment. Precision fermentation lipid partnerships in Sweden and Israel counter emerging cultivated fat substitutes. Direct procurement relationships with Tesco, Sainsbury's, and Kroger networks reinforce channel control against private-label encroachment.
For New Entrants and Emerging Players: Brazilian ANVISA novel protein pathways and streamlined fungal protein approvals represent the most penetrable entry point for Latin American formulation houses. Urban quick-service chains in Mumbai and Bangalore offer secondary white-space for dairy alternative trial. Co-manufacturing partnerships with established extrusion operators reduce capital barriers to foodservice qualification.
For Investors and Strategic Acquirers: Precision fermentation technology specialists with demonstrated lipid production pathways command acquisition priority. Long-term viability hinges on defensible IP positions in carbon-accounting methodologies and Scope 3 disclosure automation. Watch for EFSA enforcement actions against unsubstantiated protein quality claims as an inflection indicator for compliance-driven consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| High-Moisture Extrusion Capacity Expansion | Secures offtake volumes from Burger King and McDonald's procurement mandates in Germany. |
| Precision Fermentation Partnership | Closes sensory gaps in plant-based meats through Singaporean and Israeli lipid technology. |
| Carbon-Accounting Certification Program | Aligns supplier networks with EU Green Deal Scope 3 disclosure requirements. |
| Direct Foodservice Supply Agreement | Bypasses legacy distribution to capture margin through formulation exclusivity with contract caterers. |
| Pea Protein Fractionation Backward Integration | Reduces input cost volatility from Canadian crop shortfalls through captive processing. |
Research Methodology
Desk research of EFSA guidance documents, FDA novel-food submissions, and EU Green Deal regulatory filings preceded structured interviews with extrusion equipment operators, plant-based R&D directors, quick-service procurement managers, and foodservice distribution executives. Secondary validation drew from customs trade data for pea protein concentrate flows, SEC filings of publicly traded alternative protein companies, and retail audit databases tracking oat milk and meat analogue shelf-space allocation. Bottom-up volume modeling triangulated against top-down market sizing from ingredient supplier capacity disclosures.
Assumptions held fixed across the analysis window include EU Green Deal carbon disclosure enforcement timelines and quick-service restaurant procurement mandate coverage rates. Variable assumptions encompassed pea protein yield coefficients, extrusion energy intensity improvements, and flexitarian household penetration curves. The analytical framework segmented by product type, customer commitment level, distribution channel, and application intensity. CAGRs were derived from regression analysis against historical oat milk adoption patterns and meat analogue foodservice rollout trajectories. Forecast inputs included shear-cell processing maturation curves and precision fermentation lipid cost-reduction pathways.
Practitioners should monitor EFSA novel-food approval timelines, Canadian pea crop yield reports, and quick-service chain procurement specification changes for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Asia Pacific Plant-Based Milk Market
Plant Based Food
United States Plant Protein Market
Plant Based Food
Plant-Based Vegan Eggs Market
Plant Based Food
Europe Rice Protein Market
Plant Based Food
Vegan Pastry Market
Plant Based Food
Chicory Roots Market
Plant Based Food
France Plant Protein Market
Plant Based Food
Insoluble Pea Protein Market
Plant Based Food
Plant-Based Chicken Market
Plant Based Food
Plant Based Meal Kit Market
Plant Based Food
Extruded Soy Products Market
Plant Based Food
India Pea Protein Market
Plant Based Food
South America Rice Protein Market
Plant Based Food
Singapore Plant-Based Food and Beverages Market
Plant Based Food
Canada Plant-Based Food and Beverages Market
Plant Based Food
United Kingdom Tofu Market