
 Insect Protein Market | 2026-2036
Insect Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Insect Protein Market Analysis
EFSA Novel Food certification is rotating as the primary gatekeeping standard for European market entry, forcing prospective entrants to navigate multi-year safety dossier requirements. Protix leverages its vertically integrated Dutch facility to control larvae-to-meal production from breeding to oil extraction. InnovaFeed sustains a technology leadership position in automated rearing systems that optimize feed conversion ratios at industrial scale. Aspire Food Group anchors North American supply through its Texas cricket farming operations, targeting human-grade protein powder and snack applications.
Insect protein denotes processed biomass derived from farmed arthropod species, typically containing 40-75% crude protein by dry weight with favorable amino acid profiles including lysine and methionine, produced through controlled-environment rearing on organic substrate streams for incorporation into formulated feeds and human foods. Protein powder commands the dominant share of product type value due to its versatility in extruded feeds and sports nutrition formulations, while whole insects remain a niche premium segment concentrated in specialty retail channels. Aquaculture applications within the application dimension represent the fastest-expanding consumption pool, driven by salmonid and shrimp producers seeking to reduce marine ingredient dependency.
The EU Novel Food Regulation, administered by EFSA, mandates pre-market authorization for insect-derived ingredients intended for human consumption, creating a two-tier market split between approved species and pending dossiers. FDA Center for Veterinary Medicine guidance on Generally Recognized As Safe determinations for black soldier fly larvae in poultry and aquaculture feeds shapes the regulatory trajectory for US market development. Stakeholders must monitor the divergence between EU harmonized approvals and fragmented national regulations across member states, as this asymmetry will determine which production geographies achieve scalable market access first.
Market Dynamics
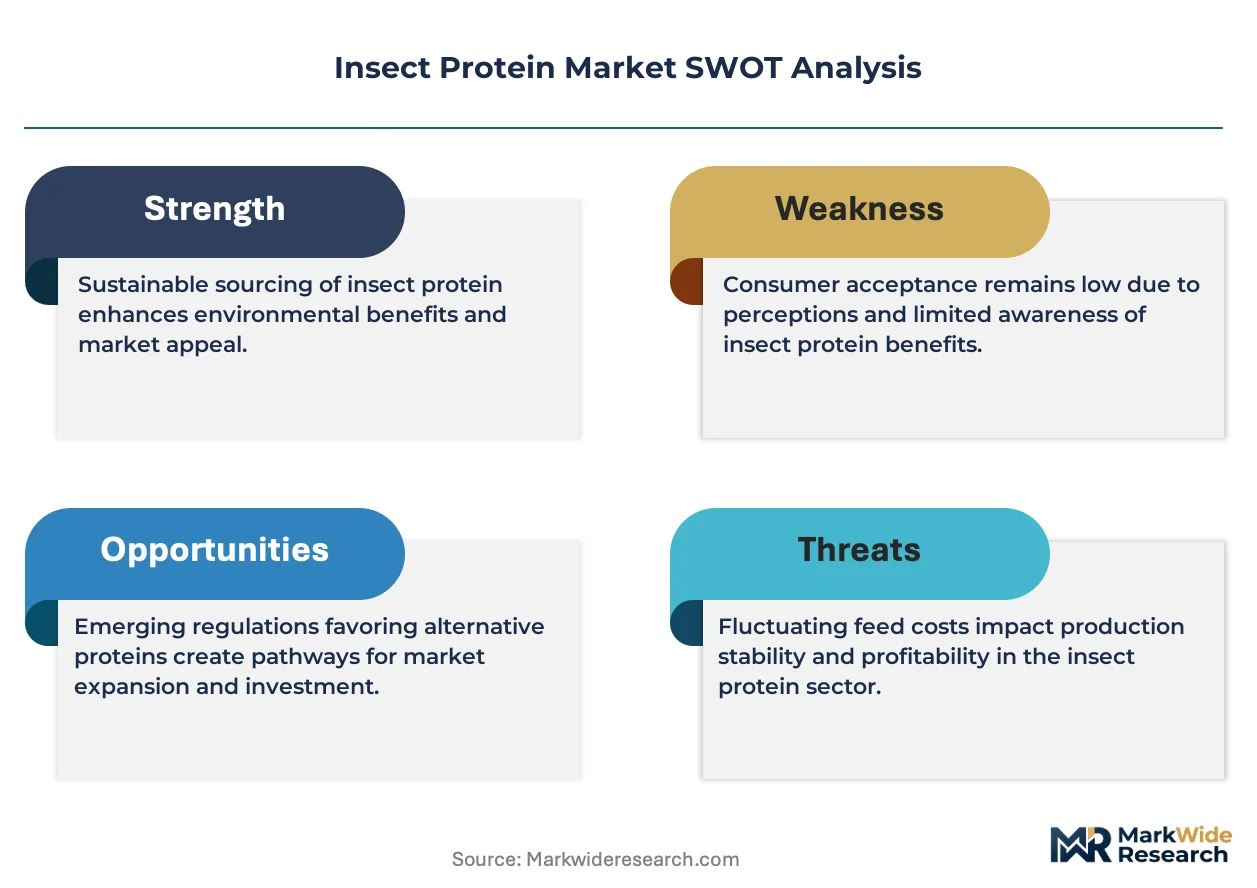
EFSA Novel Food authorizations are compressing competitive timelines, forcing producers to secure multi-year safety dossiers before commercial scale-up while vertically integrated Dutch facilities capture early-mover advantages in larvae-to-meal processing.
Growth Catalysts
- Fishmeal substitution mandates:Aquaculture feed formulators in Norway and Scotland are integrating black soldier fly larvae meal to reduce marine ingredient dependency.
- EU Green Deal protein diversification targets:The framework incentivizes alternative protein investment, directing capital toward industrial insect rearing infrastructure.
- Automated climate-controlled rearing:Sensor-driven environmental management systems are slashing mortality rates and improving feed conversion efficiency at scale.
Market Restraints
- Organic substrate supply volatility:Pre-consumer food waste streams face competition from anaerobic digestion and composting, squeezing input cost predictability.
- EFSA dossier timeline uncertainty:The multi-year Novel Food approval process creates stranded capital risk for species awaiting safety clearance.
- Soy protein concentrate substitution:Established oilseed processing infrastructure and price competitiveness limit insect meal penetration in poultry rations.
Strategic Opportunities
- Pet food premiumization in Germany:Dog and cat food manufacturers are sourcing human-grade insect protein for hypoallergenic and sustainable product lines.
- US FDA GRAS pathway expansion:Broader Generally Recognized As Safe determinations for additional insect species would unlock poultry and aquaculture feed applications.
- Direct-to-consumer whole insect retail:E-commerce platforms and specialty grocers are creating new channels for roasted cricket and mealworm snack products.
Industry Challenges
- Entomology and automation engineering talent scarcity:Industrial-scale facilities require hybrid expertise in insect biology and process engineering that academic pipelines undersupply.
- Downstream integration complexity:Larvae meal processors face technical hurdles achieving consistent lipid and protein fractions for formulated feed specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Insect Protein Market |
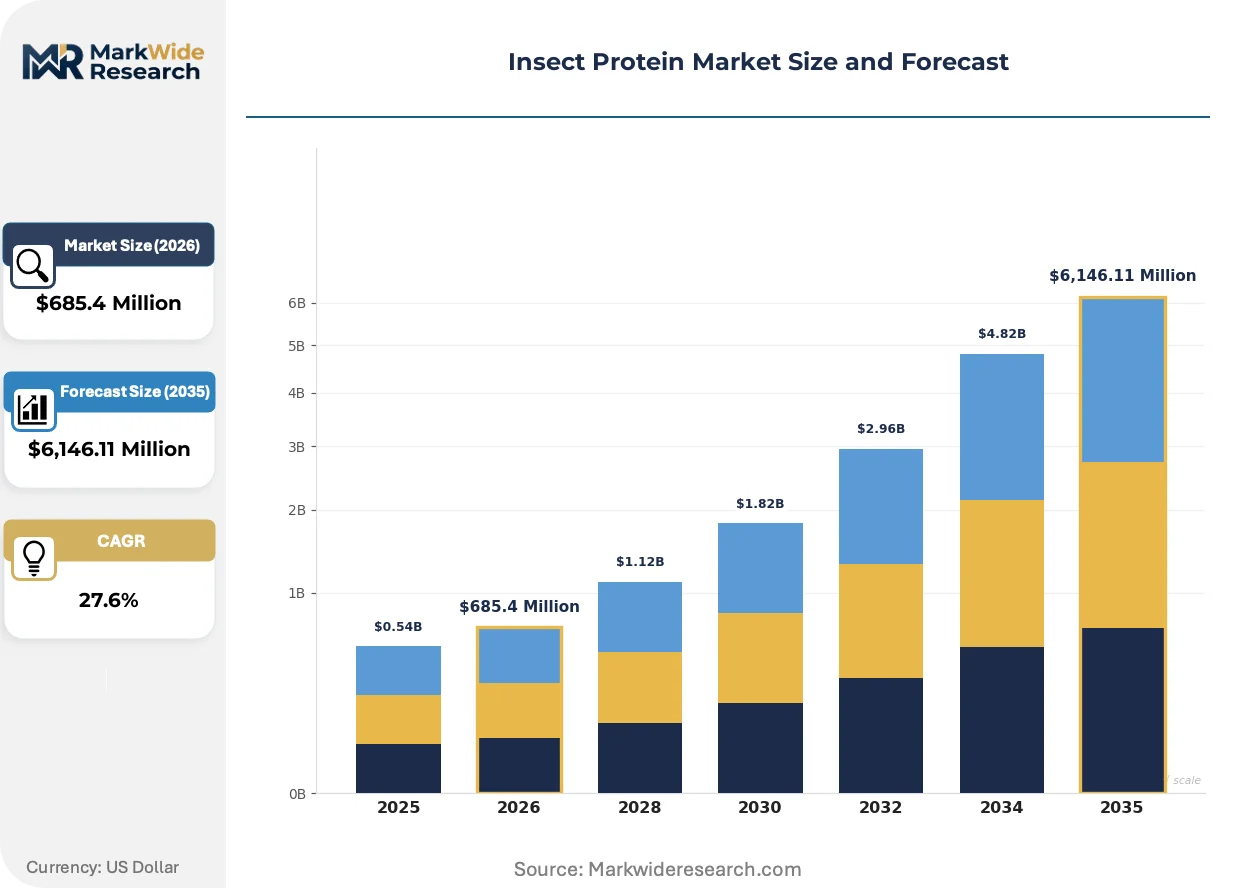
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $6,146.11 Million |
| CAGR (2026 – 2036) | 27.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Insects, Protein Powder, Protein Bars, Snacks End User: Food Industry, Animal Feed, Nutraceuticals, Cosmetics Application: Agriculture, Aquaculture, Pet Food, Dietary Supplements Delivery Mode: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Ynsect, Hexafly, EnviroFlight, Nutrition Technologies, Entomo Farms, InnovaFeed, Aspire Food Group, nextProtein, Protix, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Insect Protein Market Emerging Trajectories
Processing technology and regulatory frameworks are diverging across geographies, creating distinct competitive arenas where automation sophistication and approval status determine market access rather than commodity pricing alone.
Automated rearing infrastructure is bifurcating competitive outcomes between technology-intensive European producers and capital-constrained entrants elsewhere. Industrial-scale facilities in the Netherlands deploy AI-driven climate control and robotic harvesting systems that compress labor costs and mortality variance. Salmonid feed manufacturers in Norway now specify automated-reared larvae meal for contract security, widening the performance gap against manual operations.
EFSA's Novel Food Regulation is fragmenting market access timelines across EU member states despite harmonized Brussels-level authority. France and Belgium have accelerated national processing of pending dossiers while southern member states lag, creating arbitrage opportunities for approved-species producers. Human-grade protein powder manufacturers are prioritizing dossier investment over capacity expansion until regulatory clarity stabilizes.
Buyer concentration among aquaculture integrators is compressing supplier qualification cycles and demanding traceability certification beyond generic sustainability claims. Norwegian salmon producers now require batch-level substrate origin documentation and carbon footprint verification as standard procurement terms. This specification escalation favors vertically integrated larvae processors with captive breeding and controlled feedstock supply over merchant meal traders.
Insect Protein Market Segmentation
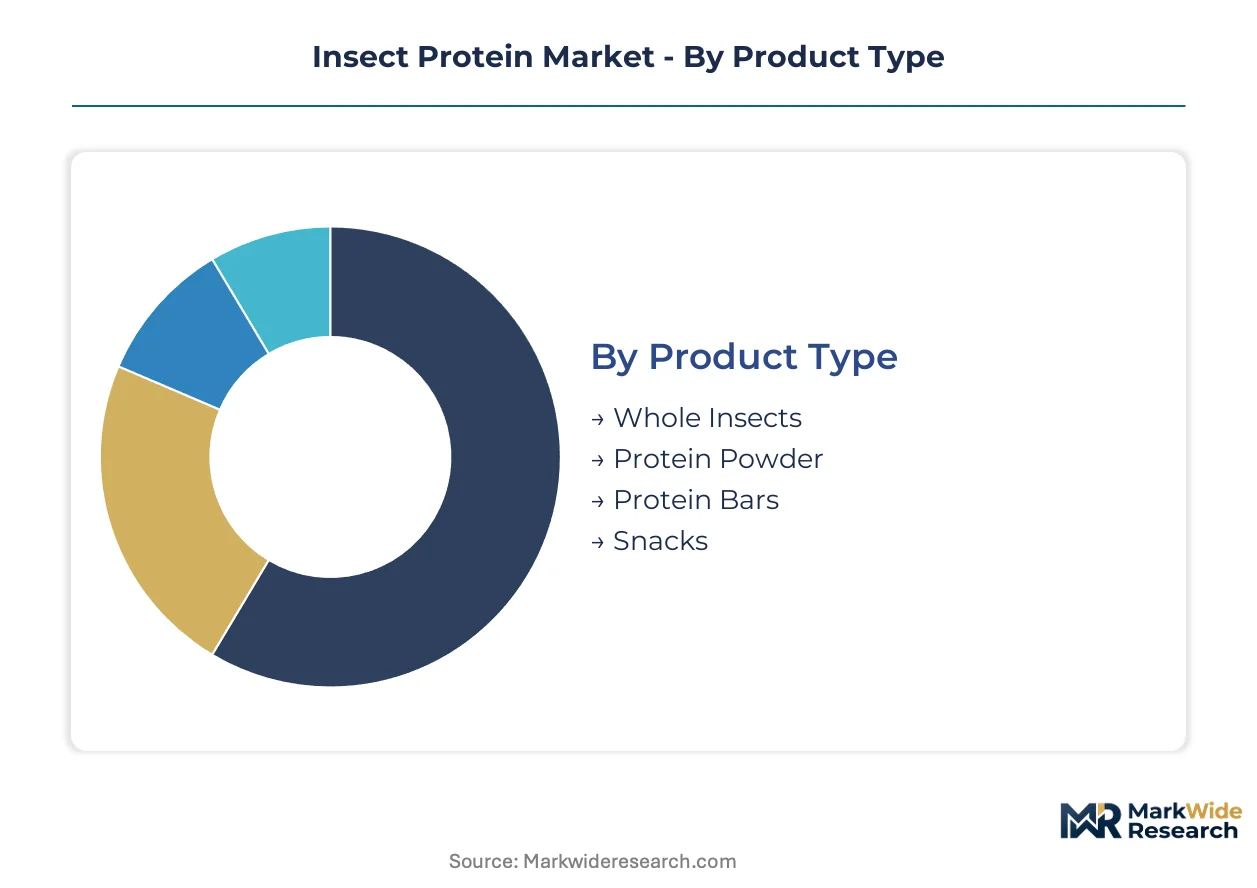
Segmentation in insect protein reveals how regulatory authorization status and processing sophistication split revenue pools between human-grade and feed-grade applications. Product form and delivery channel determine margin capture, while end-use concentration shapes capital deployment toward aquaculture integration or consumer packaged goods.
Product Type:
Protein Powder faces the most intense substitution pressure from established plant isolates and dairy concentrates, forcing differentiation through amino acid completeness and sustainability certification. Whole Insects compete against conventional meat snacks and experiential food tourism, limiting addressable market depth.
- Protein Powder:Defatted and milled biomass containing 60-75% crude protein with standardized particle size for extrusion compatibility. Aquaculture feed formulators in Norway and Scotland specify this grade for salmonid diets, driven by fishmeal reduction mandates and traceability requirements.
- Whole Insects:Roasted or freeze-dried intact specimens marketed through specialty retail and direct-to-consumer channels. German pet food manufacturers and Asian snack importers represent concentrated demand pockets, constrained by consumer acceptance thresholds and handling logistics.
- Protein Bars:Compacted formulations blending insect flour with binders and flavor masking agents. Sports nutrition brands in the Netherlands trial limited SKUs pending EFSA Novel Food clarity.
- Snacks:Seasoned and packaged whole or fragmented insects for impulse purchase occasions. E-commerce platforms and airport retail in Belgium generate trial volume, though repeat purchase rates remain variable.
Protein Powder retains volume leadership; Snacks hold the steepest expansion curve contingent on regulatory authorization timelines.
End User:
Cost tier stratification separates commodity feed applications from premium human nutrition, with Animal Feed commanding scale economics and Nutraceuticals extracting margin through bioactive fractionation.
- Animal Feed:Formulated rations for poultry, aquaculture, and livestock incorporating larvae meal or defatted protein. Poultry integrators in the US source black soldier fly larvae meal under FDA Center for Veterinary Medicine guidance, displacing soy protein concentrate in starter diets.
- Food Industry:Ingredient supply to bakery, pasta, and meat alternative manufacturers seeking protein fortification. Dutch and French processors dominate contract supply pending broader EFSA species approvals.
- Nutraceuticals:Chitin, antimicrobial peptides, and lipid fractions extracted for functional food and supplement applications. Korean and Japanese buyers import specialized fractions for gut health formulations.
- Cosmetics:Hydrolyzed protein and lipid derivatives for hair and skin conditioning. Niche demand from French and German formulators emphasizes sustainable sourcing credentials over functional superiority.
Animal Feed dominates tonnage throughput; Nutraceuticals generate the highest unit economics despite smaller volume bases.
Application:
Customer type concentration varies sharply, with Aquaculture demanding batch certification and Pet Food rewarding brand storytelling.
- Aquaculture:Salmonid and shrimp feed formulations substituting marine ingredients with insect meal. Norwegian producers mandate automated-reared larvae with substrate origin documentation as standard procurement terms.
- Pet Food:Premium dog and cat diets featuring hypoallergenic insect protein for sensitive animals. German manufacturers lead SKU proliferation, sourcing human-grade material for label differentiation.
- Agriculture:Soil amendment and biocontrol applications utilizing frass and residual biomass. Organic farming operations in the Netherlands integrate larvae byproducts into closed-loop systems.
- Dietary Supplements:Capsule and powder formats for human consumption requiring full EFSA Novel Food authorization. Dossier investment delays commercial scale-up for pending species.
Aquaculture absorbs the largest absolute volume; Pet Food climbs fastest on premiumization momentum and regulatory clarity advantages.
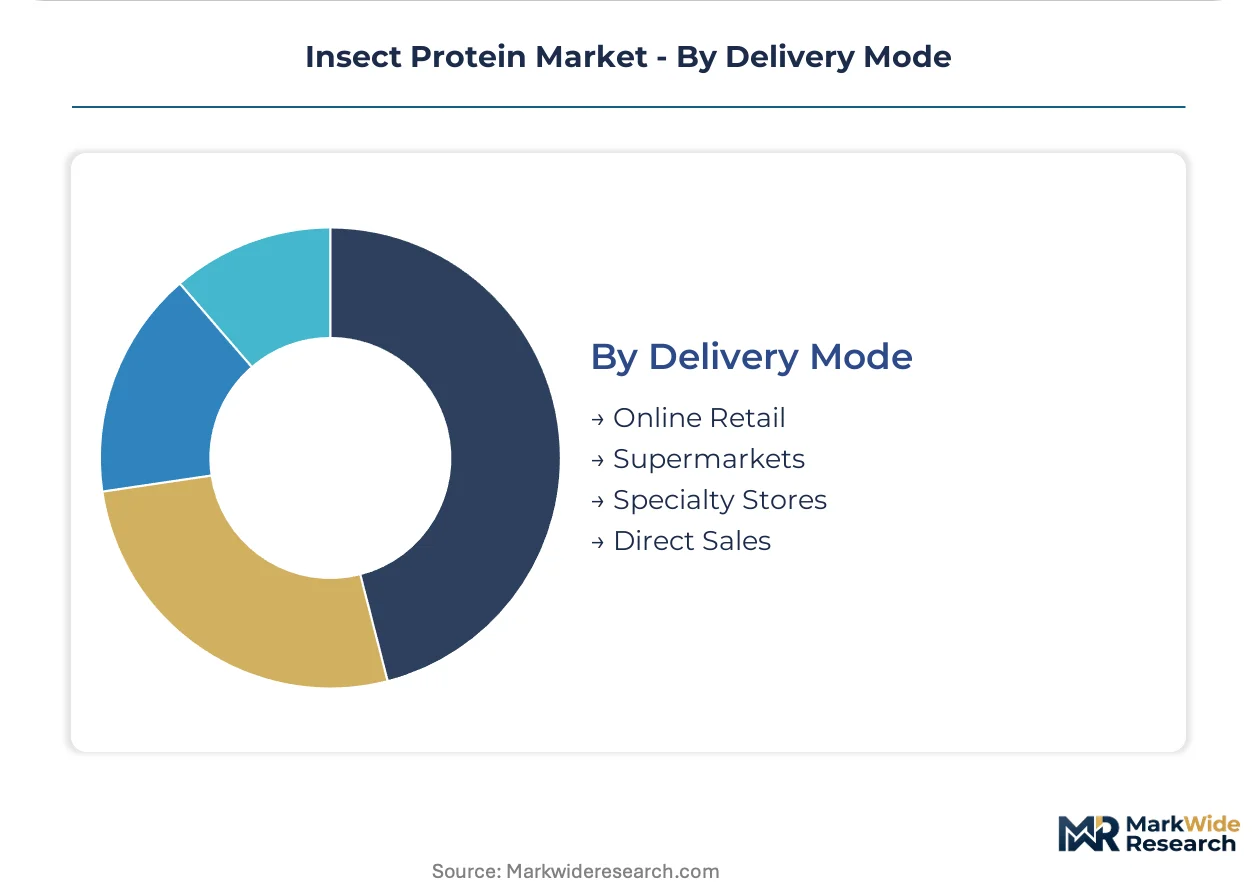
Delivery Mode:
Supply concentration in automated rearing clusters shapes channel economics, with Direct Sales capturing margin from institutional buyers and Online Retail fragmenting consumer reach.
- Direct Sales:Contract supply relationships between larvae processors and aquaculture integrators or pet food manufacturers. Protix and InnovaFeed leverage captive breeding facilities to secure multi-year supply agreements with Norwegian salmon producers.
- Specialty Stores:Curated retail environments for whole insect and premium snack products. Urban locations in Amsterdam and Berlin generate highest per-square-foot throughput for experiential categories.
- Supermarkets:Mass retail placement for protein powder and bar formats contingent on regulatory authorization. French and Belgian chains trial limited distribution for approved species only.
- Online Retail:E-commerce platforms enabling direct-to-consumer sales of whole insects and subscription protein products. Logistics complexity and temperature control requirements constrain margin structures.
Direct Sales commands the value pool through contract security; Online Retail expands most quickly as authorization broadens addressable consumer bases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal protein diversification targets are redirecting agricultural subsidies toward industrial insect rearing infrastructure. National regulators in France, Germany, and the Netherlands have accelerated Novel Food processing timelines. Production gravity clusters in automated rearing facilities across Northern Europe.
Netherlands
Dutch aquafeed formulators source black soldier fly larvae meal for salmonid diets under EFSA Novel Food specifications. The national government channels innovation grants toward circular economy protein projects. Protix operates industrial-scale breeding-to-processing facilities in Dongen serving Norwegian salmon integrators.
France
French pet food manufacturers integrate human-grade insect protein for hypoallergenic dog and cat product lines. ANSM coordinates with EFSA on accelerated safety dossier reviews for domestic processors. InnovaFeed runs automated rearing systems in Nesle optimized for feed conversion efficiency at scale.
Germany
German retailers trial whole insect snacks and protein powders through specialty and e-commerce channels pending broader EFSA authorizations. The Federal Ministry of Food and Agriculture funds alternative protein research through its Protein Strategy initiative. Berlin and Hamburg host concentrated startup activity in direct-to-consumer insect food branding.
United States
US poultry integrators procure black soldier fly larvae meal for starter diets under FDA Center for Veterinary Medicine guidance. The agency's GRAS determination pathway shapes species-by-species approval timelines for feed applications. Aspire Food Group anchors supply from cricket farming operations in Texas targeting human-grade protein markets.
Canada
Canadian aquaculture operators in British Columbia evaluate insect meal substitution for marine ingredient reduction in salmon feeds. Health Canada and PMRA coordinate on novel feed ingredient safety assessments. Entomo Farms maintains processing capacity in Ontario serving North American pet food and specialty food manufacturers.
Insect Protein Market Vendor Landscape
Player mix skews toward vertically integrated larvae processors with captive breeding infrastructure. Market structure concentrates around automated rearing specialists and regional feed-grade suppliers. Two archetypes dominate: technology-intensive European scale operators and North American human-grade specialists. Competitive moves center on multi-year supply contract capture with aquaculture integrators and EFSA dossier investment for species expansion.
Within the integrated processing tier, Protix and InnovaFeed exemplify the automated rearing archetype with Dutch and French industrial footprints respectively. Aspire Food Group occupies a position among North American human-grade specialists focused on cricket-derived ingredients. Ynsect represents the diversified species processor archetype with French origins. These anchors illustrate how regulatory authorization status and automation sophistication determine competitive positioning more than commodity scale alone.
| Leading Market Players |
|---|
| Ynsect |
| Hexafly |
| EnviroFlight |
| Nutrition Technologies |
| Entomo Farms |
| InnovaFeed |
| Aspire Food Group |
| nextProtein |
| Protix |
| Others |
Supply Flow & Price Mechanics
EFSA Novel Food authorization status gates both supply qualification and price differentiation simultaneously, forcing producers to secure multi-year safety dossiers before accessing premium human-grade pricing tiers while feed-grade suppliers compete on substrate sourcing efficiency alone.
Pricing Analysis
Certification level (EFSA Novel Food versus FDA GRAS versus feed-grade) creates the primary spread between human-grade protein powder at premium tiers and aquaculture larvae meal at standard levels. Three-tier pricing structure across premium, standard, and economy levels reflects automation sophistication, with AI-driven Dutch facilities commanding contract premiums over manual operations. Pricing pressure stems from soy protein concentrate substitution in poultry rations, compressing larvae meal margins. Aquaculture integrators in Norway exhibit lowest price sensitivity due to fishmeal reduction mandates, while commodity feed blenders in the US remain highly price-elastic.
Supply Chain Analysis
Organic substrate availability in the Netherlands, France, and Belgium underwrites production economics for industrial-scale larvae processors. Black soldier fly larvae operations draw from pre-consumer food waste streams, spent grains from breweries, and agricultural residues as primary feedstocks. Single-source vulnerability concentrates in automated climate-control equipment suppliers serving Northern European facilities. Distribution runs through direct contract supply to aquaculture integrators and pet food manufacturers, with merchant meal traders losing share to vertically integrated processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription-based substrate sourcing contracts and multi-year offtake agreements with salmon producers expand faster than standalone larvae meal sales, positioning service-attach revenue as the primary value capture mechanism.
For Market Incumbents: Shield market position by deepening captive breeding infrastructure in the Netherlands and accelerating EFSA dossier submissions for secondary insect species ahead of regulatory clarity. Soy protein concentrate price volatility in poultry feed applications threatens volume retention, requiring backward integration into organic substrate preprocessing to defend margin structures. For New Entrants and Emerging Players: Automated rearing system maintenance and substrate logistics optimization represent service-layer gaps where incumbents under-serve mid-scale operators. German pet food premiumization offers the most penetrable segment, with hypoallergenic positioning and human-grade certification as the primary go-to-market angle. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across automated rearing technology deployment as sensor and robotics costs decline. Over the projection horizon, vertically integrated larvae processors with captive breeding and EFSA-approved species portfolios represent the preferred acquisition archetype. Watch for FDA GRAS pathway expansion signals as the inflection indicator for North American feed-grade market access.| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Novel Food Dossier Investment | Multi-year safety documentation unlocks human-grade protein powder pricing premiums in Dutch and French markets. |
| Automated Rearing System Deployment | AI-driven climate control compresses mortality variance and labor costs at industrial larvae facilities in the Netherlands. |
| Backward Integration into Substrate Preprocessing | Captive organic waste stream processing insulates input cost predictability against anaerobic digestion competition. |
| Multi-Year Supply Contract Capture | Norwegian salmon integrators now mandate automated-reared larvae with batch-level traceability as standard procurement terms. |
| Direct-to-Consumer Whole Insect Retail | E-commerce platforms and specialty grocers in Germany and Belgium create new channels for roasted cricket snack products. |
Methodological Framework
Desk research of EFSA Novel Food authorization databases, FDA Center for Veterinary Medicine guidance documents, and aquaculture feed formulation specifications preceded structured interviews with larvae processing plant managers, pet food manufacturer procurement leads, Norwegian salmon integrator feed specialists, and automated rearing system engineers. Secondary validation drew from EU Green Deal protein diversification policy filings, customs trade data on insect meal imports, and SEC filings of publicly traded alternative protein companies. Bottom-up capacity modeling and top-down demand estimation triangulated volume and value outputs.
Variance decomposition across product type, end user, application, and delivery mode segmentation dimensions shaped the analytical framework over the projection horizon. CAGRs derived from production capacity buildout schedules, regulatory authorization timelines, and substitution elasticity estimates for fishmeal and soy protein concentrate. Species-specific approval status and automation adoption curves served as industry-specific forecast inputs throughout the modeling period.
Forecasts assume regulatory continuity in EFSA Novel Food and FDA GRAS regimes; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as EU member state processing speed divergence and US poultry feed approval expansion evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
Africa Protein Market
Alternative Food Sources
Fish Meal Alternative Market
Alternative Food Sources
Dunaliella Salina Market
Alternative Food Sources
North America Precision Fermentation Market
Alternative Food Sources
Meal Replacement Bars Market
Alternative Food Sources
Gluten-Free Meat Substitutes Market
Alternative Food Sources
Spirulina Beverages Market
Alternative Food Sources
Algae Fats Market
Alternative Food Sources
Mushroom Protein Market
Alternative Food Sources
Low Carbs Vegan Food Market
Alternative Food Sources
Mycoprotein Products Market
Alternative Food Sources
Asia-Pacific Algae Protein Market
Alternative Food Sources
Bagasse Disposable Cutlery Market
Alternative Food Sources
Asia-Pacific Meat Substitutes Market
Alternative Food Sources
Insect Snacks Market
Alternative Food Sources
Seaweed Protein Market