
 Algal Protein Market | 2026-2036
Algal Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Algal Protein Market Outlook
The EU Green Deal is hardening sustainability requirements for alternative protein sourcing, pushing food manufacturers toward low-carbon biomass inputs. Corbion leverages its Dutch fermentation infrastructure to supply high-purity algal proteins to European food formulators. Roquette Frères anchors its position through integrated microalgae cultivation partnerships in France. Cyanotech Corporation competes via its Hawaiian production base, specializing in astaxanthin-enriched spirulina for premium supplement channels.
Algal protein denotes protein isolates, concentrates, and whole-cell powders derived from photosynthetic microalgae and cyanobacteria, typically containing 50-70% crude protein by dry weight with complete essential amino acid profiles including lysine and methionine. Industrial production employs closed photobioreactors or open raceway ponds followed by spray-drying or cell disruption for protein extraction, serving primarily as functional ingredients in human nutrition and animal feed formulations. Spirulina dominates current volume owing to established cultivation protocols and GRAS status in multiple jurisdictions, while chlorella captures premium positioning through its chlorophyll content and detoxification marketing in nutraceutical applications. Enzymatic extraction represents the fastest-growing processing category as manufacturers seek to preserve bioactive peptides and improve protein digestibility compared with conventional mechanical or solvent methods.
EFSA novel food regulations, FDA GRAS notifications, and EU organic certification standards collectively govern market access and label claims for algal protein ingredients across major demand centers. REACH compliance for extraction solvents and USDA organic handling requirements further constrain processing choices and supply chain configurations for cross-border trade. Stakeholders must monitor evolving protein content thresholds and contaminant limits under pending EU-wide algae-specific legislation to anticipate reformulation obligations and competitive repositioning.
Market Dynamics
EFSA's novel food authorization pathways are compressing time-to-market for algal protein isolates, forcing manufacturers to reconfigure extraction protocols around enzymatic methods that preserve bioactive peptide integrity while satisfying contaminant thresholds.
Growth Catalysts
- EU Green Deal procurement mandates:Public food service contracts across Germany, France, and the Netherlands now require verified low-carbon protein sourcing, directing institutional buyers toward photobioreactor-derived biomass with documented carbon footprints.
- Enzymatic extraction maturation:Commercial-scale cellulase and protease systems are reducing protein denaturation rates versus mechanical disruption, enabling higher lysine retention in finished isolates for sports nutrition formulators.
- Clean-label retail shelf expansion:European supermarket chains are allocating dedicated plant-protein sections where spirulina and chlorella powders command premium positioning against pea and soy alternatives.
Market Restraints
- Photobioreactor capex concentration:Closed-system cultivation infrastructure requires substantial upfront investment, limiting viable production to well-capitalized operators with access to Dutch or French industrial zones.
- REACH solvent compliance costs:Extraction solvent registration and toxicity testing under ECHA frameworks add regulatory overhead that mechanical disruption methods avoid, tilting processing economics toward lower-yield alternatives.
- Soy protein isolate substitution:Established oilseed processing infrastructure delivers comparable protein concentrations at lower unit costs, constraining algal protein penetration in price-sensitive animal feed segments.
Strategic Opportunities
- EFSA novel food queue acceleration:Streamlined authorization procedures for microalgae biomass are reducing approval timelines, creating first-mover advantages for dossier-ready suppliers targeting human-grade ingredient markets.
- Pet food premiumization:Companion animal nutrition brands are sourcing astaxanthin-enriched spirulina for coat health positioning, opening a high-margin channel with less stringent regulatory barriers than human food.
- Precision fermentation convergence:Integration of heterotrophic algal strains with existing brewery and pharma fermentation infrastructure in Belgium and Ireland offers capital-efficient production scaling without dedicated photobioreactor builds.
Industry Challenges
- Phycocyanin stabilization expertise scarcity:Few formulation chemists possess demonstrated competency in preserving blue pigment bioactivity through thermal processing, creating bottlenecks for beverage applications.
- Organic certification timeline compression:USDA and EU organic handling requirements demand 36-month substrate traceability documentation that many open-pond operators cannot satisfy, excluding them from premium label claims.
- Downstream integration complexity:Protein isolate producers lack in-house extrusion capabilities for texturized vegetable protein manufacturing, forcing reliance on third-party toll processors with competing customer priorities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Algal Protein Market |
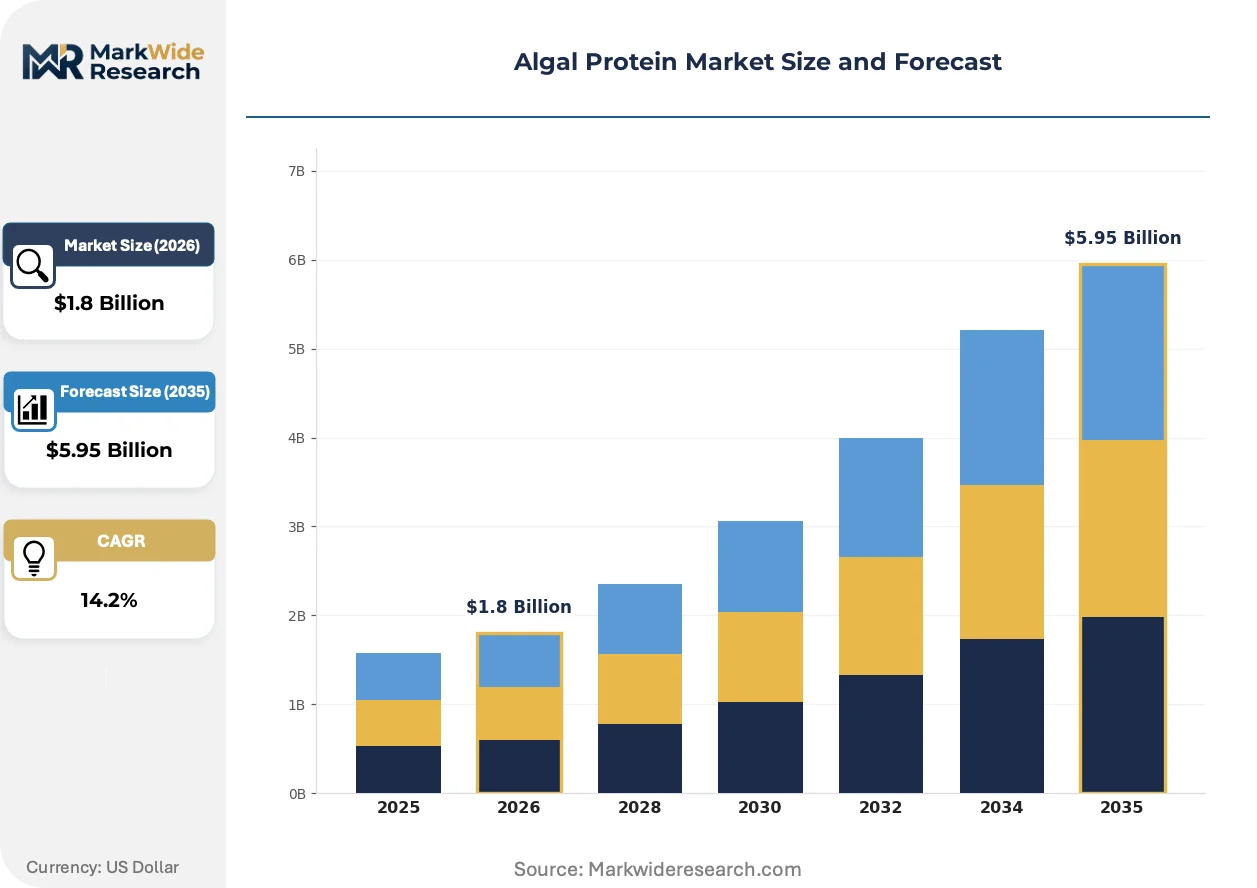
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spirulina, Chlorella, Dunaliella, Aphanizomenon End User: Food & Beverage, Dietary Supplements, Animal Feed, Cosmetics Extraction Method: Solvent Extraction, Mechanical Extraction, Drying Method, Enzymatic Extraction Application: Functional Foods, Nutraceuticals, Biofuels, Aquaculture |
| Companies Covered | Corbion, Cyanotech Corporation, Roquette Frères, Earthrise Nutritionals, Far East Bio-Tec Co., Ltd., EID Parry, Parry Nutraceuticals, Phycom, Seagrass Tech Private Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Algal Protein Market Strategic Shifts
Processing technology maturation and regulatory pathway clarification are converging to reposition algal protein from niche nutraceutical additive to mainstream functional ingredient, with extraction method selection emerging as the primary competitive differentiator.
Enzymatic protein extraction is overtaking mechanical cell disruption as the dominant processing paradigm for human-grade applications. Food formulators in Germany and the Netherlands are specifying enzyme-treated isolates for their superior digestibility scores and preserved bioactive peptide fractions. This shift is compressing margins for legacy spray-dry operators while rewarding suppliers with in-house fermentation-derived enzyme capabilities.
EFSA's 2023 guidance on algae-specific contaminant limits is tightening heavy metal and microcystin thresholds for novel food authorizations. Dutch and French producers are retrofitting closed photobioreactor systems with enhanced filtration and UV treatment stages to preempt compliance failures. Premium supplement brands are responding by sourcing exclusively from facilities with third-party batch testing protocols exceeding baseline regulatory requirements.
Sports nutrition procurement is consolidating around direct-supplier relationships that bypass traditional ingredient distributors. Large European contract manufacturers are negotiating multi-year offtake agreements with specific Dutch and French cultivation facilities, displacing spot-market purchasing through wholesale brokers. This pattern is most pronounced in Germany, where vertically integrated brands are securing dedicated production runs with customized protein concentration specifications.
Algal Protein Market Segmentation
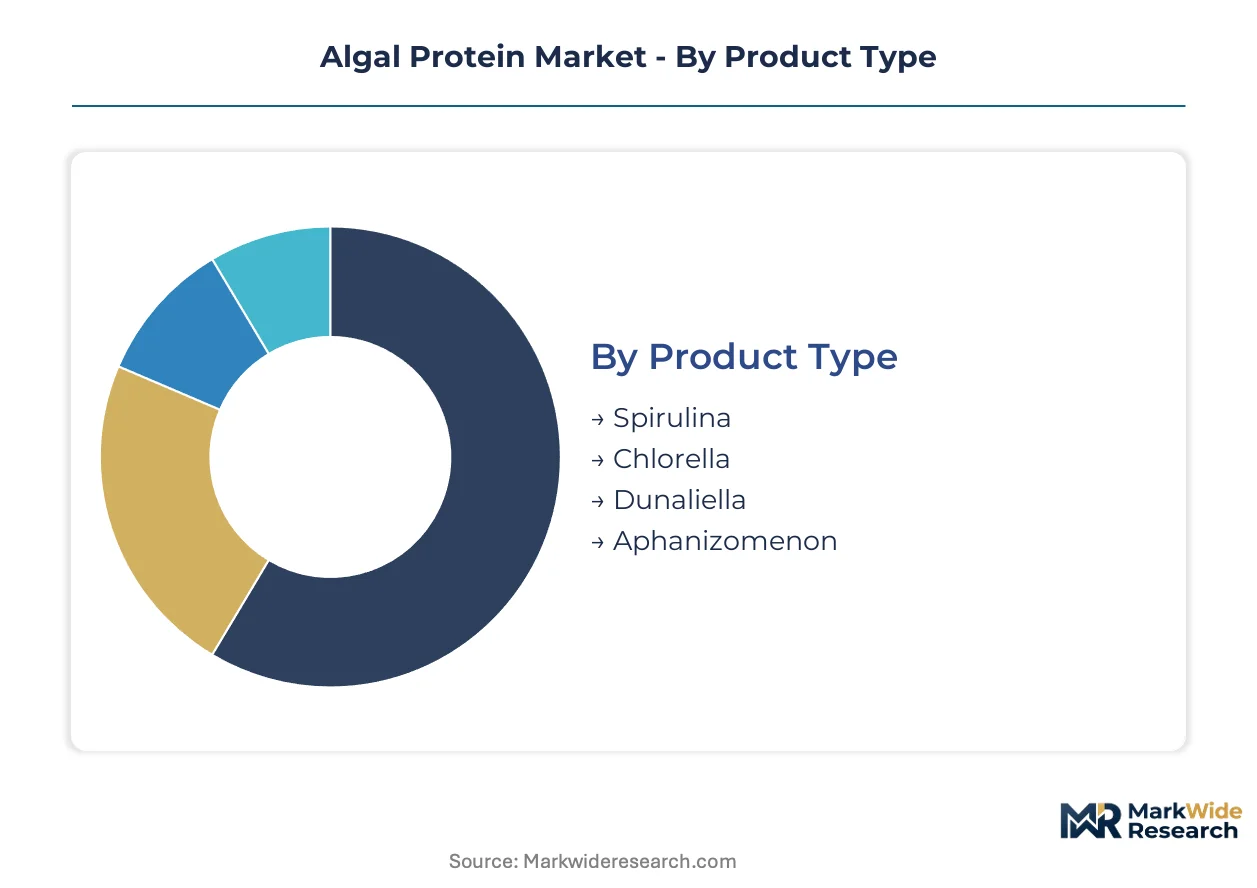
Algal protein procurement patterns diverge sharply between commodity-scale animal feed buyers and premium human nutrition formulators. Understanding these segment boundaries reveals where enzymatic extraction investments generate returns versus where mechanical methods retain cost advantages.
Product Type:
Spirulina commands volume leadership through established cultivation infrastructure, while chlorella extracts premium pricing from chlorophyll positioning and detoxification claims.
- Spirulina:Cyanobacterial biomass containing 60-70% protein by dry weight with GRAS status across multiple jurisdictions. German sports nutrition brands specify spirulina isolates for amino acid completeness in recovery formulations, though price competition from soy concentrates constrains feed-grade penetration.
- Chlorella:Single-celled green algae with rigid cell walls requiring mechanical or enzymatic disruption for protein bioavailability. Dutch clean-label manufacturers source chlorella for chlorophyll-rich positioning in detoxification supplements, paying premiums for broken-cell processing that enhances digestibility.
- Dunaliella:Halophilic microalgae cultivated in high-salinity ponds for beta-carotene co-extraction with protein isolates.
- Aphanizomenon:Freshwater cyanobacteria harvested from natural blooms in specific lake ecosystems, facing supply inconsistency challenges.
Mature deployment sits with spirulina across commodity and premium channels. Newer deployment is concentrated in chlorella as EFSA novel food authorizations validate chlorophyll bioactive claims.
End User:
Human-grade applications extract 3-5x protein pricing multiples over feed-grade offtake, driving supplier prioritization toward pharmaceutical-grade extraction investments.
- Food & Beverage:Plant-based meat formulators in the Netherlands incorporate algal protein for emulsification and color stability in burger analogues. EFSA novel food dossiers dominate procurement timelines, with enzymatic isolates specified for neutral flavor profiles that mask marine off-notes.
- Dietary Supplements:French premium brands source astaxanthin-enriched spirulina for antioxidant positioning in capsule and powder formats. Third-party contaminant testing protocols exceed baseline regulatory requirements as heavy metal thresholds tighten under pending EU-wide algae legislation.
- Animal Feed:Aquaculture and poultry operations in Germany trial algal protein as fishmeal replacement, constrained by soy isolate cost competitiveness.
- Cosmetics:Phycocyanin-derived blue pigments command specialty pricing in skincare formulations with limited volume scale.
Revenue concentration follows dietary supplements, where margin structures justify photobioreactor capex. Volume expansion is accelerating fastest in food and beverage as clean-label positioning penetrates mainstream retail.
Extraction Method:
Processing technology selection determines protein digestibility scores, bioactive peptide preservation, and regulatory compliance pathways simultaneously.
- Enzymatic Extraction:Cellulase and protease treatments rupture cell walls at ambient temperatures, preserving heat-sensitive amino acids and bioactive fractions. German contract manufacturers specify enzyme-treated isolates for sports nutrition applications where lysine retention directly impacts protein quality ratings.
- Mechanical Extraction:Bead milling and high-pressure homogenization deliver lower unit costs but generate thermal degradation of phycocyanin pigments. French open-pond operators favor mechanical disruption for feed-grade biomass where protein denaturation thresholds are less stringent.
- Solvent Extraction:Ethanol or hexane processing for lipid co-extraction faces REACH registration overhead that tilts economics toward mechanical alternatives.
- Drying Method:Spray-drying and freeze-drying represent terminal processing stages rather than protein isolation techniques, with freeze-dried powders commanding premiums in raw superfood channels.
Capital deployment concentrates in enzymatic systems for human-grade facilities. Mechanical infrastructure retains dominance in feed-grade operations where margin compression prohibits enzyme input costs.
Application:
Functional positioning versus commodity substitution dictates formulation specifications and supplier qualification requirements across end-use categories.
- Functional Foods:Algal protein isolates serve as emulsifiers, colorants, and nutritional fortifiers in pasta, bakery, and dairy alternatives. Dutch food formulators specify protein concentrations above 65% for clean-label positioning against pea and rice blends.
- Nutraceuticals:Bioactive peptide fractions with antioxidant and immunomodulatory claims drive premium pricing in capsule and tablet formats. French supplement brands source exclusively from closed photobioreactor facilities with documented carbon footprints aligned with EU Green Deal procurement mandates.
- Biofuels:Residual biomass from protein extraction supplies lipid fractions for renewable diesel, though economics depend on co-product valorization.
- Aquaculture:Salmon and shrimp feed trials substitute algal protein for fishmeal, constrained by palatability challenges and amino acid balancing requirements.
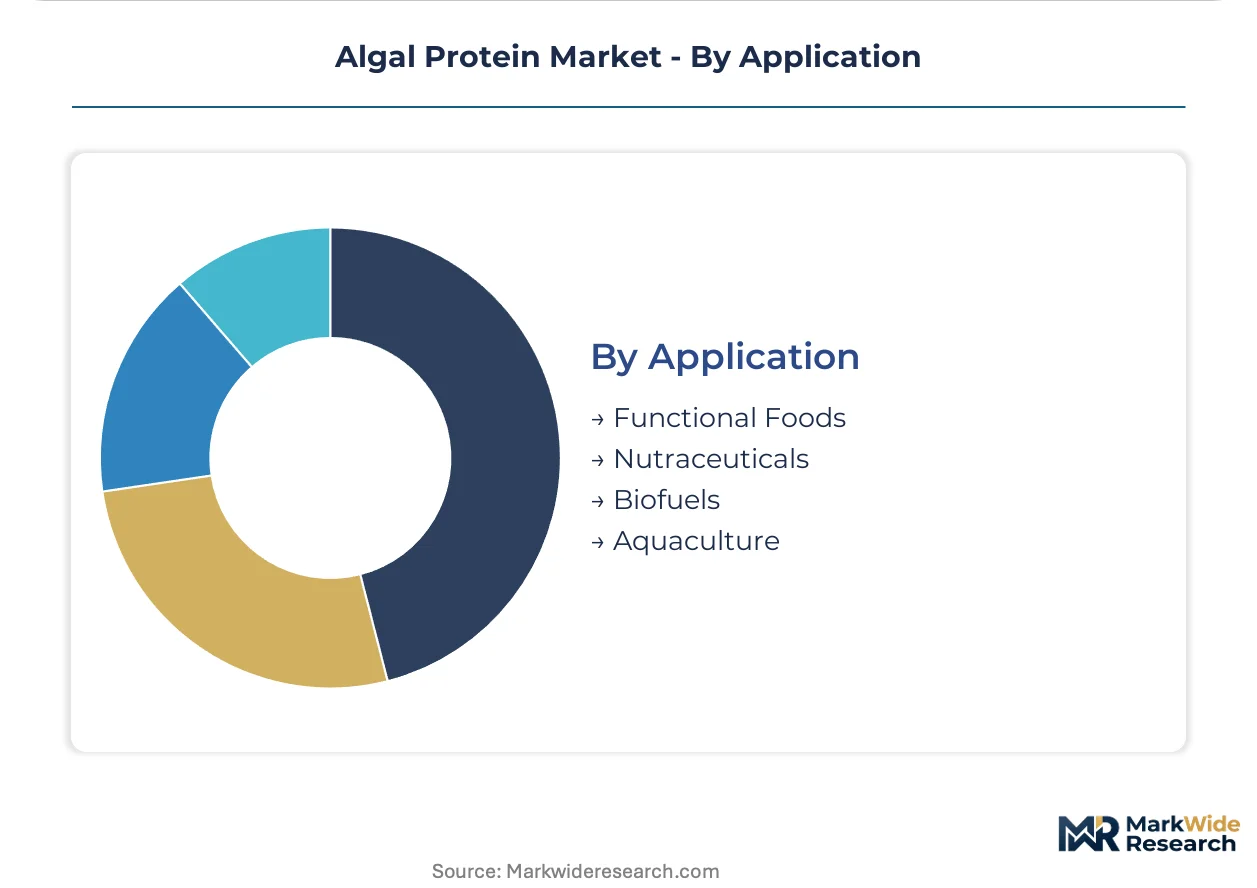
Commercial maturity centers on nutraceuticals, where established extraction protocols meet defined regulatory pathways. Steepest expansion trajectory is emerging in functional foods as enzymatic processing achieves cost parity with legacy mechanical methods at commercial scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gouda and the surrounding Dutch industrial corridor anchor European algal protein production capacity, with photobioreactor clusters serving German and French formulators under EU Green Deal procurement mandates. Facility construction concentrates in port-adjacent zones with established fermentation infrastructure and carbon footprint verification capabilities.
Germany
Berlin and Hamburg institutional buyers now require documented low-carbon protein sourcing for public food service contracts under federal procurement guidelines. EFSA novel food dossier processing accelerates market entry for enzymatic isolates targeting sports nutrition brands. North Rhine-Westphalia hosts contract manufacturers negotiating multi-year offtake agreements with Dutch cultivation facilities.
Netherlands
Roquette Frères and Corbion operate integrated production networks supplying human-grade isolates to European formulators. REACH compliance for extraction solvents shapes processing economics across Rotterdam port zones. The Randstad cluster concentrates enzymatic extraction expertise serving German clean-label manufacturers.
France
Paris-based premium supplement brands source astaxanthin-enriched spirulina for antioxidant positioning in capsule formats. ANSM oversight of novel food claims intersects with EU organic certification requirements. Auvergne-Rhône-Alpes hosts microalgae cultivation partnerships supplying functional food formulators.
United States
FDA GRAS notifications enable spirulina incorporation across sports nutrition and beverage applications. California clean-label manufacturers specify Hawaiian-sourced biomass for phycocyanin pigment stability. The Pacific Northwest concentrates extraction technology providers serving domestic nutraceutical brands.
India
FSSAI novel food regulations govern chlorella and spirulina import and domestic production for supplement channels. Tamil Nadu open-pond operators face organic certification timeline compression under USDA equivalency requirements. EID Parry anchors domestic supply through integrated cultivation and processing infrastructure.
Algal Protein Market Competitive Environment
Premium-margin players sit above commodity-margin players across extraction technology and certification tiers, with enzymatic processing capabilities commanding pricing multiples over mechanical disruption methods. The vendor base stratifies between closed-photobioreactor operators with carbon footprint documentation and open-pond suppliers serving feed-grade segments. Three archetypes dominate: integrated cultivation-extraction specialists, toll-processing contract manufacturers, and brand-house formulators with captive supply agreements. Competitive moves concentrate on EFSA dossier preparation for novel food authorization and backward integration into fermentation-derived enzyme production.
Within the integrated specialist tier, Corbion leverages Dutch infrastructure to supply high-purity isolates, while Cyanotech Corporation anchors premium positioning through Hawaiian production. Roquette Frères exemplifies the European industrial conglomerate archetype with microalgae cultivation partnerships in France. These three represent distinct geographic and technological positioning strategies without overlapping customer segments.
| Leading Market Players |
|---|
| Corbion |
| Cyanotech Corporation |
| Roquette Frères |
| Earthrise Nutritionals |
| Far East Bio-Tec Co., Ltd. |
| EID Parry |
| Parry Nutraceuticals |
| Phycom |
| Seagrass Tech Private Limited |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal procurement mandates for verified low-carbon protein sourcing are forcing institutional buyers toward photobioreactor-derived biomass with documented carbon footprints, compelling supply chain reconfiguration around Dutch and French cultivation clusters and compressing margins for open-pond operators unable to meet certification thresholds.
Pricing Analysis
Value-based pricing anchored to protein digestibility scores and bioactive peptide preservation dominates human-grade segments, with enzymatic isolates commanding premiums over mechanically disrupted alternatives. Three-tier pricing structure across premium, standard, and economy levels separates closed-photobioreactor isolates with EFSA novel food authorization from open-pond feed-grade biomass and commodity spirulina powders. Cost compression in feed-grade tiers is intensifying because soy protein isolate substitution maintains cost competitiveness for animal nutrition formulators. Animal feed buyers exhibit highest price sensitivity, while German sports nutrition brands and French premium supplement houses demonstrate lowest sensitivity when lysine retention and phycocyanin stability are guaranteed.
Supply Chain Analysis
Workforce availability constraints in Dutch and French industrial zones are concentrating enzymatic extraction expertise around Rotterdam and Gouda, with Randstad clusters drawing formulation chemists from broader EU labor pools. Supply concentrates in the Netherlands, France, and Germany, with Belgian and Irish fermentation infrastructure emerging as secondary hubs. Raw material dependencies center on fermentation-derived cellulase and protease enzymes, photobioreactor construction materials, and organic-certified growth media. Single-source vulnerability around Hawaiian astaxanthin-enriched spirulina creates geographic concentration risk for premium pigment supply. Distribution runs through direct-supplier relationships with European contract manufacturers, displacing traditional ingredient distributors in sports nutrition procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EFSA novel food authorization pathways function as a cost-of-compliance barrier, with dossier preparation expenses and contaminant testing protocols creating a regulatory moat that rewards early-mover suppliers while excluding capital-constrained open-pond operators from human-grade segments.
For Market Incumbents: Lock in multi-year offtake agreements with German contract manufacturers before enzymatic extraction capacity saturates the Randstad corridor. Prioritize backward integration into fermentation-derived enzyme production to secure input cost control against supply tightening. Defend margin position by accelerating phycocyanin stabilization expertise acquisition before beverage application demand outstrips qualified formulation chemist supply. For New Entrants and Emerging Players: Capture pet food premiumization channels where astaxanthin-enriched spirulina faces less stringent regulatory barriers than human food applications. Target precision fermentation convergence opportunities in Belgian and Irish brewery infrastructure to bypass photobioreactor capex requirements. Lead with coat health positioning in companion animal nutrition as the most penetrable white-space segment with established margin structures. For Investors and Strategic Acquirers: The window for entry favors integrated cultivation-extraction specialists with EFSA dossier readiness and carbon footprint documentation capabilities aligned with EU Green Deal procurement mandates. Long-term viability hinges on regulatory compliance infrastructure rather than commodity biomass production. Watch for EFSA algae-specific contaminant limit finalization as the signal indicating accelerated consolidation toward closed-photobioreactor operators.| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Novel Food Dossier Preparation | First-mover authorization creates exclusive supply relationships with Dutch and German formulators. |
| Backward Integration into Enzyme Production | In-house cellulase and protease capabilities reduce input cost exposure and improve isolate margins. |
| Pet Food Channel Expansion | Astaxanthin-enriched spirulina for coat health opens high-margin revenue with lower regulatory barriers. |
| Precision Fermentation Infrastructure Partnership | Brewery and pharma fermentation retrofit in Belgium and Ireland enables capital-efficient capacity scaling. |
| Carbon Footprint Verification Certification | Documented low-carbon biomass sourcing satisfies EU Green Deal public procurement mandates. |
Study Parameters
Multi-period observation of EFSA novel food authorization timelines, enzymatic extraction capacity buildouts, and EU Green Deal procurement contract awards anchored the trend analysis, supplemented by interviews with Dutch cultivation facility operators, German sports nutrition formulators, French premium supplement brand managers, and extraction technology providers. Secondary validation drew from EFSA novel food registry entries, REACH compliance documentation, EU public procurement databases, and trade flow records through Rotterdam port zones. Bottom-up facility capacity estimates triangulated against top-down segment demand projections.
Segment-weighting approaches applied differential growth assumptions across human-grade versus feed-grade applications, enzymatic versus mechanical extraction methods, and closed-photobioreactor versus open-pond supply sources. Modeled dimensions included product type, end-user industry, extraction technology, and geographic regulatory cluster. CAGRs were derived from installed capacity trajectories, offtake agreement visibility, and substitution elasticity estimates for soy protein isolates. Industry-specific inputs incorporated phycocyanin stabilization technical maturity and organic certification timeline compression effects.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EFSA contaminant limit finalization, REACH solvent registration cost inflation, and soy protein isolate price volatility. Forecasts reflect assumptions around regulatory pathway stability and enzymatic processing cost parity achievement. Material deviation in EFSA authorization timelines or EU Green Deal procurement mandate enforcement warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
Mushroom Protein Market
Alternative Food Sources
Insect Protein Market
Alternative Food Sources
Edible Packaging Market
Alternative Food Sources
North America Fat Replacers Market
Alternative Food Sources
North America Edible Insects Market
Alternative Food Sources
Fishless Fillets Market
Alternative Food Sources
Dunaliella Salina Market
Alternative Food Sources
Global Algae Protein Market
Alternative Food Sources
Fish Oil Alternatives Market
Alternative Food Sources
Spirulina Market
Alternative Food Sources
Meat Analogue Market
Alternative Food Sources
Egg Substitutes Market
Alternative Food Sources
Edible Insects Market
Alternative Food Sources
Precision Fermentation Market
Alternative Food Sources
Microalgae Based Products Market
Alternative Food Sources
Fat Replacers Market