
 Artificial Meat Market | 2026-2036
Artificial Meat Market Size, Share, and Industry Trends Forecast 2026-2036
Artificial Meat Market Intelligence
New production facility investments in the United States and the Netherlands are reconfiguring the supply landscape for cultured meat. Upside Foods leverages its early-mover advantage in securing US regulatory clearances. Mosa Meat specializes in scaling up beef cultivation technologies from its European base. Aleph Farms differentiates through its focus on developing complex, structured cultured steak products, addressing a premium segment of the market.
Artificial meat encompasses food products engineered to replicate the sensory and nutritional qualities of conventional meat using non-animal sources. These products are created via processes like cell culture proliferation in bioreactors or high-moisture extrusion of plant proteins. Cultured meat represents the fastest-growing product type, driven by advances in cell culture and precision fermentation technologies. Plant-based meat currently holds the largest market share due to its established retail presence and lower production costs.
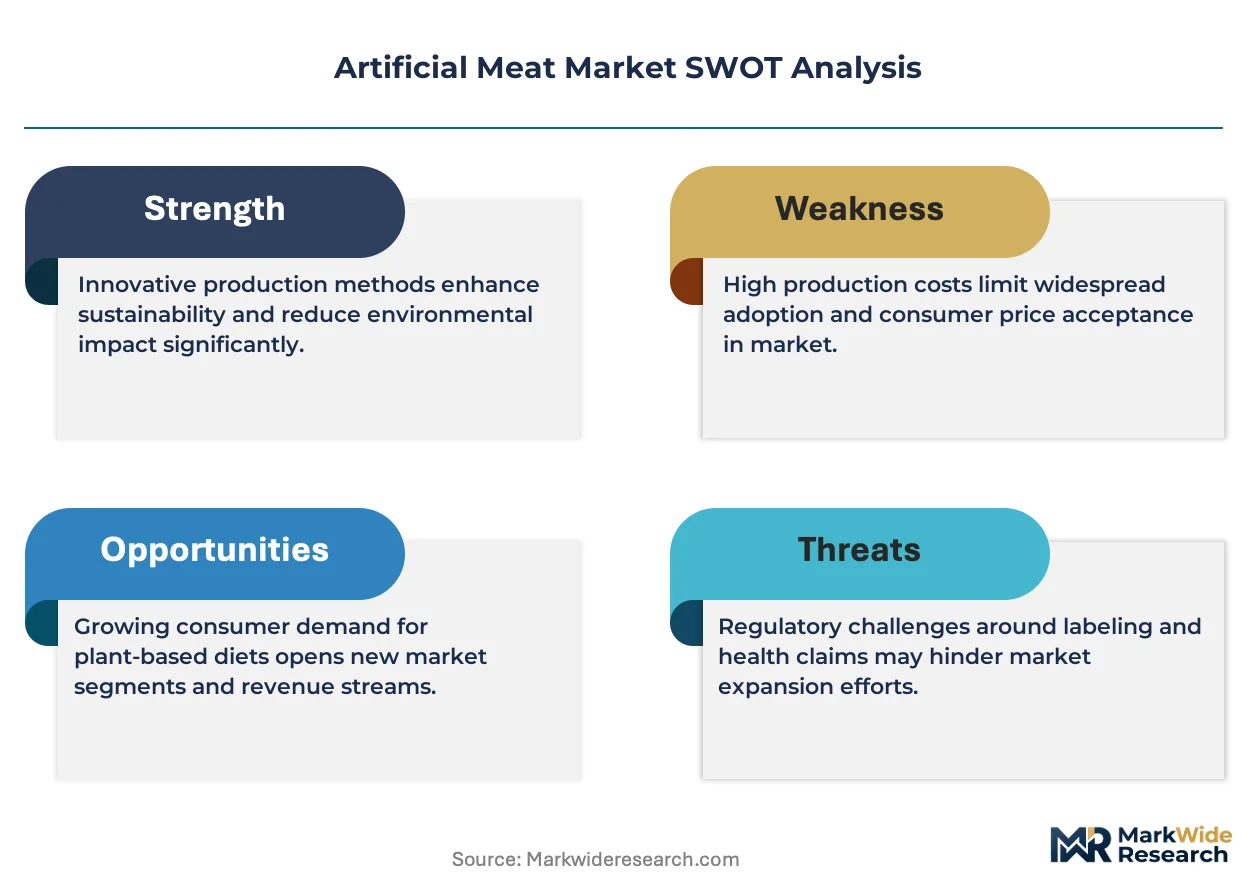
Market access depends on navigating a complex web of food safety regulations. The FDA in the United States and EFSA in Europe are establishing frameworks for cultured meat, while Singapore's SFA has already approved products for sale. Achieving price parity with conventional meat and securing clear, consumer-friendly labeling guidelines are critical next steps for industry-wide expansion.
Market Dynamics
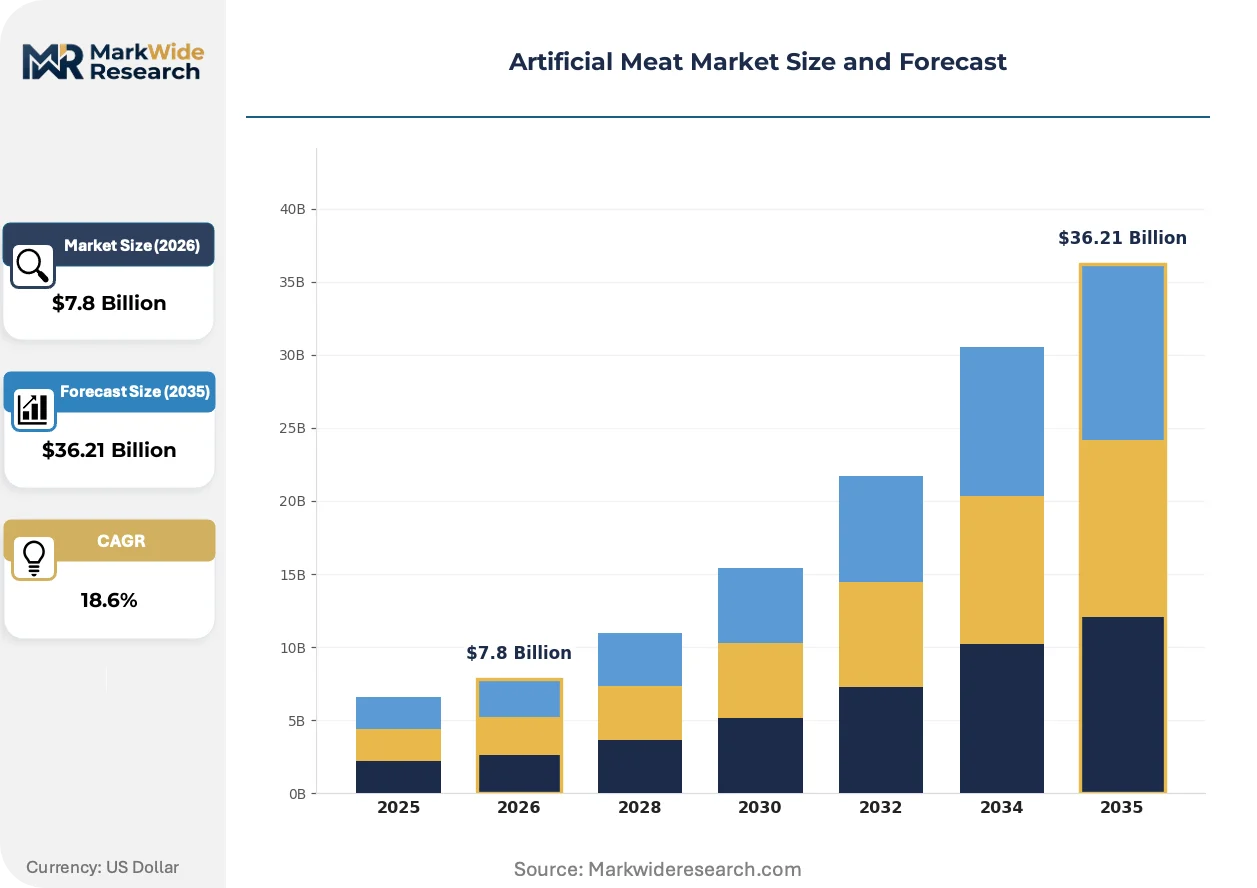
The artificial meat market's trajectory is defined by the interplay between rapid technological advancements in bioprocessing and the deliberate, cautious pace of global food safety regulators. Progress in cell culture media formulation is lowering production barriers, while agencies like the FDA and EFSA establish foundational safety frameworks.
Growth Catalysts
- Technological Advancement:Innovations in precision fermentation and bioreactor efficiency are reducing the cost and improving the scalability of cultured meat production, making it more viable for mass-market adoption.
- Foodservice Sector Expansion:Restaurants and institutional caterers are increasingly incorporating alternative proteins into menus to meet consumer demand for sustainable and novel food options, creating a significant B2B channel.
- Regulatory Clarity:The Singapore Food Agency's (SFA) approval of cultured meat for commercial sale provides a clear regulatory model, encouraging investment and development by demonstrating a viable path to market.
Market Restraints
- High Production Costs:The expense of pharmaceutical-grade growth factors and complex bioreactor systems keeps the cost of cultured meat significantly higher than conventional meat, limiting its price competitiveness.
- Regulatory Bottlenecks:Lengthy and complex approval processes, such as the novel food pathway managed by the EFSA in Europe, create significant delays and uncertainty for companies seeking market entry.
- Consumer Acceptance:Public skepticism regarding the safety, naturalness, and long-term health effects of cultured meat products presents a major hurdle for widespread adoption, requiring transparent communication and clear labeling.
Strategic Opportunities
- Product Differentiation:Developing complex, whole-cut cultured meat products, such as steaks and fillets, allows producers to target premium market segments and command higher price points, bypassing initial price competition.
- Hybrid Formulations:Combining plant-based ingredients with cultured cells offers a path to create products with improved taste and texture at a lower cost than fully cultured options, appealing to a broader consumer base.
- Geographic Expansion:Targeting markets like the Netherlands and the United States, where governments and regulators are actively creating supportive frameworks, provides first-mover advantages for establishing production and distribution.
Industry Challenges
- Scaling Production Infrastructure:The immense capital investment required to construct large-scale bioreactor facilities capable of producing cultured meat at volumes that can compete with the conventional meat industry is a primary constraint.
- Specialized Talent Scarcity:A shortage of professionals with expertise in both cell biology and large-scale bioprocess engineering hinders the ability of companies to effectively scale from laboratory pilots to commercial production.
- Standardization Gaps:The absence of industry-wide standards for cell line validation, product composition, and safety testing complicates regulatory submissions and can slow down the approval process across different jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artificial Meat Market |
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $36.21 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cultured Meat, Plant-Based Meat, Hybrid Meat, Insect Protein Technology: Cell Culture, Fermentation, 3D Bioprinting, Precision Fermentation Application: Foodservice, Retail, Food Processing, Institutional Catering End User: Restaurants, Food Manufacturers, Cafeterias, Food Retailers |
| Companies Covered | Aleph Farms, GOOD Meat, Upside Foods, Mosa Meat, Meatable, SuperMeat, Believer Meats, Wildtype, BlueNalu, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artificial Meat Market Strategic Shifts & Innovations
The industry's evolution is marked by a convergence of biotechnology, data science, and food engineering. This is creating new methods to enhance sensory profiles, reduce costs, and accelerate the path from lab to consumer, fundamentally altering production economics.
Artificial intelligence platforms are being applied to accelerate the development of cell culture media and optimize bioreactor performance. Food technology companies are adopting these computational tools to rapidly screen thousands of potential nutrient combinations, identifying more effective and less expensive formulations. This application of advanced modeling is digitizing the historically slow, trial-and-error process of bioprocess development, compressing R&D timelines for new products.
In the United States, a dual-oversight framework between the FDA and USDA is formalizing the regulatory pathway for cultured meat. This system assigns the FDA to oversee cell collection and culture processes, while the USDA manages final product labeling and facility inspections for meat and poultry products. Cultured seafood and poultry producers are most directly impacted, as they are the first to navigate this coordinated process to secure commercial approval.
A notable shift in product strategy involves the development of hybrid goods that blend plant-based proteins with cultured animal cells. This approach disrupts the binary choice between plant-based and cultured options, aiming to deliver the authentic flavor of meat at a more accessible price point. This trend is most prominent in the ground meat alternative category within North American and European retail markets, where consumer cost-sensitivity is a critical purchasing factor.
Artificial Meat Market Segmentation
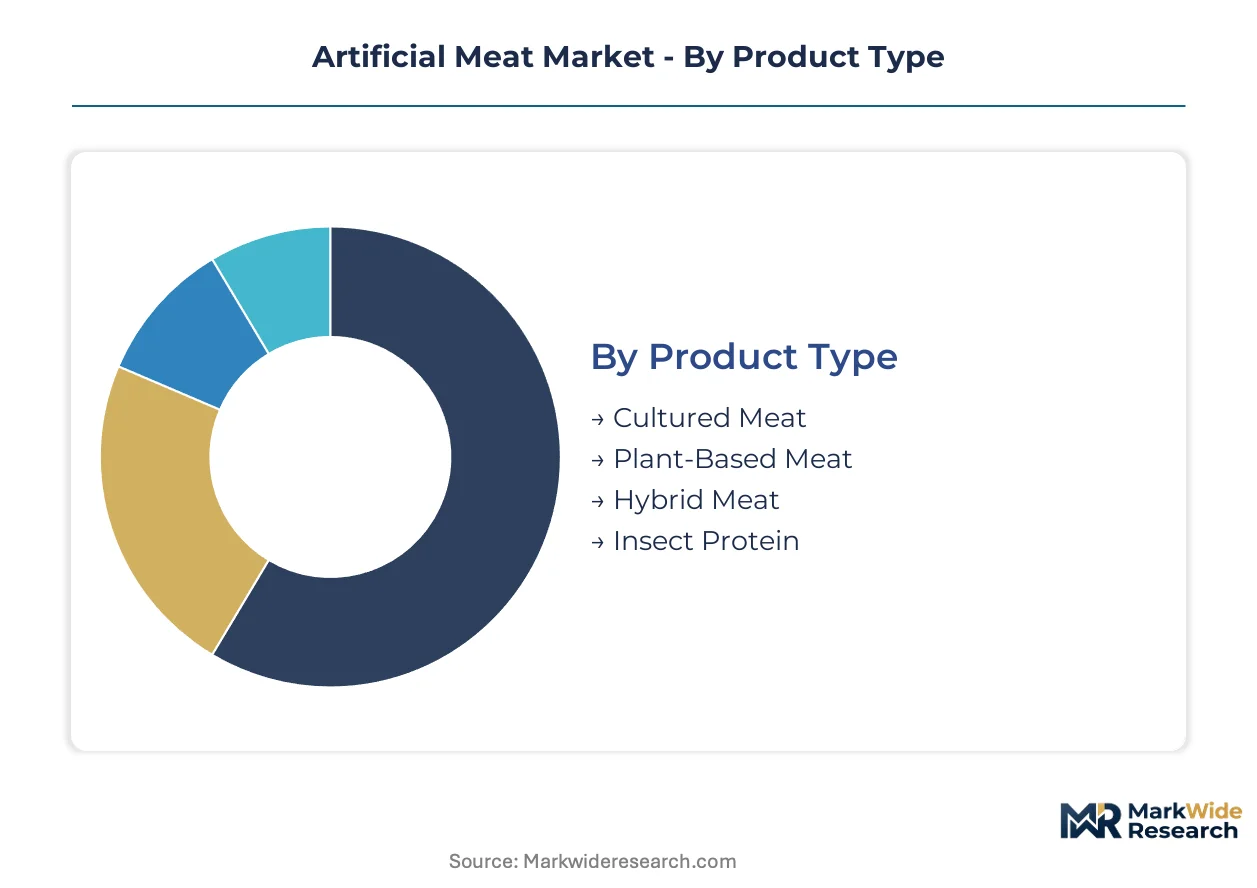
The artificial meat market is segmented to reveal distinct product lifecycles and technological adoption rates across its diverse offerings. Understanding these categories helps stakeholders identify areas of rapid innovation and established market penetration. This granular view informs strategic investments and market entry decisions.
Product Type:
The artificial meat market's product types exhibit varying development cycles, with some segments achieving rapid commercialization while others remain in advanced R&D stages.
- Cultured Meat:This product involves growing animal cells in bioreactors to produce meat without animal slaughter. Demand concentrates in Singapore and the United States, driven by regulatory clearances and scaling infrastructure.
- Plant-Based Meat:Composed of plant proteins and fats, these products mimic conventional meat's texture and flavor. Consumer demand for sustainable and healthier options fuels widespread retail presence in North America and Europe.
- Hybrid Meat:These products combine plant-based components with cultured animal cells. This formulation aims for improved sensory attributes and cost efficiency, particularly in ground meat applications.
- Insect Protein:Derived from insects, this segment offers a protein-rich alternative, often processed into powders. Its market penetration remains niche, targeting specialized nutrition sectors.
Plant-Based Meat dominates installed base. Cultured Meat is where expansion concentrates.
Technology:
Technological approaches to artificial meat production vary significantly in their current cost structures, impacting commercial viability and scalability.
- Cell Culture:This core technology involves animal cell proliferation in bioreactors using specific growth media. Advances in media formulation reduce input costs, making large-scale biomanufacturing economically feasible for producers like Mosa Meat.
- Precision Fermentation:This method uses microorganisms to produce specific proteins or fats, like heme, without animal inputs. It creates functional ingredients enhancing flavor and texture, driving adoption in North American food development.
- 3D Bioprinting:This advanced technique layers cells and biomaterials to create structured, whole-cut meat products. Its application remains in R&D, focusing on complex textures.
- Fermentation:This broad category includes biomass fermentation, where microorganisms produce protein-rich biomass. It offers a cost-effective route for bulk protein ingredients.
Cell Culture technologies currently offer the most established production pathways. Precision Fermentation is gaining share fastest in ingredient innovation.
Application:
The artificial meat market's application segments demonstrate varied volume requirements and consumer touchpoints, influencing distribution strategies.
- Foodservice:This segment includes restaurants and cafes serving prepared artificial meat dishes. Expansion is driven by chefs incorporating alternative proteins into menus, particularly in the United States and the Netherlands.
- Retail:Comprising supermarkets and online grocery platforms, this channel offers packaged artificial meat products directly to consumers. Consumer-friendly labeling and competitive pricing are critical for widespread adoption in European and North American markets.
- Food Processing:This application uses artificial meat ingredients in processed foods like frozen meals and snacks. Manufacturers integrate these components for specific dietary trends.
- Institutional Catering:This segment provides large-scale food for schools and corporate cafeterias. Sustainability mandates often drive inclusion of alternative protein options.
Retail channels manage the largest product volumes for artificial meat. Foodservice expansion represents the steepest expansion trajectory.
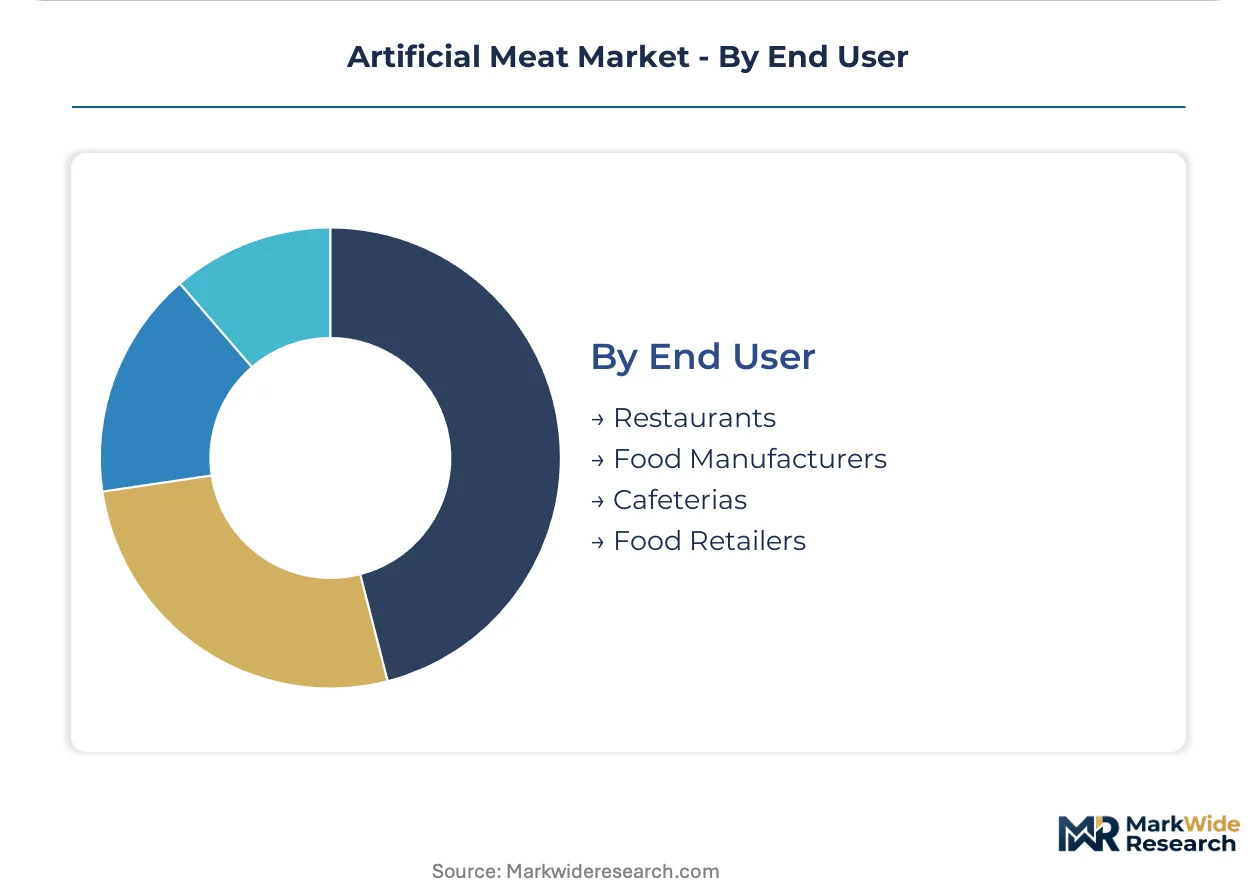
End User:
End-user segments define distinct customer types with varied purchasing motivations and product preferences within the artificial meat market.
- Restaurants:These establishments purchase artificial meat for immediate preparation and serving to diners. They seek versatile ingredients appealing to evolving consumer tastes, especially in urban centers.
- Food Retailers:Supermarkets and grocery stores stock packaged artificial meat products for household consumption. Clear branding, convenient packaging, and competitive pricing attract regular shoppers across North America and Europe.
- Food Manufacturers:These companies incorporate artificial meat components into their product lines for further processing. They prioritize consistency, cost-effectiveness, and integration into existing systems.
- Cafeterias:Institutional cafeterias procure artificial meat for sustainable and dietary-inclusive meal options. Bulk purchasing and nutritional value are key considerations.
Food Retailers command significant purchasing power due to broad consumer reach. Restaurants are increasingly diversifying their menus with these products.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supply-side investments in artificial meat production are reconfiguring market availability across key geographies. These strategic deployments focus on regions with supportive regulatory frameworks and established consumer interest. Pioneering markets are attracting significant capital for scaling up novel food technologies.
United States
Consumer demand for sustainable and novel food options drives artificial meat adoption in the United States. The FDA and USDA dual-oversight framework formalizes regulatory pathways for cultured meat, enabling market entry. California's biomanufacturing cluster attracts significant investment, with companies leveraging early regulatory clearances for production.
Singapore
Singaporean consumers show high acceptance for novel food technologies, boosting demand for cultured proteins. The Singapore Food Agency (SFA) established the world's first regulatory approval for cultured meat, setting a global precedent. The city-state's advanced food science parks foster R&D, making it a crucial test market for new products.
Netherlands
The Netherlands exhibits strong research and development in alternative proteins, fostering demand for innovative meat substitutes. Dutch regulatory bodies actively engage with EFSA guidelines, preparing for broader European market access. The Wageningen Food Valley hosts leading research institutions and startups, driving technological advancements in cellular agriculture.
Germany
German consumers increasingly seek plant-based and novel protein options, influencing retail and foodservice demand. EFSA's novel food pathway guides regulatory approvals for cultured meat across the European Union, impacting German market entry. Berlin's vibrant startup ecosystem supports alternative protein companies, focusing on product development and consumer education.
United Kingdom
UK consumers demonstrate a growing appetite for diverse protein sources, particularly in urban centers. The Food Standards Agency (FSA) is developing its own regulatory framework for novel foods, anticipating future cultured meat applications. London's financial and innovation sectors support new ventures, focusing on scaling production and market penetration.
Artificial Meat Market Key Industry Players
Early-stage innovators focused on cellular agriculture and established food conglomerates diversifying into alternative proteins split the artificial meat market. The competitive landscape features specialized biotech startups driving R&D alongside larger entities leveraging existing distribution networks. Companies prioritize significant capacity expansion and strategic partnerships to overcome scaling challenges inherent in novel food production. Portfolio diversification through hybrid products also represents a key competitive move to capture broader consumer interest.
The competitive landscape includes companies specializing in distinct product development and market entry strategies. For instance, Upside Foods exemplifies the early-mover archetype, having secured initial regulatory clearances in the United States for its cultured chicken products. Mosa Meat, based in Europe, represents a pioneering effort in scaling beef cultivation technologies for mass production. Aleph Farms, another significant player, focuses on developing complex, structured cultured steak products, targeting the premium segment of the artificial meat market. These companies collectively illustrate the diverse approaches to commercializing novel protein sources.
| Leading Market Players |
|---|
| Aleph Farms |
| GOOD Meat |
| Upside Foods |
| Mosa Meat |
| Meatable |
| SuperMeat |
| Believer Meats |
| Wildtype |
| BlueNalu |
| Others |
Cost & Logistics Intelligence
Transatlantic shipping lanes for specialized bioreactor components and growth media drive input costs, influencing supply concentration in pioneering markets and shaping downstream price differentiation for advanced artificial meat products.
Pricing Analysis
FDA and EFSA frameworks dictate the pricing tier structure for novel artificial meat products, particularly cultured meat. Pricing stratifies across premium, standard, and economy tiers, with whole-cut cultured steaks commanding higher price points than ground hybrid options. Brand premium and regulatory approval status are key price differentiation drivers. Cost compression in plant-based options is intensifying due to economies of scale, creating pricing pressure across the broader category. Retail consumers in North America and Europe demonstrate high price sensitivity, while foodservice operators prioritize product consistency and unique menu offerings.
Supply Chain Analysis
Advanced bioprocessing technology transfer restrictions could limit the global flow of critical manufacturing know-how and equipment for cultured meat production. Geographic supply concentration for key inputs centers on specialized cell culture media components sourced from pharmaceutical-grade suppliers in the United States and Europe. Raw material dependencies include pharmaceutical-grade growth factors and specialized bioreactor systems. Single-source vulnerability for these complex inputs represents a structural supply chain risk. Distribution runs through both direct-to-foodservice channels and established retail networks in markets like Singapore and the Netherlands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The artificial meat market presents a service-attach opportunity, with recurring revenue from optimized cell culture media supply expanding faster than initial bioreactor hardware sales.
For Market Incumbents: Insulate market incumbents against emerging competition by acquiring promising cell-based technology startups and investing heavily in hybrid product development. This defends against both novel food skepticism and the threat from specialized cultured meat producers. Prioritize R&D into cost-effective cell culture media formulations and leverage existing retail channel control to introduce new product lines.
For New Entrants and Emerging Players: Build out specialized production capabilities in regulatory-friendly geographies like Singapore and the United States. Target the premium whole-cut cultured meat segment or specialized B2B ingredient supply for food manufacturers. A focused go-to-market angle involves direct partnerships with high-end restaurants and institutional caterers seeking novel, sustainable protein options.
For Investors and Strategic Acquirers: Specialized bioprocessing technology developers and early-stage cultured meat producers with validated regulatory clearances represent attractive acquisition targets. The market demonstrates significant long-term viability over the next decade, driven by technological advancements and consumer demand for sustainable proteins. Widespread regulatory approvals beyond pioneering markets and achieving cost parity with conventional meat are critical signals to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Scaling bioreactor facilities is crucial for achieving cost-effective production volumes of cultured meat. |
| Regulatory Approval Pathway | Securing clearances from agencies like the FDA and EFSA unlocks commercial market access for novel products. |
| Product Diversification | Developing hybrid formulations broadens consumer appeal and offers improved taste and texture. |
| R&D Investment | Optimizing cell culture media reduces production costs and enhances the scalability of cultured protein. |
| Strategic Partnerships | Collaborating with foodservice distributors accelerates market penetration and product adoption in new channels. |
Research Approach
Two parallel data streams informed the analysis: extensive primary interviews and rigorous secondary validation. Primary data involved discussions with bioprocess engineers, food scientists, regulatory affairs specialists, and foodservice procurement managers across key regions. This qualitative input was then cross-referenced with quantitative insights from secondary sources.
Forecast inputs considered novel food regulatory pathways, consumer acceptance metrics, and technological advancements in bioprocessing across the analysis window. The market was segmented by product type, technology, application, and end-user, with regional regulatory status as an additional dimension. Compound annual growth rates were derived from historical trends and projected market expansion, incorporating bioreactor scaling efficiency and cell culture media cost reductions.
Stress conditions across regulatory approval timelines, consumer acceptance rates, and raw material cost volatility were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding technological maturity and market adoption. Material shifts in regulatory policy or production cost structures would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
Gluten-Free Meat Substitutes Market
Alternative Food Sources
Konjac Market
Alternative Food Sources
Flaxseed Based Egg Replacement Market
Alternative Food Sources
Vegan Casing Market
Alternative Food Sources
Seitan Market
Alternative Food Sources
Asia-Pacific Fat Replacers Market
Alternative Food Sources
Mycoprotein Market
Alternative Food Sources
South American Algae Protein Market
Alternative Food Sources
Global Konjac Glucomannan Market
Alternative Food Sources
Fishless Fillets Market
Alternative Food Sources
Vegetable Waste Products Market
Alternative Food Sources
Fish Meal Alternative Market
Alternative Food Sources
Quinoa Protein Market
Alternative Food Sources
Paleo Food Market
Alternative Food Sources
Fungal Protein Market
Alternative Food Sources
Africa Fat Replacers Market