
 Upcycled Food Products Market | 2026-2036
Upcycled Food Products Market Size, Share, and Industry Trends Forecast 2026-2036
Upcycled Food Products Market Analytics
Upcycled food processing expertise is redrawing competitive boundaries as trained food scientists and supply chain engineers become scarce relative to expansion plans. Matriark Foods leverages vertical integration with institutional foodservice channels to secure volume commitments. EverGrain anchors its position through proprietary protein extraction from brewer's spent grain. Renewal Mill competes by controlling flour milling infrastructure that converts agricultural byproducts into functional ingredients.
Upcycled food products transform edible byproducts, surplus crops, and processing residuals into value-added ingredients or finished goods through dehydration, fermentation, milling, or extrusion, yielding nutritional profiles comparable or superior to conventional alternatives. Their primary purpose is reducing food waste volumes while generating revenue streams from material previously discarded. Snacks and beverages occupy the largest share of consumer-facing revenue as brand recognition drives trial purchases. Ingredients represent the fastest-expanding segment as CPG formulators seek certified upcycled inputs for sustainability labeling. Direct-to-Consumer channels sustain premium pricing power through subscription models that build repeat purchase behavior.
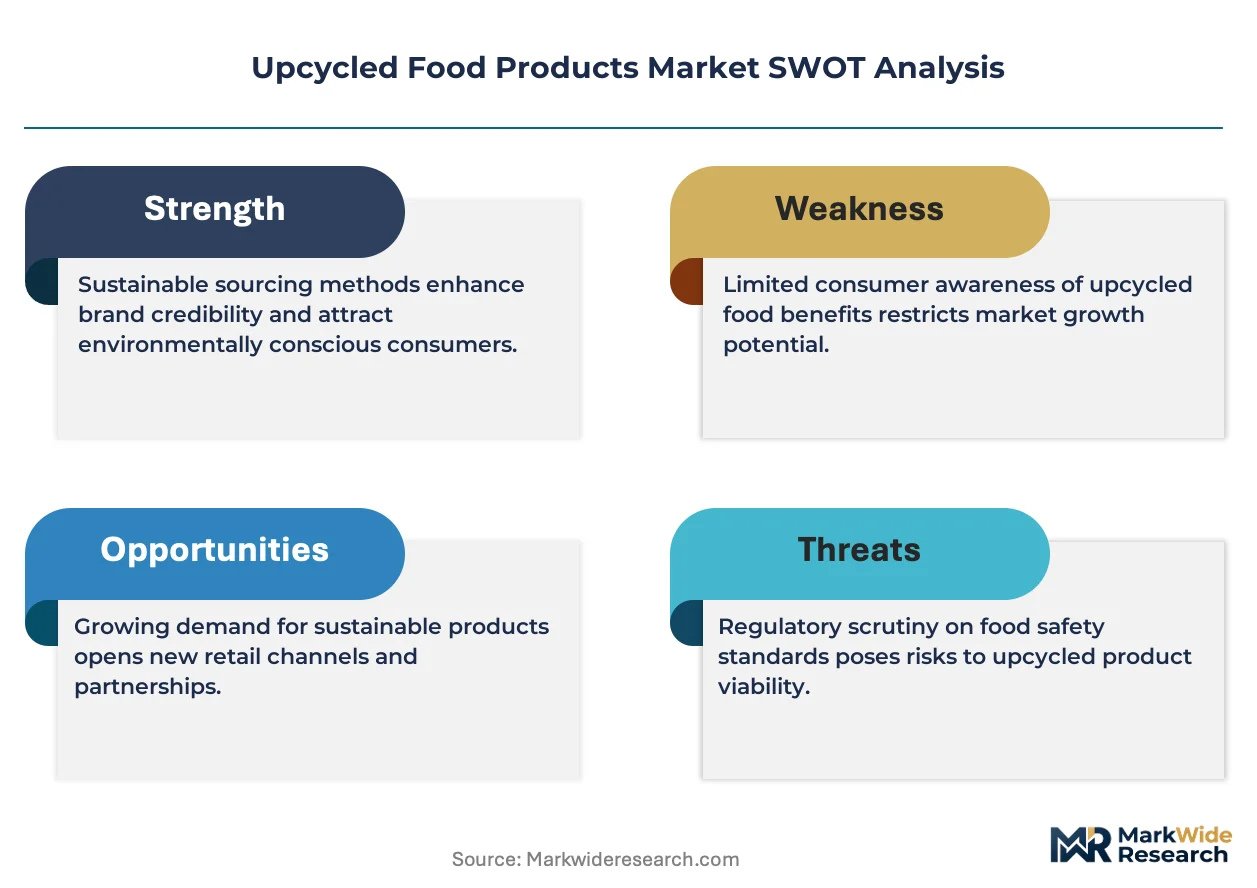
The FDA regulates upcycled ingredients under existing GRAS and food safety frameworks, while the USDA oversees organic certification pathways that many upcycled brands pursue for differentiation. The EU Green Deal's farm-to-fork waste reduction targets and REACH chemical safety standards shape ingredient approval timelines and cross-border trade access. Stakeholders must monitor how evolving definitions of "upcycled" across jurisdictions affect label claims and consumer trust metrics.
Market Dynamics
Ingredient certification requirements under the EU Green Deal are compressing approval timelines and forcing CPG brands to pre-qualify upcycled suppliers before product reformulation cycles complete.
Growth Catalysts
- EU Green Deal farm-to-fork targets:Mandatory food waste reduction quotas across member states are pulling upcycled ingredients into mainstream formulation pipelines ahead of voluntary sustainability pledges.
- Brewer's spent grain protein extraction:Proprietary enzymatic processes are unlocking functional protein concentrates that match conventional isolates on emulsification and water-binding performance.
- Germany retail shelf allocation:Dedicated upcycled product sections in Rewe and Edeka chains are normalizing consumer trial and collapsing the education burden for emerging brands.
Market Restraints
- Organic input cost volatility:Certified organic agricultural byproduct streams command premiums that fluctuate with conventional crop prices, squeezing margin predictability for flour millers.
- Single-source supply concentration:Spent grain availability clusters around major brewing hubs in Bavaria and Belgium, creating geographic dependency risk for protein extractors.
- REACH chemical safety documentation:Novel upcycled ingredients face extended ECHA evaluation timelines that delay EU market entry by 18-24 months against conventional alternatives.
Strategic Opportunities
- France institutional foodservice:Public procurement mandates for sustainable sourcing in school and hospital cafeterias are opening volume commitments unavailable in retail.
- Fermentation-convergence with precision biology:Hybrid processing routes combining traditional fermentation with strain engineering are expanding the feedstock range for flavor and texture ingredients.
- Direct-to-subscription channel innovation:Monthly replenishment models for upcycled snack assortments are capturing lifetime value metrics that wholesale distribution cannot replicate.
Industry Challenges
- Food scientist talent scarcity:Trained professionals capable of stabilizing novel byproduct matrices are outnumbered by expansion plans across ingredient startups.
- Upcycled certification timeline compression:Third-party verification bodies lack capacity to process the backlog of ingredient applications, delaying label claims.
- Legacy ERP integration friction:Lot-tracking requirements for mixed-waste-stream inputs conflict with standard food manufacturing software configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Upcycled Food Products Market |
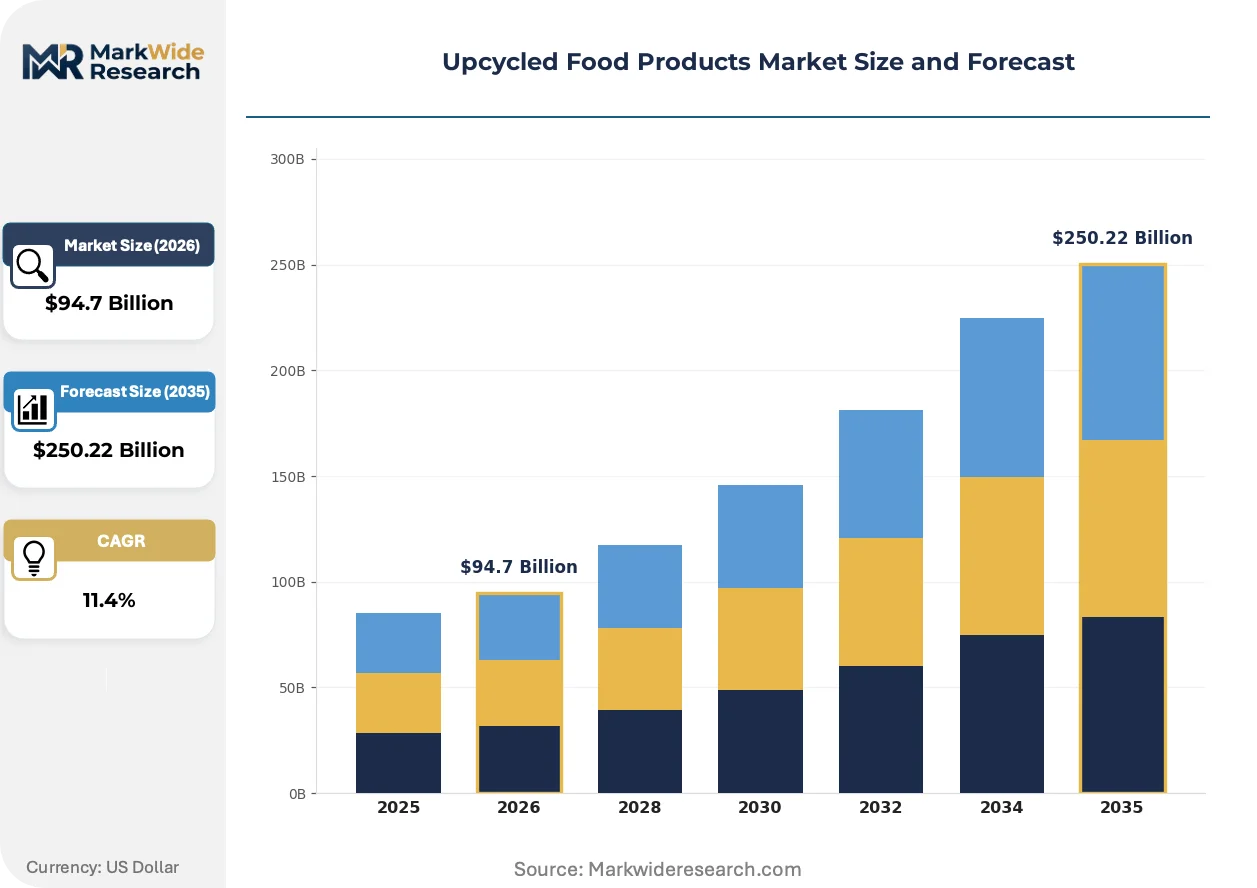
| Market Size in 2026 | $94.7 Billion |
| Market Size in 2035 | $250.22 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Snacks, Beverages, Ingredients, Meal Kits Source: Fruits, Vegetables, Grains, Spent Brewing Grains Distribution Channel: Retail, Online, Wholesale, Direct-to-Consumer Customer Segment: Health-Conscious Consumers, Eco-Friendly Shoppers, Families, Young Adults |
| Companies Covered | Matriark Foods, EverGrain, Renewal Mill, Pulp Pantry, NETZRO, Planetarians, Barnana, ReGrained, Upcycled Foods Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Upcycled Food Products Market Evolving Landscape
Processing technology convergence and procurement specification tightening are redefining what qualifies as food-grade material and who controls the valorization pipeline.
Precision fermentation hardware is miniaturizing. Modular 5,000-liter bioreactor skids are reaching ingredient startups in the Netherlands and Denmark, collapsing the capital barrier that previously restricted bioprocessing to multinational flavor houses. This distributed production architecture is compressing the minimum viable scale for viable byproduct valorization.
REACH chemical safety standards are tightening substance documentation requirements for novel upcycled feedstocks. ECHA's expanded data demands are extending pre-market notification timelines and forcing ingredient developers to front-load toxicology investments. Snack and beverage formulators in Northern Europe are responding by consolidating supplier relationships to reduce qualification overhead.
Certification-driven preference shifts are restructuring buyer evaluation criteria. Retailers in the United Kingdom are requiring third-party upcycled certification for shelf placement, displacing self-declared sustainability claims. This specification compression is most visible in the premium snack segment, where Sainsbury's and Waitrose have implemented formal vendor qualification programs.
Upcycled Food Products Market Segmentation
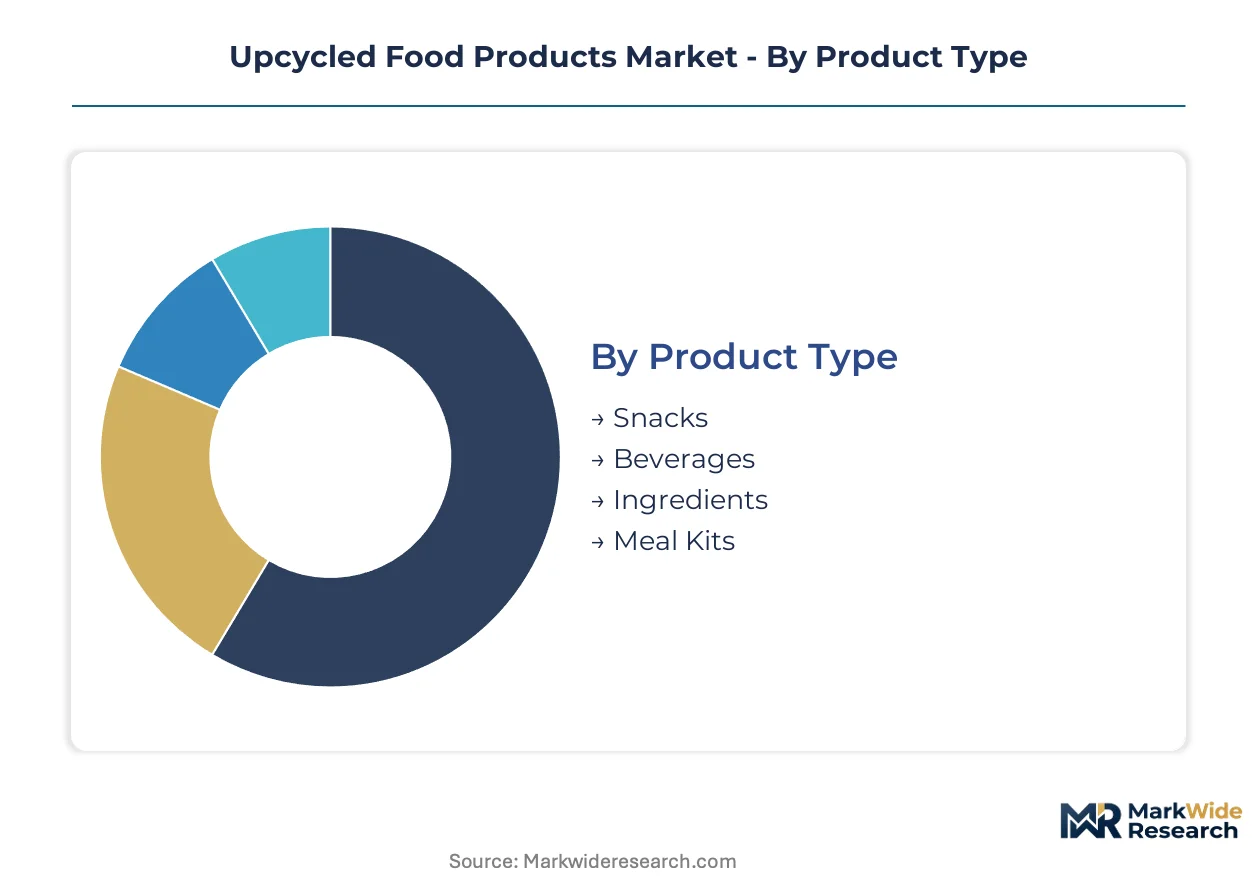
Segmentation in upcycled food products reveals how value migrates between ingredient supply and finished goods. Manufacturers configure production assets around source material availability while retailers optimize shelf space by customer motivation rather than conventional category boundaries.
Product Type:
Margin pools concentrate in ingredient supply contracts where CPG formulators pay certification premiums for supply security.
- Snacks:Extruded and puffed formats from dehydrated fruit pomace and vegetable fiber deliver crunchy textures with reduced caloric density. Demand clusters in German and UK retail chains where dedicated upcycled shelving normalizes trial purchases among mainstream shoppers.
- Beverages:Fermented grain-based drinks and fruit pulp smoothies leverage residual sugars and fiber from processing streams. Young adult consumers in France and Belgium drive volume through on-premise channels and subscription replenishment models.
- Ingredients:Functional flours, protein concentrates, and fiber additives sold to industrial formulators seeking sustainability label claims.
- Meal Kits:Pre-portioned cooking components incorporating upcycled vegetable cuts and grain byproducts for home preparation convenience.
Ingredients holds installed capacity. Snacks is rotating up the share rankings.
Source:
Feedstock economics hinge on proximity to processing residuals and seasonal harvest timing.
- Fruits:Citrus peels, apple pomace, and stone fruit pits yield pectin, fiber, and natural flavor compounds through dehydration and solvent extraction. Italian and Spanish citrus processors supply Mediterranean formulators with certified organic streams.
- Vegetables:Trimmed leaves, stems, and imperfect whole vegetables convert into purees, powders, and texture ingredients for soup and sauce applications.
- Grains:Broken kernels, hulls, and milling residuals become flour extenders and fiber enrichers for bakery and pasta manufacturing.
- Spent Brewing Grains:Post-malt barley residues supply protein extraction facilities clustered around Bavarian and Belgian brewing centers, with EverGrain operating proprietary enzymatic isolation for functional concentrates.
Spent brewing grains commands logistics infrastructure investment. Fruits is climbing the fastest on certification premiums.
Distribution Channel:
Channel selection determines pricing power and customer data access.
- Retail:Supermarket and specialty store placement with third-party certification requirements for shelf access, particularly in UK chains implementing formal vendor qualification.
- Online:E-commerce platforms enabling discovery-driven purchase with sustainability filter functionality and subscription enrollment.
- Wholesale:Bulk ingredient sales to food manufacturers and foodservice operators with volume pricing tied to contract duration.
- Direct-to-Consumer:Brand-owned websites and subscription boxes capturing lifetime value through repeat purchase automation and community building.
Direct-to-Consumer owns customer relationship data. Retail is rotating up the share rankings on mainstream normalization.
Customer Segment:
Purchase motivation splits between health optimization and waste reduction ethics.
- Health-Conscious Consumers:Shoppers prioritizing nutritional density, fiber content, and clean label credentials in functional food selections.
- Eco-Friendly Shoppers:Buyers motivated primarily by measurable waste diversion impact and carbon footprint reduction in purchasing decisions.
- Families:Household purchasers seeking value-positioned nutrition for children with allergen-friendly and school-safe format requirements.
- Young Adults:Urban professionals aged 22-35 responding to social media discovery, convenience formats, and brand narrative authenticity in trial and repeat behavior.
Eco-friendly shoppers holds early-adopter intensity. Health-conscious consumers is rotating up the share rankings on functional benefit expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal farm-to-fork mandates are pulling upcycled ingredients into mainstream formulation pipelines across Germany, France, the United Kingdom, Italy, and the Netherlands. Regulatory pressure and retail shelf allocation are compressing supplier qualification timelines in these markets.
Germany
Rewe and Edeka chains have introduced dedicated upcycled product shelves, normalizing consumer trial among mainstream shoppers. The country's national food waste reduction quotas under EU Green Deal implementation accelerate ingredient certification requirements. Bavarian brewing hubs around Munich supply spent grain protein extractors with concentrated feedstock streams.
France
Public procurement mandates for sustainable sourcing in school and hospital cafeterias open volume commitments unavailable in retail channels. ANSM and national food safety frameworks govern novel ingredient approvals with timelines that shape supplier selection. Paris and Lyon clusters host fermentation-convergence startups combining traditional processing with strain engineering.
United Kingdom
Sainsbury's and Waitrose have implemented formal third-party upcycled certification requirements for shelf placement, displacing self-declared sustainability claims. ECHA REACH standards extend pre-market notification timelines for novel feedstocks. London and Southeast England concentrate brand headquarters and direct-to-consumer subscription operations.
Italy
Citrus processors in Sicily and Calabria supply Mediterranean formulators with certified organic pomace and peel streams. EU Green Deal waste reduction targets pull agricultural byproduct valorization into compliance-focused investment. Emilia-Romagna and Lombardy clusters integrate dehydration infrastructure with conventional food manufacturing assets.
Netherlands
Modular 5,000-liter bioreactor skids are reaching ingredient startups in Randstad cities, collapsing capital barriers for distributed bioprocessing. ECHA chemical safety documentation requirements extend evaluation timelines for novel upcycled substances. Wageningen and Eindhoven regions anchor precision fermentation hardware deployment for byproduct valorization.
Upcycled Food Products Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the upcycled food products market. Matriark Foods leverages vertical integration with institutional foodservice channels to secure volume commitments, while EverGrain anchors its position through proprietary protein extraction from brewer's spent grain. Renewal Mill competes by controlling flour milling infrastructure that converts agricultural byproducts into functional ingredients. Strategic moves concentrate on supplier pre-qualification partnerships with CPG brands and capacity expansion near brewing and agricultural processing clusters.
Within the integrated leader tier, Matriark Foods and EverGrain exemplify divergent pathway strategies—one through captive foodservice distribution, the other through proprietary extraction technology. Renewal Mill occupies a position representing infrastructure-control archetypes that convert byproduct streams at scale. These three entities collectively illustrate how supply security and processing specialization define competitive positioning under tightening EU certification timelines.
| Leading Market Players |
|---|
| Matriark Foods |
| EverGrain |
| Renewal Mill |
| Pulp Pantry |
| NETZRO |
| Planetarians |
| Barnana |
| ReGrained |
| Upcycled Foods Inc. |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between spent grain processors and Bavarian brewing conglomerates lock in feedstock access and stabilize input cost visibility across volatile harvest cycles. These arrangements compress price discovery windows while insulating protein extractors from spot market fluctuations in organic agricultural byproducts.
Pricing Analysis
German retail chains command 15-20% certification premiums over Benelux wholesale channels for identical upcycled flour specifications. Three-tier pricing structure across premium certified-organic, standard third-party verified, and economy self-declared tiers separates ingredient grades. Pricing pressure stems from REACH compliance documentation costs that extractors pass through to CPG formulators. Health-conscious consumers in direct-to-subscription channels exhibit lowest price sensitivity, while institutional foodservice buyers in France negotiate hardest on volume contracts.
Supply Chain Analysis
Germany and Belgium anchor spent grain protein extraction, while Italy and Spain concentrate citrus pomace dehydration infrastructure. Raw material flows draw from Bavarian brewing clusters, Sicilian citrus processors, and Dutch precision fermentation hardware deployments. Single-source geographic concentration around Munich and Brussels creates vulnerability to harvest timing disruptions and transport bottlenecks. Distribution runs through CPG ingredient pre-qualification pipelines that consolidate supplier relationships ahead of EU Green Deal compliance deadlines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent upcycled ingredient processors face substitution pressure from precision-fermented alternatives that bypass agricultural byproduct dependency entirely. Defense requires locking in supply relationships and certification capacity before novel biotechnology routes achieve cost parity.
For Market Incumbents: Compound backward integration into brewing and agricultural processing assets to secure captive feedstock streams against spot market volatility. Anchor certification capacity investments ahead of EU Green Deal timeline compression, as third-party verification bodies face application backlogs that delay label claims. Prioritize pre-qualification partnerships with CPG brands reformulating around sustainability targets. For New Entrants and Emerging Players: Differentiate on fermentation-convergence processing routes that expand feedstock range beyond conventional byproduct streams. Target France institutional foodservice procurement mandates where public sector volume commitments exceed retail shelf allocation constraints. Pursue direct-to-subscription channel entry to capture lifetime value metrics and customer data access unavailable through wholesale distribution. For Investors and Strategic Acquirers: Proprietary extraction technology specialists with validated ECHA dossiers represent priority acquisition targets given REACH timeline compression and qualification bottlenecks. Long-term viability hinges on certification moats rather than processing scale alone across the analysis window. Monitor ECHA notification approval velocity as inflection indicator for ingredient market entry feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Brewing Assets | Bavarian spent grain supply security insulates protein extractors from spot price volatility. |
| Third-Party Certification Investment | UK retailer qualification programs at Sainsbury's and Waitrose mandate verified upcycled claims. |
| Precision Fermentation Hardware Deployment | Dutch modular bioreactor skids collapse capital barriers for distributed byproduct valorization. |
| Direct-to-Consumer Channel Launch | Subscription replenishment models capture lifetime value metrics beyond wholesale distribution reach. |
| Institutional Foodservice Partnership | France public procurement mandates open volume commitments unavailable in competitive retail. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with CPG formulation directors, foodservice procurement managers, upcycled ingredient startup founders, and third-party certification body executives. Secondary validation drew from ECHA substance registration databases, EU Green Deal implementation progress reports, retail chain vendor qualification documentation, and trade customs records for agricultural byproduct flows. Bottom-up volume modeling triangulated against top-down market sizing across ingredient and finished goods segments.
Across the analysis window, forecasts incorporate product type, source material, distribution channel, and customer motivation dimensions. CAGRs were derived from segment-level growth rate reconciliation with macro-level market expansion. Modeled inputs include EU farm-to-fork waste reduction quota implementation timelines, ECHA evaluation velocity for novel feedstocks, and retail shelf allocation expansion trajectories in Germany and the United Kingdom.
The analysis sits within stated boundaries; outcomes outside sustained EU regulatory enforcement or accelerated precision fermentation cost reduction would require recalibration. Forecasts reflect documented assumptions regarding certification body capacity expansion and CPG reformulation cycle timing. Recalibration cycles align with material shifts in ECHA notification approval rates and EU Green Deal mandate enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
Fungal Protein Market
Alternative Food Sources
Edible Packaging Market
Alternative Food Sources
Africa Potato Protein Market
Alternative Food Sources
Flaxseed Based Egg Market
Alternative Food Sources
Global Algae Protein Market
Alternative Food Sources
Organic Gluten Substitutes Market
Alternative Food Sources
Precision Fermentation Market
Alternative Food Sources
Emergency Food Market
Alternative Food Sources
Fish Meal Alternative Market
Alternative Food Sources
Asia-Pacific Fat Replacers Market
Alternative Food Sources
Europe Upcycled Food Products Market
Alternative Food Sources
Algae Oil Market
Alternative Food Sources
Vegan Casing Market
Alternative Food Sources
Algae Fats Market
Alternative Food Sources
Meat Analogue Market
Alternative Food Sources
Meal Replacement Bars Market