
 Dust Suppression Control Market | 2026-2036
Dust Suppression Control Market Size, Share, and Industry Trends Forecast 2026-2036
Dust Suppression Control Market Analysis
Mining operations is hardening as the dominant demand vertical for dust suppression systems, displacing construction sites where project cyclicality weakens procurement continuity. Ecolab Inc. leverages its institutional chemical distribution network to anchor long-term supply contracts with tier-one mining houses across North and South America. Donaldson Company, Inc. competes through filtration-adjacent expertise, extending its industrial air quality portfolio into wet suppression hybrid systems for underground extraction environments.
Dust suppression control encompasses engineered chemical formulations and mechanical systems designed to agglomerate, wet, or encapsulate airborne particulate matter, typically achieving suppression efficiencies above eighty-five percent when properly applied to respirable silica and coal dust fractions. The primary commercial purpose centers on occupational health compliance, equipment protection, and community environmental mitigation in extractive and bulk material handling industries. Liquid suppressants lead product type demand due to their compatibility with existing mine water infrastructure, while foaming agents represent the fastest-growing category as operators seek reduced moisture addition in cold climates where freezing degrades ore quality. Mining operations commands the largest application share, though road maintenance applications are gaining share as unpaved haul road networks expand in remote basins.
MSHA enforces respirable dust standards in US underground mines, mandating continuous personal dust monitors and triggering corrective action when quartz concentrations exceed permissible limits. EPA National Ambient Air Quality Standards for PM-10 and PM-2.5 shape state-level implementation plans, forcing surface operations in Arizona, Wyoming, and West Virginia to adopt chemical suppressants beyond basic water spraying. Australia's Department of Agriculture, Water and the Environment administers dust management protocols for Port Hedland and other bulk export terminals, requiring real-time monitoring and adaptive suppression during high-wind events. Stakeholders must monitor regulatory divergence between jurisdictions that mandate specific suppression technologies versus those that specify only ambient air quality outcomes, as this distinction determines whether product suppliers compete on chemistry performance or on systems integration capability.
Market Dynamics
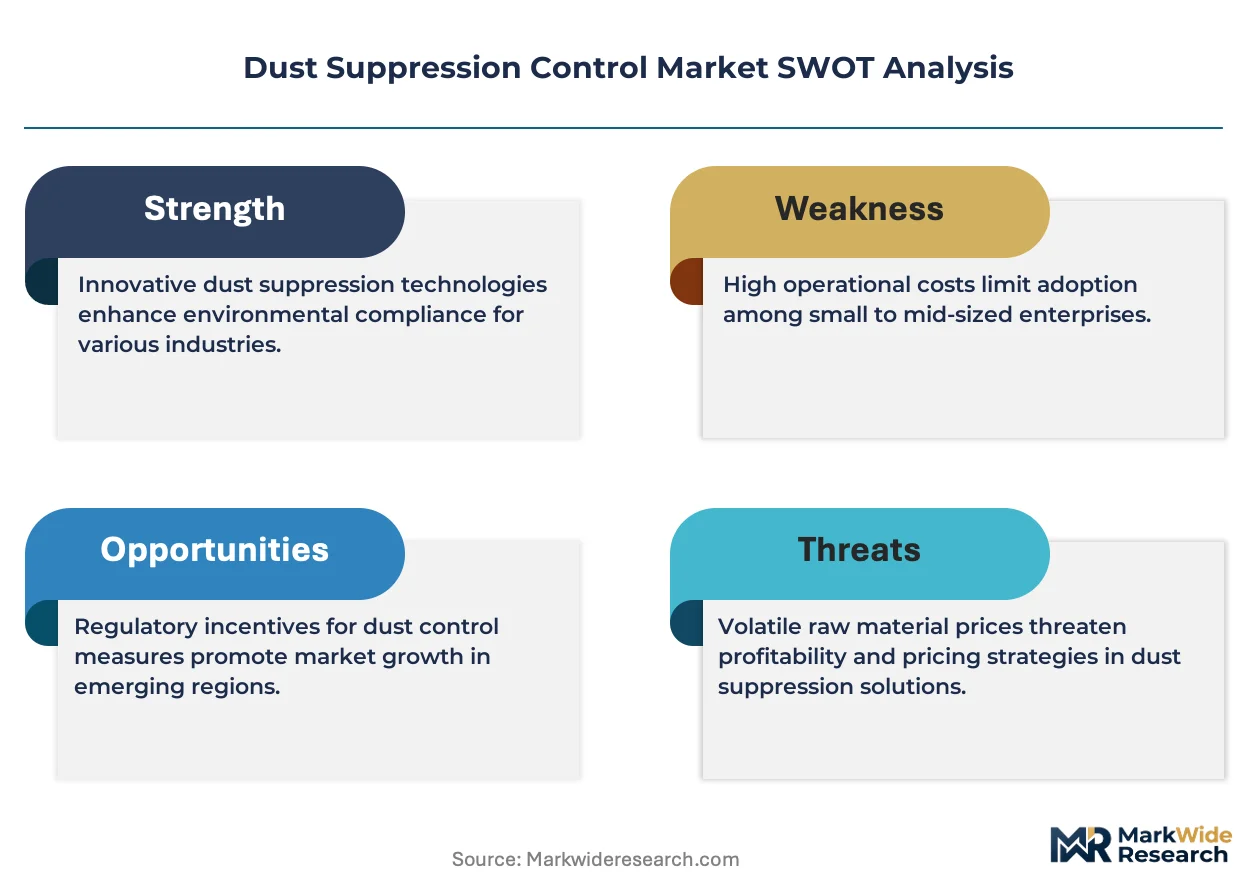
Pit deepening at Australian and Chilean iron ore and copper operations is hardening demand for chemical suppressants as ventilation costs outpace water-only spraying economics. MSHA silica enforcement and EPA PM-2.5 tightening are compressing compliance timelines, forcing capital deployment toward integrated wet-chemical hybrid systems before permit renewals.
Growth Catalysts
- MSHA respirable dust mandates:Continuous personal dust monitor requirements in US underground mines trigger immediate suppressant upgrades when quartz thresholds breach, locking in chemical agent procurement cycles.
- Pilbara port loading disruptions:Western Australia's iron ore export terminals face operational stoppages from dust events, compelling real-time adaptive suppression investments across Rio Tinto and BHP haul road networks.
- Foaming agent chemistry:Cold-climate ore bodies in Canada and Russia drive formulation demand that reduces moisture addition, preventing freezing degradation while maintaining dust capture efficiency above eighty-five percent.
Market Restraints
- Petrochemical feedstock volatility:Surfactant and polymer input costs for liquid suppressants fluctuate with crude oil indices, squeezing margin predictability for formulators serving fixed-price municipal contracts.
- Water infrastructure lock-in:Mines with sunk capital in high-pressure spraying systems face replacement friction, delaying chemical agent adoption despite superior respirable dust capture performance.
- Regional supplier concentration:Western Australian dust suppressant supply clusters around Perth chemical blending facilities, exposing Pilbara operators to logistics bottlenecks during cyclone season.
Strategic Opportunities
- Underground lithium extraction:Hard-rock lithium mines in Canada and Finland present greenfield suppressant specification windows as operators avoid silica litigation precedents set by coal and gold sectors.
- EU Green Deal procurement criteria:Public tender scoring for construction site dust control now weights biodegradable formulation chemistry, advantaging suppliers with ECHA-registered environmental fate data.
- Drone-mounted application systems:Aerial dispersal platforms enable coverage of inaccessible tailings dam surfaces and steep pit walls, opening service revenue models beyond traditional ground-based spraying equipment.
Industry Challenges
- Applied chemistry talent scarcity:Formulation chemists with mining sector experience command premium compensation, constraining R&D throughput for mid-tier suppressant vendors competing on performance differentiation.
- Legacy SCADA integration:Real-time dust monitoring networks must interface with decades-old mine control systems, extending deployment timelines and requiring custom protocol bridging hardware.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dust Suppression Control Market |
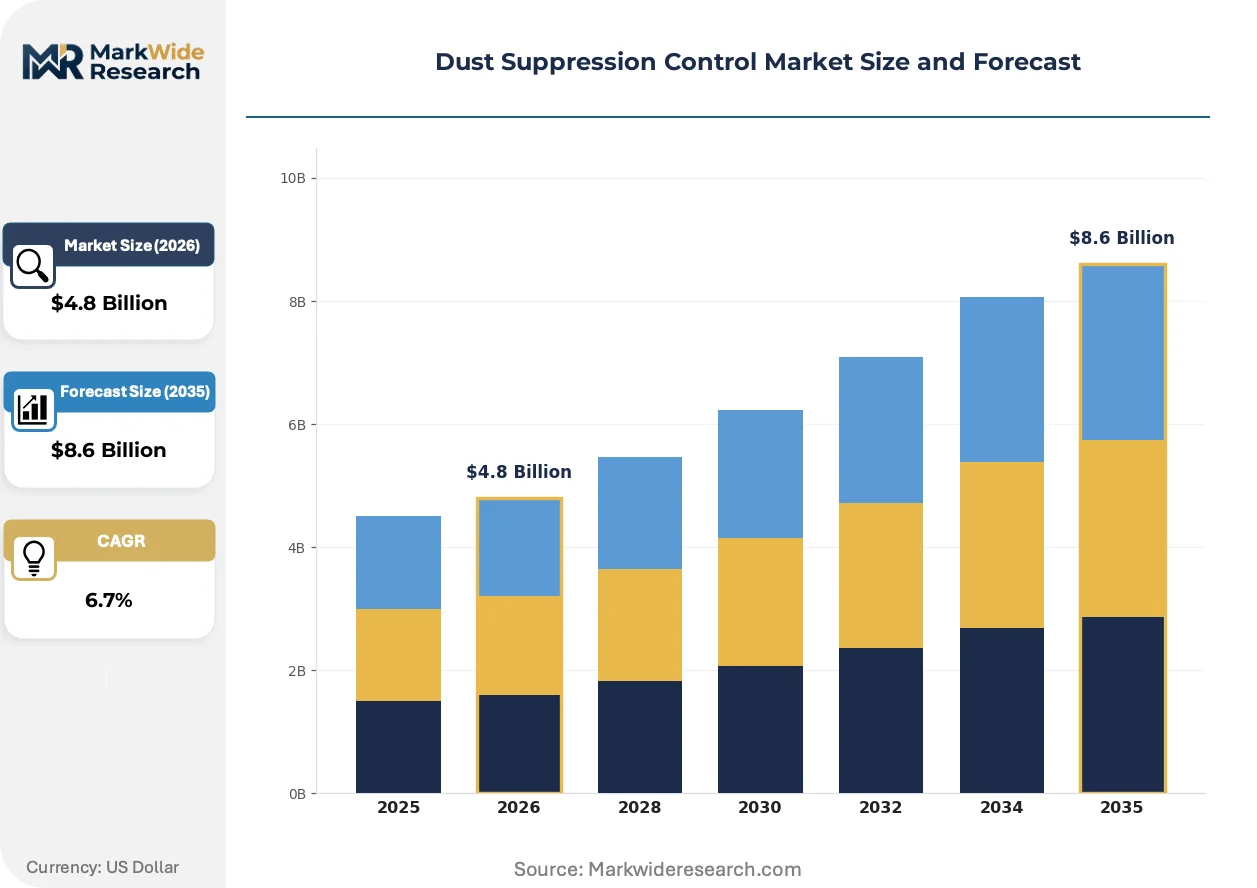
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Suppressants, Dust Control Agents, Foaming Agents, Granular Solutions Application: Mining Operations, Construction Sites, Road Maintenance, Agriculture End User: Mining Companies, Construction Firms, Agricultural Producers, Industrial Plants Distribution Channel: Direct Sales, Online Retail, Distributor Partnerships, Wholesale |
| Companies Covered | Ecolab Inc., Donaldson Company, Inc., Camfil AB, Cargill Incorporated, Dust Control Technologies, Inc., Quaker Houghton Corporation, Global Road Technology Ltd., Colliery Dust Control (Pty) Ltd, New Waste Concepts, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dust Suppression Control Market Emerging Trajectories
Suppressant delivery hardware is fragmenting into interoperable subsystems, decoupling chemical formulation from mechanical application and enabling point-solution upgrades without full system replacement. This modular architecture is compressing capital cycles and opening vendor entry points.
Electrostatic charging of liquid droplets is modularizing across Australian iron ore haul roads, enhancing particulate attraction beyond mechanical wetting alone. BHP and Fortescue Metals Group are piloting retrofittable nozzle clusters on existing water trucks, avoiding full fleet replacement. The technology is modularizing supplier relationships, allowing mines to source charging hardware from electrical specialists while maintaining chemical supply contracts with incumbent formulators.
EPA's 2024 National Ambient Air Quality Standards revision tightens PM-2.5 attainment thresholds, forcing Arizona copper surface operations into supplemental control measures beyond Best Available Control Technology determinations. State implementation plans now explicitly list chemical suppressants as presumptive compliance pathways for fugitive dust from unpaved roads. Western US mines are responding by pre-positioning multi-year suppressant supply agreements ahead of permit renewal negotiations.
Buying committees at tier-one mining houses are consolidating dust control procurement under centralized sustainability functions, displacing decentralized site-level chemical selection. Rio Tinto's corporate technical standards now mandate third-party validated suppressant performance data across all operating jurisdictions. This behavioral shift concentrates contract volumes with vendors maintaining ISO 17025 laboratory accreditation, squeezing regional formulators without certification infrastructure.
Dust Suppression Control Market Segmentation
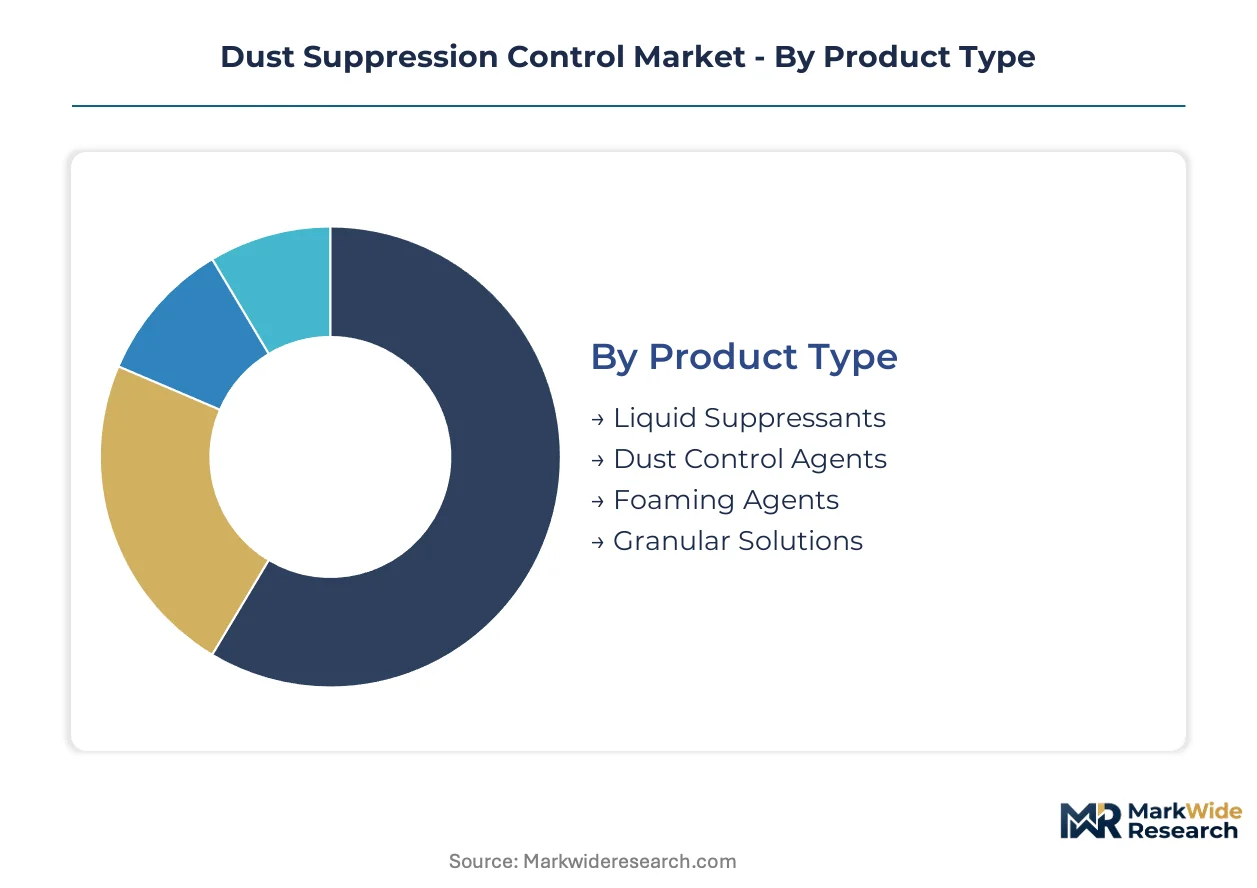
Dust suppression procurement varies sharply by deployment scale and technical complexity. Mining houses favor capital-intensive integrated systems while municipal buyers prioritize operational flexibility over upfront investment.
Product Type:
Liquid suppressants and foaming agents demand the heaviest capital allocation for storage infrastructure and precision application equipment.
- Liquid Suppressants:Water-based chemical formulations incorporating surfactants and polymers to reduce surface tension and extend particulate wetting duration. Western Australian iron ore operators in the Pilbara deploy these through high-pressure truck-mounted systems across thousand-kilometer haul road networks, with procurement concentrated under multi-year supply contracts with chemical distributors.
- Foaming Agents:Protein-based or synthetic surfactant mixtures that expand water volume through air entrainment, achieving dust capture with minimal moisture addition. Canadian hard-rock lithium mines and Russian coal basins specify these formulations to prevent freezing degradation of ore quality during winter extraction cycles.
- Dust Control Agents:Specialized binding compounds that form durable surface crusts on unpaved roads and stockpiles.
- Granular Solutions:Solid-phase absorbents applied to spill containment and localized dust sources.
Liquid suppressants absorb the bulk of installed capacity; foaming agents are expanding most quickly.
Application:
Underground extraction environments impose the most stringent performance specifications and drive premium pricing tiers.
- Mining Operations:Integrated wet-chemical hybrid systems targeting respirable silica and coal dust fractions in surface and underground extraction. US copper surface operations in Arizona and Chilean pit copper mines deploy these under MSHA and local mining authority mandates, with real-time monitoring triggering automated suppressant activation during high-wind events.
- Construction Sites:Mobile spraying equipment and temporary surface treatments for earthmoving and demolition particulate. EU Green Deal procurement criteria in Germany and France now weight biodegradable formulation chemistry in public tender scoring, advantaging suppliers with ECHA-registered environmental fate data.
- Road Maintenance:Long-duration suppressants for unpaved haul and access road networks.
- Agriculture:Low-volume applications for grain handling and livestock facility dust management.
Mining operations commands the dominant revenue share; road maintenance applications are gaining share fastest as remote basin haul networks expand.
End User:
Procurement centralization varies by buyer scale, with tier-one mining houses consolidating under corporate sustainability functions while agricultural producers remain fragmented.
- Mining Companies:Large-scale consumers specifying ISO 17025-validated performance data across operating jurisdictions. Rio Tinto's corporate technical standards now mandate third-party laboratory accreditation for all suppressant vendors, squeezing regional formulators without certification infrastructure.
- Construction Firms:Project-based procurement with cyclical demand patterns and shorter contract horizons.
- Agricultural Producers:Price-sensitive buyers favoring basic water-only spraying for grain handling operations.
- Industrial Plants:Specialized requirements for bulk material handling and processing facility fugitive dust.
Mining companies concentrate the highest contract values; construction firms show the steepest expansion trajectory as infrastructure stimulus programs accelerate.
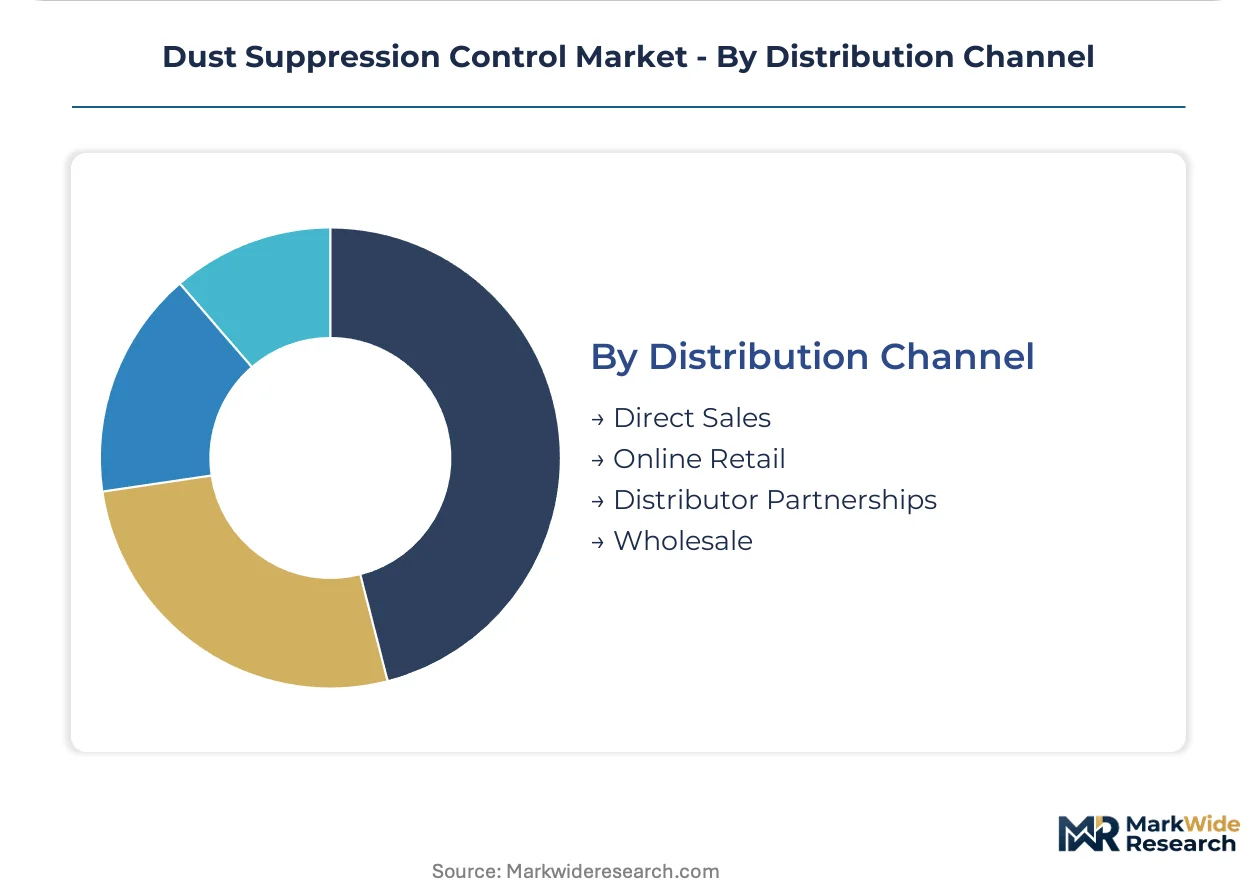
Distribution Channel:
Channel selection tracks buyer technical sophistication and inventory carrying capacity.
- Direct Sales:Long-term supply agreements between chemical formulators and tier-one mining houses. Ecolab leverages its institutional distribution network to anchor contracts across North and South American operations, embedding technical service teams at customer sites.
- Distributor Partnerships:Regional chemical blending facilities serving mid-tier mines and municipal road departments.
- Wholesale:Bulk volume transactions for standard formulation grades.
- Online Retail:Limited to small-volume agricultural and construction applications.
Direct sales channels capture the majority of mining sector volume; distributor partnerships are climbing the fastest as mid-tier operators seek localized technical support.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Western Australia generates the heaviest consumption volumes while chemical formulators cluster in North American industrial corridors. Chilean copper pits and Canadian hard-rock mines are hardening procurement specifications faster than legacy basins.
United States
Arizona copper surface operations and Appalachian coal basins drive suppressant demand as MSHA respirable dust mandates tighten enforcement timelines. EPA's 2024 National Ambient Air Quality Standards revision compresses PM-2.5 attainment thresholds, triggering supplemental control requirements. Southwestern copper corridors from Morenci to Tucson are pre-positioning multi-year chemical supply agreements ahead of permit renewals.
Australia
Pilbara iron ore haul roads and Port Hedland export terminals command the largest regional procurement volumes as dust events disrupt rail and loading operations. The Department of Agriculture, Water and the Environment administers real-time monitoring protocols for bulk export terminals during high-wind events. Western Australia's Perth chemical blending facilities concentrate supply, exposing Pilbara operators to cyclone-season logistics bottlenecks.
Chile
Pit-deepening copper operations in the Atacama Desert are displacing water-only spraying with chemical suppressants as ventilation economics deteriorate. National mining authority regulations mirror MSHA silica enforcement patterns, accelerating wet-chemical hybrid system deployments. Antofagasta and Calama mining clusters are expanding liquid suppressant procurement under centralized technical standards.
Canada
Hard-rock lithium mines in Quebec and Ontario are specifying foaming agents to prevent freezing degradation during winter extraction cycles. Provincial occupational health regulators are importing silica exposure precedents from US coal litigation, tightening permissible limits. Sudbury and Val-d'Or mining districts are mandating third-party validated suppressant performance data for new permit applications.
Germany
Construction site dust control procurement is shifting under EU Green Deal tender scoring that weights biodegradable formulation chemistry. ECHA-registered environmental fate data now advantages suppliers in public infrastructure contracts. Rhine-Ruhr industrial corridors and Bavarian highway projects are specifying suppressants with validated biodegradation profiles.
Dust Suppression Control Market Vendor Landscape
Top-tier vendors anchor multi-year mining house contracts, while regional blenders serve municipal road departments with shorter procurement cycles. The structure concentrates around chemical formulators with ISO 17025 laboratory accreditation and filtration-adjacent industrial air quality specialists. Strategic archetypes include institutional distributors embedding technical service teams, modular hardware suppliers decoupling application from chemistry, and regional blenders lacking certification infrastructure. Dominant competitive moves center on backward integration into surfactant supply chains and geographic expansion through distributor partnerships.
Within the institutional distribution tier, Ecolab Inc. and Quaker Houghton Corporation exemplify vendors leveraging embedded technical service capabilities to lock in tier-one mining contracts. Donaldson Company, Inc. occupies a position bridging filtration expertise into wet suppression hybrid architectures for underground environments. Cargill Incorporated represents agricultural-industrial crossovers applying protein-based chemistry knowledge to foaming agent formulations for cold-climate mining.
| Leading Market Players |
|---|
| Ecolab Inc. |
| Donaldson Company, Inc. |
| Camfil AB |
| Cargill Incorporated |
| Dust Control Technologies, Inc. |
| Quaker Houghton Corporation |
| Global Road Technology Ltd. |
| Colliery Dust Control (Pty) Ltd |
| New Waste Concepts, Inc. |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up chemical distributors in North America and Australia have consolidated regional blending capacity, tightening supply discipline and anchoring long-term contract pricing for tier-one mining houses while squeezing margin flexibility for municipal road departments on spot purchases.
Pricing Analysis
Margin tightening in standard-grade liquid suppressants reflects petrochemical feedstock volatility and fixed-price municipal contract exposure. Three-tier pricing structure across ISO 17025-accredited premium, performance-validated standard, and unaccredited economy levels separates mining procurement from construction site spot buying. Cost compression accelerates in economy tiers as regional blenders without certification infrastructure compete on price alone. Mining companies demonstrate lowest price sensitivity due to compliance-driven specification mandates, while agricultural producers remain most price-sensitive, favoring basic water-only spraying alternatives.
Supply Chain Analysis
Returns of unused suppressant concentrate and refurbishment of high-pressure pumping equipment flow through Perth chemical blending facilities and Houston petrochemical corridors, creating reverse-logistics revenue streams for service-embedded distributors. Surfactant and polymer formulation draws from US Gulf Coast and German industrial chemical basins, with finished suppressant blending concentrating in Australia, Chile, and Canada. Single-source vulnerability persists in Western Australian supply during cyclone season. Distribution runs through direct technical-service contracts for mining houses and regional distributor partnerships for municipal road departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dust suppression market is transitioning from water-only mechanical spraying to electrostatic-charged wet-chemical hybrid systems, with modular hardware retrofits displacing full fleet replacement cycles across Australian iron ore haul roads.
For Market Incumbents: Anchor multi-year supply agreements through embedded technical service teams at tier-one mining houses before procurement centralization under corporate sustainability functions squeezes regional formulators. Defend against modular hardware specialists by backward integrating into surfactant supply chains and securing ISO 17025 laboratory accreditation for performance validation. Prioritize certification investment to maintain contract eligibility as Rio Tinto and BHP mandate third-party validated data across all jurisdictions. For New Entrants and Emerging Players: Begin with drone-mounted aerial dispersal platforms for tailings dam and steep pit wall applications, where incumbent ground-based spraying equipment cannot access. Target Canadian hard-rock lithium mines specifying foaming agents for winter extraction cycles, a segment avoiding silica litigation precedents from coal and gold sectors. Pursue EU Green Deal public tender opportunities in German and French construction dust control, where biodegradable formulation chemistry scoring advantages suppliers with ECHA-registered environmental fate data. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier chemical blenders in Western Australia and Chile lacking certification infrastructure but holding established mining relationships, as procurement centralization pressures their standalone viability. Long-term viability across the analysis window hinges on wet-chemical hybrid system adoption rates in underground extraction environments. Watch MSHA silica enforcement intensity and EPA PM-2.5 attainment threshold revisions as inflection indicators for capital deployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Surfactant Supply | Captive polymer and surfactant production insulates Ecolab and Quaker Houghton from crude oil index volatility. |
| ISO 17025 Laboratory Accreditation Investment | Third-party validation capability locks in tier-one mining contracts as Rio Tinto mandates accredited performance data. |
| Drone-Mounted Application System Development | Aerial dispersal platforms open service revenue models for inaccessible tailings dam surfaces at BHP and Fortescue sites. |
| ECHA-Registered Environmental Fate Data Submission | Biodegradation profile validation secures EU Green Deal tender scoring advantages in German infrastructure projects. |
| Perth Chemical Blending Facility Expansion | Regional capacity addition mitigates cyclone-season logistics bottlenecks for Pilbara iron ore operators. |
Methodological Framework
Independent corroboration across primary interviews with mine operations managers, chemical procurement leads at tier-one mining houses, dust suppression formulation chemists, and environmental compliance officers underwrites the qualitative findings. Secondary validation draws from EPA National Ambient Air Quality Standards documentation, MSHA respirable dust enforcement records, Australian Department of Agriculture Water and Environment port protocols, and SEC 10-K filings of listed chemical distributors. Bottom-up segment sizing triangulates against top-down market aggregation across product type, application, and end-user dimensions.
Rate-of-change decomposition separates volume expansion from price mix effects across the projection horizon. Segmentation modeling incorporates suppressant chemistry type, deployment environment surface versus underground, buyer scale tier, and regional regulatory stringency cluster. CAGRs derive from logistic growth curve fitting to historical procurement patterns and regulatory mandate implementation timelines. Forecast inputs include pit deepening rates at Australian and Chilean operations, MSHA continuous personal dust monitor deployment schedules, and EU Green Deal procurement criteria adoption curves.
Underlying measurement precision varies by segment; mining operations carry tighter precision than agricultural applications due to concentrated buyer visibility and contract disclosure. Forecasts reflect documented assumptions regarding MSHA enforcement intensity, petrochemical feedstock correlation stability, and modular hardware adoption rates. Practitioners should monitor EPA PM-2.5 attainment threshold litigation outcomes, Western Australian cyclone season severity, and lithium mine greenfield development announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Services
Gutter Cleaning Services Market
Construction Services
Facade Cleaning and Maintenance Service Market
Construction Services
Heavy Equipment Training Simulator Market
Construction Services
Die Casting Services Market
Construction Services
Middle East and Africa Industrial Maintenance Services in Operational Improvement and Operational Maintenance Market
Construction Services
North America Testing and Commissioning Market
Construction Services
Train Contractor Market
Construction Services
Construction Project Management Services Market
Construction Services
Construction Equipment Repair and Maintenance Services Market
Construction Services
Condenser Cleaners Market
Construction Services
North America Repair and Rehabilitation Market
Construction Services
Remote Construction Market
Construction Services
Testing, Inspection, and Certification for Construction Market
Construction Services
Industrial Machinery Repair Services Market
Construction Services
North America Fire Sprinkler Systems Market
Construction Services
3D Concrete Printing Services Market