
 3D Concrete Printing Services Market | 2026-2036
3D Concrete Printing Services Market Size, Share, and Industry Trends Forecast 2026-2036
3D Concrete Printing Services Market Insights
The Netherlands is narrowing its gap with early movers in printable concrete capacity as Dutch municipalities fund pilot housing estates near Eindhoven. COBOD International A/S leverages its gantry-system expertise to anchor European project pipelines. ICON Technology Inc. competes on speed, sustaining deployment records for single-family wall assembly in Texas and Mexico. Sika AG differentiates through proprietary admixture chemistry that accelerates layer-bonding without steel reinforcement.
3D concrete printing services encompass the design, fabrication, and assembly of load-bearing structures through layer-by-layer deposition of cementitious mixes with slump values below 20 mm and print speeds ranging from 50 to 600 mm per second, primarily serving housing and infrastructure markets seeking geometric freedom and labor reduction. Construction services dominate revenue capture given the capital intensity of field-deployed robotic systems and the scarcity of certified print operators. Infrastructure applications represent the fastest-expanding margin pool as bridge culverts and retaining walls demand performance-grade mixes with fiber dosages exceeding 2% by volume.
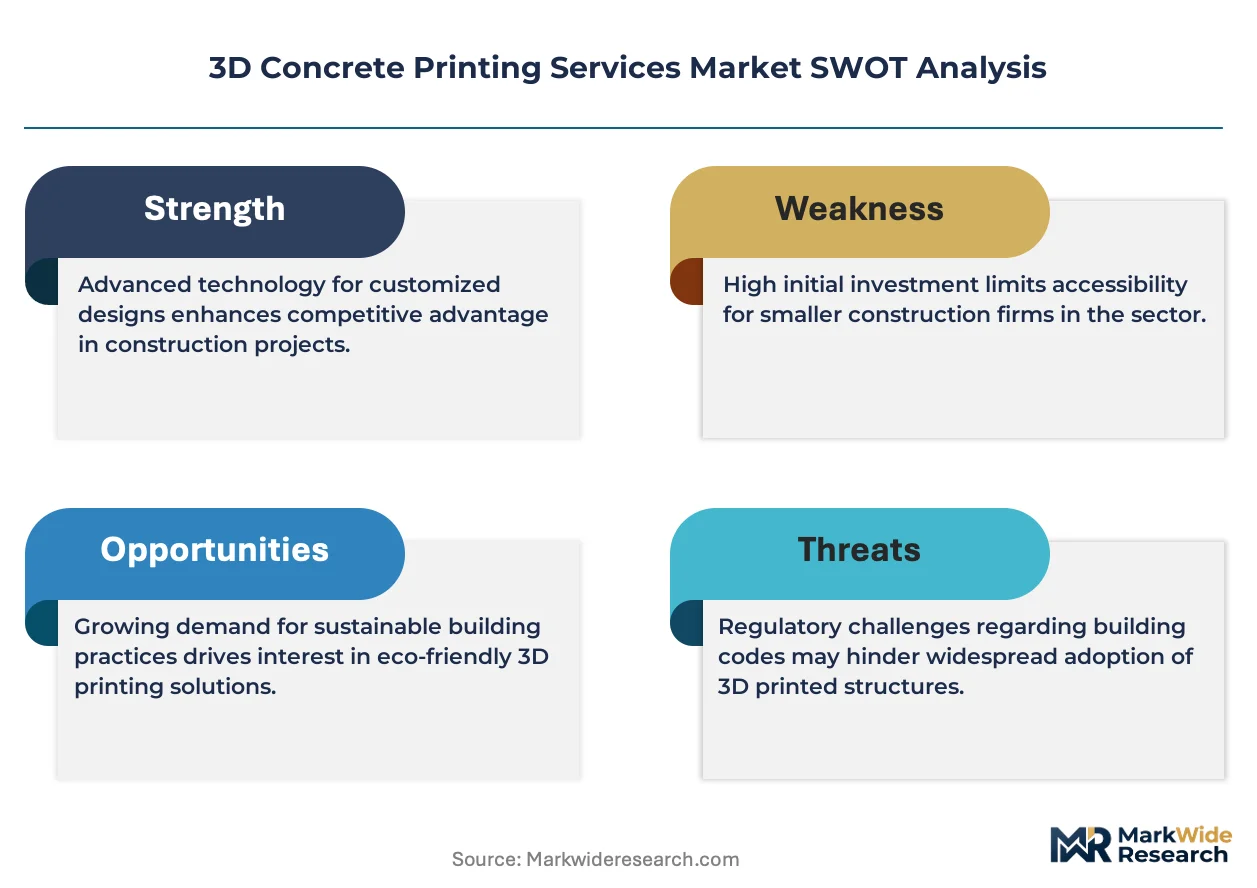
The EU Construction Products Regulation and CE marking requirements govern structural acceptance of printed elements across member states, while the US International Code Council evaluates alternate methods for seismic-zone deployment. Germany's KBA and state-level building authorities coordinate with DIN standards committees to define compressive-strength testing protocols for layered concrete. Stakeholders must monitor whether national building codes adopt prescriptive reinforcement rules that could exclude pure-extrusion systems from multi-story construction.
Market Dynamics
The 3D concrete printing services sector is restructuring around gantry-to-robotic system substitution as field-proven gantry platforms face displacement by mobile robotic arms capable of multi-axis deposition on irregular terrain.
Growth Catalysts
- CE marking harmonization:The EU Construction Products Regulation creates unified structural acceptance pathways across member states, compressing certification timelines for cross-border project deployment.
- Fiber-reinforced mix chemistry:High-dosage polypropylene and basalt fiber formulations exceeding 2% by volume eliminate steel reinforcement requirements in retaining walls and culvert applications.
- Texas municipal housing programs:Rapid single-family delivery mandates in Austin and San Antonio accelerate adoption of wall-assembly automation for affordable housing stock.
Market Restraints
- Portland cement price volatility:Clinker supply disruptions from EU ETS carbon border adjustments inflate input costs for printable mortar formulations.
- Operator certification scarcity:Germany's KBA and state building authorities maintain narrow pipelines for certified print technicians, throttling field deployment capacity.
- Precast concrete substitution:Established tilt-up and modular precast systems retain cost advantages in standardized rectangular structures below three stories.
Strategic Opportunities
- Seismic-zone code adoption:The US International Code Council's alternate methods evaluation creates pathways for printed elements in California and Pacific Northwest high-risk zones.
- Bridge infrastructure retrofit:Fiber-reinforced printed culverts and abutment walls address aging US highway infrastructure with geometric customization unavailable in precast.
- DIN standard convergence:Germany's compressive-strength testing protocol development positions early adopters for EU-wide specification dominance as harmonization proceeds.
Industry Challenges
- Layer-bond certification timelines:Interlayer adhesion testing protocols remain unsettled across national building codes, delaying multi-story structural approvals.
- Robotic system capex intensity:Field-deployed mobile print units require capital commitments exceeding traditional formwork equipment by an order of magnitude.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Concrete Printing Services Market |
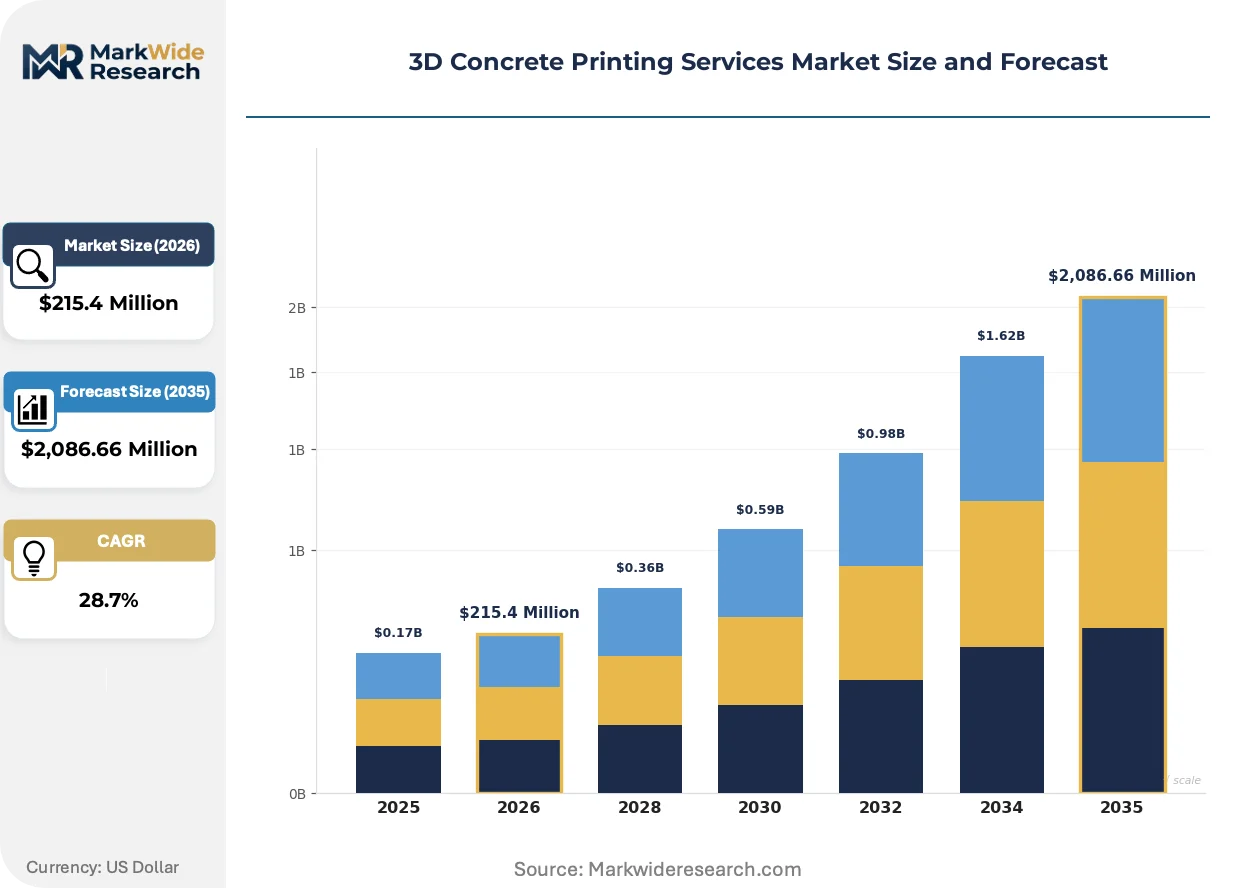
| Market Size in 2026 | $215.4 Million |
| Market Size in 2035 | $2,086.66 Million |
| CAGR (2026 – 2036) | 28.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Design Services, Construction Services, Consulting Services, Installation Services Application: Residential Buildings, Commercial Buildings, Infrastructure Projects, Art Installations Technology: Concrete Extrusion, Powder-based 3D Printing, Binder Jetting, Hybrid Printing End User: Architects, Contractors, Developers, Urban Planners |
| Companies Covered | Apis Cor, COBOD International A/S, ICON Technology Inc., XtreeE, CyBe Construction, Winsun, Sika AG, Holcim, Vertico, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Concrete Printing Services Market Trends and Innovations
Material science and motion-control engineering are converging to expand the addressable geometry of printable structures beyond rectilinear walls toward non-planar surfaces and topology-optimized load paths.
Gantry-based deposition systems are migrating from fixed-factory installations to portable field configurations. Infrastructure contractors in the Netherlands and Denmark now specify mobile units for remote bridge culvert fabrication. This shift compresses logistics costs and enables just-in-time production at constrained urban sites.
Germany's DIN standards committees are finalizing compressive-strength testing protocols specifically for layered concrete microstructures. The KBA coordinates with state building authorities to align these technical specifications with existing reinforced concrete codes. Contractors anticipating CE marking requirements are pre-qualifying mix designs to these draft protocols.
Design-build procurement models are displacing traditional design-bid-award sequences in municipal housing programs. Dutch municipalities near Eindhoven now bundle architectural design, structural engineering, and robotic fabrication under single-contractor responsibility. This consolidation accelerates project timelines and shifts liability exposure toward integrated service providers.
3D Concrete Printing Services Market Segmentation
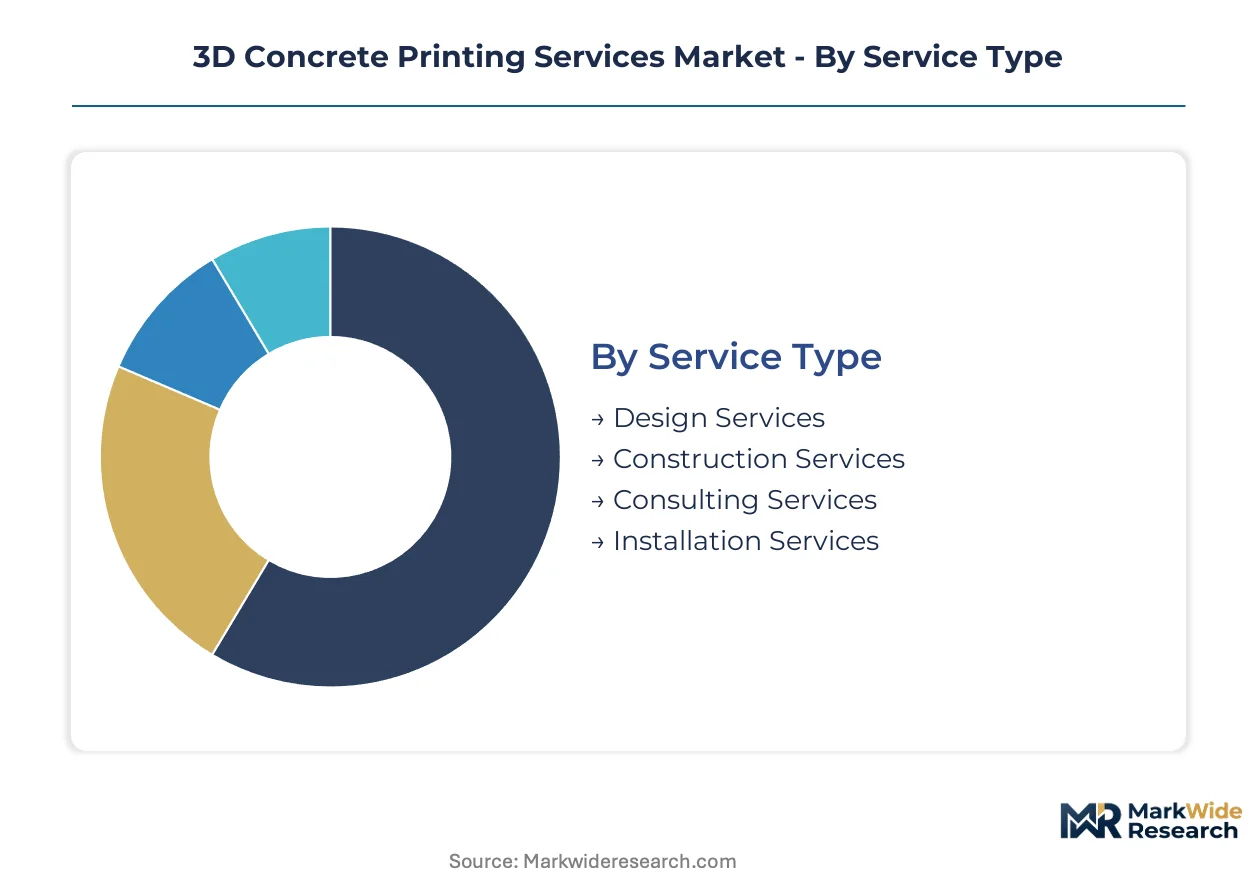
Segmentation in 3D concrete printing services reveals how value capture concentrates across the project lifecycle, from digital design through field assembly. Distinct capability requirements separate geometry-optimization services from capital-intensive robotic deployment, shaping vendor specialization and margin structures.
Service Type:
Mature construction execution services coexist with emerging design-to-fabrication integration as Dutch and Texan projects consolidate vendor responsibility.
- Design Services:Parametric modeling and topology optimization for printable geometries with slump constraints below 20 mm. Demand clusters with architects specifying non-planar surfaces for municipal housing estates near Eindhoven where geometric freedom justifies premium fees.
- Construction Services:Field-deployed robotic systems executing layer-by-layer deposition at 50–600 mm per second with certified print operators. Revenue concentrates here due to capital intensity of gantry and mobile arm platforms, with Texas municipal programs driving wall-assembly automation for affordable housing delivery mandates.
- Consulting Services:Regulatory navigation support for CE marking pathways and DIN standard pre-qualification.
- Installation Services:On-site system calibration and interlayer adhesion quality verification.
Construction Services retains volume leadership; Design Services holds the steepest expansion curve as design-build procurement consolidates liability.
Application:
Cost tier differentiation separates standardized housing from performance-grade infrastructure requiring fiber dosages above 2% by volume.
- Residential Buildings:Single-family wall assemblies and multi-unit pilot estates leveraging speed advantages for affordable housing delivery. Austin and San Antonio municipal programs in Texas anchor demand as builders compress timelines for low-rise structures.
- Infrastructure Projects:Bridge culverts, retaining walls, and abutment retrofits demanding basalt and polypropylene fiber reinforcement without steel. Aging US highway assets and Dutch remote bridge fabrication drive specifications for geometric customization unavailable in precast substitution.
- Commercial Buildings:Low-rise office and retail shells with rectangular footprints competing against tilt-up concrete cost benchmarks.
- Art Installations:Non-load-bearing sculptural elements exploiting aesthetic freedom of extrusion systems.
Infrastructure Projects gains share fastest as fiber-reinforced mix chemistry eliminates reinforcement trade-offs; Residential Buildings maintains the largest revenue base.
Technology:
Supply concentration favors extrusion platforms while hybrid systems emerge for multi-material deposition.
- Concrete Extrusion:Dominant gantry and mobile robotic arm systems depositing cementitious mixes with controlled slump and layer-bond timing. COBOD International A/S anchors European project pipelines with field-proven gantry expertise; ICON Technology Inc. sustains deployment speed records in Texas and Mexico.
- Hybrid Printing:Combined extrusion and selective reinforcement placement enabling multi-story structural approvals. Development concentrates in Germany where DIN committees draft compressive-strength testing protocols for layered microstructures.
- Powder-based 3D Printing:Binder jetting approaches for specialized architectural components with limited structural load requirements.
- Binder Jetting:Niche powder-bed systems for small-scale decorative elements outside load-bearing applications.
Concrete Extrusion dominates installed capacity; Hybrid Printing shows the most rapid capability advancement as seismic-zone codes evolve.
End User:
Customer type segmentation tracks procurement authority shifting from speculative developers to integrated design-build contractors.
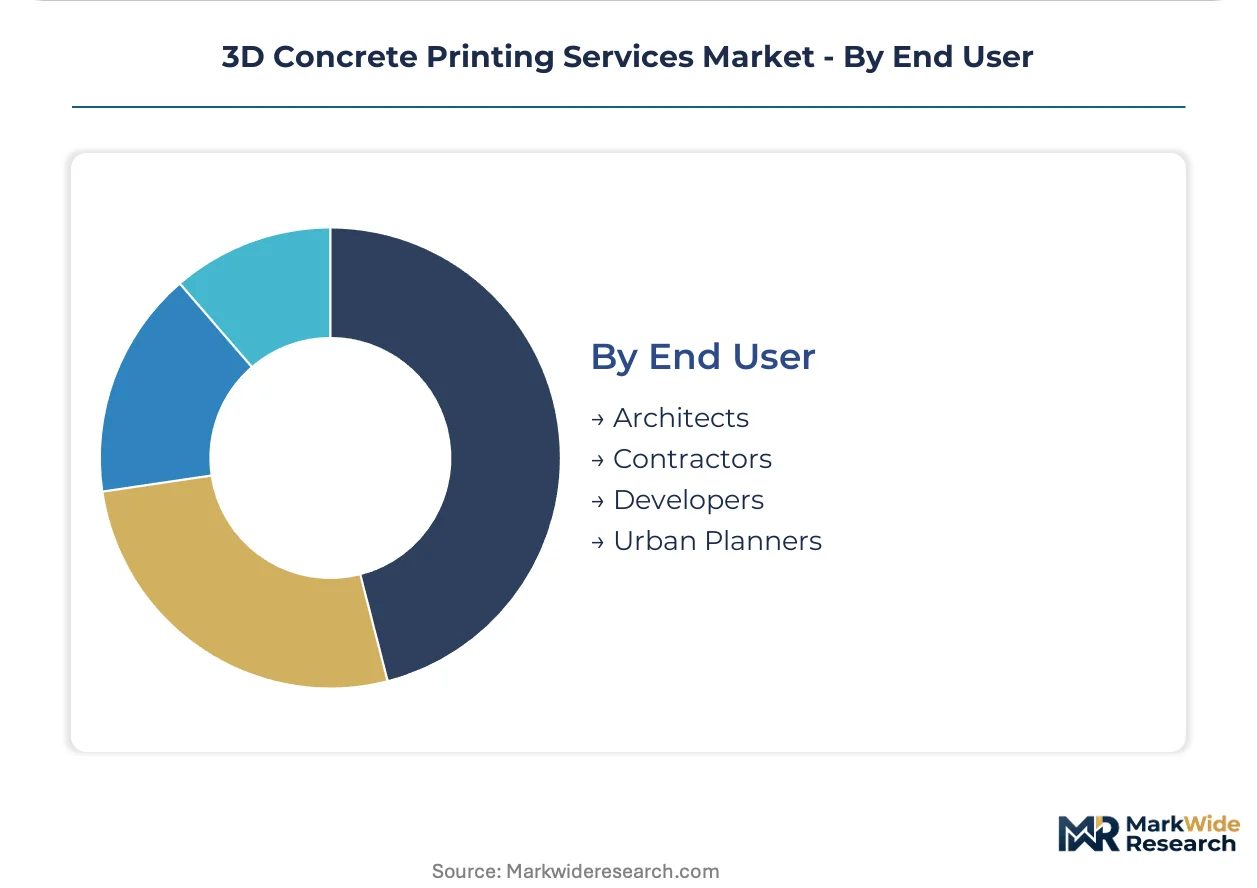
- Contractors:Primary revenue source capturing bundled fabrication responsibility under design-build models. Dutch municipalities near Eindhoven now award single-contractor packages combining design, engineering, and robotic deployment, accelerating timelines and concentrating vendor relationships.
- Developers:Speculative housing producers evaluating print speed against precast substitution economics for standardized structures below three stories.
- Architects:Early-stage geometry specification influencing material selection and system procurement.
- Urban Planners:Municipal officials mandating affordable housing delivery timelines that favor automation.
Contractors control the largest procurement volume; Urban Planners are expanding their influence fastest through delivery-mandate policies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment suppliers cluster in Germany and the Netherlands while deployment concentrates in Texas and the Dutch Brainport region. National building codes and municipal procurement programs determine adoption velocity across these concentrated zones.
United States
Texas municipal housing mandates in Austin and San Antonio accelerate single-family wall assembly automation. The International Code Council evaluates alternate methods for seismic-zone deployment in California and the Pacific Northwest. ICON Technology Inc. sustains deployment speed records across Texas and Mexico operations.
Germany
KBA coordination with state building authorities throttles certified print technician pipelines, constraining field capacity. DIN standards committees finalize compressive-strength testing protocols for layered concrete microstructures. Industrial clusters in Bavaria and North Rhine-Westphalia host pre-qualification laboratories for CE marking pathways.
Netherlands
Municipalities near Eindhoven fund pilot housing estates through bundled design-build procurement. The EU Construction Products Regulation shapes material certification pathways across member states. CyBe Construction and Vertico operate demonstration hubs serving Brainport regional housing programs.
China
Dual carbon goals and construction automation targets drive state-backed pilot projects in Yangtze River Delta infrastructure. GB standards committees draft performance specifications for fiber-reinforced printable mixes. Winsun anchors deployment capacity in Jiangsu province demonstration zones.
France
XtreeE exemplifies gantry-system adaptation for non-planar architectural geometries in Île-de-France municipal contracts. ANSM and CNIL oversight extends to construction robotics data governance in smart city integrations. Auvergne-Rhône-Alpes clusters develop topology-optimized load path specifications for bridge retrofit applications.
3D Concrete Printing Services Market Competitive Landscape
Gantry-system specialists and mobile robotic arm developers split the market between fixed-factory precision and irregular terrain adaptability. The vendor base concentrates around equipment manufacturers with field-proven deposition platforms and chemical suppliers controlling proprietary admixture formulations. Two archetypes dominate: integrated construction service providers bundling design-to-fabrication responsibility, and materials-science specialists licensing layer-bonding chemistry. Competitive moves center on strategic partnerships between equipment vendors and municipal housing authorities, plus geographic expansion through demonstration hub licensing.
Within the integrated construction tier, COBOD International A/S and ICON Technology Inc. occupy positions reflecting gantry and mobile robotic specializations respectively. COBOD anchors European project pipelines through field-proven gantry expertise. ICON exemplifies speed-focused deployment records across North American and Latin American operations. Sika AG sits within the materials-science archetype, differentiating through proprietary admixture chemistry for layer-bonding acceleration.
| Leading Market Players |
|---|
| Apis Cor |
| COBOD International A/S |
| ICON Technology Inc. |
| XtreeE |
| CyBe Construction |
| Winsun |
| Sika AG |
| Holcim |
| Vertico |
| Others |
Pricing and Supply Chain Analysis
Rotterdam-Antwerp freight corridors carry admixture chemicals and gantry system components from German industrial clusters to Dutch demonstration hubs, with transport cost volatility compressing margins for field-deployed service providers while amplifying price spreads between certified and uncertified print operators.
Pricing Analysis
CE marking harmonization dictates the pricing tier structure across member states, separating premium-certified providers from standard-tier operators lacking cross-border project eligibility. Price differentiation rests on certification grade and volume scale, with municipal housing programs in Texas and the Netherlands commanding project-based premiums for speed-guaranteed delivery. Pricing pressure stems from Portland cement input cost volatility under EU ETS carbon border adjustments. Developers of standardized structures below three stories exhibit highest price sensitivity, while infrastructure contractors retrofitting aging highway assets show lowest sensitivity due to geometric customization requirements unavailable in precast substitution.
Supply Chain Analysis
Tariff exposure between China and Germany dominates supply chain risk for robotic arm actuators and fiber reinforcement feedstock. Equipment manufacturing concentrates in Germany, the Netherlands, and Denmark, while printable mortar formulation draws from Belgian and French chemical clusters. Raw material dependencies center on Portland cement clinker, polypropylene and basalt fibers, and proprietary admixture chemistry. Single-source vulnerability persists for high-dosage fiber suppliers serving infrastructure-grade applications. Distribution runs through design-build contractors bundling design, engineering, and robotic deployment under single-contractor responsibility.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The 3D concrete printing services sector represents a high-growth disruption as fiber-reinforced mix chemistry exceeding 2% by volume eliminates steel reinforcement requirements and unlocks infrastructure retrofit applications previously uneconomical for extrusion systems.
For Market Incumbents: Pre-empt gantry-system displacement by mobile robotic arms through accelerated field deployment of multi-axis deposition platforms capable of irregular terrain adaptation. Anchor capacity in Texas and Dutch Brainport demonstration hubs before certification pipelines expand. Defend against precast concrete substitution by embedding design-build procurement relationships with municipal housing authorities.
For New Entrants and Emerging Players: Pursue seismic-zone code adoption pathways in California and the Pacific Northwest as the US International Code Council evaluates alternate methods for high-risk zone deployment. Target bridge infrastructure retrofit specifications where geometric customization unavailable in precast creates white-space opportunity. Enter through admixture chemistry licensing rather than capital-intensive robotic system ownership.
For Investors and Strategic Acquirers: Carve-out targets emerge from construction conglomerates with captive materials-science divisions underutilized for printable concrete applications. Five-to-ten year viability hinges on DIN standard convergence positioning early adopters for EU-wide specification dominance. Monitor layer-bond certification timeline resolution as the inflection signal for multi-story structural approval scalability.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pre-Qualification | Compresses cross-border project deployment timelines under EU Construction Products Regulation harmonization. |
| Mobile Robotic Arm Deployment | Displaces fixed gantry systems for irregular terrain adaptation in remote bridge culvert fabrication. |
| Fiber-Reinforced Mix Development | Eliminates steel reinforcement requirements in retaining walls and culvert applications exceeding 2% dosage. |
| Design-Build Procurement Consolidation | Shifts liability exposure toward integrated service providers bundling architectural and robotic fabrication responsibility. |
| Seismic-Zone Code Adoption | Creates structural acceptance pathways in California and Pacific Northwest through ICC alternate methods evaluation. |
Research Methodology
A standing panel of robotic fabrication engineers, municipal housing procurement officers, admixture chemists, and DIN standards committee members provided ongoing calibration across primary interviews combined with secondary validation from EU Construction Products Regulation filings, KBA certification records, and SEC disclosures from construction technology vendors. Bottom-up project pipeline tracking across Texas municipal programs and Dutch Brainport developments triangulated against top-down equipment installation estimates.
Scenario-bracketing framed projections across the analysis window, modeling segmentation dimensions including service type, application tier, deposition technology, and end-user procurement authority. CAGRs derived from layer-by-layer deployment velocity trajectories and fiber-reinforced mix adoption curves in infrastructure applications. Forecast inputs incorporated certified print operator pipeline constraints and CE marking harmonization velocity.
Sensitivities concentrate around layer-bond certification timeline resolution, Portland cement price volatility under carbon border adjustments, and precast concrete substitution economics for standardized structures. Forecasts reflect documented assumptions subject to revision from regulatory protocol finalization or robotic system capex intensity shifts. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Services
Maintenance Repair and Operations (MRO) Market
Construction Services
North and Latin America Weatherization Services Market
Construction Services
Europe Maintenance, Repair, and Operations (MRO) Market
Construction Services
MENA Architectural Services Market
Construction Services
North America Fire Sprinkler Systems Market
Construction Services
Global Industrial Services Market
Construction Services
Excavating Contractor Market
Construction Services
Die Casting Services Market
Construction Services
North America Repair and Rehabilitation Market
Construction Services
Testing, Inspection, and Certification for Construction Market
Construction Services
Construction Equipment Repair and Maintenance Services Market
Construction Services
NDT and Inspection Market
Construction Services
Condenser Cleaners Market
Construction Services
Train Contractor Market
Construction Services
Remote Construction Market
Construction Services
Construction Materials Testing Equipment Market