
 Flux Spraying Machine Market | 2026-2036
Flux Spraying Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Flux Spraying Machine Market Insights
Precision-grade flux application is collapsing the gap between manual bench operations and fully automated SMT lines. SENJU METAL INDUSTRY CO., LTD. leverages its solder material expertise to anchor integrated flux-spray solutions across Japanese electronics factories. TAMURA Corporation competes through thermal process control systems that extend into adjacent coating equipment. Seika Machinery, Inc. specializes in selective spray technologies that occupy niche positions in high-mix, low-volume contract manufacturing.
A flux spraying machine dispenses controlled volumes of soldering flux onto printed circuit boards or component leads prior to wave, selective, or reflow soldering, typically operating at spray widths between 50 mm and 500 mm with adjustable atomization pressure. Automated sprayers now dominate electronics manufacturing as line speeds exceed three meters per minute, while ultrasonic sprayers capture premium positions in semiconductor fabrication where flux uniformity directly affects die-attach yield. Thermal spray technology leads volume shipments for heavy-duty PCB applications, though cold spray variants are gaining traction in battery production where heat-sensitive substrates require minimal thermal load.
REACH in Europe restricts volatile organic compounds in flux formulations, compelling equipment redesigns that reduce overspray and chemical waste. China's SAMR enforces GB standards for electronics manufacturing emissions, creating compliance-driven replacement cycles among Guangdong-based assemblers. Japan's METI promotes JIS-aligned smart factory protocols that reward connected flux spraying systems with predictive maintenance capability. Stakeholders must weigh regional certification requirements against platform standardization when configuring equipment portfolios for multi-country deployment.
Market Dynamics
Flux spraying equipment procurement is bifurcating between high-throughput SMT line integrators and precision semiconductor fabricators, with each segment demanding incompatible performance specifications from shared supplier bases.
Growth Catalysts
- China's GB standards enforcement:SAMR-mandated emissions controls in Guangdong Province are compelling contract manufacturers to replace legacy flux applicators with closed-loop precision systems.
- Semiconductor die-attach yield requirements:Advanced packaging facilities now specify ultrasonic atomization for flux deposition uniformity below 5% coefficient of variation.
- Battery cell interconnect scaling:Lithium-ion module producers in South Korea and Japan are adopting cold spray flux systems to protect temperature-sensitive polymer substrates.
Market Restraints
- Specialized nozzle supply concentration:Precision ceramic atomization heads rely on Japanese and German ceramic sintering capabilities, creating single-source vulnerability.
- REACH compliance cost escalation:ECHA-mandated volatile organic compound reductions require activated carbon filtration retrofits that add 15-25% to equipment base cost.
- Technical limitation in high-viscosity fluxes:Nozzle clogging rates above 12% per shift persist with water-soluble flux formulations above 35% solids content.
Strategic Opportunities
- India's PLI scheme for electronics:Subsidized capacity expansion in Tamil Nadu and Karnataka is creating first-mover advantage for flux system vendors establishing local service infrastructure.
- Automotive electronics convergence:EV power module assembly lines require flux spraying integration with laser welding stations, opening combined process equipment contracts.
- Predictive maintenance protocols:METI-aligned JIS standards for smart factory certification reward connected flux systems with sensor-based nozzle wear monitoring.
Industry Challenges
- Multi-standard certification timelines:Equipment qualifying for CE marking, GB compliance, and UL listing simultaneously faces 14-18 month validation cycles.
- Legacy line integration complexity:Retrofitting selective spray heads into 1990s-era wave soldering systems requires custom mechanical interfacing that erodes project margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flux Spraying Machine Market |
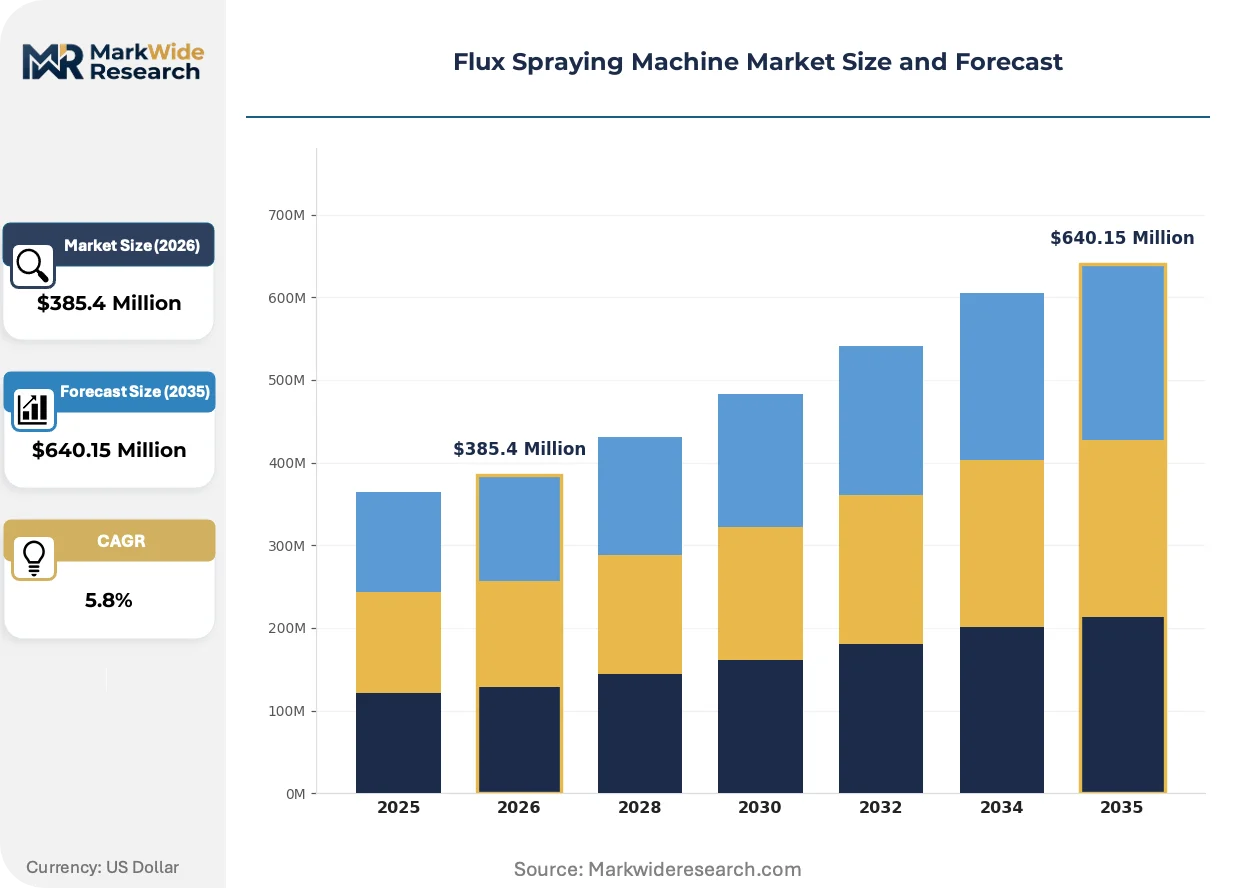
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $640.15 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Sprayers, Manual Sprayers, Ultrasonic Sprayers, Electrostatic Sprayers, Pneumatic Sprayers Technology: Thermal Spray, Cold Spray, Plasma Spray, Arc Spray, Flame Spray Application: PCB Assembly, Semiconductor Fabrication, Solar Module Manufacturing, Battery Production, Electronics Packaging End User Industry: Electronics Manufacturing, Renewable Energy, Automotive Suppliers, Aerospace Components, Defense Systems |
| Companies Covered | SENJU METAL INDUSTRY CO., LTD., Seika Machinery, Inc, TAMURA Corporation, ITT INC., OUBEL, Primetals Technologies Limited, SMS group GmbH, Danieli & C. Officine Meccaniche S.p.A., Tenova S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flux Spraying Machine Market Trends and Innovations
Active flux formulation chemistry is reshaping equipment design priorities, with low-residue and halogen-free variants demanding redesigned spray chamber materials and exhaust handling systems.
Ultrasonic atomization is bifurcating the precision segment from conventional pressure-fed systems. Semiconductor packaging houses in Taiwan and South Korea now specify 40-80 kHz transducer arrays for sub-50-micron droplet consistency. This capability gap is compressing supplier tiers into distinct precision-grade and volume-grade equipment categories with minimal overlap.
REACH Annex XVII restrictions on VOC content are forcing flux chemistry reformulation across European electronics manufacturing. Equipment vendors must now engineer spray chambers from 316L stainless steel or fluoropolymer linings to withstand more aggressive water-based fluxes. German and Czech PCB assemblers are absorbing these equipment premiums to maintain CE-marked product export eligibility.
Contract manufacturers are consolidating equipment procurement under technical service agreements rather than capital purchase models. Foxconn and Jabil equivalents in Vietnam and Mexico now demand bundled flux, equipment, and maintenance contracts with uptime guarantees. This preference shift is visible most acutely in Mexico's Baja California electronics corridor, where US-bound assembly operations prioritize operational expenditure predictability over asset ownership.
Flux Spraying Machine Market Segmentation
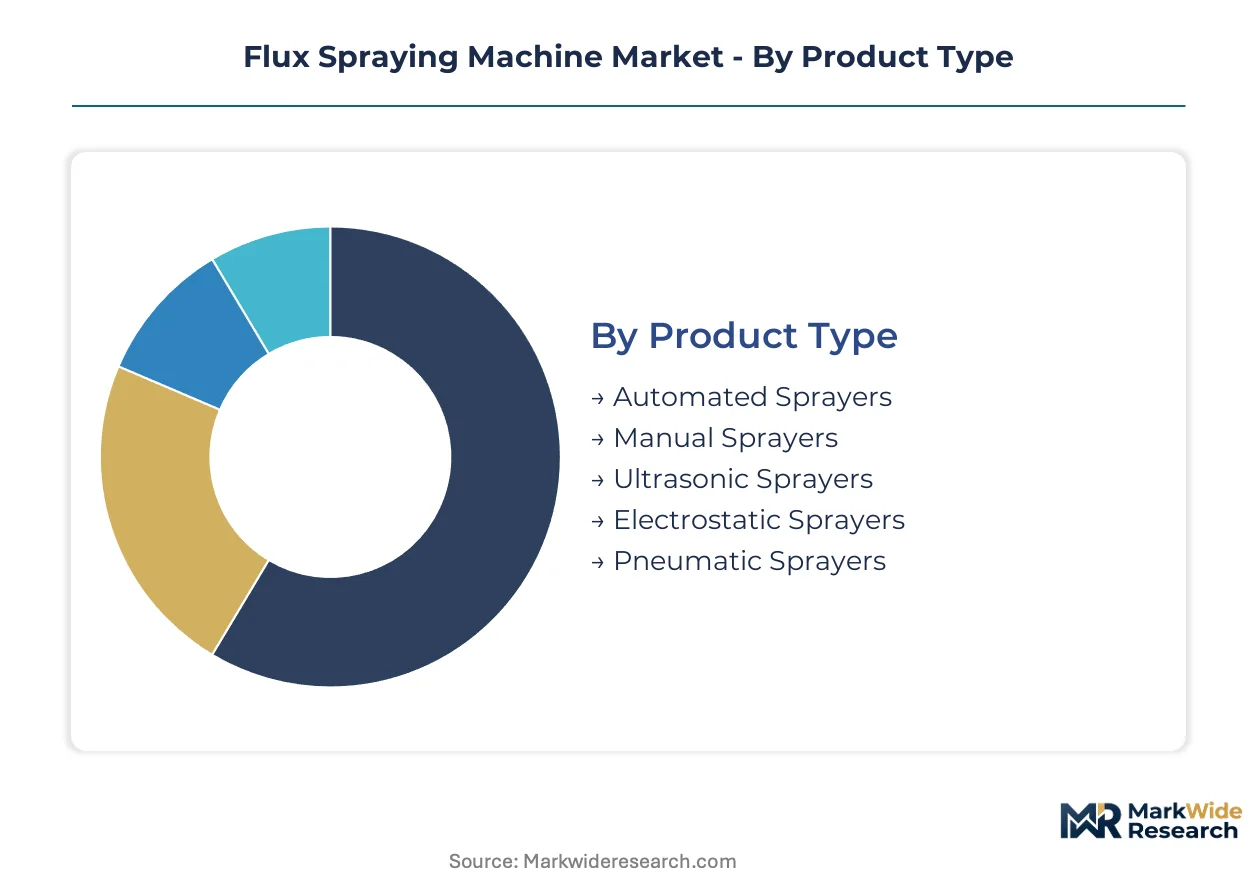
Flux spraying equipment segments diverge sharply between high-volume contract manufacturers and precision fabricators. Each dimension—product architecture, deposition physics, application environment, and end-use industry—creates distinct procurement criteria that reshape supplier positioning.
Product Type:
Domestic demand in China absorbs automated and ultrasonic variants, while manual and pneumatic systems serve export-oriented contract manufacturers in Vietnam and Mexico seeking flexible, lower-capex configurations.
- Automated Sprayers:These systems integrate with SMT lines exceeding three meters per minute, featuring closed-loop flux recovery and programmable spray widths. Guangdong Province contract manufacturers deploy these to meet SAMR emissions mandates while maintaining throughput for US-bound electronics exports.
- Ultrasonic Sprayers:Piezoelectric transducer arrays operating at 40-80 kHz deliver sub-50-micron droplet consistency for die-attach applications. Taiwan and South Korea semiconductor packaging houses specify these for flux uniformity below five percent coefficient of variation.
- Manual Sprayers:Benchtop units with adjustable atomization pressure serve high-mix, low-volume operations in Mexico's Baja California corridor.
- Electrostatic Sprayers:Charged particle deposition systems reduce overspray in European REACH-compliant facilities.
- Pneumatic Sprayers:Compressed-air atomization dominates legacy wave soldering retrofits where thermal sensitivity is secondary.
Automated sprayers command the established base. The steepest expansion runs through ultrasonic sprayers.
Technology:
Cost tiers separate thermal and arc spray systems serving commodity PCB applications from premium cold spray and plasma variants protecting temperature-sensitive substrates.
- Thermal Spray:Combustion-driven particle acceleration delivers high deposition rates for heavy-duty PCB fluxing. Volume shipments concentrate in East Asian electronics manufacturing clusters where line speed outweighs thermal load concerns.
- Cold Spray:Kinetic deposition without combustion protects polymer battery substrates in South Korean and Japanese lithium-ion module production. Minimal thermal exposure prevents separator damage during cell interconnect fabrication.
- Plasma Spray:Electric arc plasma streams enable ceramic-rich flux formulations for aerospace component soldering.
- Arc Spray:Twin-wire electric arc systems occupy mid-tier electronics packaging with balanced throughput and capital efficiency.
- Flame Spray:Oxygen-fuel combustion remains prevalent in emerging market renewable energy manufacturing.
Thermal spray anchors volume deployment. Cold spray gains share fastest in battery-adjacent segments.
Application:
Customer type bifurcation splits the segment between automotive supplier specifications demanding traceability and defense systems requiring hardened certification.
- PCB Assembly:Wave and selective soldering lines in China's Pearl River Delta absorb automated flux spraying for consumer electronics, telecommunications hardware, and industrial control boards. Miniaturization standards below 0201 component sizes drive precision nozzle specifications.
- Semiconductor Fabrication:Advanced packaging facilities in Hsinchu and Yongin require ultrasonic atomization for flip-chip and system-in-package flux deposition. Yield sensitivity at die-attach stages justifies equipment premiums exceeding standard SMT configurations.
- Solar Module Manufacturing:Tabbing and stringing operations in Vietnam and Malaysia use pneumatic spraying for cell interconnect soldering.
- Battery Production:Cold spray systems protect temperature-sensitive polymer substrates in cylindrical and prismatic cell assembly.
- Electronics Packaging:Hermetic sealing applications in aerospace and medical device manufacturing specify plasma spray for specialized flux chemistries.
PCB assembly commands the established base. Semiconductor fabrication climbs the fastest.
End User Industry:
Supply concentration in Japanese ceramic nozzle manufacturing and German filtration systems creates tiered access for electronics versus renewable energy buyers.
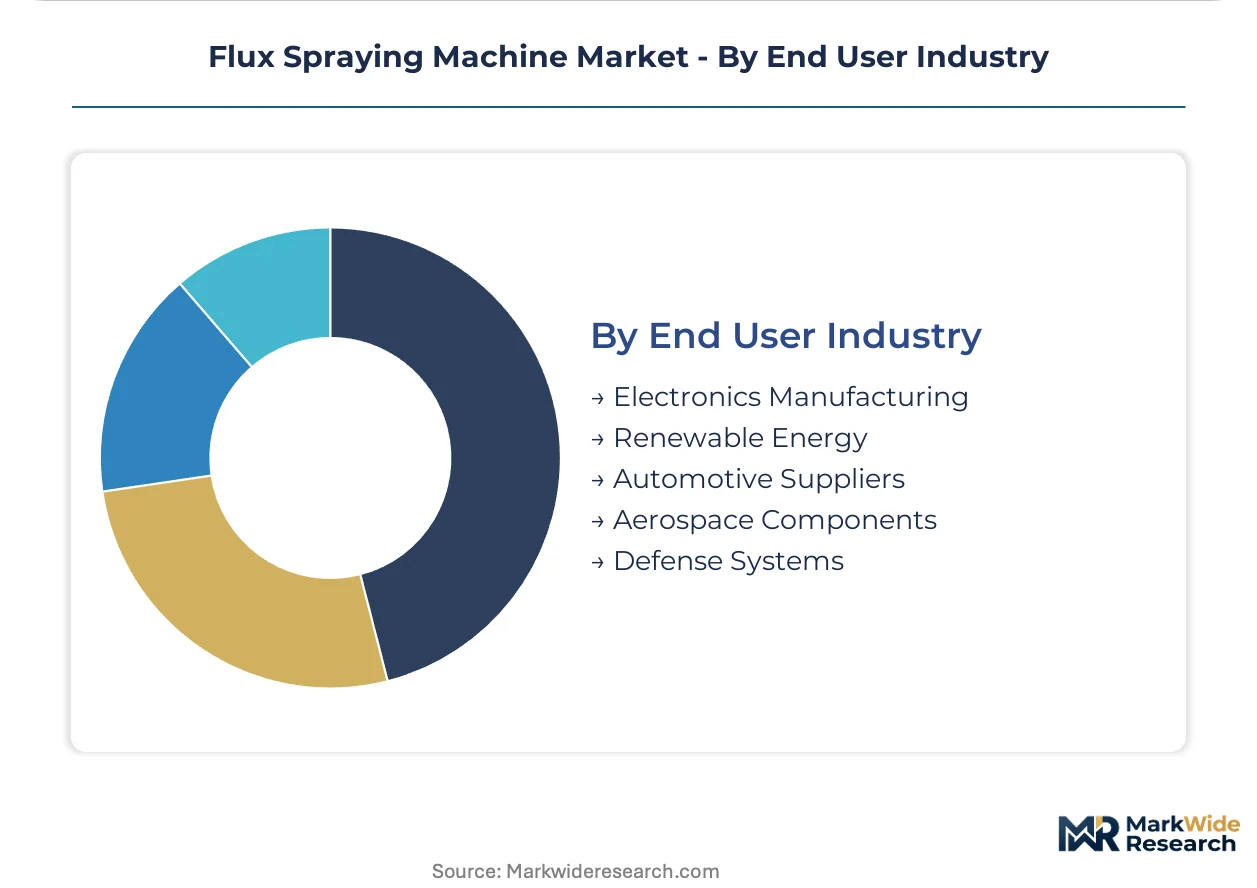
- Electronics Manufacturing:Contract assemblers in Shenzhen, Dongguan, and Suzhou deploy integrated flux-spray solutions across consumer, computing, and communication device production. REACH and GB standards drive closed-loop system replacement cycles.
- Automotive Suppliers:EV power module producers integrate flux spraying with laser welding stations for silicon carbide inverter assembly. Combined process equipment contracts favor vendors with multi-physics capabilities.
- Renewable Energy:Solar module producers in Southeast Asia prioritize capital efficiency over precision specifications.
- Aerospace Components:Nadcap-certified facilities specify plasma spray for high-reliability soldering under extreme thermal cycling.
- Defense Systems:ITAR-controlled manufacturing in domestic supply chains restricts equipment sourcing to approved vendor lists.
Electronics manufacturing commands the established base. Automotive suppliers show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese and German ceramic sintering capabilities anchor precision nozzle supply, while equipment assembly clusters concentrate in China's Pearl River Delta and South Korea's Gyeonggi corridor. Regional procurement patterns diverge sharply between REACH-compliant European retrofits and GB-standard-driven replacement cycles in East Asia.
China
Guangdong Province contract manufacturers absorb automated flux spraying systems as SAMR enforces GB emissions standards on electronics assembly operations. Shenzhen and Dongguan clusters are replacing legacy open-loop applicators with closed-loop precision equipment to maintain export eligibility for CE-marked products. Domestic vendors now capture mid-tier procurement previously held by Japanese suppliers.
Japan
Chubu and Kanto electronics corridors specify ultrasonic atomization systems for semiconductor packaging and automotive module assembly. METI smart factory protocols reward connected flux equipment with predictive maintenance certification, accelerating replacement of standalone systems. Nagoya-based precision ceramic manufacturers supply atomization heads to Taiwanese and South Korean packaging houses.
Germany
Bavarian and Baden-Württemberg automotive suppliers integrate flux spraying with laser welding stations for silicon carbide inverter production. ECHA REACH Annex XVII VOC restrictions require activated carbon filtration retrofits that add equipment cost premiums. Stuttgart industrial equipment vendors now bundle compliance engineering with hardware sales to defend margin positions.
South Korea
Gyeonggi Province battery cell producers adopt cold spray flux systems to protect temperature-sensitive polymer substrates in cylindrical and prismatic cell assembly. MFDS-aligned manufacturing standards for automotive-grade cells specify deposition uniformity below 5% coefficient of variation. Yongin semiconductor packaging facilities source ultrasonic transducer arrays from domestic precision electronics suppliers.
United States
Texas and Arizona semiconductor fabrication facilities specify precision flux deposition for advanced packaging operations serving defense and aerospace supply chains. ITAR-controlled manufacturing restricts equipment sourcing to approved vendor lists, compressing procurement timelines. EPA regional offices in Dallas and San Francisco coordinate VOC emission audits for electronics manufacturers operating under delegated state programs.
Flux Spraying Machine Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the flux spraying equipment sector. Japanese and German precision ceramic specialists anchor the premium ultrasonic and selective spray segments, while Chinese system integrators dominate volume shipments for standard SMT line configurations. Three archetypes define competitive positioning: materials-science-anchored conglomerates with captive flux chemistry expertise, precision automation specialists serving semiconductor packaging, and contract manufacturing-focused system integrators. M&A activity concentrates on nozzle technology acquisitions and regional service infrastructure expansion.
Among Japanese materials-science conglomerates, SENJU METAL INDUSTRY CO., LTD. exemplifies the integrated flux-equipment archetype, while TAMURA Corporation occupies a position within thermal process control system vendors extending into adjacent coating equipment. Seika Machinery, Inc. represents the precision automation specialist tier serving high-mix, low-volume contract manufacturing with selective spray technologies.
| Leading Market Players |
|---|
| SENJU METAL INDUSTRY CO., LTD. |
| Seika Machinery, Inc |
| TAMURA Corporation |
| ITT INC. |
| OUBEL |
| Primetals Technologies Limited |
| SMS group GmbH |
| Danieli & C. Officine Meccaniche S.p.A. |
| Tenova S.p.A. |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at Japanese ceramic sintering facilities anchors atomization head production costs, compressing margins for equipment vendors sourcing precision nozzles while simultaneously elevating price floors for REACH-compliant system configurations. Guangdong-based contract manufacturers absorb these premiums to maintain CE-marked export eligibility, creating tiered procurement dynamics across East Asian electronics corridors.
Pricing Analysis
REACH Annex XVII dictates the pricing tier structure across European electronics manufacturing, separating activated carbon filtration-equipped systems from standard configurations. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with UL-listed and METI-aligned smart factory protocols commanding equipment premiums. Cost compression in mid-tier thermal spray configurations is intensifying because domestic Chinese vendors now replicate Japanese automation architectures. Contract manufacturers in Vietnam and Mexico exhibit highest price sensitivity, prioritizing operational expenditure predictability over capital ownership, while semiconductor packaging houses in Taiwan and South Korea demonstrate lowest sensitivity due to yield-critical specifications.
Supply Chain Analysis
Strategic stockpiling of precision ceramic atomization heads characterizes procurement behavior among Taiwanese semiconductor packaging houses, contrasting with just-in-time flux chemistry replenishment practiced by Guangdong contract manufacturers. Japanese and German ceramic sintering capabilities anchor nozzle supply, while equipment assembly clusters concentrate in China's Pearl River Delta and South Korea's Gyeonggi corridor. Raw material dependencies include zirconia-based ceramics for transducer arrays, 316L stainless steel for spray chamber fabrication, and activated carbon filtration media. Single-source vulnerability persists in piezoelectric transducer supply. Distribution runs through technical service agreements bundling equipment, consumables, and maintenance contracts rather than discrete capital sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flux spraying equipment penetration remains below saturation across India's PLI-subsidized electronics corridors and Mexico's Baja California assembly operations, positioning the market for early-cycle expansion as battery cell interconnect scaling accelerates cold spray adoption.
For Market Incumbents: Secure captive supply of precision ceramic atomization heads through backward integration into Japanese or German sintering partnerships, insulating against single-source nozzle vulnerability. Defend service contract renewals by embedding predictive maintenance sensors aligned with METI JIS smart factory certification requirements, countering emerging Chinese system integrators competing on capital equipment cost.
For New Entrants and Emerging Players: Differentiate on cold spray thermal management specialization targeting South Korean and Japanese lithium-ion module producers, where temperature-sensitive polymer substrate protection commands equipment premiums. India's Tamil Nadu and Karnataka electronics clusters represent the most penetrable geography, with subsidized capacity expansion creating first-mover advantage for vendors establishing local service infrastructure. Pursue bundled technical service agreements with uptime guarantees rather than discrete equipment sales.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among precision automation specialists serving semiconductor packaging houses with ultrasonic atomization systems, where die-attach yield requirements sustain long-term service contract viability. Target acquisition archetypes include ceramic nozzle technology specialists and regional service infrastructure operators in Southeast Asia. Watch cold spray penetration rates in battery cell manufacturing as the inflection indicator for technology substitution risk in thermal spray-dominated segments.
| Strategic Initiative | Industry Significance |
|---|---|
| Nozzle Technology Acquisition | Captive ceramic sintering capability insulates against Japanese and German supply concentration. |
| Regional Service Infrastructure Expansion | Local technical presence in India's PLI corridors captures subsidized capacity buildout contracts. |
| Predictive Maintenance Platform Development | Sensor-based nozzle wear monitoring aligns with METI JIS smart factory certification rewards. |
| Cold Spray System Specialization | Thermal-minimal deposition protects battery polymer substrates in South Korean cell assembly. |
| REACH Compliance Engineering Bundling | Activated carbon filtration integration defends margin positions in Bavarian automotive supplier markets. |
Research Methodology
A standing panel of SMT line integration engineers, semiconductor packaging equipment procurement managers, contract manufacturing operations directors, and flux chemistry formulators provided ongoing calibration throughout the research process. Primary interviews with these stakeholders combined with secondary validation against SAMR GB standard enforcement records, ECHA REACH Annex XVII amendment filings, METI smart factory protocol documentation, and SEC 10-K equipment vendor disclosures. Bottom-up shipment data from Guangdong and Gyeonggi manufacturing clusters triangulated against top-down electronics production forecasts.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including deposition physics technology, application environment, end-use industry vertical, and regional regulatory compliance tier. CAGRs derived from shipment trajectory analysis incorporating line speed evolution, miniaturization standard progression, and compliance-driven replacement cycle timing. Industry-specific forecast inputs included die-attach yield sensitivity coefficients and battery cell interconnect scaling projections.
The analysis sits within stated boundaries; outcomes outside sustained enforcement of SAMR emissions mandates and REACH VOC restrictions would require recalibration. Forecasts reflect assumptions regarding ceramic nozzle supply continuity and flux chemistry formulation stability. Revision becomes warranted when cold spray penetration in battery manufacturing crosses threshold levels sufficient to displace thermal spray volume leadership.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Global Mechanical Seals Market
Material Handling Equipment
Global Industrial Lifting Equipment Market
Material Handling Equipment
Industrial Mezzanines Market
Material Handling Equipment
Explosion Proof Crane Market
Material Handling Equipment
Drag Chain for Machine Market
Material Handling Equipment
Hi Lift Jack Market
Material Handling Equipment
Global Metal Shredder Machine Market
Material Handling Equipment
Slag Handling Machine Market
Material Handling Equipment
Australia and New Zealand Industrial Fasteners Market
Material Handling Equipment
Autonomous Warehouse Equipment Market
Material Handling Equipment
Material Handling Equipment Market
Material Handling Equipment
Portable Loading Ramps Market
Material Handling Equipment
Chain-Driven Roller Conveyors Market
Material Handling Equipment
Drive-In Pallet Racking Market
Material Handling Equipment
Wear Plates Market
Material Handling Equipment
Hook Lifts and Skip Loaders Market