
 Middle East and Africa Industrial Maintenance Services in Operational Improvement and Operational Maintenance Market | 2026-2036
Middle East and Africa Industrial Maintenance Services in Operational Improvement and Operational Maintenance Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Industrial Maintenance Services in Operational Improvement and Operational Maintenance Market Foresight
Buyer concentration among Gulf-based oil and gas conglomerates is recalibrating contract structures toward long-term performance-based agreements. Siemens AG leverages its digital twin capabilities to secure multi-year maintenance partnerships with regional refiners. ABB Ltd anchors its position through integrated robotics and electrification service bundles tailored to Middle Eastern utilities. Yokogawa Electric Corporation differentiates via deep specialization in distributed control system maintenance across African power generation assets.
The Middle East and Africa Industrial Maintenance Services in Operational Improvement and Operational Maintenance encompasses systematic upkeep, diagnostic intervention, and performance optimization of industrial assets through scheduled, predictive, and condition-based protocols. These services integrate vibration analysis, thermal imaging, and oil analysis to extend equipment life cycles and sustain throughput in continuous-process environments. Predictive maintenance commands premium pricing due to its reliance on machine learning algorithms and IoT sensor networks that reduce catastrophic failure incidence. Condition-based maintenance is expanding fastest among African utilities with limited capital budgets, while routine maintenance retains volume dominance across mature oil and gas installations.
Saudi Arabia's SFDA and the UAE's MOHAP enforce occupational safety frameworks that elevate maintenance standards in hydrocarbon processing facilities. South Africa's Department of Mineral Resources and Energy mandates specific equipment inspection intervals that shape service procurement patterns in mining and power sectors. Egypt's industrial regulatory bodies are aligning with ISO 55000 asset management standards, creating compliance-driven demand for certified maintenance providers. Stakeholders must evaluate how carbon intensity reporting requirements across Gulf jurisdictions will reshape operational maintenance scopes and technology investments.
Market Dynamics
Buyer consolidation among Gulf oil and gas conglomerates is forcing maintenance providers toward outcome-based contract structures that tie fees to uptime guarantees rather than labor hours.
Growth Catalysts
- SFDA Safety Mandates:Saudi Arabia's enforcement of occupational safety frameworks in hydrocarbon processing facilities is elevating maintenance standards and expanding certified service demand.
- IoT Sensor Networks:Vibration analysis and thermal imaging systems are enabling predictive maintenance protocols that extend equipment life cycles in continuous-process environments.
- UAE Refining Clusters:Concentrated petrochemical infrastructure around Abu Dhabi and Dubai is generating sustained demand for integrated operational improvement services.
Market Restraints
- Specialized Labor Scarcity:Shortage of certified vibration analysts and thermal imaging technicians limits service capacity expansion across African utilities.
- Import Dependency:Critical spare parts and advanced diagnostic equipment concentrate supply through European and East Asian manufacturers, exposing operators to currency fluctuation risks.
- Capital Intensity:Condition monitoring hardware and machine learning platform investments require substantial upfront expenditure that constrains smaller African power generators.
Strategic Opportunities
- Egyptian ISO 55000 Alignment:Industrial regulatory bodies are adopting asset management standards that create compliance-driven demand for certified maintenance providers.
- Digital Twin Convergence:Virtual commissioning technology is merging with real-time sensor data to enable remote diagnostics across Middle Eastern refining assets.
- African Utility Modernization:Power generation operators with limited capital budgets represent an underserved segment for condition-based maintenance subscription models.
Industry Challenges
- Certification Bottlenecks:ISO 55000 and SFDA compliance timelines stretch 12-18 months, delaying contract awards for new market entrants.
- Legacy System Integration:Distributed control systems from multiple vendors create interoperability friction when deploying unified predictive maintenance platforms.
- Skills Migration:Experienced maintenance engineers relocate to Gulf hubs, depleting technical talent pools in secondary African markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Industrial Maintenance Services in Operational Improvement and Operational Maintenance Market |
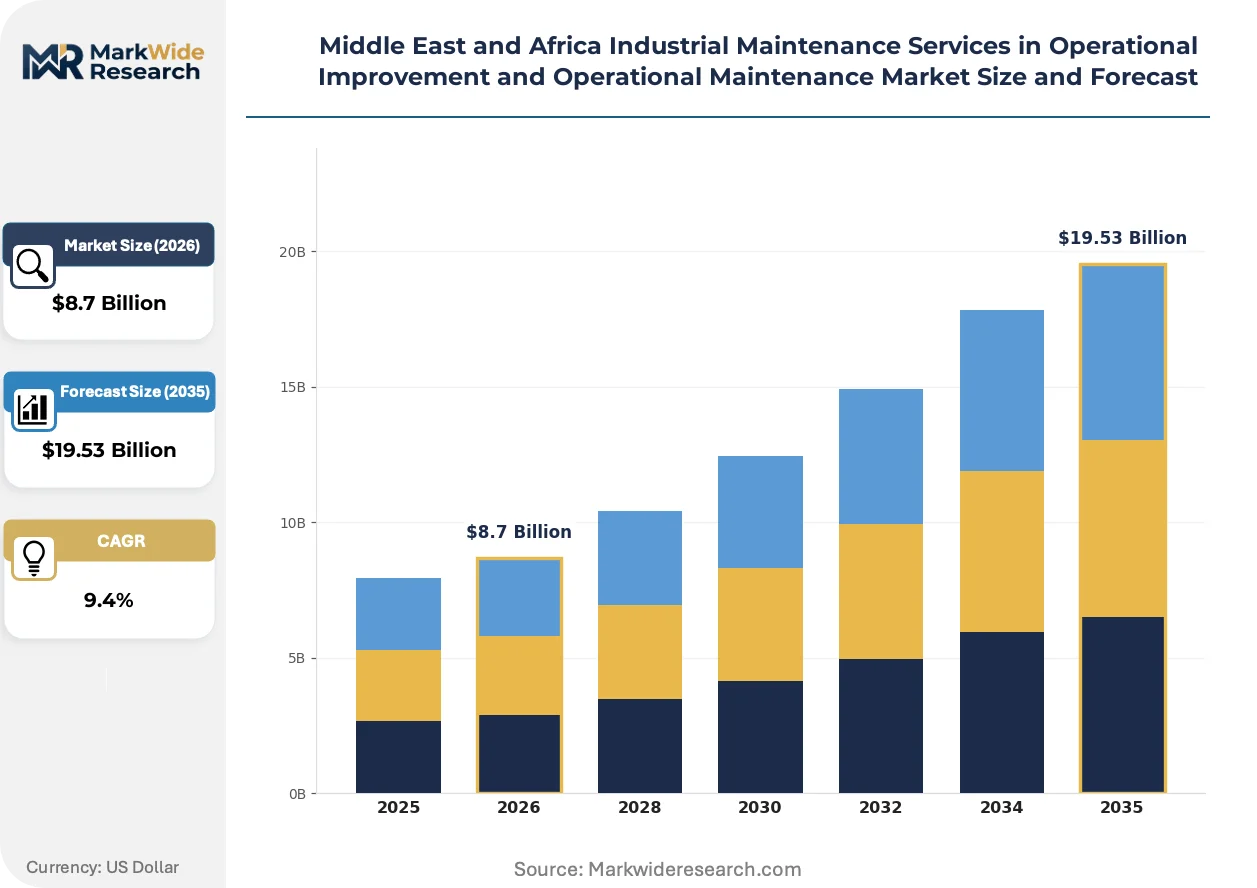
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Predictive Maintenance, Corrective Maintenance, Routine Maintenance, Condition-Based Maintenance Industry Vertical: Aerospace, Automotive Manufacturing, Oil & Gas, Power Generation Technology: IoT Sensors, CMMS, Robotics, Machine Learning End User: Manufacturers, Utilities, Refineries, Service Providers |
| Companies Covered | Rockwell Automation Inc, Yokogawa Electric Corporation, Siemens AG, Bilfinger SE, Mitsubishi Electric Corporation, ABB Ltd, Honeywell International Inc, Emerson Electric Co, Schneider Electric SE, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Industrial Maintenance Services in Operational Improvement and Operational Maintenance Market Shifts & Advancements
Maintenance service delivery is pivoting from scheduled interventions toward continuous asset health monitoring, with data analytics capabilities becoming the primary competitive differentiator among regional providers.
Machine learning algorithms for failure prediction are converging with edge computing architectures deployed directly at refinery sites. Saudi Aramco and ADNOC affiliates are piloting these systems at select facilities. This convergence is compressing response times from days to hours and enabling prescriptive maintenance recommendations that optimize spare parts inventory.
South Africa's Department of Mineral Resources and Energy mandates specific equipment inspection intervals that shape service procurement patterns in mining and power sectors. These requirements force maintenance providers to document traceable compliance records. Mining operators in the platinum belt are responding by consolidating contracts with certified providers capable of integrated electrical and mechanical service delivery.
Long-term performance-based agreements are displacing conventional time-and-materials billing across Gulf refining clusters. Buyers now demand uptime guarantees and penalty clauses for unplanned shutdowns. This behavioral shift is most visible in Saudi Arabia's Jubail and Yanbu industrial cities, where petrochemical operators bundle maintenance with digital transformation roadmaps.
Middle East and Africa Industrial Maintenance Services in Operational Improvement and Operational Maintenance Market Segmentation
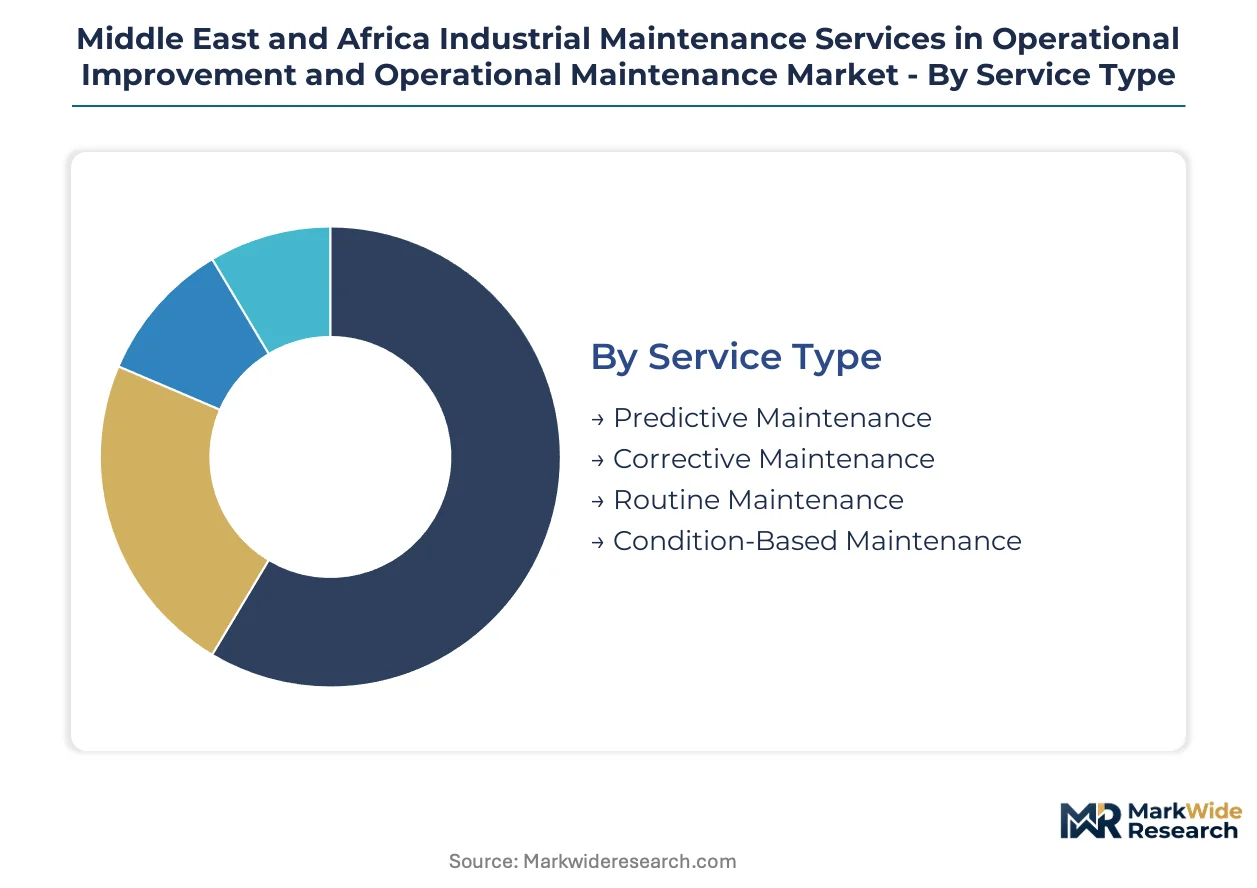
Industrial maintenance services across the Middle East and Africa fragment across four critical dimensions. Service type determines technical intensity and pricing architecture. Industry vertical dictates regulatory exposure and contract duration. Technology integration separates premium providers from commoditized competitors. End user concentration shapes geographic deployment patterns and partnership structures.
Service Type:
Predictive and condition-based maintenance sit as embedded systems requiring continuous data infrastructure, while corrective and routine maintenance function as standalone interventions triggered by failure or schedule.
- Predictive Maintenance:Machine learning algorithms process vibration, thermal, and oil analysis data to forecast equipment failure before occurrence. Saudi Aramco affiliates in Jubail and Yanbu industrial cities are expanding multi-year predictive contracts to minimize unplanned downtime in continuous-process refining.
- Condition-Based Maintenance:Real-time sensor networks trigger service interventions only when asset health indicators breach thresholds. African utilities with constrained capital budgets in Egypt and South Africa are adopting this model fastest to defer replacement expenditures.
- Corrective Maintenance:Reactive repair protocols deployed after equipment failure. Mining operators in South Africa's platinum belt rely on corrective services for non-critical auxiliary systems.
- Routine Maintenance:Scheduled inspections and component replacements based on manufacturer intervals. Mature oil and gas installations across the UAE retain volume dominance through time-based service contracts.
Routine maintenance leads volumes today; predictive maintenance is gaining share fastest.
Industry Vertical:
Cost tier stratification separates high-margin hydrocarbon processing from capital-constrained manufacturing, with power generation occupying a mid-tier position shaped by regulatory compliance burdens.
- Oil & Gas:Hydrocarbon processing facilities demand integrated operational improvement combining mechanical, electrical, and instrumentation services. SFDA safety mandates in Saudi Arabia and ADNOC technical standards in Abu Dhabi elevate procurement requirements for certified providers.
- Power Generation:Continuous-operation assets require thermal imaging and vibration monitoring to sustain grid reliability. Egypt's alignment with ISO 55000 asset management standards is creating compliance-driven demand for documented maintenance traceability.
- Aerospace:Precision component servicing and airworthiness certification requirements. MRO facilities in the UAE concentrate demand for specialized non-destructive testing and component overhaul services.
- Automotive Manufacturing:Production line uptime optimization through robotic system maintenance. Assembly plants in Morocco and South Africa require integrated mechanical and automation support.
Oil and gas commands premium pricing today; power generation is expanding most quickly.
Technology:
Application maturity separates established digital infrastructure from emerging deployment, with CMMS representing embedded enterprise systems and machine learning representing frontier integration.
- IoT Sensors:Edge-deployed vibration, temperature, and pressure monitors transmitting real-time asset health data. Refinery operators across the GCC are piloting sensor networks that compress diagnostic response from days to hours.
- CMMS:Computerized maintenance management systems scheduling work orders and tracking asset histories. Utilities in South Africa mandate CMMS documentation to satisfy Department of Mineral Resources and Energy inspection interval requirements.
- Robotics:Automated inspection drones and robotic process arms for hazardous environment access. Petrochemical clusters in Saudi Arabia's Jubail industrial city deploy robotics for flare stack and tank inspection.
- Machine Learning:Algorithmic failure prediction models trained on historical asset performance data. Digital twin convergence with real-time sensor feeds is emerging at select ADNOC-affiliated facilities.
CMMS leads installed base today; machine learning is climbing the fastest.
End User:
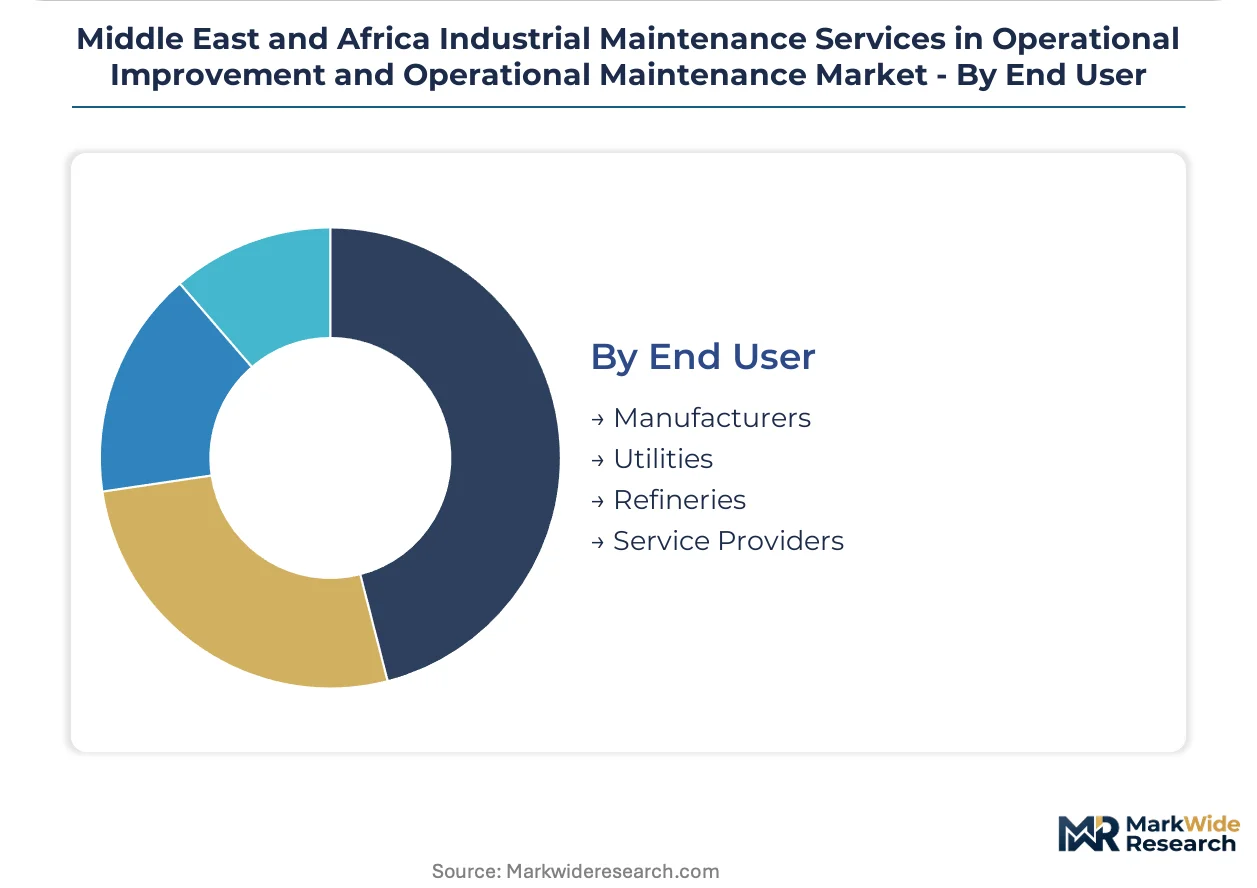
Customer type concentration shapes contract structure, with refineries demanding performance-based outcomes and utilities prioritizing compliance documentation.
- Refineries:Integrated petrochemical operators requiring uptime guarantees and penalty clauses for unplanned shutdowns. Long-term performance agreements are displacing time-and-materials billing across Abu Dhabi and Dubai refining clusters.
- Utilities:Power generation and distribution operators with regulatory compliance obligations. South African utilities consolidate contracts with providers capable of integrated electrical and mechanical service delivery.
- Manufacturers:Discrete and process production facilities optimizing equipment availability. Automotive and food processing plants in Morocco require flexible maintenance scheduling aligned with production cycles.
- Service Providers:Third-party maintenance contractors subcontracting specialized diagnostics. Independent providers across Egypt and Nigeria access certified capabilities through partnership arrangements.
Refineries dominate contract value today; utilities are expanding most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified vibration analysts and thermal imaging technicians concentrate in Gulf refining hubs, while South African mining regions retain mechanical maintenance depth despite skills migration toward Middle Eastern petrochemical clusters.
Saudi Arabia
Jubail and Yanbu industrial cities generate concentrated demand for predictive maintenance contracts tied to uptime guarantees. The Saudi Food and Drug Authority enforces occupational safety frameworks that elevate certification requirements for hydrocarbon processing facilities. Aramco-affiliated refiners are expanding multi-year performance agreements that bundle digital transformation roadmaps with mechanical service delivery.
United Arab Emirates
Abu Dhabi and Dubai refining clusters sustain integrated operational improvement demand from petrochemical operators. The Ministry of Health and Prevention mandates technical standards that shape procurement requirements for certified maintenance providers. ADNOC affiliates are piloting edge-computing sensor networks that compress diagnostic response times from days to hours at select facilities.
South Africa
The platinum belt mining operators and Eskom-linked power utilities drive condition-based maintenance adoption with constrained capital budgets. The Department of Mineral Resources and Energy mandates specific equipment inspection intervals that force documentation of traceable compliance records. Johannesburg and Rustenburg industrial corridors are consolidating contracts with providers capable of integrated electrical and mechanical service delivery.
Egypt
Suez Canal industrial zones and Cairo-Alexandria manufacturing corridors represent emerging demand for ISO 55000-aligned asset management services. The country's industrial regulatory bodies are adopting international asset management standards that create compliance-driven procurement for certified providers. Egyptian power generation operators are expanding condition-based maintenance subscriptions to defer replacement expenditures.
Middle East and Africa Industrial Maintenance Services in Operational Improvement and Operational Maintenance Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across contract tiers, creating a bifurcated structure where scale-driven integrators anchor premium long-term agreements while regional specialists capture compliance-driven maintenance mandates. The vendor base separates into three archetypes: full-service automation conglomerates with digital twin capabilities, electrical-mechanical integrators bundling robotics and electrification, and distributed control system specialists with deep protocol expertise. Dominant competitive moves include strategic partnerships with national oil companies and technology licensing arrangements that accelerate predictive maintenance platform deployment.
Within the automation conglomerate tier, Siemens AG and Rockwell Automation Inc occupy positions as archetypal scale-driven integrators securing multi-year performance agreements. Yokogawa Electric Corporation exemplifies the specialized protocol expertise archetype, anchoring competitive positioning through distributed control system maintenance depth. ABB Ltd sits between these vectors, representing the electrical-mechanical bundling strategy that targets utility and refining procurement consolidation.
| Leading Market Players |
|---|
| Rockwell Automation Inc |
| Yokogawa Electric Corporation |
| Siemens AG |
| Bilfinger SE |
| Mitsubishi Electric Corporation |
| ABB Ltd |
| Honeywell International Inc |
| Emerson Electric Co |
| Schneider Electric SE |
| Others |
Supply & Pricing Matrix
Certification-grade bifurcation between SFDA-compliant Gulf operators and uncertified African utilities manifests in parallel pricing architectures and divergent procurement networks. Premium predictive maintenance contracts in Saudi Arabia's Jubail industrial city command substantial uplifts over routine service tiers in Egypt's Suez Canal zones, while supply chain configurations track this split through European diagnostic equipment flows to Gulf hubs versus Asian component sourcing for North African power generators.
Pricing Analysis
Capacity additions in the UAE's refining corridor are reshaping price floors for integrated operational improvement services. Three-tier pricing structure across premium predictive, standard condition-based, and economy routine maintenance levels dominates contract architecture. Price differentiation rests on ISO 55000 certification status and vibration analyst credential tiers. Cost compression in routine maintenance is intensifying because mining operators in South Africa's platinum belt consolidate vendor lists. African utilities with constrained capital budgets exhibit highest price sensitivity; Aramco-affiliated refiners with uptime guarantee requirements show lowest.
Supply Chain Analysis
Regional distribution centers in Dubai's Jebel Ali Free Zone and Johannesburg's industrial corridors anchor hub-and-spoke patterns for spare parts fulfillment. Geographic supply concentration centers on Germany for precision vibration sensors, Japan for distributed control system modules, and South Korea for thermal imaging hardware. Raw material dependencies draw from rare earth elements for sensor magnetics, specialized alloys for refinery-grade robotics, and high-purity lubricants for predictive oil analysis. Single-source vulnerability from European diagnostic equipment manufacturers exposes operators to currency fluctuation risks. Distribution runs through certified service provider networks with localized technician pools.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion trajectories in this market hinge on predictive maintenance subscription scaling and SFDA certification premium capture, with cost-down drivers from edge-computing sensor deployment compressing field service delivery expenses.
For Market Incumbents: Lock in multi-year performance agreements with Saudi Aramco and ADNOC affiliates before ISO 55000 compliance mandates widen the certified provider pool. Defensive consolidation moves require backward integration into vibration sensor calibration capabilities and channel control through exclusive partnerships with European diagnostic equipment manufacturers. Emerging pure-play specialists with machine learning platform expertise represent the primary substitution threat. For New Entrants and Emerging Players: Capture condition-based maintenance subscription whitespace among Egyptian and South African utilities with limited capital budgets for upfront hardware investment. The most penetrable segment spans power generation operators in the Nile Delta and Eastern Cape seeking documented compliance traceability. A go-to-market angle anchored on ISO 55000 certification fast-track services differentiates against established incumbents. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap electrical-mechanical integrators bundling robotics and CMMS capabilities for African utility modernization waves. Long-term viability over a multi-year horizon rests on recurring revenue share from predictive maintenance platforms rather than project-based corrective services. Acquisition targets should demonstrate certified technician pipelines and existing national oil company subcontractor relationships. The signal to watch is ADNOC and Aramco affiliate pilot-to-scale conversion rates for edge-computing sensor networks.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 55000 Certification Fast-Track | Egypt's regulatory alignment creates compliance-driven procurement preference for certified providers. |
| Edge-Computing Sensor Deployment | ADNOC pilot programs compress diagnostic response times from days to hours at select facilities. |
| Condition-Based Maintenance Subscription | African utilities with capital constraints adopt deferred expenditure models fastest. |
| Backward Integration into Diagnostics | Import dependency on European equipment exposes operators to currency fluctuation risks. |
| Multi-Year Performance Agreements | Saudi Aramco affiliates bundle digital transformation roadmaps with mechanical service delivery. |
Research Methodology
Coverage spans the Middle East and Africa, with primary inputs from each regional cluster combining structured interviews with maintenance directors at Gulf refineries, plant engineers at South African mining operations, procurement leads at Egyptian power utilities, and aftermarket service heads at European OEMs. Secondary validation draws from customs and trade data for diagnostic equipment flows, SEC filings of listed automation conglomerates, IEA power sector reports, and ISO certification registry databases. Bottom-up service contract value aggregation triangulates against top-down market sizing from industrial asset installed base estimates.
Granularity-level modeling distinguishes predictive, condition-based, corrective, and routine maintenance service types; oil and gas, power generation, aerospace, and automotive manufacturing verticals; IoT sensor, CMMS, robotics, and machine learning technology tiers; and refinery, utility, manufacturer, and service provider end-user categories across the projection horizon. CAGRs derive from segment-level growth rate reconciliation against macro industrial production indices. Forecast inputs incorporate SFDA enforcement trajectory assumptions and IoT sensor network adoption curves at ADNOC-affiliated facilities.
Regulatory enforcement delays, currency volatility in Egyptian and South African markets, and skilled technician migration patterns toward Gulf hubs are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions around certification timeline compliance and national oil company digital transformation budget allocations. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Services
Condenser Cleaners Market
Construction Services
Work Order Management Market
Construction Services
Gutter Cleaning Services Market
Construction Services
Global Pipeline Maintenance Services Market
Construction Services
Industrial Maintenance Products Market
Construction Services
MENA Architectural Services Market
Construction Services
Die Casting Services Market
Construction Services
North America Testing and Commissioning Market
Construction Services
Testing, Inspection, and Certification for Construction Market
Construction Services
Construction TIC Market
Construction Services
Industrial Machinery Repair Services Market
Construction Services
Composite Autoclave Repair Market
Construction Services
North America Repair and Rehabilitation Market
Construction Services
Maintenance Repair and Operations (MRO) Market
Construction Services
Dust Suppression Control Market
Construction Services
Heavy Equipment Training Simulator Market