
 North America Repair and Rehabilitation Market | 2026-2036
North America Repair and Rehabilitation Market Size, Share, and Industry Trends Forecast 2026-2036
North America Repair and Rehabilitation Market Analytics
Canadian specialty chemical producers is pivoting toward carbon-neutral concrete admixtures for infrastructure renewal. SIKA AG leverages its North American manufacturing footprint to supply epoxy injection systems for crack repair across major metropolitan markets. MAPEI Corporation anchors its position through backward integration into cementitious repair mortars, while Simpson Strong-Tie Company, Inc. differentiates via structural connector systems for seismic retrofit of existing buildings.
Repair and rehabilitation encompasses the restoration of structural integrity, functional performance, and service life extension of deteriorated civil and built assets through engineered material intervention and structural modification. Techniques include surface-applied protective coatings with specified chloride permeability thresholds, cathodic protection systems for reinforced concrete, and externally bonded fiber-reinforced polymer laminates that restore flexural capacity to degraded structural elements. Concrete rehabilitation commands the largest share of service-type revenue, reflecting the vast stock of aging highway bridges and parking structures across the United States and Canada, while waterproofing applications in tunnel systems represent the fastest-expanding sub-segment driven by saltwater intrusion risks in coastal infrastructure. Among materials, fiber-reinforced polymers are displacing steel in corrosion-prone environments, though epoxy injection resins retain the highest margin profile due to specification-driven procurement in transportation agency contracts.
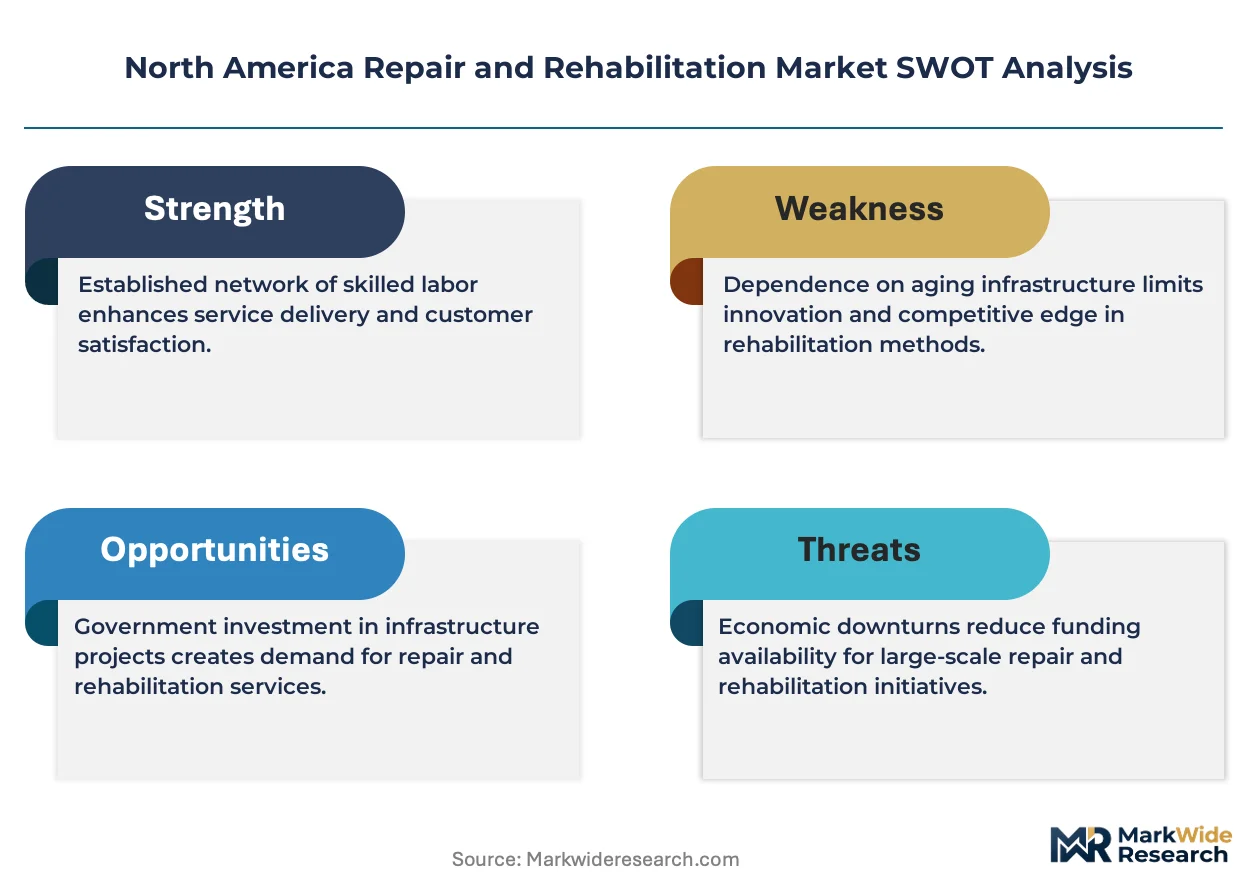
The Federal Highway Administration mandates compliance with National Bridge Inspection Standards, while state departments of transportation enforce AASHTO load-rating protocols that trigger rehabilitation expenditures; OSHA construction standards further govern worker exposure during confined-space repair operations in tunnels and culverts. EPA stormwater regulations under the Clean Water Act influence pavement restoration specifications, particularly permeable surface requirements in municipal right-of-way projects. Stakeholders must monitor evolving federal infrastructure funding allocations and state-level carbon-emission thresholds for construction materials, as these will determine competitive positioning in public-sector bidding.
Market Dynamics
Fiber-reinforced polymer composites are compressing project timelines for bridge deck rehabilitation while the Federal Highway Administration tightens National Bridge Inspection Standards compliance windows.
Growth Catalysts
- Transportation agency mandates:State departments of transportation enforce AASHTO load-rating protocols that trigger structural intervention expenditures across aging highway bridge inventories.
- Petrochemical infrastructure aging:The U.S. Gulf Coast corridor concentrates demand where refinery and pipeline assets intersect hurricane exposure and salt-laden atmospheric corrosion.
- Cathodic protection advancement:Embedded anode systems for reinforced concrete extend service life in parking structures and marine substructures without full reconstruction.
Market Restraints
- Epoxy resin price volatility:Petrochemical feedstock fluctuations compress margins for crack injection system manufacturers serving transportation agency contracts.
- Specialized applicator concentration:Certified FRP installation contractors cluster in metropolitan markets, creating bottleneck capacity in rural bridge rehabilitation programs.
- Steel reinforcement substitution limits:Structural codes in seismic zones restrict FRP use in ductility-critical applications, preserving conventional rebar specifications.
Strategic Opportunities
- Canadian carbon-neutral specifications:Provincial procurement guidelines in Ontario and British Columbia incentivize low-embodied-carbon concrete admixtures for infrastructure renewal tenders.
- Tunnel waterproofing expansion:Saltwater intrusion risks in coastal Massachusetts and Florida infrastructure accelerate membrane system specifications for subaqueous transit assets.
- Smart monitoring integration:Convergence of fiber-optic strain sensing with carbon-fiber laminates enables real-time structural health verification in critical bridge elements.
Industry Challenges
- Confined-space certification requirements:OSHA construction standards governing tunnel and culvert repair operations extend workforce training timelines and limit available labor pools.
- Legacy concrete assessment complexity:Variable aggregate chemistry and chloride contamination profiles in pre-1970s structures complicate repair mortar specification and warranty underwriting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Repair and Rehabilitation Market |
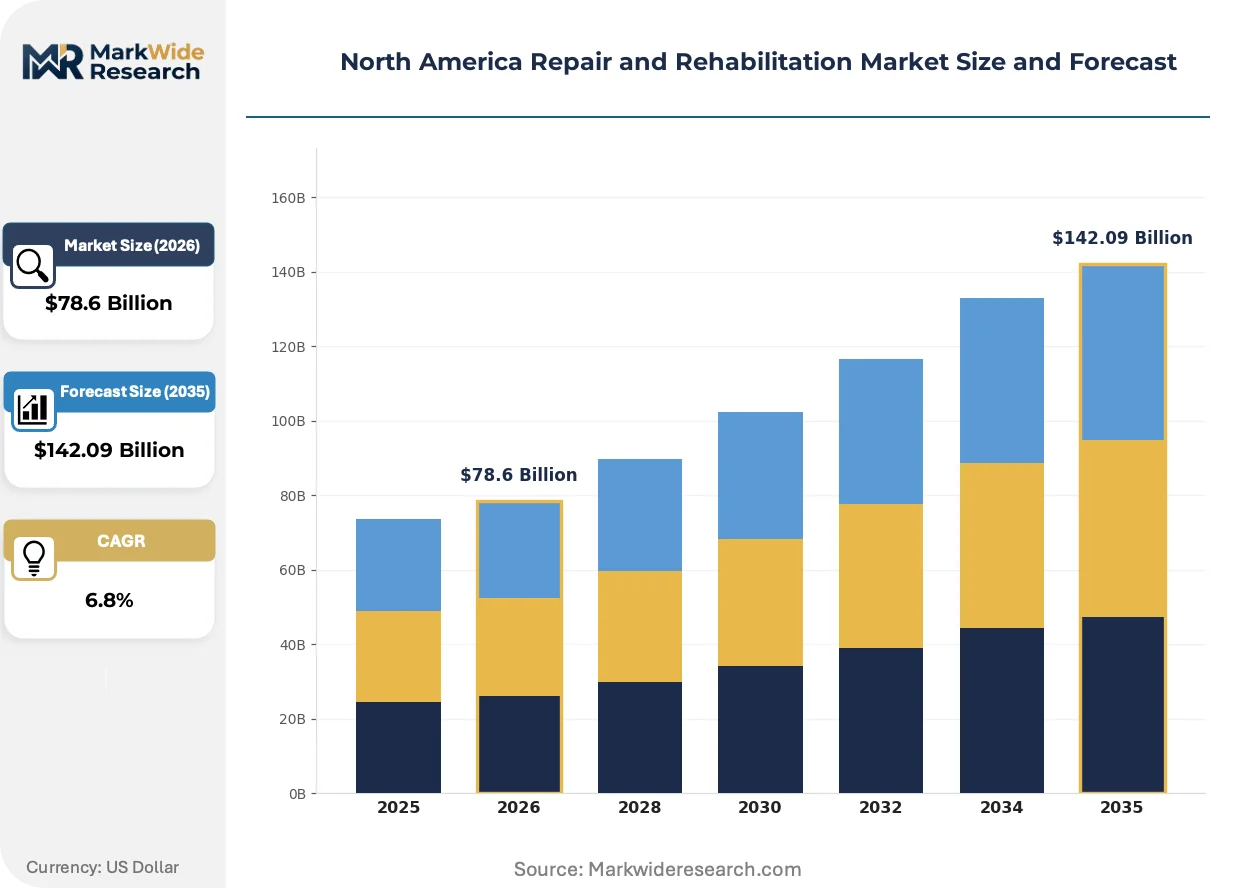
| Market Size in 2026 | $78.6 Billion |
| Market Size in 2035 | $142.09 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Structural Repair, Waterproofing, Concrete Rehabilitation, Pavement Restoration End User: Aerospace, Defense, Construction, Transportation Material: Steel, Fiber-Reinforced Polymers, Concrete, Epoxy Application: Bridges, Roads, Buildings, Tunnels |
| Companies Covered | BASF SE, SIKA AG, MAPEI Corporation, Simpson Strong-Tie Company, Inc., Dow, Fosroc Inc, W. R. Meadows, Inc., ARDEX AMERICAS, The Euclid Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Repair and Rehabilitation Market Evolving Landscape
Material science advances are compressing installation windows while digital inspection protocols reshape quality assurance workflows across transportation agency programs.
Ultra-high-performance concrete (UHPC) overlays are electrifying bridge deck rehabilitation by enabling thin-section repairs that restore load capacity without superstructure modification. State DOTs in Texas and Michigan specify UHPC for joint elimination in high-traffic corridors. The technology is electrifying competitive positioning among material suppliers capable of batch-plant mobilization within 24-hour windows.
The EPA stormwater regulations under the Clean Water Act now mandate permeable surface requirements in municipal right-of-way pavement restoration projects. Contractors must document runoff coefficients and infiltration rates to secure federal infrastructure funding allocations. Transportation departments in coastal California and Pacific Northwest jurisdictions have responded by embedding permeable interlocking concrete pavement specifications into standard plans.
Asset owners now bundle structural monitoring subscriptions with initial repair contracts, unbundling the traditional lump-sum construction model. Engineering firms and technology providers are forming joint ventures to offer multi-year performance guarantees backed by sensor networks. This arrangement concentrates in California seismic retrofit programs where post-earthquake serviceability verification carries regulatory weight.
North America Repair and Rehabilitation Market Segmentation
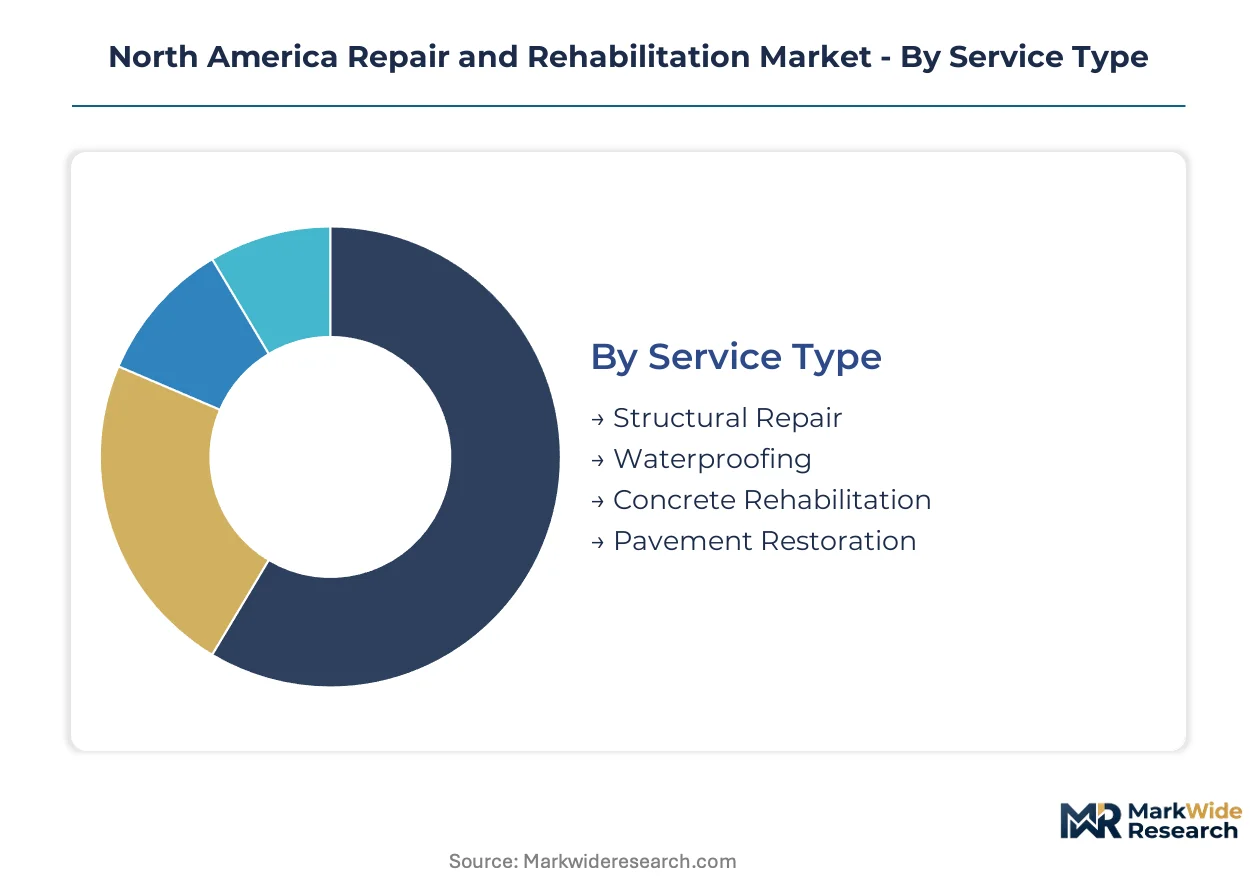
Segmentation reveals how capital intensity, regulatory exposure, and material specifications fragment procurement patterns across North American infrastructure agencies. Each dimension carries distinct margin profiles and certification barriers that reshape vendor positioning.
Service Type:
Capital intensity concentrates in structural interventions requiring engineered load-path modifications, while surface treatments demand lower fixed asset deployment.
- Structural Repair:Externally bonded fiber-reinforced polymer laminates restore flexural capacity to degraded girders and columns. Demand clusters in California seismic retrofit programs and Gulf Coast hurricane recovery where AASHTO load-rating protocols mandate intervention.
- Concrete Rehabilitation:Cathodic protection systems and chloride extraction extend service life of pre-1970s bridge decks without full reconstruction. State DOTs in Michigan and Pennsylvania specify these treatments for aging highway inventories facing National Bridge Inspection Standards compliance windows.
- Waterproofing:Membrane systems for tunnel and substructure applications address saltwater intrusion in coastal Massachusetts and Florida infrastructure.
- Pavement Restoration:Ultra-high-performance concrete overlays and permeable surface installations respond to EPA stormwater regulations under the Clean Water Act.
Most installed capacity flows through Concrete Rehabilitation. Expansion is steepest in Waterproofing.
End User:
Procurement sophistication varies sharply—transportation agencies enforce specification-driven bidding while defense contracts prioritize security-cleared labor pools.
- Transportation:Federal Highway Administration mandates govern bridge deck and pavement interventions across state DOT portfolios. Contracts bundle multi-year performance guarantees with sensor-based structural health monitoring.
- Construction:Commercial building owners drive seismic retrofit demand in urban cores, particularly for parking structures and high-rise envelopes facing corrosion-induced degradation.
- Aerospace:Runway and airfield pavement rehabilitation follows FAA specifications for load-bearing capacity and surface friction coefficients.
- Defense:Military infrastructure repair requires contractor security clearances and compliance with DOD facility standards for blast-resistant structural modifications.
Transportation commands the largest contract volume. Aerospace shows the steepest expansion trajectory as airfield modernization accelerates.
Material:
Specification-grade procurement in public infrastructure elevates margin capture for engineered systems over commodity inputs.
- Epoxy:Injection resins for crack repair carry the highest margin profile due to transportation agency certification requirements and limited qualified applicator pools. Petrochemical feedstock volatility compresses manufacturer margins during contract execution windows.
- Fiber-Reinforced Polymers:Carbon and glass fiber composites displace steel in corrosion-prone marine and coastal environments. Installation requires certified contractor networks concentrated in metropolitan markets.
- Concrete:Cementitious repair mortars and ultra-high-performance concrete formulations dominate volume but face price pressure from backward-integrated suppliers.
- Steel:Conventional rebar and plate systems retain specification in seismic zones where ductility requirements restrict polymer substitution.
Concrete accounts for the greatest material tonnage. Fiber-Reinforced Polymers are gaining share fastest as coastal agencies accelerate corrosion-resistant specifications.
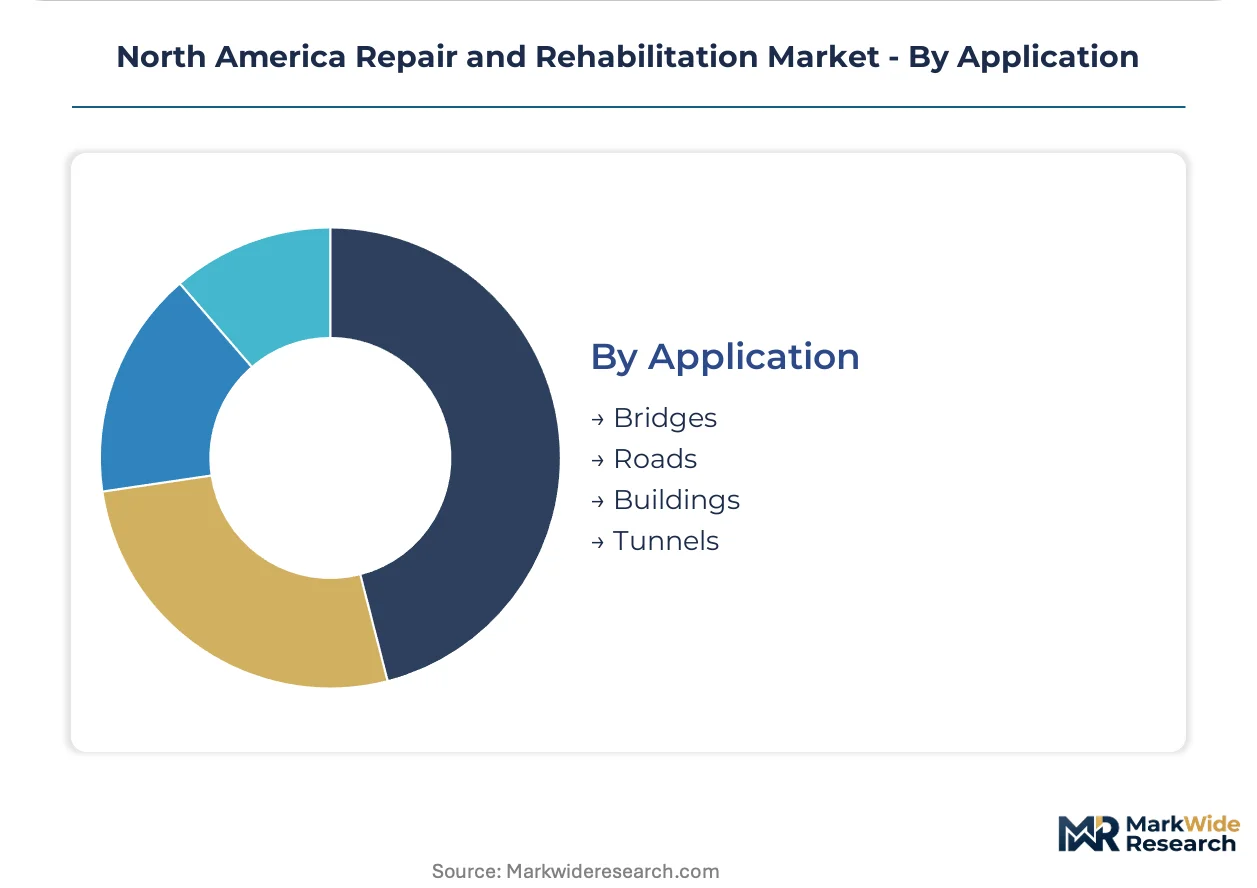
Application:
Asset ownership structures determine procurement rhythm—public agency bridge programs operate on federal funding cycles while private building owners respond to insurance and occupancy triggers.
- Bridges:Highway agency rehabilitation programs concentrate in the U.S. Gulf Coast corridor where aging inventory intersects hurricane exposure. Federal infrastructure funding allocations determine annual bid volumes.
- Buildings:Seismic retrofit of existing structures drives demand in California and Pacific Northwest urban cores. Structural connector systems for frame reinforcement face OSHA construction standards governing confined-space operations.
- Tunnels:Subaqueous transit assets in Boston and Miami accelerate membrane waterproofing specifications due to saltwater intrusion risks.
- Roads:Municipal pavement restoration incorporates permeable surface requirements tied to EPA stormwater compliance and federal funding eligibility.
Bridges absorb the largest share of engineering hours. Tunnels show the steepest specification intensity increase as coastal agencies prioritize substructure protection.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are minimal across North American jurisdictions, yet cost-of-compliance gaps between U.S. federal mandates and Canadian provincial carbon thresholds are redirecting specialty admixture production toward Ontario and British Columbia manufacturing zones.
United States
The Federal Highway Administration mandates National Bridge Inspection Standards compliance across state DOT inventories, accelerating rehabilitation expenditures in hurricane-exposed Gulf Coast corridors. OSHA construction standards govern confined-space repair operations in tunnels and culverts, extending workforce certification timelines. Texas and Michigan DOTs specify ultra-high-performance concrete overlays for high-traffic bridge deck rehabilitation.
Canada
Provincial procurement guidelines in Ontario and British Columbia incentivize low-embodied-carbon concrete admixtures for infrastructure renewal tenders. Health Canada and PMRA regulate chemical exposure limits for epoxy-based repair systems in enclosed construction environments. Specialty chemical producers concentrate manufacturing capacity in the Greater Toronto Area to serve cross-border transportation agency contracts.
Mexico
Pemex refinery infrastructure aging intersects with coastal atmospheric corrosion in Veracruz and Tampico industrial zones, generating demand for cathodic protection systems. Mexican federal transportation programs follow evolving alignment with AASHTO load-rating protocols for cross-border highway bridge maintenance. Monterrey-based construction material distributors serve northern industrial corridor rehabilitation projects.
North America Repair and Rehabilitation Market Competitive Landscape
United States producers anchor the specification-grade tier; Canadian specialists hold carbon-neutral admixture positioning. Market structure fragments across three tiers: multinational chemical conglomerates with captive resin production, regional mortar blenders with backward-integrated cement sourcing, and certified applicator networks controlling installation capacity. Strategic archetypes include specification-driven epoxy formulators, FRP laminate fabricators with certified contractor partnerships, and UHPC batch-plant mobilization specialists. Dominant competitive moves center on M&A for regional admixture brands and strategic partnerships between material suppliers and sensor-network technology providers.
Within the multinational chemical tier, BASF SE and SIKA AG exemplify scale-driven positioning through North American manufacturing footprint expansion. MAPEI Corporation anchors the cementitious repair mortar segment with integrated production control. Among structural connector specialists, Simpson Strong-Tie Company, Inc. occupies the seismic retrofit application space. These three entities represent distinct competitive archetypes: petrochemical-integrated resin supply, backward-integrated mortar manufacturing, and specification-grade structural hardware engineering.
| Leading Market Players |
|---|
| BASF SE |
| SIKA AG |
| MAPEI Corporation |
| Simpson Strong-Tie Company, Inc. |
| Dow |
| Fosroc Inc |
| W. R. Meadows, Inc. |
| ARDEX AMERICAS |
| The Euclid Chemical Company |
| Others |
Value Network & Pricing Analysis
Certified FRP installation contractors concentrated in Houston and Los Angeles metropolitan markets drive labor-cost differentials that widen pricing-tier spreads between Gulf Coast petrochemical rehabilitation projects and rural bridge programs across the Midwest.
Pricing Analysis
Distributor margins on epoxy injection resins compress project-based pricing for transportation agency contracts while specification-grade certification requirements sustain premium capture for qualified applicators. Three-tier pricing structure across premium certified-installer, standard DOT-approved, and economy unbundled-material levels separates warranty-backed performance guarantees from commodity mortar supply. Cost compression in standard-grade concrete admixtures intensifies because backward-integrated suppliers anchor volume pricing in Ontario manufacturing zones. State DOT procurement officers show highest price sensitivity on routine maintenance contracts; petrochemical facility operators demonstrate lowest sensitivity for hurricane-exposed critical infrastructure.
Supply Chain Analysis
Single-source vulnerability sits with carbon fiber precursor supply concentrated in Japan and the United States, creating exposure for North American FRP laminate fabricators. Epoxy resin formulation draws from petrochemical feedstock networks anchored in Texas and Louisiana, with specialty hardener chemistry sourcing from Germany and Switzerland. Tariff exposure on imported glass fiber roving from China elevates input cost volatility for marine substructure applications. Distribution runs through certified applicator networks that control installation capacity in metropolitan markets, with regional mortar blenders serving rural transportation agency programs through direct-to-DOT contracting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where Canadian provincial carbon-emission thresholds for construction materials create cost-advantaged positioning for Ontario-based admixture producers versus U.S. federal procurement.
For Market Incumbents: Anchor specification-grade positioning through captive supply of epoxy resin precursors and certified contractor network expansion into hurricane-exposed Gulf Coast corridors. Defend against emerging UHPC batch-plant mobilization specialists by securing 24-hour deployment contracts with Texas and Michigan DOTs. Prioritize backward integration into cementitious raw material sourcing to offset price pressure from regional mortar blenders. For New Entrants and Emerging Players: Launch via direct-to-facility contracting models targeting Pemex refinery infrastructure in Veracruz and Tampico industrial zones where cathodic protection demand outpaces qualified supplier presence. Target tunnel waterproofing specifications in coastal Massachusetts and Florida as the most penetrable sub-segment, where saltwater intrusion risks accelerate membrane system procurement faster than incumbent capacity expansion. Pursue joint-venture structures with fiber-optic sensor technology providers to bundle structural health monitoring subscriptions with initial repair contracts. For Investors and Strategic Acquirers: Specialty chemical conglomerates seeking North American infrastructure exposure represent the most active acquirer category in this space. Long-term viability hinges on positioning for federal infrastructure funding allocation cycles and state-level carbon procurement mandates. Acquisition target archetypes include regional admixture brands with Ontario or British Columbia manufacturing footprints and certified FRP applicator networks in undersupplied metropolitan markets. Watch for OSHA confined-space certification requirement expansions as the inflection indicator that will consolidate installation capacity toward scaled training-capable platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cementitious Raw Materials | MAPEI Corporation's captive supply of repair mortar precursors insulates margin pressure from commodity cement volatility. |
| Certified Contractor Network Expansion | SIKA AG's qualified applicator partnerships in Houston and Los Angeles control bottleneck capacity for Gulf Coast petrochemical rehabilitation. |
| UHPC Batch-Plant Mobilization Capability | Texas DOT specifications for 24-hour deployment windows favor suppliers with rapid-response concrete production infrastructure. |
| Sensor-Network Technology Partnership | California seismic retrofit programs bundle fiber-optic strain monitoring with carbon-fiber laminate installation for post-earthquake verification. |
| Carbon-Neutral Admixture Production | Ontario and British Columbia provincial procurement guidelines incentivize low-embodied-carbon manufacturing for cross-border DOT contracts. |
Research Methodology
Coverage spans the United States, Canada, and Mexico, with primary inputs from each jurisdiction combined with secondary validation across regulatory filings and trade data. Primary interviews engaged state DOT procurement officers, certified FRP installation contractors, petrochemical facility maintenance directors, specialty chemical plant managers, and tunnel engineering consultants. Secondary sources incorporated Federal Highway Administration bridge inventory databases, EPA stormwater compliance records, AASHTO specification documents, SEC 10-K filings from listed material suppliers, and Canadian provincial procurement guideline releases. Bottom-up project pipeline assessment triangulated against top-down infrastructure spending authorization analysis.
Rate-of-change decomposition separated volume growth from price-mix effects across the projection horizon. Segmentation dimensions modeled include service type, end-user category, material formulation, and application asset class, with additional granularity on regional regulatory cluster and certification tier. CAGRs derived from historical expenditure patterns projected through infrastructure funding authorization trajectories and asset-age distribution analysis. Industry-specific forecast inputs encompass National Bridge Inspection Standards compliance window timing and hurricane damage recurrence modeling for Gulf Coast exposure.
Forecast precision tightens around the base case; tail outcomes carry wider variance under federal infrastructure funding reallocation or accelerated state carbon-emission threshold adoption. Forecasts reflect assumptions on labor certification timeline stability, petrochemical feedstock price banding, and transportation agency specification persistence. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Services
Forklift Repair and Maintenance Service Market
Construction Services
Global Industrial Services Market
Construction Services
Work Order Management Market
Construction Services
Facade Cleaning and Maintenance Service Market
Construction Services
Remote Construction Market
Construction Services
Industrial Machinery Repair Services Market
Construction Services
Train Contractor Market
Construction Services
Construction TIC Market
Construction Services
MENA Architectural Services Market
Construction Services
Construction Project Management Services Market
Construction Services
Maintenance Repair and Operations (MRO) Market
Construction Services
North America Fire Sprinkler Systems Market
Construction Services
Grease Trap Service Market
Construction Services
Testing, Inspection, and Certification for Construction Market
Construction Services
3D Concrete Printing Services Market
Construction Services
Industrial Maintenance Products Market