
 North America Testing and Commissioning Market | 2026-2036
North America Testing and Commissioning Market Size, Share, and Industry Trends Forecast 2026-2036
North America Testing and Commissioning Market Intelligence
The United States is reconfiguring its testing infrastructure around grid modernization and decarbonization projects. Bureau Veritas leverages its coastal laboratory network to dominate marine and offshore energy commissioning. SGS sustains broad coverage across industrial end users with specialized emissions verification protocols. Intertek anchors its position through electrical safety testing aligned with evolving utility standards.
Testing and commissioning encompasses the systematic verification, validation, and documentation that buildings, industrial systems, and infrastructure perform according to design specifications and regulatory requirements, employing calibrated instrumentation, functional performance protocols, and witness testing procedures to confirm operational readiness before handover. Commissioning services command premium pricing in healthcare and energy verticals where system failure carries catastrophic liability. Mechanical testing within industrial end users represents the fastest-expanding segment as aging manufacturing assets require retrofit validation. Software and systems testing is maturing rapidly as building automation platforms integrate cybersecurity protocols into standard commissioning scope.
The EPA enforces stationary source emissions testing under Clean Air Act mandates, while OSHA mandates workplace safety verification for industrial commissioning handovers, and the Department of Energy imposes efficiency standards that require independent measurement and verification protocols. These frameworks compel facility owners to budget for third-party testing rather than rely on self-certification. Stakeholders must monitor how state-level building electrification mandates expand commissioning scope beyond traditional HVAC into battery storage and EV infrastructure integration.
Market Dynamics
Grid interconnection backlogs across the United States and Canada are forcing testing providers to expand high-voltage laboratory capacity and compress project timelines, while EPA emissions verification mandates are embedding third-party commissioning into standard capital expenditure planning.
Growth Catalysts
- Clean Air Act enforcement:EPA stationary source testing mandates compel industrial facilities to retain certified third-party verifiers for emissions compliance, creating recurring revenue streams for testing providers.
- Data center power density:Hyperscale facilities in Texas and Virginia require continuous commissioning of uninterruptible power systems and thermal management infrastructure.
- Offshore wind lease rounds:Atlantic Coast projects necessitate marine electrical testing and subsea cable commissioning, driving specialized vessel-based service demand.
Market Restraints
- Calibrated instrumentation shortages:Lead times for precision electrical measurement equipment extend to 26 weeks, constraining provider capacity expansion.
- Quebec laboratory concentration:High-voltage testing infrastructure clusters in a single province, creating geographic vulnerability for Canadian grid interconnection work.
- NFPA 70E arc flash compliance costs:Personal protective equipment and qualified electrical worker certification requirements inflate field deployment expenses by 18-22 percent.
Strategic Opportunities
- Mexico nearshoring corridors:Automotive and electronics manufacturing investments in Nuevo León and Baja California generate demand for industrial system commissioning.
- Building electrification mandates:California and New York state-level decarbonization policies expand commissioning scope into heat pump retrofits and EV charging infrastructure.
- Digital twin convergence:Integration of BIM models with IoT sensor networks enables predictive commissioning and remote performance verification.
Industry Challenges
- NETA-certified technician scarcity:The InterNational Electrical Testing Association reports 340 unfilled field positions across member firms, constraining project throughput.
- Multi-standard harmonization:Divergent IEEE, CSA, and UL testing protocols complicate cross-border project execution and documentation requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Testing and Commissioning Market |
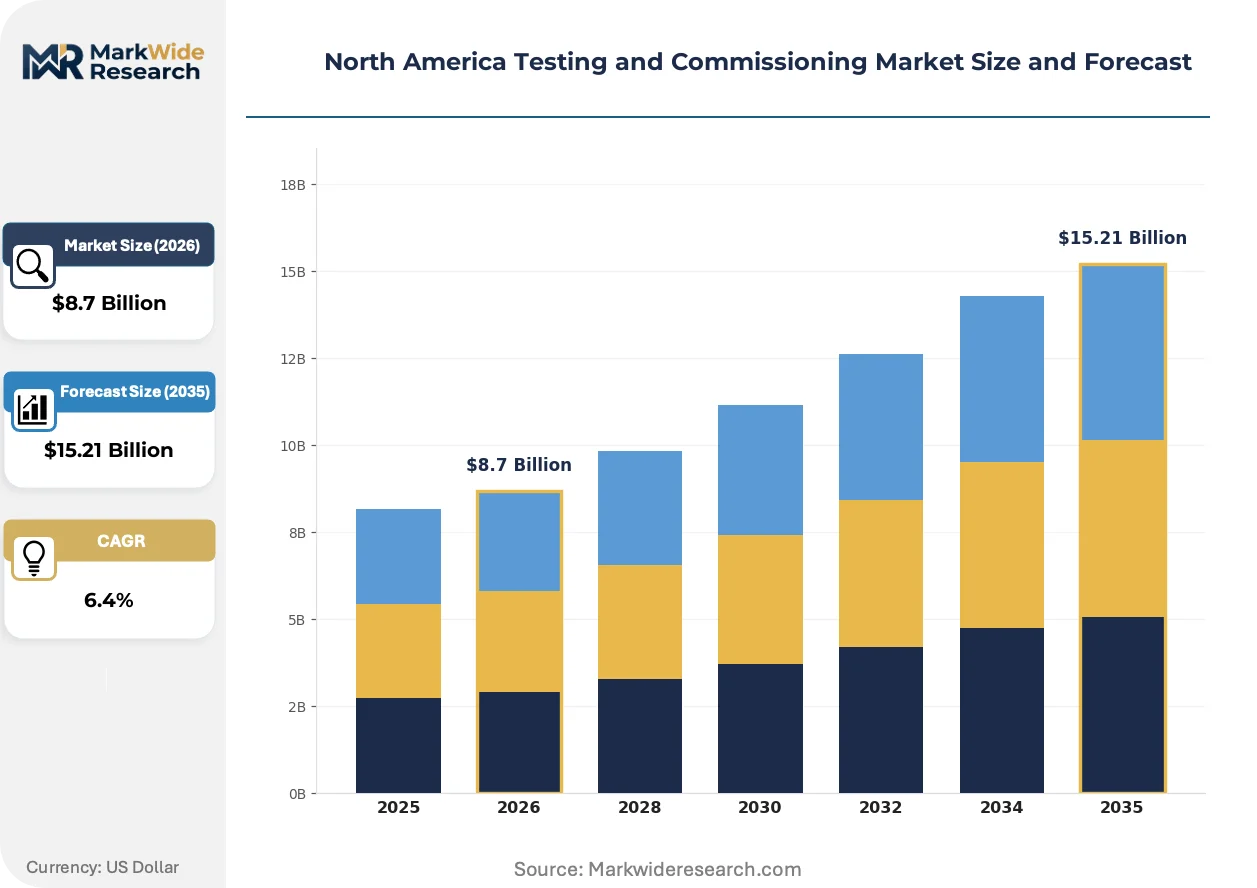
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Commissioning, Testing, Inspection, Consulting End User: Construction, Industrial, Aerospace, Retail Technology: Electrical, Mechanical, Software, Systems Industry Vertical: Healthcare, Manufacturing, Energy, Telecommunications |
| Companies Covered | Bureau Veritas, Applus, SGS, TUV Rheinland, ALS Global, Intertek, DNV GL, TUV SUD, Eurofins, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Testing and Commissioning Market Strategic Shifts & Innovations
Commissioning workflows are converging with cybersecurity validation and predictive analytics, transforming a documentation-heavy handover process into a continuous operational intelligence layer.
Digital commissioning platforms are digitizing field data capture through tablet-based test protocols and automated witness testing documentation. Engineering firms serving utility-scale solar projects in Arizona and Nevada deploy these tools to accelerate interconnection schedules. The technology is digitizing paper-based verification chains into auditable digital records that satisfy both FERC reliability standards and investor due diligence requirements.
The EPA's enhanced stack testing protocols under 40 CFR Part 60 are mandating continuous emissions monitoring systems verification for modified industrial sources. Cement and petrochemical facilities in the Gulf Coast region now budget for quarterly third-party audits rather than biennial compliance demonstrations. This regulatory compression is elevating demand for mobile analytical laboratories capable of on-site pollutant measurement.
Asset owners are unbundling commissioning from engineering-procurement-construction contracts and contracting directly with specialized verification firms. Data center developers in Northern Virginia and Dallas-Fort Worth now procure commissioning services through separate RFP processes to ensure independence from construction contractors. This procurement fragmentation is most pronounced in healthcare verticals, where Joint Commission accreditation requirements demand demonstrable third-party objectivity in critical system validation.
North America Testing and Commissioning Market Segmentation
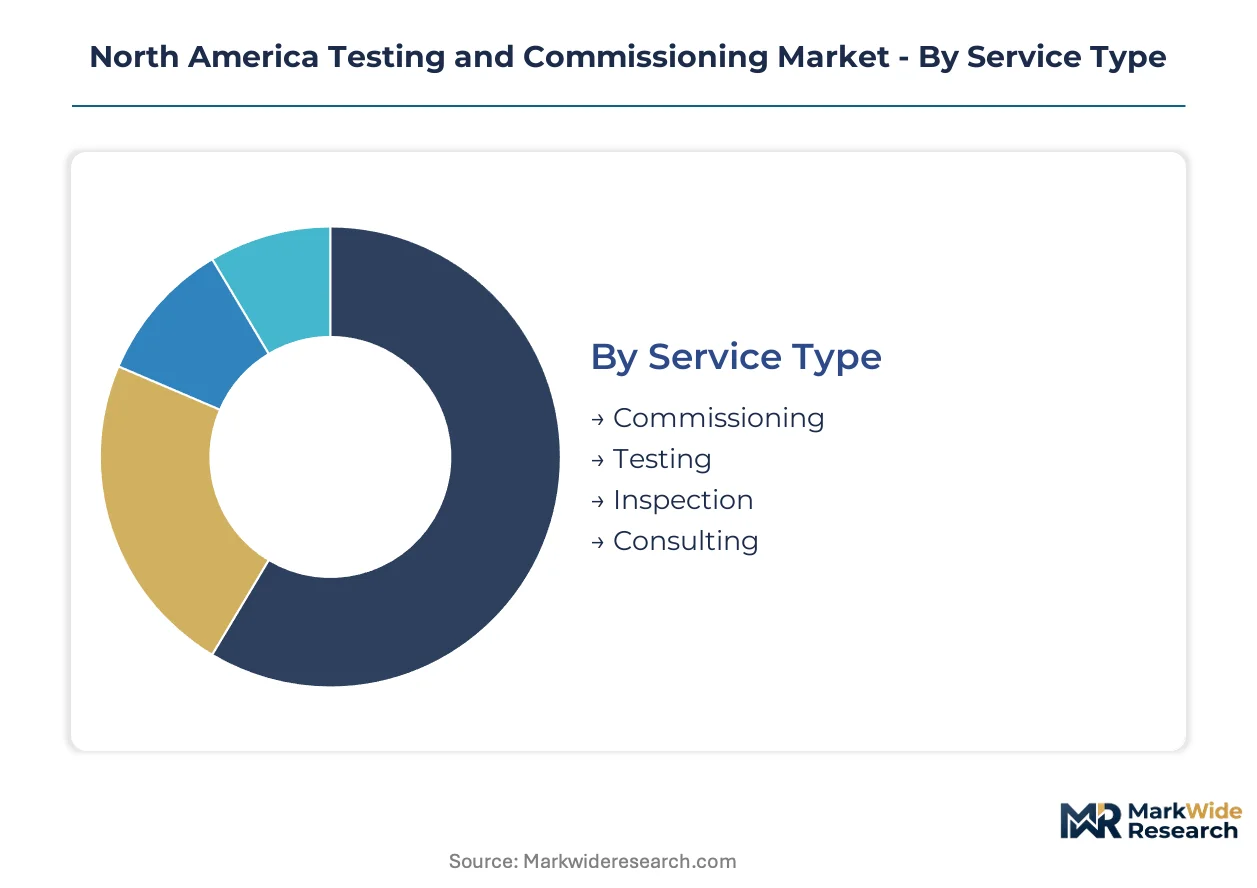
Testing and commissioning providers configure service portfolios around distinct technical capabilities, regulatory exposure profiles, and capital intensity requirements. Segment boundaries increasingly blur as integrated verification packages disperse standalone testing engagements.
Service Type:
Cost tier stratification separates episodic compliance spending from multi-year operational support contracts with embedded performance guarantees.
- Commissioning:Systematic verification protocols confirm that buildings, industrial assets, and infrastructure perform to design specifications before operational handover. Data center developers in Northern Virginia and Dallas-Fort Worth now unbundle commissioning from EPC contracts to preserve third-party independence for investor due diligence.
- Testing:Calibrated instrumentation and functional performance procedures validate electrical, mechanical, and emissions systems against IEEE, CSA, and UL protocols. EPA stationary source mandates under the Clean Air Act compress testing cycles from biennial to quarterly intervals for Gulf Coast cement and petrochemical facilities.
- Inspection:Visual and diagnostic assessments identify pre-commissioning deficiencies and ongoing maintenance requirements.
- Consulting:Advisory services optimize testing scope, schedule compression, and regulatory submission strategies.
Commissioning commands the established base. The steepest expansion runs through testing as regulatory compression accelerates compliance cycles.
End User:
Application concentration varies by capital expenditure volatility, regulatory stringency, and system failure liability exposure.
- Construction:New build and major renovation projects require phased commissioning from pre-functional through final integrated systems testing. Utility-scale renewable energy construction across Texas and California drives grid interconnection testing demand as backlogs extend project timelines.
- Industrial:Aging manufacturing assets in the Midwest and Southeast require retrofit validation and emissions verification. EPA 40 CFR Part 60 stack testing protocols embed third-party commissioning into standard capital expenditure planning for modified sources.
- Aerospace:Flight hardware and ground support systems demand specialized environmental and functional testing.
- Retail:Distributed facility portfolios require standardized commissioning protocols for HVAC and refrigeration compliance.
Industrial end users anchor revenue stability. Construction applications deliver the most volatile but highest-margin project flow.
Technology:
Maturity gradients separate established electrical and mechanical disciplines from rapidly evolving software and systems integration requirements.
- Electrical:High-voltage laboratory testing, arc flash hazard analysis, and protective relay verification address grid interconnection and safety compliance. NETA-certified technician scarcity constrains field deployment capacity across member firms.
- Mechanical:Thermal management, pressure vessel, and rotating equipment testing validates industrial process reliability. Hyperscale data center power density requirements in Texas and Virginia drive continuous commissioning of uninterruptible power systems.
- Software:Building automation platform validation and cybersecurity protocol integration expand traditional commissioning scope.
- Systems:Integrated electrical-mechanical-software verification confirms end-to-end operational readiness.
Electrical technology dominates current billings. Software testing exhibits the most rapid capability investment requirements as building automation converges with cybersecurity validation.
Industry Vertical:
Customer type differentiation reflects catastrophic liability exposure, regulatory oversight intensity, and operational continuity requirements.
- Healthcare:Joint Commission accreditation mandates demonstrable third-party objectivity in critical system validation for patient life safety. Commissioning services command premium pricing where system failure carries catastrophic liability.
- Manufacturing:Production line validation, emissions compliance, and equipment retrofit testing address operational efficiency and regulatory adherence.
- Energy:Offshore wind lease rounds along the Atlantic Coast necessitate marine electrical testing and subsea cable commissioning, driving specialized vessel-based service demand.
- Telecommunications:Network infrastructure and data center commissioning supports digital service continuity.
Healthcare verticals sustain premium pricing. Energy applications generate the most specialized capability expansion requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes commissioning services through hyperscale data center and utility-scale renewable deployments, while Canada concentrates high-voltage laboratory capacity in Quebec, and Mexico channels industrial demand through nearshoring manufacturing corridors. This tripartite consumption pattern distinguishes North American demand from European or Asian markets where building retrofits and export manufacturing dominate.
United States
Data center construction in Northern Virginia and Dallas-Fort Worth drives continuous commissioning contracts for uninterruptible power systems. EPA 40 CFR Part 60 mandates quarterly emissions verification for modified industrial sources in the Gulf Coast petrochemical corridor. Texas and California utility-scale solar and wind projects require extensive grid interconnection testing as backlogs extend project timelines.
Canada
High-voltage laboratory infrastructure clusters in Quebec, creating geographic concentration for grid interconnection work serving Atlantic offshore wind lease rounds. Canadian Environmental Protection Act enforcement elevates third-party emissions verification requirements for Alberta oil sands and Ontario manufacturing facilities. Toronto and Vancouver anchor demand for building commissioning as provincial electrification mandates expand into heat pump retrofits.
Mexico
Automotive and electronics manufacturing investments in Nuevo León and Baja California generate industrial system commissioning demand for production line validation. Mexican environmental regulations under SEMARNAT embed emissions testing into operational permits for maquiladora facilities. Mexico City Metro and Guadalajara concentrate commercial building commissioning as energy efficiency codes tighten.
North America Testing and Commissioning Market Key Industry Players
Capability concentration sits with specialized marine and high-voltage testing laboratories; scale advantage sits with diversified multi-service conglomerates. The market exhibits tiered competition where global verification firms with coastal laboratory networks command premium positioning against regional electrical testing specialists. Three archetypes dominate: diversified conglomerates with regulatory compliance breadth, specialized marine and offshore energy commissioners, and electrical safety testing firms aligned with evolving utility standards. Competitive dynamics center on laboratory capacity expansion in high-voltage testing and strategic partnerships to compress grid interconnection timelines.
Within the diversified conglomerate tier, Bureau Veritas, SGS, and Intertek occupy positions defined by geographic coverage breadth and regulatory protocol depth. Bureau Veritas leverages its coastal laboratory network positioning. SGS sustains coverage across industrial end users. Intertek anchors its market presence through electrical safety testing alignment with utility standards evolution. These three exemplify how scale and specialization vectors create distinct competitive positions without direct overlap.
| Leading Market Players |
|---|
| Bureau Veritas |
| Applus |
| SGS |
| TUV Rheinland |
| ALS Global |
| Intertek |
| DNV GL |
| TUV SUD |
| Eurofins |
| Others |
Cost & Logistics Intelligence
Quebec's high-voltage laboratory cluster concentrates grid interconnection testing capacity for North American renewable projects, creating asymmetric pricing power for providers with established facilities versus entrants facing 26-week equipment lead times. This geographic chokepoint allows incumbent laboratories to command project-based premiums while regional electrical testing specialists compete on compressed margins for standardized commissioning work.
Pricing Analysis
Long-term operational support contracts with embedded performance guarantees dominate the commissioning segment, while project-based spot pricing prevails for episodic emissions verification and grid interconnection testing. Price differentiation separates NETA-certified electrical testing from non-certified field work, with certification tier and geographic delivery cost as primary drivers. Pricing pressure stems from NETA-certified technician scarcity constraining throughput, forcing margin compression in the standard tier. Healthcare and energy verticals exhibit lowest price sensitivity due to catastrophic liability exposure, while retail facility portfolios drive hardest bargain for standardized HVAC commissioning.
Supply Chain Analysis
Export controls on precision electrical measurement equipment under US Commerce Department regulations limit flows of calibrated instrumentation from Germany, Japan, and Switzerland, extending procurement cycles for North American testing providers. The supply chain draws from these three countries for high-voltage test sets, relay test equipment, and gas analyzers, with additional dependencies on Chinese-manufactured sensor components and South Korean battery testing systems. Single-source vulnerability concentrates in precision voltage transformers and arc flash calculation software. Distribution runs through authorized equipment distributors and direct manufacturer relationships serving laboratory and field service operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent testing and commissioning providers face substitution pressure from digital twin platforms that enable predictive commissioning and remote performance verification, threatening traditional documentation-heavy handover revenues.
For Market Incumbents: Build certification moats through NETA partnership programs and EPA stack testing accreditation to defend against software-based substitutes. Expand high-voltage laboratory capacity in Texas and California to capture grid interconnection backlog premiums. Deepen vertical integration into mobile analytical laboratories for on-site emissions verification, reducing third-party equipment dependency. For New Entrants and Emerging Players: Build out specialized vessel-based marine electrical testing capabilities for Atlantic Coast offshore wind lease rounds, the most penetrable segment given incumbent capacity constraints. Target Mexico nearshoring corridors in Nuevo León for automotive production line validation services. Lead with digital commissioning platforms that compress project timelines for utility-scale solar developers facing interconnection delays. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors diversified conglomerates with regulatory compliance breadth over pure-play electrical testing specialists. Long-term viability rests on cybersecurity-integrated commissioning capabilities as building automation platforms evolve. Watch EPA enforcement intensity under 40 CFR Part 60 as the signal for emissions verification demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| High-Voltage Laboratory Expansion | Captures grid interconnection premiums as Texas and California renewable backlogs extend project timelines. |
| Marine Electrical Testing Capability | Addresses Atlantic Coast offshore wind lease rounds requiring specialized vessel-based subsea cable commissioning. |
| Digital Twin Platform Integration | Enables predictive commissioning and remote performance verification for data center hyperscale facilities. |
| Mobile Analytical Laboratory Buildout | Supports quarterly EPA emissions verification mandates for Gulf Coast cement and petrochemical facilities. |
| NETA Certification Partnership Program | Addresses technician scarcity constraining field deployment capacity across member firms. |
Research Approach
The analysis maps commissioning, testing, inspection, and consulting service segments, each validated through primary interviews with laboratory directors, EPA compliance officers, utility interconnection planners, and data center facilities managers. Secondary sources include FERC reliability filings, EPA 40 CFR Part 60 enforcement data, NETA membership directories, and EIA power plant databases. Bottom-up project pipeline tracking triangulates against top-down capital expenditure modeling across construction, industrial, and energy verticals.
Assumptions held fixed include EPA Clean Air Act enforcement continuity and IEEE/CSA/UL protocol harmonization progress, while renewable energy deployment pace and data center power density evolution were stress-tested across scenarios. Segmentation models incorporate service type, end user industry, technology discipline, and geographic regulatory cluster. CAGRs derive from installed base expansion rates and compliance cycle compression trends, with inputs from high-voltage equipment lead times and certified technician pipeline data.
Stress conditions across emissions regulation intensity, grid interconnection queue duration, and precision instrumentation availability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions with acknowledged sensitivity to OSHA workplace safety mandate expansion and state-level building electrification policy acceleration. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Services
Global Construction Scaffolding Rental Market
Construction Services
Maintenance Repair and Operations (MRO) Market
Construction Services
Excavating Contractor Market
Construction Services
Composite Autoclave Repair Market
Construction Services
Die Casting Services Market
Construction Services
Europe Maintenance, Repair, and Operations (MRO) Market
Construction Services
North and Latin America Weatherization Services Market
Construction Services
North America Fire Sprinkler Systems Market
Construction Services
Construction Project Management Services Market
Construction Services
Dust Suppression Control Market
Construction Services
Gutter Cleaning Services Market
Construction Services
Remote Construction Market
Construction Services
Construction Materials Testing Equipment Market
Construction Services
NDT and Inspection Market
Construction Services
Construction TIC Market
Construction Services
MENA Architectural Services Market