
 Industrial Machinery Repair Services Market | 2026-2036
Industrial Machinery Repair Services Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Machinery Repair Services Market Analysis
The shift from captive in-house shops to third-party service networks is decoupling maintenance budgets from capital equipment divisions at major industrials. Caterpillar Inc leverages its dealer infrastructure to control aftermarket service flows across mining and construction fleets. Deere & Company anchors its competitive position through proprietary diagnostic platforms that lock in agricultural equipment maintenance. ABB Ltd differentiates via predictive maintenance integrations tied to its automation hardware installed base.
Industrial machinery repair services encompass the restoration, refurbishment, and preventive upkeep of capital equipment used in manufacturing, extraction, and material handling, typically involving weld overlay procedures, precision alignment to ISO tolerances, and component remanufacturing to restore original equipment specifications. These services extend asset operational life, minimize unplanned downtime, and preserve production continuity across continuous-process environments. Preventive maintenance commands the largest revenue share as plant operators prioritize scheduled interventions over catastrophic failures, while emergency repair generates premium margins due to response-time premiums and expedited parts logistics. Equipment overhaul represents the fastest-growing category as capital constraints push owners toward mid-life rebuilds rather than replacement purchases.
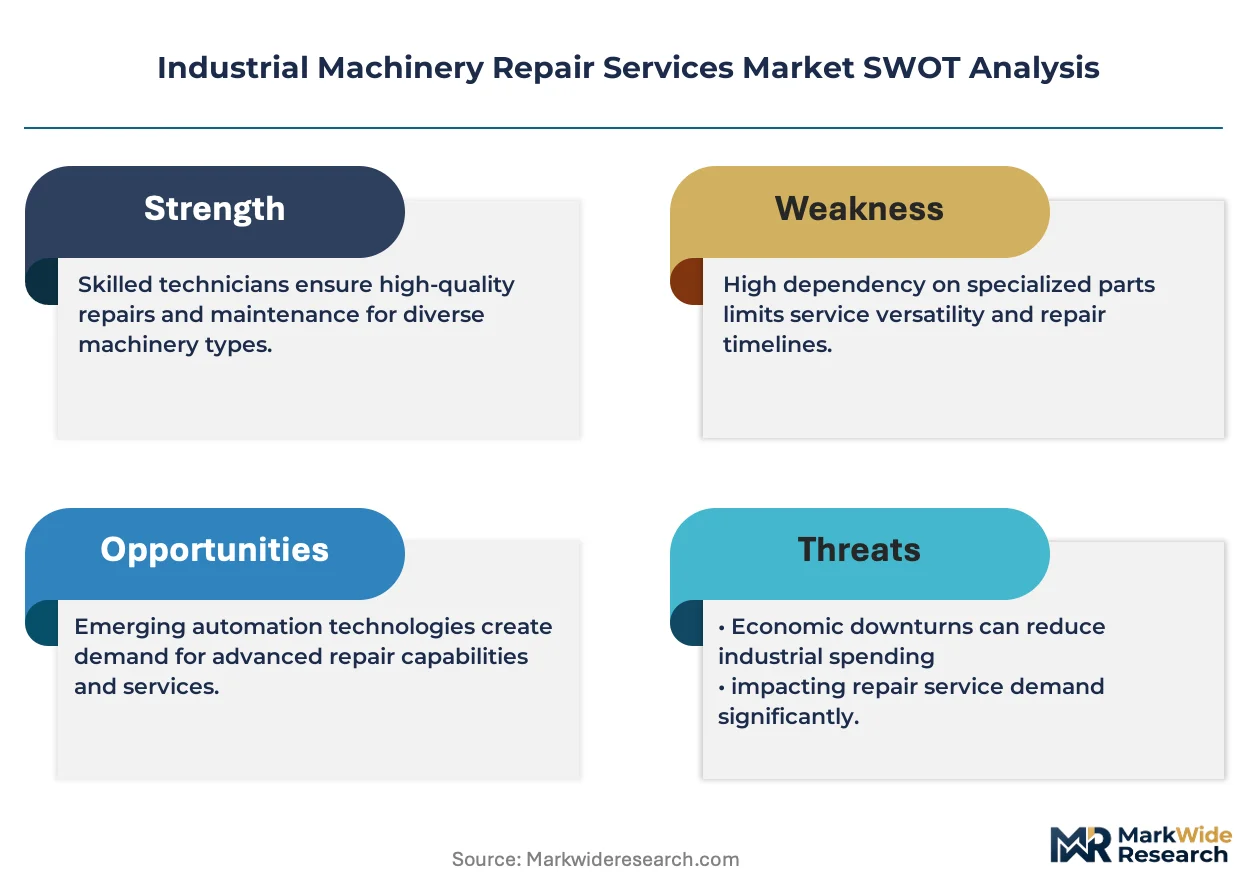
OSHA machinery safety standards mandate documented lockout-tagout procedures and periodic guarding inspections, directly elevating compliance-driven service demand across United States manufacturing facilities. EPA remanufacturing regulations for industrial engines and compressors impose emissions certification requirements on rebuilt equipment, filtering repair shop capabilities and reshaping supplier qualification criteria. Stakeholders must monitor how digital twin adoption and remote monitoring deployment alter the economics of on-site versus off-site service models.
Market Dynamics
The transition from scheduled maintenance to predictive, condition-based service models is restructuring how industrial operators budget for asset upkeep and select repair vendors. This shift decouples service procurement from traditional capital expenditure cycles, forcing repair providers to demonstrate measurable downtime reduction rather than simply parts replacement capability.
Growth Catalysts
- OSHA machinery guarding mandates:United States manufacturing facilities face intensified inspection schedules for lockout-tagout compliance, driving documented service contract growth.
- Food processing expansion:Midwest United States plants are extending multi-year service agreements for aging production lines rather than undertaking capital replacement.
- Steel cluster density:Germany's Ruhr industrial corridor sustains dense repair networks through geographic concentration of heavy machinery operators.
Market Restraints
- Specialized welder scarcity:Precision weld overlay certification requirements limit qualified technician supply in North American repair shops.
- Component supply concentration:Critical remanufactured parts for legacy mining equipment flow through single-source distributors in select geographies.
- EPA emissions certification friction:Rebuilt industrial engines and compressors face extended approval timelines, compressing repair shop throughput.
Strategic Opportunities
- Digital twin integration:Convergence of asset simulation software with vibration monitoring hardware enables remote diagnostic service offerings.
- Mid-life equipment rebuilds:Capital-constrained operators in process industries favor equipment overhaul over replacement purchases.
- Dealer network capture:Mining and construction fleet operators seek consolidated service relationships through established equipment distribution channels.
Industry Challenges
- ISO tolerance alignment expertise:Precision measurement and correction to international standards requires capital-intensive metrology equipment and certified technicians.
- Proprietary diagnostic platform lock-in:Agricultural and construction equipment manufacturers restrict third-party access to fault-code databases and calibration protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Machinery Repair Services Market |
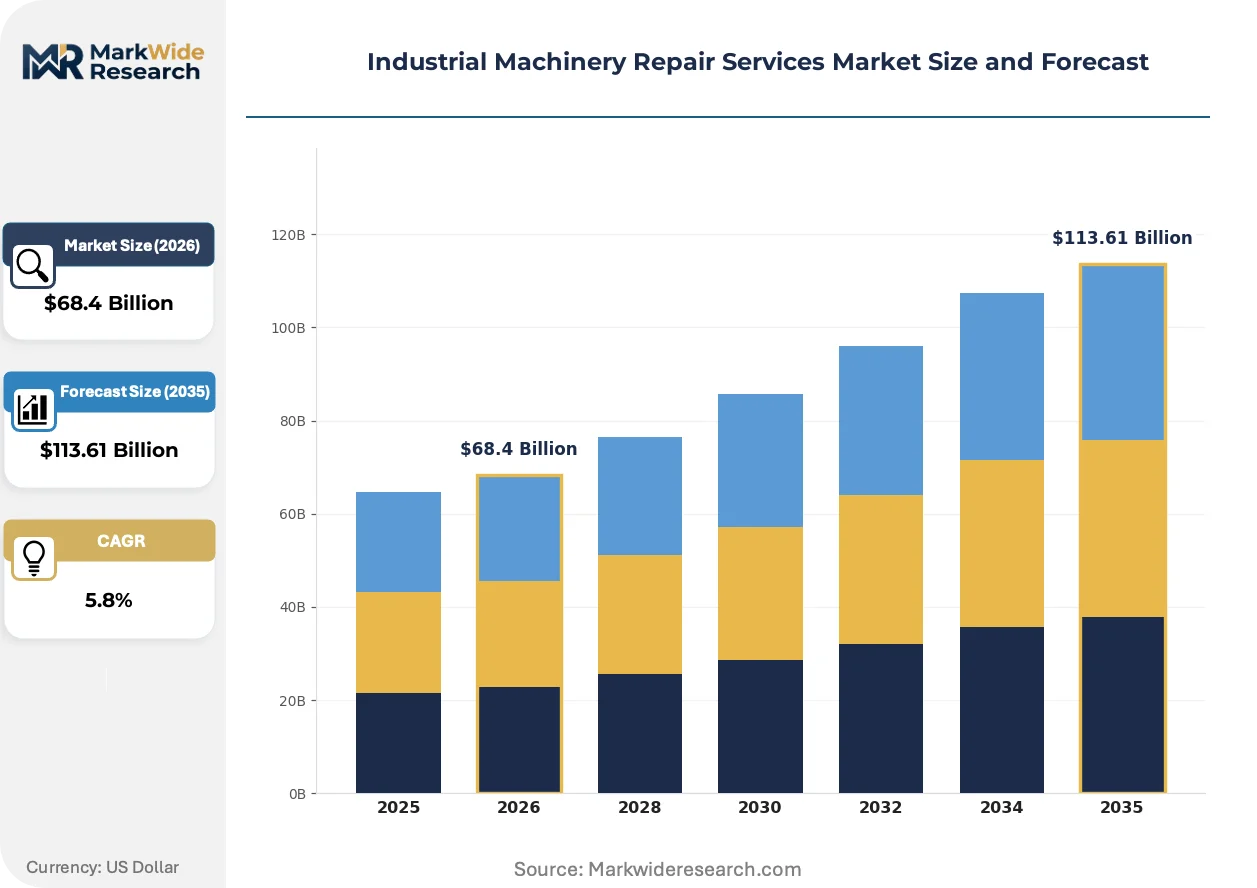
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $113.61 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Preventive Maintenance, Emergency Repair, Replacement Services, Equipment Overhaul Technology: Hydraulic Systems, Electrical Components, Pneumatic Systems, Mechanical Repairs End User: Manufacturing Plants, Construction Sites, Mining Operations, Agricultural Equipment Deployment: On-site Services, Off-site Services, Remote Monitoring, Scheduled Visits |
| Companies Covered | Caterpillar Inc, Deere & Company, CNH Industrial NV, ABB Ltd, Exline Inc, L&H Industrial, Linde AG, Emerson Electric Co, Rockwell Automation Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Machinery Repair Services Market Emerging Trajectories
Remote monitoring infrastructure and asset virtualization are compressing the distinction between preventive and predictive maintenance, enabling repair providers to intervene before mechanical failure manifests. This technological layer is reshaping contract structures and vendor qualification criteria across continuous-process industries.
Industrial digital twin technology is unifying physical asset behavior with real-time simulation models. Mining operators in Australia and process manufacturers in Germany deploy these systems to forecast component degradation windows. The technology is unifying maintenance scheduling with production planning, compressing the traditional separation between operations and asset management functions.
EPA remanufacturing regulations for industrial engines impose emissions certification requirements that filter repair shop capabilities. Rebuilt equipment must demonstrate compliance equivalent to new manufacture, elevating documentation and testing overhead. United States-based service providers serving construction and material handling segments invest in dedicated emissions testing infrastructure to maintain supplier qualification.
Service procurement patterns favor integrated maintenance contracts over transactional repair orders. Food processing and chemical plant operators in the United States consolidate vendor relationships to reduce administrative burden and improve response-time guarantees. This concentration preference disadvantages independent repair shops lacking national coverage or multi-trade capabilities.
Industrial Machinery Repair Services Market Segmentation
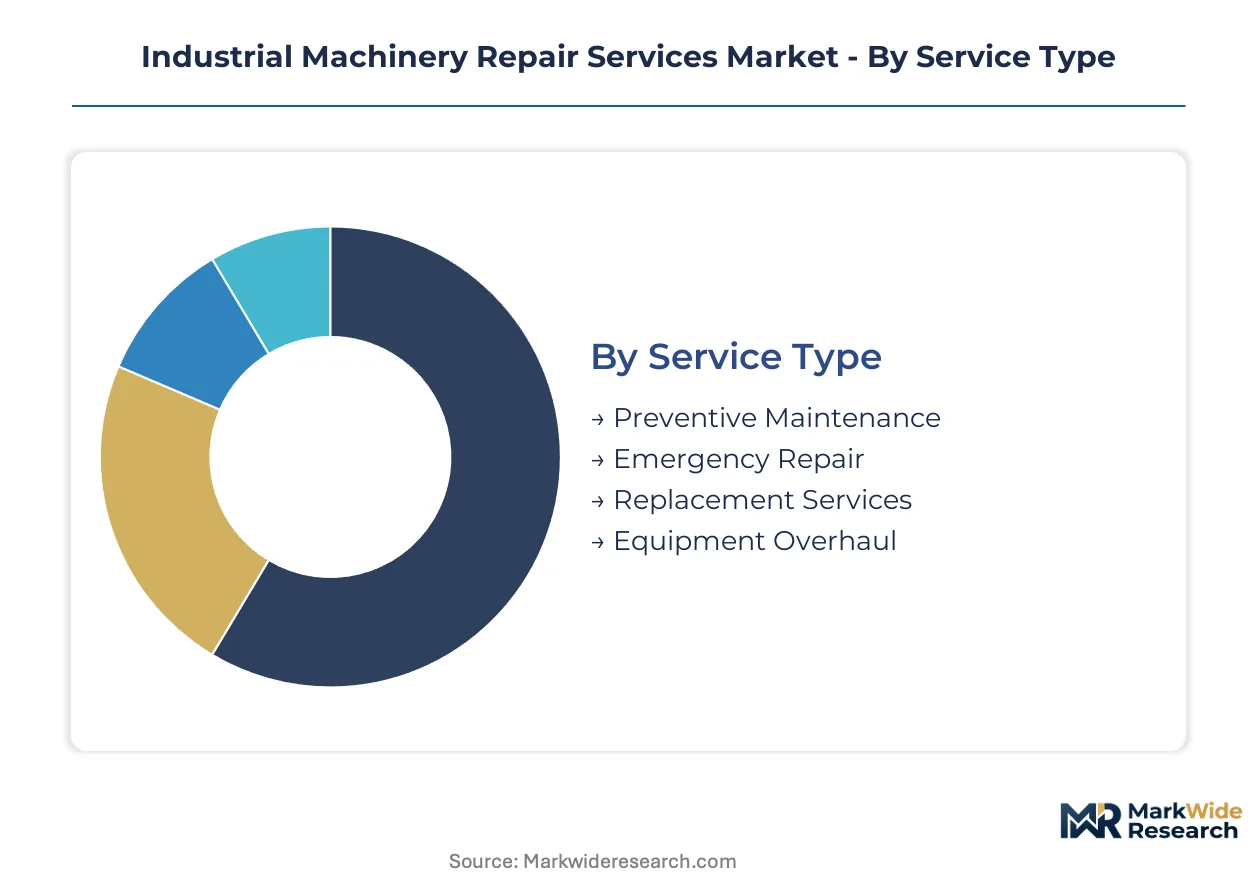
Segmentation in industrial machinery repair services determines how service providers allocate certified technician pools and compliance documentation resources. Distinct segments carry divergent regulatory burdens, from OSHA lockout-tagout mandates for on-site work to EPA emissions certification for equipment overhaul.
Service Type:
Preventive maintenance contracts require documented OSHA compliance for periodic guarding inspections, while emergency repair and overhaul categories face EPA emissions certification for rebuilt engines and compressors.
- Preventive Maintenance:Scheduled interventions including lubrication analysis, vibration monitoring, and alignment checks to ISO tolerances. Food processing plants across the Midwest United States prioritize multi-year agreements for aging production lines over capital replacement.
- Emergency Repair:Unplanned interventions demanding rapid response logistics and expedited parts procurement. Mining operations in Australia's Pilbara region absorb premium margins for 24-hour technician deployment to remote sites.
- Replacement Services:Component swap-out procedures with OEM specification matching.
- Equipment Overhaul:Mid-life rebuilds to original specifications with emissions recertification. Capital-constrained process industries favor this category over new equipment procurement.
Preventive maintenance sits at the top of the volume ranking, with equipment overhaul climbing the fastest.
Technology:
Cost tiering separates hydraulic and electrical work requiring precision certification from mechanical repairs with broader technician availability.
- Hydraulic Systems:High-pressure circuit rebuilds, seal replacement, and fluid contamination remediation. Germany's Ruhr industrial corridor sustains dense specialist networks serving steel mill continuous casting equipment.
- Electrical Components:Variable frequency drive refurbishment, motor rewinding, and control system integration. Manufacturing plants demand IEC-compliant work with documented arc-flash hazard mitigation.
- Pneumatic Systems:Compressor rebuilds and valve manifold servicing.
- Mechanical Repairs:Bearing replacement, shaft repair, and gearbox rebuilding with broadest technician pool.
Hydraulic systems command premium pricing tiers, with electrical components expanding most quickly.
End User:
Application intensity varies from continuous-process manufacturing to intermittent-use construction, dictating service contract structures and response-time guarantees.
- Manufacturing Plants:Continuous-process environments requiring predictive maintenance integration with production scheduling. Chemical facilities consolidate vendor relationships to reduce administrative burden and lock in response-time commitments.
- Mining Operations:Remote-site deployment challenges and extreme-duty equipment cycles. Australian operators deploy digital twin systems to forecast component degradation windows and unify maintenance with extraction planning.
- Construction Sites:Mobile equipment fleets with seasonal demand spikes.
- Agricultural Equipment:Seasonal concentration with proprietary diagnostic platform dependencies.
Manufacturing plants anchor contract volume, with mining operations gaining share fastest.
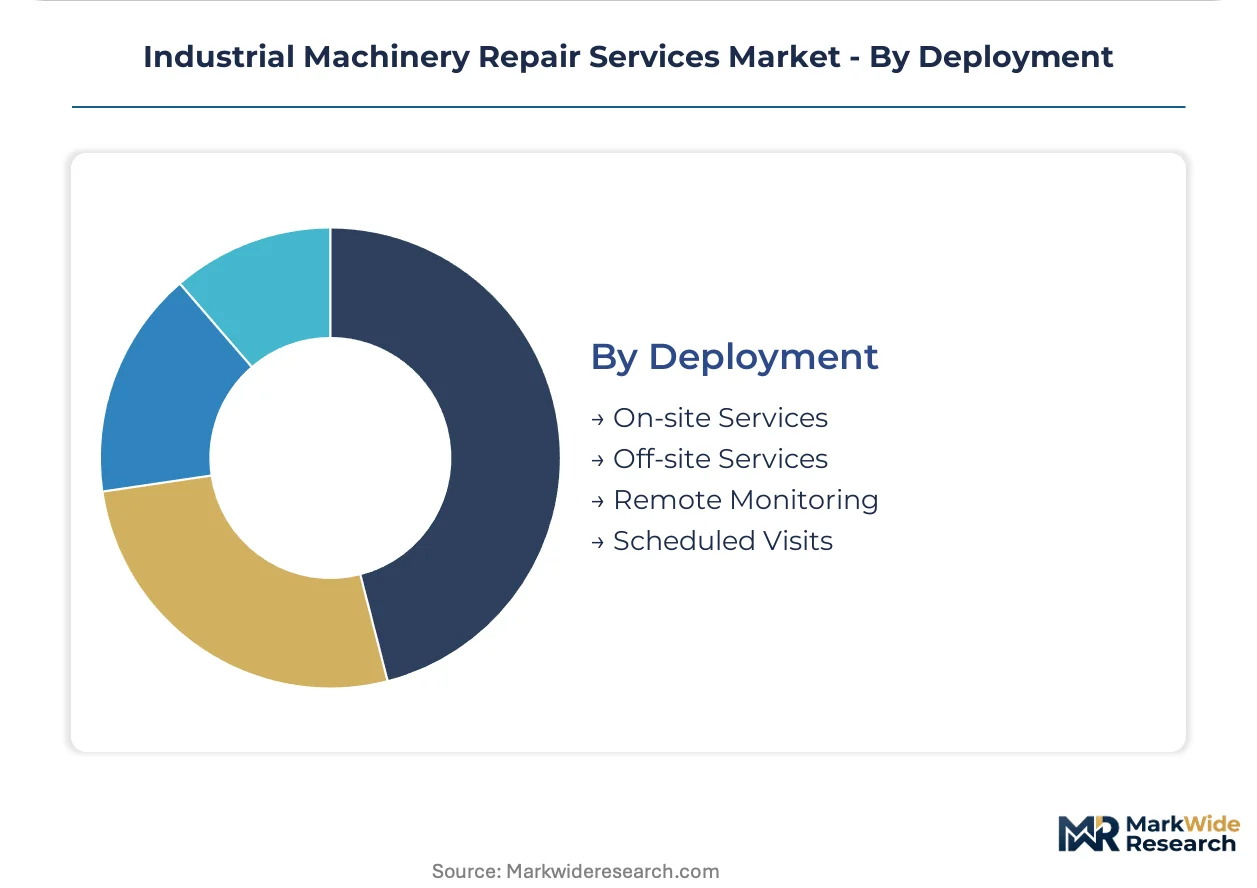
Deployment:
Margin structures diverge sharply between asset-intensive on-site mobilization and technology-leveraged remote monitoring offerings.
- On-site Services:Technician dispatch with mobile machine shops and portable metrology equipment. United States facilities demand documented lockout-tagout procedures per OSHA machinery guarding mandates.
- Remote Monitoring:Vibration analysis, thermal imaging, and digital twin convergence enabling pre-failure intervention. Process manufacturers deploy these systems to compress the traditional separation between operations and asset management functions.
- Off-site Services:Shop-based rebuilds with controlled environment precision work.
- Scheduled Visits:Calendar-based technician rotation with preventive task checklists.
On-site services retain volume leadership, with remote monitoring showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Ruhr industrial corridor sustains dense repair networks through geographic concentration of steel and automotive clusters. United States food processing plants extend service contracts for aging production lines across the Midwest. Australian mining operators deploy digital twin systems to unify maintenance with extraction planning.
United States
Food processing plants across the Midwest extend multi-year service agreements for aging production lines rather than capital replacement. OSHA machinery guarding mandates intensify inspection schedules for lockout-tagout compliance, driving documented service contract growth. EPA emissions certification requirements for rebuilt industrial engines and compressors filter repair shop capabilities across Ohio, Michigan, and Illinois industrial corridors.
Germany
Steel and automotive clusters in the Ruhr industrial corridor sustain dense repair networks through geographic concentration of heavy machinery operators. REACH regulations and CE marking requirements impose documentation standards on component remanufacturing. Bavaria's precision engineering belt hosts specialized hydraulic system rebuilders serving continuous casting equipment.
Australia
Mining operations in the Pilbara region absorb premium margins for 24-hour technician deployment to remote extraction sites. The country's national environmental regulator imposes emissions recertification requirements on rebuilt mobile equipment fleets. Queensland's Bowen Basin coal cluster drives demand for extreme-duty equipment overhaul and mid-life rebuild programs.
China
Manufacturing belt concentration in the Yangtze River Delta generates sustained demand for preventive maintenance contracts across process industries. GB standards and MIIT industrial equipment regulations mandate documented maintenance protocols for state-owned enterprise fleets. Shandong Province's chemical processing corridor consolidates vendor relationships to reduce administrative burden.
Japan
Automotive and electronics manufacturing clusters in the Chubu region around Nagoya sustain precision alignment and metrology service demand. METI industrial efficiency guidelines promote predictive maintenance adoption to minimize unplanned downtime. Kansai's Osaka-Kobe industrial zone hosts specialized electrical component rebuilders serving semiconductor fabrication equipment.
Industrial Machinery Repair Services Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue digital twin integration and remote monitoring capabilities. The vendor base spans consolidated equipment manufacturers with captive service networks alongside fragmented independent repair shops. Three archetypes dominate: OEM-affiliated dealer networks, independent multi-trade service providers, and specialized component rebuilders. Competitive moves concentrate on strategic partnerships for diagnostic platform access and geographic expansion through regional shop acquisitions.
Among equipment manufacturer-affiliated service providers, Caterpillar Inc, Deere & Company, and ABB Ltd exemplify distinct strategic positioning. Caterpillar Inc represents the dealer-network archetype controlling aftermarket flows through established distribution infrastructure. Deere & Company occupies a position defined by proprietary diagnostic platform dependencies in agricultural equipment maintenance. ABB Ltd anchors the automation-integrated tier through predictive maintenance offerings tied to hardware installed bases.
| Leading Market Players |
|---|
| Caterpillar Inc |
| Deere & Company |
| CNH Industrial NV |
| ABB Ltd |
| Exline Inc |
| L&H Industrial |
| Linde AG |
| Emerson Electric Co |
| Rockwell Automation Inc |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up repair specialists now dominate the North American aftermarket, concentrating pricing power among consolidated platforms while compressing margins for independent shops lacking scale economies in certified welder recruitment and EPA emissions testing infrastructure.
Pricing Analysis
Input-cost pass-through from scarce precision welders and specialized remanufactured parts flows into three-tier pricing structure across premium, standard, and economy levels. Premium tiers attach to ISO-certified alignment work and EPA-compliant engine rebuilds; economy tiers cover mechanical repairs with broader technician availability. Pricing pressure stems from capital-constrained food processors extending service contracts rather than replacing aging lines. Mid-sized manufacturing plants exhibit highest price sensitivity; mining operators in remote geographies absorb premium margins with minimal negotiation leverage.
Supply Chain Analysis
Critical remanufactured components for legacy mining equipment rest on single-source distributors concentrated in Australia, Germany, and the United States. Precision weld overlay consumables, high-pressure hydraulic seals, and emissions-certified engine cores constitute the primary input dependencies. Single-source vulnerability in legacy mining component flows creates structural risk for repair shop throughput. Distribution runs through OEM-affiliated dealer networks and independent multi-trade service providers, with consolidation favoring integrated platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial machinery repair services constitute a late-cycle quality story as capital-constrained operators prioritize mid-life equipment rebuilds over replacement, elevating demand for certified overhaul work with documented EPA emissions compliance and ISO tolerance alignment.
For Market Incumbents: Extend predictive maintenance platform deployments to lock in agricultural and construction fleet operators before proprietary diagnostic restrictions harden. Consolidate regional independent shops to capture scarce precision welder talent pools and expand EPA-certified rebuild capacity. Vertical integration into remanufactured component sourcing mitigates single-source distributor risk in legacy mining equipment flows. For New Entrants and Emerging Players: Mid-sized chemical processors in Shandong Province and the United States Midwest represent an underserved buyer archetype seeking consolidated vendor relationships with multi-trade capabilities and guaranteed response times. Digital twin integration for remote diagnostic services offers the most penetrable wedge against established OEM-affiliated networks. Partner with vibration monitoring hardware vendors to accelerate platform deployment without captive R&D investment. For Investors and Strategic Acquirers: Valuations sit cheapest among independent hydraulic system specialists in Germany's Ruhr corridor and precision electrical rebuilders in Japan's Kansai region, where family ownership transitions create acquisition windows. Long-term viability hinges on regulatory compliance infrastructure rather than commodity mechanical repair capacity. Watch EPA emissions certification timeline compression as the inflection signal for repair shop qualification attrition.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Platform Deployment | Remote diagnostic convergence with physical asset monitoring compresses preventive-predictive maintenance distinction for process manufacturers. |
| Precision Welder Certification Investment | OSHA-mandated weld overlay qualifications filter shop capabilities and create scarcity premiums in North American repair networks. |
| EPA Emissions Testing Infrastructure | Rebuilt engine certification requirements in Ohio, Michigan, and Illinois industrial corridors elevate documentation overhead and supplier qualification barriers. |
| Dealer Network Acquisition | Caterpillar and Deere distribution infrastructure controls aftermarket service flows across mining and agricultural equipment fleets. |
| Mid-Life Rebuild Program Expansion | Capital-constrained food processors in the Midwest United States favor equipment overhaul over production line replacement purchases. |
Methodological Framework
Bottom-up manufacturing plant modeling reconciled against top-down OEM service network tracking forms the analytical core of this study. Primary interviews with maintenance directors, plant engineers, aftermarket service heads, and OEM procurement teams were validated against secondary sources including OSHA enforcement databases, EPA remanufacturing certification records, SEC 10-K filings from listed equipment manufacturers, and customs data on remanufactured component trade flows. Triangulation across these inputs ensures segmentation integrity across service type, technology tier, and deployment mode.
Input-output matrices map certified technician supply constraints and regulatory compliance costs against demand from continuous-process manufacturing, mining operations, and agricultural equipment fleets. Segmentation dimensions include service type, technology specialization, end-use intensity, and deployment mode across the projection horizon. CAGRs derive from equipment age distribution analysis, replacement-versus-rebuild economic modeling, and regulatory compliance timeline assumptions. Forecast inputs incorporate digital twin adoption curves and predictive maintenance platform penetration rates.
Inputs from OSHA enforcement statistics and EPA certification databases were available through the study window; gaps in proprietary diagnostic platform access protocols introduce uncertainty bands around third-party service provider market share estimates. Forecasts reflect documented assumptions regarding regulatory timeline stability and capital expenditure cycle positioning. A small set of triggers—EPA emissions certification rule acceleration, precision welder training program expansion, and OEM diagnostic platform lock-in enforcement—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Services
NDT and Inspection Market
Construction Services
Hardbanding Services Market
Construction Services
Grease Trap Service Market
Construction Services
Condenser Cleaners Market
Construction Services
Global Construction Scaffolding Rental Market
Construction Services
Middle East and Africa Industrial Maintenance Services in Operational Improvement and Operational Maintenance Market
Construction Services
Heavy Equipment Training Simulator Market
Construction Services
Maintenance Repair and Operations (MRO) Market
Construction Services
Excavating Contractor Market
Construction Services
Testing, Inspection, and Certification for Construction Market
Construction Services
MENA Architectural Services Market
Construction Services
3D Concrete Printing Services Market
Construction Services
Forklift Repair and Maintenance Service Market
Construction Services
Industrial Maintenance Services Market
Construction Services
Global Industrial Services Market
Construction Services
North America Repair and Rehabilitation Market