
 Aerial Cable Car Equipment Market | 2026-2036
Aerial Cable Car Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Aerial Cable Car Equipment Market Outlook
Aftermarket service revenue is fragmenting across multiple vendor tiers as original equipment manufacturers compete with independent maintenance providers. Doppelmayr/Garaventa Group anchors its position through captive supply of proprietary grip and drive components. POMA Group differentiates via technology leadership in detachable grip systems for high-capacity urban lines. Leitner S.p.A leverages its Italian manufacturing base to sustain strong channel control across European alpine markets.
Aerial cable car equipment encompasses the mechanical and electrical systems that propel passenger cabins along suspended steel cables, including drive stations, tensioning systems, grip mechanisms, and control electronics typically rated for wind speeds up to 80 km/h and passenger loads exceeding 4,000 persons per hour. These installations serve commercial transit corridors, recreational ski domains, and industrial material transport where terrain prohibits conventional road or rail construction. Gondola systems occupy the largest value pool due to their versatility across urban and recreational settings. Chair lifts retain mature demand cycles tied to ski resort replacement schedules in North America and Europe. Urban installation types are gaining fastest as municipalities adopt cable transit for last-mile connectivity.
The EU Machinery Directive and CE marking requirements govern structural safety and electromagnetic compatibility for all European installations, while the F-Gas Regulation constrains refrigerant choices in climate-controlled cabins. The FAA coordinates with urban planners where cable crossings intersect controlled airspace near US airports. Stakeholders must monitor evolving urban air mobility corridors and heritage landscape protections that could restrict new route approvals.
Market Dynamics
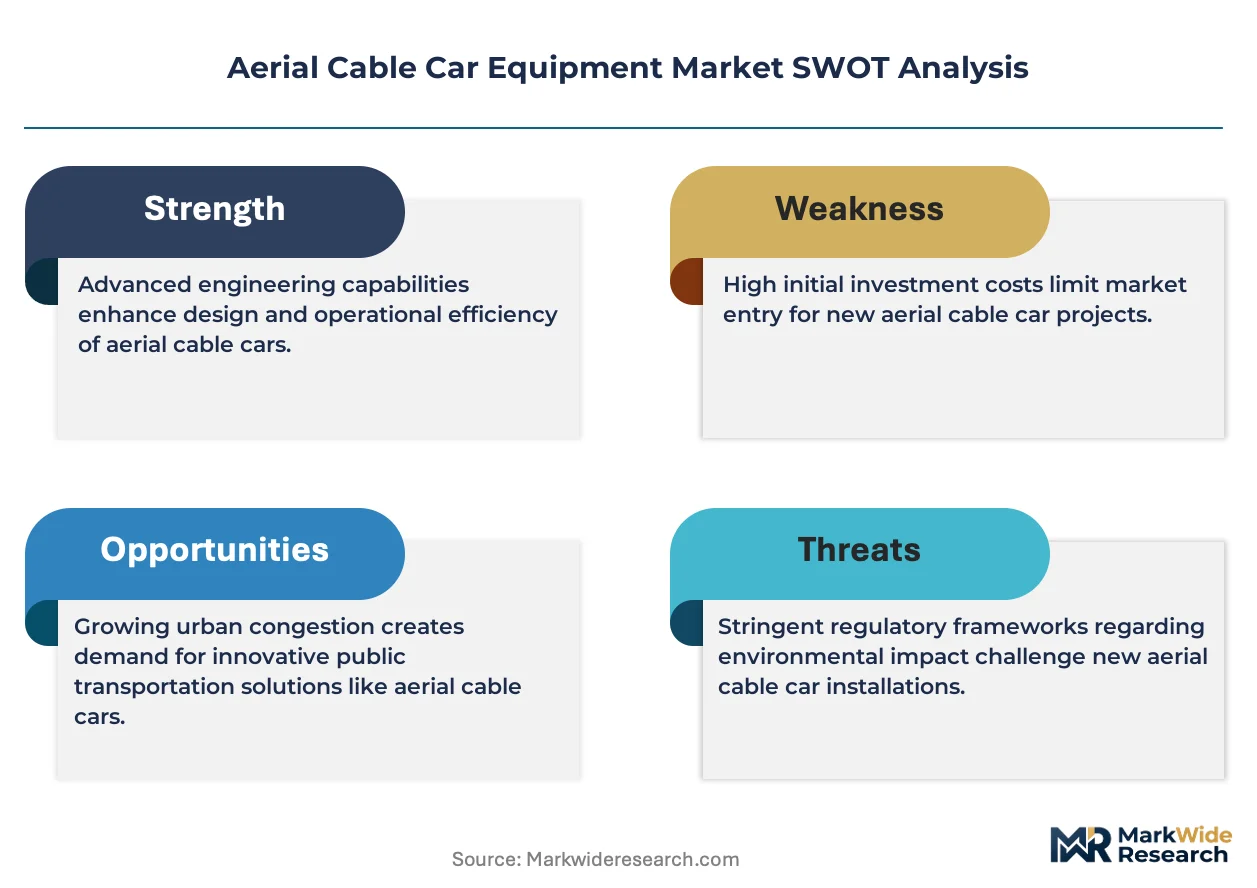
Urban congestion and terrain-constrained transit corridors are forcing municipalities toward suspended cable systems as cost-effective alternatives to tunneling or elevated rail, tightening certification timelines and reshaping competitive positioning around proprietary grip technologies.
Growth Catalysts
- EU Machinery Directive compliance mandates:European installations must meet updated structural safety and electromagnetic compatibility standards, accelerating replacement cycles for aging alpine infrastructure.
- Last-mile urban connectivity gaps:Municipalities in mountainous and island cities deploy aerial systems where road construction proves economically unviable.
- Steel cable metallurgy advances:High-strength synthetic-core cables reduce tower spacing requirements and enable longer single-span installations across deep valleys.
Market Restraints
- Copper and steel price volatility:Drive motor windings and main haul ropes constitute concentrated raw material exposure, compressing margins during commodity spikes.
- Swiss-Austrian component supply concentration:Precision-machined grip mechanisms and bullwheel assemblies source from a narrow Alpine supplier base, creating bottleneck risk.
- Wind speed operational ceilings:Current cabin designs face forced closures above 80 km/h, limiting deployment in exposed coastal or high-altitude corridors.
Strategic Opportunities
- Brazilian urban transit corridors:Rio de Janeiro and other hillside cities lack metro penetration, creating white space for integrated cable-bus networks.
- F-Gas Regulation cabin climate incentives:European mandates for low-global-warming-potential refrigerants reward early adopters of heat-pump-based cabin HVAC retrofits.
- Digital twin convergence with predictive maintenance:Sensor-integrated drive stations enable condition-based servicing, displacing fixed-interval overhaul contracts.
Industry Challenges
- Certified grip technician scarcity:Doppelmayr and Leitner proprietary systems require manufacturer-authorized training, constraining maintenance capacity expansion.
- Multi-year airspace coordination timelines:FAA clearance for airport-proximate crossings demands extended pre-construction regulatory engagement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerial Cable Car Equipment Market |
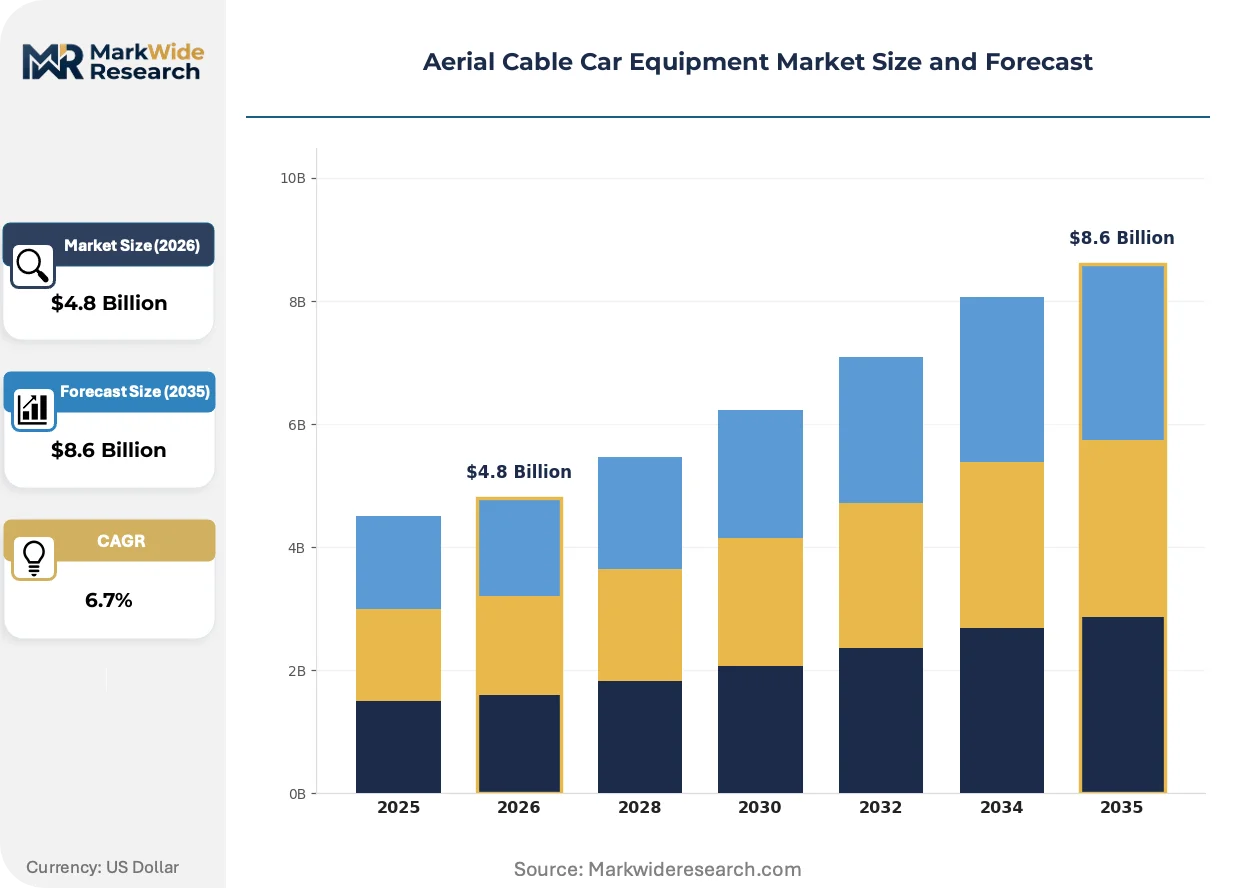
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gondolas, Trams, Chair Lifts, Funiculars End User: Transportation Authorities, Tourism Companies, Municipalities, Private Operators Installation Type: Onshore, Urban, Recreational, Industrial Service Type: Maintenance, Installation, Consulting, Upgrades |
| Companies Covered | Bartholet Maschinenbau AG, Nippon Cable Co., Ltd., Doppelmayr/Garaventa Group, Conveyor & Ropeway Services Pvt. Ltd., Damodar Ropeways & Infra Ltd, POMA Group, MND Group, Vergokan, Leitner S.p.A, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerial Cable Car Equipment Market Strategic Shifts
Digital instrumentation and predictive analytics are reshaping how operators manage safety-critical mechanical systems, compressing maintenance intervals while extending asset life through condition-based interventions.
Condition monitoring systems is digitizing drive station operations across alpine ski domains and urban transit networks. Resort operators in Colorado and Tyrol deploy vibration sensors and thermal imaging on bullwheel bearings to detect fatigue before catastrophic failure. This capability is digitizing traditional time-based maintenance schedules into predictive models that reduce unplanned downtime and extend component replacement cycles.
REACH chemical restrictions and F-Gas refrigerant phase-downs are forcing cabin HVAC redesigns throughout European installations. Manufacturers must substitute legacy hydrofluorocarbon cooling systems with CO2 or hydrocarbon alternatives to maintain CE marking compliance. Ski resort operators in Austria and Switzerland face accelerated retrofit timelines as 2027 refrigerant bans approach, prioritizing suppliers with certified low-carbon climate solutions.
After-sales service unbundling is fragmenting long-term revenue streams as independent maintenance providers capture mid-life overhaul work from original equipment suppliers. Urban transit authorities in La Paz and Medellín increasingly separate equipment procurement from multi-year service contracts, awarding maintenance to lowest-qualified bidders rather than captive vendor networks. This pattern concentrates in Latin American municipalities with constrained capital budgets and mature installed bases requiring mid-cycle refurbishment.
Aerial Cable Car Equipment Market Segmentation
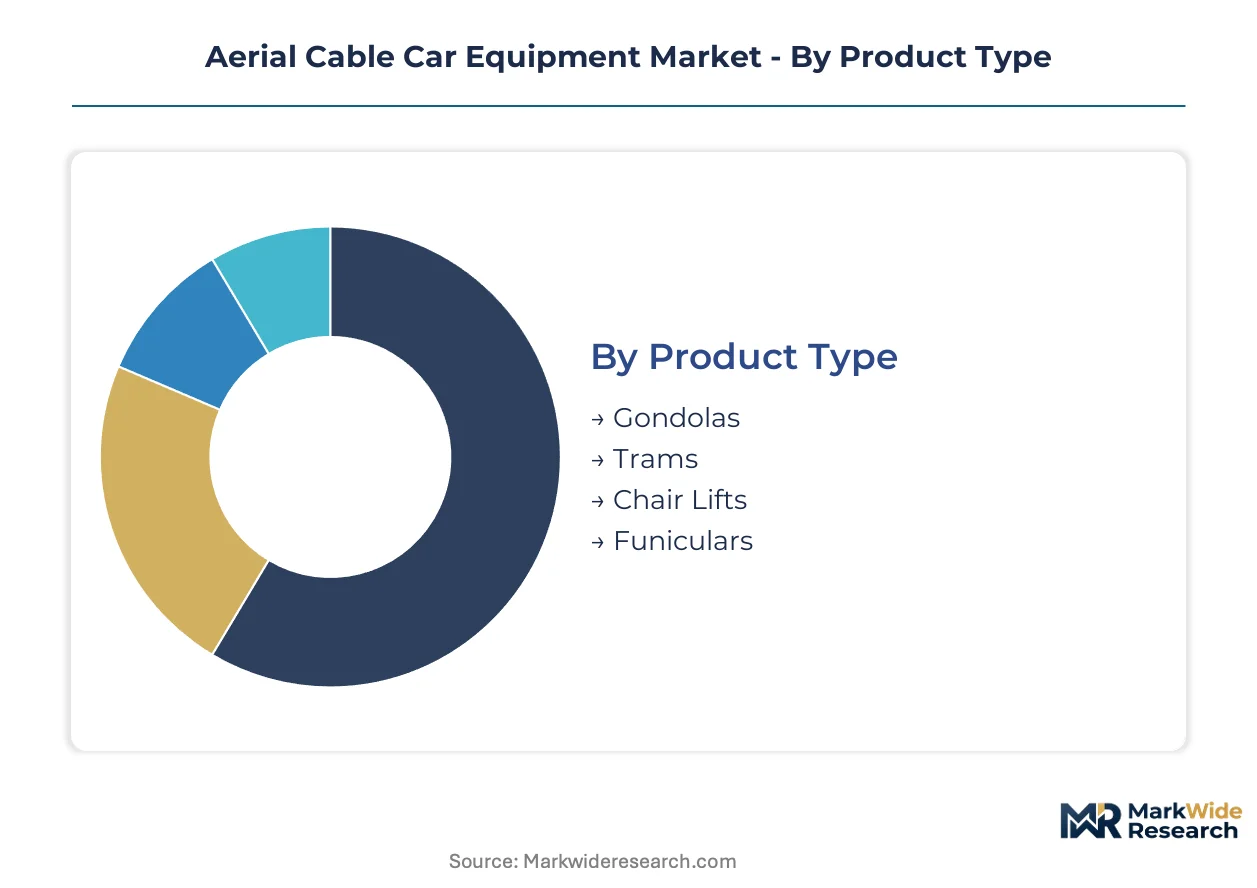
Equipment segmentation in this market determines aftermarket revenue capture, as proprietary grip systems and drive architectures lock operators into manufacturer-dependent service ecosystems. Distinct technical specifications across product categories create tiered maintenance intensity that reshapes vendor profitability over 20-year asset lifecycles.
Product Type:
After-sales service intensity varies sharply across mechanical architectures, with detachable grip systems demanding specialized technician certification that fragments the maintenance provider landscape.
- Gondolas:Enclosed cabins suspended on continuously moving cables accommodate 4-15 passengers with wind-rated designs to 80 km/h. Swiss and Austrian alpine resorts concentrate replacement demand as 1980s-era installations reach end-of-design-life, while Medellín and La Paz municipalities expand urban networks. Gondolas hold the largest share; momentum sits with urban installation types.
- Trams:Single or double cabins shuttle on reciprocating haul ropes with higher capacity per trip but lower throughput than continuous systems. Coastal and island municipalities favor these for steep terrain corridors where road construction faces geological constraints.
- Chair Lifts:Open-air seating for 2-8 passengers dominates North American and European ski resort infrastructure. Colorado and Tyrol operators face compressed replacement windows as aging bullwheel assemblies exceed fatigue limits.
- Funiculars:Counterbalanced rail-guided cars on inclined tracks serve short-haul urban hillsides and underground mining access. Rio de Janeiro hillside districts and Pittsburgh historic corridors represent concentrated demand pockets.
Gondolas command installed base dominance; urban transit applications are climbing the fastest.
End User:
Procurement authority concentration determines contract structure, with public-sector tendering rules fragmenting vendor relationships differently than captive private-operator networks.
- Transportation Authorities:Integrated urban transit agencies in La Paz and Medellín award multi-line concessions with 25-year operating contracts. These entities separate equipment purchase from service provision, enabling independent maintenance competition.
- Tourism Companies:Ski resort operators in Colorado Rockies and Swiss Alps prioritize uptime guarantees over capital expenditure minimization, favoring OEM-captive service agreements.
- Municipalities:City governments with constrained infrastructure budgets deploy aerial systems as last-mile connectors where tunneling costs prove prohibitive. Brazilian hillside cities represent emerging procurement volumes.
- Private Operators:Industrial material transport and mining access contractors favor standardized components over proprietary systems to minimize technician dependency.
Transportation authorities hold the largest share; momentum concentrates with municipalities.
Installation Type:
Environmental exposure severity dictates component replacement cycles, with coastal corrosion and urban particulate loading accelerating maintenance spend beyond alpine recreational norms.
- Onshore:Cross-valley recreational and utility installations in alpine and mountainous terrain face wind-loading extremes but minimal atmospheric corrosion. Tower foundation requirements dominate civil engineering costs.
- Urban:Street-level integration demands noise mitigation and architectural enclosure systems. FAA airspace coordination extends pre-construction timelines near US airport corridors.
- Recreational:Ski domain and scenic tourism installations concentrate in Swiss-Austrian supply chain proximity, reducing spare parts logistics complexity.
- Industrial:Mining and material transport systems prioritize payload capacity over passenger comfort, with simplified grip mechanisms enabling in-house maintenance.
Recreational installations hold the largest share; urban corridors are gaining share fastest.
Service Type:
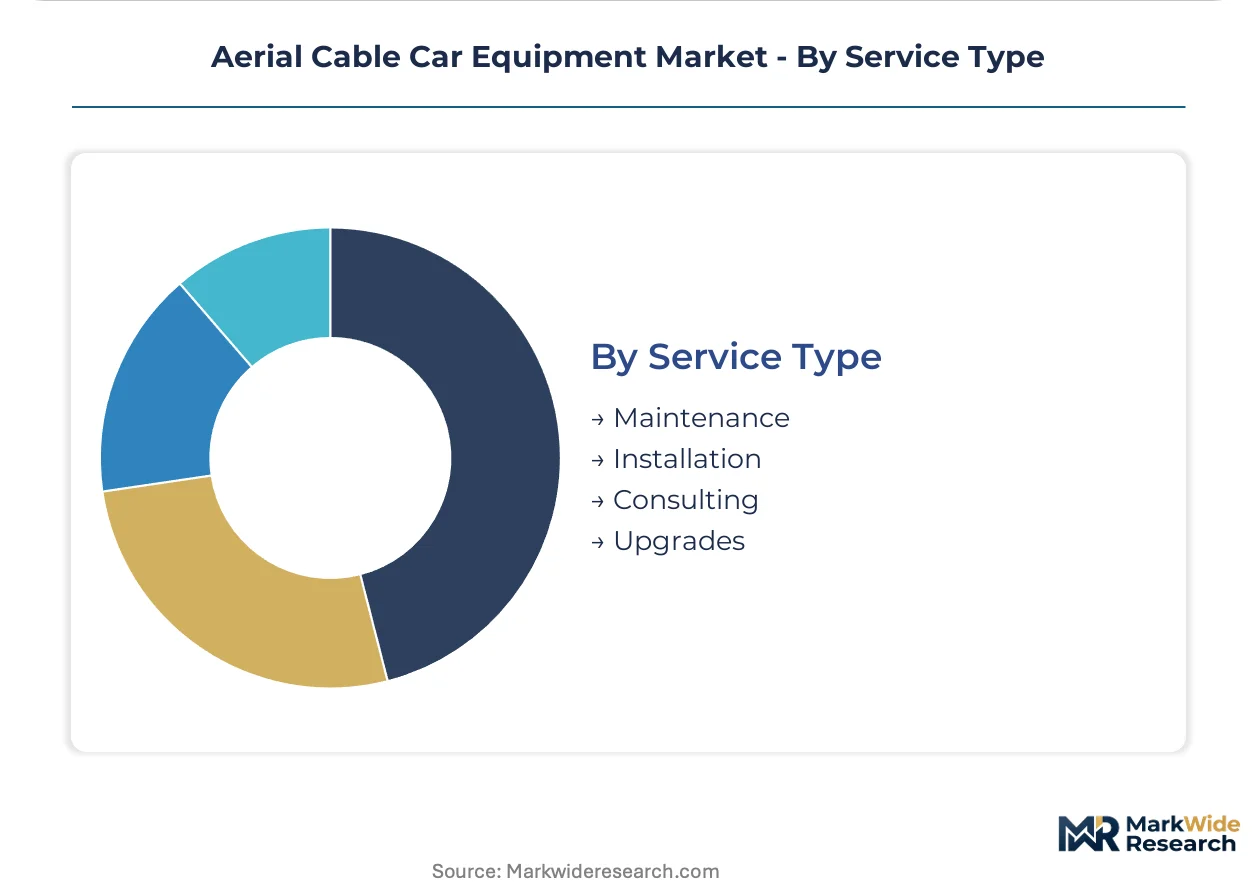
Revenue model unbundling is fragmenting long-term contract structures, with predictive maintenance technologies displacing fixed-interval overhaul arrangements.
- Maintenance:Condition monitoring via vibration sensors and thermal imaging enables predictive intervention, extending bullwheel bearing life and reducing unplanned downtime. Colorado and Tyrol resorts lead adoption.
- Installation:Greenfield project execution requires airspace clearance coordination and heritage landscape review, compressing vendor margins on regulatory delay risk.
- Consulting:Route feasibility and load analysis services support municipal planning departments in terrain-constrained transit corridor evaluation.
- Upgrades:Grip mechanism and control electronics modernization extends asset life for 1980s-era installations facing EU Machinery Directive compliance deadlines.
Maintenance holds the largest share; upgrades are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. Alpine economies prioritize recreational infrastructure replacement, while Latin American municipalities drive urban transit expansion. European regulatory compliance accelerates equipment turnover, whereas Asian markets concentrate on industrial material transport applications.
Switzerland
Swiss alpine resorts dominate replacement demand as 1980s-era installations face EU Machinery Directive fatigue limits. CE marking requirements and F-Gas refrigerant phase-downs compress retrofit timelines through 2027. The Bernese Oberland and Valais cantons concentrate modernization activity around Zermatt and Verbier ski domains.
United States
Colorado Rockies ski operators confront compressed bullwheel replacement cycles amid aging infrastructure. FAA airspace coordination extends pre-construction timelines for urban corridors near Denver and Salt Lake City airports. Vail and Aspen resort clusters prioritize uptime guarantees over capital minimization in procurement decisions.
Bolivia
La Paz Mi Teleférico operates the world's largest urban cable network with expanding line concessions. Municipal transit authorities separate equipment purchase from service contracts, enabling independent maintenance competition. The El Alto corridor demonstrates terrain-constrained transit viability at altitude extremes.
Austria
Tyrol ski domains drive precision-machined component demand from captive Alpine supplier networks. REACH chemical restrictions and EU Machinery Directive electromagnetic compatibility standards govern new installations. Innsbruck and Kitzbühel clusters source grip mechanisms from concentrated regional fabricators.
Brazil
Rio de Janeiro hillside districts lack metro penetration, creating white space for integrated cable-bus networks. Municipal procurement separates capital expenditure from operating concessions under constrained federal infrastructure budgets. The Santa Teresa and Complexo do Alemão corridors represent emerging installation volumes.
Aerial Cable Car Equipment Market Competitive Environment
Capability concentration sits with one tier; scale advantage sits with another. The vendor base organizes around three structural positions: European alpine specialists with captive component supply, diversified machinery conglomerates with cross-sector leverage, and regional system integrators serving terrain-constrained municipalities. Consolidation pressures concentrate in aftermarket service unbundling, while technology licensing and backward integration into proprietary grip manufacturing represent dominant competitive vectors.
Within the European alpine specialist tier, Doppelmayr/Garaventa Group and Leitner S.p.A exemplify capability concentration through Italian and Austrian manufacturing bases. POMA Group occupies a position representing detachable grip technology leadership for high-capacity urban installations. Among Asia-Pacific fabricators, Nippon Cable Co., Ltd. anchors regional supply for industrial material transport applications. These three entities collectively illustrate how geographic origin and corporate structure correlate with strategic archetype positioning across recreational, urban, and industrial market vectors.
| Leading Market Players |
|---|
| Bartholet Maschinenbau AG |
| Nippon Cable Co., Ltd. |
| Doppelmayr/Garaventa Group |
| Conveyor & Ropeway Services Pvt. Ltd. |
| Damodar Ropeways & Infra Ltd |
| POMA Group |
| MND Group |
| Vergokan |
| Leitner S.p.A |
| Others |
Value Chain & Pricing Dynamics
Swiss-Austrian grip mechanism supply concentration determines both pricing tier spreads and supply chain shape, as precision-machined bullwheel assemblies from Tyrol and Bernese Oberland fabricators lock operators into manufacturer-captive service ecosystems with limited substitution options.
Pricing Analysis
Long-term offtake contracts dominate procurement for urban transit authorities in La Paz and Medellín, while ski resort operators in Colorado and Tyrol favor bundled equipment-service agreements with uptime guarantees. Pricing stratifies across premium OEM-captive, standard independent-service, and economy in-house maintenance tiers based on certification level and after-sales bundling. Cost compression in the economy tier is intensifying because Latin American municipalities unbundle maintenance from equipment purchase. Transportation authorities exhibit highest price sensitivity; tourism companies prioritize reliability over capital minimization.
Supply Chain Analysis
High-strength steel cable feedstock draws from Austrian and German metallurgical suppliers, while precision-machined grip components source from concentrated Swiss-Austrian Alpine fabricators. Copper for drive motor windings and synthetic-core cable materials hinge on commodity markets with volatile price exposure. Single-source vulnerability runs through proprietary Doppelmayr and Leitner grip technician certification networks. Distribution runs through OEM-direct channels for initial installation, fragmenting into independent service providers for mid-life overhaul work.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Urban congestion and last-mile connectivity gaps are disrupting municipal transit procurement, with EU Machinery Directive compliance deadlines creating a regulatory inflection that accelerates replacement cycles across aging alpine infrastructure.
For Market Incumbents: Entrench proprietary grip technology leadership through captive technician certification programs that constrain independent maintenance competition. Deepen backward integration into high-strength cable metallurgy to secure supply continuity against commodity volatility. Defend against aftermarket unbundling by embedding predictive maintenance sensors that lock operators into data-dependent service ecosystems. For New Entrants and Emerging Players: Establish a beachhead in Brazilian hillside urban corridors where Rio de Janeiro and similar municipalities lack integrated transit penetration. Target industrial material transport segments that prioritize standardized components over proprietary systems. Pursue white-label maintenance partnerships with Latin American transportation authorities seeking to separate capital expenditure from operating concessions. For Investors and Strategic Acquirers: The market sits at an equipment replacement phase that favors aftermarket service specialists with predictive maintenance capabilities. Long-term viability rests on digital twin convergence and condition-based servicing models that displace fixed-interval contracts. Monitor EU F-Gas Regulation compliance timelines as an inflection indicator for HVAC retrofit demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cable Metallurgy | Austrian and German steel suppliers anchor component cost control for Alpine OEMs. |
| Predictive Maintenance Platform Deployment | Vibration sensors on Colorado bullwheel bearings enable condition-based intervention models. |
| Urban Transit Concession Expansion | La Paz Mi Teleférico demonstrates terrain-constrained corridor viability at altitude extremes. |
| Low-GWP Refrigerant Retrofit Certification | EU F-Gas Regulation deadlines prioritize CO2 heat-pump cabin HVAC suppliers. |
| Independent Maintenance Provider Licensing | Medellín procurement unbundling fragments long-term revenue toward lowest-qualified bidders. |
Study Parameters
A spread of perspectives from ski resort operations directors, urban transit procurement officers, Alpine component fabricators, and aftermarket maintenance providers converged on the working assumptions. Primary fieldwork combined with secondary validation against EU Machinery Directive filings, FAA airspace coordination records, and customs data on steel cable imports. Bottom-up equipment installation tracking and top-down infrastructure expenditure analysis were triangulated to establish market sizing.
Demand-supply balance dynamics across the projection horizon were modeled through segmentation by product type, end user procurement authority, installation environment, and service contract structure. CAGRs were derived from replacement cycle analysis and urban expansion pipeline assessment. Forecast inputs incorporated EU regulatory compliance timelines, alpine resort capital expenditure surveys, and Latin American municipal budget allocations.
Stress conditions across copper and steel price volatility, certified technician availability, and airspace clearance timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on regulatory implementation pace and commodity market stability. Quarterly review of EU F-Gas Regulation enforcement actions and Brazilian federal infrastructure budget approvals is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infrastructure Construction
Thailand Data Center Construction Market
Infrastructure Construction
France Transportation Infrastructure Construction Market
Infrastructure Construction
Australia Transportation Infrastructure Construction Market
Infrastructure Construction
Global Rail Infrastructure Market
Infrastructure Construction
India Transportation Infrastructure Construction Market
Infrastructure Construction
Oil and Gas Pipeline Fabrication and Construction Market
Infrastructure Construction
Singapore Transportation Infrastructure Construction Market
Infrastructure Construction
China Transportation Infrastructure Construction Market
Infrastructure Construction
Vietnam Infrastructure Market
Infrastructure Construction
Qatar Infrastructure Sector Market
Infrastructure Construction
Docks Market
Infrastructure Construction
New Zealand Infrastructure Market
Infrastructure Construction
Mexico Data Center Construction Market
Infrastructure Construction
United States Transportation Infrastructure Construction Market
Infrastructure Construction
South America Repair and Rehabilitation Market
Infrastructure Construction
Latin America Data Center Construction Market