
 Heavy Equipment Training Simulator Market | 2026-2036
Heavy Equipment Training Simulator Market Size, Share, and Industry Trends Forecast 2026-2036
Heavy Equipment Training Simulator Market Insights
Aftermarket service revenue is rewriting how simulator vendors capture lifetime value from fleet operators. Komatsu Ltd. leverages its global dealer infrastructure to bundle training subscriptions with equipment maintenance contracts. CM Labs Simulations Inc. anchors its position in port and maritime simulation through physics-engine fidelity that competing platforms struggle to replicate. ThoroughTec Simulation specializes in military-grade earthmoving trainers, occupying a defensible niche with NATO procurement standards.
Heavy equipment training simulators replicate hydraulic, electrical, and mechanical behaviors of construction and mining machinery through real-time physics modeling, enabling operators to develop muscle memory without fuel consumption or accident risk. Excavator simulators dominate product-type revenue due to universal applicability across construction and mining fleets, while mixed-reality technology represents the fastest-expanding segment as hardware costs decline and fidelity improves. Training institutes constitute the most concentrated end-user margin pool, locking in multi-year curriculum contracts that equipment manufacturers seek to displace through direct-to-operator digital platforms.
OSHA mandates in the United States and EU machinery directives under CE marking frameworks compel documented operator competency, directly expanding addressable demand for certified simulation programs. ISO 18497 standards for autonomous machinery safety create additional specification layers that simulator vendors must embed to maintain market access. Stakeholders should monitor how regulatory convergence between occupational safety and autonomous equipment protocols reshapes certification requirements and procurement criteria.
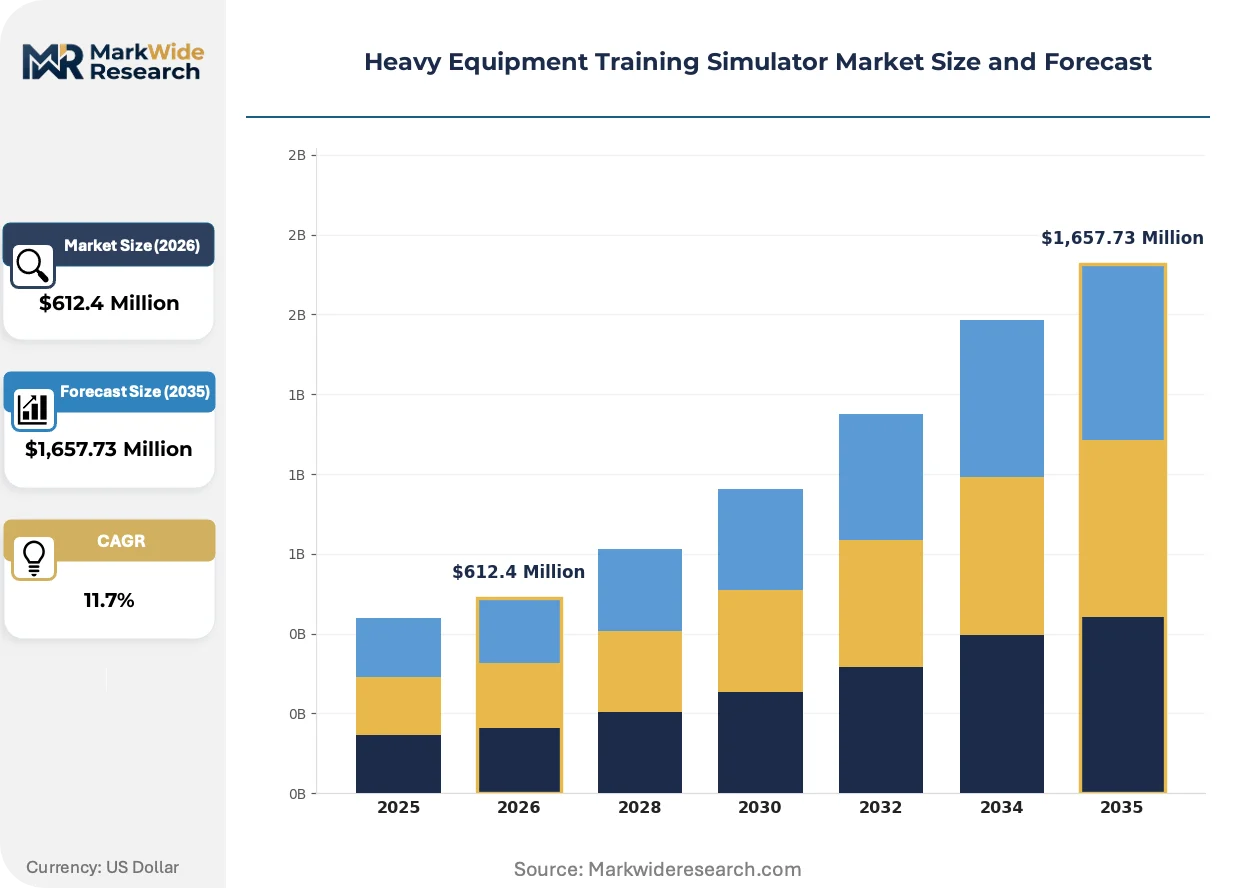
Market Dynamics
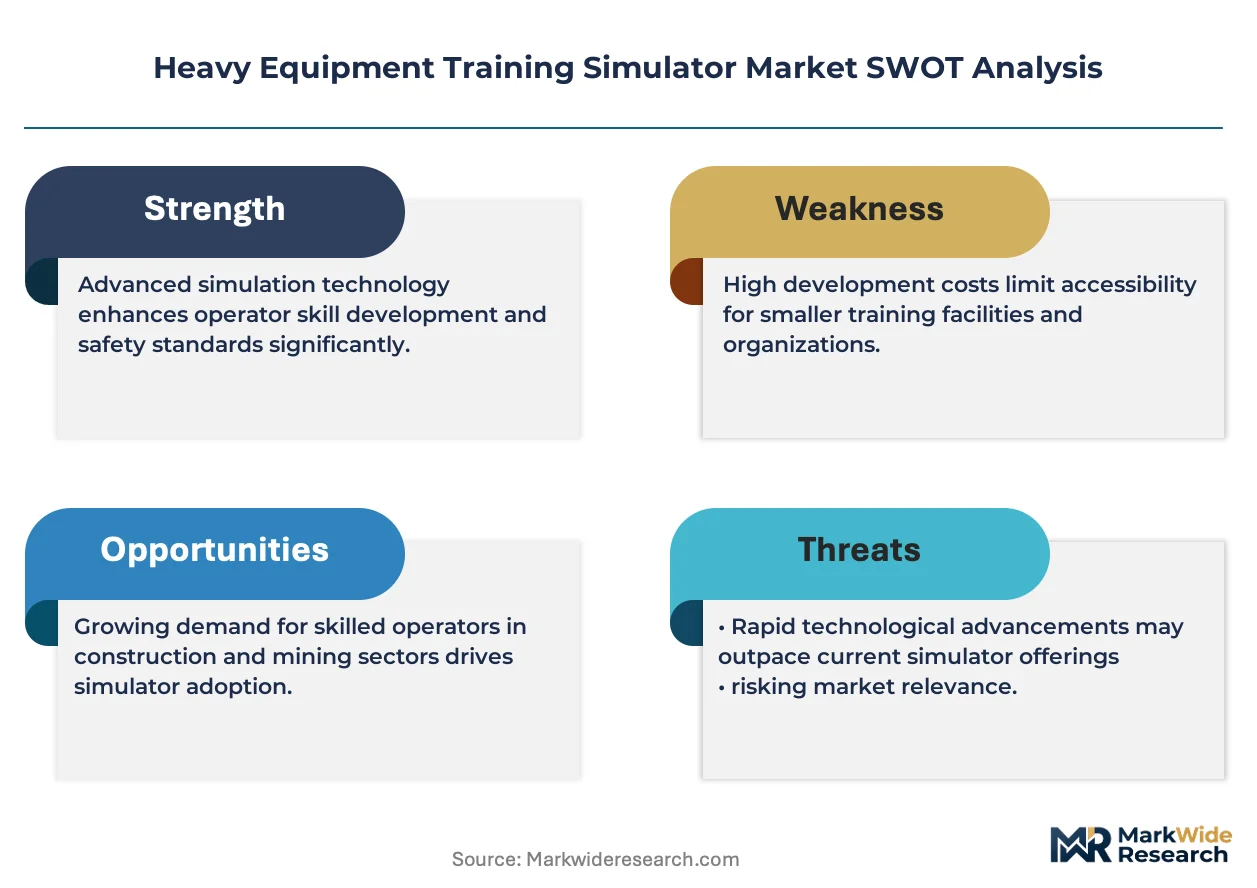
The heavy equipment training simulator market is restructuring around regulatory mandates that replace live-equipment certification with documented simulation-based competency. OSHA workplace safety directives and EU machinery directives under CE marking frameworks are forcing fleet operators to adopt certified training platforms.
Growth Catalysts
- OSHA Mandates:United States workplace safety regulations now require documented operator competency for heavy machinery, directly expanding procurement of certified simulation programs by construction and mining fleets.
- EU Machinery Directives:CE marking frameworks compel European equipment operators to demonstrate validated training records, accelerating replacement of traditional live-equipment instruction with simulator-based certification.
- Mixed-Reality Hardware Cost Decline:Falling prices for VR headsets and haptic feedback systems are enabling training institutes to deploy high-fidelity excavator and haul truck simulators at scale.
Market Restraints
- Capital Intensity:Full-motion simulator platforms require substantial upfront investment in hydraulic actuators and projection systems, limiting adoption among small independent training providers.
- Physics Engine Fidelity Gaps:Current software struggles to replicate soil compaction dynamics and hydraulic lag in extreme temperature conditions, reducing transfer validity for Arctic and desert mining operations.
- Certification Fragmentation:Divergent national standards for simulator-based operator licensing create compliance complexity for multinational equipment OEMs deploying unified training curricula.
Strategic Opportunities
- Autonomous Machinery Convergence:ISO 18497 safety standards for self-operating equipment create specification layers that simulator vendors can embed to capture emerging autonomous fleet training demand.
- Aftermarket Service Bundling:Equipment manufacturers can integrate training subscriptions into maintenance contracts, displacing independent training institutes through direct-to-operator digital platforms.
- Military-Grade Simulation Export:NATO procurement standards for earthmoving trainers present defensible niche opportunities in defense-adjacent markets with stringent fidelity requirements.
Industry Challenges
- Curriculum Integration Complexity:Training institutes face technical hurdles embedding simulator modules into existing instructor-led programs without disrupting established certification timelines.
- Multi-Site Deployment Friction:Fleet operators struggle to synchronize training records across decentralized operations, complicating audit trails for regulatory compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heavy Equipment Training Simulator Market |
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,657.73 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Excavator Simulators, Crane Simulators, Bulldozer Simulators, Forklift Simulators, Grader Simulators Technology: Virtual Reality, Augmented Reality, Mixed Reality, 3D Visualization, Motion Capture Application: Construction Sites, Mining Operations, Agriculture, Forestry, Maritime End User: Training Institutes, Equipment Manufacturers, Safety Organizations, Military Units, Commercial Operators |
| Companies Covered | Komatsu Ltd., Volvo Construction Equipment, CM Labs Simulations Inc., ThoroughTec Simulation, Liebherr Group, Caterpillar Inc., Hitachi Construction Machinery, Tenstar Simulation AB, John Deere, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heavy Equipment Training Simulator Market Trends and Innovations
Real-time physics modeling is compressing the gap between simulated and actual equipment response, enabling muscle memory development without fuel consumption or accident exposure. Three developments are actively reshaping competitive positioning.
Haptic feedback systems with force-replicating control loaders are virtualizing the tactile experience of hydraulic resistance and bucket penetration. Mining operators in Australia and Chile are deploying these platforms at accelerating pace to certify operators for autonomous haulage environments. This virtualization is compressing training duration while maintaining transfer validity to live equipment.
EU machinery directives under CE marking frameworks now mandate documented competency verification for construction equipment operators. The industrial consequence is procurement preference for simulators with embedded audit trails and standardized assessment protocols. European training institutes are responding by retrofitting legacy platforms with compliance-tracking software modules.
Subscription-based training delivery is displacing perpetual license purchases among fleet operators seeking operational flexibility. Equipment OEM dealer networks are capturing this shift through bundled hardware-software-service contracts that lock in multi-year revenue streams. This pattern concentrates in North American construction markets where capital expenditure scrutiny is intensifying.
Heavy Equipment Training Simulator Market Segmentation
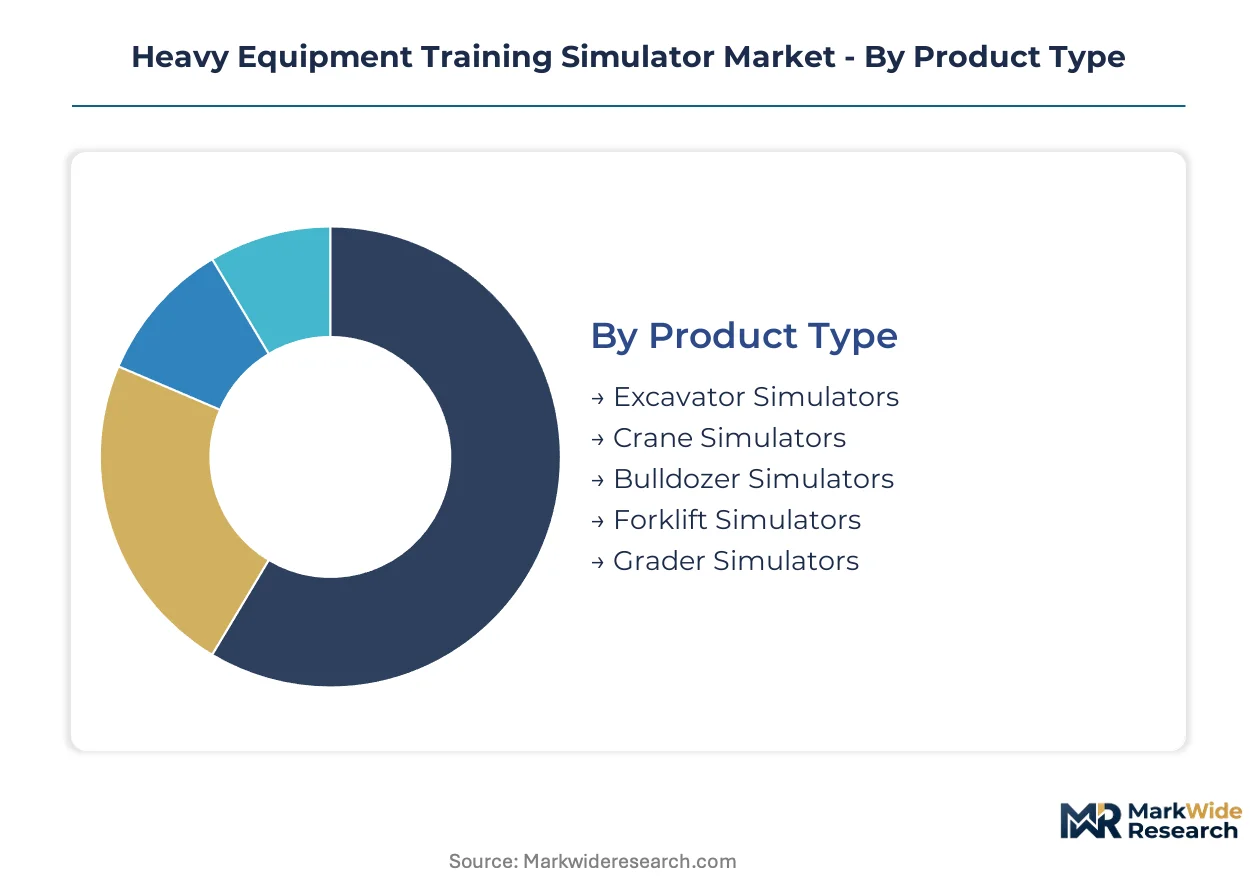
Segmentation in heavy equipment training simulators reveals distinct procurement patterns across machinery types, immersive technologies, and operator certification pathways. Equipment OEMs and training institutes prioritize different performance specifications, creating tiered demand structures that vendors must navigate.
Product Type:
Use-case spectrum spans earthmoving precision tasks, vertical lifting operations, and surface grading applications across construction and extractive industries.
- Excavator Simulators:Hydraulic articulation systems replicate bucket penetration resistance and boom positioning with force-feedback controls. Australian mining operators deploy these platforms at scale for autonomous haulage environment certification, driven by surface extraction safety mandates.
- Crane Simulators:Load moment indicators and anti-two-block systems simulate lifting dynamics across lattice boom and tower configurations. European construction firms prioritize these for urban density projects where CE marking compliance requires documented load handling competency.
- Bulldozer Simulators:Track traction modeling and blade force distribution for grading operations.
- Forklift Simulators:Warehouse maneuvering and pallet stability scenarios for logistics certification.
- Grader Simulators:Road surface precision control with moldboard angle calibration.
Established volume favors excavator platforms; emerging adoption favors crane configurations.
Technology:
Cost tier differentiation separates enterprise-grade immersive systems from entry-level visualization tools.
- Virtual Reality:Head-mounted displays with six-degrees-of-freedom tracking isolate operators in fully synthetic environments. Training institutes in the United States adopt these for OSHA-compliant certification programs where documented competency trails are mandatory.
- Mixed Reality:Passthrough cameras overlay digital equipment controls onto physical cabin replicas, preserving spatial awareness. Mining operators in Chile deploy these for haul truck transition training, climbing fastest as hardware costs decline.
- Augmented Reality:Tablet-based overlays for maintenance and operational guidance.
- 3D Visualization:Projection-based surround displays for classroom instruction.
- Motion Capture:Optical tracking for biomechanical analysis of operator posture.
Procurement concentrates in virtual reality for volume deployments; mixed reality captures premium expansion.
Application:
Customer type segmentation aligns with regulatory intensity and accident liability exposure across verticals.
- Mining Operations:Autonomous haulage integration and pit stability scenarios dominate specification requirements. Australian operators mandate simulator hours before live equipment access, driven by surface extraction fatality reduction targets.
- Construction Sites:Urban density constraints and utility strike avoidance shape curriculum design. OSHA workplace safety directives in the United States compel documented training records for crane and excavation work.
- Agriculture:Harvest timing and terrain adaptability for seasonal operator pools.
- Forestry:Slope stability and load securement for mechanized logging.
- Maritime:Port container handling and vessel stability for deck machinery.
Mining commands the steepest expansion trajectory; construction maintains the deepest installed base.
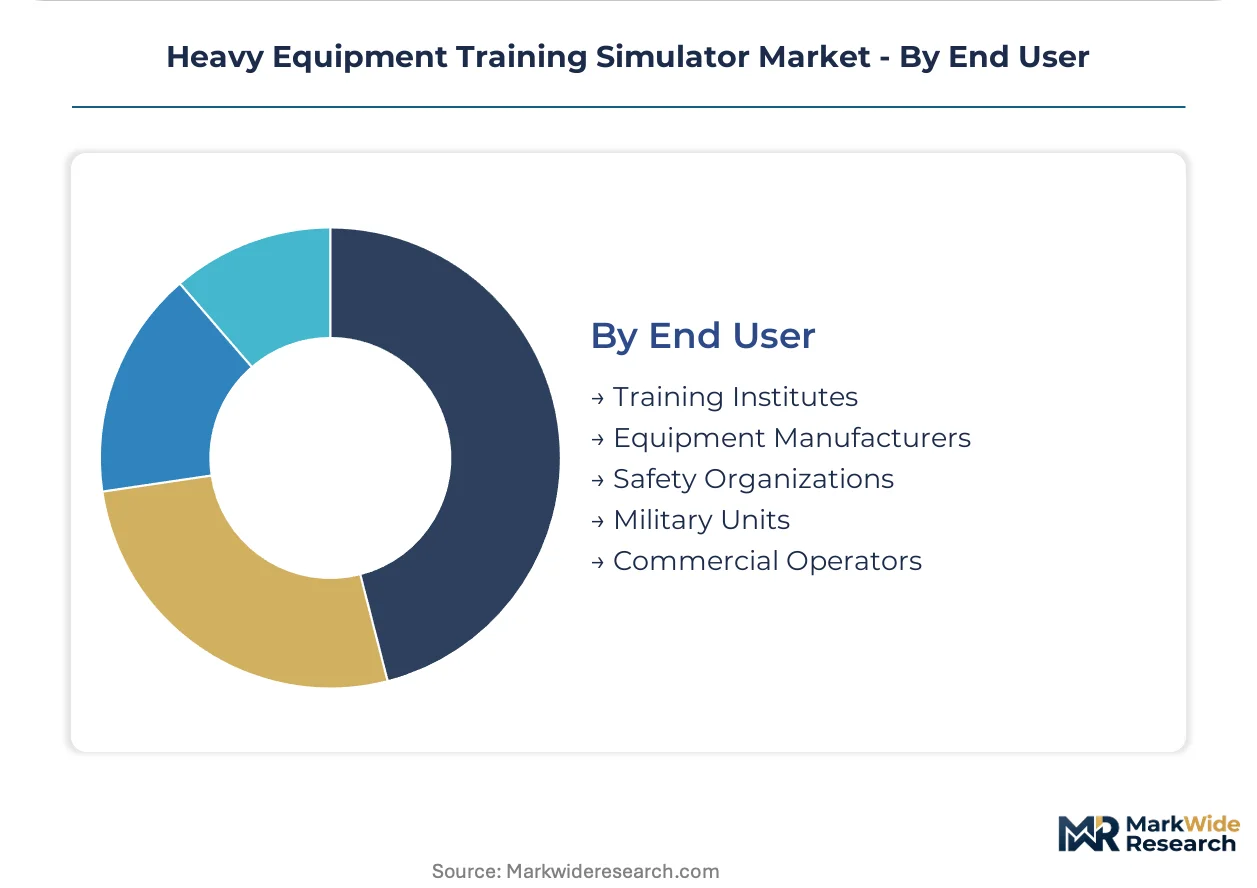
End User:
Margin concentration varies by contract duration and customization requirements across purchaser categories.
- Training Institutes:Multi-year curriculum contracts with certification body accreditation requirements lock in recurring revenue. These entities prioritize physics engine fidelity and assessment standardization to maintain regulatory approval.
- Equipment Manufacturers:Dealer network integration and aftermarket service bundling displace independent providers. OEMs embed training subscriptions within maintenance contracts, capturing direct-to-operator relationships.
- Safety Organizations:Audit trail capabilities and compliance reporting for regulatory verification.
- Military Units:NATO procurement standards for earthmoving and obstacle clearance operations.
- Commercial Operators:Fleet-specific customization and decentralized deployment needs.
Training institutes anchor current revenue; equipment manufacturers are capturing future share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Simulator deployment patterns diverge sharply by geography. Australian mining operators prioritize autonomous haulage certification, while European construction firms emphasize CE-marked compliance documentation. North American OEM dealer networks bundle training subscriptions with equipment sales.
United States
Construction equipment OEMs dominate simulator procurement through integrated dealer networks. OSHA workplace safety mandates require documented operator competency for heavy machinery, compelling fleet operators to adopt certified simulation platforms. Texas and California anchor demand concentration, with Houston-based energy contractors deploying haul truck simulators for Permian Basin operations.
Australia
Surface mining operators mandate simulator hours before live equipment access, driven by fatality reduction targets in Queensland and Western Australia. The country's national workplace safety regulator enforces stringent training documentation requirements. Pilbara region iron ore producers deploy mixed-reality platforms at scale for autonomous haulage environment certification.
Germany
CE marking frameworks under EU machinery directives compel equipment operators to demonstrate validated training records. Bavaria and North Rhine-Westphalia concentrate demand among construction machinery manufacturers integrating simulation into dealer service contracts. Munich-based OEMs lead bundling strategies that displace independent training institutes.
Chile
Copper mining operations in the Atacama Desert drive demand for high-fidelity excavator and haul truck simulators. The country's mining regulator requires competency verification for open-pit equipment operators. Antofagasta region producers deploy mixed-reality platforms for extreme altitude and temperature condition training.
China
Infrastructure construction stimulus expands demand for cost-optimized simulator platforms across provincial training centers. The Ministry of Industry and Information Technology promotes domestic equipment certification standards. Yangtze River Delta construction machinery clusters integrate simulation modules into operator licensing programs.
Heavy Equipment Training Simulator Market Competitive Landscape
Capability concentration sits with specialized physics-engine developers; scale advantage sits with diversified equipment OEMs. The market structures around three tiers: integrated machinery manufacturers with captive training divisions, independent simulation specialists with proprietary software cores, and regional system integrators serving price-sensitive training institutes. Strategic moves concentrate on aftermarket service bundling and regulatory compliance module development.
Among Japanese and Swedish machinery manufacturers, Komatsu Ltd. and Volvo Construction Equipment exemplify the OEM-integrated archetype with global dealer infrastructure. CM Labs Simulations Inc. and ThoroughTec Simulation occupy the specialist tier, anchoring positions in port maritime and military-grade earthmoving segments respectively. These four represent distinct competitive vectors: bundled hardware-software-service contracts versus standalone physics-engine licensing.
| Leading Market Players |
|---|
| Komatsu Ltd. |
| Volvo Construction Equipment |
| CM Labs Simulations Inc. |
| ThoroughTec Simulation |
| Liebherr Group |
| Caterpillar Inc. |
| Hitachi Construction Machinery |
| Tenstar Simulation AB |
| John Deere |
| Others |
Pricing and Supply Chain Analysis
Single-source dependency on Taiwanese haptic actuator manufacturers determines both pricing tier spreads and supply chain shape, compressing margins for mid-tier simulator vendors while premium OEMs secure allocation through long-term offtake commitments.
Pricing Analysis
Long-term bundled contracts dominate procurement, with equipment OEMs locking in multi-year hardware-software-service subscriptions that displace spot purchases by independent training institutes. Price differentiation hinges on physics engine fidelity certification and ISO 18497 autonomous machinery compliance tier, with premium vendors commanding substantial markups for NATO-standard military-grade configurations. Cost compression in the standard tier intensifies as Chinese motion platform suppliers enter European markets. Training institutes exhibit the highest price sensitivity, while mining operators in Australia and Chile prioritize transfer validity over unit economics.
Supply Chain Analysis
Extended payment terms from European training institutes are forcing Taiwanese haptic component suppliers and German hydraulic actuator manufacturers to absorb working capital strain. Manufacturing concentrates in Taiwan for force-feedback systems, Germany for precision hydraulics, and the United States for software cores. Raw material dependencies span rare earth magnets for servo motors, high-grade steel for motion bases, and specialized optical sensors for tracking systems. Tariff exposure on Chinese-sourced VR headsets creates procurement volatility for cost-optimized deployments. Distribution runs through OEM dealer networks and direct-to-operator digital platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Physics engine development talent scarcity constrains vendor expansion, with fewer than a dozen firms globally capable of replicating soil compaction dynamics at certification-grade fidelity.
For Market Incumbents: Build switching-cost moats through embedded compliance-tracking modules that lock training records into OEM maintenance ecosystems. Komatsu and Volvo Construction Equipment should deepen backward integration into haptic control loader production to insulate against Taiwanese supply constraints. Anchor dealer networks with multi-year curriculum subscriptions that independent institutes cannot match on price or audit trail depth. For New Entrants and Emerging Players: Latin American mining corridors present the most penetrable white space, with Chilean copper operators expanding simulator mandates faster than local supply can satisfy. Target mixed-reality haul truck configurations for the Antofagasta region's extreme altitude training requirements. Enter through partnerships with established port logistics specialists rather than direct OEM competition. For Investors and Strategic Acquirers: Specialist physics-engine developers with NATO certification credentials represent the most defensible acquisition archetype, given procurement standard stickiness in defense-adjacent markets. Monitor ISO 18497 autonomous machinery safety standard adoption rates as the primary inflection signal for simulator specification layering. Long-term viability rests on regulatory convergence between occupational safety and self-operating equipment protocols.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Haptic Component Manufacturing | Komatsu and Volvo Construction Equipment reduce exposure to Taiwanese supply constraints while capturing margin from force-feedback control loaders. |
| ISO 18497 Compliance Module Development | Simulator vendors embed autonomous machinery safety specifications to capture emerging fleet training demand from Australian and Chilean mining operators. |
| Dealer Network Training Subscription Bundling | Equipment OEMs displace independent training institutes through direct-to-operator digital platforms with embedded maintenance contract lock-in. |
| Mixed-Reality Hardware Cost Optimization | Falling VR headset and passthrough camera prices enable scaled deployment of premium immersive platforms across decentralized mining operations. |
| NATO Procurement Standard Certification | ThoroughTec Simulation and military-grade specialists secure defensible niche positioning in defense-adjacent earthmoving trainer markets. |
Research Methodology
Initial hypotheses were tested against primary input from simulator platform engineers, mining safety officers, training institute curriculum directors, and OEM aftermarket service heads, then refined through secondary validation against SEC filings from construction equipment manufacturers, EU machinery directive compliance databases, and Australian workplace safety regulator training documentation. Bottom-up triangulation across deployment volume estimates and top-down reconciliation with equipment fleet expansion projections anchored market sizing.
Demand-supply-balance framing structured the analytical approach across the analysis window, with segmentation modeling across machinery type, immersive technology tier, end-user category, and regional regulatory cluster. CAGRs were derived from equipment replacement cycle analysis and simulator penetration rate trajectories in mandatory-certification jurisdictions. Physics engine fidelity benchmarks and autonomous haulage adoption curves served as industry-specific forecast inputs.
Practitioners should monitor regulatory divergence between OSHA workplace safety mandates and EU machinery directive enforcement intensity for early signals of procurement pattern shifts. Forecasts reflect assumptions regarding hardware cost decline trajectories and certification standard harmonization. Macroeconomic contraction in mining capital expenditure, regulatory rollback on operator competency documentation, or breakthrough advances in live-equipment remote operation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Services
Testing, Inspection, and Certification for Construction Market
Construction Services
Europe Maintenance, Repair, and Operations (MRO) Market
Construction Services
3D Concrete Printing Services Market
Construction Services
North and Latin America Weatherization Services Market
Construction Services
NDT and Inspection Market
Construction Services
Work Order Management Market
Construction Services
Construction Materials Testing Equipment Market
Construction Services
Forklift Repair and Maintenance Service Market
Construction Services
MENA Architectural Services Market
Construction Services
Die Casting Services Market
Construction Services
Excavating Contractor Market
Construction Services
North America Repair and Rehabilitation Market
Construction Services
Facade Cleaning and Maintenance Service Market
Construction Services
Grease Trap Service Market
Construction Services
North America Testing and Commissioning Market
Construction Services
Gutter Cleaning Services Market