
 Testing, Inspection, and Certification for Construction Market | 2026-2036
Testing, Inspection, and Certification for Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Testing, Inspection, and Certification for Construction Market Insights
Performance-based seismic design certification is redrawing procurement priorities for engineering consultancies across high-risk zones. SGS leverages its network of accredited materials laboratories to anchor large-scale infrastructure contracts in Latin America. Bureau Veritas competes through specialized environmental testing protocols for green building portfolios. Intertek Group differentiates via digital inspection platforms that compress reporting cycles for government agencies.
Testing, inspection, and certification for construction encompasses systematic evaluation of building materials, structural assemblies, and completed works against codified safety and performance benchmarks, typically involving compressive strength testing of concrete specimens, non-destructive ultrasonic scanning of welds, and thermal imaging of building envelopes to verify energy performance. The practice ensures life-safety compliance, warranty validity, and insurance eligibility across commercial, residential, and civil infrastructure assets. Quality control services command the deepest margin pools where repeat contractor relationships reduce client acquisition costs, while environmental testing grows fastest as LEED Certification and national carbon disclosure rules tighten material sourcing requirements. Structural integrity assessment remains the most mature test type, though soil testing gains share where permafrost thaw and coastal erosion alter foundation design assumptions.
ISO 9001 accreditation serves as a baseline market-access filter, while CE Marking governs product conformity for equipment and component suppliers serving European construction firms. The US EPA and OSHA jointly shape environmental testing and worker safety inspection demand through enforceable exposure limits and site remediation protocols. ASTM Standards provide the technical substrate for material specification disputes in North American commercial arbitration. Stakeholders must monitor how building code harmonization between national standards bodies and the IEC framework alters cross-border certification reciprocity.
Market Dynamics
Performance-based seismic design mandates are compressing contractor procurement cycles and elevating third-party certification from procedural checkbox to pre-qualification gate for infrastructure awards across high-risk zones.
Growth Catalysts
- Seismic code tightening in Japan:METI-mandated structural reassessment protocols for existing commercial buildings are generating recurring inspection contracts for engineering consultancies.
- LEED v4.1 material transparency requirements:Environmental product declarations now govern specification decisions for curtain wall and concrete suppliers in North American commercial development.
- Smart city infrastructure corridors in India:CEA-mandated quality assurance for transmission substations and metro viaducts is concentrating TIC spend in designated urban agglomerations.
Market Restraints
- Accredited laboratory capacity constraints:ISO/IEC 17025-certified facilities for fire resistance testing remain concentrated in Germany, Japan, and the United States, creating cross-border logistics friction.
- Skilled technician scarcity:Certified welding inspectors and geotechnical engineers command premium compensation, compressing margins on fixed-price municipal contracts.
- CE Marking harmonization delays:Divergent national interpretations of Construction Products Regulation test methods fragment certification reciprocity across EU member states.
Strategic Opportunities
- Digital twin integration for asset monitoring:Convergence of IoT sensor networks with BIM platforms enables continuous structural health monitoring subscriptions replacing episodic inspection.
- Green hydrogen facility construction:Specialized pressure vessel and pipeline testing protocols for electrolyzer plants represent unpenetrated service expansion beyond traditional building codes.
- Modular construction quality assurance:Factory-based prefabrication shifts inspection locus from job site to manufacturing floor, opening accredited laboratory partnerships with offsite producers.
Industry Challenges
- Multi-standard compliance complexity:Projects requiring simultaneous ASTM, EN, and JIS material certification create documentation bottlenecks and arbitration exposure.
- Legacy equipment calibration backlogs:Ultrasonic and radiographic testing devices require traceable recertification cycles that strain field deployment schedules.
- Data interoperability gaps:Proprietary digital inspection platforms resist integration with client ERP systems, forcing manual report transcription.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Testing, Inspection, and Certification for Construction Market |
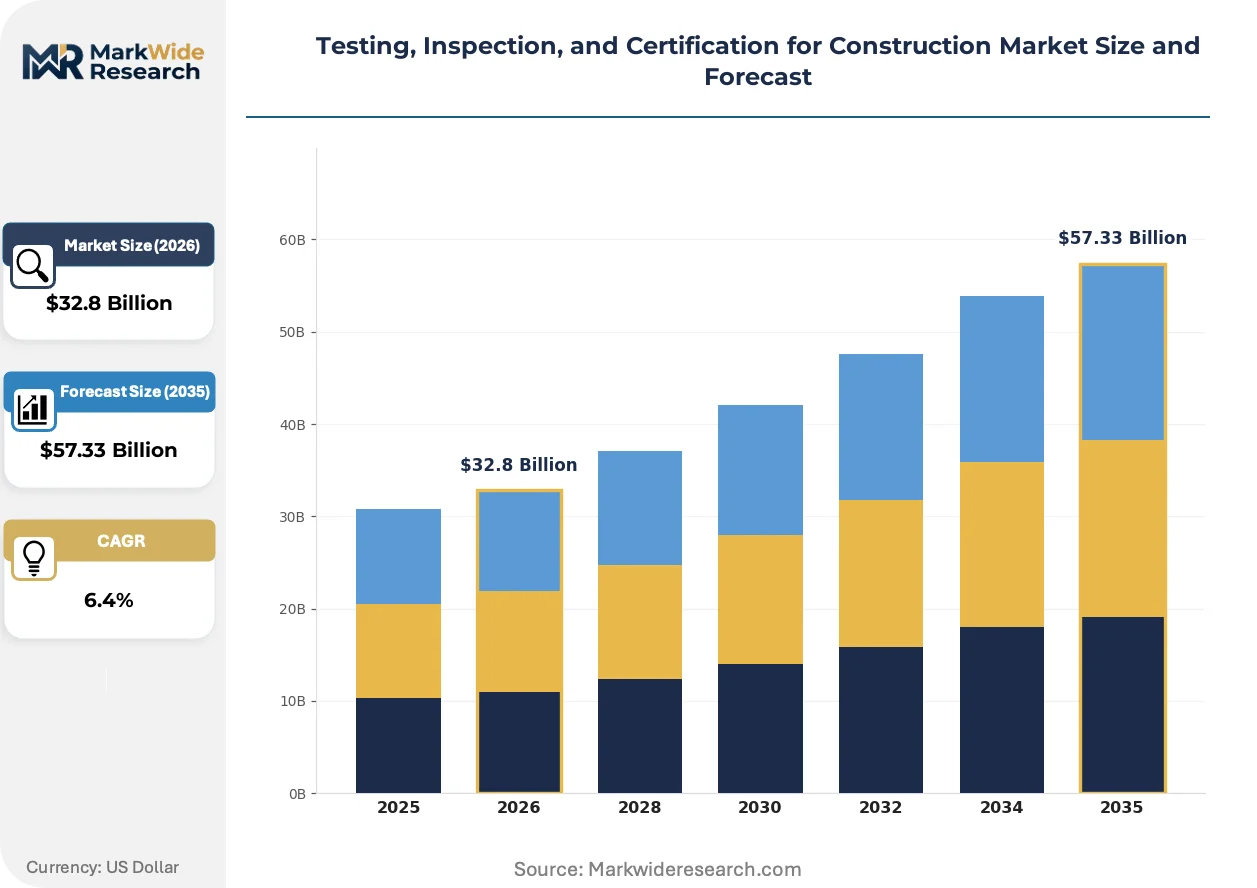
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $57.33 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Quality Control, Safety Inspection, Environmental Testing, Compliance Verification End User: Construction Firms, Government Agencies, Property Developers, Engineering Consultants Test Type: Material Testing, Structural Integrity Assessment, Soil Testing, Equipment Inspection Certification Standard: ISO 9001, ASTM Standards, CE Marking, LEED Certification |
| Companies Covered | TÜV Rheinland, Kiwa, SGS, UL Solutions, Eurofins Expert Services, Bureau Veritas, TÜV SÜD, BSI Group, Intertek Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Testing, Inspection, and Certification for Construction Market Trends and Innovations
Digital inspection platforms and automated material characterization are compressing reporting cycles while fragmenting service delivery between centralized laboratories and distributed field deployment.
Drone-mounted photogrammetry and LiDAR scanning for structural deformation monitoring is bifurcating the market between high-precision metrology providers and commodity visual inspection services. Large-scale infrastructure operators in Turkey and Chile are adopting continuous monitoring subscriptions. The technology is compressing traditional surveyor roles while expanding data analytics specialization within engineering consultancies.
EU CSRD scope expansion to construction value chains is mandating embodied carbon disclosure for concrete, steel, and aluminum inputs. ECHA-aligned environmental testing protocols are becoming specification gatekeepers for public procurement. Material suppliers serving German and French commercial developers are accelerating EPD acquisition to maintain specification status.
Owner-operators in Southeast Asian high-rise markets are unbundling quality assurance from general contractor retainers and contracting directly with accredited TIC firms. Direct procurement of structural integrity assessment compresses conflict-of-interest exposure in developer-contractor relationships. Singapore and Bangkok commercial towers are exhibiting the most pronounced shift toward independent third-party verification.
Testing, Inspection, and Certification for Construction Market Segmentation
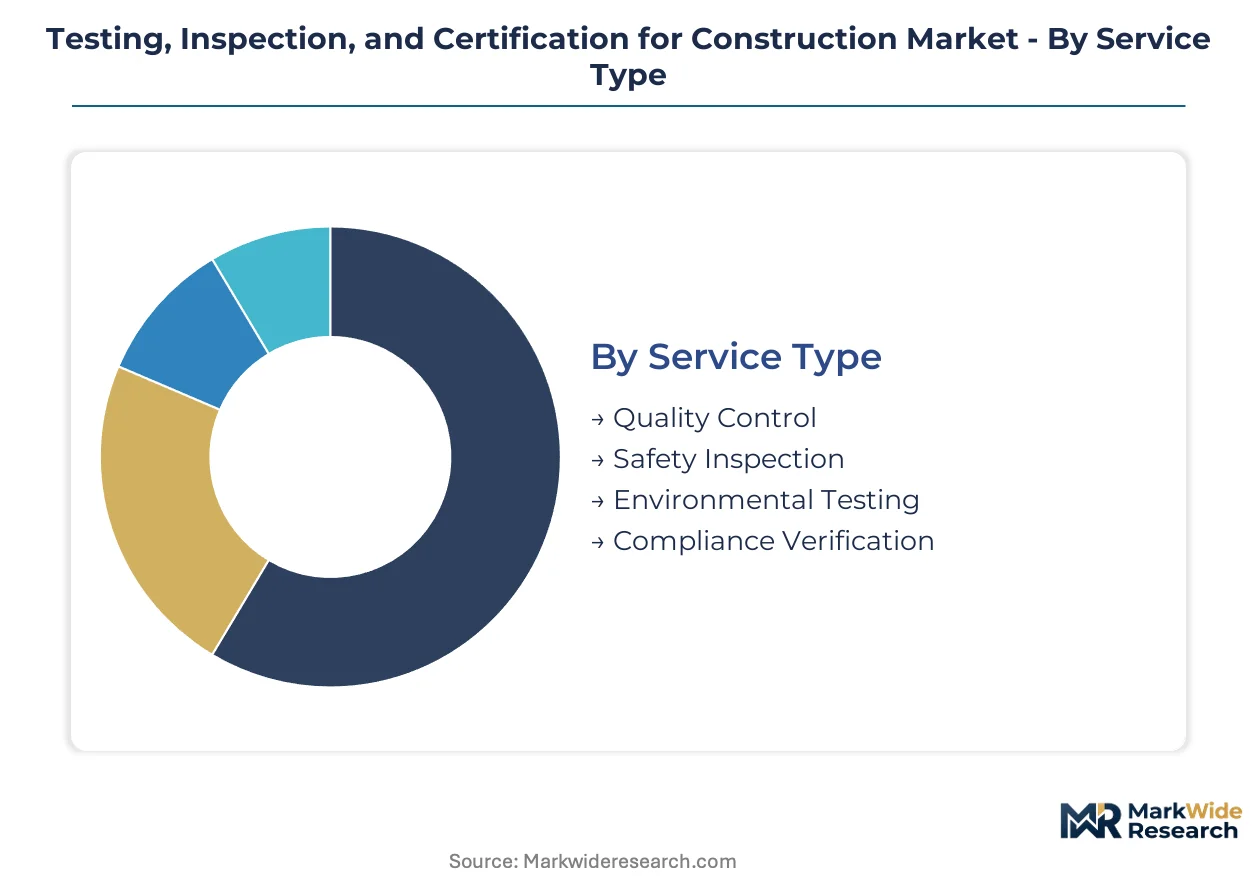
Segmentation in construction TIC reveals how service delivery fragments across project phases and regulatory jurisdictions. Understanding these divides exposes where margin pools concentrate and which certification protocols create switching costs for clients.
Service Type:
Quality control services face the strongest substitution pressure from contractor self-certification programs, while specialized environmental testing maintains defensible positioning through regulatory complexity.
- Quality Control:Systematic verification of concrete compressive strength, weld penetration, and dimensional tolerances against specification drawings. Demand concentrates in India's smart city corridors where CEA-mandated quality assurance for transmission infrastructure requires third-party witnessing. Quality control anchors the volume base while environmental testing gains share at the steepest rate.
- Safety Inspection:Site audits for fall protection, excavation stability, and heavy equipment operator certification per OSHA or national equivalents. Japanese METI-mandated structural reassessment protocols generate recurring contracts for commercial building portfolios in Tokyo and Osaka.
- Environmental Testing:Material sourcing verification for embodied carbon disclosure, soil contamination screening, and indoor air quality assessment. EU CSRD scope expansion to construction value chains mandates EPD acquisition for concrete and steel suppliers.
- Compliance Verification:Documentation audit for building code adherence, fire resistance rating confirmation, and accessibility standard certification. Turkish seismic code tightening elevates third-party verification from procedural checkbox to pre-qualification gate for public contracts.
Quality control anchors the volume base while environmental testing gains share at the steepest rate.
End User:
Cost tier segmentation separates price-sensitive municipal procurement from premium private sector contracts where liability exposure justifies comprehensive testing scope.
- Construction Firms:General contractors procuring TIC services to satisfy bond underwriters and warranty terms. Southeast Asian high-rise developers increasingly unbundle quality assurance from GC retainers to contract directly with accredited firms.
- Government Agencies:Public works departments mandating third-party verification for infrastructure awards. Brazil's ANVISA-aligned protocols for hospital construction and Chile's public works ministry requirements concentrate demand in Latin American metropolitan corridors.
- Property Developers:Owner-operators seeking insurance eligibility and LEED certification for commercial portfolios. Singapore and Bangkok commercial towers exhibit pronounced shift toward independent structural integrity assessment.
- Engineering Consultants:Design firms outsourcing specialized testing to maintain ISO 17025 accreditation without capital investment in laboratory infrastructure. SGS and Bureau Veritas anchor large-scale infrastructure contracts through accredited materials laboratory networks.
Construction firms generate the highest transaction frequency while government agencies command the longest contract tenures.
Test Type:
Volume concentration in mature structural assessment services contrasts with emerging demand for geotechnical testing where climate-altered foundation design assumptions reshape procurement.
- Material Testing:Destructive and non-destructive evaluation of concrete, steel, and composite specimens against ASTM, EN, or JIS specifications. German and French commercial developers accelerate EPD acquisition to maintain specification status under tightening carbon disclosure rules.
- Structural Integrity Assessment:Load testing, vibration analysis, and seismic performance verification for completed or existing structures. Japan's METI-mandated reassessment protocols for commercial buildings sustain recurring inspection demand.
- Soil Testing:Geotechnical investigation for bearing capacity, liquefaction potential, and permafrost stability. Permafrost thaw and coastal erosion in northern latitudes alter foundation design assumptions and expand testing scope.
- Equipment Inspection:Crane, hoist, and concrete pump certification for safe operation compliance. Green hydrogen facility construction creates specialized pressure vessel and pipeline testing protocols beyond traditional building codes.
Structural integrity assessment maintains the largest revenue base while soil testing climbs the fastest on climate adaptation spending.
Certification Standard:
Customer type segmentation separates baseline market-access accreditation from premium differentiation through specialized environmental or seismic protocols.
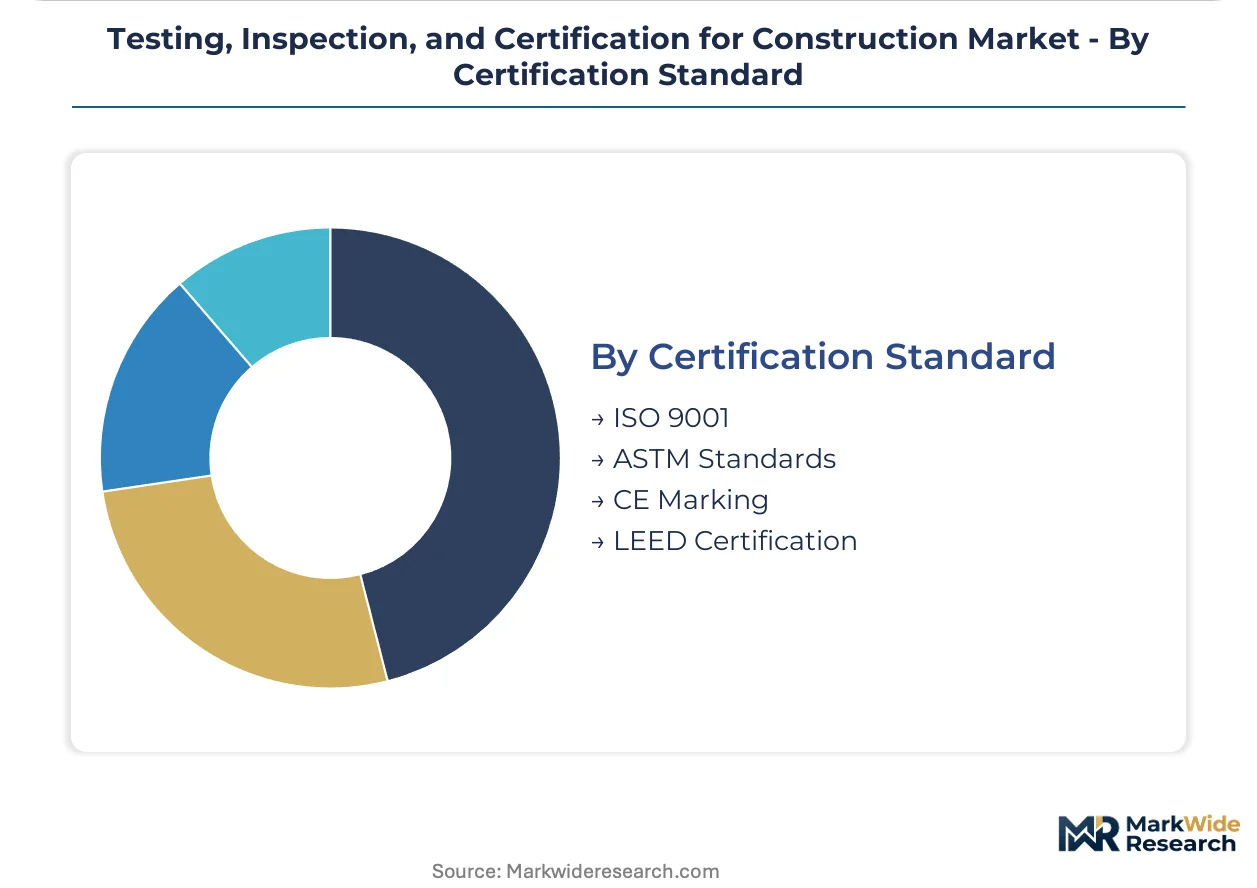
- ISO 9001:Quality management system accreditation serving as baseline filter for contractor pre-qualification. ISO 9001 anchors procurement minimums while LEED Certification commands the steepest price premiums.
- ASTM Standards:North American material specification substrate governing commercial arbitration and insurance eligibility. ASTM protocols dominate US and Canadian commercial development disputes.
- CE Marking:European Construction Products Regulation conformity for equipment and component suppliers. Divergent national interpretations fragment certification reciprocity across EU member states.
- LEED Certification:Green building performance verification for energy efficiency, water conservation, and material transparency. LEED v4.1 material transparency requirements govern specification decisions for curtain wall and concrete suppliers.
ISO 9001 anchors procurement minimums while LEED Certification commands the steepest price premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade surpluses in European testing equipment and deficits in Southeast Asian laboratory capacity are reshaping cross-border service procurement patterns. Capital flows toward accreditation infrastructure in high-growth construction corridors while mature markets export technical expertise.
United States
Commercial high-rise development in Miami and Los Angeles drives structural integrity assessment demand. EPA and OSHA jointly enforce environmental testing and worker safety inspection protocols through binding exposure limits. ASTM Standards govern material specification disputes in arbitration across Texas and California metropolitan construction clusters.
Germany
Fire resistance testing capacity concentrates in ISO/IEC 17025-certified facilities serving cross-border EU demand. ECHA-aligned environmental testing protocols gatekeep public procurement under CSRD scope expansion. Berlin and Munich commercial developers accelerate EPD acquisition to maintain specification status for concrete and steel inputs.
Japan
METI-mandated structural reassessment protocols for existing commercial buildings generate recurring inspection contracts. Seismic code tightening in Tokyo and Osaka reshapes contractor procurement cycles. Engineering consultancies in the Kanto corridor anchor performance-based design certification services.
India
Smart city infrastructure corridors concentrate TIC spend in designated urban agglomerations. CEA-mandated quality assurance for transmission substations and metro viaducts elevates third-party verification requirements. Ahmedabad and Hyderabad construction clusters exhibit direct procurement of structural assessment from accredited firms.
Brazil
ANVISA-aligned protocols for hospital construction concentrate demand in São Paulo and Rio de Janeiro metropolitan corridors. Public works ministry requirements shape municipal procurement patterns. Latin American infrastructure contracts anchor large-scale accredited laboratory networks serving cross-border projects.
Testing, Inspection, and Certification for Construction Market Competitive Landscape
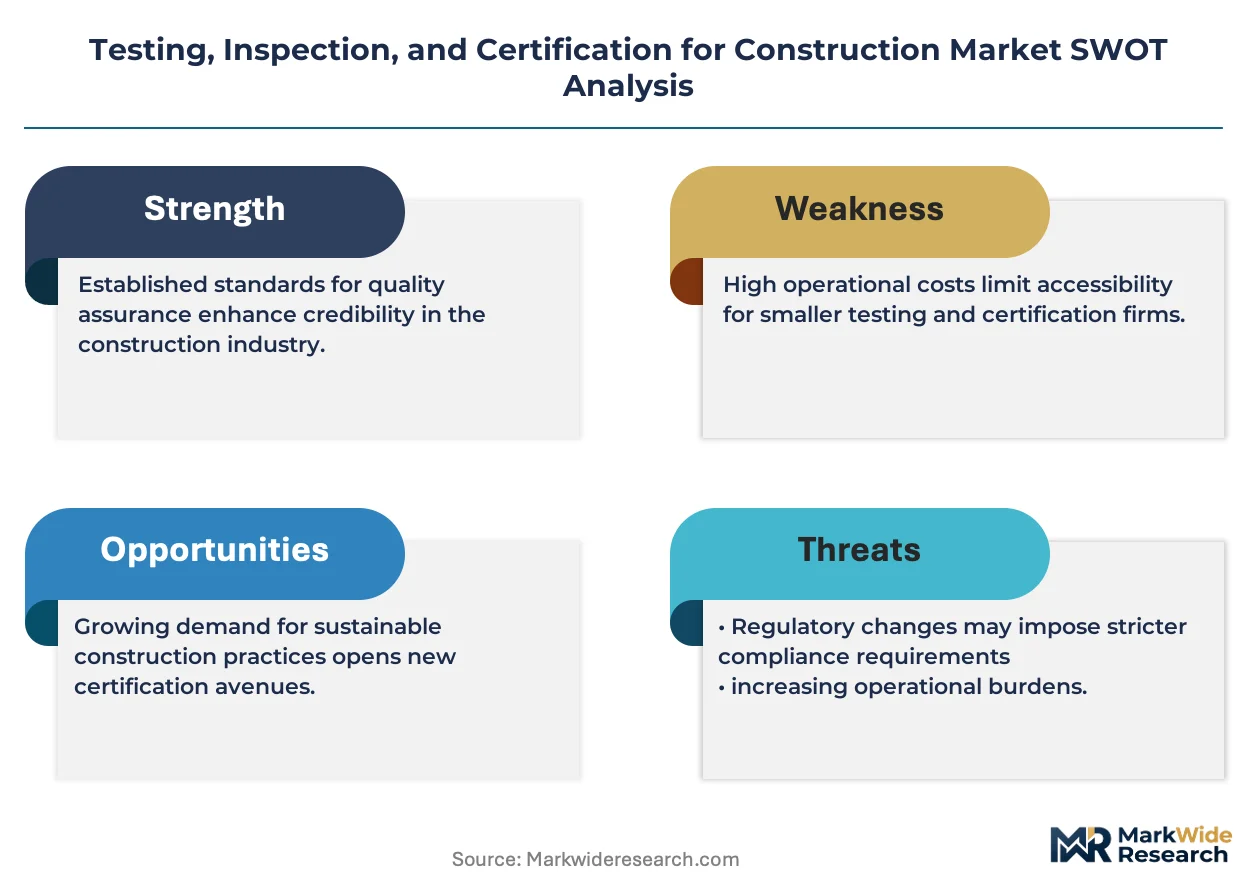
Listed leaders compete with private specialists across accreditation depth and geographic coverage. The vendor base clusters around three tiers: diversified multinational conglomerates with laboratory networks, regional specialists with regulatory proximity advantages, and technology-anchored platforms compressing reporting cycles. Consolidation pressure intensifies as ISO 17025 certification costs rise and client procurement centralizes. Dominant competitive moves include accredited laboratory partnerships with offsite producers and digital platform integration with BIM workflows.
Within the diversified multinational tier, SGS, Bureau Veritas, and Intertek Group exemplify archetypes competing on network scale and specialized protocol depth. SGS occupies a position anchored in Latin American materials laboratory infrastructure. Bureau Veritas sits within the environmental testing specialization vector for green building portfolios. Intertek Group represents the digital platform compression archetype for government agency reporting cycles. These three entities collectively illustrate how accreditation breadth, regulatory proximity, and technology integration define competitive positioning.
| Leading Market Players |
|---|
| TÜV Rheinland |
| Kiwa |
| SGS |
| UL Solutions |
| Eurofins Expert Services |
| Bureau Veritas |
| TÜV SÜD |
| BSI Group |
| Intertek Group |
| Others |
Pricing and Supply Chain Analysis
Drone-mounted LiDAR deployment for structural deformation monitoring is displacing traditional surveyor crews across Turkish and Chilean infrastructure operators, simultaneously shifting supply geography toward sensor manufacturers in Germany and the United States while compressing pricing economics for episodic inspection contracts.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in the construction TIC market. Price differentiation rests on ISO/IEC 17025 accreditation depth and digital platform integration maturity. Cost compression in standard-tier municipal contracts is intensifying because certified welding inspectors and geotechnical engineers command premium compensation. Government agencies exhibit the highest price sensitivity due to fixed-budget procurement protocols, while property developers in Singapore and Bangkok demonstrate lowest sensitivity where liability exposure justifies comprehensive testing scope.
Supply Chain Analysis
Strategic stockpiling of reference materials and calibration standards dominates over just-in-time preferences given ISO 17025 recertification cycle rigidities. Supply concentrates in Germany, Japan, and the United States for fire resistance testing capacity, while Southeast Asian laboratory infrastructure remains underdeveloped. Raw material dependencies include ultrasonic transducers, radiographic film, and concrete reference specimens. Single-source vulnerability runs through German-certified fire testing facilities serving cross-border EU demand. Distribution runs through accredited laboratory networks partnered with engineering consultancies and direct procurement channels to owner-operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-entrenchment defensive moat where ISO 17025 accreditation creates multi-year switching costs and METI-mandated reassessment protocols in Japan lock in recurring revenue streams.
For Market Incumbents: Secure accredited laboratory partnerships with modular construction offsite producers in India and Brazil before factory-based prefabrication shifts inspection locus from job site to manufacturing floor. Deepen backward integration into IoT sensor networks for continuous structural health monitoring subscriptions that displace episodic inspection revenue. Threat substitution comes from digital twin platforms integrating BIM workflows. For New Entrants and Emerging Players: Lead with specialized environmental testing protocols for green hydrogen facility construction, targeting electrolyzer plant pressure vessel certification where traditional building codes do not apply. The most penetrable white space sits in EPD acquisition services for concrete and steel suppliers under EU CSRD scope expansion. Go-to-market through direct contracts with Southeast Asian high-rise owner-operators unbundling quality assurance from general contractor retainers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional specialists possessing regulatory proximity advantages in Turkey, Chile, and Brazil. Long-term viability hinges on digital platform integration capabilities that compress reporting cycles for government agencies. The signal to watch is CEA-mandated quality assurance scope expansion across Indian smart city infrastructure corridors.| Strategic Initiative | Industry Significance |
|---|---|
| Accredited Laboratory Partnership | Factory-based prefabrication in India and Brazil shifts inspection locus from job site to manufacturing floor. |
| Digital Platform Integration | IoT sensor convergence with BIM workflows enables continuous structural health monitoring subscriptions replacing episodic inspection. |
| Specialized Certification Investment | EPD acquisition capabilities for concrete and steel suppliers gatekeep specification status under EU CSRD mandates. |
| Geographic Capacity Expansion | Fire resistance testing facilities in Southeast Asia alleviate cross-border logistics friction from German and Japanese concentration. |
| Green Hydrogen Testing Protocol | Electrolyzer plant pressure vessel certification opens unpenetrated service expansion beyond traditional building codes. |
Research Methodology
Initial hypotheses were tested against primary input from engineering consultancy directors, accredited laboratory managers, government procurement officers, and construction firm quality assurance leads and refined through secondary validation against ISO/IEC 17025 accreditation databases, national building code harmonization records, METI reassessment protocol filings, and CEA quality assurance mandates. Bottom-up triangulation across project-level contract values and top-down reconciliation against national infrastructure spending allocations anchored volume estimates.
Variance decomposition across service type, end user, test type, and certification standard dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segmented growth rate reconciliation against macro construction output trajectories. Industry-specific forecast inputs include seismic code tightening implementation schedules in Japan and Turkey, LEED v4.1 material transparency adoption curves in North America, and smart city infrastructure corridor designation timelines in India.
Forecasts assume regulatory continuity in Japanese METI reassessment protocols, EU CSRD scope expansion, and Indian CEA quality assurance mandates; material policy shifts would require re-modeling. Revision becomes warranted when accredited laboratory capacity constraints in fire resistance testing cross thresholds that fragment certification reciprocity across EU member states.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Services
Condenser Cleaners Market
Construction Services
Gutter Cleaning Services Market
Construction Services
Remote Construction Market
Construction Services
Construction Equipment Repair and Maintenance Services Market
Construction Services
Train Contractor Market
Construction Services
North America Testing and Commissioning Market
Construction Services
Composite Autoclave Repair Market
Construction Services
North and Latin America Weatherization Services Market
Construction Services
Dust Suppression Control Market
Construction Services
Construction TIC Market
Construction Services
Construction Materials Testing Equipment Market
Construction Services
Heavy Equipment Training Simulator Market
Construction Services
MENA Architectural Services Market
Construction Services
Forklift Repair and Maintenance Service Market
Construction Services
Europe Maintenance, Repair, and Operations (MRO) Market
Construction Services
Global Construction Scaffolding Rental Market