
 Construction Equipment Repair and Maintenance Services Market | 2026-2036
Construction Equipment Repair and Maintenance Services Market Size, Share, and Industry Trends Forecast 2026-2036
Construction Equipment Repair and Maintenance Services Market Analytics
The shift from captive in-house workshops to outsourced multi-vendor service networks is recalibrating how fleet operators manage total cost of ownership. Caterpillar Inc. anchors its competitive stance through an extensive dealer service infrastructure spanning North America and emerging markets. Komatsu Ltd. leverages its KOMTRAX telematics platform to deliver condition-based maintenance contracts that reduce unplanned downtime. United Rentals Inc. differentiates by integrating repair services with its rental fleet operations, capturing recurring revenue from equipment utilization cycles.
Construction equipment repair and maintenance services encompass scheduled inspections, component replacement, hydraulic system refurbishment, and engine rebuilds performed on earthmoving and lifting machinery to restore operational reliability and extend asset life. Preventive maintenance generates the largest revenue share as fleet managers prioritize scheduled servicing to avoid catastrophic failures and contractual penalties. Predictive maintenance is expanding fastest, driven by IoT sensor deployments that enable oil analysis, vibration monitoring, and thermal imaging to forecast component degradation before functional failure occurs. Equipment rental companies represent a concentrated client segment with high service contract attachment rates, while government entities drive demand through mandated maintenance clauses in public infrastructure tenders.
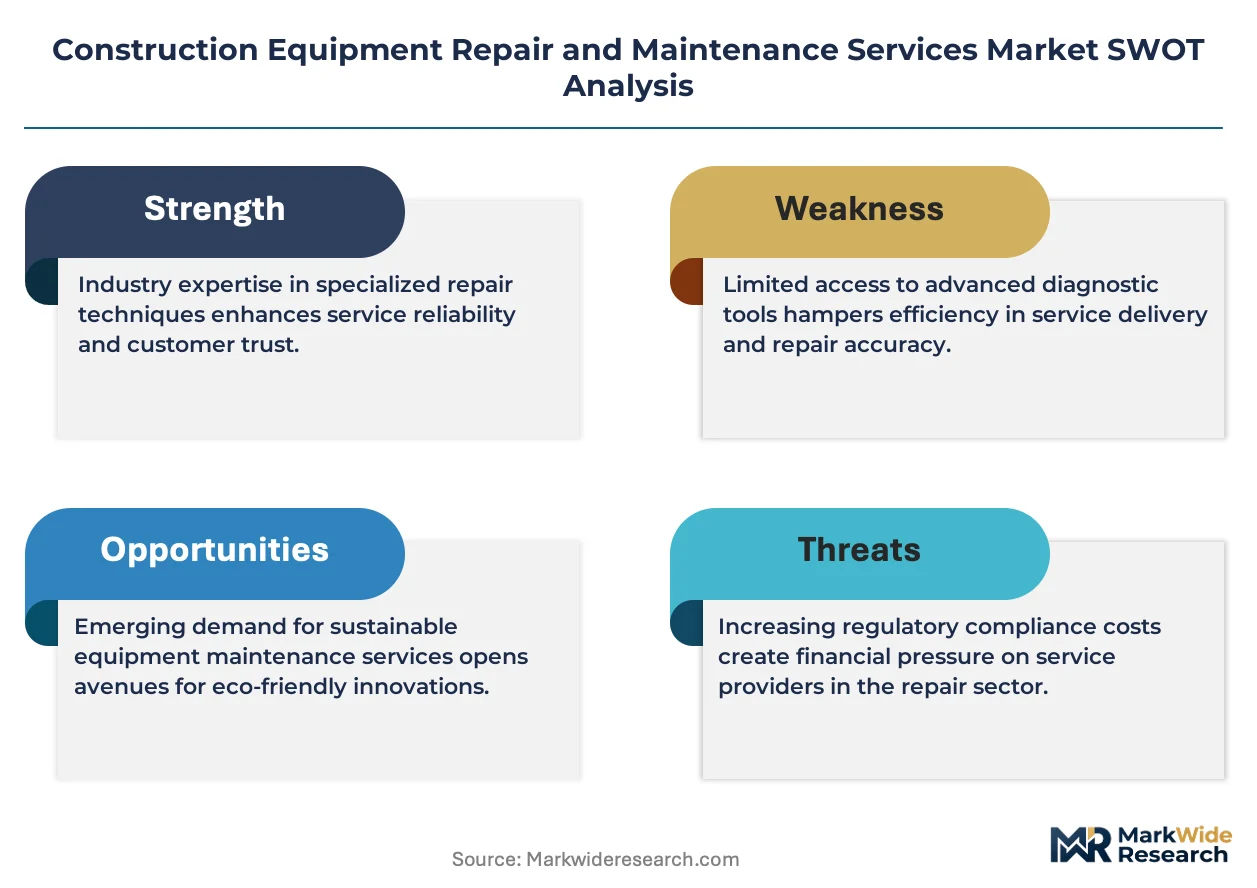
EPA Tier 4 Final emissions regulations compel specialized aftertreatment servicing for diesel particulate filters and selective catalytic reduction systems, elevating technician certification requirements. OSHA machine guarding and lockout-tagout standards shape shop-floor safety protocols during heavy equipment disassembly. Equipment operators and service providers must monitor regulatory harmonization between EPA standards and emerging state-level zero-emission mandates for construction fleets to anticipate retrofit and compliance service opportunities.
Market Dynamics
The migration from reactive breakdown repairs to predictive maintenance protocols is compressing service intervals and elevating data analytics capabilities across fleet management operations. This structural pivot demands capital deployment into IoT infrastructure and reconfigures technician skill requirements toward mechatronics competencies.
Growth Catalysts
- EPA Tier 4 Final compliance mandates:Diesel particulate filter and selective catalytic reduction servicing creates specialized revenue streams requiring certified technician networks. Fleet operators face contractual penalties for emissions non-compliance.
- Telematics platform proliferation:Real-time oil analysis and vibration monitoring enable condition-based maintenance contracts that reduce unplanned downtime for mining and earthmoving fleets.
- Australian mining expansion:Iron ore and lithium extraction operations in Western Australia are extending multi-year maintenance agreements to secure equipment availability amid labor constraints.
Market Restraints
- Specialized component supply concentration:Hydraulic pump rebuild kits and OEM-certified engine parts concentrate with select distributors, creating procurement bottlenecks during peak construction seasons.
- Technician certification escalation:EPA emissions system credentials and manufacturer-specific electronic diagnostics training extend hiring timelines and elevate wage structures.
- Electrification substitution threat:Battery-electric excavators and wheel loaders reduce engine rebuild demand and eliminate aftertreatment servicing requirements in municipal fleet segments.
Strategic Opportunities
- Retrofit service bundling:Engine repower programs combining Tier 4 Final upgrades with telematics installation capture margin from aging fleet segments seeking compliance extension.
- Equipment rental channel penetration:Service contract attachment rates remain below saturation at independent rental houses, presenting white space for integrated maintenance offerings.
- OSHA lockout-tagout automation:Electronic safety verification systems reduce shop-floor incident liability while differentiating service providers in public infrastructure tenders.
Industry Challenges
- Mechatronics skill scarcity:Hydraulic system expertise must merge with CAN bus diagnostics and sensor calibration capabilities, straining vocational pipeline output.
- Legacy fleet integration friction:Pre-Tier 4 equipment lacks standardized telematics ports, forcing custom sensor retrofits that complicate predictive maintenance rollout.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Construction Equipment Repair and Maintenance Services Market |
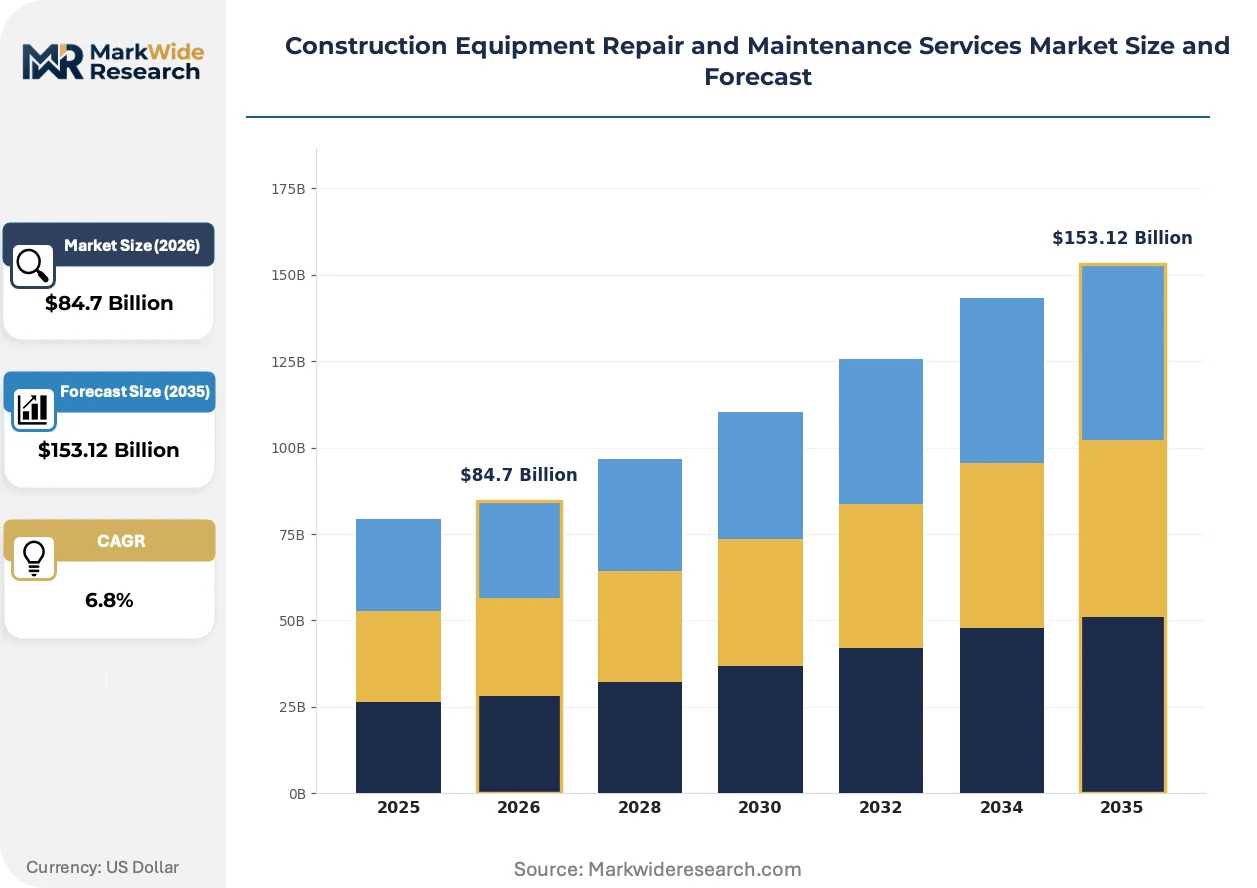
| Market Size in 2026 | $84.7 Billion |
| Market Size in 2035 | $153.12 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Preventive Maintenance, Predictive Maintenance, Emergency Repairs, Overhauls Equipment Type: Excavators, Bulldozers, Cranes, Forklifts Client Type: Construction Firms, Contractors, Equipment Rental Companies, Government Entities Technician Skill Level: Certified Technicians, Experienced Mechanics, Apprentices, Specialists |
| Companies Covered | Hitachi Ltd., AB Volvo, Alta Equipment Group, J.C. Bamford Excavators Limited, Preston Group, Caterpillar Inc., Komatsu Ltd., United Rentals Inc., WW Williams, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Construction Equipment Repair and Maintenance Services Market Evolving Landscape
Digital thread technologies are collapsing the information gap between equipment operators and service bays, enabling real-time diagnostic handoffs that compress repair cycle times. This connectivity layer is redefining accountability boundaries in outsourced maintenance relationships.
Remote diagnostic platforms is unifying sensor data streams from engine control modules, hydraulic pressure transducers, and thermal imaging arrays into single-dashboard visibility. Mining contractors in Western Australia and quarry operators in Germany are deploying these systems at fleet-wide scale. The technology is unifying previously siloed maintenance records with operational telemetry, compressing root-cause analysis from days to hours.
EU F-Gas Regulation phase-down schedules are accelerating refrigerant recovery protocol investments for mobile air conditioning systems on operator cabs. Service providers must deploy certified recovery equipment and maintain transaction logs for hydrofluorocarbon handling. Construction fleets in Germany and France face the tightest compliance timelines, with mandated service documentation now required for equipment resale and auction transfers.
Fleet managers are unbundling preventive maintenance from emergency repair contracts, creating discrete purchasing decisions that expose service pricing to direct comparison. Equipment rental companies and municipal public works departments are driving this specification shift, issuing separate RFPs for scheduled servicing versus breakdown response. The pattern is most visible in United States infrastructure rehabilitation programs where federal funding transparency requirements mandate line-item cost disclosure.
Construction Equipment Repair and Maintenance Services Market Segmentation
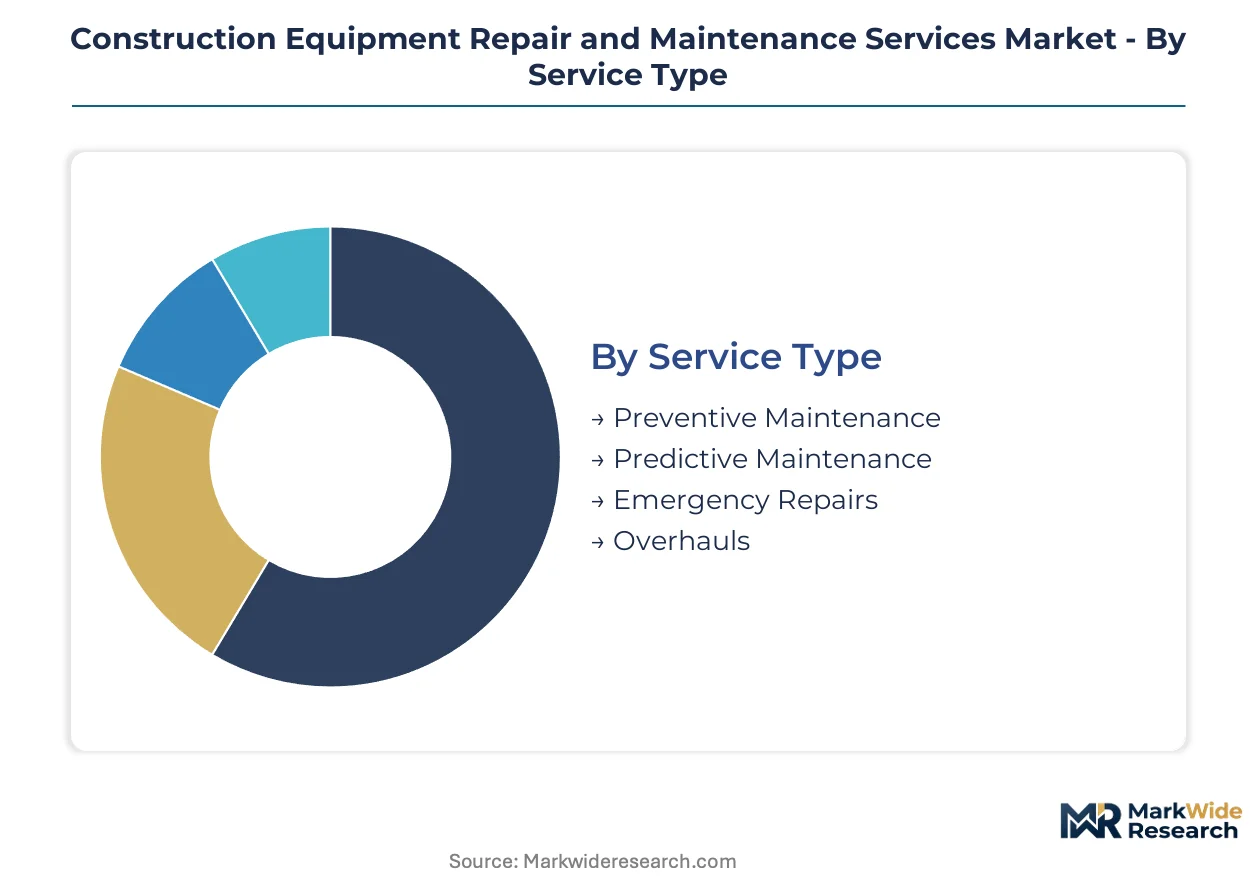
Fleet operators segment maintenance procurement to match service intensity with equipment criticality and contract risk exposure. Each segmentation axis reveals distinct pricing power dynamics and vendor qualification thresholds that reshape competitive positioning across the value chain.
Service Type:
Equipment replacement cycles and EPA compliance deadlines drive service type selection, with fleet managers calibrating spend against downtime penalties and residual asset value.
- Preventive Maintenance:Scheduled servicing protocols encompassing fluid changes, filter replacements, and component inspections performed at manufacturer-prescribed intervals. Mining contractors in Western Australia anchor demand through multi-year availability contracts that mandate strict preventive schedules to avoid production stoppages at remote extraction sites.
- Predictive Maintenance:Condition-monitoring programs leveraging IoT sensors, oil analysis, and thermal imaging to forecast component failure before functional breakdown. United States infrastructure rehabilitation programs are expanding fastest here, as federal funding transparency requirements push fleet managers toward data-validated uptime guarantees.
- Emergency Repairs:Unscheduled breakdown response addressing hydraulic failures, engine seizures, and electrical faults.
- Overhauls:Comprehensive rebuilds restoring equipment to near-original specifications.
Volume placements concentrate in Preventive Maintenance; the faster expansion belongs to Predictive Maintenance.
Equipment Type:
Application severity and hourly utilization rates differentiate equipment categories, with high-duty-cycle machines commanding premium service attach rates.
- Excavators:Hydraulic system-intensive earthmoving machinery requiring frequent boom, arm, and bucket cylinder servicing alongside undercarriage maintenance. Australian iron ore operations drive concentrated demand for track and hydraulic rebuild programs amid 24/7 extraction schedules.
- Cranes:Lifting equipment subject to structural fatigue monitoring, wire rope replacement, and load-testing certification. German construction clusters prioritize crane maintenance given strict TÜV inspection mandates and EU machinery directive compliance.
- Bulldozers:Track-type tractors demanding undercarriage rebuilds and blade attachment servicing.
- Forklifts:Material handling equipment with shorter replacement cycles and standardized component access.
Revenue concentration sits with Excavators; Cranes deliver the steepest expansion trajectory from infrastructure heightening and safety regulation tightening.
Client Type:
Procurement sophistication varies sharply across client categories, with contract structure and payment security reshaping vendor targeting priorities.
- Equipment Rental Companies:Fleet owners monetizing utilization rates through integrated maintenance programs bundled with rental agreements. United Rentals and similar operators in the United States generate recurring service revenue from equipment turnover cycles and damage waiver programs.
- Government Entities:Public agencies bound by mandated maintenance clauses in federal and state infrastructure tenders. United States Department of Transportation programs require documented service histories for equipment eligibility, creating compliance-driven demand.
- Construction Firms:General contractors managing owned fleets through captive or outsourced maintenance.
- Contractors:Specialized trade operators with project-specific equipment needs.
Contract value concentrates with Equipment Rental Companies; Government Entities are gaining share fastest from infrastructure stimulus acceleration.
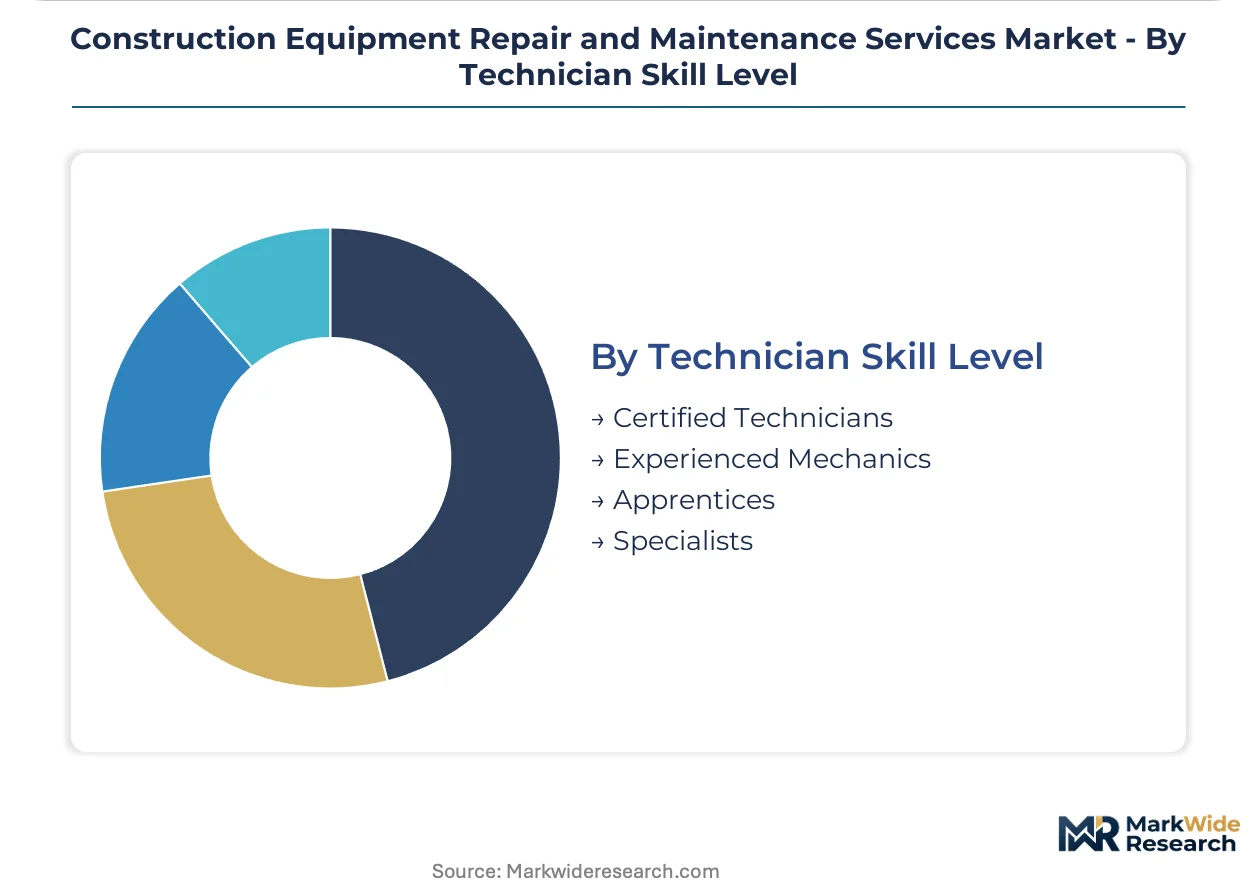
Technician Skill Level:
Labor scarcity and certification escalation fragment the technician base, with wage premiums accruing to credentials that reduce liability exposure.
- Certified Technicians:EPA-credentialed and manufacturer-authorized personnel qualified for emissions aftertreatment and electronic diagnostics. United States fleet operators face extended hiring timelines for Tier 4 Final specialists, elevating wage structures and contract pricing.
- Specialists:Deep experts in hydraulic systems, engine rebuilds, or telematics integration commanding project-based premiums.
- Experienced Mechanics:Journeyman-level practitioners handling routine servicing without specialized emissions credentials.
- Apprentices:Entry-level trainees performing supervised component replacement and shop support.
Headcount concentrates among Experienced Mechanics; Certified Technicians are climbing the fastest as emissions compliance hardens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States infrastructure rehabilitation programs concentrate demand for sustained equipment uptime, while Australian mining operations and German construction clusters anchor regional service intensity through distinct regulatory and operational drivers.
United States
Department of Transportation programs mandate documented service histories for equipment eligibility in federal infrastructure tenders. EPA Tier 4 Final enforcement compels specialized aftertreatment servicing across contractor fleets. Texas and Florida construction corridors drive preventive maintenance contract volumes amid hurricane recovery and energy infrastructure expansion.
Australia
Iron ore and lithium extraction operations in Western Australia extend multi-year maintenance agreements to secure equipment availability. The country's national mining safety regulator enforces strict availability clauses in extraction licenses. Perth-based service hubs coordinate fly-in-fly-out technician deployments to remote Pilbara mine sites.
Germany
TÜV inspection mandates and EU machinery directive compliance elevate crane maintenance protocols in construction clusters. The EU F-Gas Regulation phase-down accelerates refrigerant recovery investments for mobile air conditioning systems. Bavarian and North Rhine-Westphalian equipment fleets face the tightest compliance documentation requirements for resale and auction transfers.
China
Dual carbon goals and GB standards for non-road mobile machinery emissions reshape service protocols for domestic excavator and bulldozer fleets. The Ministry of Ecology and Environment tightens enforcement timelines for construction equipment in Beijing-Tianjin-Hebei and Yangtze River Delta zones. Shanghai and Shenzhen municipal fleets pilot predictive maintenance platforms to minimize urban construction disruption.
Japan
METI industrial efficiency standards promote telematics integration for aging construction equipment in earthquake-prone regions. JIS certification requirements govern hydraulic system rebuild quality for domestic crane and excavator operators. Osaka and Nagoya metropolitan construction authorities specify condition-based maintenance clauses in public works tenders to reduce project delay penalties.
Construction Equipment Repair and Maintenance Services Market Competitive Landscape
Strategic partnerships dominate the current landscape as equipment manufacturers, rental operators, and independent service networks recalibrate asset-light versus captive maintenance models. The market structures around three tiers: OEM-anchored dealer networks with proprietary telematics platforms, integrated rental-service hybrids monetizing utilization cycles, and independent specialists capturing legacy fleet overhauls. Archetypes include technology-forward platform operators, scale-driven rental-service integrators, and regional rebuild specialists. Geographic expansion and portfolio diversification represent the dominant competitive vectors as players seek density in high-contract-attachment segments.
Within the OEM-anchored tier, Caterpillar Inc. and Komatsu Ltd. exemplify platform-centric service architectures, while United Rentals Inc. occupies a position as the rental-service hybrid archetype. Hitachi Ltd. and AB Volvo sit within the diversified industrial equipment category, leveraging cross-border service infrastructure. Alta Equipment Group and Preston Group represent North American regional specialists, with J.C. Bamford Excavators Limited anchoring the UK-centric construction equipment service position. WW Williams exemplifies the independent specialist model focused on heavy-duty engine and powertrain rebuilds.
| Leading Market Players |
|---|
| Hitachi Ltd. |
| AB Volvo |
| Alta Equipment Group |
| J.C. Bamford Excavators Limited |
| Preston Group |
| Caterpillar Inc. |
| Komatsu Ltd. |
| United Rentals Inc. |
| WW Williams |
| Others |
Value Network & Pricing Analysis
Outsourced dealer networks anchor both supply positioning and pricing power in construction equipment maintenance, with Caterpillar and Komatsu leveraging captive parts distribution to enforce OEM-certified service premiums while independent rebuilders compete on legacy fleet overhauls.
Pricing Analysis
Warranty bundling separates OEM-dealer service contracts from unbundled preventive maintenance programs sold by independent providers. Three-tier pricing structure across premium, standard, and economy levels reflects technician certification grade and telematics integration depth. Cost compression in the economy tier is intensifying because rental companies are consolidating procurement through national framework agreements. Municipal public works departments exhibit highest price sensitivity due to federal funding transparency mandates, while mining contractors in Western Australia show lowest sensitivity given production stoppage penalties.
Supply Chain Analysis
Hydraulic pump rebuild kits rest on Japanese and German specialty component producers, with engine aftertreatment parts drawing from United States and South Korean certified distributors. OEM-certified electronic diagnostics modules and selective catalytic reduction systems concentrate with select authorized networks. Single-source vulnerability runs through Tier 4 Final emissions component suppliers facing EPA enforcement backlogs. Distribution runs through dealer service centers for warranty work, while independent jobbers and direct procurement serve the legacy fleet overhaul segment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Condition-based maintenance platforms are displacing scheduled servicing protocols across fleet operations, compressing the window for legacy preventive-only service providers to adapt their capability stacks.
For Market Incumbents: Lock in multi-year telematics integration contracts with Australian mining operators before battery-electric fleet pilots eliminate engine rebuild demand. Deepen backward integration into sensor calibration and CAN bus diagnostics training to offset mechatronics skill scarcity. Prioritize EPA Tier 4 Final certification density in Texas and Florida construction corridors where infrastructure stimulus concentrates contract volumes.
For New Entrants and Emerging Players: Begin with independent equipment rental houses in the United States where service contract attachment rates remain below saturation and procurement is fragmented across regional operators. Target OSHA lockout-tagout automation as a differentiated entry wedge for public infrastructure tenders requiring electronic safety verification. Deploy mobile diagnostic units to remote Western Australian mine sites where fly-in-fly-out technician logistics create service gaps.
For Investors and Strategic Acquirers: Exit pathways concentrate in platform-enabled service aggregators capable of unifying telematics data streams across mixed OEM fleets. Long-term viability hinges on predictive maintenance algorithm development and technician workforce scaling rather than asset-heavy shop footprints. Watch battery-electric construction equipment penetration rates in municipal fleets as the inflection signal for engine service demand displacement.
| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | Unifies sensor data from Komatsu KOMTRAX and Caterpillar Product Link into single-dashboard fleet visibility for mining contractors. |
| EPA Tier 4 Final Certification Investment | Captures specialized aftertreatment servicing revenue from diesel particulate filter and selective catalytic reduction maintenance mandates. |
| Independent Rental Channel Penetration | Addresses white space in integrated maintenance offerings where United Rentals and regional operators lack service contract saturation. |
| OSHA Lockout-Tagout Automation | Reduces shop-floor liability exposure while differentiating bids for Department of Transportation infrastructure tenders. |
| Retrofit Service Bundling | Combines engine repower programs with telematics installation to capture margin from aging fleet segments seeking compliance extension. |
Research Methodology
Independent corroboration across maintenance directors at mining contractors, aftermarket service heads at OEM dealer networks, and procurement leads at equipment rental companies underwrites the qualitative findings. Primary fieldwork included fleet managers at Western Australian iron ore operations, EPA-certified technicians in Texas construction corridors, and telematics platform engineers at Komatsu and Caterpillar. Secondary validation drew from EPA enforcement disclosures, OSHA incident databases, United States Department of Transportation tender documentation, and Australian mining safety regulator extraction license records. Bottom-up service contract value aggregation and top-down fleet size estimates triangulate market sizing.
Rate-of-change decomposition across the analysis window segments expansion by service type, equipment category, client procurement sophistication, and technician credential tier. Modeled dimensions include preventive versus predictive versus emergency repair intensity, excavator and crane utilization rates, rental company versus government entity versus construction firm contract structures, and certified versus experienced versus apprentice labor mix. CAGRs derive from equipment replacement cycle timing, EPA compliance deadline clustering, and telematics adoption curve assumptions. Forecast inputs incorporate mining production schedules in Western Australia and infrastructure rehabilitation program allocations in the United States.
Underlying measurement precision varies by segment; predictive maintenance and certified technician headcount carry tighter precision than emergency repair volumes and apprentice pipeline estimates. Forecasts reflect documented assumptions regarding electrification substitution pace, regulatory harmonization between EPA and state zero-emission mandates, and mechatronics training program expansion. A small set of triggers warrants ongoing watch: battery-electric construction equipment municipal fleet procurement acceleration, EPA Tier 5 emissions standard pre-announcement signaling, and Australian mining labor agreement renegotiations affecting fly-in-fly-out technician deployment economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Services
Hardbanding Services Market
Construction Services
Dust Suppression Control Market
Construction Services
Global Construction Scaffolding Rental Market
Construction Services
Industrial Machinery Repair Services Market
Construction Services
Heavy Equipment Training Simulator Market
Construction Services
Facade Cleaning and Maintenance Service Market
Construction Services
Excavating Contractor Market
Construction Services
Die Casting Services Market
Construction Services
3D Concrete Printing Services Market
Construction Services
Forklift Repair and Maintenance Service Market
Construction Services
Grease Trap Service Market
Construction Services
Train Contractor Market
Construction Services
Global Industrial Services Market
Construction Services
Gutter Cleaning Services Market
Construction Services
Condenser Cleaners Market
Construction Services
North America Repair and Rehabilitation Market