
 Construction Project Management Services Market | 2026-2036
Construction Project Management Services Market Size, Share, and Industry Trends Forecast 2026-2036
Construction Project Management Services Market Analysis
Digital procurement channels for construction advisory work is reshaping how owners select and retain project managers. WSP leverages its transcontinental engineering footprint to secure complex infrastructure mandates. AECOM sustains competitive positioning through integrated design-build-operate capabilities. Bechtel Corporation dominates energy and industrial megaproject segments with proprietary risk methodologies.
Construction project management services encompass planning, coordination, and control of building and infrastructure projects from concept through commissioning, typically employing critical path method scheduling, earned value management, and building information modeling protocols to deliver scope on budget and schedule. The service generates value by reducing cost overruns, compressing timelines, and ensuring regulatory compliance across multi-stakeholder environments. Execution services capture the largest revenue share due to on-site supervisory intensity, while cloud-based solutions represent the fastest-expanding segment as owners demand real-time progress visibility. Mega projects command premium fee structures reflecting embedded technical complexity and extended duration risk.
Federal construction agencies in the United States operate under FAR guidelines, while the EU Green Deal and national building codes across member states mandate embodied carbon tracking and energy performance disclosure. OSHA workplace safety standards and ISO 19650 BIM frameworks further constrain service delivery protocols. Stakeholders must evaluate which regulatory layers will tighten fastest and calibrate capability investments accordingly.
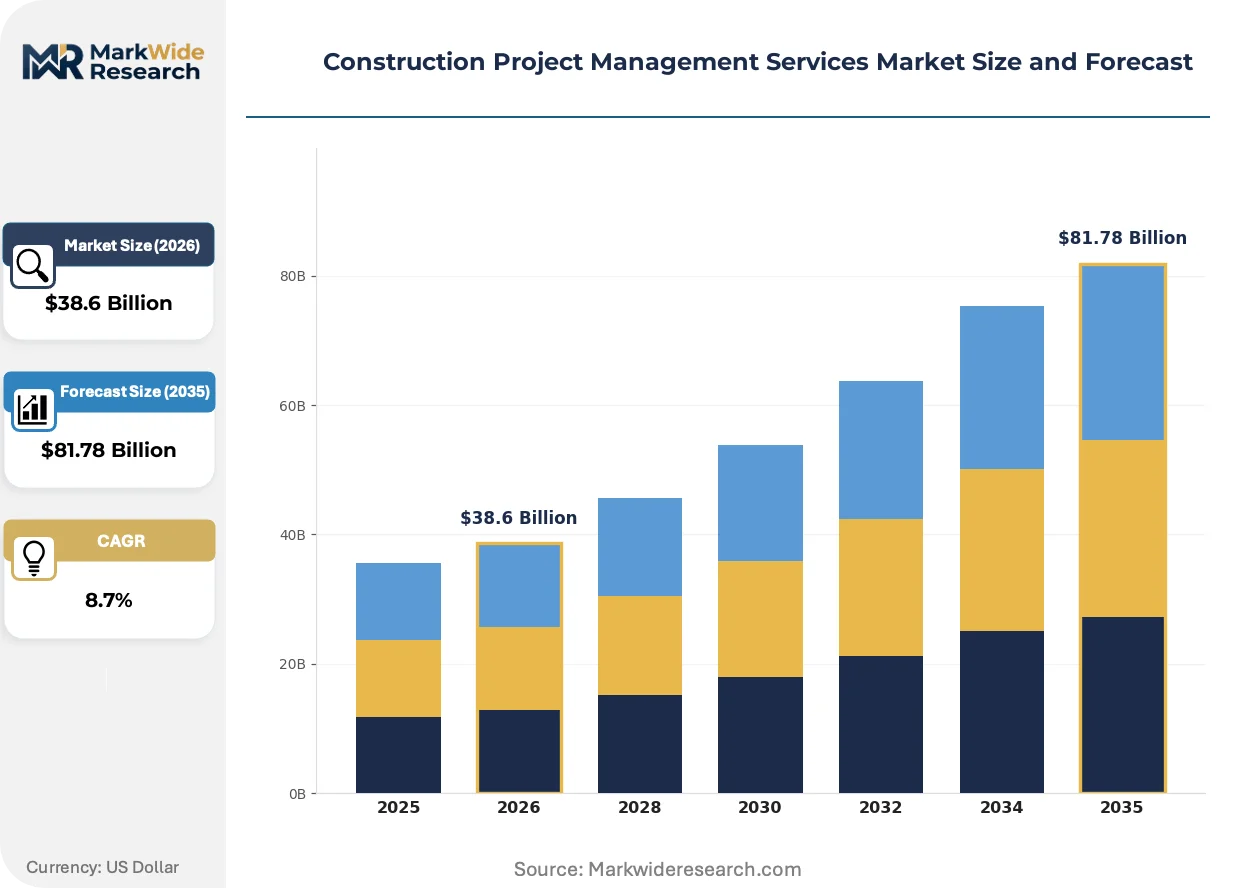
Market Dynamics
Integrated project delivery models are compressing traditional design-bid-build timelines as owners demand single-point accountability for complex infrastructure builds. BIM mandates from Germany, Singapore, and the UK are forcing workflow standardization across transnational project portfolios.
Growth Catalysts
- EU Green Deal embodied carbon tracking:Building regulators in Germany and France now mandate lifecycle carbon disclosure for public infrastructure tenders. Project managers with verified carbon accounting capabilities capture premium mandates.
- Cloud-based progress visibility platforms:Real-time dashboarding is collapsing information asymmetry between owners and field teams. Federal construction agencies in the United States now require digital reporting under FAR guidelines.
- India infrastructure investment pipeline:National highway and rail expansion programs concentrate demand for execution-phase supervisory services. Domestic and international firms compete for multi-year program management contracts.
Market Restraints
- Specialized talent scarcity:Experienced BIM coordinators and earned value management specialists command compensation premiums that compress service margins. Recruitment cycles extend project mobilization timelines.
- Steel and concrete input volatility:Commodity price swings disrupt fixed-fee contract economics. Project managers absorb margin risk when escalation clauses prove insufficient.
- ISO 19650 certification friction:Cross-border project teams face inconsistent national adoption timelines for information management protocols. Compliance gaps delay joint venture formations.
Strategic Opportunities
- Saudi Arabia giga-project pipeline:NEOM and Red Sea tourism developments require Western-standard project controls adapted to local labor regulations. First-mover firms establish reference credentials.
- Digital twin convergence with IoT sensors:Real-time structural monitoring during construction enables predictive schedule recovery. Early adopters differentiate on risk mitigation guarantees.
- UK Building Safety Regulator gateway requirements:Mandatory third-party oversight for higher-risk residential buildings creates recurring revenue streams. Compliance specialists capture multi-year asset management extensions.
Industry Challenges
- Multi-stakeholder coordination complexity:Integrated delivery models blur traditional architect-contractor boundaries. Project managers mediate conflicting incentive structures without direct authority.
- Legacy ERP integration:Owner organizations operate fragmented financial and document management systems. Middleware development costs erode platform economics for mid-scale engagements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Construction Project Management Services Market |
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $81.78 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Consulting, Planning, Execution, Monitoring End User: Residential Builders, Commercial Developers, Government Agencies, Industrial Corporations Solution: Software, Cloud-Based, On-Premises, Hybrid Project Size: Small-Scale, Medium-Scale, Large-Scale, Mega Projects |
| Companies Covered | Fluor Corporation, WSP, Turner Construction Company, Turner & Townsend, Mott MacDonald, AECOM, Jacobs, Skanska USA, Bechtel Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Construction Project Management Services Market Emerging Trajectories
Artificial intelligence applications are compressing schedule risk analysis from weeks to hours. Machine learning models trained on historical project data now predict delay probabilities before ground-breaking.
Generative design algorithms paired with BIM authoring tools are collapsing the traditional schematic design phase. Commercial developers in the United States deploy these platforms to evaluate dozens of structural alternatives against cost and carbon targets simultaneously. Engineering teams restructure around model curation rather than manual drafting.
Germany's national building code amendments now mandate digital building permits submitted through standardized BIM formats. Municipal planning departments in Bavaria and North Rhine-Westphalia reject paper documentation for major commercial projects. Architectural practices accelerate software investments to maintain entitlement timelines.
Owners are unbundling commissioning and facilities management from initial construction contracts. Hospital systems in Singapore now procure twenty-year operational advisory alongside design-phase services. Fee structures migrate from percentage-of-construction to outcome-based performance retainers tied to energy and maintenance benchmarks.
Construction Project Management Services Market Segmentation
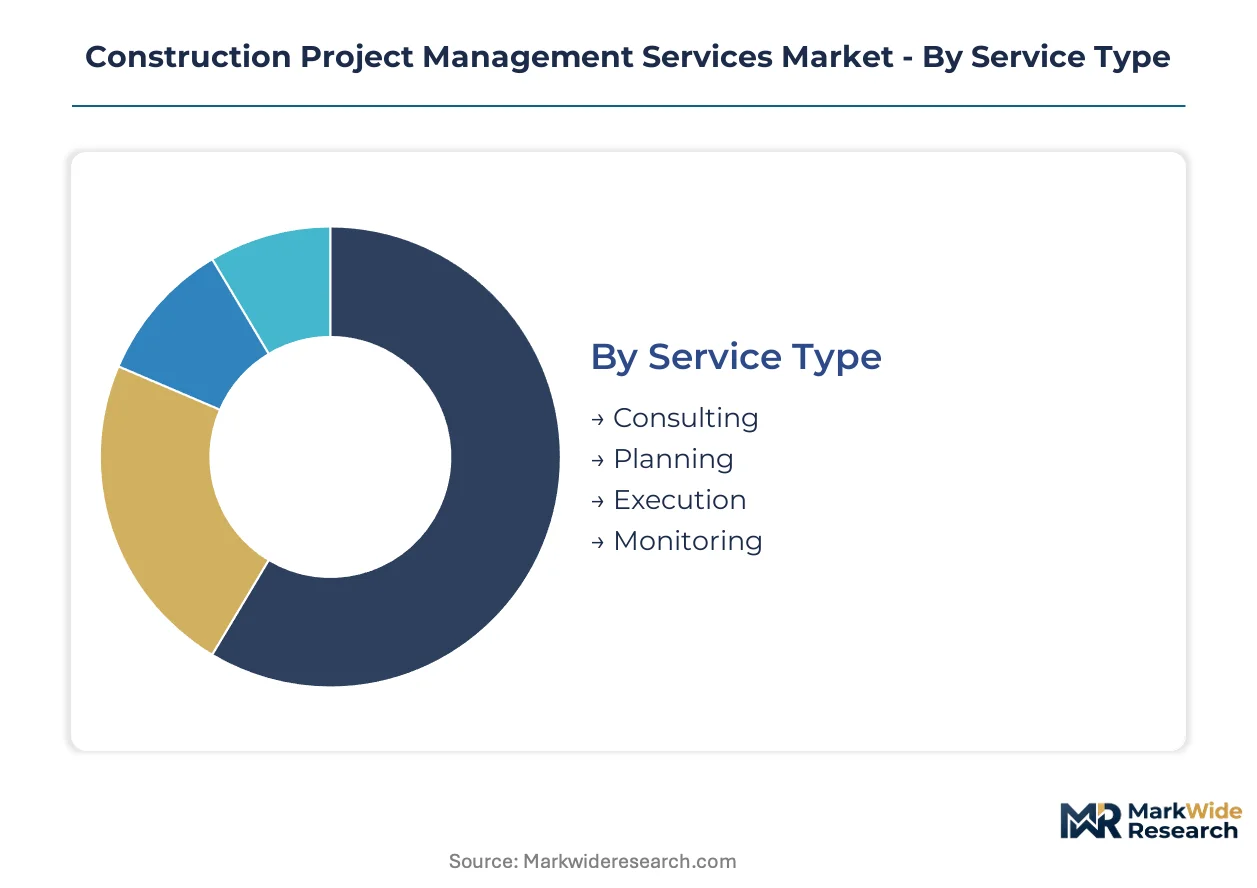
Segmentation in construction project management services reveals distinct margin profiles and contract renewal patterns. Service type determines staffing ratios and technology intensity. Project size governs risk retention structures and fee negotiation leverage.
Service Type:
Execution services turn over fastest with monthly billing cycles, while consulting engagements stretch across multi-year advisory retainers.
- Consulting:Front-loaded advisory spanning feasibility studies, risk quantification, and procurement strategy. Demand concentrates among Saudi Arabia giga-project developers seeking Western-standard governance frameworks adapted to local labor regulations. Carbon accounting capabilities now differentiate winning bids for EU public infrastructure tenders.
- Planning:Schedule compression and resource optimization using critical path method algorithms. Commercial developers in the United States deploy generative design platforms to evaluate structural alternatives against embodied carbon targets simultaneously. BIM coordinators command compensation premiums that compress margins.
- Execution:On-site supervisory intensity with real-time progress reporting through cloud dashboards.
- Monitoring:Earned value management and quality assurance protocols.
Execution anchors the volume base while consulting gains share at the steepest rate.
End User:
Government agencies impose the longest procurement cycles with multi-year qualification requirements, while residential builders close engagements fastest.
- Residential Builders:Volume-driven engagements with standardized deliverables. UK Building Safety Regulator gateway mandates for higher-risk buildings create recurring revenue streams for compliance specialists. Fee structures migrate from percentage-of-construction to outcome-based performance retainers.
- Commercial Developers:Integrated project delivery adoption compresses traditional design-bid-build timelines. Singapore hospital systems now procure twenty-year operational advisory alongside design-phase services. Digital twin convergence with IoT sensors enables predictive schedule recovery guarantees.
- Government Agencies:FAR-guided federal construction in the United States mandates digital reporting protocols.
- Industrial Corporations:Energy and industrial megaprojects require proprietary risk methodologies.
Commercial developers anchor the volume base while government agencies expand at the steepest trajectory.
Solution:
On-premises deployments carry the longest implementation horizons, while cloud-based solutions activate within weeks.
- Software:Legacy ERP integration challenges erode platform economics for mid-scale engagements. Middleware development costs concentrate among owner organizations with fragmented financial systems. ISO 19650 certification friction delays cross-border joint venture formations.
- Cloud-Based:Real-time dashboarding collapses information asymmetry between owners and field teams. Federal construction agencies in the United States now require digital reporting under FAR guidelines. This segment is expanding most quickly as owners demand continuous progress visibility.
- On-Premises:Security-sensitive deployments in defense and critical infrastructure sectors.
- Hybrid:Transitional architectures bridging legacy systems with cloud analytics.
Software anchors the volume base while cloud-based solutions climb the fastest.
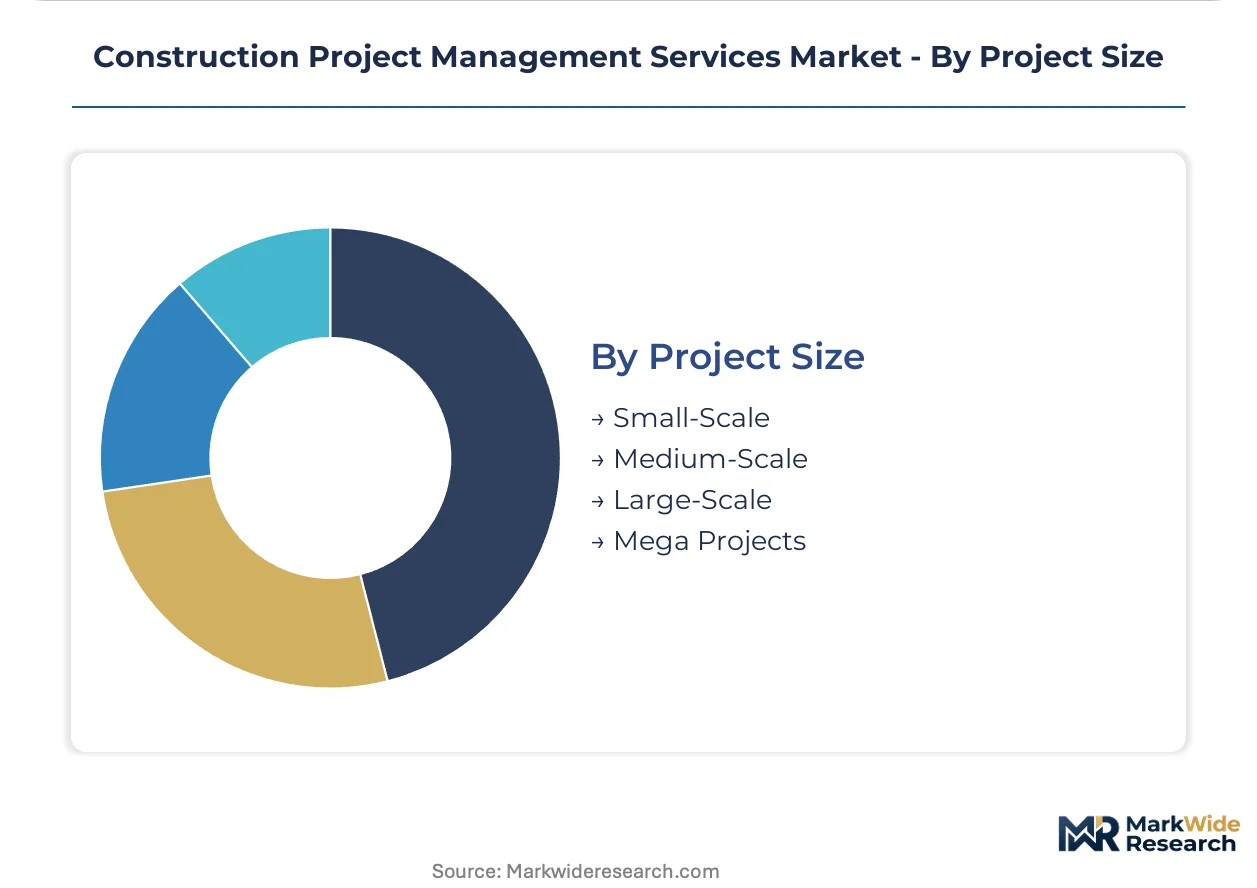
Project Size:
Small-scale projects close within quarters, while mega projects extend across decades with fee structures reflecting embedded technical complexity.
- Mega Projects:Premium fee structures capture extended duration risk and stakeholder coordination complexity. NEOM and Red Sea tourism developments in Saudi Arabia require Western-standard project controls. First-mover firms establish reference credentials for multi-year program management contracts.
- Large-Scale:Infrastructure pipelines in India concentrate demand for execution-phase supervisory services. National highway and rail expansion programs attract domestic and international firm competition. Steel and concrete input volatility disrupts fixed-fee contract economics.
- Medium-Scale:Municipal and regional infrastructure with standardized risk profiles.
- Small-Scale:Rapid-turnaround residential and light commercial engagements.
Large-scale projects anchor the volume base while mega projects gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States sustains the largest project management services volume through federal infrastructure pipelines and private commercial development. China's high-speed rail network and urban metro expansions concentrate demand for execution-phase supervisory capacity. India's national highway and logistics corridor programs attract international program management competition.
United States
Federal construction agencies operate under FAR guidelines mandating digital reporting protocols for capital projects. The Infrastructure Investment and Jobs Act sustains multi-year highway, bridge, and grid modernization programs. Texas and California metropolitan corridors concentrate commercial developer demand for integrated project delivery expertise.
China
National high-speed rail extensions and urban metro buildouts absorb substantial project controls capacity. MIIT standards for smart city infrastructure mandate BIM coordination across municipal procurement. Yangtze River Delta municipalities including Shanghai and Suzhou concentrate foreign-local joint venture formations for complex transit hubs.
India
National highway authority expansion programs and dedicated freight corridors sustain execution-service demand. Central Public Works Department guidelines increasingly require earned value management reporting for large infrastructure tenders. Gujarat and Maharashtra industrial corridors attract international firm competition for multi-year program management contracts.
Germany
National building code amendments mandate digital building permits through standardized BIM formats. EU Green Deal embodied carbon tracking requirements apply to federal infrastructure tenders. Bavaria and North Rhine-Westphalia municipal planning departments reject paper documentation for major commercial projects.
Saudi Arabia
NEOM and Red Sea tourism developments require Western-standard project controls adapted to local labor regulations. Saudi Building Code enforcement tightens technical oversight requirements for giga-project delivery. Riyadh and the Eastern Province concentrate international engineering firm regional headquarters formations.
Construction Project Management Services Market Vendor Landscape
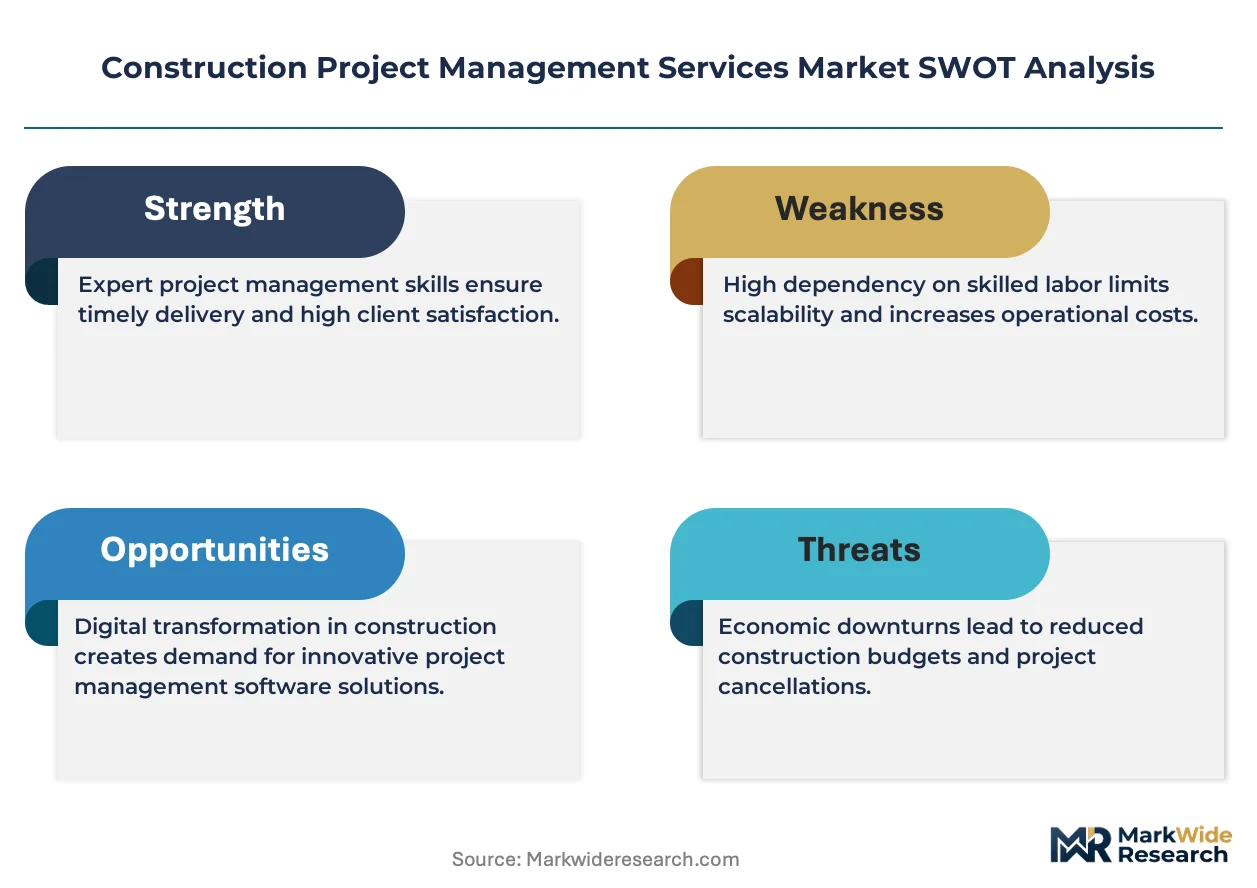
Platform integrators command the system tier; component specialists sit upstream in scheduling analytics and carbon accounting niches. The market structures around three tiers: global engineering conglomerates with transcontinental footprints, regional specialists with embedded regulatory relationships, and technology-enabled boutiques with proprietary risk algorithms. Consolidation pressure concentrates among mid-scale firms lacking either scale economies or specialized tooling. Dominant competitive moves include strategic partnerships for digital twin capabilities and selective hiring of BIM coordinators from rival organizations.
Within the global engineering tier, AECOM, WSP, and Bechtel Corporation exemplify contrasting archetypes. AECOM represents integrated design-build-operate positioning across federal and commercial portfolios. WSP anchors transcontinental infrastructure mandates through engineering breadth. Bechtel Corporation occupies a position in energy and industrial megaproject segments where proprietary risk methodologies differentiate fee structures.
| Leading Market Players |
|---|
| Fluor Corporation |
| WSP |
| Turner Construction Company |
| Turner & Townsend |
| Mott MacDonald |
| AECOM |
| Jacobs |
| Skanska USA |
| Bechtel Corporation |
| Others |
Supply Flow & Price Mechanics
Overcapacity in European engineering talent pools is compressing day-rate premiums for BIM coordinators and earned value specialists, forcing suppliers to absorb margin compression while buyers consolidate vendor panels around integrated delivery capabilities.
Pricing Analysis
Volume-discount tiering structures dominate procurement, with mega-project owners capturing 15-30% fee reductions against standard commercial rates through multi-year program mandates. Pricing stratifies across premium certified tiers, standard execution-only engagements, and economy advisory packages. Cost compression in mid-scale consulting is intensifying because commodity-linked construction inputs disrupt fixed-fee economics. Residential builders exhibit highest price sensitivity due to standardized deliverables, while Saudi giga-project developers accept premium positioning for Western-standard governance frameworks.
Supply Chain Analysis
Upstream feedstock for construction project management services draws from professional labor markets concentrated in the United States, United Kingdom, and India. Talent pipelines rest on university engineering programs, military infrastructure veterans, and cross-trained architecture graduates. Single-source vulnerability concentrates in BIM software platforms and cloud infrastructure providers. Distribution runs through direct owner relationships, engineering conglomerate prime contracts, and specialized boutique referrals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Construction project management services function as a service-attach opportunity where twenty-year operational advisory contracts for hospital systems and airport authorities expand faster than discrete construction-phase engagements.
For Market Incumbents: Build proprietary risk methodology moats around carbon accounting capabilities and digital twin integration. Defensive consolidation should concentrate on acquiring BIM coordination specialists in Germany and Singapore where regulatory mandates tighten fastest. Capacity addition in Riyadh and Mumbai captures Saudi and India infrastructure pipeline concentration. Certification investment in ISO 19650 information management protocols delays joint venture competitor formations.
For New Entrants and Emerging Players: Southeast Asian secondary cities present underpenetration for cloud-based progress visibility platforms serving mid-scale commercial developers. White-space targets include earned value management outsourcing for Central Public Works Department contractors in India and third-party gateway compliance for UK higher-risk residential buildings. Go-to-market positioning as ISO 19650 compliance specialists with rapid-deployment cloud dashboards penetrates fastest.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among firms with multi-year asset management extensions tied to UK Building Safety Regulator mandates and Singapore hospital operational advisory. Long-term viability favors boutiques with proprietary AI schedule risk algorithms over commodity execution brokers. Acquisition targets should demonstrate verified carbon accounting capabilities and established credentials in Saudi giga-project delivery. Watch for inflection when federal agencies tighten FAR digital reporting requirements beyond current guidelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Accounting Capability Buildout | EU Green Deal embodied carbon mandates now gate public infrastructure tender access in Germany and France. |
| Digital Twin Platform Integration | Real-time structural monitoring during construction enables predictive schedule recovery guarantees for commercial developers. |
| ISO 19650 Certification Investment | Cross-border joint venture formations accelerate when compliance gaps close across Germany, Singapore, and UK portfolios. |
| Saudi Arabia Regional Headquarters Establishment | NEOM and Red Sea tourism developments require Western-standard project controls adapted to local labor regulations. |
| AI Schedule Risk Algorithm Development | Machine learning models trained on historical project data compress risk analysis from weeks to hours for competitive differentiation. |
Methodological Framework
Initial hypotheses were tested against primary input from project controls directors, federal construction procurement officers, BIM coordinators, and engineering firm practice leaders and refined through secondary validation against SEC 10-K filings, Infrastructure Investment and Jobs Act program disclosures, EU Green Deal implementation guidance, and ISO 19650 certification databases. Bottom-up service line revenue builds triangulated against top-down infrastructure investment pipeline assessments.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling service type, project size tier, solution deployment model, and end-user vertical alongside geographic regulatory cluster intensity. CAGRs were derived from segment-level growth rate convergence analysis. Forecast inputs incorporated steel and concrete commodity volatility indices and federal construction agency digital reporting mandate timelines.
Macroeconomic conditions sit as an overlay; deviation in infrastructure stimulus appropriations, construction labor availability, and commodity price trajectories would shift the trajectory. Cross-checking against Engineering News-Record Top 400 revenue benchmarks and federal agency obligation data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Services
Dust Suppression Control Market
Construction Services
MENA Architectural Services Market
Construction Services
Maintenance Repair and Operations (MRO) Market
Construction Services
North and Latin America Weatherization Services Market
Construction Services
Excavating Contractor Market
Construction Services
NDT and Inspection Market
Construction Services
Grease Trap Service Market
Construction Services
Industrial Machinery Repair Services Market
Construction Services
3D Concrete Printing Services Market
Construction Services
Condenser Cleaners Market
Construction Services
North America Fire Sprinkler Systems Market
Construction Services
Hardbanding Services Market
Construction Services
Industrial Maintenance Products Market
Construction Services
Die Casting Services Market
Construction Services
Composite Autoclave Repair Market
Construction Services
Global Industrial Services Market