
 Train Contractor Market | 2026-2036
Train Contractor Market Size, Share, and Industry Trends Forecast 2026-2036
Train Contractor Market Analysis
India's dedicated freight corridor build-out is fragmenting contractor specialization between civil infrastructure consortia and rolling-stock-integrated system providers. CRRC Corporation Limited leverages its captive manufacturing base to underbid on bundled construction-and-vehicle packages across African and Latin American markets. Siemens AG anchors European high-speed rail upgrades through its signaling-electrification integration, while Alstom SA competes on automated metro turnkey contracts in the Middle East and Asia-Pacific.
A train contractor executes rail infrastructure projects spanning civil engineering, track laying, electrification installation, signaling deployment, and rolling-stock integration, typically conforming to axle-load specifications and gauge standards dictated by the host railway network. The primary purpose is delivering interoperable, safety-certified rail systems that meet scheduled performance benchmarks under long-term concession or fixed-price agreements. Construction and upgrade project scopes command the largest revenue pools given their capital intensity and multi-year execution timelines, whereas maintenance and repair services generate steadier, annuity-like cash flows that attract infrastructure-focused investors. Electrification and signaling technology segments are outpacing civil construction in margin expansion, as digital signaling and automation command premium pricing over conventional track-and-station work.
The European Union Agency for Railways enforces Common Safety Methods and Technical Specifications for Interoperability that dictate contractor certification thresholds for cross-border corridors. India's Ministry of Railways and Dedicated Freight Corridor Corporation impose domestic-content requirements and phased manufacturing program obligations that reshape vendor eligibility for publicly funded projects. China's National Railway Administration and Ministry of Transport coordinate state-owned contractor deployment along Belt and Road rail corridors, blending export finance with construction execution. Stakeholders must monitor how divergent localization mandates and safety standard harmonization timelines reshape bidding strategies across jurisdictions.
Market Dynamics
Digital signaling convergence with automated train operation is compressing contractor qualification timelines while fragmenting traditional civil-electrical-mechanical specialization boundaries across procurement packages.
Growth Catalysts
- EU Safety Mandates:The European Union Agency for Railways Common Safety Methods are forcing corridor-wide interoperability upgrades that bundle signaling, electrification, and track renewal into single-source contracts.
- Urban Rail Density:Southeast Asian megacities including Jakarta, Bangkok, and Ho Chi Minh City are consolidating metro construction with 25-year maintenance concessions to attract long-horizon infrastructure capital.
- Domestic Content Rules:India's Phased Manufacturing Program obligations for metro and freight corridor projects are redirecting component sourcing toward local joint ventures and technology transfer partnerships.
Market Restraints
- Steel and Copper Volatility:Track rail, overhead catenary, and substation equipment face input cost swings that erode fixed-price contract margins during multi-year execution periods.
- Signaling Technology Concentration:European and Japanese suppliers dominate communications-based train control intellectual property, limiting contractor choice for automated metro and mainline projects.
- Cross-Border Certification Friction:Divergent national safety approvals for rolling-stock-integrated systems delay handover timelines and inflate compliance overhead on international corridors.
Strategic Opportunities
- African Belt and Road Corridors:Chinese state-backed export finance is packaging construction with equipment supply across Kenya, Ethiopia, and Nigeria, opening turnkey contractor entry points.
- Battery-Electric Traction:Convergence of lithium-ion powerpacks with conventional electrification infrastructure is creating hybrid system design contracts for non-electrified branch lines.
- Performance-Based Maintenance:Availability-contract structures that tie contractor payments to uptime metrics are displacing conventional time-and-materials service agreements in European and Australian markets.
Industry Challenges
- Systems Integration Talent Gap:Scarce expertise in integrating legacy signaling with European Train Control System Level 2 deployment is extending commissioning timelines and inflating specialist labor costs.
- Multi-Stakeholder Coordination Complexity:Bundled tenders requiring simultaneous civil, electrical, and rolling-stock delivery create interface risk allocation disputes between prime contractors and specialist subcontractors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Train Contractor Market |
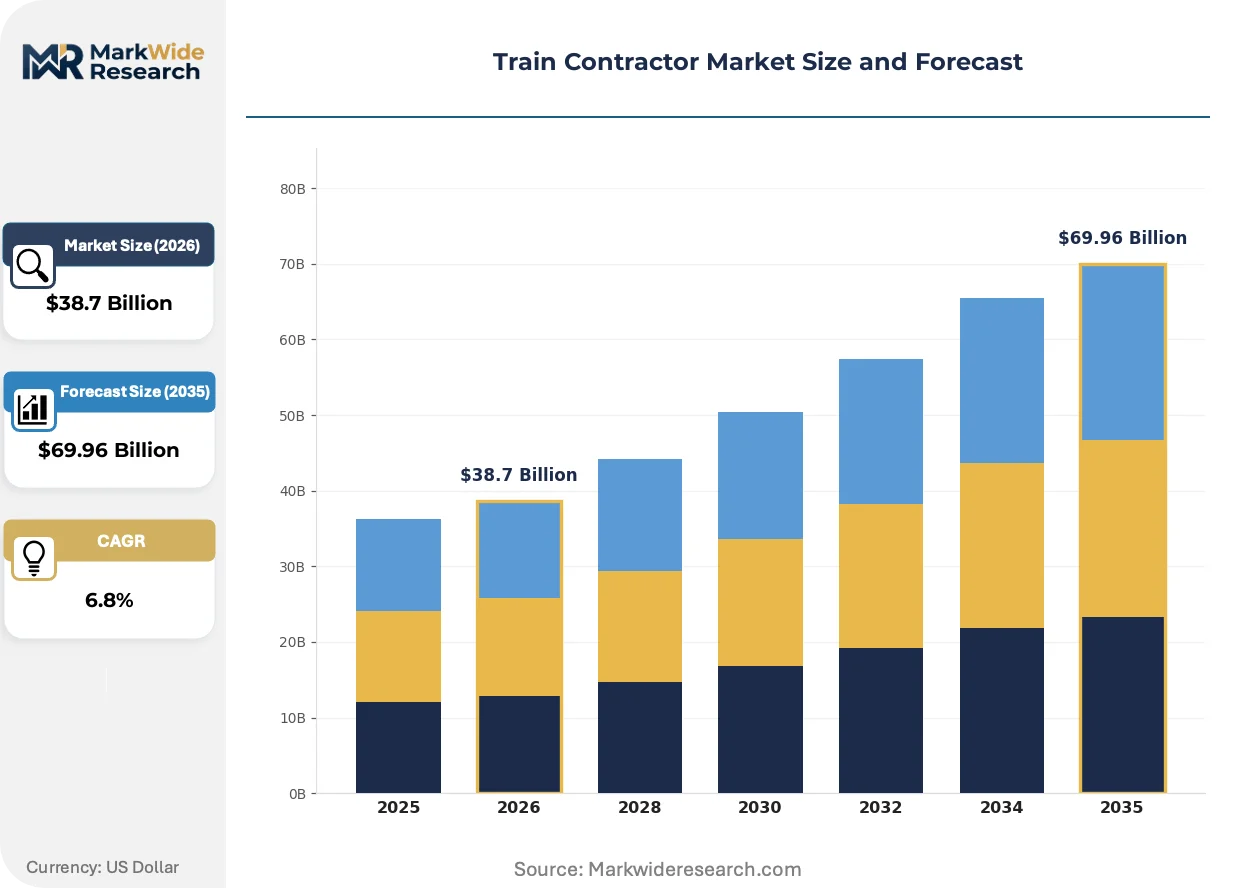
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Construction, Maintenance, Repair, Inspection End User: Government Agencies, Private Operators, Freight Companies, Commuter Services Project Scope: New Build, Upgrade, Rehabilitation, Demolition Technology: Electrification, Signaling Systems, Automation, Safety Solutions |
| Companies Covered | CRRC Corporation Limited, Alstom SA, Siemens AG, Stadler Rail AG, Wabtec Corporation, Hitachi Rail Limited, China Railway Group, China Railway Construction Corporation, Bombardier Transportation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Train Contractor Market Emerging Trajectories
Automation and digitalization are collapsing the traditional sequencing of rail infrastructure delivery, compressing design-build-handover cycles while elevating data-driven performance guarantees in contract structures.
Communications-based train control systems with moving-block signaling are rendering obsolete fixed-block track circuits and wayside signal infrastructure. Urban metro operators in Riyadh, Doha, and Singapore are mandating GoA4 unattended operation for new lines, forcing contractors to absorb signaling-vehicle integration risk that previously sat with separate equipment suppliers.
REACH chemical restrictions and the EU F-Gas Regulation are phasing out sulfur hexafluoride in high-voltage switchgear used for traction substations. Equipment manufacturers must redesign gas-insulated switchgear portfolios around fluoronitrile or vacuum interruption technologies, with German and French corridor projects imposing the tightest compliance deadlines.
Buyers are unbundling rolling-stock procurement from infrastructure construction on greenfield high-speed lines in Morocco, Egypt, and Uzbekistan. This separation allows national railways to optimize vehicle financing independently while forcing civil contractors to deliver track and electrification systems compatible with multiple supplier platforms, elevating interface specification discipline.
Train Contractor Market Segmentation
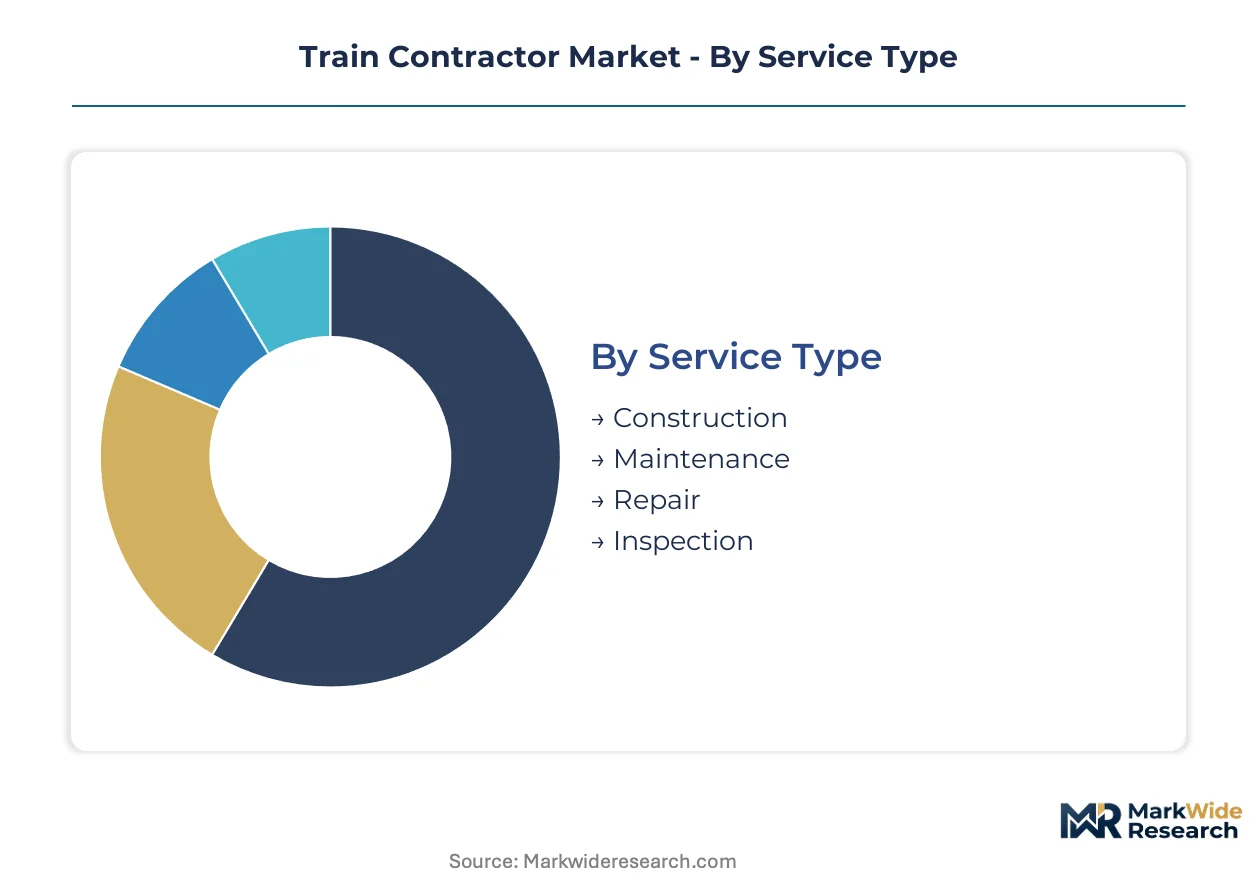
Train contractor procurement bundles disparate technical capabilities into unified tenders, making segment boundaries increasingly porous as buyers consolidate civil, electrical, and systems work. Understanding how service types, end users, project scopes, and technology layers intersect determines bidding strategy and partnership formation.
Service Type:
Mature maintenance contracts anchor recurring revenue streams while emerging construction formats absorb capital deployment risk through turnkey structures.
- Construction:Greenfield rail lines, stations, and depots demand integrated civil-electrical-mechanical execution under fixed-price agreements with multi-year horizons. India's Dedicated Freight Corridor Corporation bundles track, electrification, and signaling into single-source awards spanning hundreds of route-kilometers.
- Maintenance:Scheduled preventive and corrective work on track, rolling stock, and fixed infrastructure generates annuity-like cash flows under 15-25 year concessions. Southeast Asian metro operators in Jakarta and Bangkok package construction with long-haul maintenance to attract infrastructure fund capital.
- Repair:Unplanned restoration of storm-damaged embankments, flood-affected signaling, or collision-impacted track sections operates on emergency mobilization terms.
- Inspection:Ultrasonic rail testing, overhead line geometry verification, and tunnel structural assessment contracts deploy specialized measurement trains and drone-based surveys.
Construction retains volume leadership; maintenance holds the steepest expansion curve as availability-based payment structures displace conventional time-and-materials billing.
End User:
Public procurement concentration shapes qualification requirements while private capital deployment introduces alternative financing mechanisms.
- Government Agencies:National railways, transport ministries, and municipal transit authorities specify domestic content thresholds, safety certification tiers, and technology transfer obligations. India's Ministry of Railways imposes Phased Manufacturing Program requirements that reshape vendor eligibility.
- Private Operators:Concession-based rail freight and passenger services in Brazil, Mexico, and Australia negotiate design-build-operate-maintain contracts with revenue-sharing mechanisms. These entities prioritize whole-life cost optimization over lowest capital expenditure.
- Freight Companies:Mining and logistics corporations fund dedicated heavy-haul lines connecting extraction sites to export terminals, specifying axle-load ratings above standard network limits.
- Commuter Services:Urban rail agencies in Riyadh, Doha, and Singapore mandate GoA4 unattended operation, forcing contractors to absorb vehicle-signaling integration risk.
Government agencies dominate contract value; private operators are gaining share fastest as availability-payment structures proliferate.
Project Scope:
Capital intensity gradients separate greenfield development from asset renewal, with each tier demanding distinct risk allocation frameworks.
- New Build:Greenfield corridors on previously undeveloped land require land acquisition coordination, environmental clearance sequencing, and virgin subgrade preparation. Morocco, Egypt, and Uzbekistan high-speed lines exemplify this category.
- Upgrade:Capacity expansion through additional tracks, station remodeling, and speed enhancement on existing alignments demands operational railway protection protocols. European corridors undergoing ETCS Level 2 retrofit fall here.
- Rehabilitation:Structural renewal of aging bridges, tunnels, and earthworks without capacity alteration extends asset life while maintaining traffic. UK's Network Rail renewals program illustrates this scope.
- Demolition:Decommissioned industrial spurs, redundant freight yards, and abandoned metro infrastructure require environmental remediation and materials recovery.
New build commands the largest absolute spend; upgrade work expands most quickly as European interoperability mandates accelerate corridor-wide renewal.
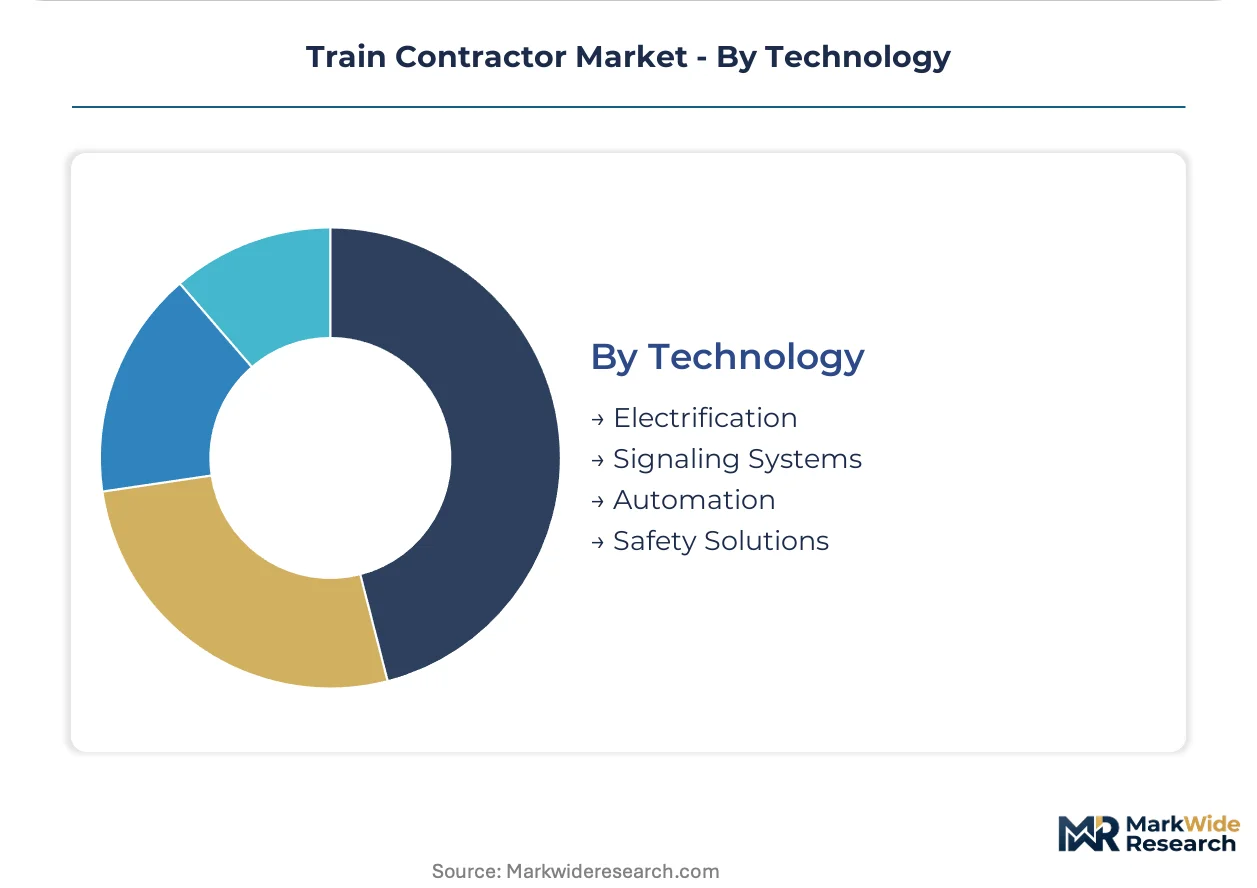
Technology:
Digital layers command margin premiums over conventional civil construction as signaling-electrification convergence reshapes contractor specialization.
- Electrification:Overhead catenary systems, substations, and traction power distribution networks convert diesel corridors to electric operation. REACH chemical restrictions and EU F-Gas Regulation are phasing out sulfur hexafluoride in high-voltage switchgear, forcing equipment redesign around fluoronitrile or vacuum interruption.
- Signaling Systems:Communications-based train control with moving-block operation replaces fixed-block track circuits. European and Japanese suppliers dominate CBTC intellectual property, constraining contractor choice for automated metro deployment.
- Automation:Driverless train operation platforms integrate platform screen doors, automatic train supervision, and precision docking systems. Urban metro mandates in Gulf Cooperation Council states and Singapore accelerate adoption.
- Safety Solutions:Automatic train protection, obstacle detection, and fire suppression systems satisfy national safety regulator certification thresholds including EU Agency for Railways Common Safety Methods.
Electrification retains installed base dominance; signaling systems follow the steepest trajectory as digital convergence compresses design-build-handover cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Contractor capacity clusters in China, Germany, India, and Japan, with state-backed consortia and private engineering groups competing for cross-border corridor awards. Domestic content mandates and safety certification regimes fragment procurement across national boundaries.
China
Belt and Road rail corridors in Kenya, Ethiopia, and Nigeria absorb turnkey construction-and-equipment packages financed through state-backed export credit. The National Railway Administration coordinates contractor deployment alongside rolling-stock supply, blending construction execution with equipment financing. CRRC Corporation Limited and China Railway Construction Corporation anchor project delivery from Beijing and Shanghai hubs.
Germany
European high-speed rail upgrades under EU Agency for Railways mandates bundle signaling-electrification-track renewal into single-source awards. REACH chemical restrictions and F-Gas Regulation compliance deadlines force equipment redesign for traction substations. Siemens AG anchors corridor modernization from Munich and Berlin engineering centers.
India
The Dedicated Freight Corridor Corporation and metro rail corporations bundle electrification, signaling, and civil works into large-scale tenders exceeding hundreds of route-kilometers. Phased Manufacturing Program obligations redirect component sourcing toward local joint ventures with technology transfer requirements. Contractor specialization fragments between civil infrastructure consortia and rolling-stock-integrated system providers in Delhi-Mumbai industrial corridors.
Japan
Communications-based train control intellectual property concentration supports automated metro and mainline project execution across Asia-Pacific. METI-coordinated export finance packages construction with signaling technology licensing for overseas markets. Hitachi Rail Limited represents the integrated engineering-manufacturing archetype from Tokyo and Osaka metropolitan bases.
United States
Freight railroad capital programs and Amtrak corridor upgrades sustain demand for track renewal and signaling modernization. Federal Railroad Administration safety mandates shape contractor certification thresholds for positive train control deployment. Wabtec Corporation occupies the freight-focused technology-integration position from Pennsylvania and California operational centers.
Train Contractor Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream. The vendor base separates into consolidated turnkey providers and fragmented civil-electrical subcontractors. Three archetypes dominate: state-backed engineering conglomerates bundling construction with equipment supply; European-Japanese technology integrators anchoring signaling-electrification convergence; and North American freight specialists optimizing heavy-haul infrastructure. Competitive positioning hinges on geographic expansion through export finance packaging and backward integration into captive manufacturing capacity.
Among state-backed Chinese conglomerates, CRRC Corporation Limited and China Railway Construction Corporation exemplify the construction-equipment bundling archetype across Belt and Road corridors. Siemens AG and Alstom SA represent the European signaling-electrification integration tier competing for high-speed and automated metro contracts. These five entities anchor the competitive structure without exhausting the participant base.
| Leading Market Players |
|---|
| CRRC Corporation Limited |
| Alstom SA |
| Siemens AG |
| Stadler Rail AG |
| Wabtec Corporation |
| Hitachi Rail Limited |
| China Railway Group |
| China Railway Construction Corporation |
| Bombardier Transportation |
| Others |
Supply Flow & Price Mechanics
Tangshan steel rail manufacturing clusters anchor global track supply capacity, with their output fluctuations transmitting directly into contractor bidding power across Asian and African procurement cycles. Buyers in price-sensitive markets face compressed margins when raw material volatility coincides with fixed-price tender structures.
Pricing Analysis
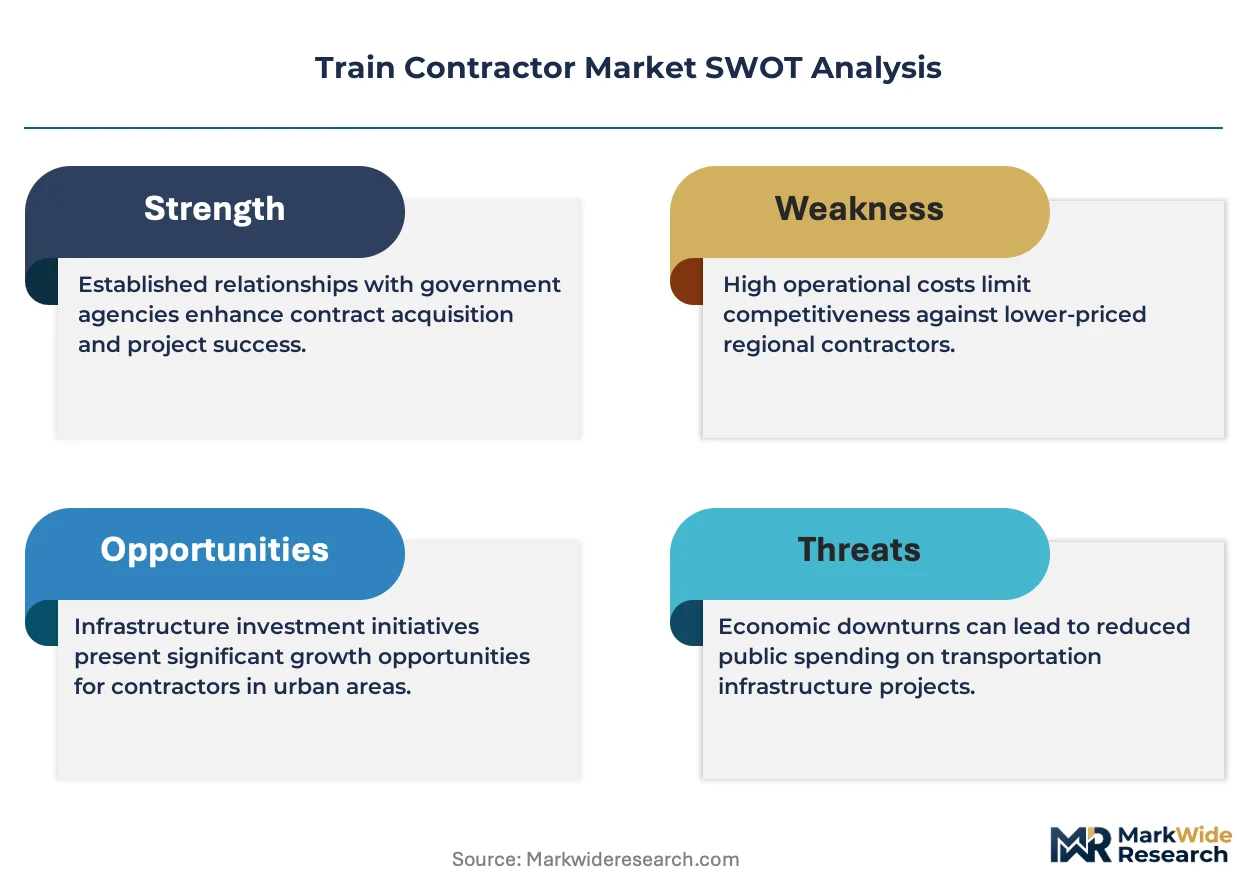
The European Union Agency for Railways Common Safety Methods dictates the pricing tier structure across cross-border corridor contracts. Three-tier pricing separates ETCS Level 2 certified integrators from conventional signaling contractors and basic civil infrastructure vendors. Price differentiation hinges on certification grade and domestic content compliance. Cost compression in standard electrification packages is intensifying because Chinese state-backed consortia underbid on bundled construction-and-equipment awards. Government agencies in India and Southeast Asia exhibit highest price sensitivity; Gulf Cooperation Council metro authorities prioritize whole-life availability over lowest capital expenditure.
Supply Chain Analysis
High-grade steel rail production draws from China, Japan, and Germany, while copper catenary wire concentrates in Chile and Zambia extraction sites. Lithium-ion battery powerpacks for hybrid traction systems feed from South Korean and Chinese cell manufacturers. Single-source vulnerability in communications-based train control intellectual property constrains contractor choice for automated metro deployment. Distribution runs through state-backed export finance packages on Belt and Road corridors, blending construction execution with equipment supply into unified turnkey structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The train contractor market exhibits cyclical recovery characteristics as deferred European interoperability upgrades and Southeast Asian urban rail densification release pent-up procurement volume. Steel and copper input cost normalization supports margin stabilization across multi-year execution timelines.
For Market Incumbents: Insulate signaling-electrification integration capabilities from emerging Chinese construction-equipment bundlers by deepening captive manufacturing of digital control systems. Prioritize certification investment in EU Agency for Railways Common Safety Methods tiers that emerging entrants cannot replicate without decade-long track records. Anchor capacity in Indian joint ventures to satisfy Phased Manufacturing Program domestic content thresholds.
For New Entrants and Emerging Players: African Belt and Road secondary corridors represent the most penetrable entry point where Chinese state-backed financing has not yet saturated contractor relationships. Battery-electric traction retrofits for non-electrified branch lines in Australia and Brazil offer technology-differentiated positioning against incumbent electrification specialists. Pursue performance-based maintenance concessions with infrastructure fund co-investment to bypass capital-intensive construction qualification barriers.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors signaling-electrification integrators with ETCS Level 2 deployment track records over pure civil infrastructure contractors facing commodity input volatility. Long-term viability rests on automation convergence capabilities spanning platform screen doors, automatic train supervision, and precision docking systems. Monitor European corridor award timelines and Indian Dedicated Freight Corridor Corporation tender release cadence as inflection indicators for contractor backlog quality.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Digital Signaling IP | Captive control over CBTC and ETCS Level 2 systems reduces licensing costs to European and Japanese patent holders. |
| Joint Venture Formation for Domestic Content Compliance | Indian Phased Manufacturing Program obligations require local component sourcing partnerships for metro and freight corridor eligibility. |
| Performance-Based Maintenance Concession Bidding | Availability contracts tying payments to uptime metrics attract infrastructure fund capital in European and Australian markets. |
| Battery-Electric Traction System Development | Hybrid powerpack integration for non-electrified lines creates differentiation against conventional overhead catenary specialists. |
| EU Safety Certification Tier Advancement | Common Safety Methods compliance unlocks cross-border corridor awards with premium pricing over national-only qualified competitors. |
Methodological Framework
Initial hypotheses were tested against primary input from rail project procurement directors, signaling system integration engineers, infrastructure fund investment officers, and national railway planning executives and refined through secondary validation against European Union Agency for Railways certification databases, Indian Ministry of Railways tender archives, Belt and Road project finance disclosures, and customs trade data for steel rail and copper wire imports. Bottom-up contractor capacity assessments and top-down national rail investment program aggregations were triangulated to establish market sizing boundaries.
Demand-supply balance modeling across the projection horizon incorporated service type segmentation by construction, maintenance, and repair intensity; end user categorization across government agencies, private operators, and freight corporations; project scope differentiation between new build, upgrade, and rehabilitation; and technology layer stratification spanning electrification, signaling, automation, and safety systems. CAGRs were derived from corridor-specific award timelines and maintenance concession renewal patterns, with inputs from steel and copper price trajectory assumptions and regulatory compliance deadline clustering.
Practitioners should monitor EU interoperability mandate acceleration, Indian Phased Manufacturing Program enforcement stringency, and Chinese export finance availability for early signals of contractor competitive intensity shifts. Quarterly review of national railway capital budget approvals and raw material futures curves is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Services
Condenser Cleaners Market
Construction Services
Maintenance Repair and Operations (MRO) Market
Construction Services
Dust Suppression Control Market
Construction Services
North America Testing and Commissioning Market
Construction Services
Industrial Maintenance Services Market
Construction Services
Construction Materials Testing Equipment Market
Construction Services
Grease Trap Service Market
Construction Services
Composite Autoclave Repair Market
Construction Services
Excavating Contractor Market
Construction Services
Facade Cleaning and Maintenance Service Market
Construction Services
North America Repair and Rehabilitation Market
Construction Services
Middle East and Africa Industrial Maintenance Services in Operational Improvement and Operational Maintenance Market
Construction Services
Europe Maintenance, Repair, and Operations (MRO) Market
Construction Services
Forklift Repair and Maintenance Service Market
Construction Services
MENA Architectural Services Market
Construction Services
Construction Project Management Services Market