
 Gutter Cleaning Services Market | 2026-2036
Gutter Cleaning Services Market Size, Share, and Industry Trends Forecast 2026-2036
Gutter Cleaning Services Market Insights
The gutter cleaning industry is shifting between premium subscription models and one-time commodity dispatch. Ned Stevens Gutter Cleaning leverages recurring maintenance plans to sustain predictable revenue across seasonal cycles. The Brothers that Just Do Gutters anchors its position through franchise-standardized training and localized territory control. Window Genie differentiates by bundling gutter work with pressure washing and window cleaning under unified scheduling.
Gutter cleaning services encompass the removal of leaves, sediment, and debris from roof drainage systems to prevent water damage, foundation erosion, and pest harborage; technicians typically operate from ladders, aerial lifts, or ground-based vacuum systems depending on building height and access constraints. Residential cleaning occupies the largest volume share as aging housing stock and mature suburban tree cover generate persistent clogging cycles. Robotics represents the fastest-expanding technology segment, though manual tools still dominate margin capture in complex architectural settings where automated systems face access limitations.
OSHA fall-protection standards and state contractor licensing boards shape operational compliance costs and barrier to entry for new entrants. EPA stormwater runoff guidelines increasingly tie gutter maintenance to municipal drainage system performance, expanding commercial client liability exposure. Facility managers and property owners must weigh capital investment in gutter guard systems against recurring service expenditures as climate-intensified precipitation patterns strain legacy drainage infrastructure.
Market Dynamics
Property management firms now drive volume concentration as institutional owners outsource building envelope maintenance, while OSHA fall-protection mandates force capital reallocation toward aerial lift equipment and technician certification programs.
Growth Catalysts
- Hurricane-season debris accumulation:Dense tree canopy in the southeastern United States creates recurring service requirements that sustain predictable revenue cycles for regional operators.
- EPA stormwater runoff guidelines:Municipal drainage system performance standards tie gutter maintenance to commercial client liability exposure, expanding contract scope for facility managers.
- Robotics technology:Ground-based vacuum systems and automated cleaning tools penetrate residential segments where labor availability constrains manual service capacity.
Market Restraints
- Capital equipment intensity:OSHA-compliant aerial lifts and fall-arrest systems require substantial upfront investment that compresses margins for independent contractors.
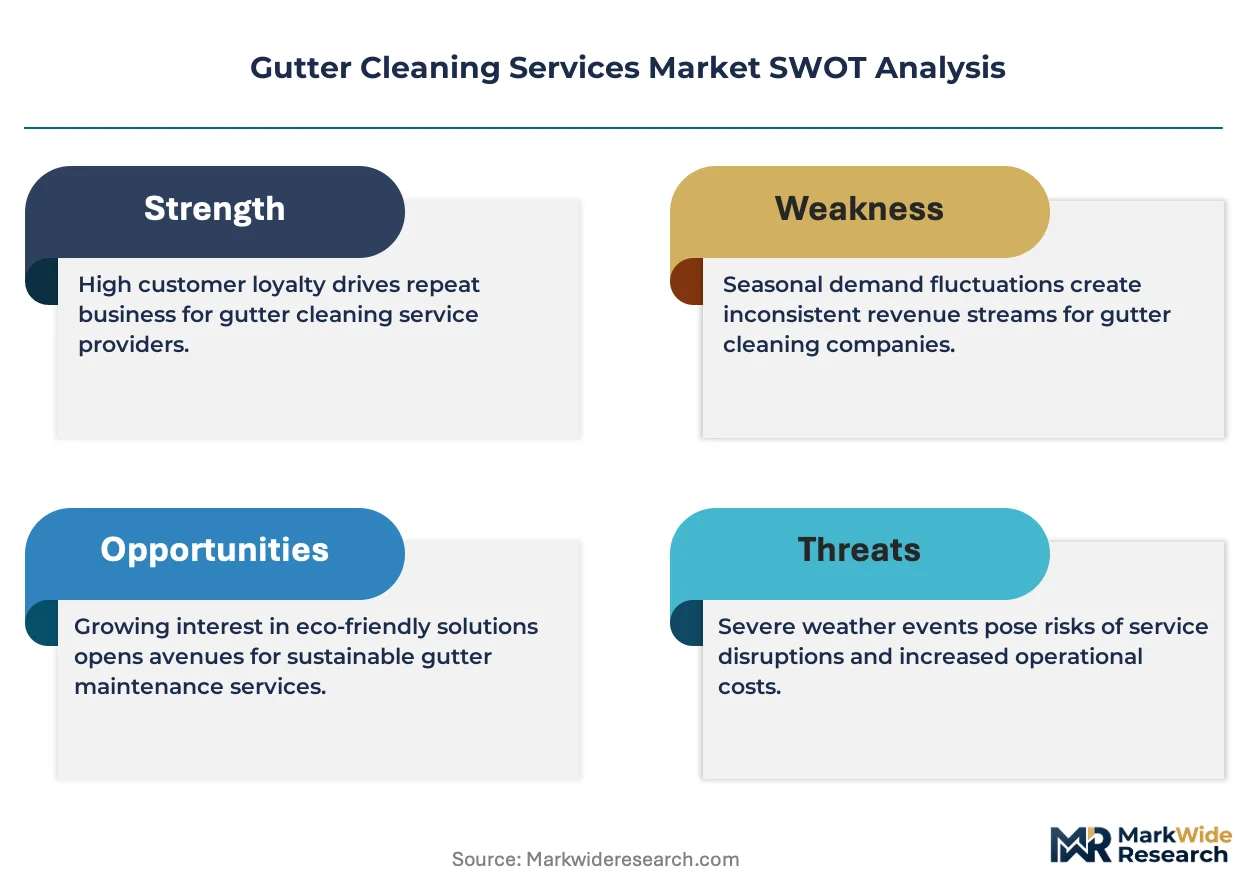
- Seasonal demand volatility:Weather-dependent scheduling concentrates revenue in narrow windows, straining cash flow management across the fiscal year.
- Gutter guard substitution:Capital investment in physical barrier systems by property owners reduces recurring service dependency in mature suburban markets.
Strategic Opportunities
- Subscription model penetration:Recurring maintenance plans displace one-time dispatch services among aging housing stock owners seeking predictable home maintenance budgeting.
- Climate-intensified precipitation:Legacy drainage infrastructure strain from altered rainfall patterns expands commercial client urgency for proactive system maintenance.
- Cross-service bundling:Unified scheduling platforms that combine gutter work with pressure washing and window cleaning capture higher per-visit revenue.
Industry Challenges
- Technician certification pipelines:State-level ladder-safety directives and OSHA compliance requirements lengthen training timelines and constrain workforce expansion velocity.
- Equipment utilization optimization:Aerial lift fleet deployment across dispersed geographic territories demands sophisticated routing logistics to recover capital costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gutter Cleaning Services Market |
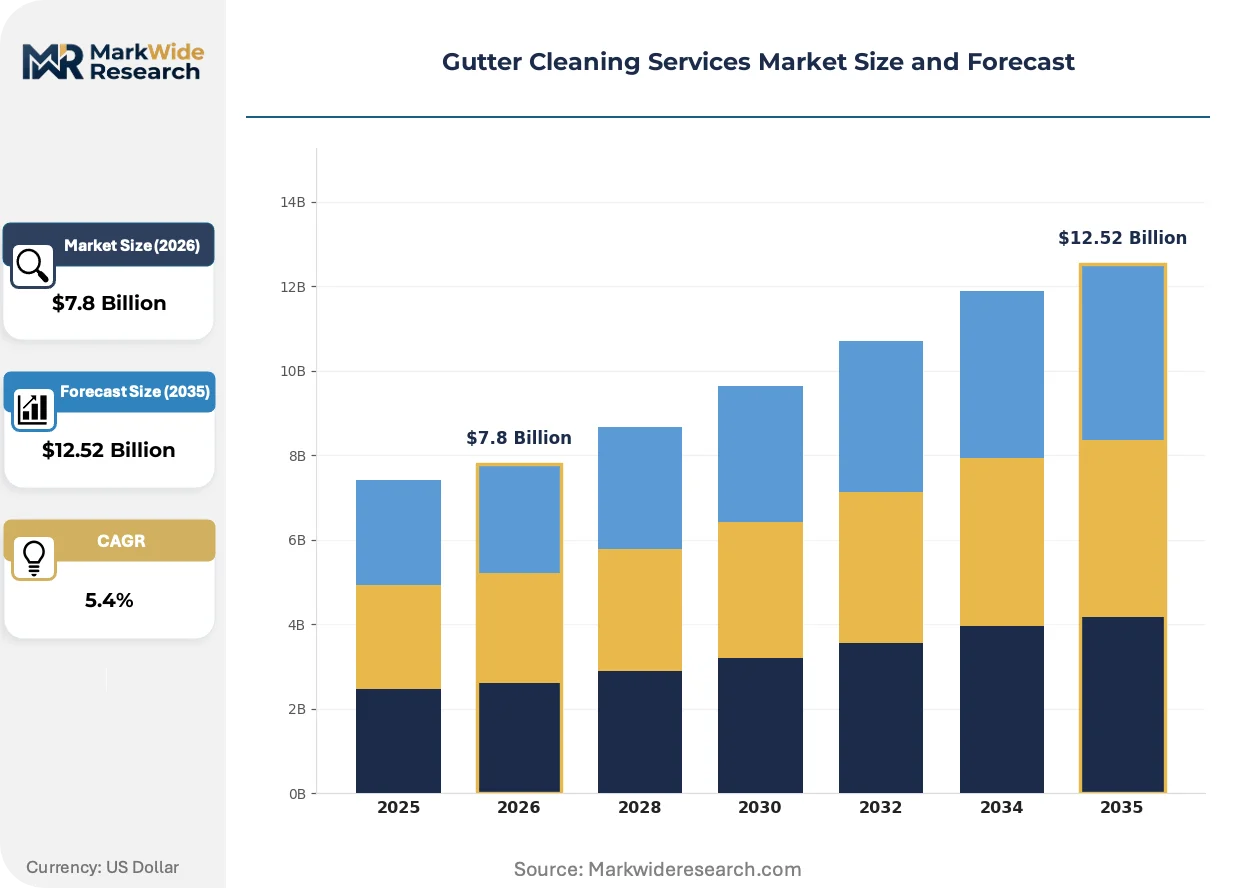
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $12.52 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Residential Cleaning, Commercial Cleaning, Gutter Installation, Downspout Clearing Customer Type: Homeowners, Property Managers, Facility Managers, Real Estate Agents Frequency: Biannual Cleaning, Annual Cleaning, Seasonal Cleaning, One-Time Service Technology: Manual Tools, Pressure Washing, Robotics, Vacuum Systems |
| Companies Covered | The Brothers that Just Do Gutters, Ned Stevens Gutter Cleaning, Window Genie, Men In Kilts, LeafFilter, ServiceMaster Restore, Gutter Helmet, All American Gutter Protection, Shack Shine, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gutter Cleaning Services Market Trends and Innovations
Service delivery models are compressing toward integrated maintenance platforms that unify scheduling, billing, and cross-trade coordination. Technology adoption accelerates where labor scarcity and safety compliance costs intersect.
Ground-based vacuum extraction systems with telescopic reach capabilities are unifying residential and low-rise commercial access methods. Property management firms in labor-constrained markets adopt these tools to reduce technician exposure hours. The technology is unifying previously separate ladder-dependent and lift-dependent service tiers into a single equipment category.
OSHA fall-protection standards now mandate documented hazard assessments and personal arrest systems for work above specified heights. Compliance costs have shifted competitive advantage toward capitalized operators with dedicated safety officers. Multi-site commercial clients in the United States increasingly require proof of compliance before contract award.
Facility managers now consolidate building envelope maintenance under single-source contracts rather than fragmenting across specialty trades. This procurement compression favors service providers with cross-trained technicians and unified scheduling platforms. The shift is most visible in institutional property portfolios where procurement standardization reduces vendor management overhead.
Gutter Cleaning Services Market Segmentation
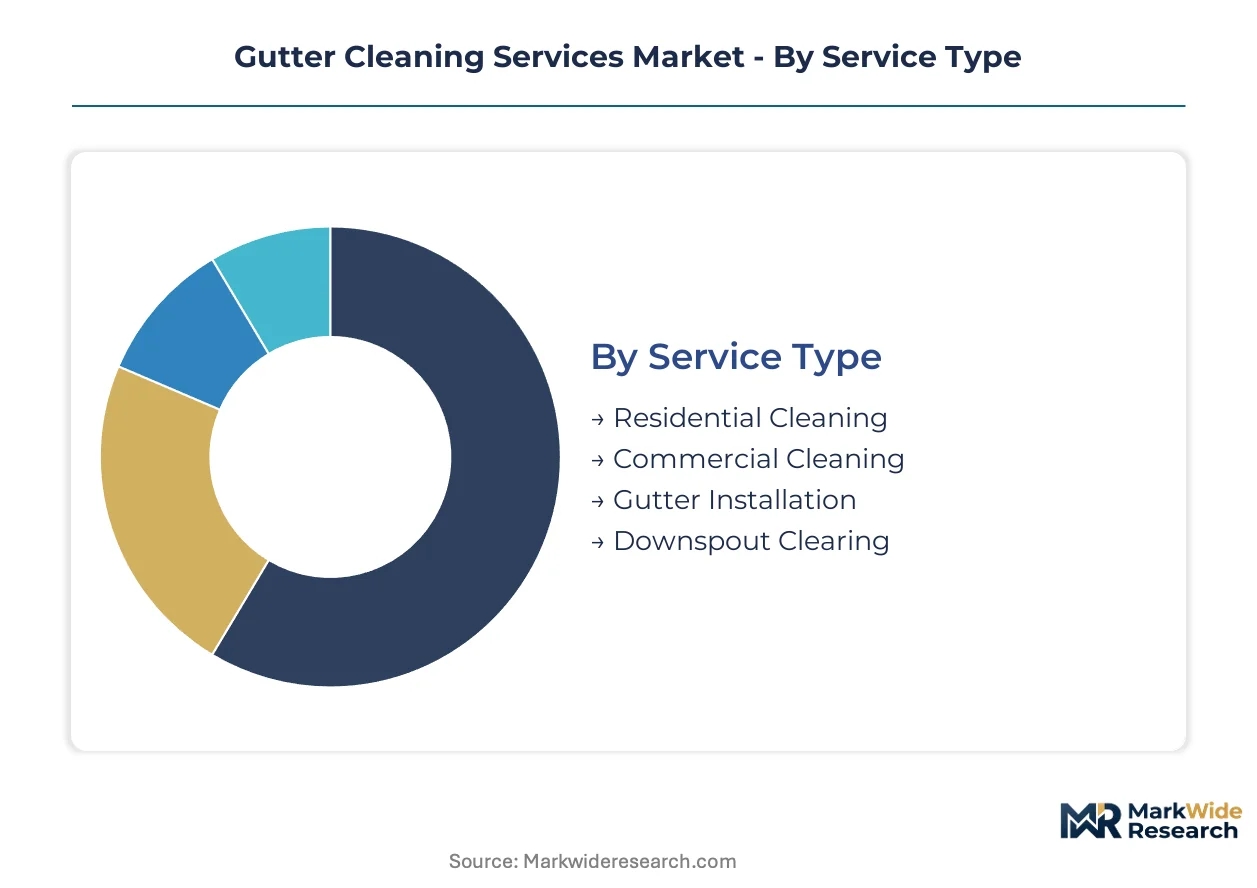
Gutter cleaning markets fragment sharply between routine maintenance contracts and specialized installation work. Service providers must align equipment investments and technician training with the specific revenue concentration within each segment tier.
Service Type:
Residential cleaning commands volume dominance while commercial contracts capture premium pricing through liability complexity and access constraints.
- Residential Cleaning:Technicians remove leaves, sediment, and debris from single-family roof drainage systems using ladders or ground-based vacuum systems. Demand clusters in southeastern United States suburbs where mature oak and pine canopy generate recurring clogging cycles alongside hurricane-season debris accumulation.
- Commercial Cleaning:Multi-story buildings and institutional portfolios require aerial lift deployment and OSHA-compliant fall-arrest systems for technician safety. Property management firms in dense urban markets consolidate these contracts under building envelope maintenance budgets to reduce vendor management overhead.
- Gutter Installation:New construction and replacement projects involve aluminum, steel, or vinyl system fabrication with precise slope engineering for drainage performance.
- Downspout Clearing:Specialized service addressing underground drainage connections and foundation perimeter systems prone to root intrusion and sediment compaction.
Today's leader: Residential Cleaning. Tomorrow's challenger: Commercial Cleaning.
Customer Type:
Institutional procurement patterns diverge from individual consumer behavior in contract structure, price sensitivity, and compliance documentation requirements.
- Homeowners:Individual property owners schedule reactive services following visible overflow or seasonal reminders, with price transparency from digital platforms compressing margin capture.
- Property Managers:Institutional owners outsource building envelope maintenance through multi-year agreements with standardized service level specifications and documented safety compliance.
- Facility Managers:Corporate and government building operators integrate gutter work into comprehensive facilities management contracts with cross-trade coordination requirements.
- Real Estate Agents:Transaction-triggered services address inspection findings and curb appeal optimization for property listings.
Property Managers now drive volume concentration fastest. Homeowners retain absolute transaction count leadership.
Frequency:
Revenue predictability separates subscription-based operators from weather-dependent dispatch services in cash flow stability and customer lifetime value.
- Biannual Cleaning:Spring and fall service cycles align with peak leaf shed periods and pre-winter drainage verification. Aging housing stock owners in deciduous forest zones prioritize this schedule to prevent ice dam formation and foundation moisture intrusion.
- Annual Cleaning:Single yearly maintenance suits properties with gutter guard systems or minimal tree canopy exposure where debris accumulation remains moderate.
- Seasonal Cleaning:Hurricane-prone coastal markets require pre-storm system verification and post-event debris removal on compressed timelines.
- One-Time Service:Reactive dispatch following visible overflow, pest harborage complaints, or property sale preparation generates spot revenue with highest customer acquisition cost.
Biannual Cleaning anchors recurring revenue models. One-Time Service represents the most vulnerable to gutter guard substitution.
Technology:
Labor scarcity and OSHA compliance costs accelerate capital substitution across residential and low-rise commercial access methods.
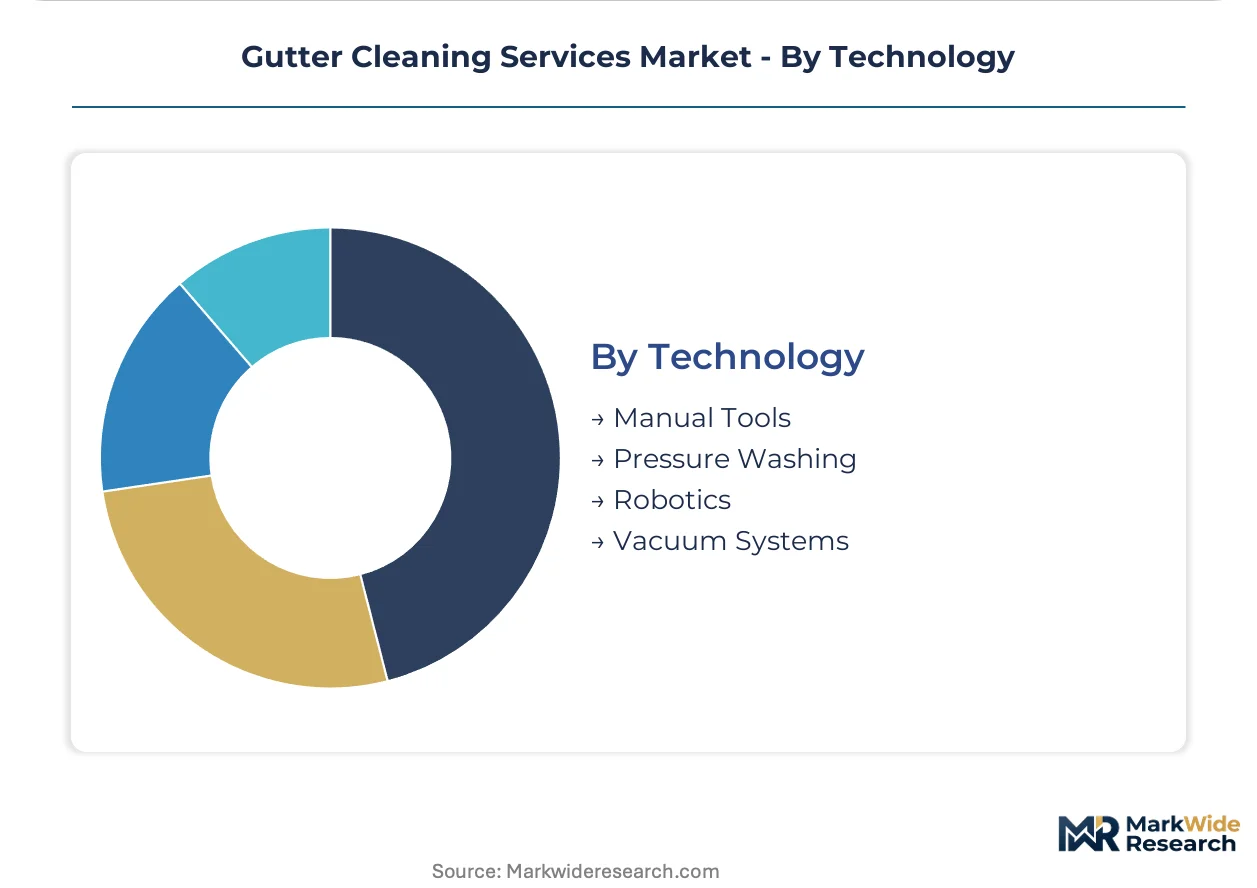
- Manual Tools:Hand scoops, brushes, and flush hoses dominate complex architectural settings with steep pitches, ornate fascia, or limited ground access where automated systems face maneuverability constraints.
- Robotics:Automated ground-based systems with camera guidance and telescopic reach penetrate labor-constrained markets by reducing technician exposure hours and enabling single-operator deployment.
- Pressure Washing:High-velocity water systems clear compacted sediment and biological growth from interior gutter surfaces and downspout channels.
- Vacuum Systems:Truck-mounted or portable debris extraction equipment with carbon fiber pole extensions unify previously separate ladder-dependent and lift-dependent service tiers.
Manual Tools retain margin leadership in architectural complexity. Robotics climbs the fastest as labor availability tightens and safety compliance costs escalate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled technician pools concentrate in southeastern states with dense tree canopy coverage, where hurricane-season debris cycles sustain recurring service demand. OSHA-certified workforces in the Northeast command premium wages due to stricter fall-protection enforcement. Regional fragmentation persists as localized operators dominate suburban markets with limited national brand penetration.
United States
Mature oak and pine canopy across Georgia, Florida, and the Carolinas generates biannual clogging cycles that sustain predictable revenue streams. OSHA fall-protection mandates compel capital investment in aerial lift fleets and documented hazard assessment protocols. Atlanta anchors the largest regional operator concentration, where property management firms consolidate building envelope maintenance contracts under standardized service specifications.
Canada
Ice dam prevention drives spring and fall service urgency in Ontario and British Columbia, where aging housing stock requires proactive drainage verification. Provincial occupational health regulators enforce ladder-safety training requirements that lengthen technician certification timelines. Toronto's suburban ring hosts the densest franchise operator networks, competing for single-family homeowners seeking subscription-based maintenance budgeting.
United Kingdom
Historic building stock with ornate fascia and steep pitches preserves demand for manual tool expertise that automated systems cannot replicate. HSE working-at-height regulations mandate comprehensive risk assessments for residential and commercial access work. London's property management sector leads procurement consolidation, bundling gutter maintenance with window cleaning and pressure washing under unified facilities contracts.
Australia
Eucalyptus leaf shed and bushfire debris accumulation create unique clogging patterns distinct from northern hemisphere deciduous cycles. Safe Work Australia guidelines govern fall-arrest system deployment across residential and commercial roof access scenarios. Sydney's strata management companies drive commercial contract volume, outsourcing envelope maintenance for multi-unit residential portfolios.
Germany
Precise slope engineering standards for drainage performance elevate technical skill requirements beyond debris removal alone. DGUV regulations mandate documented safety training for roof and facade access work above specified height thresholds. Munich's commercial property clusters exhibit highest subscription model penetration, with facility managers prioritizing predictable maintenance expenditures over reactive dispatch services.
Gutter Cleaning Services Market Competitive Landscape
Capital-heavy equipment operators compete with asset-light franchise licensors for margin capture across residential and commercial segments. Market structure fragments between national subscription platforms, regional lift-equipped fleets, and localized ladder-dependent contractors serving dense suburban territories. Three archetypes dominate: recurring revenue specialists anchoring customer lifetime value, cross-service bundlers capturing higher per-visit revenue, and installation-forward players monetizing gutter guard substitution. Competitive moves concentrate on franchise territory expansion and safety compliance certification as procurement differentiators.
Within the recurring revenue archetype, Ned Stevens Gutter Cleaning and The Brothers that Just Do Gutters exemplify contrasting scale strategies. Window Genie occupies a position among cross-service bundlers, representing the unified scheduling platform approach that combines gutter work with pressure washing and window cleaning. These three names anchor the visible competitive set, though localized operators retain substantial share in markets where technician relationships and rapid response times outweigh brand recognition.
| Leading Market Players |
|---|
| The Brothers that Just Do Gutters |
| Ned Stevens Gutter Cleaning |
| Window Genie |
| Men In Kilts |
| LeafFilter |
| ServiceMaster Restore |
| Gutter Helmet |
| All American Gutter Protection |
| Shack Shine |
| Others |
Pricing and Supply Chain Analysis
Property management firm consolidation into multi-year building envelope contracts forces service providers to absorb upfront aerial lift capital costs and certified technician training investments, compressing margins until fleet utilization rates cross threshold efficiency. This procurement compression shifts competitive advantage toward capitalized operators with dedicated safety officers and documented OSHA compliance protocols.
Pricing Analysis
Bundled subscription maintenance plans separate from unbundled one-time dispatch services across residential and commercial tiers. Three-tier pricing structure across premium subscription, standard biannual, and economy reactive service levels reflects technician certification grade and liability insurance coverage depth. Cost compression in the unbundled tier intensifies because digital price transparency platforms enable homeowner comparison shopping. Homeowners exhibit highest price sensitivity; institutional property managers prioritize compliance documentation over per-service cost minimization.
Supply Chain Analysis
Dual-sourcing requirements from multi-site commercial clients compel regional operators to qualify multiple aerial lift equipment vendors and certified technician training providers. Equipment manufacturing concentrates in the United States, China, and Germany; aluminum gutter system fabrication feeds from domestic sheet metal processors. Supply chain risk centers on single-source vulnerability for OSHA-compliant fall-arrest system components subject to extended lead times. Distribution runs through localized fleet depots with technician dispatch radius optimization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Institutional buyers now mandate proof of OSHA fall-protection compliance and documented technician certification before contract award, elevating specification thresholds.
For Market Incumbents: Acquire aerial lift fleet capacity in hurricane-prone southeastern territories where dense tree canopy sustains recurring revenue cycles. Consolidate fragmented suburban operators to secure technician certification pipelines and optimize equipment utilization across dispersed service territories. Gutter guard substitution technology threatens recurring service dependency; anchor customer lifetime value through subscription maintenance plans that bundle proactive inspection with debris removal. For New Entrants and Emerging Players: Ground-based vacuum robotics with telescopic reach capabilities offer technology-first entry into labor-constrained residential markets where manual service capacity faces absolute constraints. White-space targets include aging suburban housing stock in the southeastern United States with mature oak and pine canopy coverage. Franchise-standardized training platforms enable rapid geographic replication without proprietary technician development timelines. For Investors and Strategic Acquirers: Asymmetric upside sits with recurring revenue specialists anchoring predictable cash flow through subscription maintenance plans rather than weather-dependent dispatch services. Long-term viability favors operators with cross-trained technicians capable of unified scheduling across gutter cleaning, pressure washing, and window cleaning trades. Watch for inflection when municipal EPA stormwater runoff guidelines expand commercial client liability exposure and contract scope.| Strategic Initiative | Industry Significance |
|---|---|
| Technician Certification Pipeline Investment | OSHA-compliant training programs shorten workforce expansion timelines and reduce liability exposure. |
| Aerial Lift Fleet Expansion | Capital equipment deployment enables multi-story commercial contract capture in dense urban markets. |
| Subscription Model Penetration | Recurring maintenance plans displace one-time dispatch services and stabilize cash flow across seasonal cycles. |
| Cross-Service Bundling Platform | Unified scheduling combines gutter work with pressure washing and window cleaning for higher per-visit revenue. |
| Robotics Technology Integration | Ground-based vacuum systems reduce technician exposure hours and enable single-operator residential deployment. |
Research Methodology
Direct dialogue with property management executives, facility maintenance directors, franchise operations managers, and certified gutter cleaning technicians grounded qualitative insights in operational reality. Secondary validation drew from OSHA enforcement records, EPA stormwater guidance documents, state contractor licensing board filings, and equipment manufacturer technical specifications. Bottom-up service provider capacity modeling triangulated against top-down property stock and tree canopy coverage data.
Segmented outputs across service type, customer archetype, frequency tier, and technology category structured the analytical framework over the projection horizon. Residential and commercial volume splits incorporated housing age demographics and institutional property portfolio concentration. CAGRs derived from technician workforce growth constraints, equipment replacement cycles, and climate-intensified precipitation pattern impacts on service urgency.
The model holds under stable OSHA enforcement intensity and continued property management firm consolidation; deviation in aerial lift equipment availability or gutter guard technology penetration rates would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Services
Condenser Cleaners Market
Construction Services
Dust Suppression Control Market
Construction Services
3D Concrete Printing Services Market
Construction Services
Grease Trap Service Market
Construction Services
North America Repair and Rehabilitation Market
Construction Services
Composite Autoclave Repair Market
Construction Services
Construction Materials Testing Equipment Market
Construction Services
Train Contractor Market
Construction Services
Heavy Equipment Training Simulator Market
Construction Services
Global Industrial Services Market
Construction Services
Facade Cleaning and Maintenance Service Market
Construction Services
Work Order Management Market
Construction Services
MENA Architectural Services Market
Construction Services
North America Fire Sprinkler Systems Market
Construction Services
Construction Equipment Repair and Maintenance Services Market
Construction Services
Industrial Maintenance Products Market