
 Maintenance Repair and Operations (MRO) Market | 2026-2036
Maintenance Repair and Operations (MRO) Market Size, Share, and Industry Trends Forecast 2026-2036
Maintenance Repair and Operations (MRO) Market Intelligence
The EU Green Deal is hardening carbon-accounting requirements for industrial supply chains, forcing MRO buyers to track embedded emissions in replacement parts and consumables. W.W. Grainger leverages its North American distribution density to sustain same-day fulfillment for energy-sector contractors. Ferguson PLC anchors its competitive stance through specialized waterworks and HVAC maintenance inventories. Motion Industries differentiates via bearing and power transmission technical support embedded at branch level.
Maintenance Repair and Operations encompasses the procurement, storage, and deployment of spare parts, tools, and consumables required to keep production equipment, facilities, and vehicles in working condition; technical specifications include torque-rated fasteners, viscosity-graded lubricants, and safety-certified personal protective equipment calibrated to ANSI and ISO standards. The primary industrial purpose is minimizing unplanned downtime through preventive replacement and rapid restorative intervention. Fasteners and lubricants command the largest product-type revenue pools due to universal applicability across asset classes, while repair services extract premium margins from aerospace and automotive customers demanding OEM-traceable documentation. Distributors occupy the dominant customer-type channel position by aggregating fragmented supplier bases and offering vendor-managed inventory programs.
OSHA mandates govern workplace safety equipment specifications, EPA regulations restrict solvent-based cleaner formulations, and ISO 55000 standards shape asset-management procurement protocols across industrial buyers. These frameworks elevate compliance costs for smaller distributors while creating certification barriers that favor established suppliers with documented quality systems. Stakeholders must monitor evolving Scope 3 emissions disclosure rules and assess whether their supplier networks can deliver auditable carbon data without service degradation.
Market Dynamics
Industrial asset owners are consolidating supplier relationships around distributors capable of embedding predictive analytics into vendor-managed inventory programs, compressing procurement cycles from quarterly to continuous replenishment.
Growth Catalysts
- EU Green Deal carbon-accounting mandates:Procurement teams must document embedded emissions in replacement fasteners, lubricants, and consumables, creating pull for certified low-carbon MRO suppliers.
- Automotive preventive maintenance expansion:OEMs and tier suppliers are extending service intervals and condition-monitoring protocols, elevating consumption of torque-calibrated fasteners and viscosity-graded synthetic lubricants.
- China industrial facility upgrade wave:State-directed modernization of steel, cement, and chemical plants is accelerating demand for ANSI-compliant safety equipment and ISO-certified power transmission components.
Market Restraints
- Specialty alloy input cost volatility:Fastener and bearing manufacturers face margin compression from nickel and chromium price swings tied to mining supply disruptions.
- Regional solvent cleaner restrictions:EPA formulation limits on chlorinated and aromatic solvents force reformulation investments that smaller chemical distributors cannot absorb.
- Technical documentation gaps:Aerospace and medical device MRO buyers reject suppliers lacking OEM-traceable lot records, disqualifying uncertified distributors from premium segments.
Strategic Opportunities
- India manufacturing capacity buildout:PLI scheme incentives for electronics and automotive production create virgin demand for localized MRO distribution with same-day fulfillment.
- Predictive maintenance-AI convergence:Machine-learning platforms analyzing vibration and thermal data are creating bundled service contracts that combine sensor hardware with consumable replenishment.
- Waterworks infrastructure stimulus:US EPA revolving fund allocations for municipal pipe replacement are concentrating demand for specialized HVAC and plumbing maintenance inventories.
Industry Challenges
- Certified reliability engineer scarcity:Facilities struggle to staff ISO 55000 asset-management auditors capable of validating distributor quality systems.
- Legacy ERP integration friction:Vendor-managed inventory APIs from modern distributors clash with decades-old manufacturing execution systems at mid-sized plants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Maintenance Repair and Operations (MRO) Market |
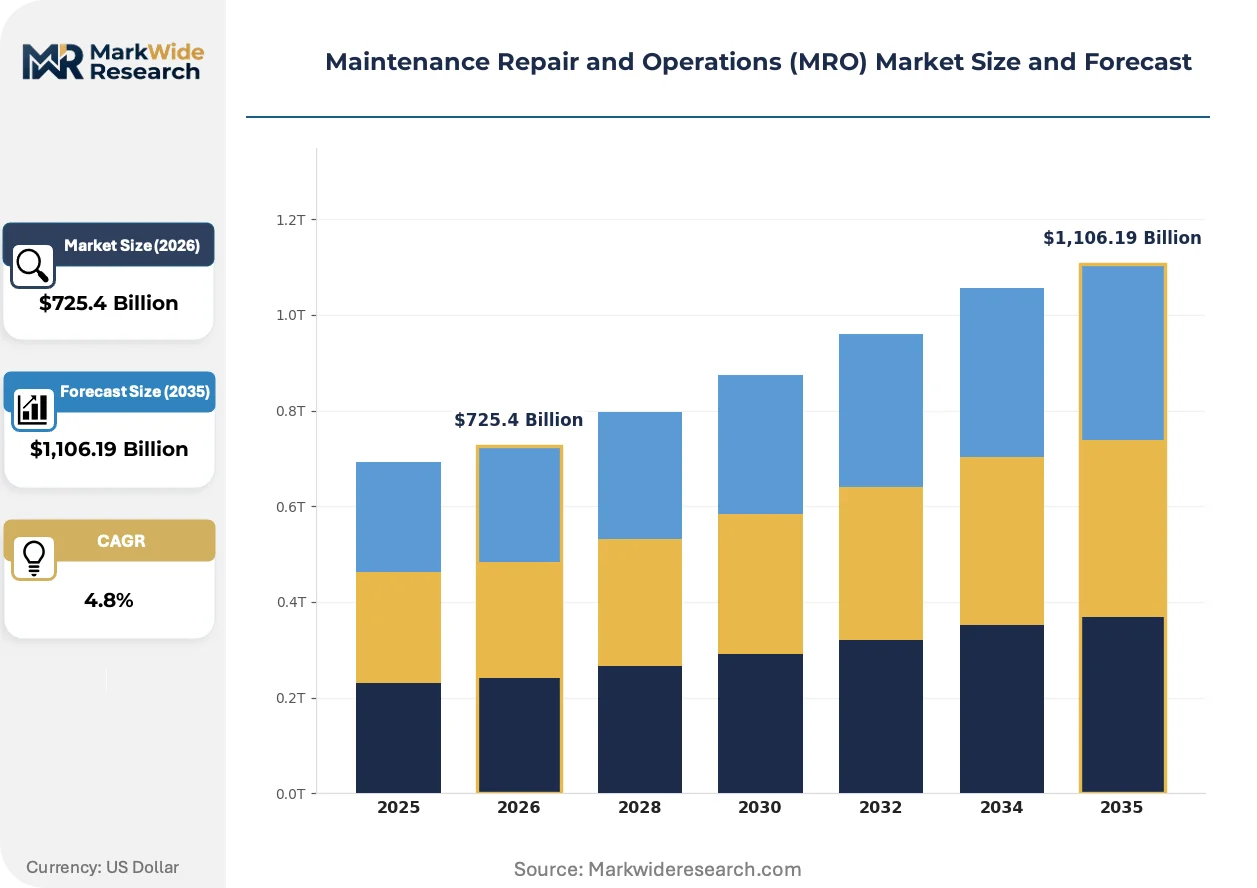
| Market Size in 2026 | $725.4 Billion |
| Market Size in 2035 | $1,106.19 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hand Tools, Power Tools, Fasteners, Lubricants Customer Type: Manufacturers, Distributors, Retailers, Contractors Service Type: Repair Services, Maintenance Services, Support Services, Cleaning Services Application: Aerospace, Automotive, Construction, Industrial |
| Companies Covered | W.W. Grainger, Ferguson PLC, Motion Industries, Fastenal Company, MSC Industrial Direct, Airgas, DNOW, HD Supply Holdings, Applied Industrial Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Maintenance Repair and Operations (MRO) Market Strategic Shifts & Innovations
Digital thread technologies are collapsing the information gap between equipment sensors and procurement systems, enabling condition-triggered replenishment that replaces calendar-based ordering.
Industrial IoT sensor networks paired with edge computing analytics are overtaking manual inspection schedules in rotating equipment maintenance. Food processing and pharmaceutical manufacturers with FDA-validated environments are deploying these systems fastest. The technology is overtaking traditional time-based lubrication and fastener replacement programs, compressing MRO spend toward data services and away from excess safety stock.
REACH authorization requirements for chromium trioxide in surface treatments are forcing fastener suppliers to certify alternative coating chemistries. The regulation elevates compliance costs for European distributors while creating certification barriers that favor suppliers with documented substitution pathways. German automotive and French aerospace MRO buyers are prioritizing suppliers with pre-approved REACH alternatives.
Integrated supply contracts bundling inventory management with technical field support are displacing transactional spot purchasing among energy and heavy machinery operators. Distributors with embedded bearing and power transmission specialists are capturing multi-year agreements. This pattern is most visible in Texas and Alberta oilfield services clusters where contractor consolidation favors single-source MRO relationships.
Maintenance Repair and Operations (MRO) Market Segmentation
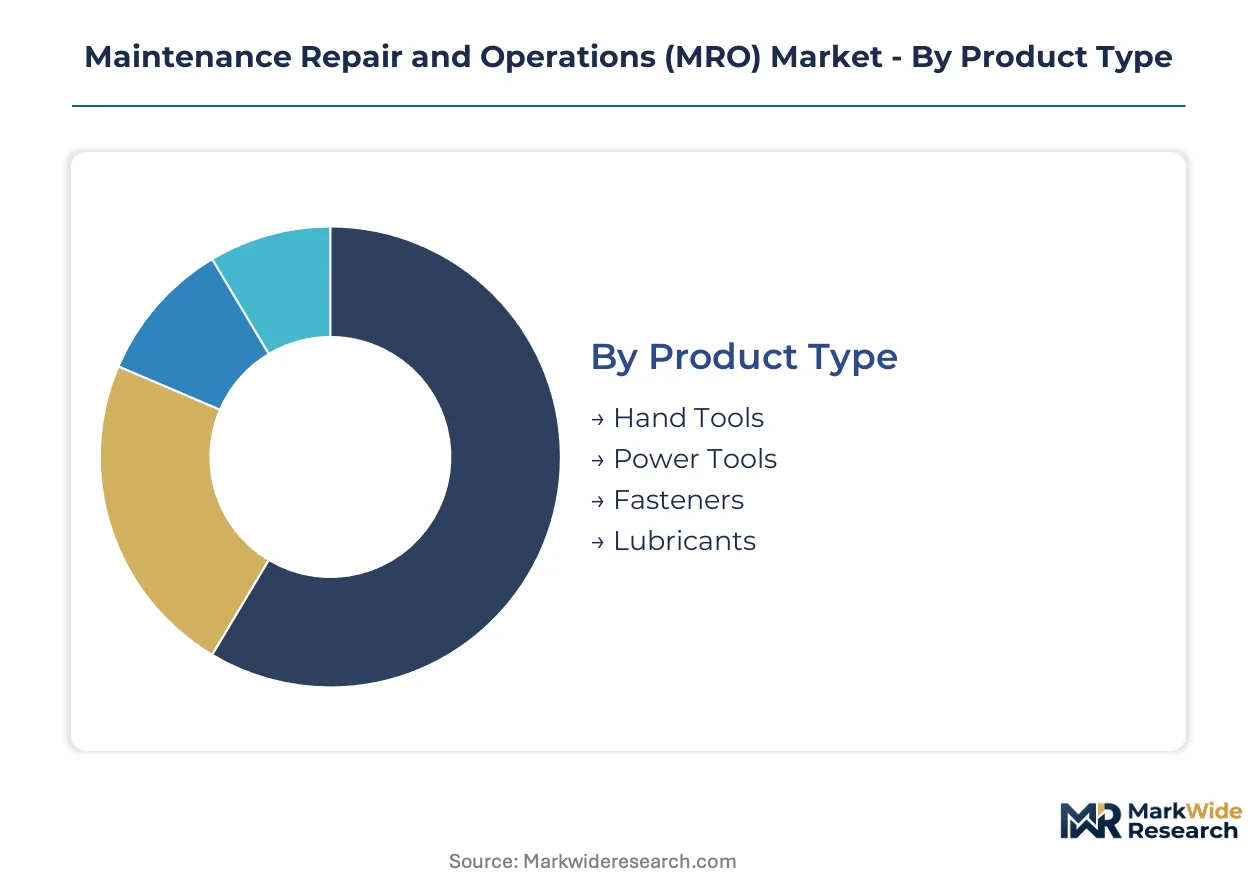
Segmentation in MRO procurement reveals how certification requirements, inventory velocity, and technical complexity fragment purchasing authority across industrial buyers. Understanding these divides exposes where distributors can capture premium positioning through specialized compliance capabilities.
Product Type:
ANSI torque specifications govern hand tools and fasteners, while ASTM viscosity grades and ISO cleanliness codes regulate lubricant formulations.
- Hand Tools:Torque-calibrated wrenches, sockets, and precision measurement instruments carry calibration certificates traceable to NIST standards. Demand concentrates in automotive assembly plants across Michigan and Ohio where OEMs mandate tool audit trails for warranty compliance.
- Fasteners:Grade 5 and Grade 8 carbon steel bolts, stainless hardware, and specialty alloy threaded components dominate procurement volumes. German automotive and French aerospace buyers prioritize REACH-compliant surface coatings, disqualifying suppliers lacking ECHA-registered substitution pathways.
- Power Tools:Cordless lithium-ion drills, grinders, and impact drivers with brushless motor architectures.
- Lubricants:Synthetic and mineral-based oils, greases, and cutting fluids graded by ISO viscosity classification.
Leading the category by volume: Fasteners. Growing fastest: Lubricants as condition-monitoring extends oil-drain intervals.
Customer Type:
Procurement scale and technical support intensity separate these channels, with distributors capturing the largest transaction volumes through vendor-managed inventory programs.
- Distributors:Industrial supply houses aggregate fragmented SKU bases and embed technical specialists at branch level. W.W. Grainger's same-day fulfillment density and Motion Industries' bearing expertise exemplify how distributors compress procurement cycles from quarterly to continuous replenishment.
- Contractors:Oilfield services, construction trades, and facility maintenance operators purchase spot and project-based. Texas and Alberta energy clusters favor single-source MRO relationships bundling inventory with field engineering support.
- Manufacturers:OEMs and tier suppliers with captive maintenance operations.
- Retailers:Big-box and specialty hardware channels serving tradesmen and small commercial accounts.
Highest margin capture: Contractors. Expanding most quickly: Distributors as predictive maintenance-AI convergence creates bundled service contracts.
Service Type:
Documentation rigor and technician certification separate premium segments from commodity maintenance labor.
- Repair Services:Component rebuilds, equipment overhauls, and restorative interventions requiring OEM-traceable lot records. Aerospace and medical device buyers reject suppliers lacking AS9100 or ISO 13485 documentation, creating certification moats around premium segments.
- Maintenance Services:Scheduled preventive interventions including lubrication, alignment, and fastener torque verification.
- Support Services:Technical hotlines, field engineering, and reliability consulting.
- Cleaning Services:Solvent-based and aqueous parts washing with EPA formulation compliance.
Steepest expansion trajectory: Repair Services. Largest addressable base: Maintenance Services.
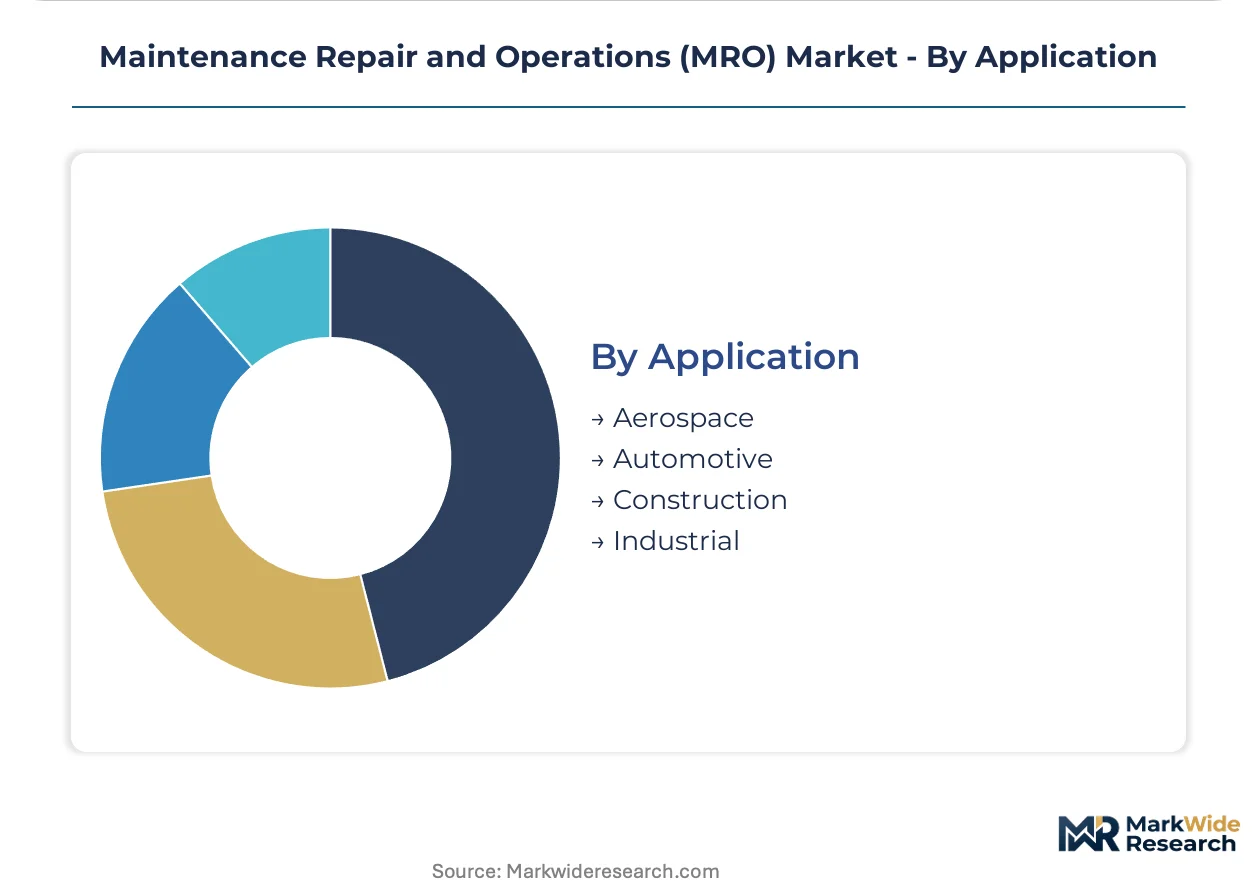
Application:
Regulatory intensity and asset criticality shape procurement specifications across end-use sectors.
- Aerospace:FAA-regulated maintenance with AS9100 quality system mandates and OEM-traceable documentation requirements. Component reliability directly ties to airworthiness certificates, elevating supplier qualification barriers.
- Industrial:Heavy machinery, process equipment, and production line maintenance across steel, cement, and chemical facilities. China's state-directed modernization of these sectors accelerates demand for ANSI-compliant safety equipment and ISO-certified power transmission components.
- Automotive:OEM and tier supplier preventive maintenance programs with extended service intervals.
- Construction:Infrastructure and commercial building maintenance with OSHA-driven safety equipment procurement.
Tightest supplier qualification: Aerospace. Fastest demand acceleration: Industrial.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes the largest absolute MRO volume, while Germany and China concentrate specialized manufacturing capacity for precision components. Production and procurement geography diverge sharply across fasteners, lubricants, and safety equipment categories.
United States
Energy-sector contractors in Texas and Alberta oilfield clusters drive demand for integrated supply contracts bundling inventory with field engineering support. OSHA workplace safety standards tighten procurement specifications for ANSI-certified personal protective equipment. Michigan and Ohio automotive assembly plants mandate torque-calibrated tool audit trails for warranty compliance, concentrating distributor technical service investments in the Midwest industrial corridor.
Germany
Automotive OEMs and tier suppliers extend preventive maintenance programs, elevating consumption of REACH-compliant surface coatings on Grade 8 fasteners. ECHA authorization requirements for chromium trioxide in surface treatments force fastener suppliers to certify alternative coating chemistries. Bavaria and Baden-Württemberg host dense clusters of machinery manufacturers embedding predictive analytics into vendor-managed inventory programs.
China
State-directed modernization of steel, cement, and chemical plants accelerates demand for ANSI-compliant safety equipment and ISO-certified power transmission components. MIIT industrial facility upgrade directives channel procurement toward certified distributors with documented quality systems. Yangtze River Delta manufacturing hubs concentrate MRO distribution infrastructure serving electronics and automotive production facilities.
India
PLI scheme incentives for electronics and automotive production create virgin demand for localized MRO distribution with same-day fulfillment capability. BIS standards govern hand tool and fastener specifications across domestic manufacturing operations. Maharashtra and Gujarat industrial zones attract distributor branch expansions targeting contract manufacturers serving export markets.
Japan
Precision equipment manufacturers deploy Industrial IoT sensor networks for condition-triggered lubricant replenishment, compressing safety stock holdings. METI carbon neutrality roadmaps pressure suppliers to document embedded emissions in replacement components. Kansai region machinery builders integrate predictive maintenance platforms with consumable procurement systems.
Maintenance Repair and Operations (MRO) Market Key Industry Players
The competitive structure tilts toward broad-line distributors with embedded technical specialists and dense fulfillment networks. Consolidation pressure favors players capable of vendor-managed inventory integration and predictive analytics bundling. Three archetypes dominate: North American distribution density leaders, European specialized inventory anchors, and technical support-embedded branch operators. M&A activity concentrates on regional distributor roll-ups, while strategic partnerships with Industrial IoT platform providers reshape service contract structures.
Among North American distribution leaders, W.W. Grainger exemplifies the density-driven fulfillment archetype with same-day service capabilities. Ferguson PLC represents specialized inventory positioning through waterworks and HVAC maintenance concentration. Motion Industries occupies the technical support-embedded tier, anchoring competitive stance through bearing and power transmission expertise at branch level. These three patterns illustrate how scale, specialization, and service integration separate viable competitors from transactional spot suppliers.
| Leading Market Players |
|---|
| W.W. Grainger |
| Ferguson PLC |
| Motion Industries |
| Fastenal Company |
| MSC Industrial Direct |
| Airgas |
| DNOW |
| HD Supply Holdings |
| Applied Industrial Technologies |
| Others |
Cost & Logistics Intelligence
Nickel and chromium price volatility in specialty alloy feedstocks cascades through fastener and bearing manufacturing tiers, compressing margins at mid-sized distributors while concentrating pricing power with integrated suppliers holding captive smelter capacity in Germany and Japan.
Pricing Analysis
Uptime guarantees and equipment availability metrics anchor value-based contracts for predictive maintenance bundles, displacing per-unit transactional models in energy and heavy machinery sectors. Three-tier pricing structure across premium, standard, and economy levels separates AS9100-traceable aerospace fasteners from commodity Grade 5 hardware and uncertified imports. Cost compression in synthetic lubricants is intensifying because base oil supply disruptions from South Korean refineries are forcing reformulation investments. Small commercial contractors exhibit the highest price sensitivity, while aerospace OEMs prioritize documentation compliance over unit cost.
Supply Chain Analysis
Container freight rate fluctuations between Chinese Yangtze River Delta ports and US Gulf Coast terminals directly impact landed costs for ANSI-certified safety equipment and ISO-grade power transmission components. Manufacturing concentration in China, Germany, and the United States shapes global availability of torque-calibrated fasteners and viscosity-graded lubricants. Supply chains draw from chromium ore deposits in South Africa, nickel laterite in Indonesia, and synthetic base oil from South Korean petrochemical complexes. Single-source vulnerability around REACH-compliant surface coating chemistries threatens European fastener availability. Distribution runs through branch-level industrial supply houses embedding technical specialists for same-day fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial IoT sensor networks are displacing calendar-based maintenance schedules, compressing MRO procurement toward continuous replenishment models and away from quarterly spot purchasing.
For Market Incumbents: Deepen vendor-managed inventory integration with predictive analytics platforms to defend against bundled service contracts from industrial IoT providers. Motion Industries and W.W. Grainger exemplify how branch-level technical specialists create switching costs that transactional distributors cannot replicate. Vertical integration into REACH-compliant fastener coating capacity insulates margin position from ECHA authorization delays. For New Entrants and Emerging Players: EU Green Deal carbon-accounting mandates in Europe open a window for certified low-carbon MRO suppliers lacking legacy ERP integration friction. India's PLI scheme incentives for electronics and automotive production represent the most penetrable geography, with Maharashtra and Gujarat industrial zones starved for same-day fulfillment capability. A go-to-market angle bundling BIS-certified hand tools with localized technical support captures contract manufacturers serving export markets. For Investors and Strategic Acquirers: Multi-year integrated supply agreements bundling inventory with field engineering support are the leading indicator that distributor consolidation will accelerate among mid-sized players lacking predictive maintenance-AI convergence capability. Acquisition targets should display dense regional branch networks with embedded bearing or power transmission specialists. Watch for ISO 55000 certification investments as the signal that asset-owner procurement committees are consolidating supplier relationships.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Integration | Industrial IoT sensor networks from Kansai region machinery builders compress procurement cycles from quarterly to continuous replenishment. |
| REACH-Compliant Coating Certification | ECHA authorization requirements for chromium trioxide alternatives force fastener suppliers to document substitution pathways for German automotive buyers. |
| Regional Distribution Density Expansion | Same-day fulfillment capability in Texas and Alberta oilfield clusters captures integrated supply contracts bundling inventory with field engineering. |
| Carbon Accounting Data Infrastructure | EU Green Deal Scope 3 disclosure rules elevate compliance costs for distributors lacking auditable supplier network emissions data. |
| Technical Specialist Embedding | Branch-level bearing and power transmission expertise creates certification moats that disqualify uncertified competitors from aerospace and medical device segments. |
Research Approach
Multi-period observation of fastener procurement volumes, lubricant consumption patterns, and distributor branch expansion timelines anchored the trend analysis, supplemented by interviews with maintenance directors at steel and cement facilities, procurement leads at automotive OEMs, aftermarket service heads at bearing manufacturers, and reliability engineers at oilfield services contractors. Secondary validation drew from EPA enforcement databases, ECHA authorization registries, MIIT facility upgrade directives, customs trade data for specialty alloy imports, and SEC filings from listed industrial distributors. Bottom-up SKU-level demand aggregation and top-down macroeconomic factor modeling enabled cross-verification.
Input-output matrices mapping raw material flows through manufacturing tiers to end-use consumption generated segment-level projections across the analysis window. Segmentation dimensions modeled include product type, customer channel, service intensity, and application sector with regulatory intensity overlays. CAGRs derived from regression analysis against industrial production indices and capital expenditure cycles. Forecast inputs incorporated REACH authorization timelines for surface treatment chemistries and MIIT modernization directive implementation pacing.
The model assumes a particular technology adoption path for Industrial IoT sensor networks; alternative pathways for edge computing analytics deployment would alter the outlook for condition-triggered replenishment penetration. Forecasts reflect assumptions about carbon accounting disclosure enforcement intensity and specialty alloy supply stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Services
Work Order Management Market
Construction Services
NDT and Inspection Market
Construction Services
North America Testing and Commissioning Market
Construction Services
Global Pipeline Maintenance Services Market
Construction Services
Construction Project Management Services Market
Construction Services
Composite Autoclave Repair Market
Construction Services
Gutter Cleaning Services Market
Construction Services
3D Concrete Printing Services Market
Construction Services
Global Construction Scaffolding Rental Market
Construction Services
Die Casting Services Market
Construction Services
Industrial Maintenance Services Market
Construction Services
Construction TIC Market
Construction Services
Excavating Contractor Market
Construction Services
North and Latin America Weatherization Services Market
Construction Services
Industrial Maintenance Products Market
Construction Services
Construction Equipment Repair and Maintenance Services Market