
 North America Fire Sprinkler Systems Market | 2026-2036
North America Fire Sprinkler Systems Market Size, Share, and Industry Trends Forecast 2026-2036
North America Fire Sprinkler Systems Market Analytics
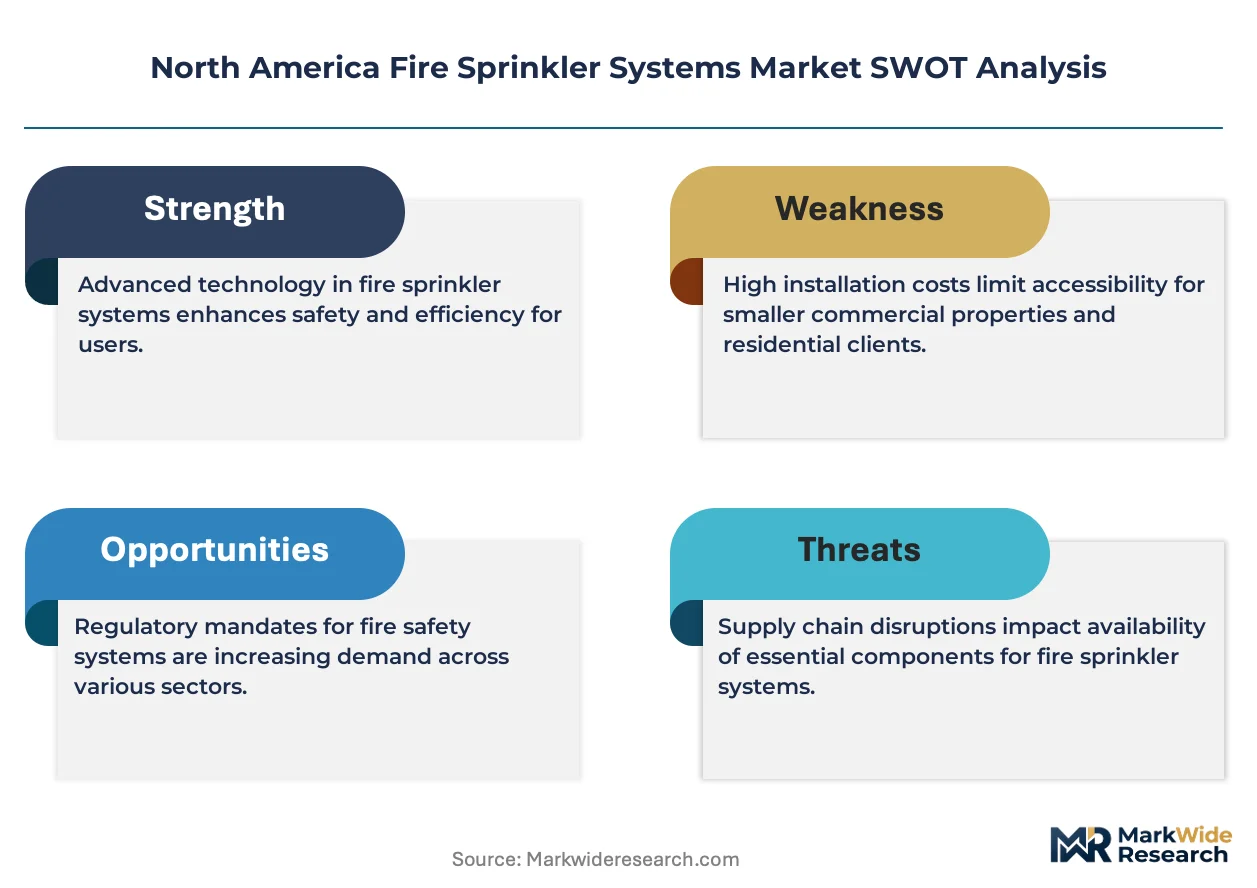
The gap between NFPA 13R light-hazard specifications and full NFPA 13 commercial standards is collapsing as mid-rise residential builders adopt heavier-duty wet pipe configurations. Johnson Controls International PLC leverages its building automation integration to bundle sprinkler systems with fire alarm platforms across commercial portfolios. Reliable Automatic Sprinkler Co. Inc anchors its position through specialized manufacturing of high-challenge storage sprinklers for industrial warehouses. The Viking Corporation competes aggressively on grooved coupling compatibility, extending its influence into retrofit installation channels.
Fire sprinkler systems are engineered networks of pressurized water distribution pipes fitted with thermally activated discharge heads designed to suppress or control structural fires through automatic water application at specified flow densities and coverage areas. These systems integrate hydraulic calculation protocols, pipe schedule methodologies, and response time index ratings to ensure activation within designated temperature thresholds for life safety and property protection. Wet pipe systems dominate new construction volumes due to lower installation complexity and maintenance burden, while smart systems incorporating IoT-enabled flow monitoring and remote valve control represent the fastest-expanding technology segment as building operators seek predictive maintenance capabilities. Pre-action configurations command premium positioning in data center and museum applications where accidental discharge carries catastrophic asset risk.
The National Fire Protection Association sets the dominant technical standards through NFPA 13, 13D, and 13R codes that govern system design, installation, and acceptance testing across the United States. Canada's National Building Code and provincial amendments administered by the Canadian Commission on Building and Fire Codes establish parallel compliance frameworks that manufacturers must satisfy for cross-border market access. Mexico's building safety regulations, coordinated through the national standards body, create additional certification requirements for suppliers targeting industrial expansion near northern border manufacturing clusters. Stakeholders must monitor evolving amendments to residential sprinkler mandates at the municipal level, where local jurisdictions increasingly exceed minimum state requirements and reshape addressable market boundaries faster than national code cycles.
Market Dynamics
NFPA 13D and 13R code revisions are collapsing the historical divide between residential and commercial sprinkler specifications, forcing manufacturers to reconfigure product portfolios around unified hydraulic performance standards.
Growth Catalysts
- Texas and Florida Multifamily Mandates:Local ordinances in Houston, Dallas, Miami, and Orlando now require sprinkler coverage in mid-rise wood-frame construction previously exempt under state codes.
- NFPA 13R Light-Hazard Expansion:The revised standard extends automatic sprinkler requirements to four-story residential buildings, opening retrofit volumes in aging southeastern housing stock.
- Wet Pipe System Simplification:Builders favor single-interlock configurations over pre-action alternatives, reducing installation labor hours and accelerating project timelines.
Market Restraints
- Copper and Steel Input Volatility:Pipe fabrication costs fluctuate with commodity indexes, compressing margins for fixed-bid municipal contracts.
- Midwest Manufacturing Concentration:Foundry capacity clusters in Ohio and Illinois create geographic vulnerability to regional weather disruptions and freight bottlenecks.
- NFPA 25 Inspection Burden:Annual testing mandates for commercial systems impose recurring operational costs that deter small-property ownership segments.
Strategic Opportunities
- Mexico Border Industrial Corridors:Nuevo León and Tamaulipas warehouse construction is outpacing local fire protection infrastructure, creating import demand for NFPA-compliant systems.
- IoT-Enabled Flow Monitoring:Remote valve control and predictive leak detection converge with building automation platforms, opening subscription revenue streams.
- Canadian National Building Code Harmonization:Provincial amendments in British Columbia and Ontario are tightening residential sprinkler timelines ahead of federal cycles.
Industry Challenges
- Certified Hydraulic Technician Scarcity:NICET Level III and IV certification pipelines lag behind installation demand in high-growth southeastern metros.
- Legacy Dry System Integration:Retrofit contractors face complexity marrying modern wet pipe configurations with existing unheated warehouse infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Fire Sprinkler Systems Market |
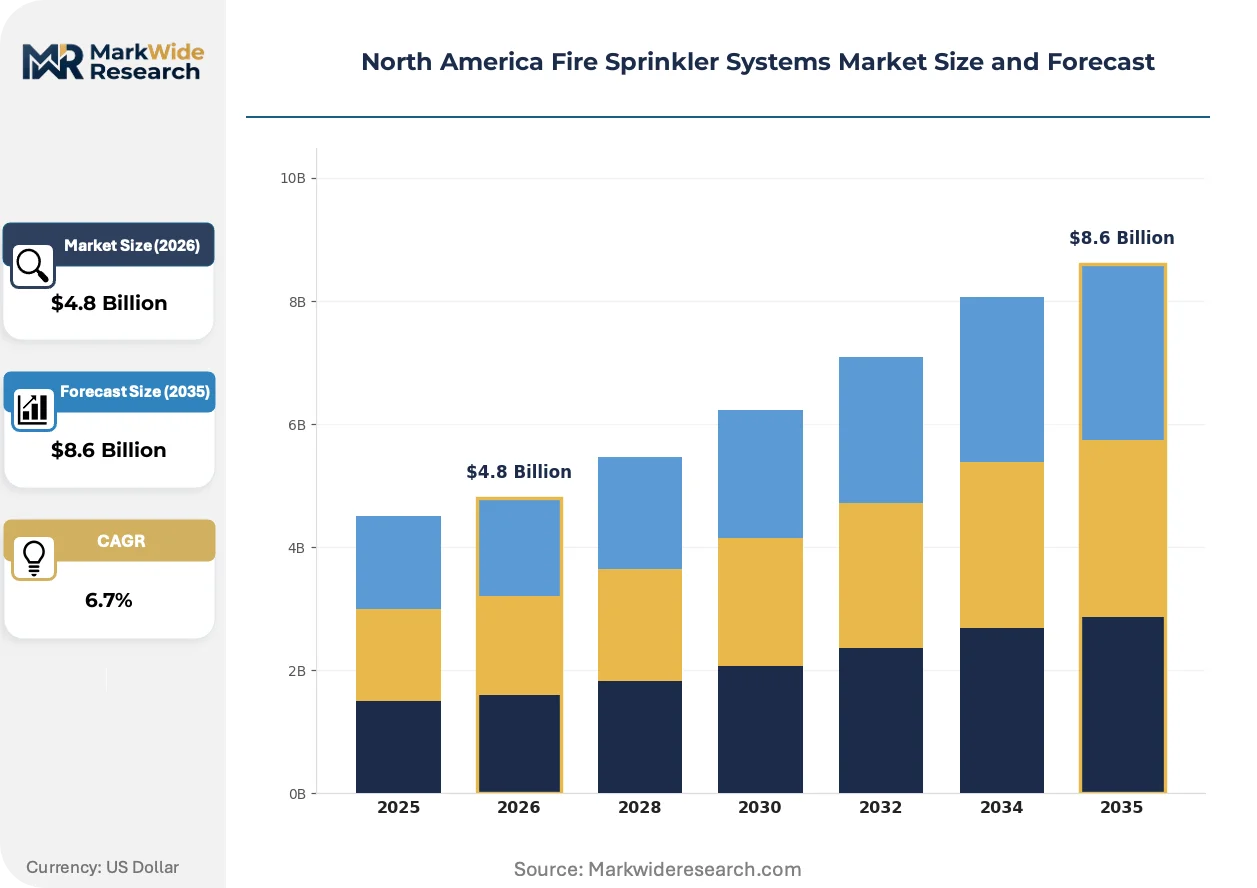
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wet Pipe, Dry Pipe, Pre-Action, Deluge Installation Type: New Construction, Retrofit, Service, Maintenance End User: Commercial, Industrial, Residential, Hospitality Technology: Electromechanical, Smart Systems, Traditional, NFPA Compliant |
| Companies Covered | Johnson Controls International PLC, Reliable Automatic Sprinkler Co. Inc, The Viking Corporation, Carrier Global Corporation, Tyco Fire Products LP, Potter Electric Signal Company LLC, Victaulic Company, Minimax USA LLC, Fireline Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Fire Sprinkler Systems Market Evolving Landscape
Smart infrastructure integration and material science advances are compressing system footprints while expanding performance envelopes across residential and commercial deployments.
Concealed pendant sprinkler heads with ultra-low profile escutcheons are miniaturizing visible hardware in high-end multifamily interiors. Developers in Miami and Austin specify these units to preserve ceiling aesthetics in amenity spaces. The form-factor reduction is enabling sprinkler penetration into luxury residential segments historically resistant to exposed industrial hardware.
NFPA 13D now permits calculated system designs using listed CPVC pipe in one- and two-family dwellings, displacing traditional copper and steel in new construction. The material substitution reduces installation weight and labor intensity. Single-family builders in Florida and California are adopting CPVC configurations to accelerate rough-in schedules and reduce skilled trade dependencies.
Building operators now unbundle inspection and maintenance contracts from original equipment providers, favoring third-party specialty firms with digitized compliance documentation. This procurement fragmentation disrupts traditional manufacturer-captive service models. The shift is most pronounced in Texas, where portfolio owners managing dozens of properties seek centralized compliance dashboards across dispersed assets.
North America Fire Sprinkler Systems Market Segmentation
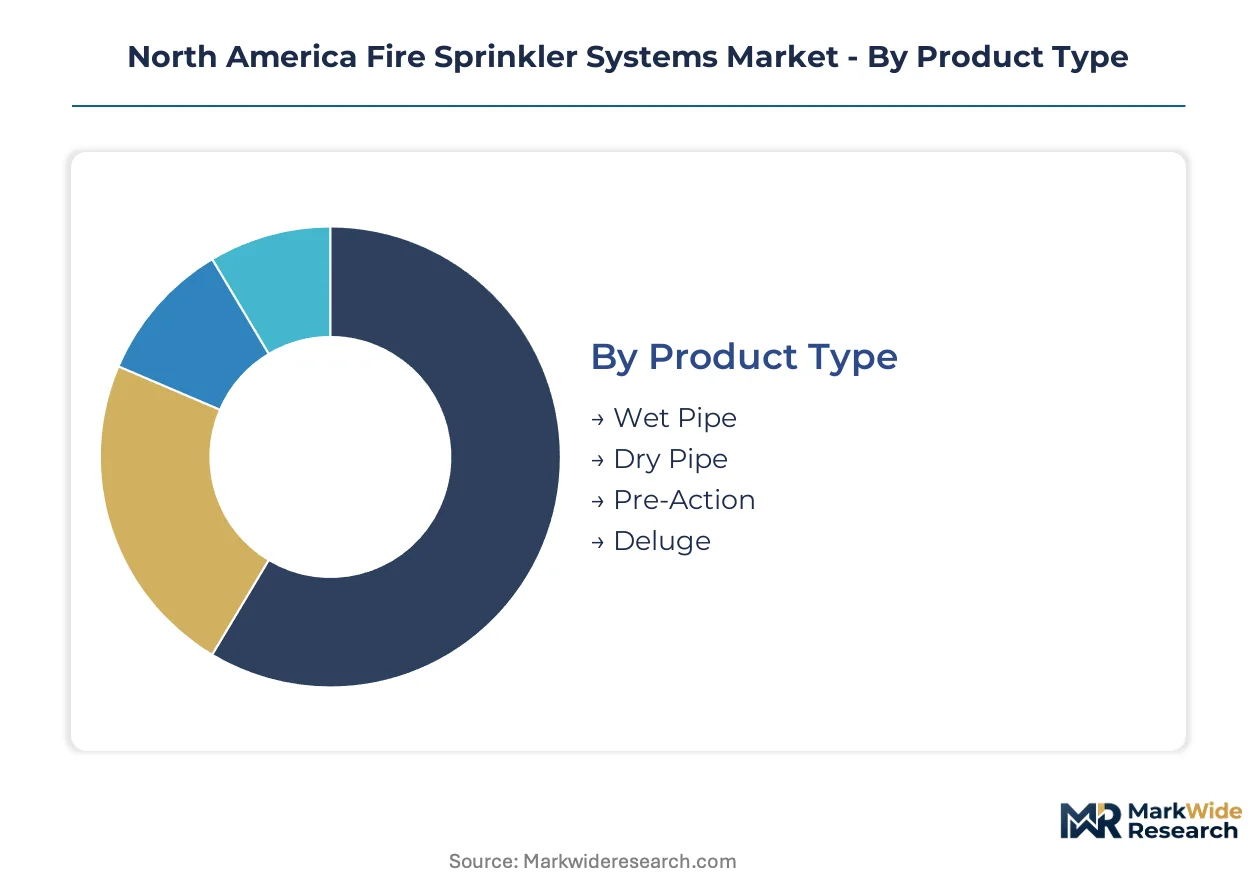
Segmentation in the North America fire sprinkler systems market reveals distinct procurement patterns across building lifecycles and regulatory exposure. Product specifications diverge sharply between new construction and retrofit channels, while end-user risk profiles determine technology adoption rates.
Product Type:
Wet pipe configurations face intensifying substitution pressure from smart-enabled alternatives in commercial portfolios, while dry pipe systems retain defensive positioning in cold-climate warehousing.
- Wet Pipe:Pressurized water-filled piping networks deliver immediate discharge upon thermal activation without mechanical delay mechanisms. Demand concentrates in Texas and Florida multifamily construction where NFPA 13R mandates accelerate new installation timelines and builders prioritize simplified commissioning.
- Dry Pipe:Pressurized air or nitrogen chambers hold water at a remote valve, preventing freeze damage in unheated environments. Industrial warehouse expansion across Minnesota and Wisconsin sustains procurement volumes despite higher installation complexity and maintenance burden.
- Pre-Action:Dual-interlock configurations requiring both detection and sprinkler activation protect data centers and museums where accidental discharge carries catastrophic asset risk.
- Deluge:Open-nozzle systems activated by external detection serve high-hazard chemical processing and aircraft hangar applications with rapid suppression requirements.
Wet pipe anchors the volume base while smart-enabled configurations gain share at the steepest rate.
Installation Type:
Cost tier differentiation separates capital-intensive new construction from recurring-revenue service contracts, with retrofit channels commanding premium pricing for access constraints.
- New Construction:Rough-in installation during framing stages permits optimized pipe routing and reduced labor intensity. Southeastern housing development in Houston, Dallas, and Orlando drives specification volumes as local ordinances extend sprinkler mandates to mid-rise wood-frame buildings previously exempt under state codes.
- Retrofit:Post-occupancy installation demands specialized techniques including surface-mount piping and structural penetration minimization. Aging southeastern housing stock facing NFPA 13R four-story requirements generates concentrated demand in Miami and Atlanta metropolitan corridors.
- Service:NFPA 25-mandated annual testing and maintenance contracts provide recurring revenue streams for certified contractors.
- Maintenance:Valve replacement, head cleaning, and hydraulic recalculation extend system operational lifespans beyond original design horizons.
New construction dominates absolute volumes while retrofit climbs fastest as municipal mandates reshape existing building obligations.
End User:
Application-specific performance requirements segment procurement by hazard classification and occupancy density, with residential codes undergoing the most rapid regulatory revision.
- Commercial:Office, retail, and institutional buildings specify NFPA 13 full-standard systems with comprehensive coverage density. Portfolio owners in Texas increasingly unbundle inspection contracts from original equipment providers, favoring third-party specialty firms with digitized compliance documentation.
- Residential:One- and two-family dwellings and multifamily buildings operate under NFPA 13D and 13R light-hazard specifications. CPVC pipe substitution accelerates in Florida and California single-family construction to reduce skilled trade dependencies and rough-in schedules.
- Industrial:High-challenge storage and manufacturing facilities demand specialized sprinkler heads with elevated K-factors and extended coverage areas.
- Hospitality:Hotels and resorts balance life safety requirements with aesthetic concealment through ultra-low profile pendant heads in amenity spaces.
Commercial anchors the volume base while residential gains share at the steepest rate.
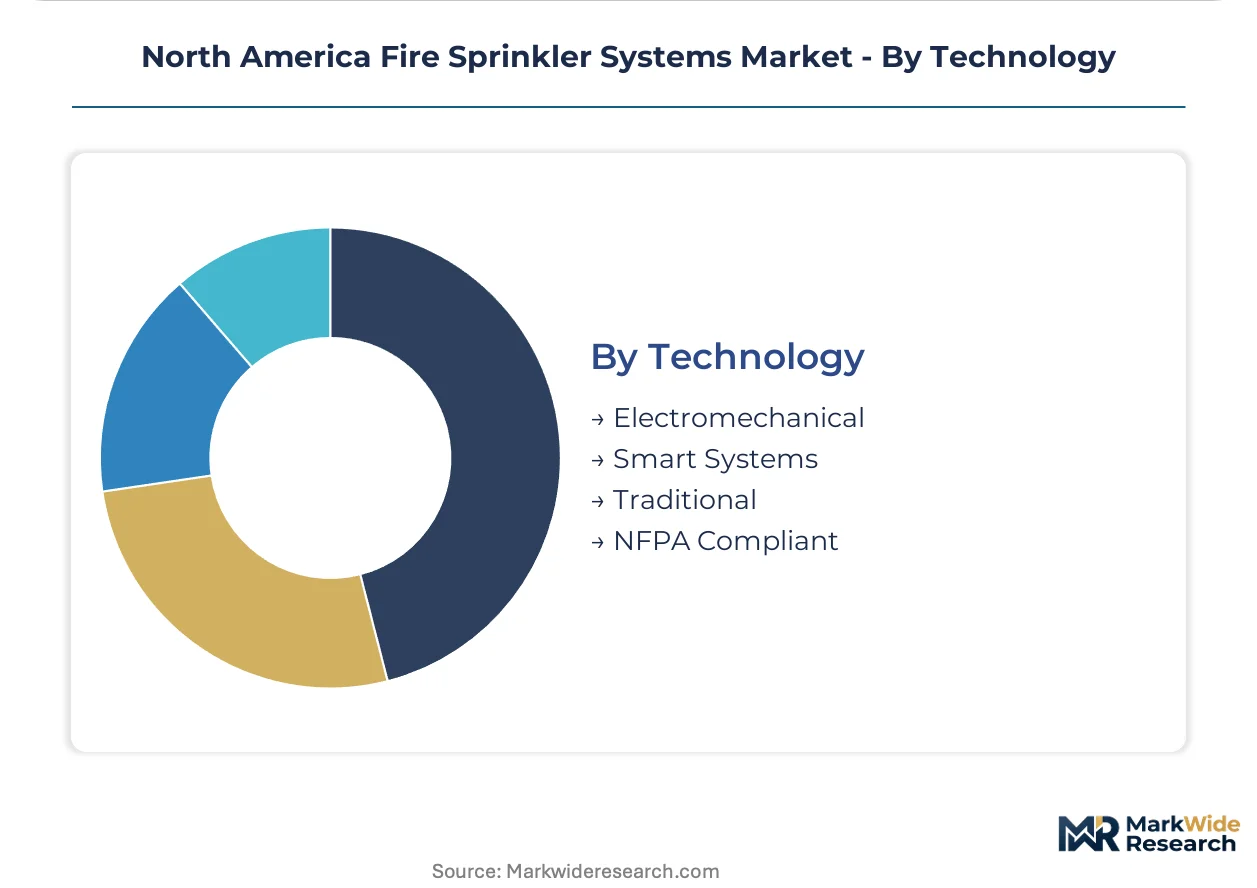
Technology:
Customer type stratification separates building automation integrators seeking platform convergence from cost-sensitive developers prioritizing baseline compliance.
- Smart Systems:IoT-enabled flow monitoring, remote valve control, and predictive leak detection integrate with building management platforms. Portfolio operators across dispersed Texas assets seek centralized compliance dashboards and subscription-based maintenance revenue streams.
- NFPA Compliant:Standards-certified configurations satisfying NFPA 13, 13D, and 13R testing protocols dominate municipal and insurance-mandated procurement.
- Electromechanical:Conventional detection and activation mechanisms without network connectivity serve budget-constrained projects and simple hazard environments.
- Traditional:Legacy system designs lacking smart infrastructure compatibility persist in maintenance and like-for-like replacement channels.
NFPA compliant configurations anchor the volume base while smart systems gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foundry capacity for sprinkler components clusters in Ohio and Illinois, creating geographic vulnerability to regional weather disruptions and freight bottlenecks. This concentration shapes procurement patterns across the continent.
United States
Multifamily construction in Texas and Florida is expanding sprinkler mandates beyond traditional commercial footprints. NFPA 13D and 13R code revisions accelerate residential retrofit obligations. Houston, Dallas, Miami, and Orlando now require sprinkler coverage in mid-rise wood-frame construction previously exempt under state codes.
Canada
The National Building Code and provincial amendments administered by the Canadian Commission on Building and Fire Codes establish parallel compliance frameworks. British Columbia and Ontario are tightening residential sprinkler timelines ahead of federal cycles. Vancouver and Toronto metropolitan areas drive specification volumes for NFPA-compliant system imports.
Mexico
Nuevo León and Tamaulipas warehouse construction is outpacing local fire protection infrastructure. The national standards body coordinates building safety regulations that create additional certification requirements for suppliers. Monterrey and Reynosa manufacturing clusters generate import demand for NFPA-compliant systems.
Southeastern United States
Rapid housing development intersects with stricter local fire safety ordinances across Georgia, South Carolina, and North Carolina. Municipal jurisdictions increasingly exceed minimum state requirements. Atlanta and Charlotte metropolitan corridors generate concentrated retrofit demand in aging housing stock facing four-story sprinkler requirements.
North America Fire Sprinkler Systems Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the North America fire sprinkler systems market. The vendor base clusters around three strategic positions: building automation integrators seeking platform convergence, specialized manufacturers of high-challenge industrial components, and coupling-focused hardware suppliers competing on retrofit installation efficiency. Dominant competitive moves include strategic partnerships for smart system integration and geographic expansion into Mexico border industrial corridors.
Among building automation integrators, Johnson Controls International PLC represents the convergence archetype bundling sprinkler systems with fire alarm platforms. Reliable Automatic Sprinkler Co. Inc exemplifies specialized manufacturing positioning through high-challenge storage sprinkler production. The Viking Corporation anchors the hardware compatibility tier competing aggressively on grooved coupling standards.
| Leading Market Players |
|---|
| Johnson Controls International PLC |
| Reliable Automatic Sprinkler Co. Inc |
| The Viking Corporation |
| Carrier Global Corporation |
| Tyco Fire Products LP |
| Potter Electric Signal Company LLC |
| Victaulic Company |
| Minimax USA LLC |
| Fireline Corporation |
| Others |
Value Network & Pricing Analysis
Fixed-bid municipal contracts lock in both copper and steel pipe access and cost visibility for installers across Texas and Florida multifamily developments. This structure transfers commodity volatility risk to contractors while insulating municipal buyers from input price swings.
Pricing Analysis
NFPA 13, 13D, and 13R code tiers dictate the pricing stratification across commercial, residential light-hazard, and single-family dwelling specifications. Three-tier pricing structure across premium smart-enabled systems, standard wet pipe configurations, and economy CPVC residential packages differentiates by certification grade and IoT integration depth. Cost compression in standard wet pipe tiers is intensifying because copper and steel input volatility squeezes fixed-bid contractor margins. Small-property ownership segments in the Midwest exhibit highest price sensitivity due to NFPA 25 inspection burden, while data center operators demonstrate lowest sensitivity given catastrophic discharge risk exposure.
Supply Chain Analysis
Ohio and Illinois foundry concentration creates a geographic chokepoint for sprinkler component fabrication across North America. Manufacturing draws from brass ingot, steel coil, and CPVC resin inputs. Single-source vulnerability in Midwest foundry capacity exposes the market to regional weather disruptions and freight bottlenecks. Distribution runs through authorized wholesale distributors serving mechanical contractor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Building automation platform convergence is transforming fire sprinkler procurement from standalone hardware to integrated safety ecosystem sales, with interoperability standards now determining vendor selection criteria.
For Market Incumbents: Secure backward integration into brass foundry capacity to offset Ohio and Illinois geographic concentration risk. Deepen certification investment in NICET Level III and IV technician training pipelines to outpace installation demand bottlenecks in southeastern metros. Lock in long-term CPVC resin supply agreements as Florida and California single-family builders accelerate material substitution away from copper and steel. For New Entrants and Emerging Players: Anchor in Mexico border industrial corridors where Nuevo León and Tamaulipas warehouse construction outpaces local fire protection infrastructure. Target the smart-enabled retrofit segment in Texas portfolio properties seeking centralized compliance dashboards across dispersed assets. Lead with subscription-based maintenance revenue models rather than equipment-only sales. For Investors and Strategic Acquirers: Capital is best deployed toward building automation integrators with captive sprinkler-fire alarm bundling capabilities. The 5-10 year viability window favors platform convergence plays over standalone hardware manufacturers. Monitor NFPA 13R municipal amendment velocity as the inflection indicator for residential retrofit addressable market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Smart System Platform Integration | IoT-enabled flow monitoring converges with Johnson Controls building automation to capture predictive maintenance subscriptions. |
| Mexico Border Corridor Expansion | NFPA-compliant system imports serve Monterrey and Reynosa manufacturing clusters ahead of local infrastructure buildout. |
| CPVC Material Substitution Scale-Up | Listed CPVC pipe adoption reduces Florida and California single-family builder dependence on scarce copper and steel trades. |
| Third-Party Service Unbundling | Digitized compliance documentation specialists capture Texas portfolio owner contracts from manufacturer-captive service models. |
| NICET Certification Pipeline Investment | Level III and IV technician training capacity expansion addresses certified hydraulic scarcity in Atlanta and Miami corridors. |
Research Methodology
A spread of perspectives from fire protection contractors, municipal code officials, building automation integrators, and real estate portfolio managers converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with wholesale distributor principals and mechanical contractor estimators. Secondary validation drew from NFPA technical committee documentation, municipal ordinance amendment records, and building permit databases. Bottom-up installation volume estimates triangulated against top-down construction spending allocations.
Product type, installation channel, end-use hazard classification, and technology integration level segmented the analytical framework across the projection horizon. CAGRs were derived from weighted average of historical installation permit trajectories and forward code amendment schedules. Smart system adoption curves and CPVC material penetration rates served as industry-specific forecast inputs alongside housing start projections and commercial construction pipeline data.
Decision-makers should treat outputs as directional under stable copper and steel commodity price assumptions; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as NFPA 13R municipal adoption velocity and Mexico industrial construction timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Services
Global Construction Scaffolding Rental Market
Construction Services
Dust Suppression Control Market
Construction Services
Industrial Maintenance Products Market
Construction Services
Global Industrial Services Market
Construction Services
Work Order Management Market
Construction Services
Grease Trap Service Market
Construction Services
Condenser Cleaners Market
Construction Services
North America Repair and Rehabilitation Market
Construction Services
Europe Maintenance, Repair, and Operations (MRO) Market
Construction Services
Train Contractor Market
Construction Services
Construction Equipment Repair and Maintenance Services Market
Construction Services
Remote Construction Market
Construction Services
Facade Cleaning and Maintenance Service Market
Construction Services
Heavy Equipment Training Simulator Market
Construction Services
MENA Architectural Services Market
Construction Services
Composite Autoclave Repair Market