
 Die Casting Services Market | 2026-2036
Die Casting Services Market Size, Share, and Industry Trends Forecast 2026-2036
Die Casting Services Market Analysis
The capability gap between high-pressure die-casting specialists and generalist foundries is collapsing as multi-slide and trim-cell automation becomes table stakes. Nemak leverages captive aluminum smelting and tooling design to anchor long-term supply contracts with powertrain electrification programs. Rheinmetall AG competes through defense-aerospace dual-use certification and magnesium thin-wall expertise for transmission housings. GF Casting Solutions differentiates via water-management and building-technology castings that diversify revenue beyond automotive cyclicality.
Die casting services encompass the production of complex metal components by forcing molten non-ferrous alloys into reusable steel molds under pressures typically ranging from 1,500 to 25,000 psi, yielding net-shape or near-net-shape parts with tolerances as tight as ±0.002 inches for critical dimensions. These services supply structural, thermal-management, and electromagnetic-shielding components across transportation, industrial, and consumer sectors where machining from solid would waste material and extend cycle times. Aluminum die-casting dominates volume due to its strength-to-weight ratio and recyclability, while magnesium commands premium positioning in handheld electronics and racing applications where every gram carries design consequence. Zinc retains mature demand in lock hardware, plumbing fittings, and decorative automotive trim where corrosion resistance and castability outweigh density concerns. The delivery-model dimension reveals structural tension: just-in-time contracts capture stable margin pools through inventory risk transfer, yet on-demand and prototyping services attract engineering-intensive accounts that shape subsequent bulk-production awards.
EPA emissions standards and NHTSA corporate average fuel economy rules tighten material-performance requirements for automotive die castings, pushing suppliers toward heat-treatable alloys and vacuum-assisted processes that reduce porosity. China's SAMR enforces GB standards for recycled-content claims and MEE tracks foundry energy intensity, creating compliance cost tiers that favor scaled operators with environmental monitoring systems. Stakeholders must monitor how battery-electric platform architectures eliminate traditional transmission cases while creating demand for motor housings, battery trays, and thermal-management plates that reshape die-casting design priorities.
Market Dynamics
Automotive electrification is decomposing traditional die-casting demand patterns as transmission housings disappear and battery enclosures, motor housings, and thermal-management plates emerge as replacement volume anchors.
Growth Catalysts
- EPA fleet efficiency mandates:NHTSA CAFE standards tighten annually, forcing OEMs toward aluminum structural components that die-casting delivers at scale.
- China's MIIT dual carbon framework:Subsidy redirection toward NEV platforms concentrates supplier investment in magnesium and recycled aluminum capabilities.
- Yangtze River Delta clustering:Tier-one suppliers co-locate with vehicle assembly plants, compressing logistics costs and enabling just-in-time delivery models.
Market Restraints
- Primary aluminum price volatility:LME pricing swings compress margins for non-integrated foundries lacking captive smelting or long-term hedging.
- Tooling lead-time concentration:High-precision mold fabrication concentrates in German and Japanese specialty shops, creating 16-24 week procurement bottlenecks.
- Porosity limitations in conventional HPDC:Vacuum-assisted and squeeze-casting processes add 15-25% cost premiums that price-sensitive applications cannot absorb.
Strategic Opportunities
- India's PLI scheme for auto components:Localization incentives attract die-casting investment to serve domestic NEV production and export markets.
- Data center thermal-management plates:Liquid-cooled server architectures create demand for complex aluminum channel geometries that die-casting produces efficiently.
- EU Green Deal recycled-content mandates:Ecodesign regulations favor suppliers with verified secondary aluminum traceability and closed-loop scrap systems.
Industry Challenges
- Process simulation talent scarcity:MAGMASOFT and ProCAST expertise gaps delay tooling validation and first-article approval timelines.
- Multi-material joining certification:Aluminum-to-steel and aluminum-to-composite weld-bonding qualifications extend automotive qualification cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Die Casting Services Market |
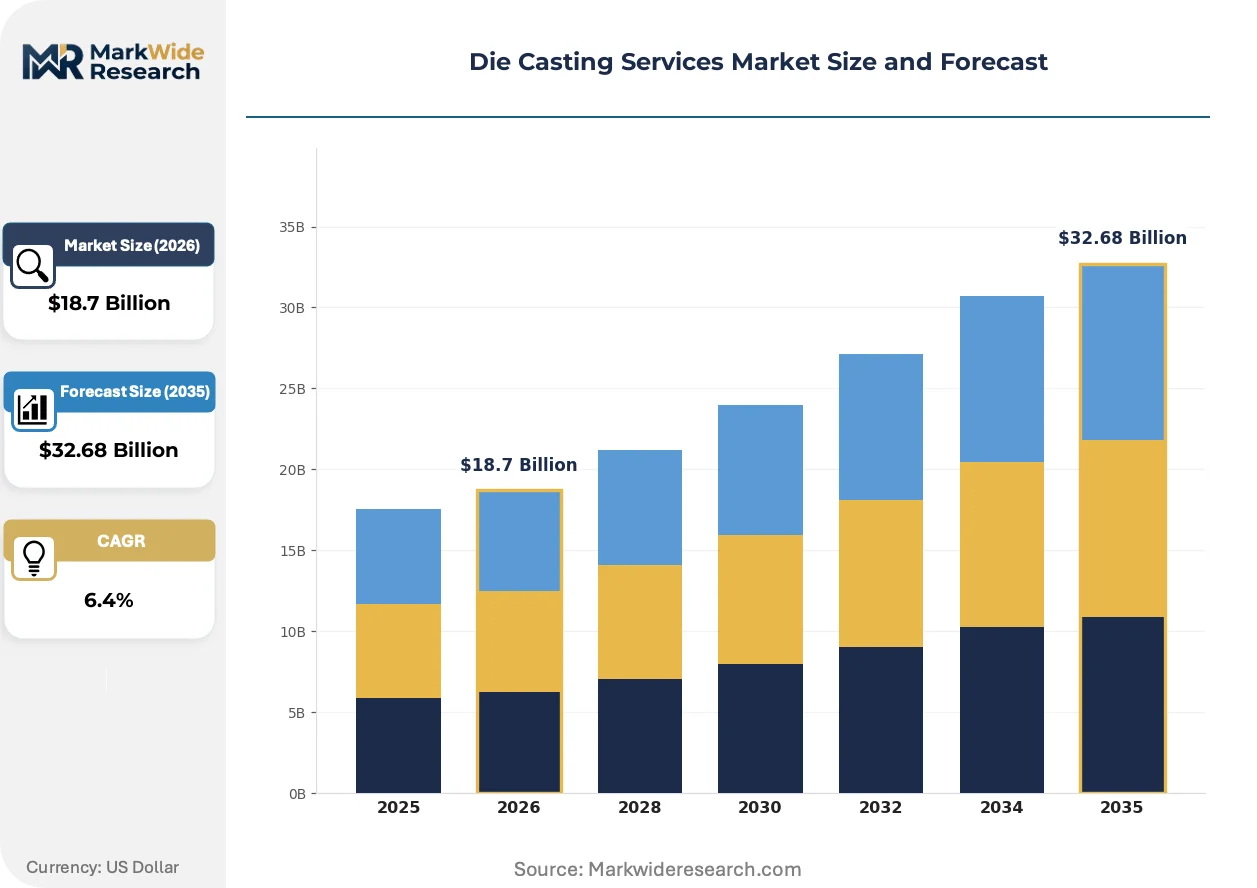
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum, Zinc, Magnesium, Copper Application: Automotive Components, Consumer Electronics, Industrial Equipment, Aerospace Parts Delivery Model: On-Demand Manufacturing, Bulk Production, Just-In-Time, Prototyping End User: OEMs, Aftermarket Providers, Manufacturers, Assemblers |
| Companies Covered | Nemak, Ryobi Die Casting, Linamar Corporation, Pace Industries, Alcoa, Dynacast, GF Casting Solutions, Rheinmetall AG, Martinrea, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Die Casting Services Market Emerging Trajectories
Process automation and materials science advances are compressing the capability gap between commodity foundries and precision specialists, while regulatory pressure on carbon intensity reshapes alloy sourcing and energy inputs.
Large-scale integrated die-casting is decomposing multi-part assemblies into single castings. Tesla's giga-press architecture at 6,000-9,000 ton clamping force enables rear-floor single-piece castings that replace 70+ stamped and welded components. Automotive OEMs in Germany and China are adopting similar cell configurations, collapsing tiered supplier structures and transferring design authority to integrated casting houses.
REACH substance restrictions and the EU F-Gas Regulation are phasing out sulfur hexafluoride cover gas in magnesium die-casting. Foundries are retrofitting SO2-based or salt-flux protection systems that add capital intensity but eliminate regulatory exposure. German automotive suppliers lead this transition, with KBA type-approval processes now requiring documented SF6-free process certification for magnesium structural components.
Engineering service unbundling is fragmenting traditional full-service contracts. OEMs now separate tooling design, process development, and serial production awards, enabling competitive bidding at each phase. This pattern concentrates in China's NEV startup ecosystem, where vehicle programs launch faster than traditional qualification cycles permit, forcing foundries to accept prototype-to-production handoff risks that established tier-ones previously absorbed.
Die Casting Services Market Segmentation
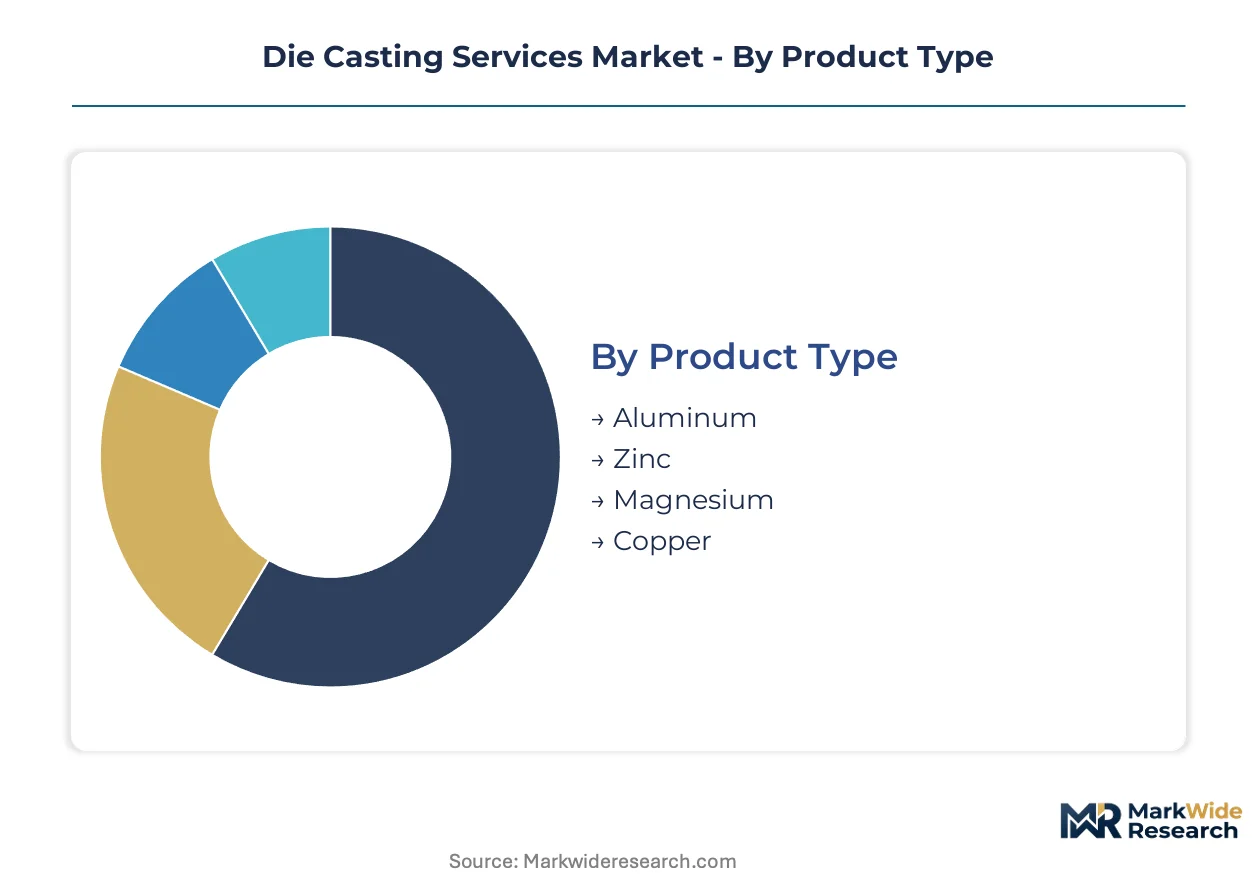
Die casting service providers compete across distinct technical and commercial boundaries where alloy selection, delivery cadence, and customer integration depth determine margin sustainability. Segmentation reveals where process specialization commands premium positioning versus where commoditization pressures dominate procurement decisions.
Product Type:
Aluminum faces substitution pressure from magnesium in weight-critical applications and from polymer composites in non-structural housings, forcing die casters to defend positioning through alloy innovation and heat-treatment capabilities.
- Aluminum:Heat-treatable alloys A380 and A383 dominate automotive structural components due to strength-to-weight ratios and established recycling infrastructure. Demand concentrates in China's Yangtze River Delta manufacturing cluster where NEV OEMs source battery trays and motor housings under MIIT dual carbon compliance requirements.
- Magnesium:AZ91D and AM60B alloys enable thin-wall casting for transmission housings and handheld electronics where density reduction outweighs material cost premiums. German automotive suppliers lead process certification under KBA type-approval for SF6-free protection systems mandated by EU F-Gas Regulation phase-outs.
- Zinc:ZAMAK alloys retain lock hardware and plumbing fitting demand where corrosion resistance and decorative surface finish drive specification.
- Copper:High-conductivity alloys serve electrical connector and heat-sink applications in industrial power distribution equipment.
Aluminum retains volume leadership across transportation and industrial end-uses; magnesium holds the steepest expansion curve as NEV platforms proliferate and aerospace lightweighting intensifies.
Application:
Cost tier stratification separates capital-intensive automotive programs from price-sensitive consumer electronics contracts, with industrial equipment occupying a middle band where batch flexibility matters more than scale economies.
- Automotive Components:Structural castings for chassis, powertrain, and electrification hardware require vacuum-assisted HPDC processes meeting ±0.002 inch tolerances. EPA fleet efficiency mandates and NHTSA CAFE standards tighten annually, redirecting procurement toward aluminum-intensive platform architectures.
- Consumer Electronics:Magnesium thin-wall housings for laptops and tablets demand rapid tooling iteration cycles that favor on-demand service models over traditional bulk production contracts.
- Industrial Equipment:Pump housings, valve bodies, and compressor components tolerate conventional HPDC porosity levels where cost sensitivity limits adoption of squeeze-casting premiums.
- Aerospace Parts:Defense-aerospace dual-use certification requirements concentrate demand among foundries with AS9100 and NADCAP credentials, creating supply scarcity for structural magnesium castings.
Automotive Components commands the dominant revenue share; Consumer Electronics is climbing the fastest as device miniaturization accelerates magnesium adoption.
Delivery Model:
Customer type determines contract structure, with OEMs demanding inventory risk transfer through just-in-time arrangements while NEV startups fragment awards across prototype-to-production handoffs.
- Just-In-Time:Long-term supply contracts with dedicated line-side delivery capture stable margin pools by transferring inventory carrying costs to the die caster. Tier-one suppliers in Germany and China co-locate with vehicle assembly plants to enable hourly replenishment cycles.
- On-Demand Manufacturing:Engineering-intensive accounts with volatile forecast accuracy pay premium piece rates for capacity flexibility, particularly in China's NEV startup ecosystem where program launch velocities exceed traditional qualification timelines.
- Bulk Production:Commodity zinc and aluminum castings for industrial and construction hardware operate on spot-market pricing with minimal technical service content.
- Prototyping:Soft-tooling and bridge-production services shape subsequent serial-production awards, concentrating in regions with dense automotive R&D presence.
Just-In-Time retains contract value concentration; On-Demand Manufacturing is gaining share fastest as OEMs disaggregate traditional full-service relationships.
End User:
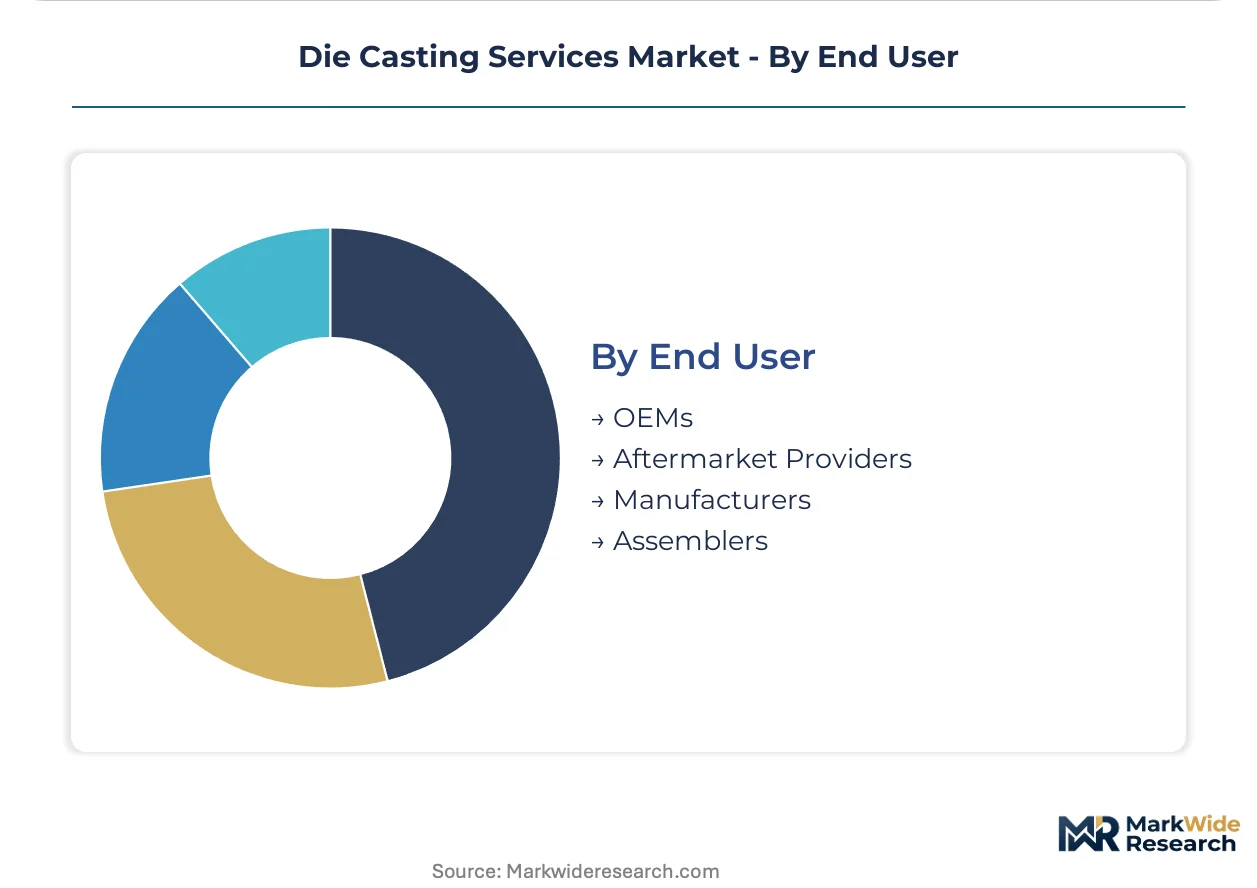
Supply concentration varies sharply by customer scale, with global OEMs consolidating awards among integrated casting houses while aftermarket providers fragment demand across regional job shops.
- OEMs:Direct automotive and electronics manufacturer relationships require design authority transfer, captive tooling investment, and multi-year capacity commitments. Tesla's giga-press adoption for single-piece rear-floor castings exemplifies this integration depth.
- Aftermarket Providers:Replacement part demand for legacy vehicle platforms and industrial equipment sustains smaller foundries with lower capital intensity requirements.
- Manufacturers:Tier-two and tier-three component suppliers purchase die-cast subassemblies for further machining and finishing operations.
- Assemblers:Contract manufacturers in electronics and appliance sectors source finished housings and brackets on specification-driven procurement terms.
OEMs anchor procurement volume; Aftermarket Providers is expanding most quickly as vehicle parc age lengthens replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances tilt toward deficit in North America and Europe as automotive OEMs source aluminum die-cast battery trays and motor housings from Asian foundries. China maintains surplus positioning through Yangtze River Delta manufacturing density, while India builds domestic capacity under PLI incentives to reduce import dependency.
China
NEV platform proliferation and MIIT dual carbon mandates concentrate die-casting investment in magnesium and recycled aluminum capabilities. SAMR enforces GB standards for recycled-content claims while MEE tracks foundry energy intensity, creating compliance tiers that favor scaled operators. The Yangtze River Delta manufacturing cluster anchors supplier co-location with vehicle assembly plants, compressing logistics costs for just-in-time delivery.
Germany
Automotive electrification and defense-aerospace dual-use demand sustain premium positioning for magnesium thin-wall and vacuum-assisted processes. KBA type-approval now requires documented SF6-free process certification for magnesium structural components under EU F-Gas Regulation phase-outs. Bavaria and Baden-Württemberg house specialized mold fabrication shops that supply precision tooling across European OEM networks.
United States
EPA fleet efficiency mandates and NHTSA CAFE standards tighten annually, redirecting procurement toward aluminum-intensive platform architectures. The Southeast manufacturing corridor attracts die-casting investment to serve domestic EV assembly expansion. Tier-one suppliers co-locate with vehicle plants in Tennessee and South Carolina to enable hourly replenishment cycles under long-term supply contracts.
India
PLI scheme localization incentives draw die-casting investment to serve domestic NEV production and export markets. Maharashtra and Gujarat host emerging foundry clusters positioned to capture battery tray and motor housing demand from Tata Motors and Mahindra electric platforms. BIS certification requirements for automotive components extend qualification timelines but create barriers against low-cost import competition.
Japan
METI industrial policy supports magnesium die-casting process innovation for electronics lightweighting and automotive transmission applications. Chubu and Kansai regions maintain precision foundry capabilities serving Toyota and Honda electrification programs. JIS standards for aluminum alloy specifications create technical entry barriers that protect established supplier relationships.
Die Casting Services Market Vendor Landscape
Concentration sits with integrated aluminum specialists and defense-certified magnesium foundries that anchor multi-year OEM supply contracts. The vendor base stratifies across three tiers: captive casting houses with in-house smelting, independent precision specialists with vacuum-assisted process certification, and commodity zinc foundries serving industrial hardware. Strategic moves center on giga-press capacity installation for single-piece structural castings and backward integration into primary aluminum supply.
Among North American automotive suppliers, Nemak and Linamar Corporation exemplify integrated casting-to-assembly positioning, while GF Casting Solutions represents diversification beyond automotive cyclicality into water-management and building-technology applications. Rheinmetall AG occupies a defense-aerospace certification niche that creates supply scarcity for structural magnesium components. These archetypes illustrate how process specialization and customer integration depth determine margin sustainability across contract structures.
| Leading Market Players |
|---|
| Nemak |
| Ryobi Die Casting |
| Linamar Corporation |
| Pace Industries |
| Alcoa |
| Dynacast |
| GF Casting Solutions |
| Rheinmetall AG |
| Martinrea |
| Others |
Supply Flow & Price Mechanics
Giga-press capacity utilization above 85% anchors price floors for aluminum structural castings, compressing margins at smaller foundries lacking equivalent scale while concentrating procurement leverage among integrated operators with captive smelting. This scale dynamic reinforces supply concentration in China's Yangtze River Delta and Germany's automotive corridor, where hourly replenishment contracts transfer inventory risk downstream.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures with dedicated line-side delivery, while on-demand services for NEV startups command premium piece rates. Price differentiation separates vacuum-assisted HPDC certification tiers from conventional porosity-tolerant processes, with EPA fleet efficiency mandates intensifying cost compression in standard-grade aluminum. Tier-two suppliers exhibit highest price sensitivity due to LME-linked input exposure, whereas defense-aerospace buyers absorb magnesium premiums for AS9100-credentialed supply security.
Supply Chain Analysis
Sixteen-to-twenty-four week tooling lead times from German and Japanese specialty mold fabricators tether production schedules to upstream capacity constraints. Primary aluminum draws from China, Russia, and UAE smelters, while magnesium feedstock rests on Chinese production dominance. Single-source vulnerability concentrates in high-precision die sets and vacuum-assisted process equipment. Distribution runs through tier-one supplier co-location with vehicle assembly plants, compressing logistics costs for just-in-time programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
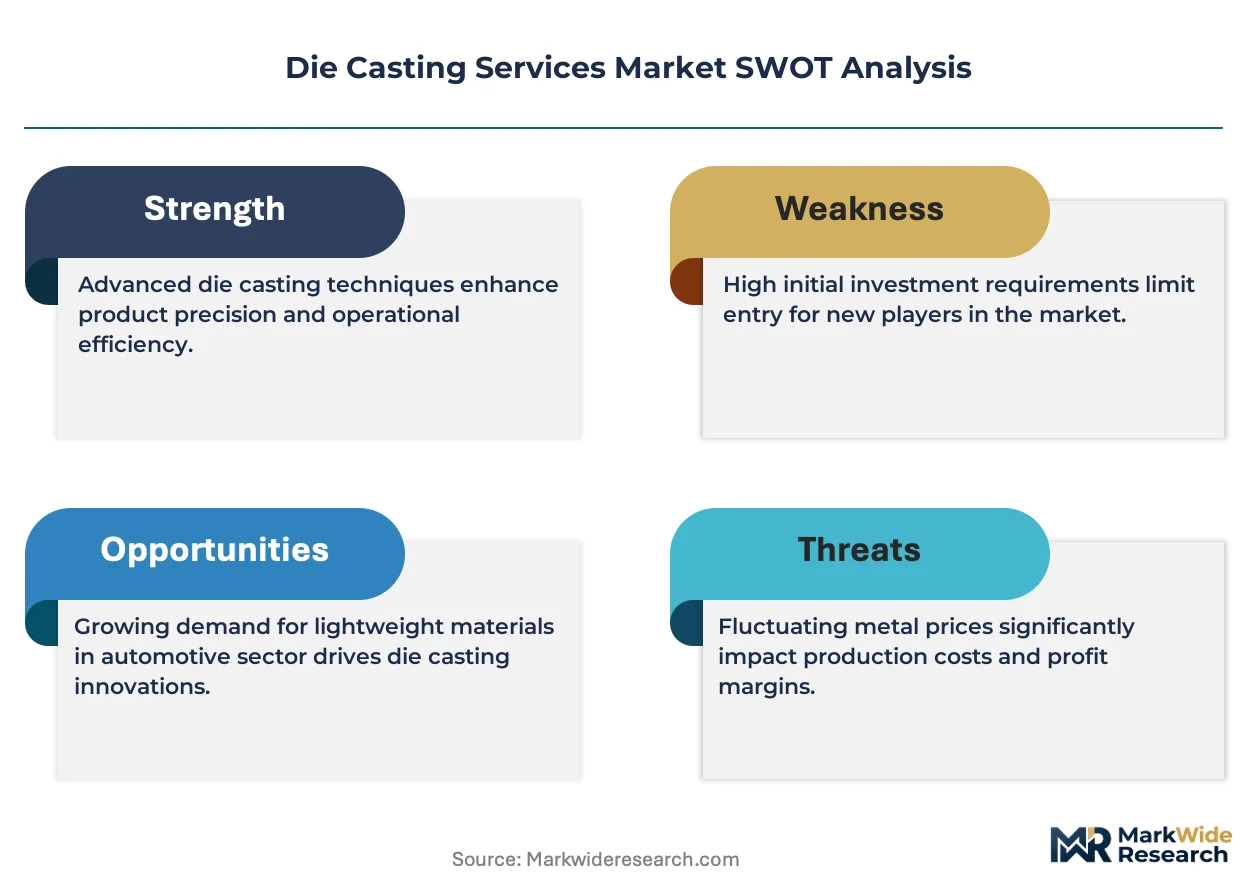
Polymer composite battery enclosures and stamped-aluminum hybrid structures threaten die-casting volume in non-structural applications, forcing incumbents to defend positioning through alloy innovation and process certification depth.
For Market Incumbents: Compound defensive moats by securing KBA type-approval for SF6-free magnesium processes before EU F-Gas Regulation phase-outs harden, and backward integrate into secondary aluminum traceability systems to capture EU Green Deal recycled-content premiums. Electrification-driven platform consolidation favors foundries with giga-press capacity and multi-year OEM capacity commitments.
For New Entrants and Emerging Players: Anchor in India's PLI scheme localization corridors to serve domestic NEV production and export markets, where BIS certification barriers filter import competition. Target data center thermal-management plate demand as the most penetrable white-space segment, leveraging rapid tooling iteration capabilities for liquid-cooled server architectures.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated casting houses with captive aluminum smelting and vacuum-assisted HPDC certification, as process simulation talent scarcity extends tooling validation timelines and concentrates design authority. Monitor MAGMASOFT expertise acquisition patterns as the inflection signal for qualification-cycle compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Giga-Press Capacity Installation | Enables single-piece rear-floor castings that displace 70+ welded components under Tesla's architecture. |
| Backward Integration into Secondary Aluminum | Captures EU Green Deal recycled-content mandates through closed-loop scrap traceability systems. |
| SF6-Free Process Certification | Secures KBA type-approval for magnesium structural components ahead of EU F-Gas Regulation phase-outs. |
| Co-Location with NEV Assembly Plants | Compresses logistics costs for hourly replenishment cycles under Yangtze River Delta clustering dynamics. |
| Process Simulation Talent Acquisition | Accelerates tooling validation timelines threatened by MAGMASOFT and ProCAST expertise gaps. |
Methodological Framework
Operator-level perspectives from foundry operations directors, OEM platform engineers, Tier 1 supplier procurement leads, and aftermarket distribution managers anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation across SEC 10-K filings, customs and trade databases, IHS Markit vehicle production data, and SAMR GB standard enforcement records. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Sensitivity analysis tested volume and value outputs across alloy substitution scenarios, NEV platform penetration curves, and primary aluminum price volatility bands. Segmentation dimensions modeled include alloy type, application end-use, delivery model structure, and regional production cluster. CAGRs derived from regression analysis of historical capacity utilization, OEM procurement award patterns, and regulatory compliance cost trajectories, with specific weighting for MIIT dual carbon mandate timing and EPA CAFE standard phase-in intensity.
Material uncertainties — LME pricing swings, tooling fabrication bottlenecks, and multi-material joining certification delays — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding electrification platform architectures and recycled aluminum feedstock availability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Services
North America Repair and Rehabilitation Market
Construction Services
Middle East and Africa Industrial Maintenance Services in Operational Improvement and Operational Maintenance Market
Construction Services
Facade Cleaning and Maintenance Service Market
Construction Services
Heavy Equipment Training Simulator Market
Construction Services
Maintenance Repair and Operations (MRO) Market
Construction Services
Excavating Contractor Market
Construction Services
Construction Project Management Services Market
Construction Services
Remote Construction Market
Construction Services
North America Testing and Commissioning Market
Construction Services
Train Contractor Market
Construction Services
Condenser Cleaners Market
Construction Services
Dust Suppression Control Market
Construction Services
Construction Materials Testing Equipment Market
Construction Services
Construction TIC Market
Construction Services
Composite Autoclave Repair Market
Construction Services
Work Order Management Market