
 Condenser Cleaners Market | 2026-2036
Condenser Cleaners Market Size, Share, and Industry Trends Forecast 2026-2036
Condenser Cleaners Market Analysis
Multi-source procurement for chemical formulations is decoupling from traditional single-vendor maintenance contracts in the condenser cleaning sector. Nu-Calgon Wholesaler, Inc. leverages its wholesale distribution network to supply HVAC service contractors across North America with specialized foaming agents. Conco Systems, Inc. anchors its position through engineered cleaning programs for power generation and industrial heat exchangers. Taprogge GmbH differentiates via automated on-line cleaning systems for marine and power plant condensers.
Condenser cleaners are formulated chemical solutions or mechanical systems designed to remove fouling, scale, and biological deposits from heat transfer surfaces, typically operating at pH ranges between 2 and 12 depending on substrate compatibility. These products restore thermal efficiency in shell-and-tube, plate, and air-cooled condensers by dissolving mineral deposits or dislodging particulate matter without damaging copper, aluminum, or stainless steel substrates. Heavy-duty alkaline and acid-based formulations still dominate value sales across industrial equipment applications, though biodegradable cleaners are gaining fastest in food processing and municipal water treatment settings where effluent discharge regulations tighten. Chemical cleaning technology occupies the largest installed base, while ultrasonic cleaning is penetrating precision electronics cooling and medical refrigeration niches where zero-residue requirements apply.
The US EPA regulates condenser cleaner chemistries through FIFRA pesticide registration requirements and SNAP program phase-down rules affecting associated refrigerant systems. Germany's Federal Environment Agency enforces REACH compliance and F-Gas Regulation quotas that constrain volatile solvent content in maintenance products. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions under EU REACH annex amendments, as these directly impact formulation options for high-performance degreasing applications.
Market Dynamics
Commercial refrigeration operators are expanding maintenance budgets for coil and fin cleaning protocols. The US EPA's SNAP program restrictions on high-GWP refrigerants are accelerating cleaner formulation changes across the installed base.
Growth Catalysts
- Commercial Refrigeration Maintenance Budget Expansion:Food retail chains and cold storage operators are institutionalizing preventive cleaning schedules to protect energy efficiency guarantees on refrigeration equipment.
- F-Gas Regulation Compliance Mandates:Germany's Federal Environment Agency enforces strict volatile solvent quotas that compel industrial HVAC operators to replace legacy cleaning chemistries with compliant formulations.
- Power Generation Heat Exchanger Refurbishment Cycles:Aging thermal power plants across Asia-Pacific markets are driving replacement demand for heavy-duty alkaline and acid-based condenser cleaning systems.
Market Restraints
- Copper and Aluminum Substrate Compatibility Constraints:Aggressive pH formulations that dissolve mineral deposits risk corrosion damage, limiting cleaner concentration options for mixed-metal condenser designs.
- REACH Compliance Cost Burden:EU chemical registration requirements impose testing and documentation expenses that compress margins for small-formulation suppliers serving niche end-uses.
- Zero-Liquid-Discharge Substitution Pressure:Dry ice blasting and mechanical pigging systems are capturing share in marine and power plant applications where effluent restrictions prohibit chemical discharge.
Strategic Opportunities
- Biodegradable Formulation White Space:Food processing facilities and municipal water treatment plants face tightening effluent discharge regulations, creating demand for pH-neutral, biodegradable cleaners that maintain performance parity with legacy chemistries.
- Ultrasonic Technology Convergence:Precision electronics cooling and medical refrigeration niches require zero-residue cleaning protocols, opening penetration paths for ultrasonic systems integrated with automated handling equipment.
- On-Line Cleaning System Retrofit Demand:Marine and power plant operators are retrofitting fixed condenser installations with automated Taprogge-type ball cleaning systems to eliminate downtime associated with offline chemical cleaning.
Industry Challenges
- Multi-Metal Corrosion Control Expertise Gap:Formulation chemists with simultaneous expertise in copper, aluminum, and stainless steel substrate protection remain scarce, constraining product development velocity for universal cleaner platforms.
- EPA FIFRA Registration Timeline Compression:Pesticide registration requirements for antimicrobial cleaner claims extend commercialization timelines by 18-24 months, delaying revenue recognition for novel biocide formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Condenser Cleaners Market |
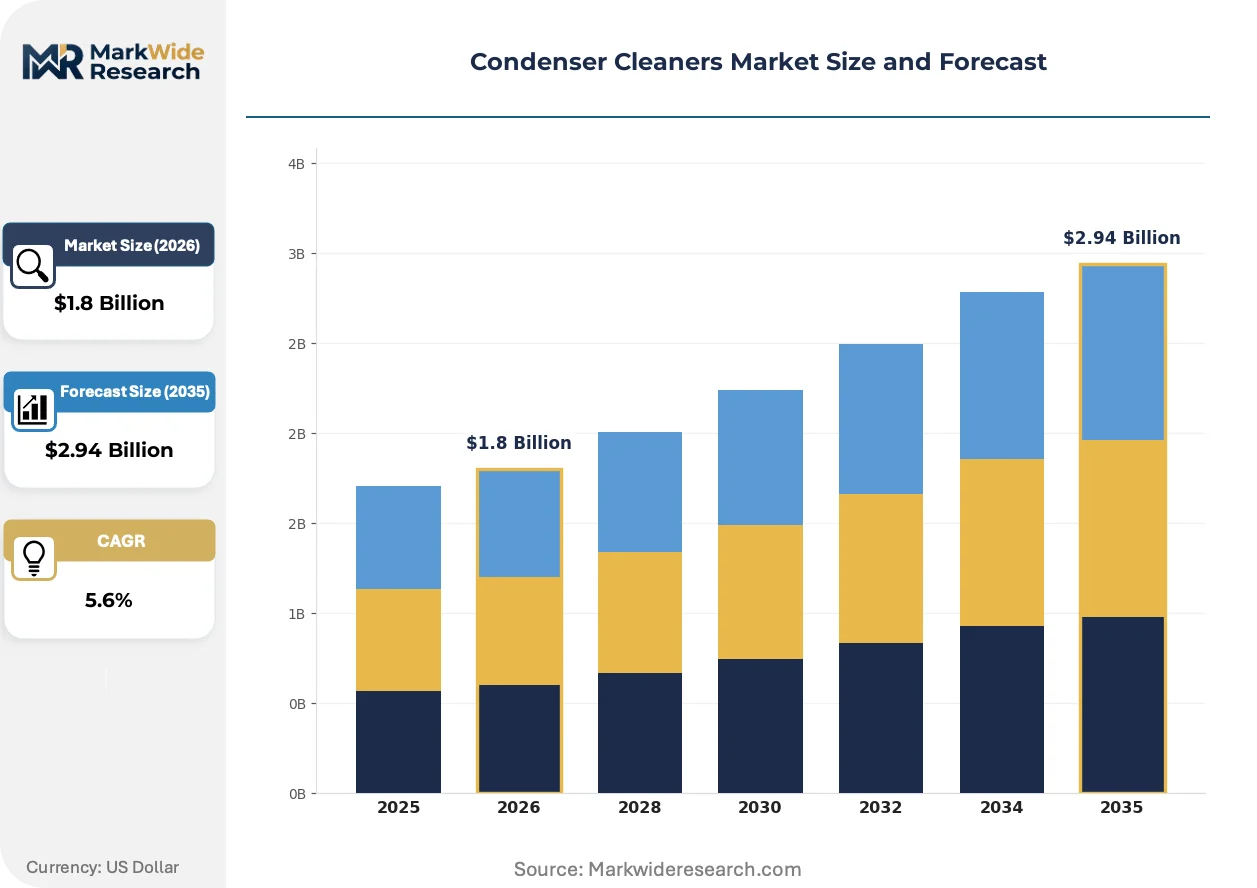
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.94 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heavy-Duty Cleaners, Biodegradable Cleaners, Foam Cleaners, Liquid Cleaners Application: HVAC Systems, Marine Equipment, Industrial Equipment, Commercial Refrigeration Technology: Chemical Cleaning, Electrostatic Cleaning, Steam Cleaning, Ultrasonic Cleaning End User: Manufacturers, Service Providers, Municipalities, Maintenance Professionals |
| Companies Covered | Nu-Calgon Wholesaler, Inc., Conco Systems, Inc., Taprogge GmbH, BEAUDREY, Goodway Technologies Corp., DiversiTech Corporation, RectorSeal LLC, WesTech Engineering, LLC, Atlantic Chemical & Equipment Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Condenser Cleaners Market Emerging Trajectories
Formulation chemistry is pivoting toward substrate-specific compatibility and effluent-neutral biodegradability. Equipment automation is reducing labor dependence in large-scale industrial cleaning operations.
Surfactant-based foaming agents are absorbing market share from solvent-heavy degreasers in HVAC maintenance applications. Commercial refrigeration service contractors are adopting these formulations to comply with volatile organic compound restrictions. The shift is absorbing capital from traditional solvent manufacturing capacity and redirecting it toward biosurfactant fermentation and green chemistry pilot plants.
REACH annex amendments targeting per- and polyfluoroalkyl substances are constraining high-performance degreasing options in EU jurisdictions. Industrial maintenance departments are reformulating standard operating procedures to exclude fluorinated surfactants previously relied upon for heavy fouling removal. German chemical suppliers are accelerating substitution trials with silicone-based and hydrocarbon alternatives ahead of 2025 restriction deadlines.
Multi-source procurement patterns are fragmenting traditional single-vendor maintenance contracts. HVAC service contractors are unbundling chemical supply from equipment service agreements, creating direct purchasing relationships with wholesale distributors. This disintermediation is most visible in North American commercial refrigeration markets where regional service chains are building captive chemical inventories to capture margin previously allocated to integrated service providers.
Condenser Cleaners Market Segmentation
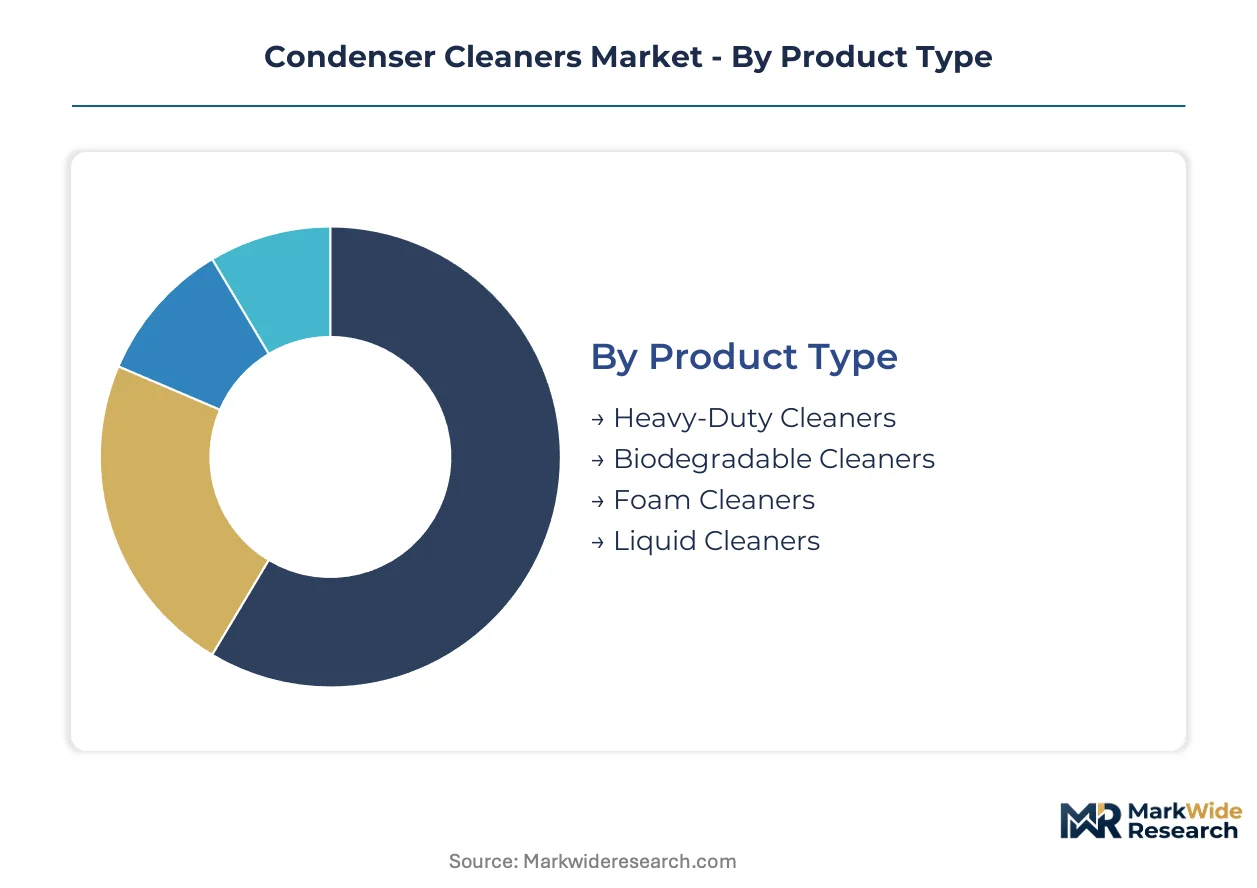
Condenser cleaner procurement decisions hinge on substrate compatibility requirements and discharge permit conditions. Segmentation reveals how formulation chemistry and delivery technology align with specific maintenance protocols across end-use verticals.
Product Type:
EPA FIFRA registration applies to antimicrobial formulations, while biodegradable variants face additional OECD 301 testing for effluent compliance in EU jurisdictions.
- Heavy-Duty Cleaners:Acidic and alkaline formulations with pH extremes between 2 and 12 dissolve mineral scale and biological fouling from industrial heat exchangers. Power generation operators in Germany specify these for turbine condenser refurbishment cycles driven by F-Gas Regulation compliance mandates.
- Biodegradable Cleaners:pH-neutral surfactant systems derived from plant-based feedstocks degrade within 28 days per OECD 301B protocols. Food processing facilities in the United States adopt these to satisfy EPA NPDES discharge limits without sacrificing copper coil compatibility.
- Foam Cleaners:Viscous foaming agents cling to vertical fin surfaces during HVAC maintenance.
- Liquid Cleaners:Low-viscosity solutions penetrate deep into shell-and-tube bundles for circulation-based cleaning.
Heavy-Duty Cleaners sits at the top of the volume ranking, with Biodegradable Cleaners climbing the fastest.
Application:
Cost tier stratification separates scheduled preventive maintenance from capital-intensive refurbishment projects.
- HVAC Systems:Coil and fin cleaning protocols protect energy efficiency guarantees on commercial refrigeration equipment. Service providers in North America unbundle chemical procurement from maintenance contracts to capture margin through direct wholesale purchasing.
- Marine Equipment:Seawater-cooled condensers aboard cargo vessels accumulate biological fouling that degrades thermal transfer. Automated on-line ball cleaning systems eliminate port downtime for chemical cleaning, displacing traditional offline methods in Asian-Pacific shipping lanes.
- Industrial Equipment:Heat exchangers in petrochemical and power generation facilities require heavy-duty formulations.
- Commercial Refrigeration:Food retail chains institutionalize preventive cleaning schedules to protect equipment warranties.
HVAC Systems commands the largest addressable base, with Marine Equipment expanding most quickly as fleet operators retrofit automated cleaning systems.
Technology:
Customer type determines automation tolerance, with industrial asset owners accepting higher capital expenditure for labor reduction.
- Chemical Cleaning:Formulated solutions dissolve deposits through acid-base reactions or surfactant action. This technology occupies the largest installed base across power generation and municipal water treatment sectors where substrate compatibility expertise constrains formulation options.
- Ultrasonic Cleaning:High-frequency acoustic cavitation removes contaminants without residue. Medical refrigeration and precision electronics cooling niches require zero-residue protocols, opening penetration paths for ultrasonic systems integrated with automated handling equipment.
- Electrostatic Cleaning:Charged particle attraction captures airborne debris from fin arrays.
- Steam Cleaning:High-pressure vapor dislodges organic matter without chemical discharge.
Chemical Cleaning retains dominant share, with Ultrasonic Cleaning gaining share fastest in regulated zero-discharge environments.
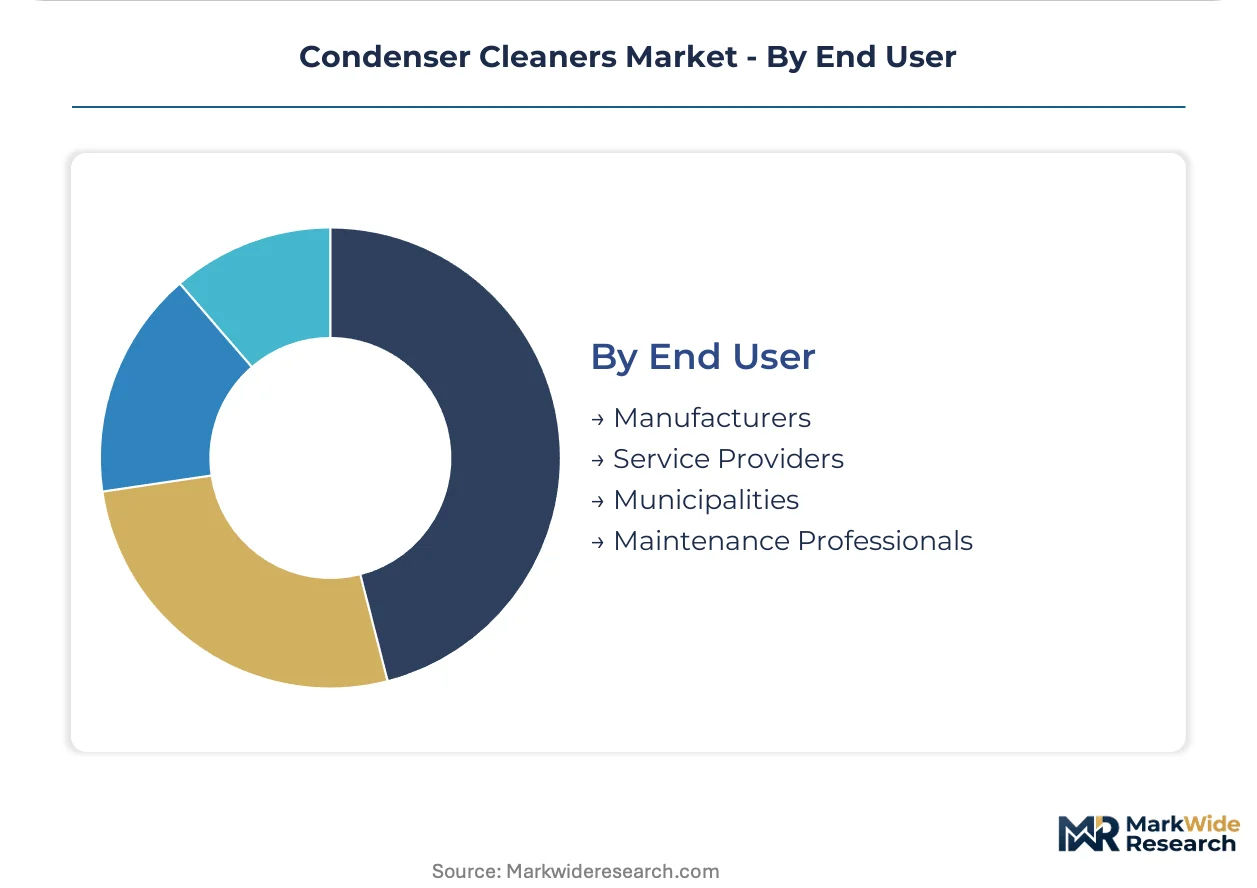
End User:
Supply concentration varies by procurement sophistication, with integrated service providers consolidating chemical volumes against fragmented independent contractors.
- Service Providers:HVAC and refrigeration contractors execute scheduled maintenance under performance contracts. Multi-source procurement patterns fragment traditional single-vendor agreements as regional chains build captive chemical inventories.
- Manufacturers:Original equipment producers specify approved cleaners for warranty compliance. REACH registration requirements impose testing costs that favor established formulation suppliers with dedicated regulatory affairs capacity.
- Municipalities:Water treatment plants face tightening effluent standards.
- Maintenance Professionals:Independent technicians purchase through wholesale distribution networks.
Service Providers represent the largest demand pool, with Manufacturers restructuring procurement fastest toward direct chemical sourcing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial HVAC retrofit cycles and F-Gas Regulation enforcement anchor regional demand patterns for condenser cleaning formulations. Chemical suppliers face divergent compliance frameworks across major economies, with substrate compatibility and discharge regulations shaping procurement decisions.
United States
Commercial refrigeration operators expand maintenance budgets for coil cleaning protocols. The EPA's SNAP program restricts high-GWP refrigerants, accelerating cleaner formulation changes. Food retail chains in the Midwest institutionalize preventive schedules to protect energy efficiency guarantees on equipment.
Germany
Industrial HVAC retrofit cycles and strict F-Gas Regulation compliance drive replacement of legacy cleaning chemistries. The Federal Environment Agency enforces REACH compliance and volatile solvent quotas. Chemical suppliers in the Ruhr region accelerate substitution trials with silicone-based alternatives ahead of restriction deadlines.
China
Aging thermal power plants across coastal provinces drive demand for heavy-duty alkaline and acid-based cleaning systems. The Ministry of Ecology and Environment tightens effluent discharge standards for industrial maintenance operations. Equipment fabricators in Jiangsu province retrofit fixed condenser installations with automated on-line cleaning systems.
Japan
Precision electronics cooling and medical refrigeration niches require zero-residue cleaning protocols. METI guidelines promote substrate-specific compatibility in chemical formulations. Manufacturers in the Kansai region integrate ultrasonic systems with automated handling equipment for regulated zero-discharge environments.
India
Municipal water treatment plants face tightening effluent standards under Central Pollution Control Board mandates. Food processing facilities adopt pH-neutral, biodegradable cleaners to satisfy discharge limits. Service providers in Maharashtra unbundle chemical procurement from maintenance contracts to capture margin through direct wholesale purchasing.
Condenser Cleaners Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue biodegradable formulation niches and automated equipment segments. The vendor base spans wholesale distributors, engineered program specialists, and automated system fabricators. Three archetypes dominate: chemical formulators with regulatory affairs capacity, equipment-integrated solution providers, and wholesale distributors serving fragmented contractor networks. Capacity expansion and strategic partnerships represent the dominant competitive moves, with suppliers building captive chemical inventories and licensing automated cleaning technologies.
Within the wholesale distribution archetype, Nu-Calgon Wholesaler, Inc. occupies a position serving HVAC service contractors across North America. Conco Systems, Inc. anchors the engineered program tier through power generation and industrial heat exchanger applications. Taprogge GmbH exemplifies the automated equipment vector for marine and power plant condenser installations.
| Leading Market Players |
|---|
| Nu-Calgon Wholesaler, Inc. |
| Conco Systems, Inc. |
| Taprogge GmbH |
| BEAUDREY |
| Goodway Technologies Corp. |
| DiversiTech Corporation |
| RectorSeal LLC |
| WesTech Engineering, LLC |
| Atlantic Chemical & Equipment Co. |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap chemical formulators in Germany's Ruhr region anchor supply-side discipline through captive fermentation capacity for biosurfactant feedstocks, translating into pricing power over biodegradable cleaner tiers where REACH compliance costs exclude commodity competitors.
Pricing Analysis
Input-cost pass-through from surfactant feedstock volatility shapes tiered pricing across heavy-duty alkaline, biodegradable neutral, and foam cleaner categories. Price differentiation separates EPA FIFRA-registered antimicrobial formulations from standard degreasers based on registration investment recovery and substrate compatibility certification. Pricing pressure stems from REACH compliance documentation burdens compressing margins for small-batch suppliers serving niche end-uses. Independent maintenance technicians exhibit highest price sensitivity through wholesale distributor channels, while power generation operators accept premium positioning for engineered cleaning programs with performance guarantees.
Supply Chain Analysis
Freight cost escalation from specialty chemical consolidation centers in Germany, China, and the United States drives regional inventory positioning strategies among HVAC service contractors. Raw material sourcing draws from palm-derived surfactant feedstocks, phosphoric acid for pH adjustment, and silicone-based defoamers substituting fluorinated alternatives. Supply chain risk centers on single-source vulnerability for OECD 301B-certified biodegradable base stocks amid EU restriction timelines. Distribution runs through wholesale distributor networks serving fragmented contractor markets, with direct procurement patterns emerging among regional service chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The condenser cleaners market functions as a regulatory compounder where EU F-Gas Regulation phase-down schedules and REACH annex amendments on per- and polyfluoroalkyl substances create recurring formulation refresh cycles that lock in replacement demand.
For Market Incumbents: Lock in substrate-specific formulation expertise across copper-aluminum-stainless steel compatibility matrices to defend against ultrasonic cleaning substitution in medical refrigeration niches. Deepen captive supply of biosurfactant fermentation capacity to capture margin from biodegradable cleaner demand acceleration under tightening effluent standards. For New Entrants and Emerging Players: Begin with pH-neutral biodegradable formulations for food processing facilities facing EPA NPDES discharge limits, where incumbent REACH registration costs create entry barriers. Pursue direct wholesale distribution relationships with regional HVAC service chains unbundling chemical procurement from integrated maintenance contracts. For Investors and Strategic Acquirers: Valuations sit cheapest among automated equipment fabricators with marine and power plant installed bases, where on-line cleaning system retrofit demand compounds recurring revenue streams. Monitor ball cleaning system adoption rates in Asia-Pacific shipping lanes as inflection indicator for capital deployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Biosurfactant Feedstocks | German formulators secure OECD 301B certification pathways while insulating margin from agricultural commodity volatility. |
| REACH Registration Capacity Expansion | Established suppliers amortize testing documentation costs across broader formulation portfolios to exclude small-batch competitors. |
| Automated On-Line System Licensing | Equipment fabricators in China retrofit fixed condenser installations for marine operators eliminating port downtime. |
| Direct Wholesale Distribution Buildout | Regional HVAC service chains capture chemical margin previously allocated to integrated maintenance providers. |
| Fluorinated Surfactant Substitution R&D | Ruhr region chemists accelerate silicone-based and hydrocarbon alternative trials ahead of EU restriction deadlines. |
Methodological Framework
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core, combining primary interviews with maintenance directors at power generation facilities, HVAC service contractors, food processing plant engineers, and marine fleet operations managers with secondary validation through EPA FIFRA registration databases, ECHA REACH dossiers, customs trade flow records, and SEC filings from chemical distribution companies.
Historical trendline analysis of formulation chemistry shifts and equipment automation adoption patterns anchors projection modeling across product type, application, technology, and end user segments throughout the forecast period. CAGRs derive from regression analysis of maintenance budget expansion rates, regulatory compliance cost pass-through coefficients, and substrate compatibility constraint matrices.
Several conditions sit outside the modeled scope, including unannounced regulatory acceleration beyond current EU restriction timelines and breakthrough zero-residue cleaning technologies displacing chemical formulations entirely. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Services
Facade Cleaning and Maintenance Service Market
Construction Services
Remote Construction Market
Construction Services
Grease Trap Service Market
Construction Services
Global Industrial Services Market
Construction Services
North and Latin America Weatherization Services Market
Construction Services
Construction Equipment Repair and Maintenance Services Market
Construction Services
3D Concrete Printing Services Market
Construction Services
MENA Architectural Services Market
Construction Services
Train Contractor Market
Construction Services
Composite Autoclave Repair Market
Construction Services
Construction Materials Testing Equipment Market
Construction Services
Excavating Contractor Market
Construction Services
Heavy Equipment Training Simulator Market
Construction Services
Die Casting Services Market
Construction Services
Middle East and Africa Industrial Maintenance Services in Operational Improvement and Operational Maintenance Market
Construction Services
Industrial Maintenance Services Market