
 Dust Control Systems Market | 2026-2036
Dust Control Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Dust Control Systems Market Analysis
HEPA-grade and near-HEPA specification upgrades is bifurcating the competitive landscape between premium engineered systems and commodity filtration hardware. Donaldson Company leverages its vertically integrated filter media production to sustain margin advantage across North American mining accounts. Nederman Holding AB anchors its position through modular extraction architectures that dominate European manufacturing facilities. Illinois Tool Works Inc. competes via portable collection units purpose-built for construction site mobility.
Dust control systems encompass engineered equipment and consumable media designed to capture, suppress, or filter particulate matter across industrial and commercial environments, typically achieving capture efficiencies from 99.0% to 99.97% depending on filter class and airflow configuration. Their primary purpose centers on protecting worker respiratory health, maintaining process equipment integrity, and ensuring compliance with ambient air quality mandates. Wet suppression systems lead product type revenue due to lower capital barriers and simpler retrofit compatibility with existing material handling infrastructure. Mechanical filtration technologies occupy the largest technology share as baghouse and cartridge collectors remain the default specification for cement and mining applications with heavy particulate loads. Indoor air quality applications within manufacturing end users represent the fastest-expanding segment as semiconductor and battery cell producers impose sub-micron cleanliness protocols.
The US Mine Safety and Health Administration and OSHA enforce progressively lower permissible exposure limits for respirable crystalline silica, directly accelerating replacement cycles for legacy dry collection equipment. China's Ministry of Ecology and Environment implements regional air quality action plans that mandate continuous emissions monitoring and upgraded dust capture at cement and steel facilities, conditioning market access on demonstrated compliance. Stakeholders must monitor evolving filter efficiency testing protocols and regional enforcement variance to align R&D roadmaps with compliance timelines that outpace current product certification baselines.
Market Dynamics
Stringent respirable silica exposure limits enforced by the US Mine Safety and Health Administration and China's Ministry of Ecology and Environment are forcing wholesale replacement of legacy dry collection infrastructure across mining and heavy manufacturing clusters.
Growth Catalysts
- OSHA Silica Rule:The US Occupational Safety and Health Administration's tightened permissible exposure limit for respirable crystalline silica mandates equipment upgrades at cement plants and foundries, accelerating capital deployment toward HEPA-grade filtration systems.
- Battery cell manufacturing:Gigafactory construction for electric vehicle batteries imposes sub-micron cleanliness protocols that require engineered dust capture solutions for electrode coating and dry room operations.
- Wet suppression retrofits:Australian mining operations expand misting and foam injection systems to meet workplace exposure standards while avoiding production downtime from dry collector maintenance cycles.
Market Restraints
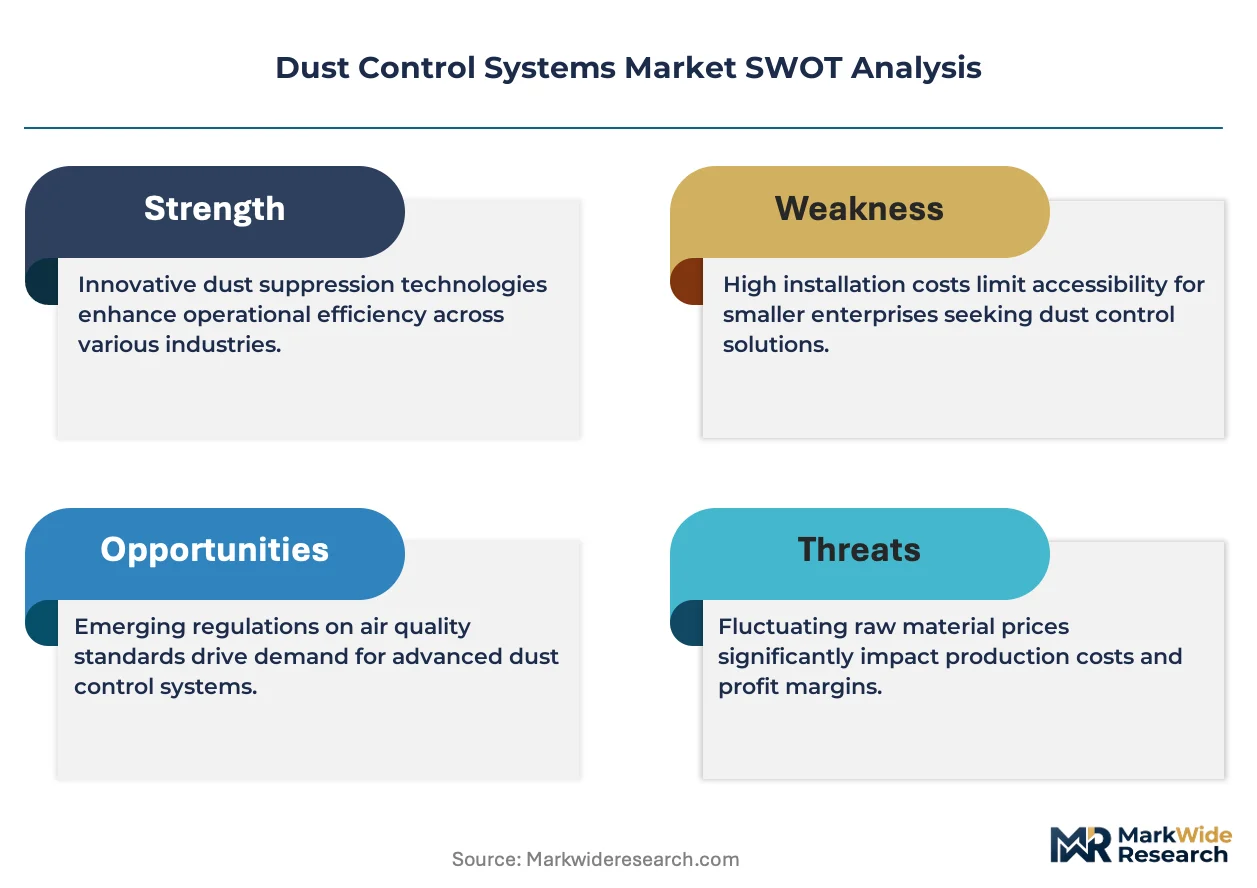
- Filter media cost volatility:Specialized synthetic fibers and nanofiber layers face input price pressure from petrochemical feedstock fluctuations, compressing margins for cartridge and baghouse suppliers.
- Technical performance ceiling:Conventional baghouse designs struggle to achieve consistent sub-micron capture efficiency without excessive pressure drop penalties that increase fan energy consumption.
- Substitution threat:Process redesign toward enclosed pneumatic conveying and slurry transport eliminates dust generation at source, reducing demand for end-of-pipe capture equipment in greenfield facilities.
Strategic Opportunities
- Indonesia nickel processing:Smelter expansion to feed battery supply chains creates demand for high-temperature gas conditioning and particulate control in rotary kiln and electric furnace operations.
- EU Green Deal industrial transitions:Carbon border adjustment mechanisms and emissions trading scheme reforms incentivize dust capture upgrades as co-benefits of energy efficiency and process intensification investments.
- Predictive maintenance convergence:Integration of differential pressure sensors and IoT connectivity with filtration systems enables remote monitoring contracts and consumables replenishment automation.
Industry Challenges
- Filter certification lag:Evolving ISO 16890 and EN 1822 test protocols for ePM1 efficiency ratings outpace product recertification timelines, creating compliance gaps for export-bound equipment.
- Retrofit integration complexity:Legacy material handling infrastructure in established mining and cement sites requires custom ductwork and airflow balancing that extends project delivery schedules and erodes contractor margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dust Control Systems Market |
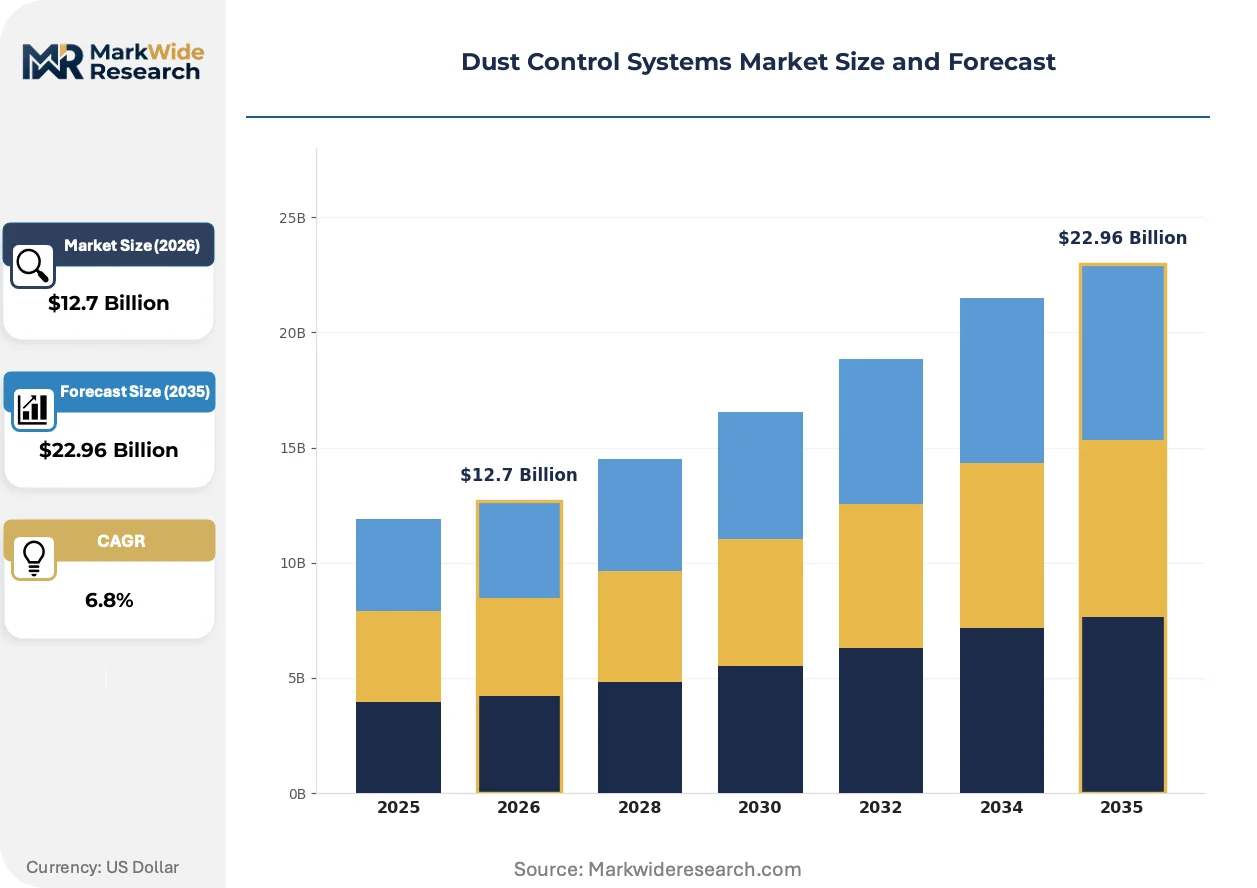
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $22.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wet Suppression, Dust Collectors, Air Filtration Systems, Vacuum Systems End User: Construction, Mining, Cement, Manufacturing Technology: Electrostatic Precipitation, Mechanical Filtration, Chemical Treatment, Biological Control Application: Road Dust Control, Indoor Air Quality, Work Safety, Industrial Processes |
| Companies Covered | Donaldson Company, Nederman Holding AB, Illinois Tool Works Inc., Dust Control Technologies, Sly Filters, Camfil APC, CW Machine Worx, Duztech AB, HEYLO GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dust Control Systems Market Emerging Trajectories
Active filtration architectures are displacing passive capture designs as energy costs and space constraints reshape equipment specifications. Three convergent developments are redefining competitive positioning.
Sintered metal fiber media is supplanting traditional cellulose and spunbond polyester in high-temperature pulse-jet applications. Nickel battery cathode producers and cement kiln operators adopt these cartridges for thermal stability above 200°C. The shift compresses replacement intervals from six months to three years while enabling smaller housing footprints.
China's Ministry of Ecology and Environment mandates continuous emissions monitoring systems at all cement and steel facilities above designated capacity thresholds. This policy forces integration of dust concentration sensors with control systems for real-time compliance demonstration. Domestic suppliers capture upgrade contracts by bundling hardware with data platform subscriptions.
Equipment-as-a-service contracting displaces capital purchase models for mid-scale manufacturing facilities. Filtration OEMs retain ownership and responsibility for performance guarantees, charging per cubic meter of air treated. German automotive suppliers and Japanese electronics assemblers pilot these arrangements to convert fixed capital to operational expenditure.
Dust Control Systems Market Segmentation
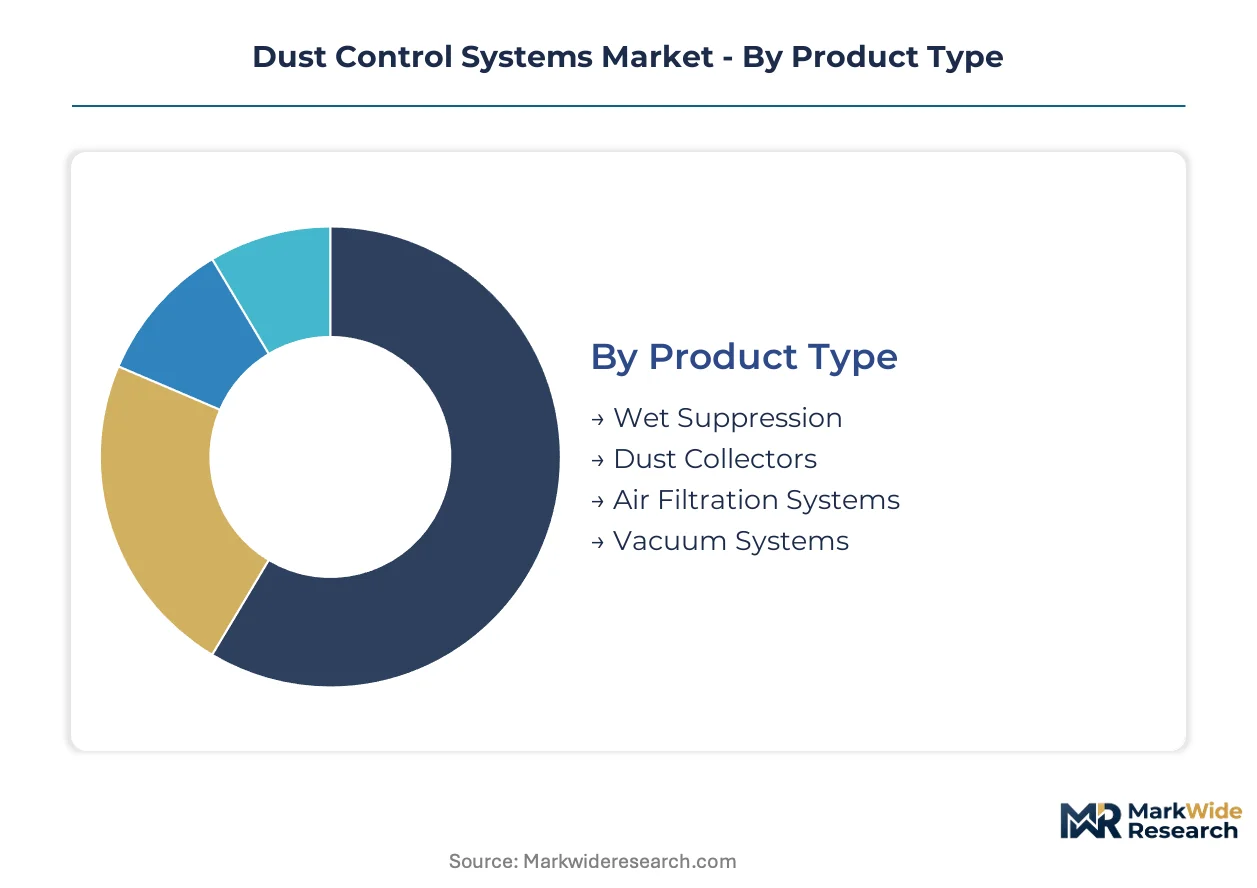
Dust control systems serve heterogeneous operational environments where specification requirements diverge sharply between heavy particulate mining operations and sub-micron semiconductor cleanrooms. Channel strategy must align product portfolios with distinct procurement pathways: mining and cement buyers favor direct OEM relationships for engineered systems, while manufacturing facilities increasingly source through integrated facility management contractors.
Product Type:
Wet suppression systems and dust collectors move primarily through direct sales channels with extensive field engineering support, whereas air filtration and vacuum systems increasingly route through HVAC distributors and industrial supply houses.
- Wet Suppression:Misting, fogging, and foam injection systems deploy water or chemical surfactants to agglomerate airborne particles before they disperse. Australian iron ore operations in the Pilbara region are expanding these deployments to meet workplace exposure standards without interrupting production cycles.
- Dust Collectors:Baghouse and cartridge collector assemblies with pulse-jet cleaning mechanisms handle heavy particulate loads in cement kilns and foundry operations. China's cement corridor cities mandate continuous emissions monitoring integration, forcing control system upgrades on legacy installations.
- Air Filtration Systems:HEPA and near-HEPA specification units address sub-micron capture requirements in battery cell gigafactories and pharmaceutical cleanrooms.
- Vacuum Systems:Portable and centralized vacuum extraction equipment serves construction site remediation and metalworking chip recovery applications.
Wet suppression dominates installed base in mining and material handling. Air filtration systems are where expansion concentrates as semiconductor and battery manufacturing impose stricter cleanliness protocols.
End User:
Cost tier segmentation separates premium engineered solutions for process-critical manufacturing from standard commodity equipment for general construction applications.
- Construction:Mobile dust suppression and portable collection units address silica exposure during demolition, concrete cutting, and tunneling operations. OSHA enforcement of respirable crystalline silica limits drives replacement of legacy dry sweep methods with vacuum-assisted surface preparation.
- Mining:High-volume wet suppression and dry collection infrastructure protects workers in underground coal, hard rock, and surface extraction operations. The US Mine Safety and Health Administration's tightened permissible exposure limits force wholesale equipment upgrades across Appalachian and Western operations.
- Cement:Kiln gas conditioning and clinker cooling particulate control systems manage high-temperature, high-humidity process streams.
- Manufacturing:Semiconductor fabrication, battery electrode coating, and pharmaceutical processing impose sub-micron cleanliness standards that demand engineered filtration architectures.
Mining holds the largest equipment installed base. Manufacturing is climbing the fastest as cleanroom protocols expand beyond traditional semiconductor into battery and pharmaceutical production.
Technology:
Volume concentration favors mechanical filtration for established heavy industry, while emerging applications drive investment in precision precipitation and advanced treatment methods.
- Electrostatic Precipitation:High-voltage ionization systems capture fine particulate in power generation and metallurgical smelting gas streams. Indonesia's nickel processing smelter expansion creates demand for high-temperature gas conditioning paired with precipitation systems in rotary kiln off-gas treatment.
- Mechanical Filtration:Fabric filter media in baghouse and cartridge configurations remains the default specification for cement, mining, and bulk material handling with heavy dust loads.
- Chemical Treatment:Surfactant and binder additives enhance wet suppression effectiveness on hydrophobic ore bodies and unpaved haul roads.
- Biological Control:Microbial and enzymatic treatments address organic dust and odor in agricultural processing and waste handling facilities.
Mechanical filtration commands the largest technology footprint. Electrostatic precipitation is gaining share fastest in high-temperature metallurgical and energy applications where thermal constraints exclude fabric media.
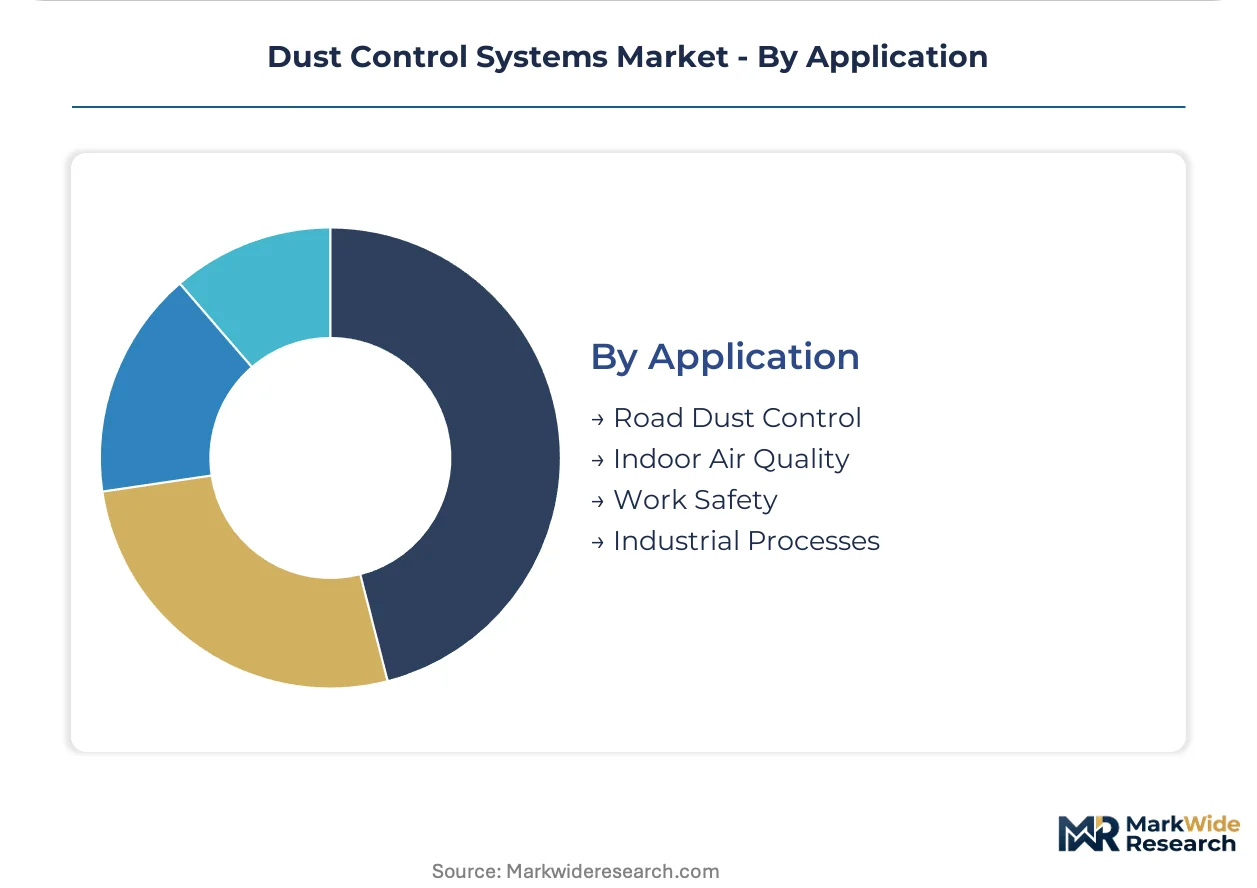
Application:
Customer type segmentation distinguishes between regulatory-driven compliance purchases and process-quality-driven performance specifications.
- Road Dust Control:Surface stabilization and suppression treatments for unpaved haul roads, construction sites, and municipal infrastructure. Chemical binder and magnesium chloride applications face growing substitution from foam-based suppression in environmentally sensitive jurisdictions.
- Indoor Air Quality:Engineered filtration for manufacturing cleanrooms, commercial buildings, and healthcare facilities. Battery cell gigafactories impose sub-micron protocols for electrode coating and dry room operations that exceed traditional HVAC specifications.
- Work Safety:Personal and area dust exposure reduction to meet occupational exposure limits in mining, construction, and demolition.
- Industrial Processes:Process-integrated capture and recovery systems that protect equipment integrity while enabling material recycling.
Industrial process applications dominate current equipment value. Indoor air quality is where specification intensity is expanding most quickly as semiconductor and battery manufacturing multiply cleanroom square footage requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment trade flows concentrate where mining and heavy manufacturing clusters face simultaneous regulatory tightening. Export-oriented suppliers in Germany and the United States ship engineered filtration systems to Australia's iron ore belt and China's cement corridor, while domestic fabricators in Indonesia and India capture smelter and construction demand.
United States
Appalachian coal operations and Western hard rock mines drive replacement demand for dry collection infrastructure. OSHA's respirable crystalline silica rule mandates HEPA-grade upgrades at cement plants and foundries. The Permian Basin and Powder River Basin mining districts are retrofitting legacy baghouses with continuous emissions monitoring integration.
China
Cement and steel production clusters in the Yangtze and Pearl River Deltas face intensifying MEE enforcement of regional air quality action plans. Continuous emissions monitoring is now mandatory at facilities above designated capacity thresholds. Zhengzhou and Tangshan steelworks are bundling dust capture hardware with domestic data platform subscriptions.
Australia
Pilbara iron ore operators expand wet suppression deployments to meet workplace exposure limits without production downtime. The national mining regulator enforces progressively lower respirable dust thresholds across surface and underground operations. Western Australia's dust control equipment imports are shifting toward misting and foam injection systems.
Germany
Automotive suppliers and precision manufacturers pilot equipment-as-a-service filtration contracts to convert fixed capital to operational expenditure. The EU Green Deal's carbon border adjustment mechanisms incentivize dust capture upgrades alongside energy efficiency investments. Bavarian and Baden-Württemberg industrial zones are integrating IoT-enabled differential pressure monitoring with maintenance contracts.
Indonesia
Nickel processing smelter expansion for battery supply chains creates demand for high-temperature gas conditioning and particulate control. The national mineral processing regulator is tightening emissions standards for rotary kiln and electric furnace operations. Sulawesi and Halmahera smelter clusters are importing electrostatic precipitation and fabric filter systems.
Dust Control Systems Market Vendor Landscape
Concentration sits with vertically integrated filter media producers and modular extraction specialists who control critical component supply. The vendor base spans three tiers: multinational engineered systems houses with captive media production, regional specialists in high-temperature or portable applications, and commodity hardware assemblers serving construction and small manufacturing. Dominant competitive moves include backward integration into synthetic fiber and sintered metal media production, plus geographic expansion through distribution partnerships in Southeast Asian smelter markets.
Among North American filtration houses, Donaldson Company exemplifies the vertically integrated archetype through in-house filter media production. Nederman Holding AB anchors the modular extraction tier with European manufacturing facility dominance. Illinois Tool Works Inc. occupies the portable equipment vector purpose-built for construction site mobility. These three represent distinct strategic positions rather than direct overlap, with each anchoring a procurement pathway: direct OEM relationships for mining, integrated facility management contracts for manufacturing, and rental channels for construction remediation.
| Leading Market Players |
|---|
| Donaldson Company |
| Nederman Holding AB |
| Illinois Tool Works Inc. |
| Dust Control Technologies |
| Sly Filters |
| Camfil APC |
| CW Machine Worx |
| Duztech AB |
| HEYLO GmbH |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at sintered metal fiber foundries in Germany and Japan shapes both supply concentration and price floors for high-temperature filtration media. Mining OEMs in Australia and cement producers in China absorb tiered pricing premiums for thermal-stable cartridges that compress replacement cycles from six months to three years.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Premium tiers command certification-grade HEPA and near-HEPA specifications for battery gigafactories and semiconductor cleanrooms, while economy tiers serve construction remediation with portable vacuum units. Cost compression in standard-tier baghouse media is intensifying because petrochemical feedstock volatility squeezes synthetic fiber margins. Construction rental channels exhibit highest price sensitivity, whereas pharmaceutical and battery cell manufacturers prioritize performance guarantees over unit cost.
Supply Chain Analysis
Strategic stockpiling of synthetic fiber media and nanofiber layers dominates inventory strategy over just-in-time approaches, given petrochemical price volatility and six-month lead times for specialized roll goods. Supply concentrates in Germany, Japan, and China for sintered metal fiber and high-efficiency filter media. Raw material dependencies draw from polypropylene meltblown webs, PTFE membranes, and nickel-alloy sintered matrices. Single-source vulnerability sits with German producers of high-temperature metal fiber media. Distribution runs through direct OEM relationships for mining and cement engineered systems, while HVAC distributors and industrial supply houses channel air filtration and vacuum equipment to manufacturing and construction end users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dust control systems sit in early-cycle expansion as sub-micron cleanliness protocols proliferate beyond semiconductor fabrication into battery electrode coating and pharmaceutical processing. OSHA silica enforcement and China's MEE air quality mandates accelerate replacement demand faster than historical equipment depreciation schedules.
For Market Incumbents: Fortify backward integration into synthetic fiber and sintered metal media production to defend margin position against petrochemical feedstock volatility. Expand captive filter media capacity in Germany and Japan to secure thermal-stable cartridge supply for nickel processing smelters in Indonesia. Accelerate ISO 16890 and EN 1822 recertification programs to close compliance gaps before export equipment faces rejected entry at Chinese and EU ports.
For New Entrants and Emerging Players: Anchor in Indonesia's nickel processing corridor where Sulawesi and Halmahera smelter clusters import electrostatic precipitation and fabric filter systems for rotary kiln off-gas treatment. Target equipment-as-a-service contracting models for mid-scale German automotive suppliers seeking to convert fixed capital to operational expenditure. Lead with IoT-enabled differential pressure monitoring bundled with predictive maintenance subscriptions rather than capital hardware sales.
For Investors and Strategic Acquirers: Modular extraction specialists with European manufacturing facility dominance represent the most defensible acquisition archetype as cleanroom protocols expand across battery and pharmaceutical production. Long-term viability hinges on differentiation through real-time emissions monitoring integration rather than commodity hardware assembly. Watch for MEE enforcement intensity in Tangshan and Zhengshan steelworks as the inflection signal—accelerated compliance deadlines trigger upgrade contract surges that outpace current supplier capacity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Filter Media | Captive synthetic fiber production insulates margins from petrochemical volatility affecting cartridge suppliers. |
| Equipment-as-a-Service Contracts | Per-cubic-meter pricing converts fixed capital to operational expenditure for German automotive suppliers. |
| Continuous Emissions Monitoring Integration | Hardware-data platform bundles satisfy China's MEE mandatory monitoring mandates at cement and steel facilities. |
| Predictive Maintenance Platform Development | IoT-enabled differential pressure sensors enable remote monitoring contracts and automated consumables replenishment. |
| High-Temperature Media Certification | Sintered metal fiber recertification opens nickel battery cathode and cement kiln applications above 200°C. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with plant engineers, OEM procurement teams, aftermarket service heads, and maintenance directors at mining and cement operations; and secondary validation through SEC 10-K filings, customs and trade data, MEE enforcement bulletins, and OSHA regulatory dockets. Bottom-up equipment shipment tallies by product type and end-use segment were triangulated against top-down market sizing derived from capital expenditure disclosures at major mining houses and cement producers.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning product type, end-use industry, technology class, and regional regulatory cluster. CAGRs were derived from regression analysis of historical equipment replacement cycles against regulatory compliance deadline schedules. Forecast inputs incorporated MEE air quality action plan enforcement trajectories, OSHA silica rule implementation phases, and gigafactory construction pipelines for battery cell manufacturing.
Material uncertainties—petrochemical feedstock price shocks, ISO 16890 test protocol revisions, and MEE enforcement intensity variance—sit outside the modeled envelope. Forecasts reflect assumptions about regulatory deadline adherence and smelter expansion timelines in Indonesia. Revision becomes warranted when OSHA or MEE accelerates permissible exposure limit reductions beyond currently published compliance schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Engineering
North America Rainwater Harvesting Market
Environmental Engineering
Outdoor Noise Barrier Market
Environmental Engineering
Aerobic Treatment Units Market
Environmental Engineering
Septic Tanks Market
Environmental Engineering
Secondary Water and Wastewater Treatment Equipment Market
Environmental Engineering
Fume Hoods Market
Environmental Engineering
Silt Curtain Market
Environmental Engineering
Global Rainwater Harvesting System Market
Environmental Engineering
Global Built and Natural Environment Consulting Market
Environmental Engineering
Rainwater Harvesting Market
Environmental Engineering
Tunnel Ventilation and Environmental Monitoring Systems Market
Environmental Engineering
Wet Scrubber Market
Environmental Engineering
Outdoor Sound Barrier Market
Environmental Engineering
Gas Scrubber Market