
 Remote Construction Market | 2026-2036
Remote Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Remote Construction Market Outlook
A chronic shortage of on-site heavy equipment operators is unwinding traditional project timelines across remote infrastructure zones. Trimble Inc. leverages its precision positioning hardware and software stack to anchor telematics workflows in mining and energy corridors. Procore Technologies competes through cloud-native project coordination tools that extend contractor oversight across dispersed job sites. Caterpillar Inc. dominates autonomous haulage and remote dozing systems, sustaining R&D intensity in machine-to-machine command protocols.
Remote construction encompasses the deployment of teleoperated, autonomous, and digitally tethered equipment to execute earthmoving, structural assembly, and quality verification in geographically isolated or hazardous environments where persistent human presence is impractical; systems typically integrate GNSS correction services, latency-tolerant control links, and real-time kinematic positioning achieving sub-centimeter accuracy to maintain grade and alignment tolerances. The technology dimension clusters around drones and IoT sensors as the fastest-expanding layer, with drone photogrammetry displacing manned aerial surveys and sensor networks enabling predictive equipment diagnostics that reduce unplanned downtime in fly-in-fly-out operations. BIM anchors the mature design-to-field data thread, while VR remains nascent outside training simulators and client walkthroughs, suggesting margin pools will concentrate in sensor fusion and edge-computing middleware rather than visualization hardware.
OSHA's evolving remote-work safety directives and the US Inflation Reduction Act's domestic content requirements are tightening compliance thresholds for contractors deploying teleoperated fleets on federally funded projects. Australia's Work Health and Safety Act and Canada's provincial occupational health statutes are similarly mandating redundant control failover and geofenced exclusion zones for autonomous equipment, reshaping vendor certification requirements. Stakeholders must weigh the capital burden of regulatory pre-certification against the operational leverage of early-mover positioning in jurisdictions where labor mobility constraints are structural rather than cyclical.
Market Dynamics
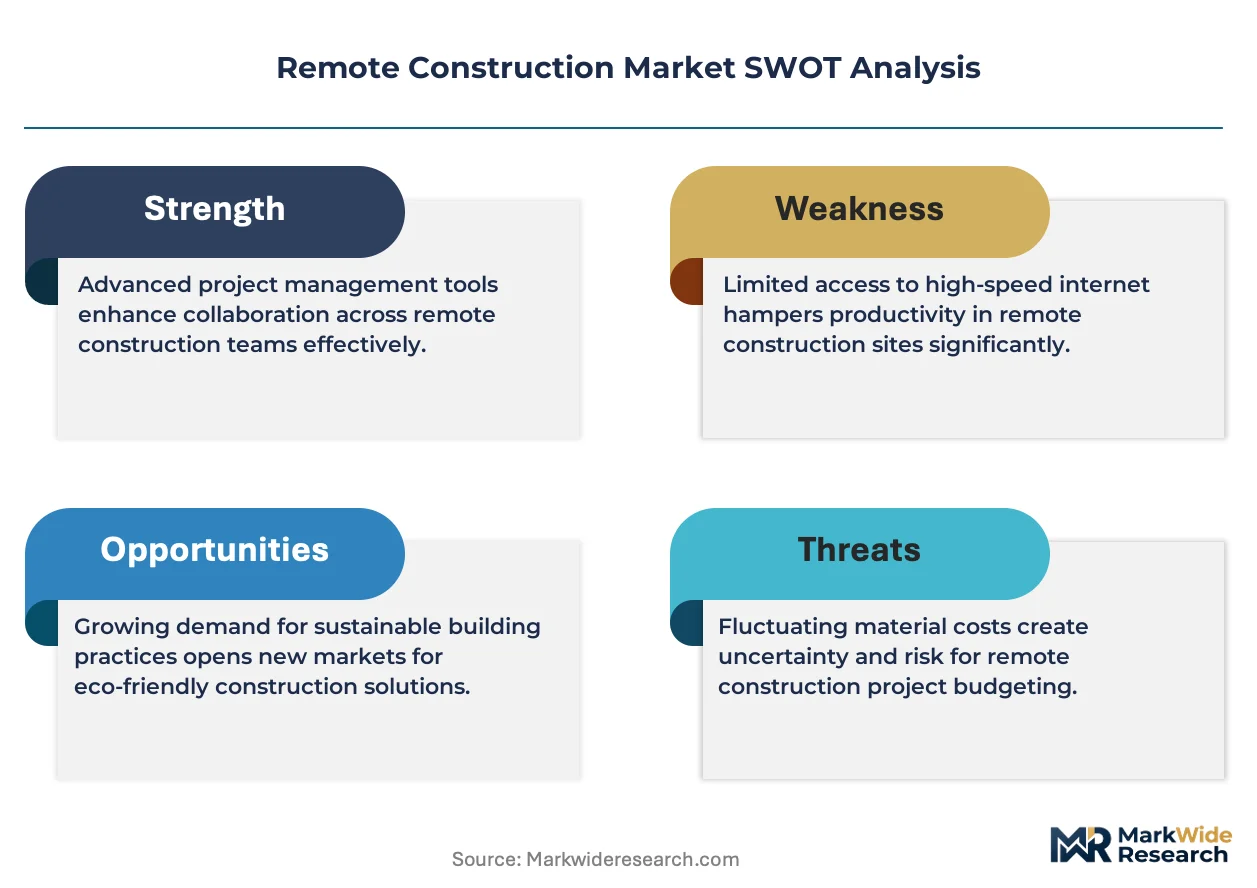
The persistent scarcity of qualified heavy equipment operators in geographically isolated mining and energy corridors is forcing contractors to restructure capital deployment around teleoperated and autonomous machine fleets rather than traditional labor-intensive models.
Growth Catalysts
- OSHA Remote-Work Safety Mandates:Tightening federal requirements for redundant control failover and operator visibility standards are compelling infrastructure contractors to upgrade legacy fleets with certified teleoperation systems on federally funded projects.
- Drone Photogrammetry:Unmanned aerial surveying platforms are compressing site mapping timelines from weeks to hours across Pilbara iron ore operations and Alberta oil sands developments, eliminating weather-dependent manned flight schedules.
- Labor Mobility Constraints:Structural shortages of fly-in-fly-out workers in Australia's northwest and Canada's northern territories are accelerating procurement of autonomous haulage and remote dozing capabilities as permanent operational fixtures.
Market Restraints
- Latency-Sensitive Control Links:Sub-100 millisecond command-response thresholds for precision earthmoving require dedicated low-orbit satellite bandwidth or fiber backhaul unavailable in many remote site locations.
- Capital Intensity of Fleet Conversion:Retrofit costs for teleoperation-ready cabs, redundant sensor arrays, and fail-safe braking systems often exceed 40% of baseline equipment value, stretching contractor balance sheets.
- Fragmented Certification Standards:Australia's Work Health and Safety Act, Canada's provincial occupational statutes, and US OSHA directives impose non-harmonized equipment pre-certification requirements that multiply compliance overhead for multinational fleet operators.
Strategic Opportunities
- Edge-Computing Middleware:Real-time sensor fusion and local inference processing at the machine level is opening margin pools in predictive maintenance and autonomous collision avoidance beyond hardware manufacturing.
- US Inflation Reduction Act Incentives:Domestic content requirements and clean energy infrastructure tax credits are redirecting federal procurement toward teleoperated construction systems assembled with qualifying North American component shares.
- VR Training Simulators:Immersive operator certification programs are reducing time-to-competency for remote equipment handlers while lowering insurance premiums and incident liability exposure in hazardous site conditions.
Industry Challenges
- RTK-GNSS Integration Complexity:Sub-centimeter positioning accuracy demands sophisticated correction service orchestration between base stations, rovers, and machine controllers, creating integration bottlenecks with legacy grade-control systems.
- Geofenced Exclusion Zone Enforcement:Autonomous equipment mandates for redundant perimeter monitoring and emergency stop protocols require site-wide infrastructure investment that smaller contractors struggle to amortize across limited project portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Remote Construction Market |
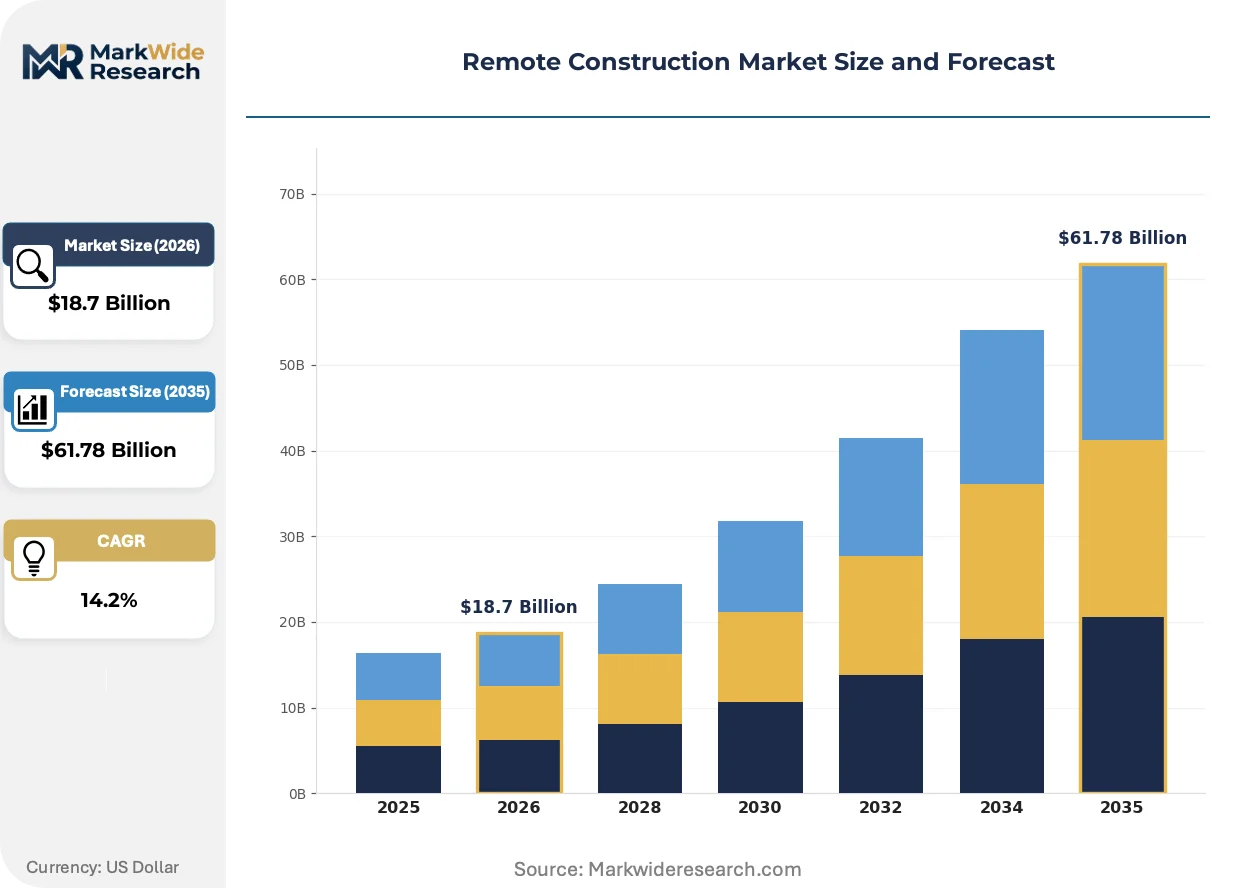
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Site Monitoring, Project Management, Remote Inspection, Quality Assurance Technology: Drones, IoT Sensors, VR, BIM End User: Contractors, Engineers, Architects, Surveyors Application: Infrastructure, Residential, Commercial, Industrial |
| Companies Covered | Trimble Inc., Topcon Corporation, Hexagon AB, Autodesk, Inc., Oracle Corporation, Procore Technologies, Bentley Systems, Caterpillar Inc., Hitachi Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Remote Construction Market Strategic Shifts
Teleoperation architectures are fragmenting from monolithic control systems into modular software stacks that permit rapid reconfiguration across equipment types and site conditions without vendor lock-in.
Real-time kinematic positioning hardware is decomposing traditional survey-grade accuracy from dedicated total station setups into embedded machine controllers. Mining contractors in Western Australia and oil sands operators in Alberta are adopting factory-integrated GNSS correction modules at replacement cycle points. This decomposition collapses the boundary between machine guidance and quality verification, compressing surveyor headcount requirements on remote sites.
The US Inflation Reduction Act's domestic content bonus credits are restructuring procurement evaluation criteria for federally supported remote infrastructure. Contractors now weight total cost of ownership against assembly origin documentation and component traceability. Equipment vendors with captive North American sensor and actuator supply chains are capturing disproportionate share in Department of Energy-funded geothermal and carbon capture construction programs.
Equipment-as-a-service contracting is displacing outright purchase for teleoperated fleets in capital-constrained mid-tier mining operations. Australian contract miners and Canadian energy services firms are leasing autonomous haulage capacity with bundled maintenance and operator training, transferring residual value risk to OEM financing arms. This model concentrates most rapidly in fly-in-fly-out operations where equipment utilization rates fluctuate with commodity price cycles.
Remote Construction Market Segmentation
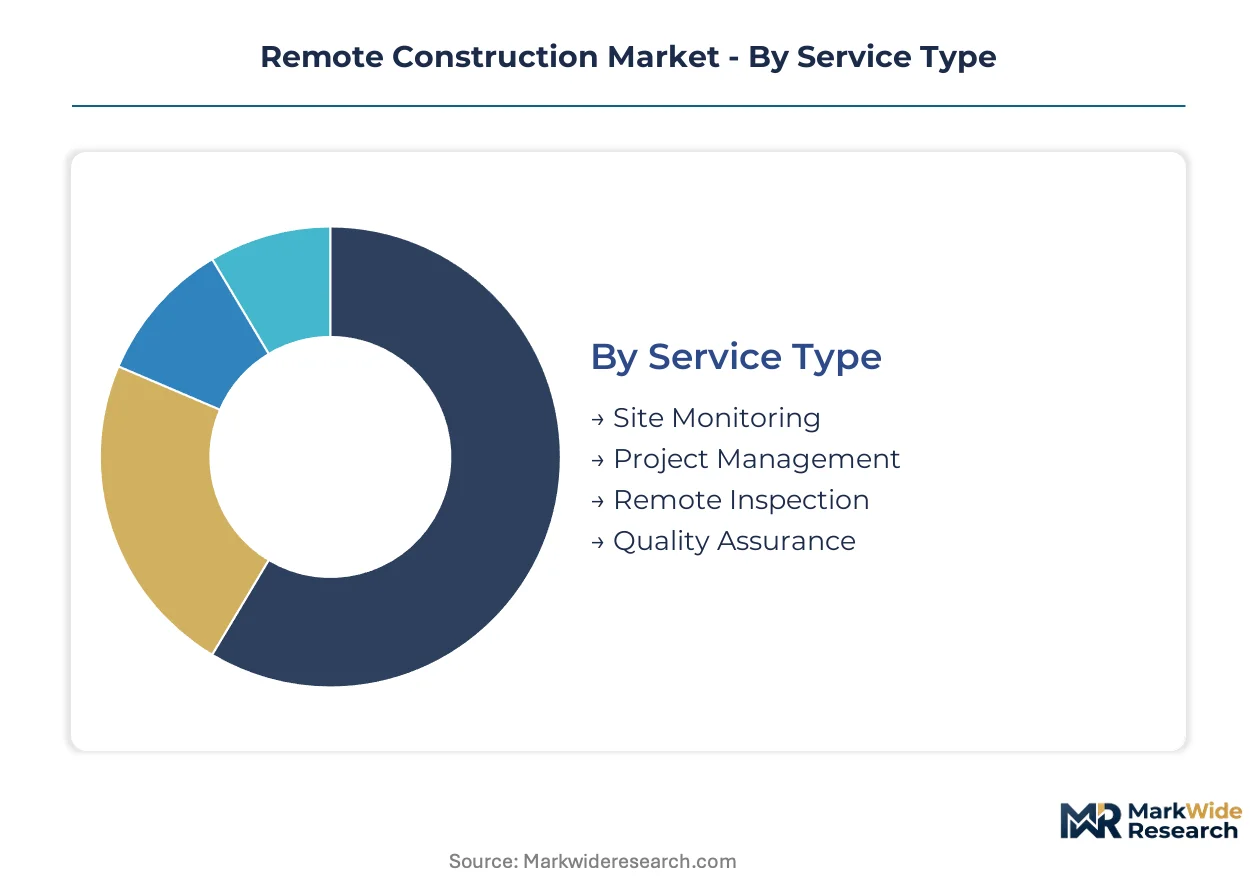
Segmentation in remote construction reveals how technology deployment varies by operational intensity and regulatory exposure. Service models diverge sharply between capital-heavy autonomous fleets and software-centric oversight platforms. Understanding these splits illuminates where margin pools concentrate and which customer types drive procurement decisions.
Service Type:
Geographic concentration splits this category: site monitoring and remote inspection serve predominantly domestic infrastructure markets tied to federal procurement rules, while project management and quality assurance platforms export across multinational contractor portfolios.
- Site Monitoring:Continuous telemetry feeds from teleoperated equipment and fixed sensor networks enable real-time visibility into earthmoving progress and safety perimeter compliance. Demand concentrates in Australia's Pilbara iron ore corridor where fly-in-fly-out labor constraints make persistent remote oversight essential for maintaining production schedules.
- Project Management:Cloud-native coordination platforms integrate BIM models with field data streams to synchronize dispersed contractor teams across time zones. Procurement is accelerating among Canadian oil sands operators managing multi-year developments with rotating joint-venture partners and shifting regulatory reporting requirements.
- Remote Inspection:Drone-based photogrammetry and thermal imaging replace manned site visits for structural verification and environmental compliance documentation.
- Quality Assurance:Automated grade-control verification using RTK-GNSS correction services ensures earthwork tolerances without surveyor presence on hazardous or inaccessible terrain.
Site monitoring commands the established base. The steepest expansion runs through project management platforms.
Technology:
Cost tiering separates this landscape: drones and IoT sensors operate at hardware-plus-subscription economics accessible to mid-tier contractors, while VR and BIM demand enterprise-scale integration budgets and specialized implementation partners.
- Drones:Unmanned aerial platforms equipped with multispectral and LiDAR payloads compress topographic survey timelines from weeks to hours. Western Australian mining contractors deploy these for pit wall stability monitoring and stockpile volumetrics where manned aviation faces weather and regulatory constraints.
- IoT Sensors:Edge-deployed vibration, temperature, and hydraulic pressure transducers enable predictive maintenance on remote-operated earthmoving fleets. Alberta oil sands operators embed these in autonomous haul trucks to reduce unplanned downtime during extreme winter conditions when technician access is severely limited.
- VR:Immersive training simulators and client walkthrough environments reduce operator certification time and pre-construction design review cycles.
- BIM:Mature design-to-field data threads anchor quality verification and as-built documentation workflows in federally funded infrastructure projects.
BIM anchors the revenue base across established contractor relationships. Drones are gaining share fastest in new remote site deployments.
End User:
Customer type determines purchasing authority and technology sophistication: contractors control equipment procurement decisions, while engineers and architects influence design-phase platform selection that constrains downstream field implementation.
- Contractors:Primary procurement decision-makers for teleoperated fleets and autonomous haulage systems. Large infrastructure builders in the US Southwest prioritize OSHA-compliant redundant control architectures for federally funded renewable energy construction.
- Engineers:Technical specification authors who mandate RTK-GNSS accuracy thresholds and sensor fusion requirements in project tender documents.
- Architects:Design-phase influencers selecting VR visualization tools and BIM coordination platforms for client engagement and regulatory submission workflows.
- Surveyors:Specialized users of drone photogrammetry and machine-integrated grade control systems displacing traditional total station field crews.
Contractors represent the volume anchor. Surveyors are expanding most quickly as autonomous equipment dissolves boundaries between machine guidance and quality verification.
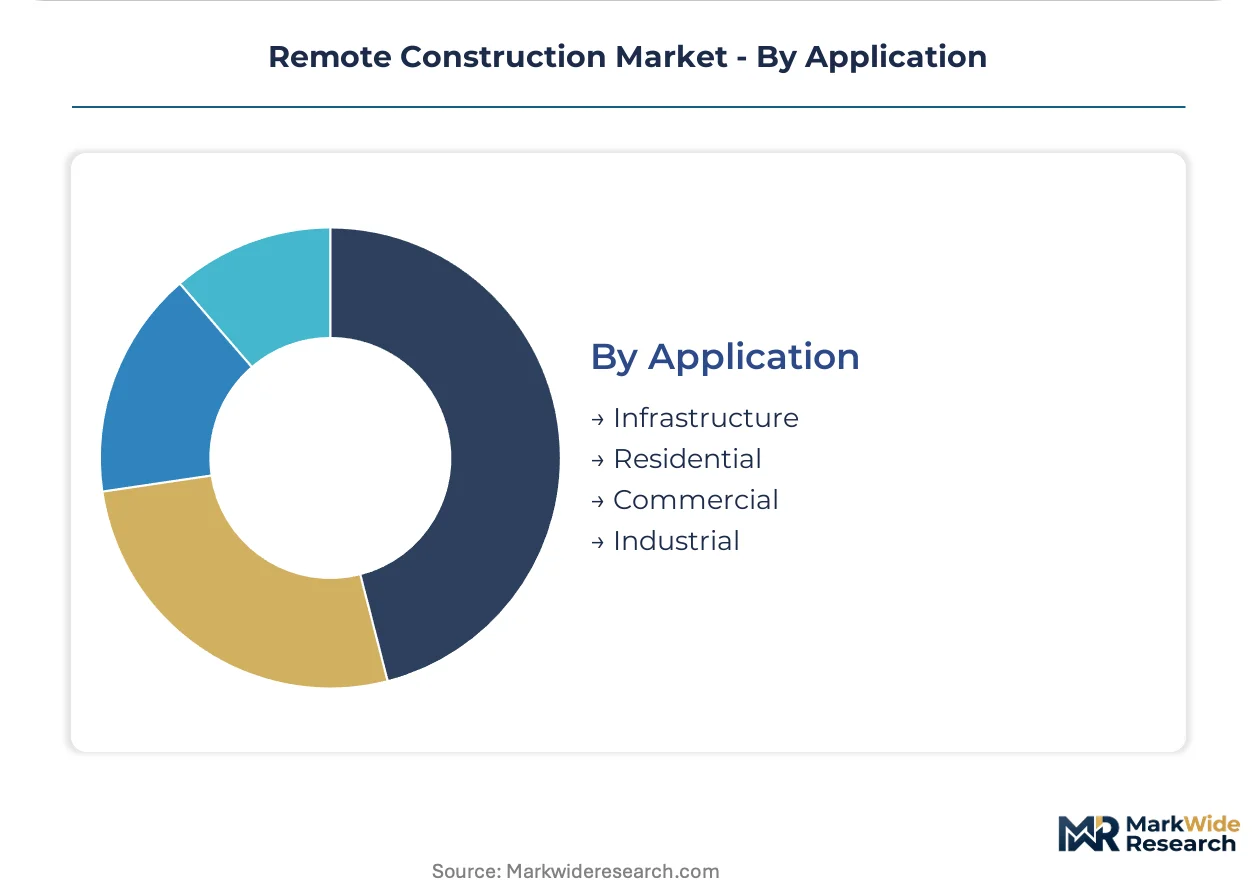
Application:
Maturity gradients separate this category: infrastructure carries established regulatory compliance requirements and federal funding access, while industrial applications face the steepest labor scarcity pressures driving autonomous adoption.
- Infrastructure:Federally funded roads, bridges, and utility corridors where US Inflation Reduction Act domestic content requirements and OSHA remote-work mandates reshape equipment procurement criteria. Contractors must document North American assembly origins for teleoperated fleets to qualify for tax credit bonuses.
- Industrial:Mining, oil sands, and energy extraction in geographically isolated zones where structural fly-in-fly-out labor shortages make autonomous haulage and remote dozing permanent operational fixtures rather than pilot programs.
- Commercial:Urban and suburban building construction where teleoperation addresses skilled operator shortages in high-cost labor markets.
- Residential:Smaller-scale developments with limited capital budgets and shorter project durations constraining autonomous equipment amortization.
Infrastructure holds the established revenue base. Industrial applications show the steepest expansion trajectory as commodity producers automate against persistent labor constraints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Remote construction technology consumption varies sharply by geography: Australia's Pilbara mining corridor prioritizes autonomous haulage systems, while US federal infrastructure projects emphasize OSHA-compliant teleoperation for renewable energy construction.
United States
OSHA remote-work safety mandates and Inflation Reduction Act domestic content requirements are reshaping procurement for federally funded geothermal and carbon capture projects. Southwestern states concentrate demand for teleoperated renewable energy construction equipment.
Australia
Structural fly-in-fly-out labor shortages in Western Australia's Pilbara iron ore corridor drive permanent adoption of autonomous haulage and remote dozing systems. The Work Health and Safety Act mandates redundant control failover and geofenced exclusion zones for autonomous equipment.
Canada
Provincial occupational health statutes in Alberta enforce strict certification for teleoperated fleets operating in oil sands developments. Northern territories face extreme winter conditions that limit technician access, accelerating predictive maintenance sensor deployment on autonomous haul trucks.
China
Dual carbon goals and domestic mining automation programs expand demand for precision positioning hardware in remote western mining zones. State-backed infrastructure investment prioritizes machine-to-machine command protocols for geographically isolated energy extraction projects.
Germany
Industrial machinery manufacturers supply RTK-GNSS correction modules and edge-computing middleware to global mining and energy contractors. Baden-Württemberg engineering clusters anchor European R&D in latency-tolerant control systems for hazardous environment operations.
Remote Construction Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in remote construction technology. Precision positioning hardware vendors and cloud-native project coordination platforms occupy distinct competitive spaces with limited direct overlap. Three archetypes dominate: integrated positioning-system providers, autonomous equipment manufacturers, and software-centric coordination platforms. Competitive moves center on strategic partnerships bridging hardware and software stacks, alongside geographic expansion into Australia's mining corridors and Canada's oil sands.
Within the integrated positioning tier, Trimble Inc. and Topcon Corporation exemplify hardware-software convergence for telematics workflows. Hexagon AB anchors European precision measurement capabilities. Among software-centric coordinators, Procore Technologies occupies a position representing cloud-native project oversight platforms, while Autodesk, Inc. exemplifies design-to-field data thread integration. Bentley Systems represents infrastructure engineering software specialization. Caterpillar Inc. and Hitachi Ltd. sit within the autonomous equipment manufacturing archetype, though this study makes no specific claims about their product portfolios or strategic actions.
| Leading Market Players |
|---|
| Trimble Inc. |
| Topcon Corporation |
| Hexagon AB |
| Autodesk, Inc. |
| Oracle Corporation |
| Procore Technologies |
| Bentley Systems |
| Caterpillar Inc. |
| Hitachi Ltd. |
| Others |
Value Chain & Pricing Dynamics
Project-based equipment-as-a-service contracting locks in supply access for Australian contract miners and Canadian energy services firms while stabilizing price visibility against commodity price cycle volatility. This structure transfers residual value risk to OEM financing arms and bundles maintenance, operator training, and sensor fusion middleware into predictable operational expenditures.
Pricing Analysis
Long-term offtake agreements dominate procurement for autonomous haulage capacity in fly-in-fly-out operations, with pricing stratifying across premium, standard, and economy tiers based on RTK-GNSS correction service accuracy levels and bundled predictive maintenance sensor arrays. Price differentiation hinges on certification grade under Australia's Work Health and Safety Act and OSHA remote-work safety mandates, plus geographic delivery cost premiums for northern Canadian territories. Cost compression in standard-tier teleoperation retrofits is intensifying because mid-tier contractors face balance sheet constraints from capital intensity exceeding 40% of baseline equipment value. Mid-tier mining operators show highest price sensitivity, while Pilbara iron ore majors prioritize premium-tier redundant control failover systems with minimal price elasticity.
Supply Chain Analysis
Strategic stockpiling of RTK-GNSS correction modules and edge-computing middleware dominates inventory strategy among Western Australian mining contractors facing extreme weather logistics windows. Component manufacturing concentrates in Germany for precision positioning hardware, the United States for cloud-native project coordination platforms, and Japan for autonomous equipment control systems. Raw material dependencies include rare earth elements for sensor arrays, high-grade steel for teleoperation-ready cabs, and semiconductor chips for machine-to-machine command protocols. Single-source vulnerability in low-orbit satellite bandwidth for latency-sensitive control links poses structural supply chain risk. Distribution runs through OEM direct sales for autonomous fleets and specialized industrial distributors for retrofit sensor packages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against substitution from modular software stacks that fragment teleoperation architectures and erode vendor lock-in advantages. The threat of rapid reconfiguration across equipment types without proprietary hardware tethering demands proactive positioning.
For Market Incumbents: Secure backward integration into captive North American sensor and actuator supply chains to satisfy US Inflation Reduction Act domestic content requirements for federally funded geothermal and carbon capture construction programs. Secure certification pre-approval under Australia's Work Health and Safety Act and Canada's provincial occupational statutes to compress procurement evaluation timelines against emerging modular software competitors. Vertical integration into edge-computing middleware development anchors margin pools beyond hardware manufacturing.
For New Entrants and Emerging Players: OSHA-compliant redundant control architecture fast-tracks market entry among US Southwest renewable energy contractors facing federal procurement mandates. White-space concentration sits in VR training simulators for remote equipment handlers, where immersive operator certification programs reduce time-to-competency and insurance premiums. Target Canadian oil sands operators through equipment-as-a-service leasing models that transfer residual value risk and bundle predictive maintenance sensor deployment.
For Investors and Strategic Acquirers: Edge-computing middleware specialists with real-time sensor fusion capabilities represent the priority acquisition archetype for autonomous collision avoidance and predictive diagnostics applications. Long-term viability over the coming decade rests on machine-to-machine command protocol standardization and latency-tolerant control system maturation. Signal to monitor: adoption velocity of factory-integrated GNSS correction modules at equipment replacement cycle points in Western Australia and Alberta.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Supply Chains | Captive North American component sourcing satisfies IRA domestic content bonus credits for federal procurement eligibility. |
| Edge-Computing Middleware Development | Real-time sensor fusion at machine level opens margin pools in predictive maintenance beyond hardware manufacturing. |
| Equipment-as-a-Service Contracting Expansion | Leasing models with bundled maintenance transfer residual value risk in commodity-price-sensitive fly-in-fly-out operations. |
| Multi-Jurisdiction Certification Pre-Approval | Harmonized compliance under OSHA, Australia's Work Health and Safety Act, and Canadian provincial statutes compresses sales cycles. |
| VR Training Simulator Platform Launch | Immersive operator certification reduces time-to-competency and insurance premiums in hazardous site conditions. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with teleoperation system engineers, mining operations directors, federal procurement officers, and OEM aftermarket service heads; and secondary validation through SEC 10-K filings, FAA drone operation registries, Australian Work Health and Safety Act compliance databases, and Canadian provincial occupational statute filings. Bottom-up equipment shipment tracking and top-down infrastructure investment flow analysis were triangulated against RTK-GNSS correction service subscription records.
Across the analysis window, the forecasting framework modeled volume and value outputs through segmentation dimensions spanning service type, technology layer, end-user purchasing authority, and application maturity gradient. CAGRs were derived from equipment replacement cycle timing, federal infrastructure appropriation schedules, and autonomous haulage adoption curves in Pilbara and oil sands corridors. Industry-specific inputs included latency-tolerant control link deployment rates and predictive maintenance sensor penetration in extreme winter conditions.
Decision-makers should treat outputs as directional under assumptions of persistent fly-in-fly-out labor scarcity and stable federal infrastructure funding authorization; material deviation in either assumption would warrant model refresh. Revision becomes warranted when low-orbit satellite bandwidth deployment for sub-100 millisecond command-response thresholds crosses commercial viability thresholds in remote site locations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Services
MENA Architectural Services Market
Construction Services
Work Order Management Market
Construction Services
Hardbanding Services Market
Construction Services
Construction TIC Market
Construction Services
North America Testing and Commissioning Market
Construction Services
Construction Materials Testing Equipment Market
Construction Services
Industrial Maintenance Products Market
Construction Services
3D Concrete Printing Services Market
Construction Services
Global Pipeline Maintenance Services Market
Construction Services
Grease Trap Service Market
Construction Services
Middle East and Africa Industrial Maintenance Services in Operational Improvement and Operational Maintenance Market
Construction Services
Die Casting Services Market
Construction Services
Industrial Maintenance Services Market
Construction Services
Construction Equipment Repair and Maintenance Services Market
Construction Services
North America Repair and Rehabilitation Market
Construction Services
Global Industrial Services Market