
 Geology and Mine Planning Solution Market | 2026-2036
Geology and Mine Planning Solution Market Size, Share, and Industry Trends Forecast 2026-2036
Geology and Mine Planning Solution Market Insights
Buyer concentration among tier-one mining houses is hardening as Rio Tinto, BHP, and Vale centralize procurement under enterprise digital transformation mandates. Bentley Systems leverages its Seequent Leapfrog geological modeling suite to anchor subsurface intelligence workflows across copper-gold belts. Hexagon Mining sustains competitive pressure through MinePlan integration with pit-to-port automation ecosystems. Maptek specializes in underground mine design through Vulcan, occupying a defensible niche in narrow-vein operations.
Geology and mine planning solutions comprise software platforms that process drillhole data, geophysical surveys, and geochemical assays to construct three-dimensional block models with grade interpolation algorithms such as kriging and inverse distance weighting. These systems optimize pit shell configurations, stope layouts, and tailings placement to maximize net present value while enforcing geotechnical stability constraints. Resource estimation software leads segment revenue by securing feasibility-stage investment decisions, while cloud computing deployment grows fastest as remote operations centers demand real-time collaboration across dispersed assets. GIS technology dominates installed base but faces margin compression from open-source alternatives.
ISO 19650 digital information management standards and Australia's Work Health and Safety Act mine design provisions shape platform requirements by mandating auditable geotechnical decision trails. The US Mine Safety and Health Administration and Canada's provincial mineral tenure regulators enforce similar documentation rigor for slope stability and ground control plans. Stakeholders must evaluate vendor cloud sovereignty commitments and API interoperability before committing to multi-decade mine lifecycle platforms.
Market Dynamics
Cloud-native deployment architectures and ISO 19650 digital asset management standards are restructuring vendor selection criteria across the mine lifecycle software stack.
Growth Catalysts
- Underground reserve depletion:Australian iron ore and copper producers are driving demand for subsurface intelligence platforms as near-surface deposits exhaust. This forces investment in 3D block modeling and stope optimization tools.
- ISO 19650 compliance mandates:Australia's Work Health and Safety Act mine design provisions require auditable geotechnical decision trails. Procurement specifications now embed these standards as non-negotiable.
- Remote operations center expansion:Cloud computing infrastructure enables real-time collaboration across dispersed mining assets. Underground operators centralize planning functions in Perth and Brisbane hubs.
Market Restraints
- Specialized geoscience talent scarcity:Resource estimation and geostatistics expertise concentrates in Perth, Santiago, and Johannesburg. Hiring cycles extend 8-14 months for senior roles.
- Legacy data migration friction:Decades of drillhole databases in proprietary formats resist automated conversion. Manual cleansing consumes 30-40% of implementation budgets.
- High-performance computing costs:Complex kriging simulations and pit optimization routines demand GPU clusters. Smaller mid-tier miners defer cloud migration due to compute expenditure uncertainty.
Strategic Opportunities
- Artificial intelligence convergence:Machine learning grade interpolation is converging with traditional geostatistical methods. This hybrid approach reduces resource model uncertainty in structurally complex orebodies.
- Canada's provincial mineral tenure digitization:British Columbia and Ontario regulators are mandating electronic submission of technical reports. Vendors can anchor SaaS offerings to these compliance workflows.
- Pit-to-port integration demand:Copper-gold producers in Chile and Peru seek unified platforms spanning geology, mine design, and logistics scheduling. This creates attach opportunities for planning software vendors.
Industry Challenges
- Interoperability protocol fragmentation:Mine planning platforms, GIS systems, and fleet management tools use incompatible data exchange formats. API standardization remains incomplete across vendor ecosystems.
- Cybersecurity certification timelines:Critical infrastructure designations in Australia and Canada impose mandatory security assessments. Vendor product roadmaps stall awaiting government accreditation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Geology and Mine Planning Solution Market |
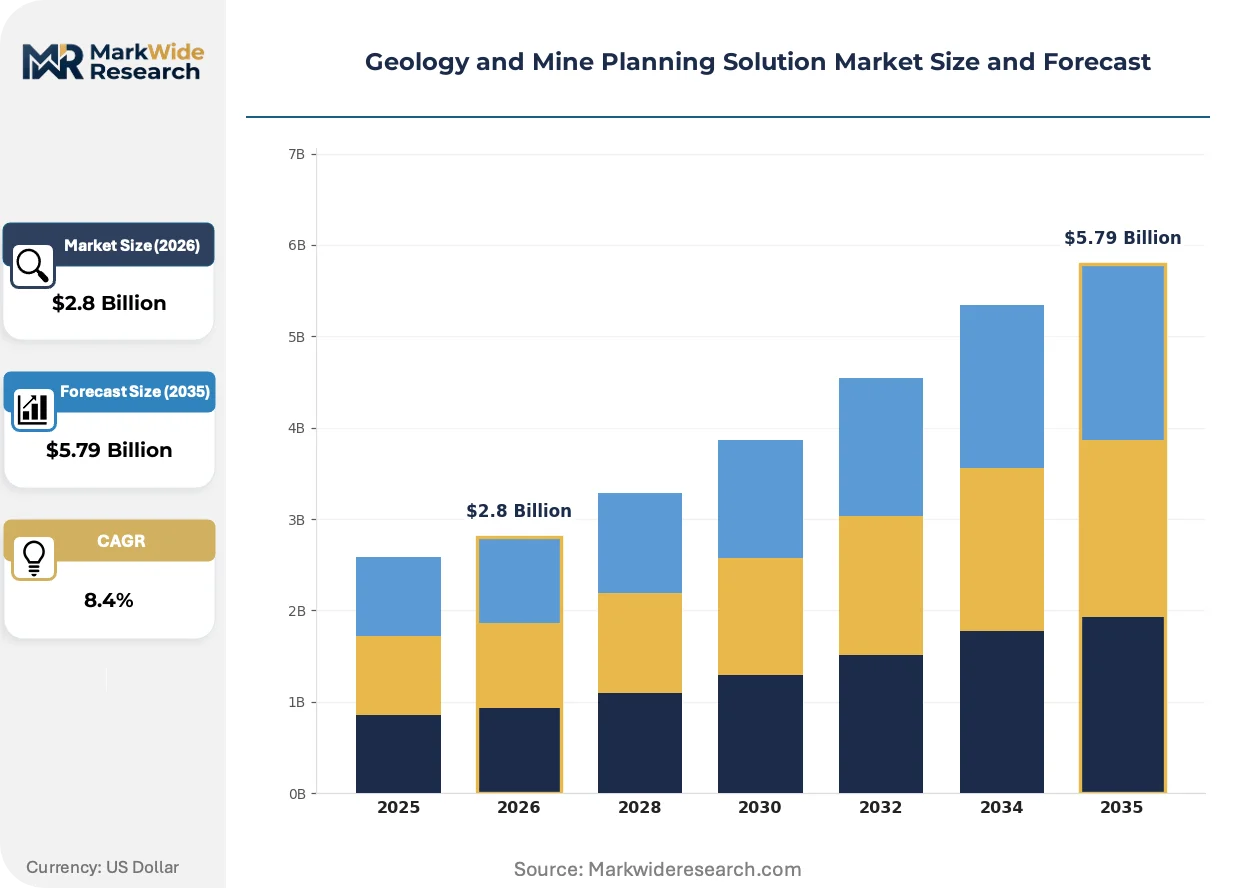
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.79 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 3D Modeling, Geological Surveying, Mapping Software, Resource Estimation Technology: GIS, Data Analysis, Remote Sensing, Cloud Computing End User: Mining Companies, Exploration Firms, Geologists, Consultants Application: Site Assessment, Resource Management, Environmental Impact, Mining Operations |
| Companies Covered | Bentley Systems (Seequent Leapfrog), Hexagon Mining (MinePlan), Maptek (Vulcan), RPMGlobal (Xpac), Minemax, Dassault Systèmes (GEOVIA), Sandvik (Deswik), Micromine, Datamine (MineScape), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Geology and Mine Planning Solution Market Trends and Innovations
Digital twin technology and real-time sensor fusion are compressing the feedback loop between geological interpretation and production scheduling decisions.
Machine learning-based grade interpolation is converging with traditional kriging workflows. Tier-one copper-gold producers in Chile and Western Australia are piloting neural network models for structurally controlled deposits. This convergence is compressing resource model update cycles from quarterly to weekly frequencies.
Australia's adoption of ISO 19650-2 for digital information management is mandating structured data handovers between exploration, feasibility, and operations phases. Engineering contractors must now deliver machine-readable geotechnical models. Underground narrow-vein operators face the steepest compliance adaptation costs.
Enterprise software procurement is consolidating under single-vendor pit-to-port mandates. Rio Tinto and BHP are deprecating point solutions in favor of integrated planning suites. Western Australian iron ore operations exhibit the most advanced centralized procurement models.
Geology and Mine Planning Solution Market Segmentation
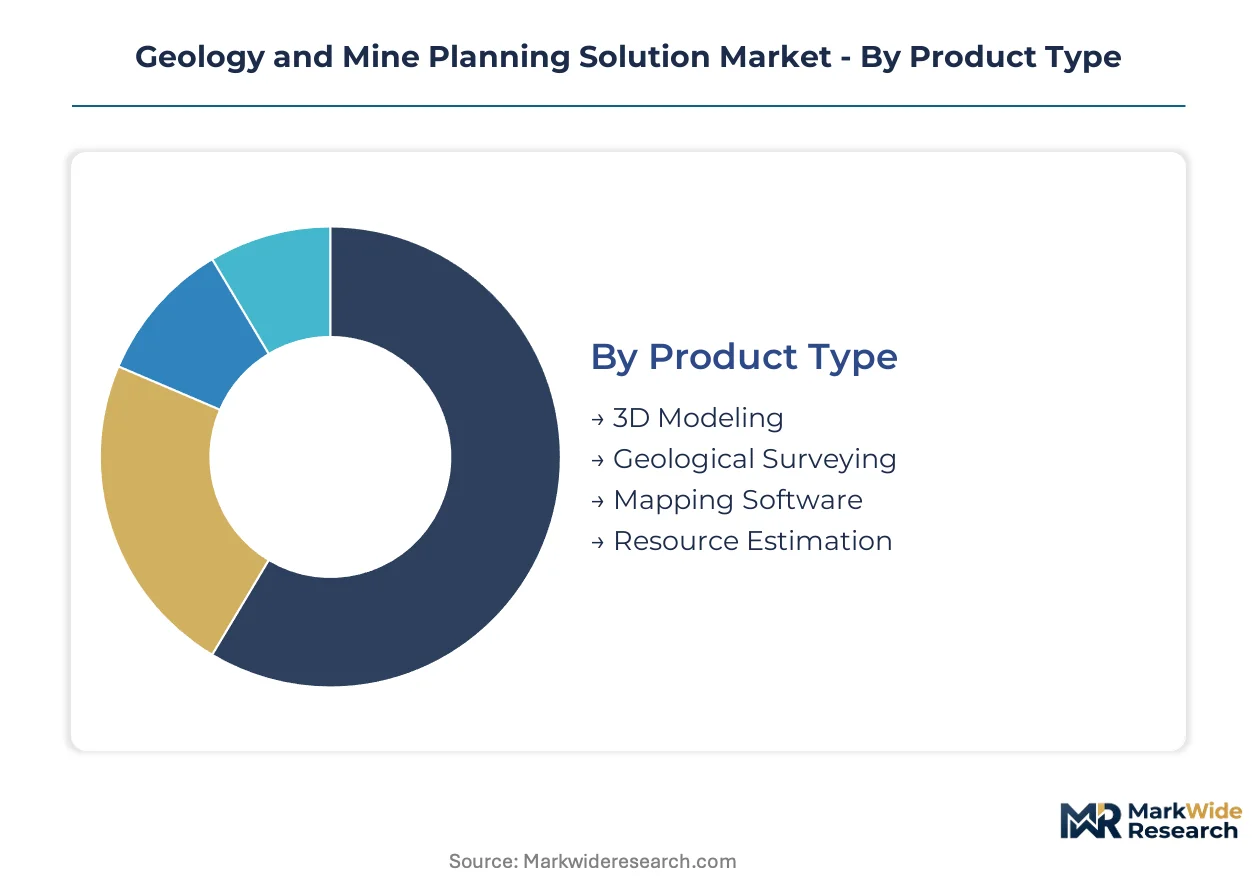
Segmentation in geology and mine planning solutions reveals how capital deployment varies sharply across technology tiers. Procurement patterns diverge between tier-one miners pursuing pit-to-port integration and mid-tier operators prioritizing discrete point solutions.
Product Type:
Capital intensity peaks in segments requiring specialized computational infrastructure and proprietary algorithm development.
- 3D Modeling:Platforms construct subsurface block models using kriging and inverse distance weighting algorithms. Australian iron ore producers in the Pilbara region drive demand as near-surface deposits deplete and underground geometries grow complex.
- Resource Estimation:Software secures feasibility-stage investment decisions through auditable grade interpolation and geostatistical validation. Procurement concentrates among copper-gold producers facing structurally controlled orebodies where model uncertainty directly impacts project finance.
- Geological Surveying:Field data acquisition systems integrate drillhole databases with geophysical surveys.
- Mapping Software:Surface and subsurface visualization tools support pit shell configuration and stope layout optimization.
Resource Estimation absorbs the bulk of installed capacity; 3D Modeling is expanding most quickly.
Technology:
Deployment architecture determines operational scalability and cross-asset collaboration potential.
- Cloud Computing:Native architectures enable real-time collaboration across remote operations centers in Perth and Brisbane. ISO 19650 compliance mandates accelerate procurement as Australian operators centralize planning functions.
- GIS:Spatial data management dominates legacy installed base across open-pit operations. Margin compression intensifies from open-source alternatives and interoperability friction with modern planning platforms.
- Data Analysis:Machine learning convergence with traditional geostatistics reduces model update cycles.
- Remote Sensing:Satellite and aerial survey integration supports early-stage exploration targeting.
GIS retains the largest legacy footprint; Cloud Computing shows the steepest expansion trajectory.
End User:
Buyer sophistication and procurement centralization create distinct service requirements across customer tiers.
- Mining Companies:Tier-one houses mandate enterprise-wide platform standardization under digital transformation programs. Rio Tinto and BHP deprecate point solutions in favor of integrated suites spanning geology through logistics.
- Exploration Firms:Junior miners prioritize capital-efficient solutions with rapid implementation timelines. Budget constraints limit adoption of GPU-intensive simulation capabilities.
- Geologists:Individual practitioners require specialized resource estimation and geostatistics expertise.
- Consultants:Engineering contractors deliver machine-readable geotechnical models under Australia's ISO 19650-2 structured data handover requirements.
Mining Companies command the largest procurement volumes; Exploration Firms are gaining share fastest.
Application:
Regulatory compliance intensity and technical risk exposure shape segment-specific platform requirements.
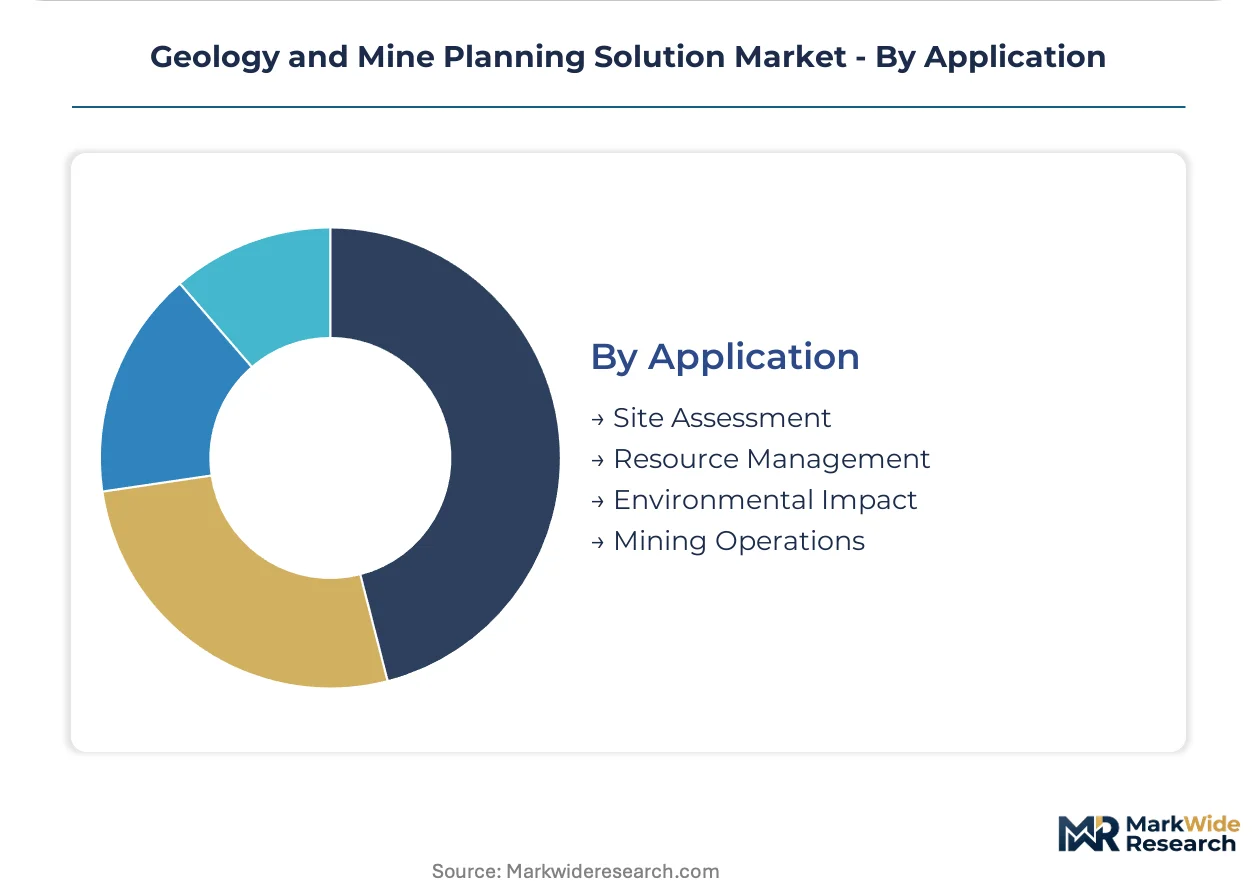
- Mining Operations:Pit-to-port integration demands unified platforms spanning geology, mine design, and logistics scheduling. Chilean and Peruvian copper-gold producers anchor this segment's growth.
- Environmental Impact:Tailings placement optimization and geotechnical stability documentation satisfy Australia's Work Health and Safety Act mine design provisions.
- Site Assessment:Pre-feasibility technical studies require rapid block model generation.
- Resource Management:Long-term reserve reporting and mineral tenure compliance support investor and regulatory disclosure.
Mining Operations represents the dominant installed base; Environmental Impact is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for geology and mine planning solutions concentrates in mineral-rich jurisdictions where reserve depletion and regulatory digitization intersect. Australian iron ore and copper producers anchor procurement volumes as near-surface deposits exhaust. Chilean and Peruvian copper-gold belts drive adoption of subsurface intelligence platforms.
Australia
Western Australian Pilbara operations and Queensland copper-gold belts drive demand for 3D block modeling and stope optimization tools. The country's Work Health and Safety Act mine design provisions mandate auditable geotechnical decision trails under ISO 19650-2 standards. Perth and Brisbane remote operations centers centralize planning functions for dispersed assets across the continent.
Chile
Structurally controlled copper-gold deposits in the Atacama and Central regions require advanced grade interpolation and resource estimation capabilities. The national mining regulator enforces slope stability documentation rigor for open-pit and underground operations alike. Antofagasta and Santiago host concentrated vendor implementation teams serving northern mining districts.
Canada
British Columbia porphyry copper and Ontario gold camps demand unified pit-to-port planning platforms. Provincial mineral tenure regulators in both jurisdictions mandate electronic submission of technical reports and machine-readable geotechnical models. Vancouver and Toronto engineering clusters anchor SaaS vendor support infrastructure for western and eastern mining belts respectively.
Peru
Andean copper-gold producers seek integrated logistics scheduling attached to geological modeling workflows. The Ministry of Energy and Mines enforces progressive technical report digitization for large-scale operations. Lima serves as the procurement coordination hub for southern Andean mining districts including Arequipa and Cusco regions.
United States
Nevada gold-silver districts and Arizona copper porphyries require cloud-native deployment for dispersed asset portfolios. The Mine Safety and Health Administration enforces ground control plan documentation standards with audit trail requirements. Denver and Reno engineering centers concentrate vendor technical support for western mineral belts.
Geology and Mine Planning Solution Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue cloud-native architectures and AI-augmented geostatistics. The vendor ecosystem structures around three tiers: integrated platform providers spanning pit-to-port workflows, specialized subsurface modeling specialists, and point-solution vendors serving mid-tier miners. Competitive positioning hardens through strategic archetypes including enterprise suite consolidators, narrow-vein underground specialists, and compliance-focused SaaS providers. Dominant competitive moves include M&A-driven portfolio expansion and API interoperability partnerships to reduce data migration friction.
Within the integrated platform tier, Bentley Systems and Hexagon Mining exemplify enterprise consolidation strategies. Bentley's Seequent Leapfrog geological modeling suite anchors subsurface intelligence workflows, while Hexagon sustains competitive pressure through MinePlan integration with automation ecosystems. Maptek occupies a defensible position among narrow-vein underground specialists through Vulcan mine design capabilities. These three vendors represent distinct archetypes: the geological modeling incumbent, the automation-integrated platform, and the underground niche specialist.
| Leading Market Players |
|---|
| Bentley Systems (Seequent Leapfrog) |
| Hexagon Mining (MinePlan) |
| Maptek (Vulcan) |
| RPMGlobal (Xpac) |
| Minemax |
| Dassault Systèmes (GEOVIA) |
| Sandvik (Deswik) |
| Micromine |
| Datamine (MineScape) |
| Others |
Pricing and Supply Chain Analysis
ISO 19650 digital asset management compliance gates qualified supply access and anchors premium-tier pricing for geology and mine planning platforms. Australian Work Health and Safety Act mandates and Chilean slope stability documentation requirements restrict vendor participation to certified providers, compressing margins for uncertified entrants while sustaining pricing power for accredited incumbents.
Pricing Analysis
Volume concentrates in standardized SaaS tiers while margins accrue to customized enterprise implementations. Subscription-based pricing stratifies across premium, standard, and economy tiers, with differentiation driven by ISO 19650 certification level and GPU-intensive simulation capabilities. Cost compression in the mid-tier intensifies as open-source GIS alternatives erode legacy installed-base pricing. Exploration firms exhibit acute price sensitivity due to capital constraints, whereas tier-one mining houses prioritize compliance assurance over unit cost.
Supply Chain Analysis
ISO 19650-2 qualification requirements filter vendor ecosystems before procurement engagement, concentrating certified development capacity in Australia, Canada, and the United States. Software engineering draws from specialized geoscience talent pools in Perth, Santiago, and Johannesburg, with cloud infrastructure sourcing from hyperscaler regions in Sydney, Toronto, and São Paulo. Single-source vulnerability runs through proprietary drillhole database formats that resist automated migration. Distribution runs through direct enterprise sales teams serving tier-one miners and channel partners addressing mid-tier operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geostatistics expertise scarcity in Perth and Santiago props pricing for qualified vendors, creating a supply-constrained market structure that favors incumbents with established talent pipelines.
For Market Incumbents: Cement platform stickiness through API interoperability partnerships that reduce legacy data migration friction for tier-one mining houses. Deepen vertical integration into cloud infrastructure provisioning to capture GPU-compute expenditure flows from mid-tier miners deferring capital commitments. Cloud-native entrants threaten margin compression in the standard tier; defend through certification investment in emerging regulatory jurisdictions like British Columbia and Ontario. For New Entrants and Emerging Players: Capture white-space in narrow-vein underground operations where Maptek's Vulcan dominance leaves compliance-adaptation gaps for smaller operators. Target Canada's provincial mineral tenure digitization mandates as the most penetrable regulatory entry point, anchoring SaaS offerings to electronic technical report submission workflows. Pursue channel partnerships with Perth-based engineering contractors serving ISO 19650-2 structured data handover requirements. For Investors and Strategic Acquirers: Tier-one mining house procurement centralization under Rio Tinto and BHP enterprise mandates is the leading indicator that platform consolidation will accelerate. Long-term viability centers on vendors spanning pit-to-port workflows with proven automation ecosystem integration. Watch for inflection when Chilean or Peruvian regulators mandate machine-readable geotechnical model submission, signaling SaaS attach opportunity expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | MinePlan integration with Hexagon's pit-to-port automation ecosystems secures tier-one procurement mandates. |
| Acquisition of Specialist Firm | Leapfrog geological modeling capabilities anchor Bentley Systems' subsurface intelligence workflow dominance. |
| Geographic Expansion | Vulcan mine design specialization in narrow-vein operations defends Maptek's defensible underground niche. |
| Strategic Partnership | API interoperability alliances reduce legacy data migration friction consuming implementation budgets. |
| Product Launch | Cloud-native architectures enable real-time collaboration across Perth and Brisbane remote operations centers. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with mine planning officers, geotechnical engineering leads, procurement directors at tier-one mining houses, and software integration specialists combined with secondary validation from Australia's Work Health and Safety Act compliance databases, Chilean mining regulator slope stability documentation, and Canadian provincial mineral tenure electronic submission records. Bottom-up vendor revenue triangulation against top-down mining capital expenditure allocations calibrated market sizing.
Data-stream reconciliation across deployment model, end-user tier, and application intensity dimensions shaped the analytical framework throughout the projection horizon. CAGRs derived from segment-level growth rate convergence with mining investment cycle patterns and cloud migration adoption curves. GPU-intensive simulation demand and ISO 19650 compliance mandate penetration served as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to geoscience talent availability in Perth and Santiago, hyperscaler pricing volatility, and regulatory digitization timeline shifts. Forecasts reflect documented assumptions on mining capital expenditure trajectories and cloud infrastructure cost curves. A model refresh is warranted upon material change in Australian or Canadian compliance mandate enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mining Equipment
Global Dozers Market
Mining Equipment
Asia Pacific Mining Equipment Market
Mining Equipment
Auger Drilling Market
Mining Equipment
Mine Ventilation System Market
Mining Equipment
Kazakhstan Mining Market
Mining Equipment
Rotary Drilling Rig Market
Mining Equipment
Hydraulic Drilling Rig Market
Mining Equipment
Surface Mining Market
Mining Equipment
Mining Remanufacturing Components Market
Mining Equipment
Commonwealth of Independent States (CIS) Underground Mining Equipment Market
Mining Equipment
Mine Scaler Market
Mining Equipment
Stone Mining and Quarrying Market
Mining Equipment
Underground Mining Automation Market
Mining Equipment
Smart Mining Technologies Market
Mining Equipment
Mining Drill Bits Market
Mining Equipment
Mining Locomotive Market