
 Facade Cleaning and Maintenance Service Market | 2026-2036
Facade Cleaning and Maintenance Service Market Size, Share, and Industry Trends Forecast 2026-2036
Facade Cleaning and Maintenance Service Market Insights
Modular service bundling is broadening buyer choice across the facade maintenance sector. ISS Facility Services leverages its integrated facility platform to combine cleaning with envelope diagnostics. ABM Industries Incorporated anchors its position through specialized rope-access teams serving dense urban corridors. CBRE Group, Inc. competes by embedding facade upkeep within broader property management contracts.
Facade cleaning and maintenance service encompasses the systematic removal of contaminants, restoration of weatherproofing performance, and preservation of exterior cladding materials on built structures. Technicians apply controlled-pressure water systems, pH-neutral chemical formulations, and abrasive-free restoration compounds to glass, stone, metal, and composite surfaces while preserving structural integrity and thermal envelope function. Chemical cleaning and restorative cleaning command premium positioning due to substrate-specific expertise and regulatory compliance requirements. Automated systems and rope access methods are gaining share as labor costs rise and building geometries grow more complex. Manual cleaning with telescopic poles retains dominance in low-rise commercial and residential segments where capital investment in automation proves uneconomical.
OSHA governs rope-access worker certification and fall-protection standards in the United States, directly shaping service delivery costs and insurance structures. The EU Green Deal and national building codes across France, Germany, and Italy mandate periodic envelope inspection and maintenance as conditions for energy-performance certification, creating recurring demand streams. Stakeholders must monitor regulatory divergence between jurisdictions where chemical cleaning agent approvals fragment and those where automated system subsidies consolidate procurement preferences.
Market Dynamics
Building envelope energy-performance mandates across Germany, France, and Italy are forcing property managers to treat facade maintenance as a compliance function rather than discretionary upkeep. This regulatory compression is restructuring procurement cycles and bundling inspection, cleaning, and restoration into single-contract obligations.
Growth Catalysts
- EU Green Deal building renovation requirements:Heritage structure owners across Italy and France must now complete restorative cleaning to qualify for energy-efficiency certification subsidies.
- High-rise commercial clustering:Dense urban corridors in New York and London generate concentrated demand for rope-access teams capable of servicing complex geometries.
- Municipal envelope mandates:German cities now require documented facade maintenance as a condition for building operating permits, creating recurring revenue streams.
Market Restraints
- Skilled rope-access labor scarcity:OSHA certification requirements and insurance liability structures limit the pool of qualified technicians in the United States.
- Chemical formulation fragmentation:pH-neutral cleaning agent approvals diverge between EU member states under REACH implementation, complicating cross-border service standardization.
- Automation capex barriers:Building managers of structures under 12 stories cannot justify robotic system investments against manual pole-access economics.
Strategic Opportunities
- Predictive inspection convergence:Drone-based envelope diagnostics combined with AI damage classification is unifying assessment and cleaning workflows for commercial portfolios.
- Retrofit-driven restorative demand:Thermal bridge remediation projects in northern European markets require substrate-specific cleaning before insulation installation.
- Subscription maintenance models:Property management platforms are embedding facade upkeep into multi-year facility contracts, locking out spot-market competitors.
Industry Challenges
- Fall-protection compliance complexity:OSHA rope-access recertification timelines compress workforce availability during seasonal demand peaks.
- Substrate expertise fragmentation:Historic stone restoration requires craft skills distinct from glass-and-metal high-rise maintenance, fragmenting talent pools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Facade Cleaning and Maintenance Service Market |
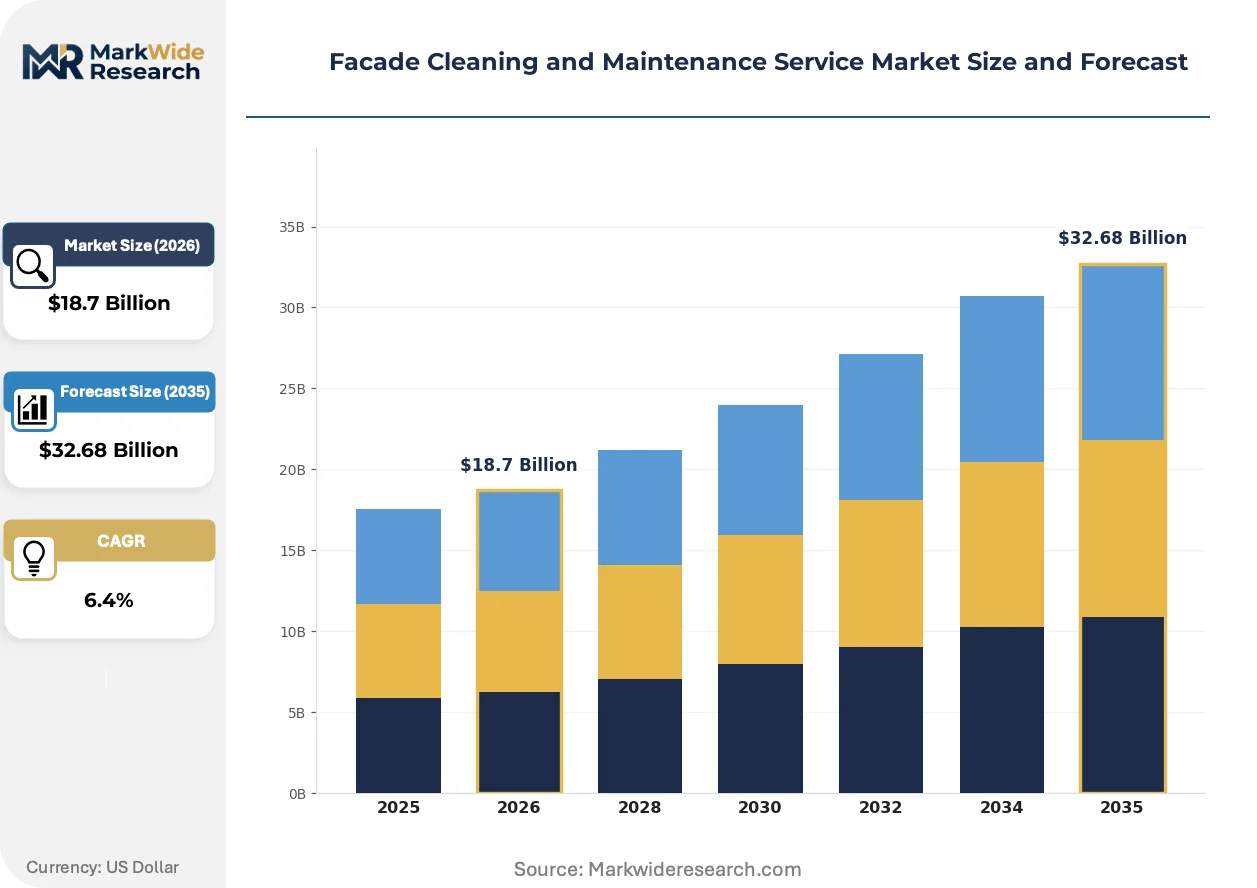
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Pressure Washing, Chemical Cleaning, Window Washing, Restorative Cleaning Building Type: Commercial Buildings, Residential Complexes, Industrial Facilities, Historical Structures Cleaning Method: Manual Cleaning, Automated Systems, Rope Access, Telescopic Poles Maintenance Frequency: Daily, Weekly, Monthly, Seasonal |
| Companies Covered | ISS Facility Services, ABM Industries Incorporated, CBRE Group, Inc., Mitie Group PLC, Compass Group PLC, Cushman & Wakefield, Sodexo, GDI Integrated Facility Services, Jones Lang LaSalle (JLL), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Facade Cleaning and Maintenance Service Market Trends and Innovations
Controlled-pressure water systems and abrasive-free compounds are displacing legacy chemical-heavy methods as environmental liability tightens. The sector is witnessing convergence between diagnostic hardware and cleaning execution, compressing the traditional inspect-then-bid cycle into continuous monitoring models.
Drone-mounted LiDAR and photogrammetry is unifying envelope assessment with maintenance scheduling. Commercial property managers in London and Singapore are adopting these platforms to pre-qualify cleaning scope before contractor engagement. This technology compression is reducing bid-cycle friction and enabling outcome-based pricing structures.
REACH chemical authorization timelines are extending formulation approval periods across EU member states. Cleaning service providers must now maintain jurisdiction-specific compound inventories, raising working capital requirements. German and French operators are responding by consolidating formulation R&D in-house rather than relying on third-party chemical suppliers.
Buyer concentration among institutional real estate investment trusts is compressing vendor selection cycles. These entities now mandate multi-service bundled contracts covering HVAC, envelope, and grounds maintenance. New York and London property managers are the most advanced in this consolidation, with mid-tier European cities following the procurement template.
Facade Cleaning and Maintenance Service Market Segmentation
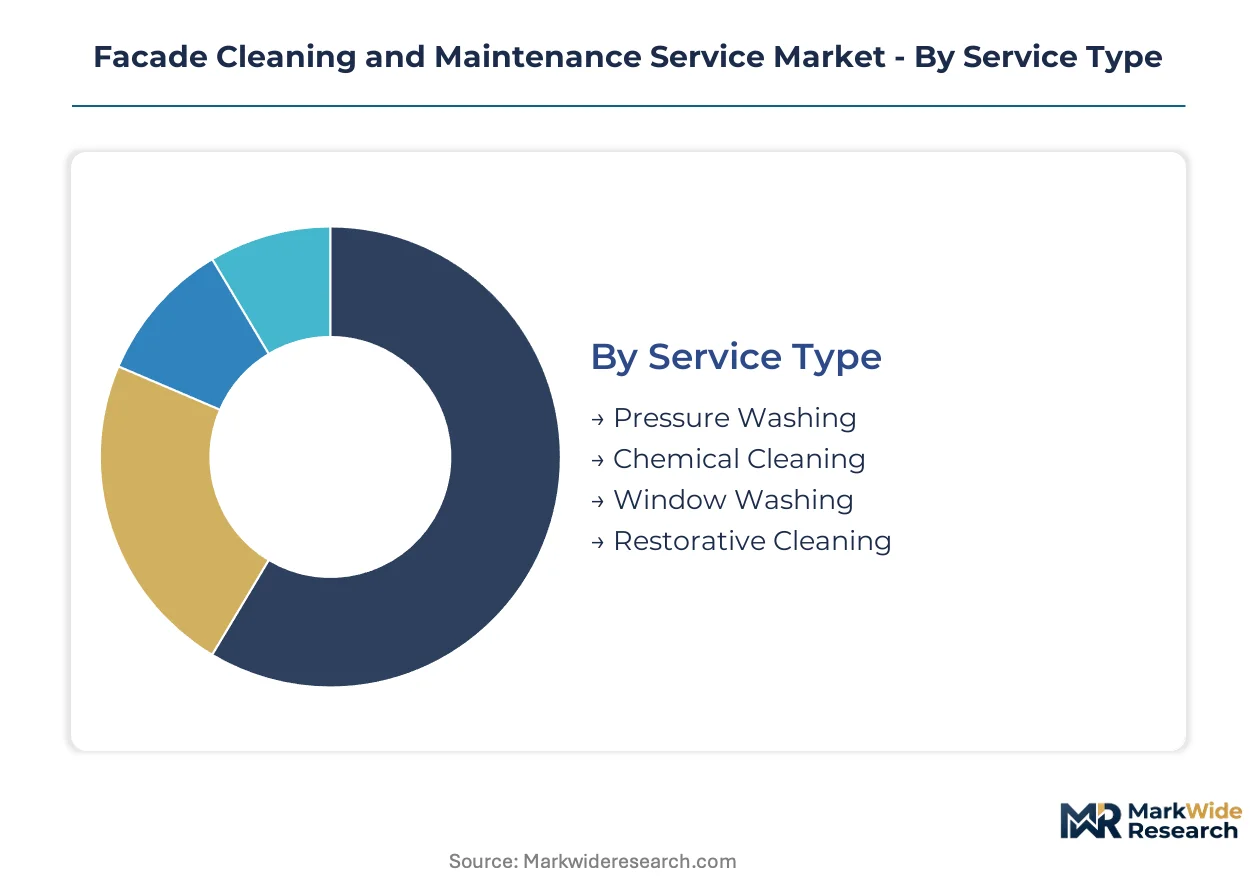
Facade cleaning and maintenance service procurement varies sharply by building envelope characteristics and regulatory exposure. Buyers select service configurations based on substrate sensitivity, access complexity, and compliance-driven maintenance cycles rather than price alone.
Service Type:
Upgrade cycles for facade maintenance contracts now bundle diagnostic assessment with cleaning execution, compressing traditional bid timelines. Property managers increasingly specify service tiers based on envelope material sensitivity and energy-performance certification requirements.
- Chemical Cleaning:pH-neutral formulations target sensitive substrates including heritage stone and anodized aluminum. REACH authorization timelines in Germany and France force operators to maintain jurisdiction-specific compound inventories, raising working capital barriers for cross-border providers.
- Restorative Cleaning:Abrasive-free compounds remove deep contaminants while preserving weatherproofing integrity. EU Green Deal renovation mandates across Italian and French heritage structures concentrate demand here, with subsidies contingent on documented envelope restoration.
- Pressure Washing:Controlled-pressure water systems serve durable concrete and metal cladding where chemical residue poses liability risks.
- Window Washing:Glass-specific protocols dominate high-rise commercial portfolios in dense urban corridors.
Volume placements concentrate in Chemical Cleaning; the faster expansion belongs to Restorative Cleaning.
Building Type:
Cost-tier differentiation separates premium heritage restoration from standardized commercial maintenance contracts. Procurement sophistication varies directly with asset-value concentration and regulatory scrutiny intensity.
- Commercial Buildings:High-rise office towers in New York and London generate concentrated demand for rope-access teams capable of complex geometry navigation. Institutional real estate investment trusts now mandate multi-year bundled contracts covering HVAC, envelope, and grounds maintenance, locking out spot-market competitors.
- Historical Structures:Substrate-specific craft requirements fragment talent pools away from glass-and-metal standardization. EU Green Deal certification subsidies in Italy and France require documented restorative cleaning as a condition for energy-efficiency funding approval.
- Residential Complexes:Low-rise economics favor telescopic pole access over capital-intensive automation.
- Industrial Facilities:Contaminant-heavy environments drive pressure-washing specifications with shortened maintenance intervals.
Commercial Buildings capture the largest contract values; Historical Structures are climbing the fastest as regulatory compliance restructures procurement.
Cleaning Method:
Labor cost trajectories and building geometry complexity determine automation adoption thresholds. Methods segment by capital intensity, certification requirements, and height-access economics.
- Rope Access:OSHA-certified technicians navigate complex geometries unreachable by mechanical platforms. Insurance liability structures and recertification timelines compress workforce availability during seasonal demand peaks in the United States.
- Automated Systems:Robotic platforms gain share above 12-story thresholds where manual pole economics fail. Drone-mounted LiDAR integration enables pre-qualification of cleaning scope, reducing bid-cycle friction for London and Singapore property managers.
- Manual Cleaning:Telescopic pole methods retain dominance where capital investment in automation proves uneconomical.
- Telescopic Poles:Extendable-reach systems serve low-rise commercial and residential segments with minimal equipment overhead.
Rope Access commands premium pricing; Automated Systems are gaining share fastest as labor scarcity intensifies.
Maintenance Frequency:
Regulatory compliance mandates in Germany now require documented facade maintenance as a condition for building operating permits, converting discretionary upkeep into recurring revenue streams.
- Seasonal:Climate-driven cycles align with pre-winter envelope integrity verification and post-pollution-season restoration. German municipal energy-efficiency mandates concentrate demand here, with documented maintenance required for permit renewal.
- Monthly:High-visibility commercial assets in dense urban corridors maintain brand-standard presentation through frequent service intervals.
- Weekly:Hospitality and retail facades in high-traffic districts require near-continuous presentation management.
- Daily:Limited to flagship properties and critical infrastructure with extreme visibility exposure.
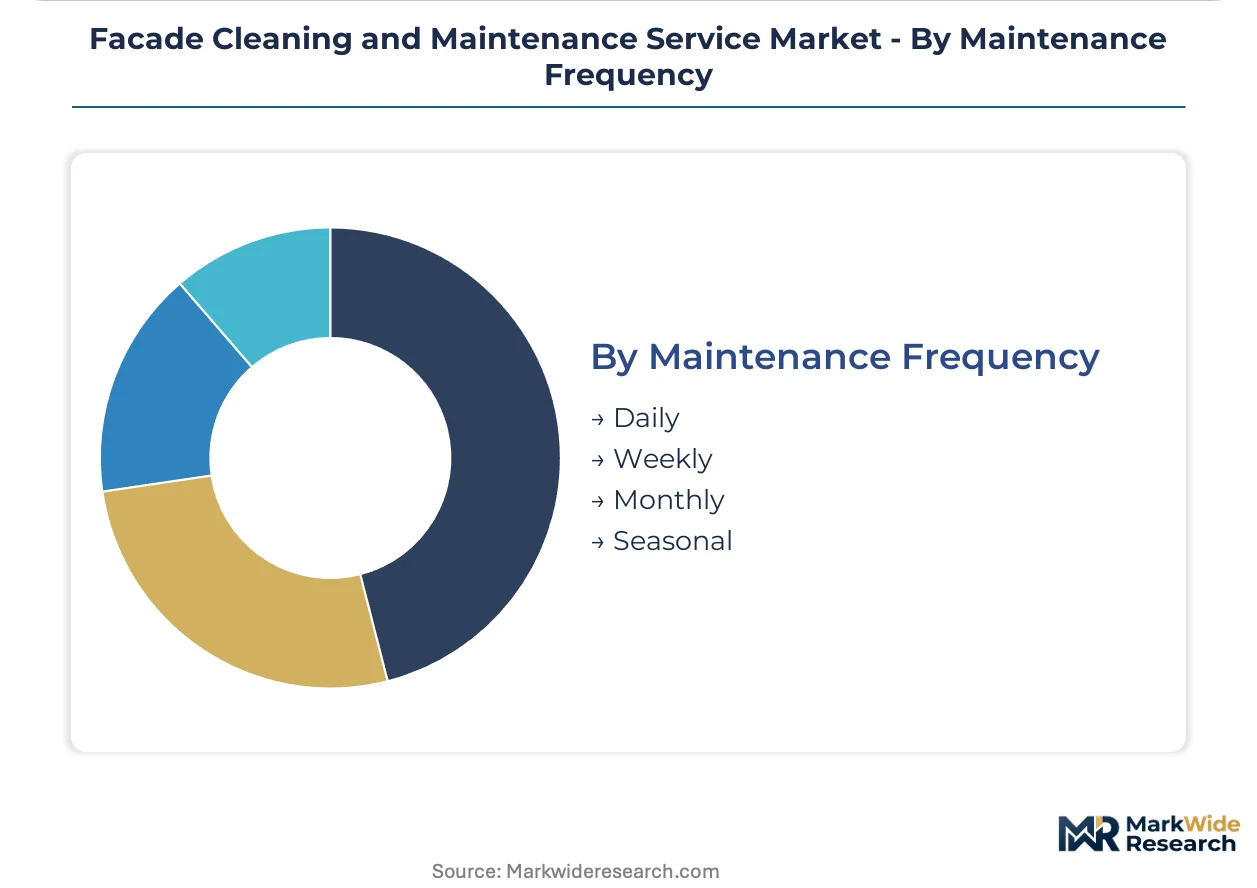
Seasonal placements dominate contract volumes; Monthly intervals show the steepest expansion trajectory as compliance documentation requirements tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free economic zones in Dubai and Singapore concentrate high-rise development, funneling facade maintenance demand into dense commercial corridors where rope-access specialization commands premium positioning.
United States
OSHA-certified rope-access teams serve Manhattan and Chicago's vertical clusters where complex geometries defy mechanical platform deployment. The agency's fall-protection recertification timelines compress workforce availability during seasonal peaks. New York property managers now bundle predictive inspection with cleaning execution.
Germany
Municipal energy-efficiency mandates in Berlin and Munich require documented facade maintenance as a condition for building operating permits. The EU Green Deal's building renovation requirements accelerate restorative cleaning across heritage structures. Frankfurt's financial district concentrates demand for automated system integration.
United Kingdom
London's institutional real estate investment trusts mandate multi-year bundled contracts covering HVAC, envelope, and grounds maintenance. Historic England's conservation guidelines impose substrate-specific craft requirements on Westminster and City of London landmarks. Crossrail development zones generate supplemental new-build maintenance contracts.
France
ANSM chemical authorization timelines extend pH-neutral cleaning agent approvals, forcing operators to maintain jurisdiction-specific compound inventories. Parisian Haussmann facades require abrasive-free restoration to qualify for energy-efficiency certification subsidies. Lyon and Marseille commercial corridors follow the procurement template.
Singapore
Marina Bay and Raffles Place high-rises adopt drone-mounted LiDAR for pre-qualification of cleaning scope, reducing bid-cycle friction. The Building and Construction Authority's envelope performance standards mandate periodic inspection. Southeast Asian headquarters concentration sustains year-round service demand.
Facade Cleaning and Maintenance Service Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered service configurations. Facility management platforms leverage integrated infrastructure to bundle envelope diagnostics with cleaning execution, while rope-access contractors anchor position through height-access certification scarcity. Three archetypes dominate: integrated facility conglomerates, specialized access technicians, and technology-augmented inspection platforms. Consolidation proceeds through strategic partnerships and in-house predictive capability development.
Among facility management conglomerates, ISS Facility Services and ABM Industries Incorporated exemplify the integrated platform model, embedding facade upkeep within broader property service contracts. CBRE Group, Inc. occupies a position representing the real-estate-services anchor archetype, competing through contract bundling rather than technical specialization. These three entities collectively illustrate how scale-driven procurement consolidation favors diversified service portfolios over standalone cleaning operations.
| Leading Market Players |
|---|
| ISS Facility Services |
| ABM Industries Incorporated |
| CBRE Group, Inc. |
| Mitie Group PLC |
| Compass Group PLC |
| Cushman & Wakefield |
| Sodexo |
| GDI Integrated Facility Services |
| Jones Lang LaSalle (JLL) |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal building renovation mandates gate both qualified supply and premium-tier pricing access, as heritage structure owners in Italy and France must secure REACH-compliant chemical formulations and OSHA-certified rope-access teams to qualify for energy-efficiency subsidies. This regulatory filtering concentrates pricing power among operators with jurisdiction-specific compound inventories and fall-protection certifications.
Pricing Analysis
Margin tightening in chemical cleaning reflects REACH authorization timeline extensions across Germany and France, forcing operators to maintain multiple jurisdiction-specific compound inventories. Three-tier pricing structure across premium, standard, and economy levels separates restorative heritage stone work from glass-and-metal high-rise maintenance and basic pressure-washing contracts. Price differentiation hinges on certification grade and substrate expertise, with EU Green Deal compliance documentation commanding substantial premiums. Property managers of structures under twelve stories exhibit highest price sensitivity, while institutional real estate investment trusts prioritize outcome-based bundled contracts over unit pricing.
Supply Chain Analysis
Freight logistics for pH-neutral chemical formulations concentrate supply chain attention on Germany, France, and Italy as REACH implementation fragments cross-border standardization. Raw material dependencies center on specialty surfactant suppliers, biodegradable solvent manufacturers, and abrasive-free restoration compound producers. Single-source vulnerability persists where German operators have consolidated formulation R&D in-house rather than relying on third-party chemical suppliers. Distribution runs through facility management platforms that bundle envelope diagnostics with cleaning execution, compressing traditional procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into predictive inspection capabilities has become the defining competitive race, as drone-mounted LiDAR and AI damage classification compress the traditional inspect-then-bid cycle into continuous monitoring models that lock out spot-market competitors.
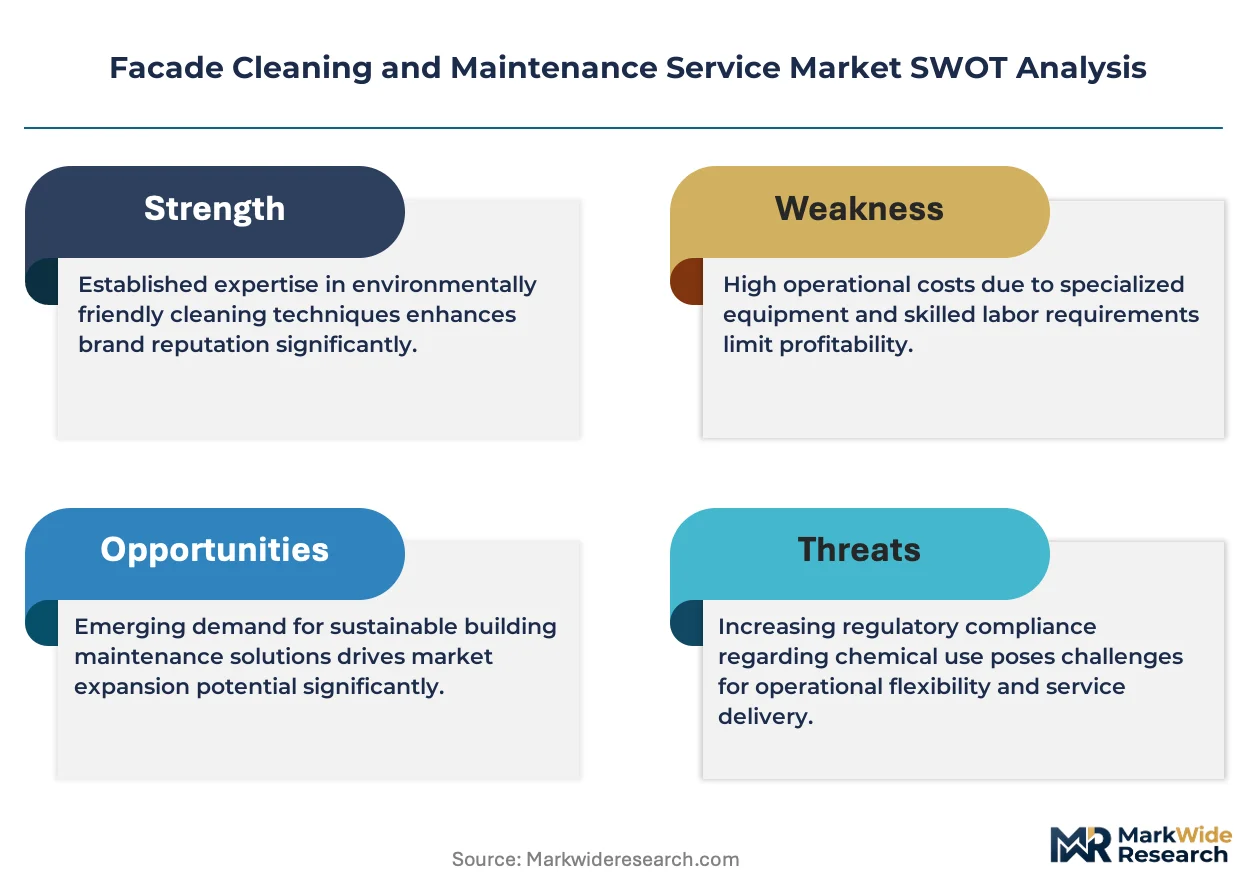
For Market Incumbents: Anchor market position through multi-year bundled contracts covering HVAC, envelope, and grounds maintenance, as institutional real estate investment trusts in New York and London increasingly mandate integrated facility platforms. Invest in in-house formulation R&D to reduce REACH authorization timeline exposure and working capital requirements. Defend against technology-augmented inspection platforms by acquiring or developing drone-based envelope diagnostics capabilities. For New Entrants and Emerging Players: Regional facility management partnerships offer the fastest path to contract volume, as mid-tier European cities follow the procurement template established by London and New York property managers. Target German municipal markets where documented facade maintenance is now required for building operating permit renewal, creating recurring revenue streams with lower competitive intensity. Penetrate through subscription maintenance models that embed facade upkeep into multi-year facility contracts. For Investors and Strategic Acquirers: OSHA rope-access recertification timeline compression is the leading indicator that labor scarcity will intensify pricing power for certified technician networks. Long-term viability favors operators with integrated predictive inspection platforms rather than standalone cleaning execution. Monitor German municipal mandate expansion as signal for regulatory-driven demand inflection across other EU member states.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Predictive Inspection | Drone-mounted LiDAR acquisition unifies assessment and cleaning workflows for commercial portfolios. |
| REACH-Compliant Formulation R&D Consolidation | In-house compound development reduces working capital barriers from jurisdiction-specific inventory requirements. |
| Multi-Service Bundled Contract Expansion | Envelope-HVAC-grounds integration locks out spot-market competitors in institutional REIT procurement. |
| OSHA-Certified Technician Network Acquisition | Fall-protection certification scarcity creates defendable moats as recertification timelines compress workforce availability. |
| Heritage Structure Restoration Specialization | EU Green Deal subsidies concentrate demand for substrate-specific craft skills distinct from glass-and-metal standardization. |
Research Methodology
Trade association filings, customs records, and municipal procurement databases formed the secondary backbone, cross-referenced with primary interviews involving facade maintenance contractors, property management executives, rope-access safety trainers, and REACH compliance officers. Bottom-up and top-down triangulation validated service-type segmentation and regional demand patterns across the analysis window.
Bottom-up modeling anchored volume projections to building stock data and regulatory mandate implementation schedules, while top-down cross-checks referenced facility management contract disclosure patterns. Segmentation dimensions included service type, building envelope material, cleaning method, and maintenance frequency tier. CAGRs were derived from regression analysis against energy-performance certification timelines and municipal operating permit renewal cycles.
Caveats apply where OSHA regulatory revisions or REACH authorization timeline accelerations could materially shift the outlook for labor availability and chemical formulation costs. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Services
Remote Construction Market
Construction Services
Testing, Inspection, and Certification for Construction Market
Construction Services
Heavy Equipment Training Simulator Market
Construction Services
Excavating Contractor Market
Construction Services
Work Order Management Market
Construction Services
North and Latin America Weatherization Services Market
Construction Services
Global Industrial Services Market
Construction Services
Middle East and Africa Industrial Maintenance Services in Operational Improvement and Operational Maintenance Market
Construction Services
Construction Project Management Services Market
Construction Services
North America Testing and Commissioning Market
Construction Services
Gutter Cleaning Services Market
Construction Services
Maintenance Repair and Operations (MRO) Market
Construction Services
Construction Materials Testing Equipment Market
Construction Services
MENA Architectural Services Market
Construction Services
Global Construction Scaffolding Rental Market
Construction Services
North America Repair and Rehabilitation Market