
 Australia Oil and Gas Upstream Market | 2026-2036
Australia Oil and Gas Upstream Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Oil and Gas Upstream Market Outlook
Aftermarket subsea equipment refurbishment is reconfiguring margin pools across the Australian upstream value chain, drawing capital from greenfield exploration budgets into asset life extension programs. Woodside Energy Group leverages its Scarborough and Pluto Train 2 integration to dominate Western Australia's LNG corridor, while Santos Limited anchors its position through the Barossa gas project and Cooper Basin infill drilling. Beach Energy competes aggressively in the Otway Basin with a tight-gas specialization that sustains lower breakeven costs than most offshore developments.
Australia oil and gas upstream encompasses the search for, recovery of, and initial processing of crude petroleum and natural gas from subterranean reservoirs, typically involving seismic surveying, directional drilling through formations up to six kilometers deep, and well completion with steel casing and cement bonding to isolate productive zones from aquifers. The primary purpose is to supply feedstock for liquefaction facilities, domestic gas-fired power generation, and petrochemical manufacturing across the Asia-Pacific rim. Exploration service demand concentrates on 3D and 4D seismic surveys over the North West Shelf and Browse Basin, where reservoir complexity rewards advanced geophysical imaging, while hydraulic fracturing activity is accelerating in Queensland's Surat Basin coal seam gas fields as operators target higher initial production rates from tighter formations. Offshore platform fabrication and installation remains the most capital-intensive equipment segment, with jack-up rigs and floating production vessels commanding premium day-rates during cyclical upswings.
The National Offshore Petroleum Safety and Environmental Management Authority enforces strict well integrity and spill-response standards that shape drilling permit timelines and capital deployment schedules across Commonwealth waters. Australia's Safeguard Mechanism, administered by the Clean Energy Regulator, imposes baseline emissions intensity thresholds that force gas producers to integrate carbon capture feasibility into field development plans or purchase offset credits. The offshore decommissioning framework under NOPSEMA and the Department of Industry, Science and Resources creates contingent liabilities that influence portfolio rationalization decisions as mature fields approach end-of-life. Stakeholders must monitor how the interaction of carbon pricing, Indigenous title negotiations, and Asian buyer contract renegotiations reshapes project sanctioning timelines before committing to long-cycle investments.
Market Dynamics
The Albanese government's Safeguard Mechanism reforms are compressing project sanctioning timelines as operators must integrate carbon capture feasibility into field development plans or absorb escalating offset credit costs. This regulatory pressure is redistributing capital from frontier exploration toward brownfield asset life extension programs.
Growth Catalysts
- Beetaloo Basin drilling programs:Unconventional tight-gas appraisal campaigns in Northern Territory are expanding the addressable resource base for domestic supply and LNG export feedstock.
- Safeguard Mechanism baseline thresholds:The Clean Energy Regulator's emissions intensity framework is accelerating carbon capture and storage feasibility studies across offshore developments.
- LNG offtake commitments from Japan and South Korea:Long-term purchase agreements are anchoring final investment decisions for Western Australian liquefaction capacity expansions.
Market Restraints
- Specialized offshore rig availability:Premium jack-up and floating production vessel day-rates spike during cyclical upswings, compressing project internal rates of return.
- NOPSEMA decommissioning liability frameworks:Contingent end-of-life obligations are forcing premature portfolio rationalization as mature North West Shelf fields approach economic limits.
- Coal seam gas well density requirements:Queensland's Surat Basin development economics depend on sustained drilling intensity that strains water management infrastructure and regulatory approval bandwidth.
Strategic Opportunities
- Subsea equipment refurbishment aftermarket:Asset life extension programs are capturing margin pools previously allocated to greenfield exploration budgets across the Cooper Basin and Otway Basin.
- Timor Sea appraisal campaigns:Commonwealth waters offshore Northern Territory contain underexplored carbonate reservoirs amenable to advanced 4D seismic imaging.
- Indigenous title negotiation frameworks:Structured benefit-sharing agreements are unlocking access to onshore permits previously stalled by native title complexity in Western Australia.
Industry Challenges
- Directional drilling talent scarcity:Extended-reach horizontal well construction through formations exceeding five kilometers depth requires specialized geosteering expertise concentrated among a limited contractor pool.
- Hydraulic fracturing water sourcing:Queensland coal seam gas operators face intensifying competition for non-potable water rights against agricultural and municipal demand centers.
- Well integrity certification timelines:NOPSEMA's spill-response and cement-bonding verification protocols extend drilling permit approval cycles by six to eighteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Oil and Gas Upstream Market |
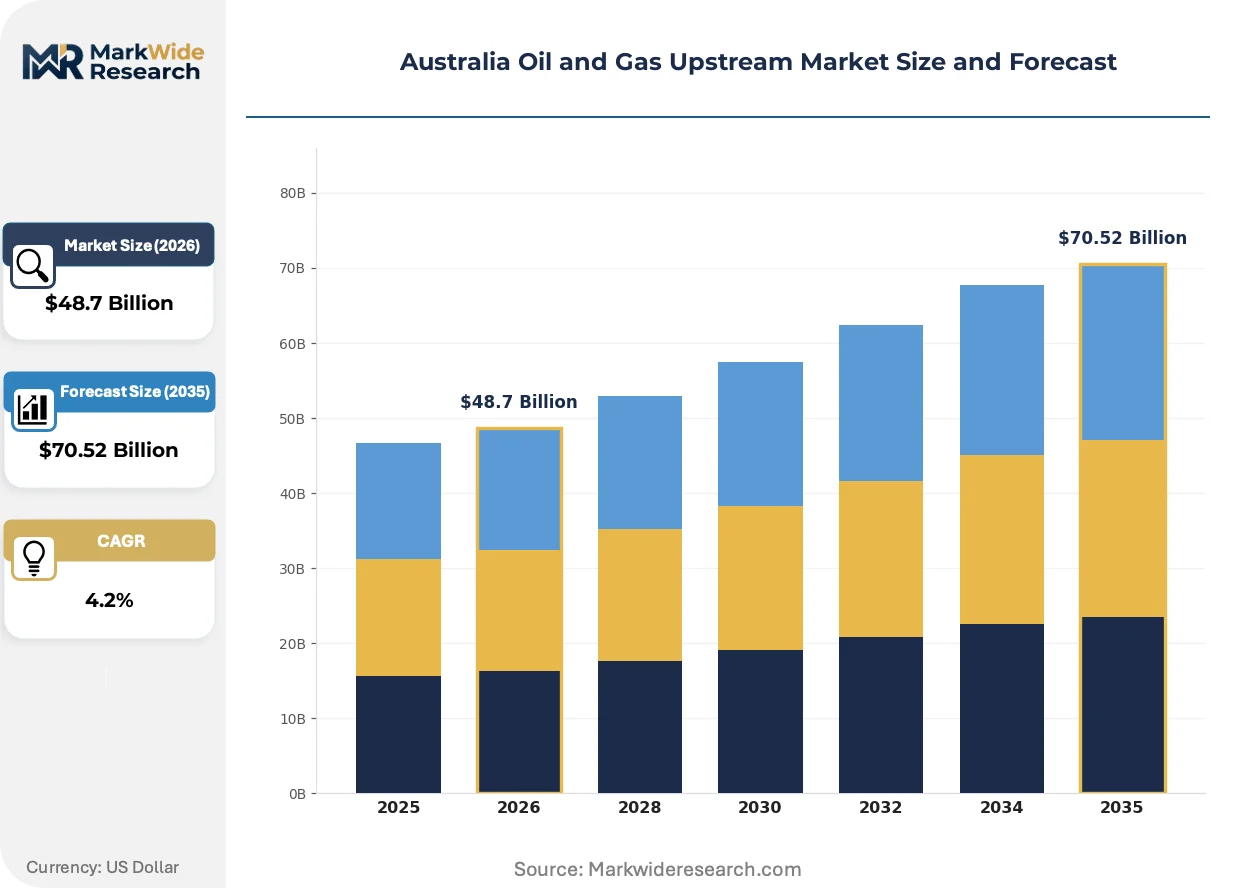
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $70.52 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Exploration, Production, Drilling, Completion Technology: Seismic, Hydraulic Fracturing, Offshore Platforms, Enhanced Oil Recovery Equipment Type: Drilling Rigs, Pumps, Compressors, Separation Units End User: Exploration Companies, National Oil Companies, Private Firms, Contractors |
| Companies Covered | Woodside Energy Group, Santos Limited, Chevron Corporation, ExxonMobil Corporation, Shell PLC, BP PLC, Origin Energy Limited, Beach Energy, BHP Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Oil and Gas Upstream Market Strategic Shifts
Digital reservoir characterization and emissions monitoring technologies are compressing the feedback loop between exploration decisions and carbon liability exposure. Operators are reconfiguring capital allocation around real-time data streams rather than static geological models.
Time-lapse 4D seismic acquisition is migrating from discretionary exploration expenditure to mandatory reservoir management infrastructure. Woodside Energy Group and Santos Limited now deploy permanent ocean-bottom sensor arrays across the North West Shelf and Browse Basin to optimize recovery factors from complex carbonate and turbidite formations. This capability is enabling predictive well intervention schedules that extend plateau production rates.
Australia's Safeguard Mechanism reforms administered by the Clean Energy Regulator are forcing gas producers to baseline emissions intensity before field sanctioning. The framework compresses project economics unless operators demonstrate carbon capture integration or secure verified offset credit pipelines. Offshore developments in Commonwealth waters face the steepest compliance gradients given their distance from onshore storage infrastructure.
Asian LNG buyers are compressing contract renegotiation cycles from decennial to triennial intervals, forcing Australian exporters to absorb greater volume and price volatility. Procurement teams at Japanese and South Korean utilities now demand destination flexibility clauses and carbon intensity disclosures that were absent in legacy agreements. This behavioral shift is most visible in Western Australia's LNG corridor where Pluto Train 2 and Scarborough integration projects must accommodate buyer-mandated certification standards.
Australia Oil and Gas Upstream Market Segmentation
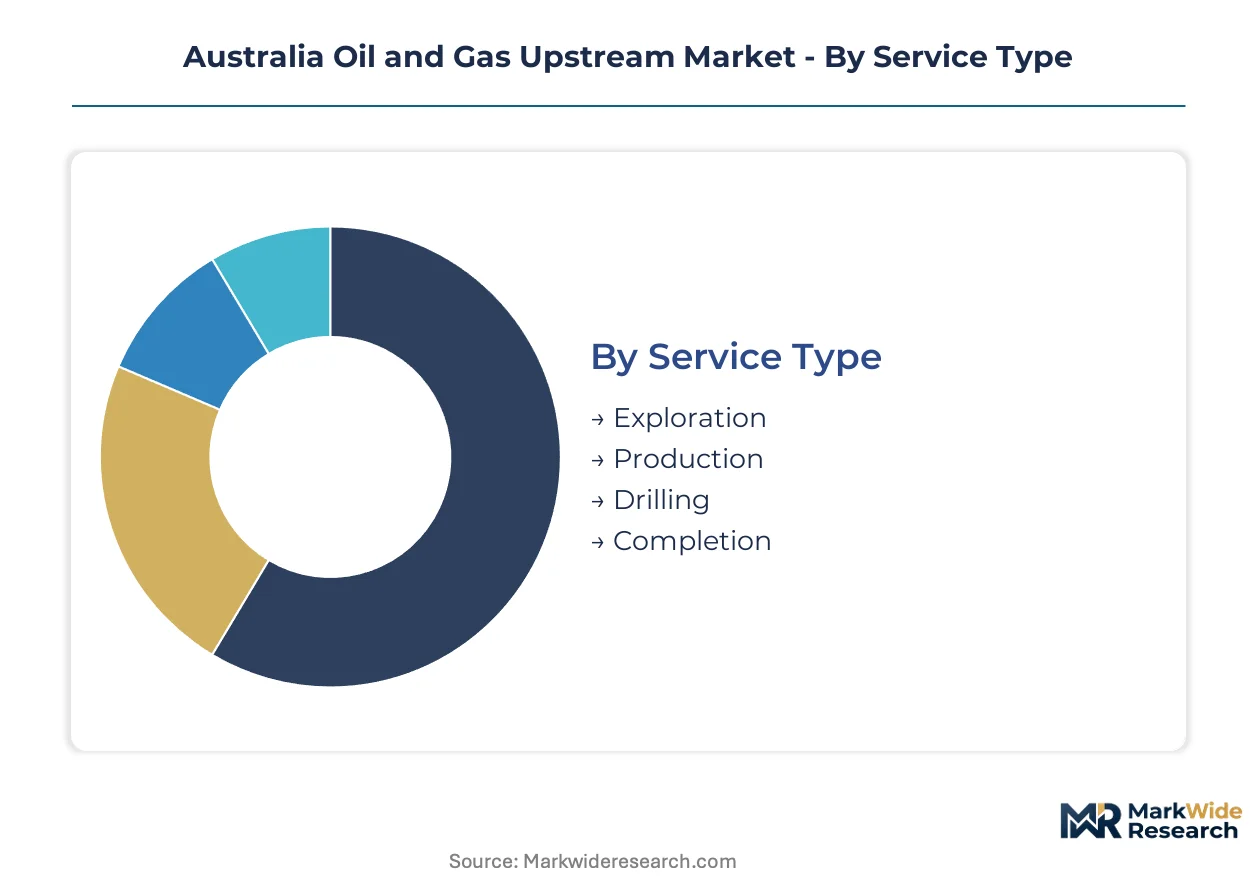
Upstream segmentation in Australia reflects the tension between mature basin redevelopment and frontier resource appraisal. Each dimension—service delivery, technology deployment, equipment procurement, and customer archetype—channels capital differently across the North West Shelf, Cooper Basin, and emerging Northern Territory plays.
Service Type:
Mature production maintenance dominates capital allocation, while exploration services recover from decade-low investment levels.
- Exploration:Seismic surveying and frontier drilling in the Beetaloo Basin and Timor Sea appraisal blocks. Demand concentrates in Northern Territory permits where Origin Energy and Tamboran Resources accelerate tight-gas evaluation programs ahead of pipeline infrastructure commitments.
- Production:Brownfield optimization across the North West Shelf and Gippsland Basin, encompassing artificial lift installation, well intervention, and facility debottlenecking. Santos Limited and Woodside Energy Group redirect maintenance budgets toward extended-reach sidetracks that sustain plateau rates from legacy reservoirs.
- Drilling:Extended-reach horizontal wells through the Surat Basin coal seam gas fairway and Browse Basin deepwater targets. Queensland drilling intensity strains contractor availability for specialized coiled-tubing and managed-pressure systems.
- Completion:Multi-stage hydraulic fracturing design and intelligent well architecture for Barossa gas field subsea tiebacks. Completion engineering integrates carbon capture readiness into wellhead specifications under Safeguard Mechanism compliance timelines.
Production handles the majority of throughput; exploration is gaining share fastest as Beetaloo appraisal campaigns advance toward development decisions.
Technology:
Cost tier stratification separates discretionary exploration tools from mandatory production infrastructure.
- Seismic:Time-lapse 4D acquisition and permanent ocean-bottom sensor arrays across carbonate reservoirs in the Browse Basin. Woodside Energy Group deploys advanced geophysical imaging to optimize recovery from complex turbidite formations where conventional 3D surveys prove inadequate.
- Hydraulic Fracturing:Multi-stage stimulation of Surat Basin coal seam gas wells and Beetaloo Basin tight-gas formations. Queensland operators face intensifying water sourcing competition as agricultural and municipal demand centers contest non-potable rights.
- Offshore Platforms:Floating production vessel integration for Scarborough gas field development and Pluto Train 2 expansion. Western Australian liquefaction corridor projects command premium fabrication yard capacity across Asian supply chains.
- Enhanced Oil Recovery:Gas injection and chemical flooding pilots in mature Cooper Basin oilfields. Carbon dioxide utilization for EOR aligns with Safeguard Mechanism emissions reduction pathways while extending economic field life.
Seismic absorbs the largest technology budget; hydraulic fracturing is expanding most quickly as unconventional gas appraisal accelerates.
Equipment Type:
Supply concentration favors established fabrication centers, with premium day-rates compressing project returns during cyclical upswings.
- Drilling Rigs:Jack-up and semi-submersible units for North West Shelf and Timor Sea campaigns. Premium vessel availability constraints force operators into multi-year charter commitments that reshape field development sequencing.
- Pumps:Subsea boosting systems and artificial lift infrastructure for Gippsland Basin oil production. Electric submersible pump refurbishment programs capture margin pools previously allocated to greenfield exploration budgets.
- Compressors:Gas compression trains for Barossa field subsea tiebacks and domestic gas processing facilities. Compression specification integrates carbon intensity baselining under Clean Energy Regulator protocols.
- Separation Units:Three-phase separators and produced water treatment systems for Surat Basin coal seam gas central processing plants. Queensland water management infrastructure strains under sustained drilling intensity requirements.
Drilling rigs command the highest capital commitment; pumps are climbing the fastest on refurbishment-driven demand.
End User:
Customer type determines risk tolerance and contract structure across the investment cycle.
- Exploration Companies:Pure-play upstream operators focused on frontier appraisal and farm-in arrangements. Beetaloo Basin drilling programs concentrate demand among junior explorers seeking production certification to attract LNG offtake partners.
- National Oil Companies:International NOCs with Australian portfolio exposure through joint venture structures. Japanese and South Korean utility-affiliated producers anchor Western Australian LNG capacity expansion through equity participation and long-term purchase agreements.
- Private Firms:Privately held operators in the Cooper Basin and Otway Basin tight-gas plays. Beach Energy and smaller competitors sustain lower breakeven costs than offshore developments through focused operational execution.
- Contractors:Integrated service providers and drilling consortiums executing lump-sum turnkey projects. Directional drilling talent scarcity concentrates expertise among limited contractor pools commanding premium day-rates for extended-reach horizontal wells.
National oil companies direct the largest capital flows; exploration companies are expanding most quickly as Beetaloo and Timor Sea campaigns advance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Western Australia's LNG corridor display the lowest price elasticity, absorbing destination flexibility premiums under long-term Japanese and South Korean contracts. Queensland coal seam gas operators face the highest sensitivity, with Surat Basin breakevens vulnerable to water sourcing cost spikes and domestic gas price caps.
Western Australia
The North West Shelf and Browse Basin concentrate offshore production maintenance demand, with Scarborough gas field development and Pluto Train 2 expansion anchoring fabrication yard commitments. NOPSEMA enforces spill-response and well integrity standards that extend permit timelines for Commonwealth waters drilling. Perth serves as the engineering hub where Woodside Energy Group and Santos Limited coordinate subsea equipment procurement for Browse Basin tiebacks.
Queensland
Surat Basin coal seam gas fields drive hydraulic fracturing intensity as operators target higher initial production rates from tighter formations. The state's water management frameworks impose non-potable sourcing constraints that compete with agricultural demand centers. Brisbane-based processing facilities and Gladstone liquefaction infrastructure strain under sustained drilling programs from Origin Energy and junior explorers.
Northern Territory
Beetaloo Basin tight-gas appraisal campaigns expand the addressable resource base for domestic supply and LNG export feedstock. The Albanese government's Safeguard Mechanism reforms force carbon capture feasibility into field development plans across frontier permits. Darwin anchors logistics coordination for Timor Sea appraisal blocks where Tamboran Resources accelerates drilling ahead of pipeline infrastructure commitments.
Victoria
The Otway Basin sustains Beach Energy's tight-gas specialization with lower breakeven costs than offshore developments. Gippsland Basin mature fields require artificial lift installation and well intervention programs as production maintenance dominates capital allocation. Melbourne hosts technical service providers executing extended-reach sidetracks for plateau rate preservation.
South Australia
Cooper Basin infill drilling and enhanced oil recovery pilots concentrate demand for gas injection and chemical flooding services. Carbon dioxide utilization for EOR aligns with Clean Energy Regulator emissions reduction pathways while extending economic field life. Adelaide-based contractors execute refurbishment programs capturing margin pools previously allocated to greenfield exploration budgets.
Australia Oil and Gas Upstream Market Competitive Environment
Capability concentration sits with integrated LNG developers possessing subsea engineering expertise; scale advantage sits with diversified majors leveraging global procurement networks. The market structures around two tiers: full-cycle operators controlling liquefaction capacity, and pure-play upstream specialists optimizing tight-gas breakevens. Strategic archetypes include basin-anchored consolidators, unconventional-focused nimble operators, and service-integrated engineering houses. Competitive moves center on portfolio rationalization near end-of-life fields and carbon capture integration to satisfy Safeguard Mechanism baselines.
Among integrated developers, Woodside Energy Group and Santos Limited exemplify the full-cycle archetype with Western Australian LNG corridor dominance and Cooper Basin tight-gas positioning respectively. Beach Energy occupies the specialist tier with Otway Basin focus. Chevron Corporation represents the multinational major archetype with Browse Basin exposure through joint venture structures.
| Leading Market Players |
|---|
| Woodside Energy Group |
| Santos Limited |
| Chevron Corporation |
| ExxonMobil Corporation |
| Shell PLC |
| BP PLC |
| Origin Energy Limited |
| Beach Energy |
| BHP Group |
| Others |
Value Chain & Pricing Dynamics
The Darwin-Singapore LNG shipping corridor shapes cost dynamics across Australian upstream operations, concentrating supply leverage among integrated exporters while forcing price differentiation between spot-traded cargoes and long-term offtake contracts tied to Japanese and South Korean buyers.
Pricing Analysis
Aftermarket refurbishment contracts and extended service agreements generate lifetime value exceeding original equipment sales for subsea infrastructure across the North West Shelf. Project-based pricing dominates greenfield developments, with Scarborough and Barossa gas fields commanding premiums for carbon-capture-ready specifications under Safeguard Mechanism baselines. Price differentiation rests on certification grade for well integrity and geographic delivery cost to Commonwealth waters. Cost compression in standard-grade drilling services is intensifying because contractor availability constraints have eased. Exploration companies exhibit highest price sensitivity, while Japanese utility buyers absorb destination flexibility premiums with minimal elasticity.
Supply Chain Analysis
Upstream steel casing, wellhead equipment, and subsea trees draw from fabrication centers in South Korea, Singapore, and the United Arab Emirates. Australian operators source specialized jack-up rigs and floating production vessels from Singaporean and South Korean yards, with premium day-rates feeding from cyclical demand spikes. Single-source vulnerability concentrates in subsea umbilical manufacturing, where Norwegian and UK suppliers dominate proprietary connector technologies. Distribution runs through Perth-based engineering hubs coordinating Browse Basin and Timor Sea campaigns, with Darwin anchoring Northern Territory logistics for Beetaloo appraisal programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Australia's upstream sector faces a platform-economics inflection as carbon intensity data interoperability becomes the binding constraint for LNG offtake negotiations, with Japanese and South Korean buyers demanding real-time emissions verification that favors integrated operators with captive monitoring infrastructure.
For Market Incumbents: Build regulatory compliance moats through carbon capture integration across Western Australian LNG corridors. Woodside Energy Group and Santos Limited should consolidate subsea engineering capabilities to control Scarborough and Browse Basin tieback costs. Defensive positioning requires securing long-term rig charters before cyclical upswings compress project returns. The threat of Safeguard Mechanism baseline revisions demands preemptive offset credit pipelines.
For New Entrants and Emerging Players: Northern Territory onshore permits offer the most penetrable geography for tight-gas specialists seeking production certification ahead of pipeline infrastructure commitments. Beetaloo Basin farm-in arrangements with Tamboran Resources or Origin Energy provide lowest-barrier entry points. Targeting Surat Basin water management subcontracting leverages Queensland's regulatory bandwidth constraints as a go-to-market angle.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors pure-play upstream operators with Otway Basin and Cooper Basin tight-gas breakevens below offshore development thresholds. Long-term viability hinges on portfolio rationalization timing as mature North West Shelf fields approach decommissioning liabilities. Acquisition targets should display subsea equipment refurbishment capabilities capturing margin pools from greenfield budget reallocation. Watch for Clean Energy Regulator baseline tightening as the inflection signal compressing project sanctioning windows.
| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Capture Integration | Safeguard Mechanism compliance secures LNG offtake contracts with Japanese utilities demanding intensity disclosures. |
| Subsea Equipment Refurbishment | Asset life extension programs redirect capital from exploration budgets into higher-margin aftermarket services. |
| Beetaloo Basin Appraisal Acceleration | Tight-gas certification attracts farm-in partners for pipeline infrastructure commitments ahead of development decisions. |
| Long-term Rig Charter Lock-in | Multi-year vessel commitments insulate project economics from cyclical day-rate spikes during upswings. |
| Indigenous Title Structured Agreements | Benefit-sharing frameworks unlock Western Australian onshore permits previously stalled by native title complexity. |
Study Parameters
Initial hypotheses were tested against primary input from upstream project developers, drilling contractors, LNG offtake procurement officers, and Clean Energy Regulator compliance leads, then refined through secondary validation. Field intelligence combined structured interviews with operations executives at Woodside Energy Group and Santos Limited alongside regulatory affairs specialists navigating NOPSEMA permitting timelines. Secondary sources encompassed NOPSEMA well integrity filings, Clean Energy Regulator Safeguard Mechanism baseline data, Australian Bureau of Statistics energy production records, and Asian utility LNG procurement disclosures. Bottom-up field development cost modeling and top-down sector revenue aggregation were triangulated to anchor projections.
Demand-supply balance framing shaped the analytical approach across the projection horizon, with segmentation modeled by service type, technology deployment, equipment category, and end-user archetype. Service delivery splits between exploration, production, drilling, and completion were cross-referenced against technology tiers spanning seismic acquisition, hydraulic fracturing, offshore platforms, and enhanced recovery systems. CAGRs were derived from production maintenance intensity curves and frontier appraisal campaign pacing. Forecast inputs incorporated Safeguard Mechanism compliance cost trajectories and Asian buyer contract renegotiation cycle compression.
The forecast holds incumbent behavior within observed patterns; aggressive carbon capture deployment acceleration by integrated majors or sudden NOPSEMA baseline revisions would shift outcomes materially. Forecasts assume continued Japanese and South Korean LNG demand anchoring and stable Indigenous title negotiation frameworks. Cross-checking against IEA Australia gas market outlooks and Asian utility procurement disclosure trends is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Oil and Gas Processing Seals Market
Oil & Gas
Sucker Rod Market
Oil & Gas
South-East Asia Oil and Gas Pipeline Market
Oil & Gas
Nigeria Oil and Gas Upstream Market
Oil & Gas
Workover Rigs Market
Oil & Gas
Iraq Oil and Gas Market
Oil & Gas
Oil and Gas Downhole Cables Market
Oil & Gas
Kazakhstan Oil and Gas Downstream Market
Oil & Gas
South Korea Oil and Gas Market
Oil & Gas
Russia Oil and Gas EPC Market
Oil & Gas
Oil and Gas Midstream Market
Oil & Gas
Oil and Gas Seals Market
Oil & Gas
Digital Oil Rigs Market
Oil & Gas
Oil and Gas Fabrication Market
Oil & Gas
Oil and Gas Automation Market
Oil & Gas
Middle East and Africa Drill Collar Market