
 Polycrystalline Solar Cell Market | 2026-2036
Polycrystalline Solar Cell Market Size, Share, and Industry Trends Forecast 2026-2036
Polycrystalline Solar Cell Market Analytics
A widening capital-intensity divergence between fully integrated polysilicon-to-module manufacturers and cell-only specialists is redrawing competitive boundaries in polycrystalline solar. LONGi Green Energy Technology leverages captive polysilicon capacity to sustain margin structures that pure-play cell producers cannot match. JinkoSolar Holding Co., Ltd anchors its position through vertical control over wafer and module stages, while Tongwei Co., Ltd dominates high-purity polysilicon supply and extends downstream into cell manufacturing at scale.
Polycrystalline solar cells consist of silicon ingots formed from multiple crystal structures, typically manufactured through directional solidification and featuring conversion efficiencies in the range of sixteen to twenty percent under standard test conditions; these cells serve as the foundational electricity-generating units assembled into modules for grid-connected and distributed power systems. P-V Panels command the largest installed base among product type segments, though Bifacial Modules represent the fastest-growing category as dual-sided energy harvest gains traction in ground-mounted applications. Utility-Scale deployments absorb the majority of polycrystalline output, while Residential installations compete for supply amid rooftop program expansions across multiple jurisdictions.
FERC interconnection standards and the IRA domestic content provisions in the United States, alongside China's MIIT efficiency benchmarks and India's BIS certification requirements for photovoltaic modules, collectively elevate product qualification thresholds and reshape procurement criteria for project developers. EMA and REACH compliance obligations in Europe add further layers of material traceability and environmental performance verification. Stakeholders must monitor how evolving efficiency mandates and local content rules alter competitive access across major demand centers.
Market Dynamics
China's MIIT efficiency benchmarks and India's BIS certification requirements are compressing the addressable market for conventional polycrystalline cells while bifacial module architectures capture procurement preference in utility-scale tenders.
Growth Catalysts
- India's PLI scheme for solar manufacturing:Production-linked incentives for domestic module assembly are sustaining polycrystalline demand as developers seek cost-competitive procurement for state-level solar parks.
- Feed-in tariff evolution in Southeast Asia:Vietnam and Thailand are adjusting tariff structures to favor rapid deployment over premium efficiency, preserving polycrystalline competitiveness in ground-mounted installations.
- Directional solidification furnace upgrades:Advanced crucible designs and optimized thermal profiles are lifting average cell efficiencies toward the upper bound of the polycrystalline range without requiring monocrystalline conversion capex.
Market Restraints
- Polysilicon price volatility:Metallurgical-grade silicon feedstock costs fluctuate with Chinese industrial electricity pricing and Xinjiang region production quotas, compressing margin predictability for cell-only manufacturers.
- Monocrystalline PERC substitution:Passivated emitter and rear contact cells manufactured on single-crystal wafers now dominate residential and commercial rooftop segments where efficiency premiums command price acceptance.
- EU Ecodesign and energy labeling requirements:Minimum efficiency thresholds for module imports into European markets are tightening faster than polycrystalline technology roadmaps can match without substantial retooling.
Strategic Opportunities
- Rajasthan and Gujarat solar park expansion:India's National Solar Mission targets for desert installations favor cost-optimized module procurement where polycrystalline pricing holds advantage against monocrystalline alternatives.
- Agrivoltaics and dual-use land applications:Ground-mounted bifacial polycrystalline installations over agricultural plots are qualifying for differentiated tariff treatment in Italy and Japan where land-use efficiency drives policy design.
- Second-life module refurbishment channels:Emerging reverse logistics networks for end-of-life photovoltaic recovery are creating aftermarket value capture for polycrystalline units with degradable but serviceable output characteristics.
Industry Challenges
- Wafer thinning and cell breakage rates:Cost pressure to reduce silicon consumption per watt is pushing thickness tolerances that elevate fracture losses during automated module assembly.
- Silver paste consumption and metallization reformulation:Screen-printed front contacts rely on volatile silver commodity markets, forcing investment in copper-plated or aluminum-back contact architectures with unproven field degradation profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polycrystalline Solar Cell Market |
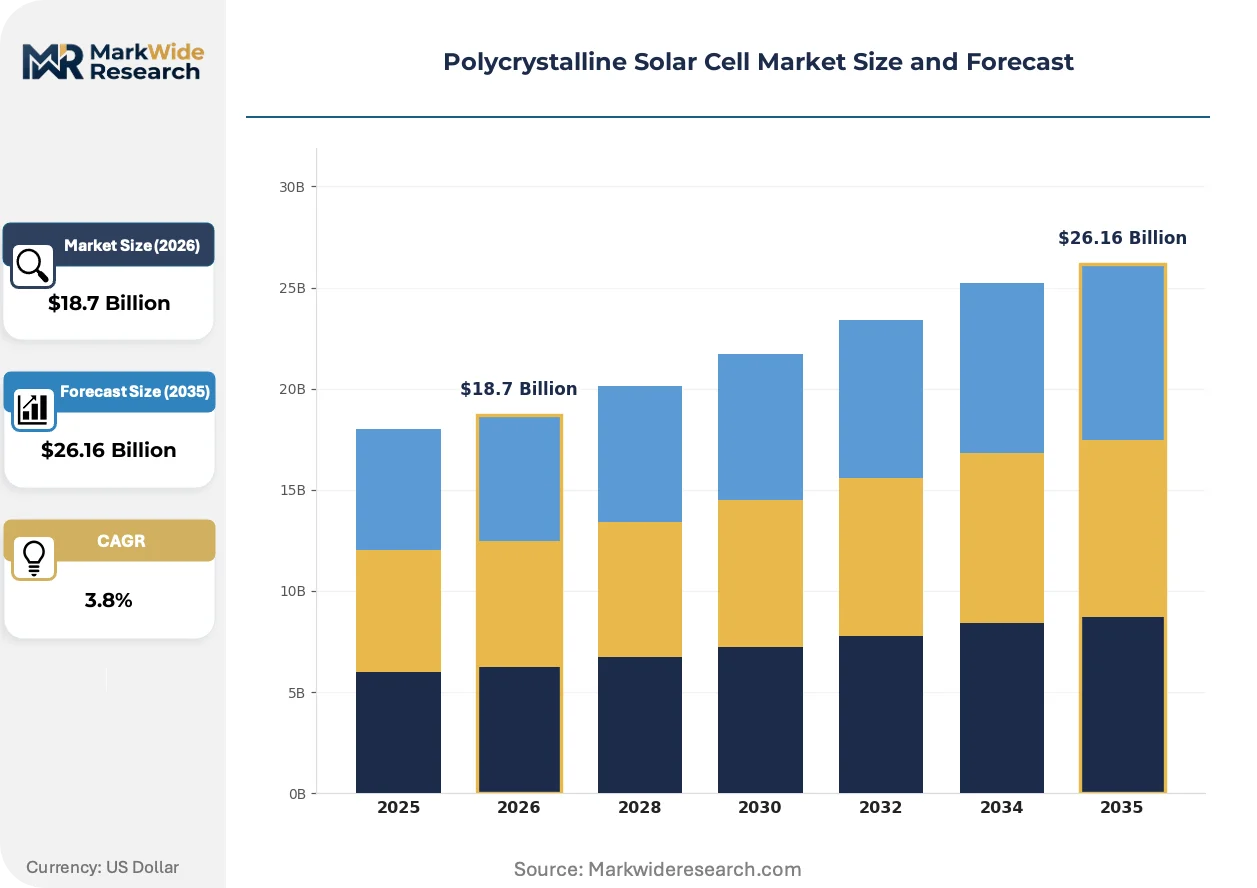
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $26.16 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: P-V Modules, P-V Panels, Solar Cell Arrays, Bifacial Modules Technology: Wafer-Based, Cell and Module Efficiency, Thin Film, Concentrated Photovoltaics End User: Residential, Commercial, Industrial, Utility-Scale Installation: Ground-Mounted, Roof-Mounted, Building-Integrated, Off-Grid |
| Companies Covered | JA Solar Technology Co., Ltd., LONGi Green Energy Technology, JinkoSolar Holding Co., Ltd, Yingli Green Energy Holding Co. Ltd., GCL-Poly Energy Holdings Ltd., Canadian Solar Inc., Tongwei Co., Ltd., SunPower Corporation, Trina Solar Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polycrystalline Solar Cell Market Evolving Landscape
Module architecture and manufacturing process evolution are fragmenting the polycrystalline value chain into distinct performance tiers while regulatory efficiency floors and procurement model innovation reshape competitive access.
Multicrystalline silicon ingot production is bifurcating between standard directional solidification for commodity utility supply and quasi-mono casting techniques that blend polycrystalline cost structures with enhanced crystal uniformity. Ground-mounted developers in India and Brazil are absorbing standard-grade output for tariff-optimized projects, while quasi-mono variants command modest premiums in distributed commercial installations where space constraints elevate efficiency value. This technology stratification is compressing the middle tier of the polycrystalline market as procurement concentrates at the efficiency extremes.
China's updated GB/T 6495 standards for photovoltaic device measurement are tightening spectral response and temperature coefficient reporting requirements for modules sold into domestic and export markets. Cell manufacturers must now certify performance degradation curves under extended thermal cycling protocols that expose polycrystalline material quality variations previously masked by snapshot efficiency ratings. Export-oriented producers are restructuring quality assurance departments to manage dual certification tracks for GB-compliant domestic supply and IEC 61215-aligned international shipments.
Utility-scale developers are consolidating module procurement through multi-year framework agreements that bundle engineering, procurement, and construction services with performance guarantees. Independent power producers in Saudi Arabia and South Africa are displacing spot-market module purchasing with integrated EPC-plus-O&M contracts that transfer operational risk to vertically integrated suppliers. This buying-pattern shift favors manufacturers with captive polysilicon and in-house module assembly capable of underwriting 25-year output warranties without third-party supply chain exposure.
Polycrystalline Solar Cell Market Segmentation
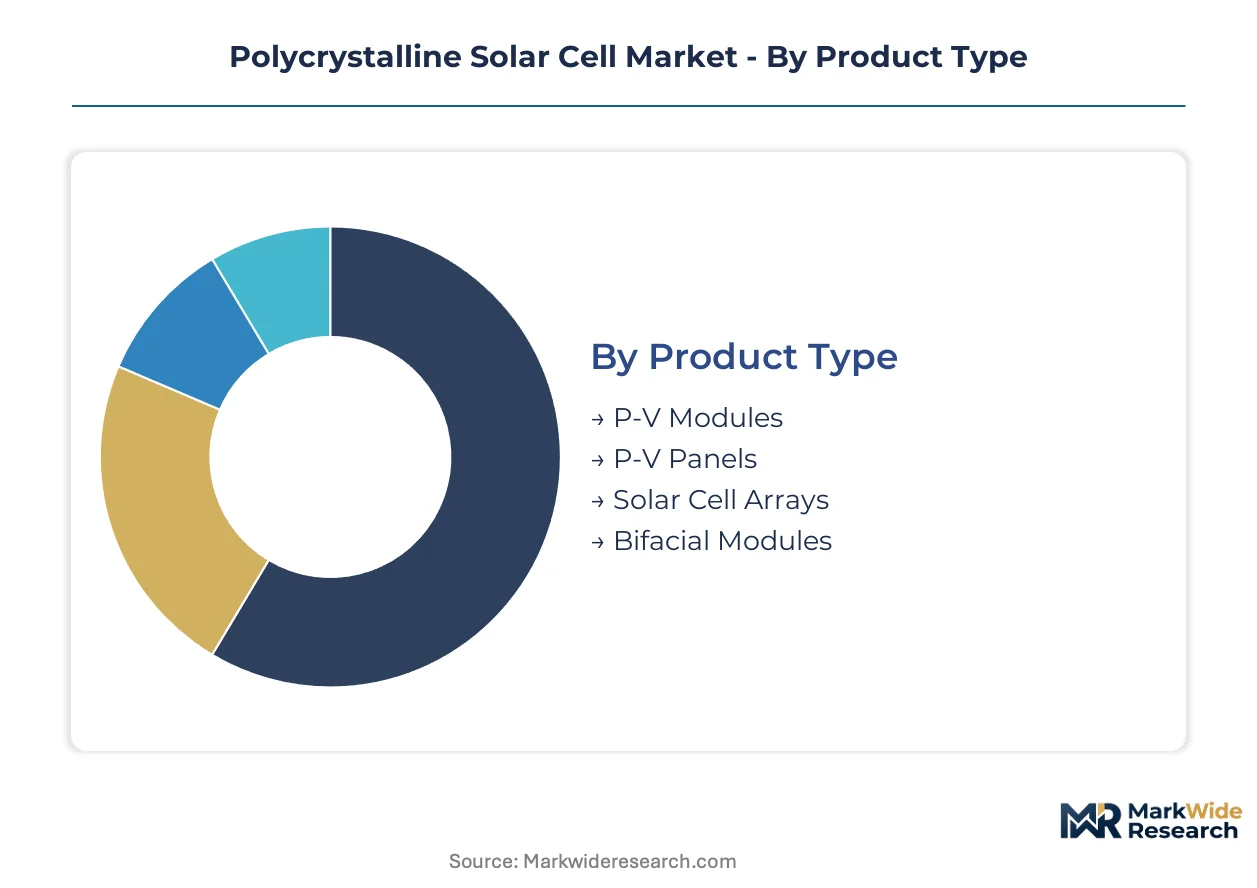
Polycrystalline solar cell segmentation reveals where monocrystalline PERC substitution pressure concentrates most intensely. Technology and end-use splits expose which customer tiers still tolerate efficiency trade-offs for cost advantage.
Product Type:
Monocrystalline substitution pressure falls heaviest on standard-format segments while dual-sided architectures carve defensive niches.
- P-V Panels:Standard glass-backsheet assemblies using polycrystalline cells dominate India's state-level solar parks and Brazilian distributed generation. Procurement in Gujarat's Charanka Solar Park and Rajasthan's Bhadla cluster sustains volume despite residential rooftop losses to higher-efficiency alternatives.
- Bifacial Modules:Dual-sided polycrystalline designs capture albedo-reflected irradiance from desert and snow-ground installations. Ground-mounted deployments in Saudi Arabia's Sakaka and South Africa's Northern Cape favor these units where land costs are minimal and rear-side gain justifies modest efficiency premiums.
- P-V Modules:Framed assemblies with aluminum rails serve commercial rooftop retrofits where structural load limits restrict heavier glass-glass alternatives. Southeast Asian feed-in tariff projects in Vietnam's Ninh Thuan province absorb significant output.
- Solar Cell Arrays:Unglaminated cell strings feed specialized applications including solar-powered irrigation pumps and telecom tower electrification in sub-Saharan Africa.
P-V Panels anchors the volume base while Bifacial Modules gains share at the steepest rate.
Technology:
Cost-tier stratification separates segments that can absorb polysilicon volatility from those requiring capital-intensive retooling.
- Wafer-Based:Directional solidification of multicrystalline silicon ingots remains the dominant production pathway for Indian and Southeast Asian supply. China's MIIT efficiency benchmarks are compressing addressable market share for conventional casting methods without quasi-mono upgrades.
- Cell and Module Efficiency:Process optimization through selective emitter doping and anti-reflective coating refinement offers polycrystalline producers a defensible trajectory. Advanced thermal profile control in directional solidification furnaces lifts average efficiencies toward the upper bound of the sixteen-to-twenty percent range.
- Thin Film:Cadmium telluride and copper indium gallium selenide technologies compete indirectly through utility-scale PPA pricing rather than efficiency comparison. First Solar's manufacturing scale in Ohio and Malaysia establishes reference pricing that constrains polycrystalline module ceiling prices.
- Concentrated Photovoltaics:Multi-junction III-V cell systems serve niche high-DNI desert applications with tracking infrastructure. These installations absorb negligible polycrystalline volume given fundamental technology incompatibilities.
Wafer-Based technology commands the installed base while Cell and Module Efficiency improvements drive the most rapid competitive repositioning.
End User:
Application-based demand concentration shows where space constraints force efficiency premiums versus cost-optimized ground-mounted procurement.
- Utility-Scale:Independent power producers in India, Saudi Arabia, and South Africa prioritize levelized cost of electricity over module efficiency. Multi-year framework agreements bundle EPC services with performance guarantees that favor vertically integrated polycrystalline suppliers.
- Residential:Rooftop installations in Germany, Australia, and Japan face severe area constraints that elevate monocrystalline PERC preference. Polycrystalline share concentrates in price-sensitive segments of emerging markets where net metering policies are less generous.
- Commercial:Flat-roof warehouses and manufacturing facilities in Italy and Spain balance structural load limits against energy yield targets. Bifacial polycrystalline designs gain traction where white membrane roofing enhances rear-side collection.
- Industrial:Captive power arrangements for cement, steel, and aluminum producers in India and Indonesia favor cost-optimized procurement. Open land availability at industrial park peripheries reduces efficiency premium requirements.
Utility-Scale deployments absorb the dominant production share while Residential applications retreat fastest under monocrystalline substitution pressure.
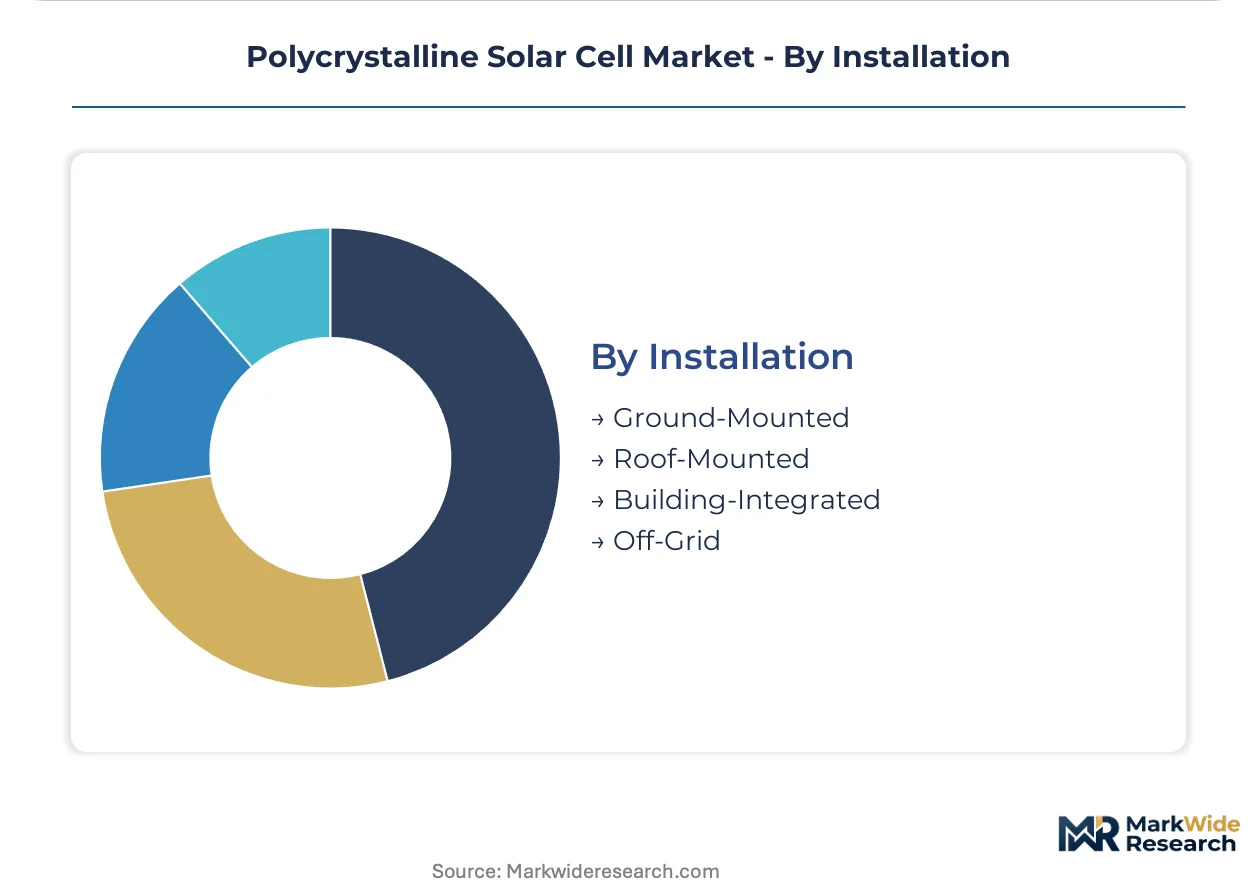
Installation:
Geography-of-deployment splits reveal where land abundance permits lowest-cost module selection versus where integration complexity elevates system value.
- Ground-Mounted:Fixed-tilt and tracking installations on agricultural margins and desert scrubland dominate polycrystalline absorption. India's National Solar Mission desert targets in Rajasthan and Gujarat explicitly optimize for cost-competitive module supply.
- Roof-Mounted:Residential and small commercial attachments face accelerating monocrystalline capture as efficiency-per-square-meter drives customer economics. Polycrystalline retention concentrates in subsidy-constrained emerging markets.
- Building-Integrated:Façade and skylight applications require customized module dimensions and aesthetic tolerances that polycrystalline producers rarely serve. European Ecodesign efficiency thresholds further restrict access.
- Off-Grid:Rural electrification, water pumping, and telecom backup in sub-Saharan Africa and island Southeast Asia sustain demand for robust, cost-minimized units. Durability concerns in high-temperature, high-humidity environments favor established polycrystalline supply chains.
Ground-Mounted systems anchor procurement volume while Off-Grid applications expand most quickly as rural electrification programs accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price-sensitive utility-scale developers in India and Southeast Asia sustain polycrystalline absorption, while efficiency-focused residential markets in Germany and Japan accelerate monocrystalline substitution. This demand elasticity divergence is reshaping regional manufacturing footprints and procurement patterns.
China
MIIT efficiency benchmarks and updated GB/T 6495 standards are compressing the addressable market for conventional casting methods. The dual carbon goals policy framework tightens industrial electricity quotas for Xinjiang polysilicon smelters. Yangtze River Delta ingot producers are upgrading directional solidification furnaces to quasi-mono casting to retain domestic procurement share.
India
State-level solar parks in Rajasthan and Gujarat absorb standard-grade polycrystalline modules under PLI scheme incentives for domestic assembly. BIS certification requirements for photovoltaic modules elevate product qualification thresholds for imported cells. Bhadla and Charanka clusters sustain volume despite residential rooftop losses to higher-efficiency alternatives.
United States
FERC interconnection standards and IRA domestic content provisions reshape procurement criteria for utility-scale developers. Independent power producers prioritize levelized cost economics in Texas and California desert installations. Ohio and Arizona manufacturing footprints face margin pressure from Asian module pricing.
Germany
EU Ecodesign and energy labeling requirements tighten minimum efficiency thresholds faster than polycrystalline roadmaps can match. Residential rooftop installations in Bavaria and North Rhine-Westphalia face severe area constraints that elevate monocrystalline PERC preference. REACH compliance obligations add material traceability layers for module imports.
Brazil
Feed-in tariff structures for distributed generation preserve polycrystalline competitiveness in ground-mounted commercial installations. Minas Gerais and São Paulo industrial parks favor cost-optimized procurement where open land availability reduces efficiency premium requirements. ANVISA environmental licensing adds procedural duration to utility-scale project timelines.
Polycrystalline Solar Cell Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the polycrystalline solar cell market. Fully integrated polysilicon-to-module manufacturers command margin structures that pure-play cell specialists cannot replicate, creating a tiered competitive structure. The vendor base clusters around three strategic archetypes: captive polysilicon integrators, wafer-stage controllers, and scale-driven assemblers. Dominant competitive moves include backward integration into high-purity polysilicon supply and multi-year framework agreements bundling EPC services with performance guarantees.
Among Chinese-integrated specialists, JA Solar Technology Co., Ltd. and LONGi Green Energy Technology exemplify the captive-polysilicon archetype, while JinkoSolar Holding Co., Ltd. anchors the wafer-control tier. These entities occupy positions that reflect divergent strategic bets on vertical scope versus modular specialization.
| Leading Market Players |
|---|
| JA Solar Technology Co., Ltd. |
| LONGi Green Energy Technology |
| JinkoSolar Holding Co., Ltd |
| Yingli Green Energy Holding Co. Ltd. |
| GCL-Poly Energy Holdings Ltd. |
| Canadian Solar Inc. |
| Tongwei Co., Ltd. |
| SunPower Corporation |
| Trina Solar Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Capacity utilization at Xinjiang polysilicon smelters shapes margin structures throughout the polycrystalline value chain, compressing price floors for cell-only manufacturers while integrated producers capture spread advantages. Chinese industrial electricity pricing and regional production quotas feed directly into module pricing power across Indian and Southeast Asian procurement markets.
Pricing Analysis
Performance guarantees bundled into 25-year EPC-plus-O&M contracts drive lifetime value capture for vertically integrated suppliers. Three-tier pricing structure across premium quasi-mono, standard directional-solidification, and economy-grade utility formats separates procurement tiers. Cost compression in standard-grade segments is intensifying because Indian PLI scheme incentives favor domestic assembly scale over import reliance. Utility-scale developers in Rajasthan and Gujarat exhibit highest price sensitivity, while distributed commercial installers in Italy and Japan tolerate modest premiums for bifacial architectures.
Supply Chain Analysis
Port congestion at Shanghai-Ningbo and container availability constraints on Asia-Middle East trade lanes elevate inbound logistics costs for polysilicon feedstock and metallization pastes. Supply concentrates in China, India, and Vietnam for wafer casting and module assembly, with Xinjiang and Inner Mongolia anchoring high-purity polysilicon output. The chain draws from silver commodity markets, metallurgical-grade silicon, and aluminum framing materials. Single-source vulnerability around Xinjiang polysilicon smelters exposes procurement to regional electricity quota adjustments. Distribution runs through vertically integrated EPC contractors and multi-year framework agreements with independent power producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polycrystalline solar cell technology faces high-growth disruption as bifacial architectures and quasi-mono casting techniques fragment the efficiency-cost frontier. China's MIIT efficiency benchmarks and India's BIS certification requirements compress the addressable market for conventional casting methods.
For Market Incumbents: Secure captive polysilicon supply through backward integration into Xinjiang or Inner Mongolia smelter networks to defend margin structures against pure-play cell manufacturers. Anchor module assembly capacity in Gujarat and Rajasthan to capture PLI scheme incentives and reduce logistics exposure to Indian solar park procurement. Monocrystalline PERC substitution in residential rooftop segments demands selective emitter doping R&D investment to lift polycrystalline efficiency ceilings. For New Entrants and Emerging Players: Anchor in agrivoltaics and dual-use land applications across Italy and Japan where differentiated tariff treatment rewards ground-mounted bifacial deployments. Target off-grid rural electrification in sub-Saharan Africa and island Southeast Asia where durability requirements and cost minimization favor established polycrystalline supply chains. Pursue second-life module refurbishment channels through reverse logistics partnerships with European end-of-life photovoltaic recovery networks. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors quasi-mono casting specialists with furnace upgrade pathways and captive polysilicon access over conventional directional-solidification pure-plays. Long-term viability hinges on efficiency roadmap alignment with China's GB/T 6495 standards evolution and India's BIS certification trajectory. Monitor polysilicon price volatility as the primary inflection indicator for margin compression events across cell-only manufacturer portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polysilicon Supply | Xinjiang smelter access insulates margin structures from feedstock volatility and electricity quota shocks. |
| Quasi-Mono Casting Furnace Upgrades | Yangtze River Delta producers retain domestic procurement share against MIIT efficiency benchmark compression. |
| Multi-Year EPC-Plus-O&M Framework Agreements | Saudi and South African IPPs transfer operational risk to vertically integrated suppliers with captive module assembly. |
| Bifacial Module Architecture Development | Dual-sided designs capture albedo gains in Rajasthan desert installations and Saudi Sakaka ground-mounted projects. |
| Second-Life Refurbishment Channel Investment | European reverse logistics networks create aftermarket value capture for degradable but serviceable polycrystalline units. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with utility-scale project developers, EPC contractors, polysilicon procurement managers, and module quality assurance directors. Secondary validation drew from MIIT efficiency benchmark filings, BIS certification databases, FERC interconnection standards documentation, and EMA REACH compliance records. Bottom-up capacity and shipment estimates triangulated against top-down market sizing across wafer-based and thin-film technology splits.
Across the analysis window, the forecasting framework modeled product type segmentation between P-V panels, bifacial modules, and solar cell arrays alongside technology splits across wafer-based casting methods and efficiency tiers. End-use segmentation captured utility-scale, residential, commercial, and industrial demand concentration. CAGRs were derived from installed base evolution and replacement cycle analysis, with polysilicon price volatility and feed-in tariff structure adjustments serving as key sensitivity inputs.
Material uncertainties — polysilicon smelter electricity quota revisions, monocrystalline PERC substitution acceleration, and EU Ecodesign efficiency threshold tightening — sit outside the modeled envelope. Forecasts reflect assumptions around PLI scheme continuity and GB standards implementation pace. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Bifacial Solar Module Market
Solar Power Systems
Residential Solar Inverter Market
Solar Power Systems
Asia-Pacific Solar Blanket Market
Solar Power Systems
Solar Cells Market
Solar Power Systems
Organic PV Solar Cells Market
Solar Power Systems
Belgium Solar Energy Market
Solar Power Systems
Middle East and Africa Solar PV Inverters Market
Solar Power Systems
Argentina Solar Energy Market
Solar Power Systems
Perovskite Solar Module Market
Solar Power Systems
Graphene Solar Cell Market
Solar Power Systems
Chile Solar Energy Market
Solar Power Systems
Global Solar Water Heaters Market
Solar Power Systems
Czech Republic Solar Energy Market
Solar Power Systems
Residential Solar Energy Market
Solar Power Systems
Germany Distributed Solar Power Generation Market
Solar Power Systems
Solar Photovoltaics Wafer Market