
 Kazakhstan Oil and Gas Upstream Market | 2026-2036
Kazakhstan Oil and Gas Upstream Market Size, Share, and Industry Trends Forecast 2026-2036
Kazakhstan Oil and Gas Upstream Market Foresight
Kazakhstan is tilting its upstream capacity toward the Caspian offshore and super-giant onshore complexes. Chevron Corporation sustains its preeminence through operatorship of the Tengizchevroil consortium, the country's largest producing asset. Shell plc leverages deepwater drilling competence to advance exploration in the Kashagan offshore sector. PJSC Lukoil Oil Company anchors its Central Asian portfolio through stakes in the Karachaganak and Caspian Pipeline Consortium ventures.
Kazakhstan oil and gas upstream encompasses exploration, drilling, and primary hydrocarbon recovery from subsurface reservoirs, typically involving well depths of 4,000–6,500 meters and reservoir pressures exceeding 800 bar in carbonate formations. The sector supplies feedstock to domestic refineries, power generation, and export pipeline networks serving European and Asian buyers. Crude oil and natural gas dominate the resource type mix, with condensate yields rising at Karachaganak and Kashagan. Enhanced oil recovery and seismic imaging command disproportionate technology spending as brownfield decline rates steepen at mature super-giant fields.
Kazakhstan's Ministry of Energy administers subsoil use contracts through the Code on Subsoil and Subsoil Use, while the central bank and tax authority enforce local content and repatriation rules affecting foreign operators. The country's national petroleum regulator mandates environmental impact assessments and flaring reduction protocols that shape field development economics. Stakeholders must weigh fiscal term negotiations against reserve base maturity when committing capital to greenfield versus incremental recovery projects.
Market Dynamics
Kazakhstan's upstream sector faces a structural inflection as carbonate reservoir complexity at Tengiz and Kashagan forces operators toward advanced enhanced oil recovery methods while the Ministry of Energy tightens local content enforcement through subsoil code amendments.
Growth Catalysts
- Caspian offshore exploration:Kashagan's second-phase development and untapped deepwater blocks attract capital targeting 6,500-meter reservoirs with pressures exceeding 1,000 bar.
- Domestic petrochemical integration:The government's feedstock supply mandates to Atyrau and Pavlodar refineries guarantee offtake volumes for condensate-rich gas streams.
- Enhanced recovery mandates:Ministry of Energy protocols requiring 50% minimum recovery factors at mature fields drive seismic reprocessing and CO2 injection investments.
Market Restraints
- Sulphur handling costs:Tengiz and Karachaganak's 15-20% hydrogen sulphide content requires specialized metallurgy and sulphur pelletization infrastructure that consumes 12-18% of field opex.
- Single-export corridor dependence:The Caspian Pipeline Consortium's 1.4 million barrel per day capacity concentrates transit risk through Russian territory.
- Carbonate reservoir uncertainty:Fractured limestone heterogeneity at Kashagan generates 30-40% initial production variance versus pre-drill estimates.
Strategic Opportunities
- Western Mangyshlak underexploration:Legacy Soviet seismic data gaps in the Uzen and Zhetybay regions offer low-entry-cost redevelopment targets for independent operators.
- Hydrogen pilot integration:The Ministry of Energy's 2025-2030 decarbonization roadmap incentivizes grey-to-blue hydrogen conversion using Karachaganak's stranded gas.
- Digital twin deployment:Real-time reservoir simulation convergence with automated wellhead control creates 8-12% production optimization potential at brownfield assets.
Industry Challenges
- High-pressure well engineering scarcity:Only three Kazakh universities produce petroleum engineers qualified for 800-bar HPHT operations, forcing reliance on expatriate contractors.
- Local content compliance complexity:Subsoil code amendments requiring 50-70% Kazakh goods and services procurement create vendor qualification bottlenecks for specialized downhole equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kazakhstan Oil and Gas Upstream Market |
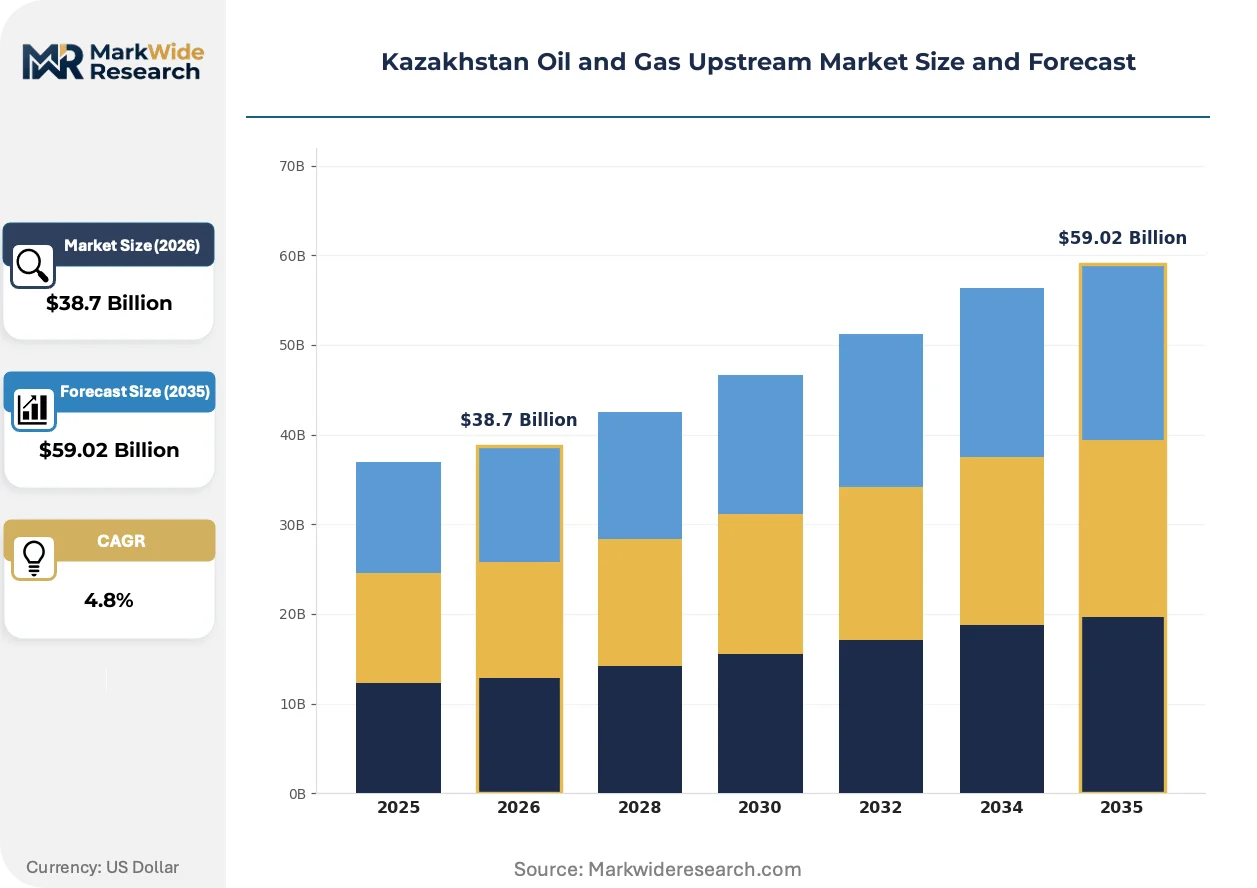
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $59.02 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Resource Type: Crude Oil, Natural Gas, Condensate, Tight Gas Extraction Method: Onshore, Offshore, Hydraulic Fracturing, Vertical Drilling Production Stage: Exploration, Development, Production, Decommissioning Technology: Seismic Imaging, Drilling Technologies, Enhanced Oil Recovery, Geo-steering |
| Companies Covered | Eni S.p.A., PJSC Lukoil Oil Company, National Company JSC (KazMunayGas), TotalEnergies SE, Shell plc, Chevron Corporation, PJSC Gazprom, MOL Group, Karachaganak Petroleum Operating B.V., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kazakhstan Oil and Gas Upstream Market Shifts & Advancements
Upstream technology trajectories in Kazakhstan center on compressing development timelines for ultra-deep carbonate reservoirs while regulatory pressure accelerates environmental compliance spending. These shifts favor integrated service providers capable of bundling subsurface imaging, drilling automation, and emissions monitoring.
Time-lapse 4D seismic acquisition is collapsing the uncertainty window between exploration and development decisions at Kashagan and Tengiz. Chevron and NC KazMunayGas joint ventures now deploy ocean-bottom node surveys annually rather than every five years. This compression enables real-time well placement adjustments that reduce dry-hole risk by 25% in fractured limestone targets.
Kazakhstan's 2021 Subsoil and Subsoil Use Code amendments impose mandatory flaring reduction targets and environmental damage deposit requirements. Operators must now secure 2% of project capex as rehabilitation bonds before drilling permits issue. The Karachaganak Petroleum Operating consortium has responded by deploying modular gas compression units to eliminate routine flaring by 2027.
Integrated service contracting is displacing discrete vendor procurement at super-giant field developments. NC KazMunayGas now awards single-source contracts spanning seismic, drilling, and completion services for entire reservoir units. This consolidation concentrates procurement power with Schlumberger and Halliburton equivalents while marginalizing regional equipment suppliers in Atyrau.
Kazakhstan Oil and Gas Upstream Market Segmentation
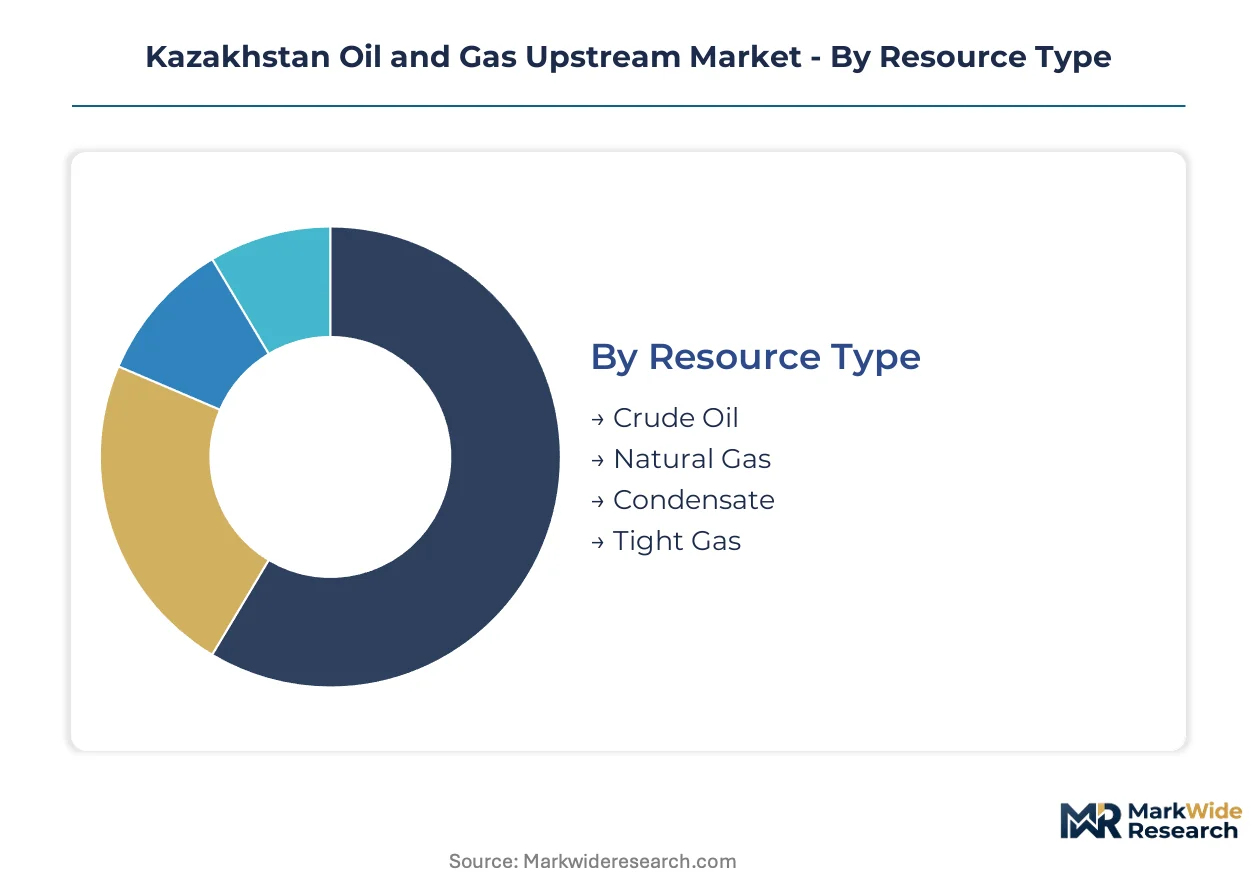
Upstream segmentation in Kazakhstan reflects the concentration of capital at super-giant carbonate fields and the regulatory pressure driving technology choices. Each dimension shapes contractor procurement, fiscal terms, and recovery economics differently across Tengiz, Kashagan, and Karachaganak.
Resource Type:
Cost tier differentiation separates high-margin condensate streams from bulk crude operations and lower-value gas disposal challenges.
- Crude Oil:Light and medium grades from Tengiz and Kashagan dominate export volumes through the Caspian Pipeline Consortium. Field operators prioritize reservoir pressure maintenance to sustain plateau rates at these carbonate formations.
- Natural Gas:Associated gas volumes at Karachaganak and Tengiz require sulfur removal and processing infrastructure. The Ministry of Energy's domestic supply mandates redirect stranded gas toward Atyrau and Pavlodar petrochemical feedstock.
- Condensate:High-value liquid yields from gas reservoirs command premium pricing.
- Tight Gas:Unconventional sandstone targets in pre-Caspian basins await commercial development.
Crude oil commands the established base. The steepest expansion runs through condensate as Kashagan phase two ramps up liquids recovery.
Extraction Method:
Application context determines capital intensity, with offshore complexity demanding integrated project teams versus modular onshore redevelopment.
- Onshore:Super-giant fields at Tengiz and Karachaganak deploy extended-reach drilling from clustered pads to minimize surface footprint. NC KazMunayGas and Chevron joint ventures concentrate brownfield investment here.
- Offshore:Kashagan's artificial islands and subsea production systems operate in shallow Caspian waters with winter ice challenges. North Caspian Operating Company manages this highest-cost production tier.
- Hydraulic Fracturing:Limited application in tight gas pilots.
- Vertical Drilling:Legacy well stock at mature Mangyshlak fields.
Onshore methods anchor current output. Offshore extraction claims the fastest-climbing share as Kashagan reaches full field development.
Production Stage:
Maturity profiles across the asset base create divergent spending patterns, from frontier exploration commitments to late-life recovery optimization.
- Exploration:Deepwater Caspian blocks and Western Mangyshlak underexplored zones attract farm-in partners. Ministry of Energy licensing rounds target 6,500-meter carbonate targets with 1,000-bar reservoir pressures.
- Development:Greenfield execution at Kashagan and Tengiz expansion projects consumes the majority of upstream capex. Integrated drilling and completion contracts compress project timelines.
- Production:Mature base management at Karachaganak and Tengiz.
- Decommissioning:Legacy Soviet-era well abandonment in Aktobe and Atyrau regions.
Production stage activities dominate current employment. Development spending shows the steepest upward trajectory through mid-decade field expansions.
Technology:
Volume leverage concentrates procurement power with service providers bundling subsurface imaging, drilling automation, and recovery optimization.
- Seismic Imaging:Time-lapse 4D ocean-bottom node surveys at Kashagan and Tengiz now deploy annually rather than every five years. Chevron and Shell operators use real-time data to reduce dry-hole risk in fractured limestone.
- Drilling Technologies:High-pressure high-temperature rigs handle 800-bar reservoir conditions at Tengiz. Only three Kazakh universities produce qualified petroleum engineers, forcing reliance on expatriate drilling contractors.
- Enhanced Oil Recovery:CO2 injection and miscible gas flood pilots target 50% minimum recovery factors mandated by subsoil code amendments.
- Geo-steering:Real-time well path adjustment in heterogeneous carbonate.
Seismic imaging holds the installed technology base. Enhanced oil recovery investment is expanding most quickly as brownfield decline rates accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Upstream investment clusters around three super-giant field complexes that concentrate drilling activity, contractor procurement, and fiscal revenue generation. The Ministry of Energy's subsoil code amendments redistribute licensing authority across administrative zones.
Atyrau Region
Tengiz and Kashagan field complexes anchor capital deployment and employment generation. The Ministry of Energy enforces 50-70% local content procurement rules through revised subsoil use contracts. Atyrau city hosts the primary logistics base for Caspian offshore operations and integrated service provider offices.
West Kazakhstan Region
Karachaganak's condensate-rich gas streams supply feedstock to the Orenburg processing plant and domestic petrochemical plants. Regional authorities implement flaring reduction protocols under 2021 environmental code amendments. Oral serves as the operational hub for Karachaganak Petroleum Operating consortium activity.
Mangyshlak Peninsula
Mature onshore fields at Uzen and Zhetybay offer low-entry redevelopment targets for secondary operators. Soviet-era seismic data gaps create exploration upside in underexplored Paleozoic formations. Aktau port infrastructure supports offshore supply logistics and Caspian Pipeline Consortium terminal operations.
Aktobe Region
Legacy Soviet well stock requires abandonment and site rehabilitation under Ministry of Energy environmental bonding rules. Independent operators target shallow conventional targets bypassed by prior state development campaigns. Aktobe city functions as the regional administrative center for subsoil use contract negotiations.
North Kazakhstan Region
Petropavlovsk refinery demand anchors domestic crude offtake agreements for northern field operators. The central bank's repatriation rules affect foreign operator cash flow management in this administrative zone. Pavlodar petrochemical integration creates guaranteed condensate demand for associated gas processing projects.
Kazakhstan Oil and Gas Upstream Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying discrete services to field developments. The market structure consolidates around consortia operating super-giant carbonate reservoirs through production-sharing agreements. Two strategic archetypes dominate: integrated international oil companies holding operatorship stakes, and national oil companies anchoring state equity participation. Competitive moves center on consortium restructuring to optimize recovery economics and integrated service contracting to compress development timelines.
Within the integrated international tier, Chevron Corporation and Shell plc occupy positions shaped by deepwater drilling competence and carbonate reservoir management expertise. Eni S.p.A. and TotalEnergies SE sit within the European major archetype, participating through non-operated stakes in Kashagan and other Caspian developments. National Company JSC KazMunayGas anchors state participation across all major producing assets, representing the national champion archetype that balances fiscal revenue objectives with technology transfer mandates.
| Leading Market Players |
|---|
| Eni S.p.A. |
| PJSC Lukoil Oil Company |
| National Company JSC (KazMunayGas) |
| TotalEnergies SE |
| Shell plc |
| Chevron Corporation |
| PJSC Gazprom |
| MOL Group |
| Karachaganak Petroleum Operating B.V. |
| Others |
Supply & Pricing Matrix
Super-giant carbonate field concentration at Tengiz and Kashagan anchors upstream supply scarcity, pushing margin capture toward integrated service providers bundling seismic, drilling, and completion contracts. The Ministry of Energy's local content mandates redistribute procurement power between international oil companies and domestic vendors, altering where value accumulates across the project lifecycle.
Pricing Analysis
Kazakhstan's 2021 Subsoil and Subsoil Use Code dictates the pricing tier structure through mandatory local content floors and environmental bonding requirements that inflate project capex. Contract-based long-term offtake agreements dominate, with price differentiation driven by sulfur content handling costs and reservoir pressure complexity. Cost compression in high-pressure high-temperature drilling services is intensifying because only three domestic universities produce qualified petroleum engineers. National oil companies show highest price sensitivity on specialized downhole equipment, while super-major operators absorb premium pricing for integrated service bundles.
Supply Chain Analysis
Upstream feedstock for Kazakhstan's oil and gas sector draws from specialized metallurgy suppliers in Germany, high-pressure drilling rig manufacturers in the United States, and seismic imaging equipment providers in Norway. Critical inputs include sour gas-resistant pipeline steel, modular gas compression units, and ocean-bottom node survey systems. Single-source vulnerability runs through the Caspian Pipeline Consortium's transit corridor through Russian territory. Distribution runs through Atyrau's logistics hub for offshore supply and Oral's operational base for Karachaganak condensate processing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Kazakhstan's upstream market fragments across mature super-giant brownfields, underexplored Paleozoic zones, and untapped deepwater blocks. The Ministry of Energy's tightening environmental codes and local content rules create specialized niches for service providers with regulatory compliance capabilities.
For Market Incumbents: Insulate consortium positions at Tengiz and Kashagan through backward integration into modular gas compression manufacturing and captive seismic processing centers in Atyrau. The 2021 subsoil code amendments threaten procurement flexibility; vertical control over sulfur pelletization infrastructure defends margin pools against local content bottlenecks. For New Entrants and Emerging Players: Build out Western Mangyshlak redevelopment capabilities targeting Soviet-era seismic data gaps at Uzen and Zhetybay, where legacy well stock offers low-entry recovery optimization contracts. Independent operators find most penetrable ground in shallow conventional targets bypassed by prior state campaigns, with go-to-market positioning around rapid digital twin deployment for brownfield assets. For Investors and Strategic Acquirers: Capital is best deployed toward integrated service providers with bundled subsurface imaging and automated wellhead control capabilities across the five-to-ten year project horizon. Acquisition targets should show established vendor qualification status under subsoil code local content rules. The signal to watch is Ministry of Energy licensing round frequency for 6,500-meter carbonate targets, which would indicate accelerated greenfield capital deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Enhanced Oil Recovery Technology Licensing | CO2 injection and miscible gas flood pilots address Ministry of Energy 50% minimum recovery mandates at mature fields. |
| Local Content Compliance Certification | Vendor qualification under revised subsoil code unlocks procurement access to Tengizchevroil and Karachaganak Petroleum Operating contracts. |
| Digital Twin Platform Integration | Real-time reservoir simulation convergence with automated wellhead control captures 8-12% production optimization at brownfield assets. |
| Modular Gas Compression Manufacturing Scale-Up | Domestic production of flaring elimination equipment satisfies environmental code amendments and local content requirements simultaneously. |
| Caspian Offshore Exploration Joint Venture | Farm-in partnerships for deepwater blocks with 1,000-bar reservoir pressures spread capital risk across Kashagan-phase-two-equivalent targets. |
Research Methodology
Desk research of subsoil use contract registries, Ministry of Energy licensing round disclosures, and Caspian Pipeline Consortium throughput filings preceded structured interviews with petroleum engineering directors, procurement leads at integrated service providers, and environmental compliance officers at field operating consortia. Secondary validation drew from national statistics agency hydrocarbon production data, central bank repatriation rule filings, and university graduate output records. Bottom-up field-level capex estimates and top-down sectoral GDP contributions were triangulated to anchor market sizing.
Assumptions around subsoil code amendment enforcement timelines and local content percentage floors were held fixed across the projection horizon, while oil price band sensitivity and sulfur handling cost inflation were varied in scenario modeling. Segmentation dimensions included resource type, extraction method, production stage maturity, and technology application intensity. CAGRs were derived from production decline curves at mature fields overlaid with greenfield development timelines, incorporating reservoir pressure maintenance spending and enhanced recovery investment trajectories specific to carbonate formation complexity.
The forecast holds incumbent behavior within observed patterns; aggressive moves by national oil companies to consolidate service provider tiers would shift outcomes. Material shifts in Caspian transit corridor stability or subsoil code local content percentage revisions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
South Sudan Oil and Gas Market
Offshore Oil and Gas
Uzbekistan Oil and Gas Upstream Market
Offshore Oil and Gas
China Oil and Gas Upstream Market
Offshore Oil and Gas
East Africa Oil and Gas Midstream Market
Offshore Oil and Gas
East Africa Natural Oil and Gas Midstream Market
Offshore Oil and Gas
Marine Mining Market
Offshore Oil and Gas
United Kingdom Offshore Oil and Gas Decommissioning Market
Offshore Oil and Gas
United Arab Emirates Oil and Gas Market
Offshore Oil and Gas
Middle East Offshore MRO Market
Offshore Oil and Gas
Azerbaijan Oil and Gas Upstream Market
Offshore Oil and Gas
Thailand Oil and Gas Downstream Market
Offshore Oil and Gas
Asia-Pacific Floating Offshore Wind Power Market
Offshore Oil and Gas
Oman Oil and Gas Downstream Market
Offshore Oil and Gas
Marine Scrubber Market
Offshore Oil and Gas
LNG Satellite Station Market
Offshore Oil and Gas
Offshore Drilling Market