
 Coal Mining Market | 2026-2036
Coal Mining Market Size, Share, and Industry Trends Forecast 2026-2036
Coal Mining Market Analysis
Aftermarket mine rehabilitation and closure liability management is rewriting where margin pools settle across the coal value chain. China Shenhua Energy leverages its captive rail-port infrastructure to sustain delivered-cost advantages in coastal Chinese markets. BHP anchors its metallurgical coal portfolio through tier-one Queensland assets that dominate seaborne premium hard coking coal supply. Peabody Energy Corp navigates Powder River Basin headwinds by specializing in domestic utility contracts with cost-flexible strip-mining operations.
Coal mining encompasses the extraction of carbonaceous sedimentary rock from surface or subsurface seams for combustion or feedstock conversion, with run-of-mine calorific values spanning 10 MJ/kg for lignite to 30 MJ/kg for anthracite depending on rank and moisture content. The primary commercial purpose centers on thermal power generation and metallurgical coke production for iron reduction in blast furnaces. Bituminous coal commands the largest value share due to its dual utility in electricity and steel applications, while surface mining leads volume output through lower stripping ratios in thick, shallow seams. Underground longwall operations concentrate in deeper, gassier deposits where mechanized shearer extraction sustains productivity despite higher capital intensity.
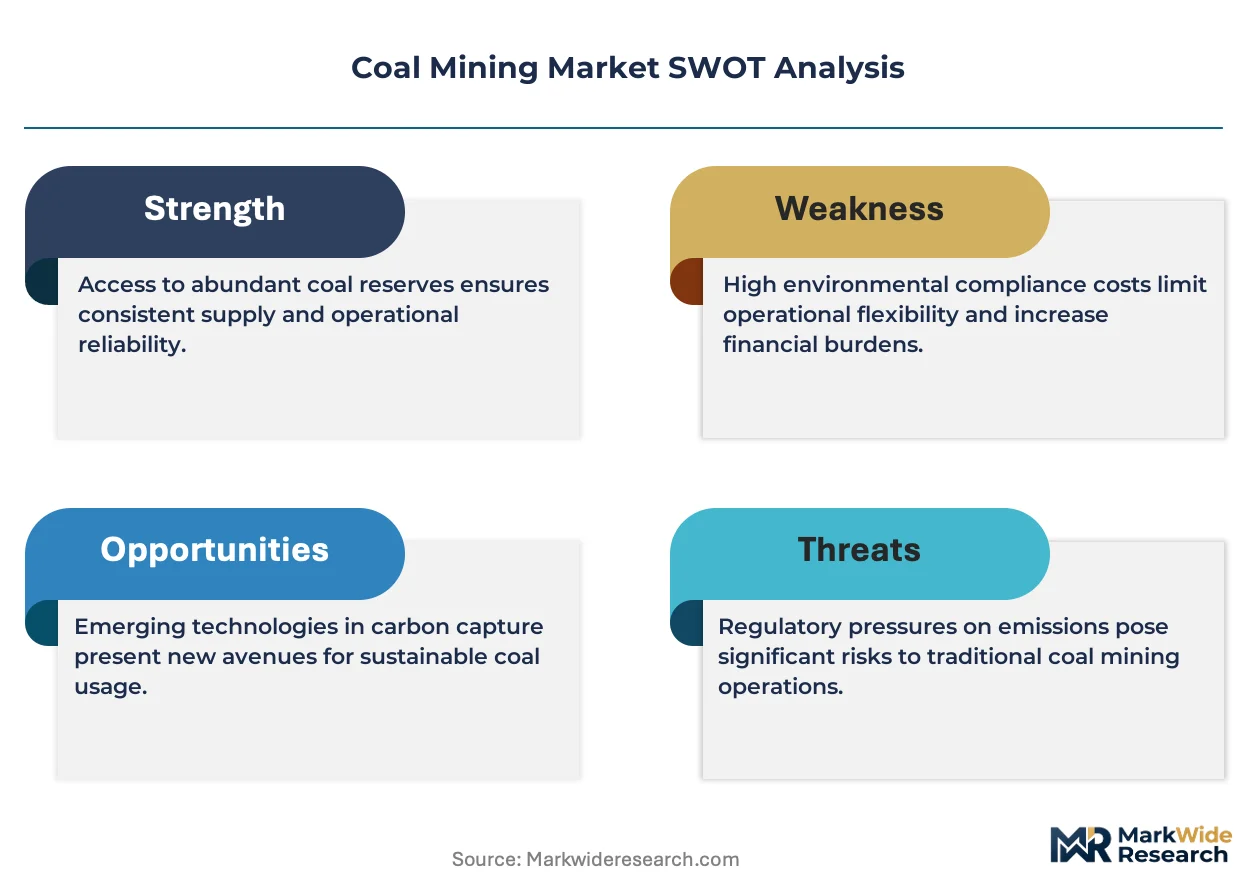
EPA coal ash regulations and Mine Safety and Health Administration ventilation mandates shape operational compliance costs and site permitting timelines across US operations. China's MEE enforces emissions caps and mine-mouth washing standards that filter market access for high-sulfur producers. India's CEA mandates coal quality monitoring and fleet efficiency benchmarks that redirect utility procurement toward washed, higher-energy product. Stakeholders must weigh stranded asset exposure against near-term cash generation as carbon border adjustments and alternative reductant pilots redefine offtake security.
Market Dynamics
China's dual carbon goals and India's CEA mandates are compressing thermal coal expansion timelines while metallurgical coal demand from steelmakers sustains selective investment. This regulatory divergence is fragmenting capital deployment across the value chain.
Growth Catalysts
- Steel decarbonization timelines:Metallurgical coal retains irreplaceable blast-furnace feedstock status as hydrogen-based direct reduction remains pre-commercial at scale.
- India's CEA quality mandates:Washed coal procurement requirements redirect utility offtake toward higher-calorific product, upgrading mine-mouth economics.
- Longwall automation:Shearer automation and roof support integration sustain productivity in deeper, gassier deposits where labor costs escalate.
Market Restraints
- Carbon border adjustment exposure:EU CBAM phase-in threatens seaborne thermal coal competitiveness in European power markets.
- Capital intensity escalation:Underground longwall installations require sustained capex commitments that conflict with shortened asset-life assumptions.
- Renewable substitution:Utility-scale solar and wind with battery storage displace baseload coal contracts in procurement auctions.
Strategic Opportunities
- Underpenetrated metallurgical demand:Southeast Asian blast furnace capacity expansion creates seaborne premium hard coking coal offtake beyond Chinese import substitution.
- Mine rehabilitation services:Closure liability management and post-mining land use conversion open recurring revenue streams as legacy sites proliferate.
- Coal-to-chemicals pivot:Coal gasification for methanol and ammonia production leverages stranded thermal assets in regions with petrochemical demand growth.
Industry Challenges
- Specialized mining engineering shortage:Longwall system operators and ventilation engineers face generational workforce attrition without adequate training pipeline replacement.
- Legacy methane monitoring integration:Retrofitting continuous emissions monitoring into aged underground infrastructure strains operational budgets and downtime windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coal Mining Market |
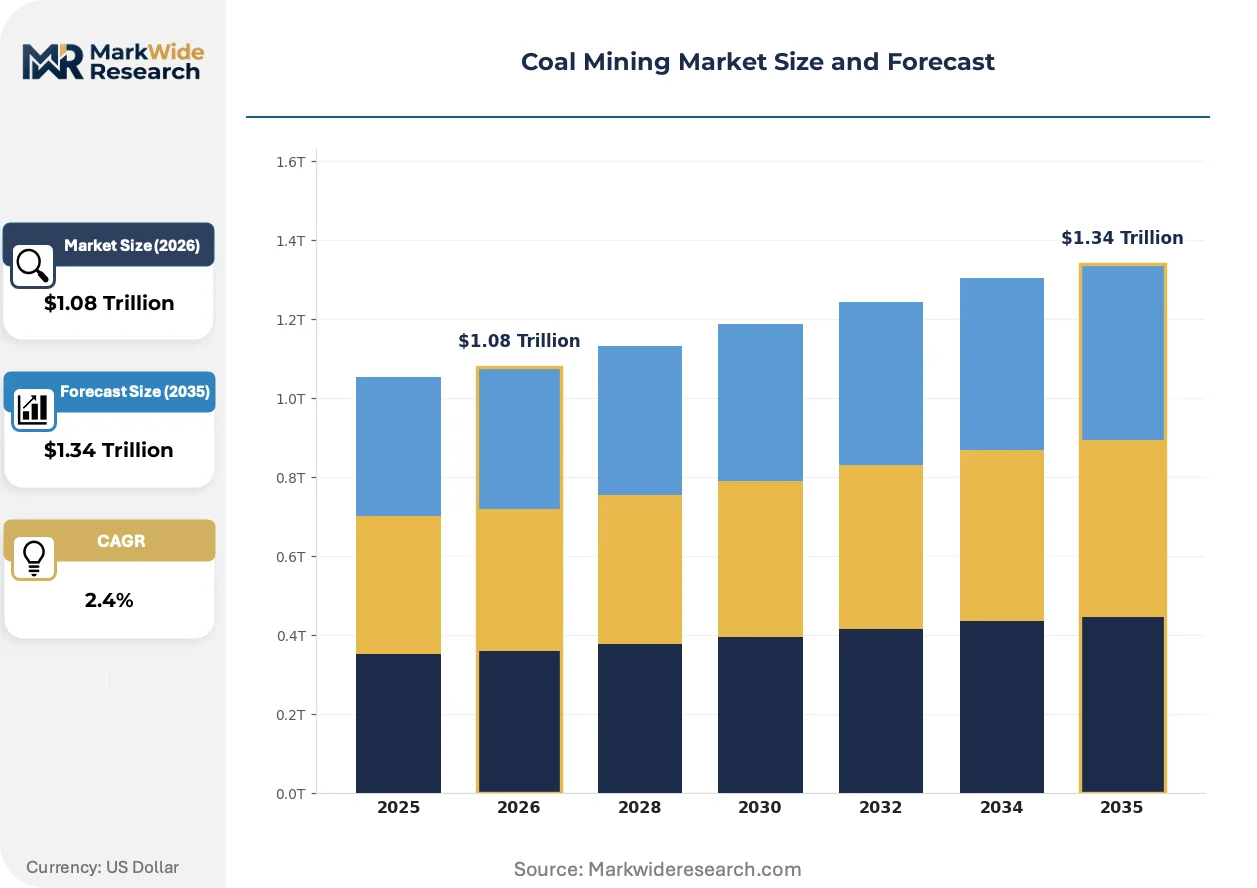
| Market Size in 2026 | $1.08 Trillion |
| Market Size in 2035 | $1.34 Trillion |
| CAGR (2026 – 2036) | 2.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bituminous Coal, Anthracite Coal, Lignite Coal, Sub-bituminous Coal Mining Technique: Surface Mining, Underground Mining, Room and Pillar Mining, Longwall Mining End User: Electric Utilities, Cement Industry, Steel Manufacturing, Chemical Industry Distribution Channel: Direct Sales, Wholesale, Online Sales, Retail |
| Companies Covered | China Shenhua Energy, Coal India, BHP, Rio Tinto, Peabody Energy Corp, Core Natural Resources, Anglo American plc, Yankuang Energy, Teck Resources, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coal Mining Market Emerging Trajectories
Autonomous extraction systems and emissions accountability frameworks are redefining operational viability thresholds. Technology convergence with environmental compliance is compressing the margin for conventional practice.
Longwall automation is hybridizing shearer-cutting sequences with real-time roof geology sensing. Australian and Chinese underground operators deploy these integrated systems to sustain output in deeper seams where manual operation becomes uneconomical. The technology is hybridizing labor models toward remote surface monitoring centers that consolidate multiple mine oversight.
China's MEE enforces mine-mouth washing standards and emissions caps that filter market access for high-sulfur producers. Compliance costs redirect investment toward beneficiation infrastructure rather than greenfield thermal capacity. Seaborne exporters to Chinese coastal markets face quality premiums that reward low-ash, low-sulfur product differentiation.
Utility procurement is consolidating around multi-year offtake contracts with coal quality guarantees rather than spot-market exposure. Indian state electricity boards and Southeast Asian independent power producers favor supply security over price volatility. This contractual preference shift concentrates supplier relationships toward integrated miners with captive rail-port infrastructure.
Coal Mining Market Segmentation
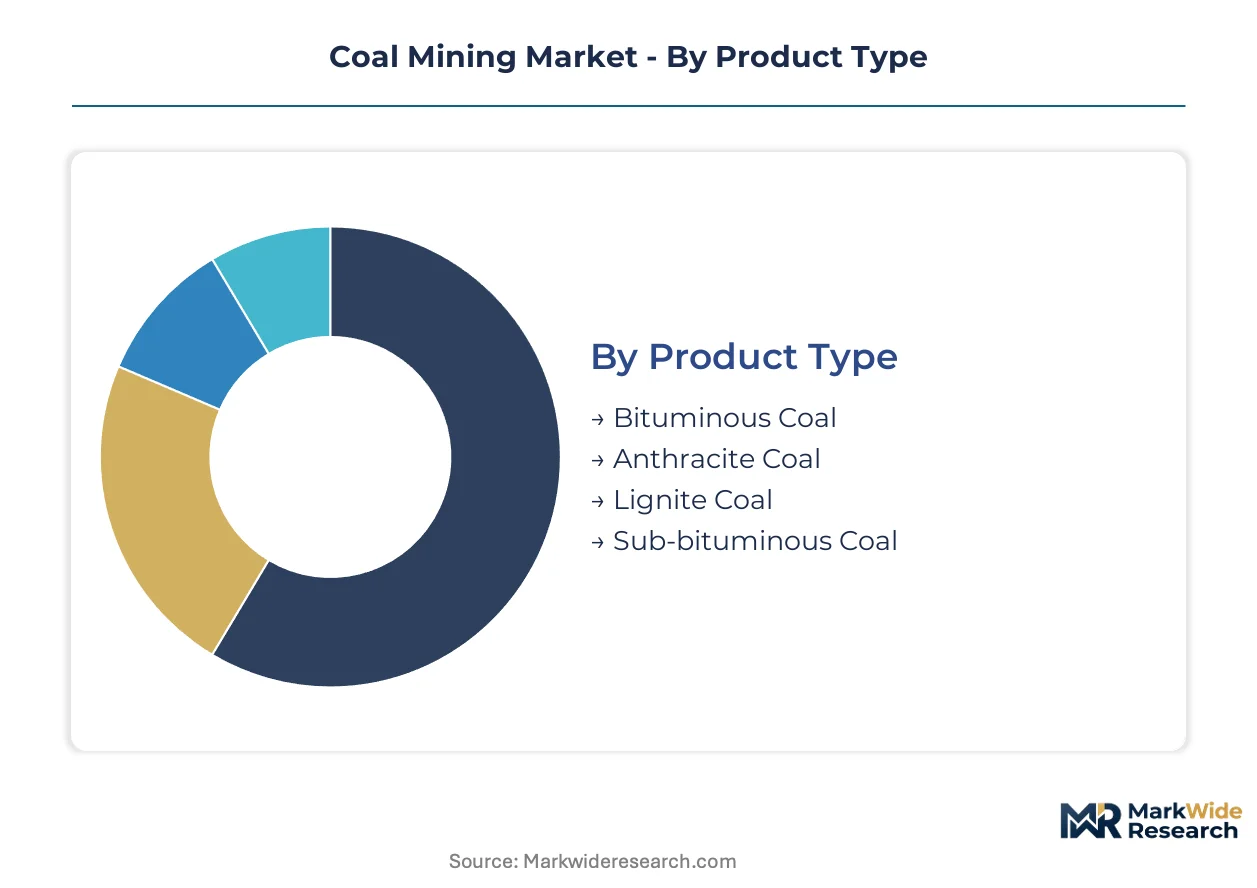
Coal mining segmentation reveals how calorific value, extraction economics, and end-use specifications fragment procurement patterns across power generation and metallurgical feedstock channels. Product rank and mining method together determine delivered cost structures that reshape competitive positioning in regional markets.
Product Type:
Calorific value and carbon content differentiate coal economics across combustion and industrial reduction applications.
- Bituminous Coal:Intermediate-to-high rank coal delivers 24-30 MJ/kg energy density with moderate volatile matter, serving dual utility in thermal power generation and metallurgical coke production. Steel manufacturers in India and China concentrate procurement on low-sulfur, low-ash variants that meet blast furnace permeability requirements.
- Anthracite Coal:Highest-rank coal with carbon content exceeding 90% and minimal volatile matter provides concentrated heat output for residential heating and specialized industrial processes. Residential and small industrial consumers in Northeastern US and Eastern European markets sustain niche demand despite premium pricing over bituminous alternatives.
- Lignite Coal:Low-rank deposits with high moisture content dominate mine-mouth power generation in Germany, Poland, and parts of India where low extraction costs offset transportation inefficiencies.
- Sub-bituminous Coal:Intermediate energy density coal from the Powder River Basin feeds domestic US utility contracts with low sulfur content that satisfies EPA emissions standards without washing infrastructure.
Bituminous coal commands the established base across steel and power applications. The steepest expansion runs through metallurgical-grade bituminous as Southeast Asian blast furnace capacity climbs.
Mining Technique:
Capital intensity and labor productivity tradeoffs determine method selection based on seam depth, thickness, and geology.
- Surface Mining:Strip and open-pit methods exploit thick, shallow seams with stripping ratios below 15:1, minimizing labor requirements and enabling rapid production scaling. Australian and Indonesian thermal coal exporters leverage this method to sustain delivered-cost advantages in seaborne markets.
- Underground Mining:Shaft and slope access methods penetrate deeper deposits where surface methods become uneconomical, requiring ventilation and methane management infrastructure that elevates operating complexity.
- Room and Pillar Mining:Selective extraction with retained coal pillars stabilizes roof conditions in gassy, faulted seams where longwall retreat is impractical.
- Longwall Mining:Mechanized shearer systems with automated roof support achieve maximum recovery in uniform, deep seams where labor cost escalation demands productivity concentration.
Surface mining anchors volume output through cost efficiency. Longwall automation is gaining share fastest where labor scarcity and depth economics converge.
End User:
Application-specific quality requirements and contract structures redirect mine output toward distinct value pools.
- Electric Utilities:Baseload power generators prioritize supply security through multi-year offtake agreements with calorific and sulfur specifications that align with scrubber investments and fleet efficiency mandates.
- Steel Manufacturing:Blast furnace operators require premium hard coking coal with specific caking properties, CSR values, and low phosphorus content that commands price premiums over thermal grades.
- Cement Industry:Kiln operators absorb mid-tier thermal coal with moderate ash content, substituting alternative fuels where carbon costs escalate.
- Chemical Industry:Coal gasification and carbon black producers seek specific volatile matter and sulfur profiles for feedstock conversion to ammonia, methanol, and specialty chemicals.
Electric utilities represent the largest volume sink. Steel manufacturing offers the strongest margin expansion as premium coking coal supply tightens.
Distribution Channel:
Logistics integration and contract duration shape how coal moves from mine mouth to combustion or conversion.
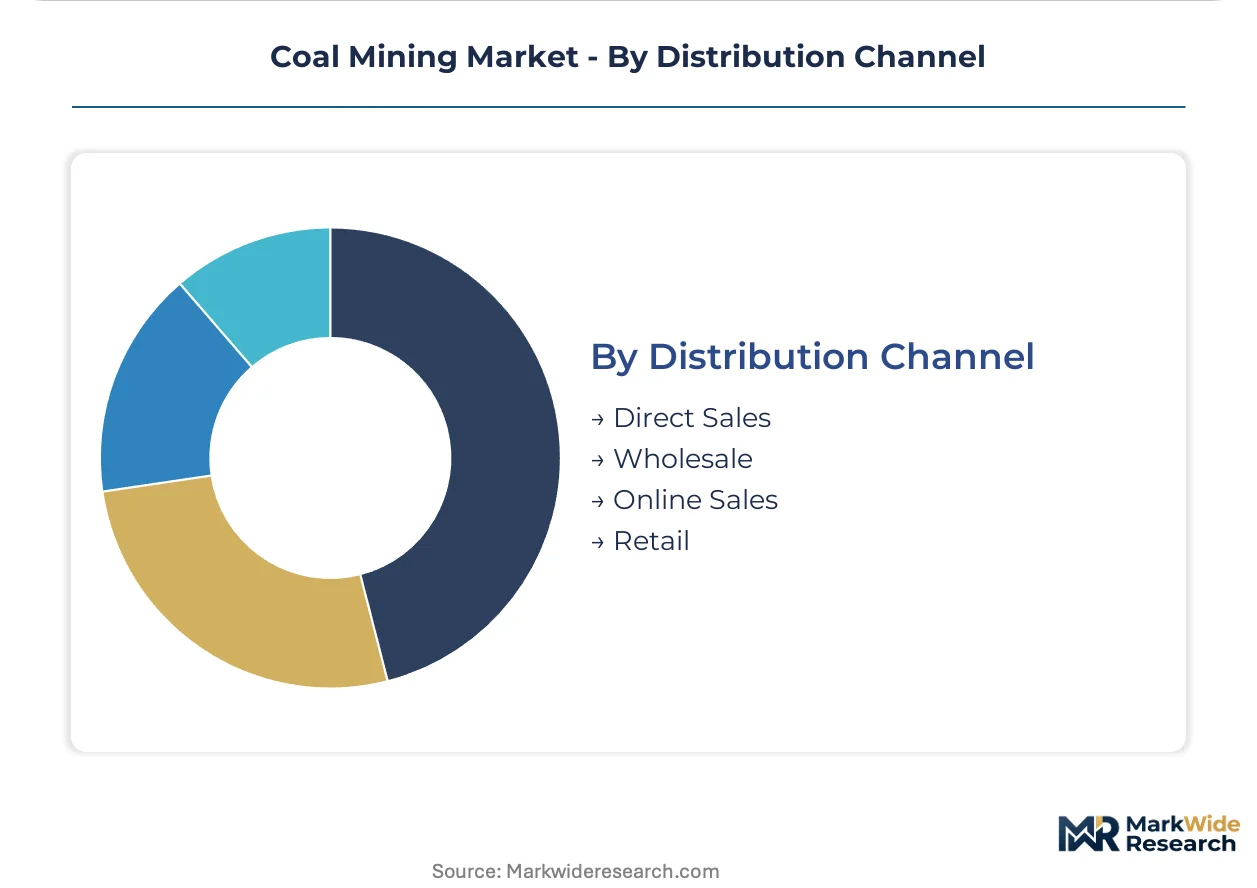
- Direct Sales:Captive rail-port infrastructure and long-term supply agreements connect integrated miners directly to utility and steel customers, eliminating intermediary margins.
- Wholesale:Trading houses and aggregators consolidate volumes from smaller producers for resale to utilities lacking procurement scale or seeking spot-market flexibility.
- Online Sales:Digital platforms for standardized thermal coal grades emerge in Chinese domestic markets, though physical delivery logistics limit penetration.
- Retail:Bagged anthracite and specialty coal products reach residential heating and small industrial consumers through regional distributors.
Direct sales dominate value capture through infrastructure control. Wholesale channels expand most quickly as merchant trading aggregates fragmented supply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian power utilities demonstrate the lowest price elasticity as Coal India secures long-term supply agreements, while European buyers face acute cost sensitivity under EU CBAM phase-in. Chinese coastal markets split the difference, rewarding quality premiums but punishing high-sulfur delivered costs.
China
Steel mills in Tangshan and Baotou sustain metallurgical coal intake despite blast furnace efficiency mandates. MEE emissions caps and mine-mouth washing standards filter market access for high-sulfur producers. Shaanxi and Inner Mongolia concentrate thermal output where Shenhua's captive rail-port infrastructure controls delivered-cost positioning.
India
State electricity boards in Maharashtra and Gujarat absorb rising volumes through Coal India linkages as renewable buildouts lag demand growth. CEA quality mandates redirect procurement toward washed, higher-calorific product. The Singareni Collieries cluster in Telangana upgrades beneficiation capacity to meet utility specifications.
Australia
Queensland's Bowen Basin anchors seaborne premium hard coking coal supply as Asian blast furnace expansion sustains offtake. EPA-equivalent state environmental authorities enforce rehabilitation bonds that elevate closure liability planning. Hunter Valley thermal operations face contracting utility contract durations as LNG and renewables displace baseload coal.
United States
Powder River Basin strip mines feed domestic utility contracts with cost-flexible operations as export markets narrow. EPA coal ash regulations and MSHA ventilation mandates shape compliance costs and permitting timelines. Appalachian metallurgical producers in West Virginia and Pennsylvania concentrate on low-volatile coking coal for domestic steel and specialty export grades.
Indonesia
Kalimantan surface mines sustain delivered-cost advantages in seaborne thermal markets through low stripping ratios and labor efficiency. Domestic power plant buildouts under the 35 GW program absorb growing mine-mouth volumes. The Tarakan and Berau clusters concentrate export infrastructure investment as European demand contracts.
Coal Mining Market Vendor Landscape
Capability concentration sits with integrated miners controlling captive logistics; scale advantage sits with state-backed producers commanding domestic market access. The vendor base stratifies across three tiers: diversified resource majors with metallurgical specialization, national champions with monopoly thermal positions, and regional strip-mining operators serving contracted utility offtake. Dominant competitive moves include portfolio divestment of thermal assets and backward integration into rail-port infrastructure to secure delivered-cost positioning.
Within the national champion tier, Coal India and China Shenhua Energy exemplify state-backed scale advantage through domestic market dominance and vertical logistics control. Among diversified resource majors, BHP occupies a position representing metallurgical coal portfolio concentration through tier-one Queensland assets. Peabody Energy Corp sits within the regional operator archetype, navigating Powder River Basin headwinds through cost-flexible strip-mining and domestic utility contract specialization.
| Leading Market Players |
|---|
| China Shenhua Energy |
| Coal India |
| BHP |
| Rio Tinto |
| Peabody Energy Corp |
| Core Natural Resources |
| Anglo American plc |
| Yankuang Energy |
| Teck Resources |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Indonesian Kalimantan surface operations compresses realized prices across seaborne thermal grades while simultaneously forcing suppliers toward longer contract tenors and quality upgrades to defend margin. This utilization dynamic reshapes procurement negotiations as buyers extract concessions through volume commitments.
Pricing Analysis
Long-term offtake contracts dominate metallurgical coal procurement as steelmakers prioritize supply security over spot-market volatility. Premium hard coking coal commands substantial premiums over thermal grades based on CSR values and phosphorus content. Cost compression in Powder River Basin thermal supply intensifies as renewable substitution accelerates domestic utility contract renegotiations. European buyers exhibit acute price sensitivity under EU CBAM phase-in, while Indian state electricity boards demonstrate lowest elasticity through Coal India linkages.
Supply Chain Analysis
Tariff exposure between Australia and China reshapes seaborne coking coal routing as Mongolian rail capacity expands alternative supply corridors. Mine output concentrates in Australia, Indonesia, and China. Production draws from diesel fuel, explosives, and steel consumables for longwall equipment. Single-source vulnerability runs through Queensland port congestion during cyclone seasons. Distribution runs through captive rail-port infrastructure controlled by integrated miners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as metallurgical coal quality mandates split procurement between premium seaborne supply and domestic beneficiation upgrades. Steel decarbonization timelines create divergent investment horizons across thermal and coking segments.
For Market Incumbents: Harden metallurgical coal portfolio positioning through tier-one Queensland asset concentration as hydrogen-based direct reduction threatens long-term blast furnace feedstock demand. Defend margin structure by deepening backward integration into captive rail-port infrastructure that controls delivered-cost positioning against seaborne competitors. Prioritize longwall automation deployment to offset generational workforce attrition in underground operations. For New Entrants and Emerging Players: Pursue mine rehabilitation and closure liability management services as legacy site proliferation accelerates across Australia and the United States. Southeast Asian blast furnace capacity expansion offers the most penetrable metallurgical demand growth corridor beyond Chinese import substitution. Establish contractual relationships through direct sales to independent power producers seeking supply security over trading house intermediation. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across surface mining operations as strip-mining technology improves and labor efficiency gains compress unit costs. Five-to-ten year viability framing favors metallurgical specialization over thermal exposure given steel decarbonization uncertainty. Target integrated miners with captive logistics and premium coking coal reserves. Monitor EU CBAM implementation pace as the critical signal for European thermal coal demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Longwall Automation Deployment | Shearer automation sustains productivity in deeper Australian and Chinese seams where labor costs escalate. |
| Backward Integration into Rail-Port Infrastructure | China Shenhua's captive logistics model demonstrates delivered-cost control in coastal Chinese markets. |
| Metallurgical Coal Portfolio Concentration | BHP's Queensland coking coal assets anchor seaborne premium hard coking coal supply to Asian steelmakers. |
| Mine Rehabilitation Services Expansion | Closure liability management opens recurring revenue as EPA and state environmental authorities enforce rehabilitation bonds. |
| Coal-to-Chemicals Pivot | Gasification for methanol and ammonia production leverages stranded thermal assets in regions with petrochemical demand growth. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of company filings, customs and trade databases, and national energy statistics. Mine operations managers, utility procurement officers, steel mill raw materials directors, and rail-logistics coordinators provided operational perspective. Secondary validation drew from EIA thermal coal data, IEA energy outlooks, FERC infrastructure filings, and state environmental authority enforcement records. Bottom-up mine-level capacity assessment triangulates against top-down national production targets.
Forecast inputs incorporate coal rank segmentation, mining method economics, end-use demand channels, and regional regulatory frameworks across the analysis window. Product type, mining technique, end user category, and distribution channel dimensions structure the analytical framework. CAGRs derive from production capacity trajectories, demand elasticity by buyer archetype, and policy-driven demand destruction timelines. Steel decarbonization pilot scale and renewable substitution rates in power generation constitute industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by state-backed national champions or diversified resource majors would shift outcomes beyond modeled ranges. Regulatory acceleration in emissions caps, carbon border adjustments, or mine safety mandates could compress asset lives faster than projected. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Middle East Wireline Logging Services Market
Oil & Gas
Oil and Gas Separation Equipment Market
Oil & Gas
Algeria Oil and Gas Upstream Market
Oil & Gas
Southeast Asia Oil and Gas Market
Oil & Gas
North America Oil and Gas Line Pipe Market
Oil & Gas
Well Cementing Market
Oil & Gas
Mud Logging Unit Market
Oil & Gas
Russia Oilfield Services Market
Oil & Gas
Nigeria Oil and Gas Market
Oil & Gas
Sidetracking Market
Oil & Gas
Colombia Oil and Gas Midstream Market
Oil & Gas
Vietnam Oil and Gas Market
Oil & Gas
West Africa Oil and Gas Midstream Market
Oil & Gas
Drilling and Completion Fluids Market
Oil & Gas
Subsea Boosting Systems Market
Oil & Gas
Asia-Pacific Oil Country Tubular Goods Market