
 Europe Oil and Gas Drones Market | 2026-2036
Europe Oil and Gas Drones Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Oil and Gas Drones Market Foresight
EASA's Specific Category certification under EU Regulation 2019/947 is redrawing competitive access across the European unmanned aerial systems landscape. Cyberhawk Innovations Limited leverages its offshore inspection pedigree to anchor North Sea contracts. DJI Enterprise competes through manufacturing scale and sensor integration density. Sky-Futures Limited specializes in predictive analytics layers atop raw drone imagery.
Europe oil and gas drones are unmanned aerial vehicles rated for hydrocarbon facility operations, typically carrying payloads exceeding 10 kg with flight endurance of 45-90 minutes and ATEX-certified components for Zone 2 proximity work; they execute flare stack inspection, pipeline corridor monitoring, and methane leak detection without manned helicopter exposure. Multi-rotor platforms dominate near-field refinery work due to hovering precision and obstacle tolerance, while fixed-wing systems capture longer linear pipeline surveys at higher transit speeds. Thermal imaging technology commands premium positioning where fugitive emission detection mandates drive sensor specification minimums.
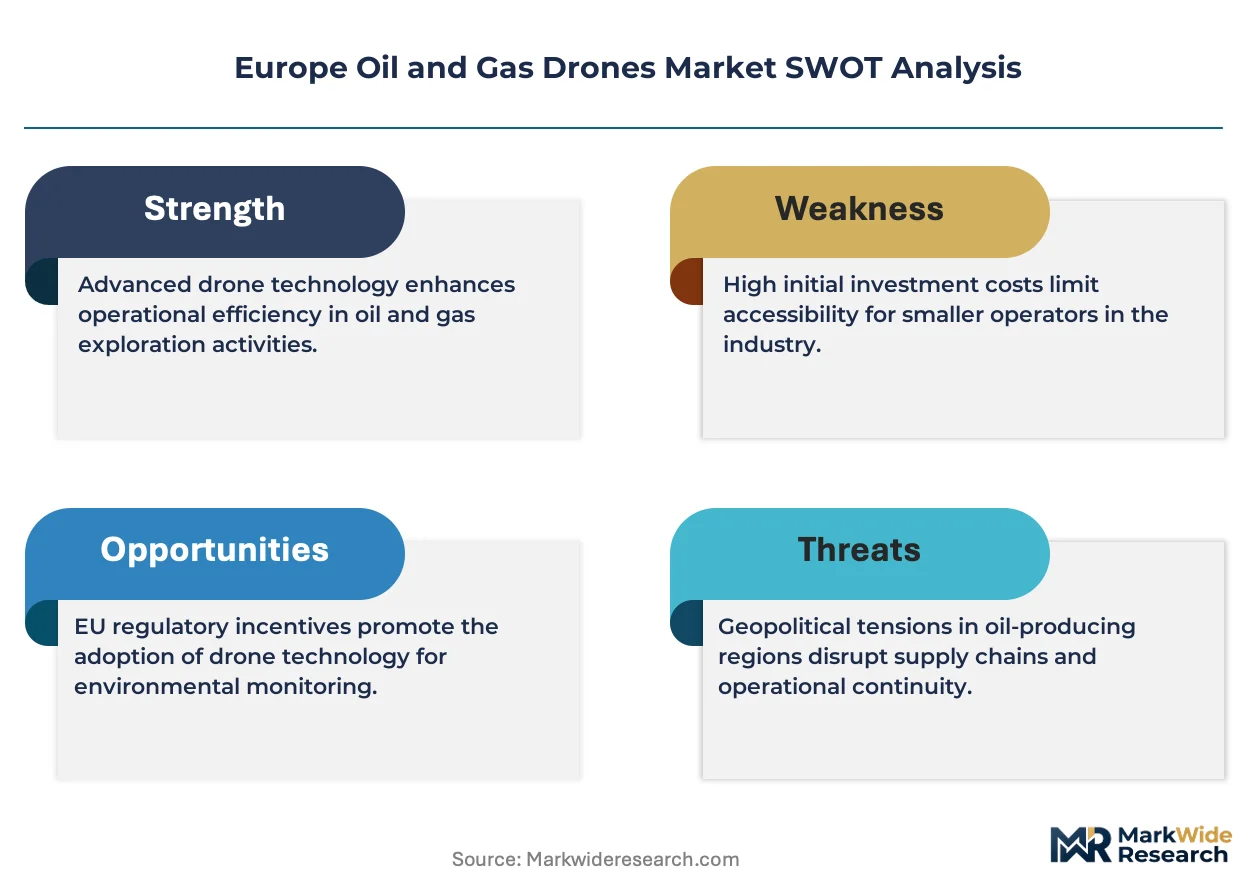
EU Regulation 2019/947, the F-Gas Regulation, and national civil aviation authorities including Norway's CAA-N and the UK's CAA jointly determine operational altitude waivers, sensor calibration standards, and environmental compliance thresholds for hydrocarbon sector deployment. EASA's ongoing standardization of detect-and-avoid systems will determine which operators gain routine beyond-visual-line-of-sight approvals. Stakeholders must weigh certification investment timelines against the operational cost savings that certified autonomy unlocks.
Market Dynamics
EASA's Specific Category framework under EU Regulation 2019/947 is compressing certification timelines for beyond-visual-line-of-sight operations, unlocking routine deployment across North Sea hydrocarbon infrastructure. This regulatory acceleration is redrawing competitive access for inspection service providers.
Growth Catalysts
- EU Regulation 2019/947:EASA's risk-based operational authorization system is expanding certified flight envelopes for offshore platform inspection, reducing waiver processing from months to weeks.
- Flare stack inspection:Manned helicopter exposure elimination is driving procurement of ATEX-certified multi-rotor systems with thermal payloads for live refinery work.
- North Sea corridor:Pipeline operators across Norway, UK, and Denmark are consolidating drone service contracts under multi-year framework agreements.
Market Restraints
- Sensor cost concentration:Thermal imaging and methane detection payloads rely on germanium optics and cooled detector arrays subject to supply bottlenecks.
- Detect-and-avoid gaps:EASA has not yet standardized autonomous collision avoidance, forcing operators to maintain costly visual observer networks.
- Fixed-wing substitution:Long-range pipeline surveys face competition from satellite-based synthetic aperture radar monitoring at lower per-kilometer cost.
Strategic Opportunities
- Netherlands offshore:Port of Rotterdam hydrogen conversion projects are creating demand for drone-based construction monitoring and leak detection services.
- F-Gas Regulation alignment:Mandatory refrigerant leak inspection intervals are expanding addressable market for optical gas imaging drones in LNG terminals.
- AI-photogrammetry convergence:Automated defect classification is compressing analysis timelines from days to hours, enabling predictive maintenance contracts.
Industry Challenges
- Pilot certification throughput:EASA's remote pilot competency requirements are creating bottlenecks as demand outpaces training capacity.
- Legacy SCADA integration:Drone data streams require custom middleware to interface with existing asset management platforms at major operators.
- ATEX recertification cycles:Zone 2 proximity equipment mandates periodic component validation, extending fleet refresh timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Oil and Gas Drones Market |
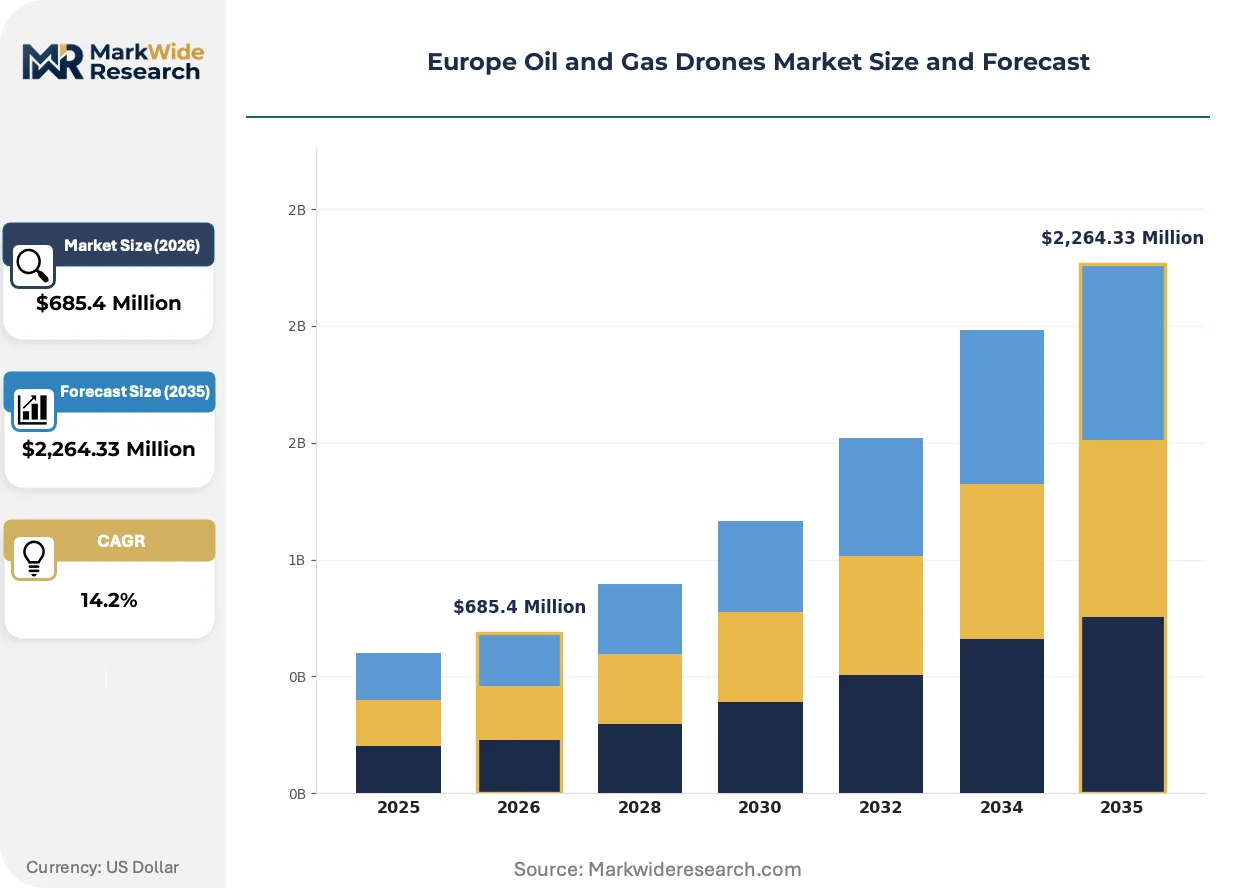
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $2,264.33 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drone Type: Fixed-Wing, Multi-Rotor, Single Rotor, Hybrid Application: Inspection, Monitoring, Surveying, Mapping End User: Exploration Companies, Production Firms, Pipeline Operators, Service Providers Technology: Autonomous Flight, GPS Navigation, Thermal Imaging, Data Analytics |
| Companies Covered | Sky-Futures Limited, Sharper Shape Inc., Cyberhawk Innovations Limited, AeroVironment Inc., Phoenix LiDAR Systems, Airobotics Ltd, Viper Drones, DJI Enterprise, Terra Drone Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Oil and Gas Drones Market Shifts & Advancements
Sensor payload architecture is fragmenting into application-specific configurations, while regulatory automation and procurement model compression are restructuring vendor-client relationships across European hydrocarbon operations.
Solid-state lidar is miniaturizing. These chip-scale ranging modules enable centimeter-precision obstacle avoidance without mechanical spinning assemblies. Offshore platform operators in Norway are specifying solid-state units for confined-space inspection. The technology is miniaturizing payload budgets, allowing twin-sensor configurations previously requiring separate flights.
EU Regulation 2019/947's standardization of specific operational risk assessments is displacing national variance in beyond-visual-line-of-sight approvals. Harmonized detect-and-avoid performance requirements are emerging through EASA rulemaking. Offshore inspection providers with prior North Sea certifications are capturing first-mover advantage in cross-border service expansion.
Service contract unbundling is fragmenting traditional full-stack drone offerings. Major operators are separating hardware procurement from data analytics, creating openings for specialized software vendors. This disaggregation is most visible in UK North Sea operations, where Aker BP and Shell have moved to multi-vendor frameworks with distinct sensor, flight, and analysis tiers.
Europe Oil and Gas Drones Market Segmentation
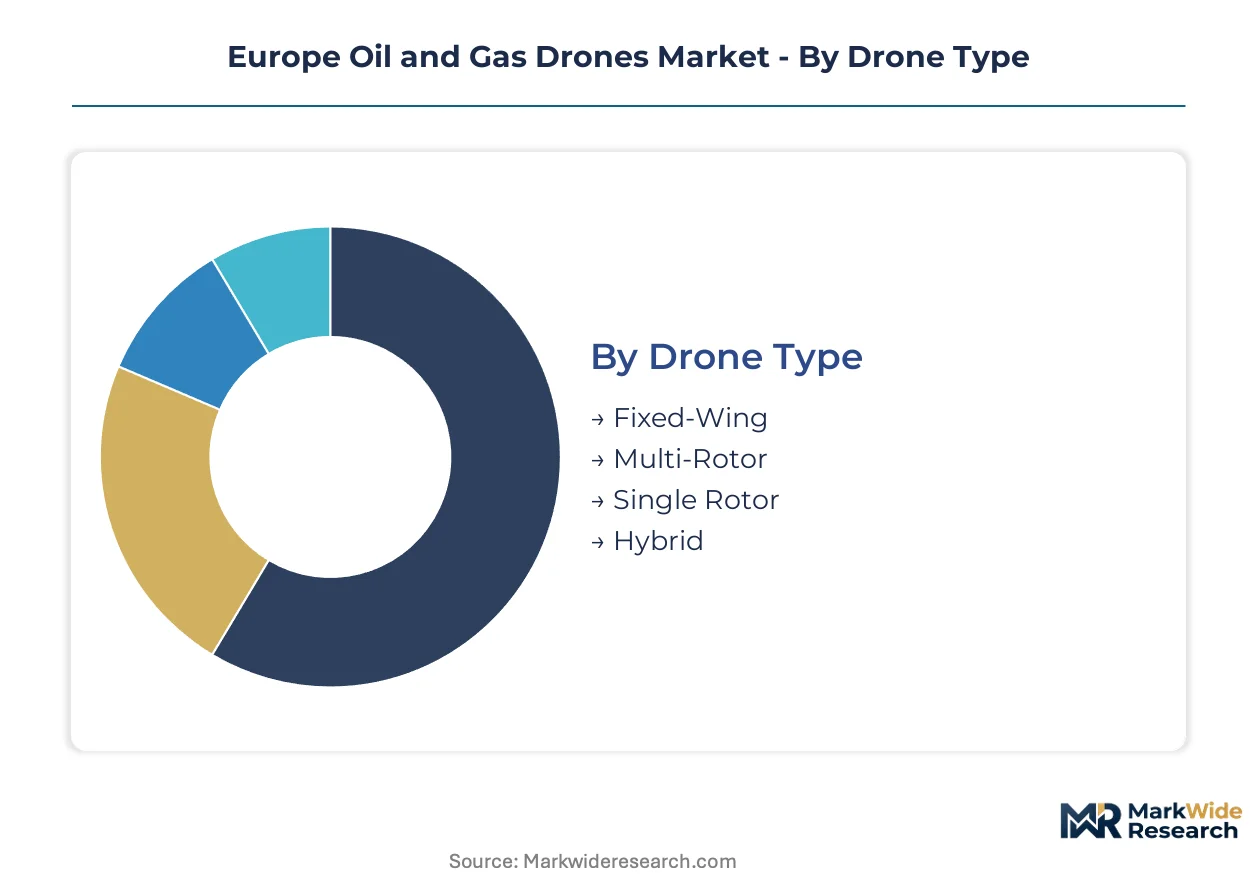
Drone configuration choices in European hydrocarbon operations trace directly to EASA certification pathways and payload requirements. Each segmentation dimension reflects distinct procurement priorities across North Sea infrastructure, refinery complexes, and pipeline corridors.
Drone Type:
EASA's Specific Category risk assessments differentiate flight envelope permissions by platform architecture, with endurance and payload capacity determining operational authorization tiers.
- Multi-Rotor:Vertical takeoff and landing capability with six to eight propeller configurations dominates offshore platform work. Equinor specifies these for flare stack inspection where hovering precision eliminates manned helicopter exposure over live hydrocarbon facilities.
- Fixed-Wing:Extended range platforms with 90-120 minute endurance capture linear pipeline surveys across the UK-Norway corridor. Pipeline operators consolidate multi-year framework agreements around these systems for subsea corridor monitoring where transit speed outweighs maneuverability.
- Single Rotor:Helicopter-style platforms with higher payload ceilings serve specialized methane detection missions requiring dual-sensor configurations.
- Hybrid:Convertible VTOL-fixed-wing designs merge takeoff flexibility with cruise efficiency for remote North Sea installations.
Multi-Rotor handles the majority of throughput; Hybrid designs are expanding most quickly on share as operators seek single-platform versatility.
Application:
Procurement patterns align with asset lifecycle stages, from construction-phase surveying through decommissioning inspection.
- Inspection:ATEX-certified flight operations over live refinery equipment, flare stacks, and pressure vessels drive premium sensor specifications. Thermal imaging payloads detect insulation degradation and refractory failures without production shutdowns.
- Monitoring:Continuous methane leak detection and corrosion assessment across Denmark's pipeline network. F-Gas Regulation alignment expands optical gas imaging mandates at LNG terminals.
- Surveying:Pre-construction seabed mapping and as-built verification for Port of Rotterdam hydrogen conversion projects.
- Mapping:Photogrammetric terrain capture for pipeline route planning and environmental baseline documentation.
Inspection commands the dominant procurement volume; Monitoring is climbing the fastest as predictive maintenance contracts displace reactive schedules.
End User:
Customer sophistication varies by asset ownership structure and in-house aviation capability.
- Pipeline Operators:Cross-border infrastructure owners across Norway, UK, and Denmark consolidate drone service contracts under multi-vendor frameworks with distinct flight, sensor, and analysis tiers.
- Production Firms:Aker BP and Shell field operations drive North Sea inspection service procurement with stringent data integration requirements into legacy SCADA systems.
- Exploration Companies:Seismic survey coordination and frontier basin reconnaissance with lower flight frequency but higher per-mission payload demands.
- Service Providers:Specialized inspection contractors capturing outsourced flight operations from operators divesting in-house aviation units.
Pipeline Operators account for the largest contract value; Service Providers are gaining share fastest as asset owners unbundle full-stack procurement.
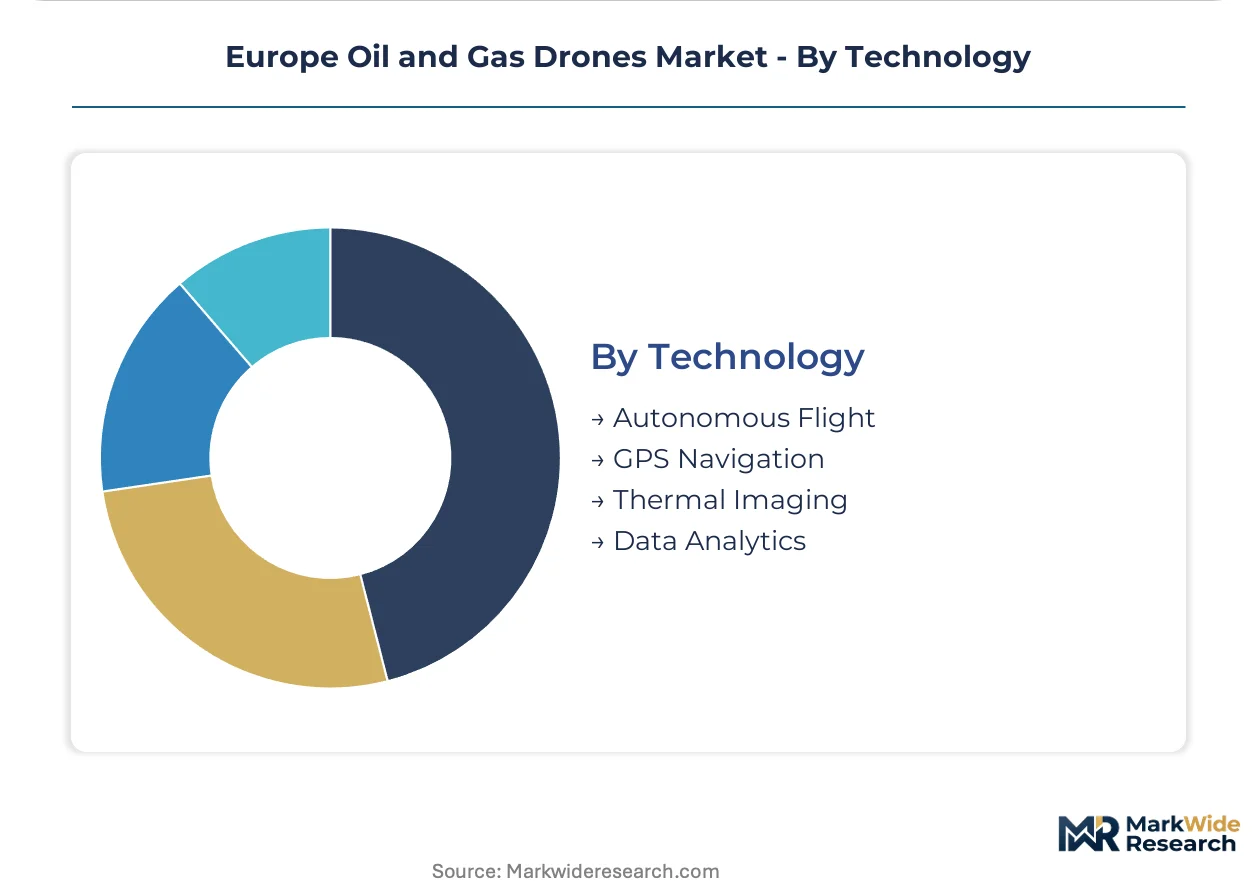
Technology:
Technology stack choices determine regulatory compliance depth and data output quality.
- Thermal Imaging:Cooled detector arrays with germanium optics enable fugitive emission detection and electrical hotspot identification. Supply bottlenecks in detector manufacturing constrain fleet expansion timelines.
- Autonomous Flight:EASA's pending detect-and-avoid standardization will determine which operators gain routine beyond-visual-line-of-sight approvals for offshore platform work.
- Data Analytics:AI-photogrammetry convergence compresses defect classification from days to hours, enabling predictive maintenance contracting models.
- GPS Navigation:RTK-GNSS precision for centimeter-level georeferencing of inspection findings against digital twin baselines.
Thermal Imaging anchors the highest-value deployments; Autonomous Flight is the steepest expansion trajectory as certification timelines compress.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EASA's Specific Category framework under EU Regulation 2019/947 is compressing certification timelines for beyond-visual-line-of-sight operations, unlocking routine deployment across North Sea hydrocarbon infrastructure. This regulatory acceleration is redrawing competitive access for inspection service providers.
Norway
Equinor and Aker BP field operations drive inspection service procurement with stringent data integration requirements. Norway's CAA-N aligns with EASA risk-based operational authorizations, expanding certified flight envelopes for offshore platform work. Stavanger and Bergen anchor the North Sea corridor where pipeline operators consolidate multi-year framework agreements.
United Kingdom
Shell and BP operations in the UK North Sea are unbundling full-stack drone procurement into distinct flight, sensor, and analysis tiers. The UK's CAA processes beyond-visual-line-of-sight waivers under EASA harmonized standards, reducing approval timelines. Aberdeen serves as the primary cluster for inspection service providers capturing outsourced aviation from divesting operators.
Netherlands
Port of Rotterdam hydrogen conversion projects are creating demand for drone-based construction monitoring and leak detection services. The Dutch Human Environment and Transport Inspectorate implements EASA's Specific Category for offshore wind-to-hydrogen infrastructure inspection. Rotterdam and Amsterdam harbor zones concentrate service provider activity around LNG terminal optical gas imaging mandates.
Denmark
Ørsted and Energinet pipeline networks deploy continuous methane leak detection across subsea corridors. The Danish Transport Authority applies EU Regulation 2019/947 for cross-border infrastructure authorization with Norway and Germany. Esbjerg anchors North Sea service hub activity where corrosion assessment contracts consolidate under multi-vendor frameworks.
Germany
Industrial refinery complexes along the Rhine corridor are procuring ATEX-certified multi-rotor systems for flare stack inspection. Germany's Federal Aviation Office integrates EASA detect-and-avoid standardization into national implementation for chemical plant proximity work. Ludwigshafen and Leverkusen chemical clusters drive thermal imaging payload specifications for fugitive emission detection.
Europe Oil and Gas Drones Market Competitive Landscape
Player mix skews toward specialized inspection service providers with offshore aviation pedigrees. Market structure concentrates around vendors holding prior North Sea certifications, creating tiered access based on EASA operational authorization depth. Three archetypes dominate: full-stack hardware-to-analytics integrators, pure-play flight operators, and predictive analytics software layers. Competitive moves center on multi-vendor framework capture and detect-and-avoid technology licensing ahead of EASA standardization.
Among UK-based service specialists, Sky-Futures Limited and Cyberhawk Innovations Limited occupy positions within the inspection-tier vendor set. DJI Enterprise represents the manufacturing-scale archetype with sensor integration density. These three exemplify the market's segmentation between offshore pedigree, manufacturing scale, and platform-agnostic analytics layers.
| Leading Market Players |
|---|
| Sky-Futures Limited |
| Sharper Shape Inc. |
| Cyberhawk Innovations Limited |
| AeroVironment Inc. |
| Phoenix LiDAR Systems |
| Airobotics Ltd |
| Viper Drones |
| DJI Enterprise |
| Terra Drone Corporation |
| Others |
Supply & Pricing Matrix
Multi-year framework agreements with distinct flight, sensor, and analysis tiers lock in supply access for North Sea operators while anchoring price visibility across volatile ATEX component markets. EASA certification timelines and germanium detector availability determine contract renegotiation leverage for both buyers and inspection service providers.
Pricing Analysis
Certification level under EASA's Specific Category creates the primary spread between premium and standard service tiers. Three-tier pricing structure across premium, standard, and economy levels reflects ATEX Zone 2 proximity ratings, thermal payload specifications, and data analytics bundling. Price differentiation intensifies as pipeline operators unbundle full-stack procurement and pit specialized flight operators against analytics-only vendors. Margins are tightening in the standard tier due to detect-and-avoid equipment cost inflation, while premium tier buyers show lowest price sensitivity where manned helicopter substitution justifies mission-critical premiums.
Supply Chain Analysis
Rotterdam port congestion and container availability on Asia-Europe trade lanes strain inbound logistics for solid-state lidar and cooled thermal detector arrays. Manufacturing concentrates in China for multi-rotor airframes, Germany for precision optics, and the United States for AI-enabled analytics software. Supply chain risk centers on single-source vulnerability for germanium substrates and indium antimonide detector materials. Distribution runs through Stavanger, Aberdeen, and Esbjerg service hubs where inspection providers maintain forward-staged equipment pools for rapid offshore deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe oil and gas drones market rewards operators holding prior North Sea certifications, with pilot training throughput and SCADA integration expertise emerging as binding constraints on expansion velocity.
For Market Incumbents: Secure EASA detect-and-avoid technology licensing ahead of standardization to entrench beyond-visual-line-of-sight operational advantages. Lock in multi-year framework renewals with Equinor and Aker BP before satellite-based synthetic aperture radar substitutes erode long-range pipeline survey margins. Prioritize backward integration into thermal payload refurbishment to compress ATEX recertification cycles and defend service tier positioning. For New Entrants and Emerging Players: Differentiate on AI-photogrammetry defect classification speed to capture unbundled analytics contracts from Shell and BP's UK North Sea operations. Target Netherlands Port of Rotterdam hydrogen conversion monitoring where F-Gas Regulation alignment expands optical gas imaging mandates with lower incumbent saturation. Lead with subscription-based predictive maintenance pricing to bypass capital-intensive fleet ownership barriers. For Investors and Strategic Acquirers: Capital is best deployed toward inspection service providers holding cross-border EASA authorizations and established SCADA middleware integrations. Long-term viability hinges on regulatory automation rather than hardware manufacturing scale. Watch EASA's detect-and-avoid standardization release as the inflection signal separating certified autonomy leaders from visual observer-dependent laggards.| Strategic Initiative | Industry Significance |
|---|---|
| EASA Detect-and-Avoid Certification | First-mover certification under EU Regulation 2019/947 unlocks routine offshore platform access without costly observer networks. |
| SCADA Middleware Development | Custom data integration layers enable predictive maintenance contracts with Aker BP and Shell legacy asset management platforms. |
| Thermal Payload Backward Integration | In-house germanium detector refurbishment compresses ATEX recertification timelines and secures supply against detector manufacturing bottlenecks. |
| Multi-Vendor Framework Capture | Unbundled procurement tiers with Equinor separate hardware, flight, and analytics contracts for specialized vendor positioning. |
| Netherlands Hydrogen Infrastructure Positioning | Port of Rotterdam conversion projects create drone-based leak detection demand with F-Gas Regulation compliance mandates. |
Research Methodology
Operator-level perspectives from offshore inspection service heads, EASA authorized remote pilot trainers, SCADA integration engineers, and pipeline operations managers anchored the qualitative base. Secondary validation drew from EU Regulation 2019/947 implementation guidance, EASA Specific Category authorization databases, Norwegian CAA-N operational statistics, and North Sea framework agreement disclosures. Bottom-up service provider revenue aggregation and top-down hydrocarbon operator procurement spend estimates were triangulated to anchor market sizing.
Sensitivity analysis across certification timeline scenarios, detector supply disruption cases, and satellite substitution elasticity shaped the analytical framework. Segmentation dimensions modeled include drone type architecture, application lifecycle stage, end-user ownership structure, and technology stack compliance depth. CAGRs were derived from installed base expansion rates and mission frequency intensification across the projection horizon. Forecast inputs incorporated EASA rulemaking velocity for autonomous flight approvals and F-Gas Regulation inspection interval enforcement patterns.
The analysis sits within stated boundaries; outcomes outside EASA standardization timelines, germanium supply continuity, or North Sea operator procurement consolidation would require recalibration. Forecasts reflect documented assumptions around regulatory automation pace and payload cost trajectories. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
HPHT Cubic Press Market
Oil & Gas
Kuwait Oil and Gas Upstream Market
Oil & Gas
LAMEA Oilfield Auxiliary Rental Equipment Market
Oil & Gas
Vietnam Oil and Gas Market
Oil & Gas
Iran Oil and Gas Market
Oil & Gas
Europe Coiled Tubing Market
Oil & Gas
Natural Gas Market
Oil & Gas
Europe Intelligent Pigging Market
Oil & Gas
Oman Oil and Gas Upstream Market
Oil & Gas
Oilwell Spacer Fluids Market
Oil & Gas
Russia Oilfield Services Market
Oil & Gas
Large Scale LNG Terminal Market
Oil & Gas
Mobile Servicing Rig Market
Oil & Gas
North America Wireline Logging Services Market
Oil & Gas
Asia-Pacific AI in Oil and Gas Market
Oil & Gas
Asia-Pacific Oil Country Tubular Goods Market