
 North Sea Oil and Gas Upstream Market | 2026-2036
North Sea Oil and Gas Upstream Market Size, Share, and Industry Trends Forecast 2026-2036
North Sea Oil and Gas Upstream Market Analytics
Norway's Johan Sverdrup phase expansion is reshaping regional supply dynamics. Equinor ASA leverages subsea compression technology to sustain plateau production at mature fields. Shell plc anchors its North Sea position through integrated gas hub operations at Shetland. BP plc competes via digital twin deployment across its Clair Ridge complex, differentiating operational uptime metrics.
North Sea oil and gas upstream encompasses exploration, drilling, and production activities conducted in offshore environments at water depths ranging from 80 to 300 meters, utilizing fixed platforms, floating systems, and subsea tie-backs to extract hydrocarbons from Paleogene and Cretaceous reservoirs. The primary purpose is delivering crude oil and natural gas to European refining and power generation infrastructure. Exploration activity leads capital allocation among type segments, while enhanced oil recovery commands premium service margins within technology categories. Seismic surveys occupy the fastest-growing service type slot as operators target near-field prospects with compressed cycle times.
The Norwegian Petroleum Safety Authority enforces facility electrification deadlines that force platform power-from-shore investments, while the UK's North Sea Transition Authority imposes emissions reduction targets through its revised licensing rounds. REACH chemical standards govern drilling fluid formulations across EU-member offshore zones, shaping procurement specifications for service providers. Stakeholders must monitor regulatory divergence between UK and Norwegian carbon pricing mechanisms as this determines project sanctioning economics for cross-border developments.
Market Dynamics
Platform electrification mandates from the Norwegian Petroleum Safety Authority are forcing capital reallocation toward power-from-shore infrastructure, compressing project sanction timelines and reshaping field development economics across the mature basin.
Growth Catalysts
- Power-from-shore electrification:Norway's Petroleum Safety Authority deadlines for platform decarbonization are pulling investment into offshore grid connections and subsea cable infrastructure.
- Near-field exploration:4D seismic surveys and ocean bottom node technology are shortening discovery-to-production cycles at tie-back prospects adjacent to existing hub facilities.
- Enhanced oil recovery:Subsea compression and gas injection methods are sustaining plateau rates at Paleogene reservoirs beyond original decline curves.
Market Restraints
- Steel and alloy input volatility:Corrosion-resistant pipeline grades and subsea tree forgings face price swings tied to nickel and molybdenum supply concentration in Chinese smelting capacity.
- Decommissioning liability concentration:UK Continental Shelf operators confront accelerated plug-and-abandonment obligations as 1970s-era platforms reach end-of-design life.
- Carbon pricing divergence:Misalignment between UK and Norwegian emissions trading schemes creates tax friction for cross-border developments straddling median lines.
Strategic Opportunities
- Electrification service integration:Combined power-from-shore and offshore wind hybridization offers bundled decarbonization solutions for marginal field clusters.
- Digital twin deployment:Virtual facility modeling enables predictive maintenance contracts that unbundle traditional integrated service agreements.
- Hydrogen hub repurposing:Existing pipeline corridors and terminal infrastructure at St Fergus and Easington present blue hydrogen export pathways under UK hydrogen production contracts.
Industry Challenges
- Subsea engineering talent scarcity:Deepwater riser design and subsea control system expertise pools have thinned as veteran cohorts retire without sufficient apprenticeship pipeline replacement.
- Legacy platform integration:Brownfield automation retrofits must interface with 1980s-era SCADA architectures, complicating cybersecurity hardening and sensor density upgrades.
- REACH compliance timelines:Drilling fluid reformulation to meet ECHA chemical registration deadlines is compressing procurement qualification windows for service providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North Sea Oil and Gas Upstream Market |
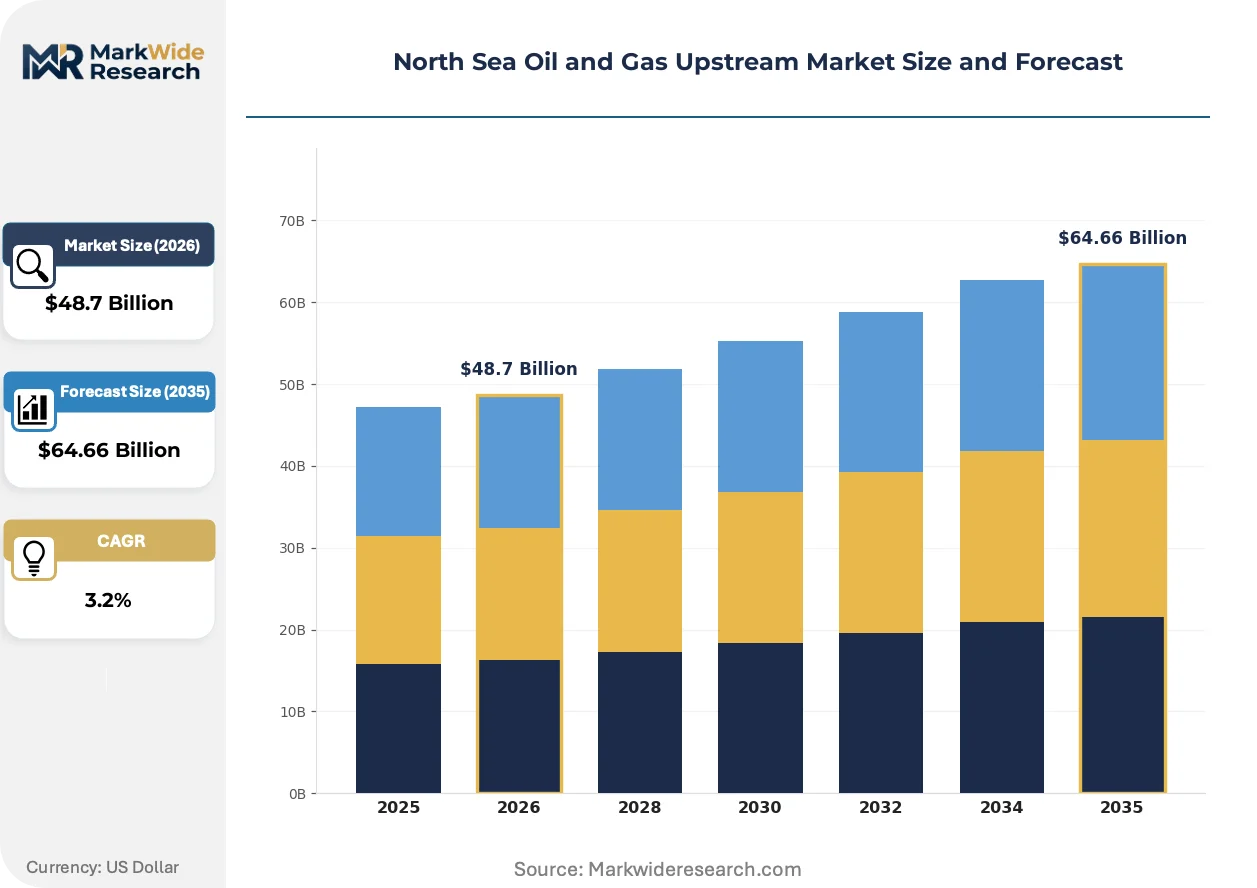
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $64.66 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Exploration, Production, Drilling, Production Support Service Type: Seismic Surveys, Well Testing, Engineering Services, Environmental Studies Technology: Subsea Systems, Enhanced Oil Recovery, Floating Production Systems, Offshore Rigs End User: Independent Operators, Major Oil Companies, Integrated Firms, Service Providers |
| Companies Covered | ExxonMobil Corporation, Eni SpA, Equinor ASA, ConocoPhillips, Var Energi, BP plc, TotalEnergies, Transocean Ltd, Shell plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North Sea Oil and Gas Upstream Market Evolving Landscape
Subsea processing technology and digital infrastructure are compressing development cycles and enabling remote operation models that reduce offshore headcount exposure. Three developments are restructuring competitive capabilities across the basin.
Subsea compression systems are collapsing the economic threshold for marginal field development by eliminating topside platform requirements at water depths previously requiring fixed structures. Equinor and Aker BP are deploying these systems at brownfield extensions to sustain plateau production without new manned installations. The technology is collapsing capital intensity benchmarks for tie-back projects, allowing cluster developments around existing hubs that were previously sub-commercial.
Norway's Petroleum Safety Authority electrification mandates are forcing platform power-from-shore investments that rewire offshore energy economics. Operators must secure grid connection agreements and onshore substation capacity years ahead of first oil, compressing front-end engineering schedules. UK fields are responding through shared infrastructure consortia to distribute cable costs across multiple license holders.
Service contract unbundling is fragmenting the integrated project delivery model that dominated 2010s developments. European refiners are driving this shift by demanding transparent cost allocation between drilling, subsea installation, and facility construction workstreams. The Norwegian Continental Shelf exhibits the most advanced procurement sophistication, with operators separating engineering from equipment supply and installation to sharpen competitive tension.
North Sea Oil and Gas Upstream Market Segmentation
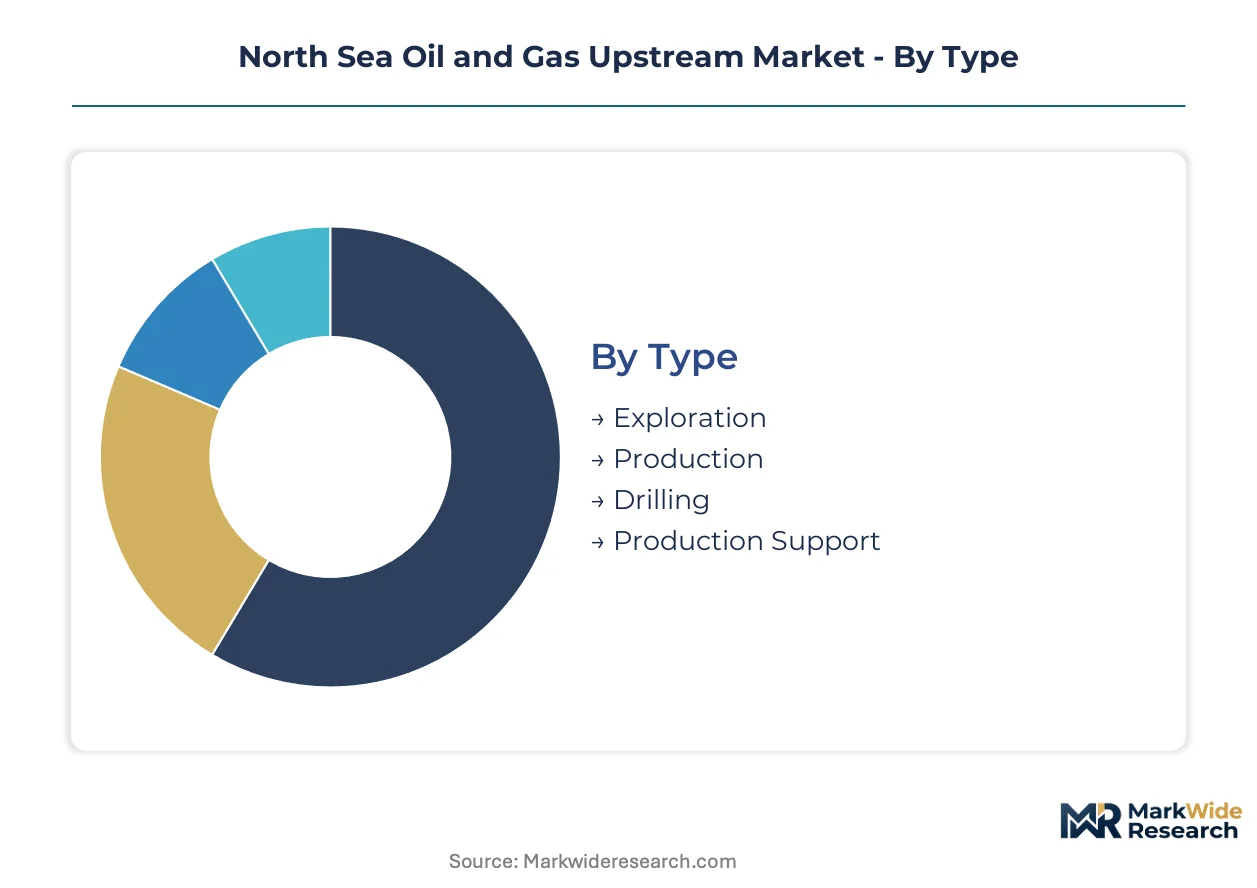
Segmentation in the North Sea upstream market reflects divergent capital cycles and regulatory exposure profiles. Each category maps to distinct procurement patterns and margin structures shaped by Norwegian electrification mandates and UK decommissioning timelines.
Type:
Cycle times vary dramatically across activity types, with exploration contracting measured in months while production operations span decades of field life.
- Exploration:Seismic acquisition and wildcat drilling programs deploy capital rapidly with high technical uncertainty. Operators concentrate 4D survey spending on near-field prospects adjacent to Johan Sverdrup and Clair Ridge infrastructure to compress discovery-to-sanction intervals.
- Production:Brownfield redevelopment and plateau sustainment operations lock in long-term service relationships. Norwegian Continental Shelf operators prioritize subsea compression tie-backs to extend Paleogene reservoir life without new platform construction.
- Drilling:Jack-up and semi-submersible rig contracting follows seasonal North Sea weather windows.
- Production Support:Maintenance, logistics, and supply vessel operations provide recurring revenue streams.
Production anchors the volume base while exploration gains share at the steepest rate as operators replenish declining reserves through near-field programs.
Service Type:
Cost tiers separate commoditized field services from premium technical offerings commanding margin premiums.
- Seismic Surveys:Ocean bottom node technology and 4D time-lapse imaging deliver subsurface resolution for reservoir management. UK operators deploy these services at mature fields to identify bypassed pay zones before decommissioning commitments trigger.
- Engineering Services:Front-end engineering design and subsea architecture planning absorb concentrated specialist labor. Norwegian electrification mandates are pulling FEED spending toward power-from-shore integration and platform retrofit engineering.
- Well Testing:Formation evaluation and flow assurance diagnostics verify reservoir performance.
- Environmental Studies:Baseline surveys and impact assessments satisfy regulatory permitting requirements.
Engineering services anchors the volume base while seismic surveys expand most quickly as operators prioritize near-field exploration efficiency.
Technology:
Application maturity determines whether segments compete on installed base maintenance or first-of-kind deployment risk.
- Subsea Systems:Trees, manifolds, and processing equipment enable remote hydrocarbon extraction without surface facilities. Equinor and Aker BP are deploying subsea compression at Norwegian brownfield extensions to sustain plateau production without new manned platforms.
- Enhanced Oil Recovery:Gas injection and chemical flooding methods target incremental recovery from mature Paleogene reservoirs. UK operators apply these technologies to extend field life ahead of accelerated plug-and-abandonment obligations on 1970s-era installations.
- Floating Production Systems:FPSO and semi-submersible hulls serve remote or marginal discoveries.
- Offshore Rigs:Jack-up and drillship assets execute exploration and development drilling programs.
Subsea systems anchors the volume base while enhanced oil recovery climbs the fastest as operators maximize recovery factors before decommissioning.
End User:
Customer type shapes procurement sophistication and contract structure preferences across the basin.
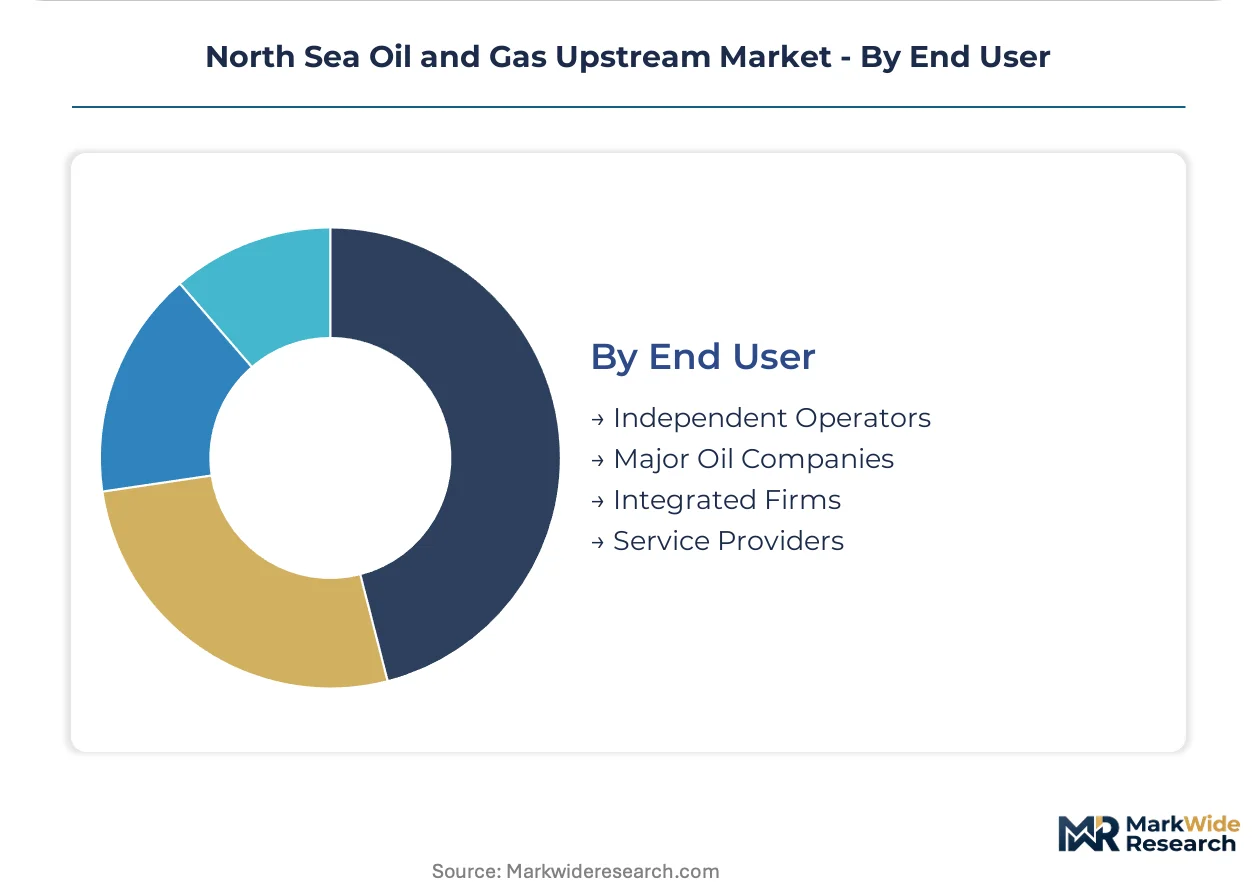
- Major Oil Companies:Equinor, Shell, and BP wield integrated technical capabilities and balance sheet capacity for complex developments. These operators are unbundling service contracts to sharpen competitive tension between engineering, equipment supply, and installation providers.
- Independent Operators:Harbour Energy, Ithaca Energy, and similar firms focus on asset optimization and cost discipline. UK independents concentrate on late-life field acquisitions where decommissioning liability transfer creates valuation arbitrage opportunities.
- Integrated Firms:Vertically organized entities spanning upstream through refining operations.
- Service Providers:Schlumberger, Halliburton, and regional contractors deliver specialized technical execution.
Major oil companies anchors the volume base while independent operators gain share at the steepest rate through late-life asset acquisitions and portfolio rationalization by incumbents.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Exploration and production activity clusters around mature hydrocarbon provinces where existing infrastructure enables tie-back economics. Basin maturity drives capital toward brownfield extensions rather than frontier wildcatting.
Norway
Equinor ASA and Aker BP dominate field redevelopment through subsea compression installations at Johan Sverdrup. The Petroleum Safety Authority enforces platform electrification deadlines that mandate power-from-shore connections. Stavanger anchors the technical services cluster, where engineering firms concentrate on FEED work for cable infrastructure and retrofit projects.
United Kingdom
Harbour Energy and Ithaca Energy acquire late-life assets where decommissioning liability transfers create valuation opportunities. The North Sea Transition Authority imposes emissions reduction targets through revised licensing round criteria. Aberdeen hosts the primary supply chain concentration, with service providers clustering around well intervention and plug-and-abandonment capabilities.
Netherlands
Neptune Energy and ONE-Dyas target small-field developments through shared infrastructure consortia that distribute pipeline costs. The State Supervision of Mines regulates offshore safety and environmental compliance for southern North Sea operations. Den Helder maintains the offshore logistics hub, with helicopter and supply vessel operations supporting Dutch sector platforms.
Denmark
TotalEnergies and BlueNord advance redevelopment of Tyra and other mature gas fields through platform reconstruction investments. The Danish Energy Agency administers licensing rounds with carbon intensity screening criteria. Esbjerg functions as the primary service base, with fabrication yards executing jacket and topside modules for North Sea deployment.
Germany
Wintershall Dea concentrates on low-volume production from Schleswig-Holstein offshore concessions through extended-reach drilling from onshore pads. The Federal Mining Act governs extraction permits and environmental impact assessments for the exclusive economic zone. Cuxhaven supports limited offshore logistics, with most technical services sourced from Norwegian and UK supply chains.
North Sea Oil and Gas Upstream Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the supply chain, feeding subsea trees, manifolds, and processing equipment into larger field development packages. The competitive structure exhibits moderate consolidation among field operators, with service provision fragmenting across specialized technical niches. Three archetypes dominate: integrated majors with balance sheet capacity for complex developments; independent operators focused on late-life asset optimization; and engineering specialists delivering subsea architecture and electrification design. Competitive moves concentrate on portfolio rationalization through asset divestiture and strategic partnering to share infrastructure costs across marginal field clusters.
Within the integrated major tier, Equinor ASA, BP plc, and Shell plc exemplify the capital-intensive archetype that dominates sanctioning authority for large-scale projects. These Norwegian and UK-registered entities occupy positions that shape procurement patterns across the basin, unbundling service contracts to sharpen competitive tension between engineering, equipment supply, and installation providers. Their collective presence determines technical standards for subsea compression, platform electrification, and digital infrastructure deployment.
| Leading Market Players |
|---|
| ExxonMobil Corporation |
| Eni SpA |
| Equinor ASA |
| ConocoPhillips |
| Var Energi |
| BP plc |
| TotalEnergies |
| Transocean Ltd |
| Shell plc |
| Others |
Value Network & Pricing Analysis
Stavanger-to-Aberdeen supply corridors transmit cost volatility from Norwegian fabrication yards to UK brownfield operators, compressing margins at independent producers while concentrating pricing power among integrated majors with captive vessel fleets and long-term charter agreements.
Pricing Analysis
REACH chemical standards dictate the pricing tier structure for drilling services across EU-member offshore zones, separating premium-certified fluid formulations from standard synthetic alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale, with major oil companies showing lowest price sensitivity due to integrated procurement functions. Cost compression in standard-tier services is intensifying because independent operators are consolidating purchasing through shared service consortia.
Supply Chain Analysis
Dual-use technology controls on subsea control systems and blowout preventer components limit technology flows from US and Norwegian engineering centers to non-allied operators. Supply concentration rests on fabrication yards in Norway, Scotland, and Singapore for subsea trees and manifolds, with nickel and molybdenum feedstocks drawing from Chinese smelting capacity. Single-source vulnerability runs through specialized forging facilities for corrosion-resistant pipeline grades. Distribution runs through integrated majors with direct vendor relationships rather than distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform electrification mandates are triggering an interoperability shift where power-from-shore infrastructure becomes the shared substrate for marginal field clusters, rewiring competitive economics around grid access rather than standalone facility ownership.
For Market Incumbents: Harden cybersecurity architectures at legacy SCADA installations before sensor density upgrades expose 1980s-era control systems to network intrusion. Secure long-term grid connection agreements at onshore substations to lock in electrification capacity ahead of competitor queue positions. Consolidate procurement volumes across brownfield portfolios to sharpen pricing leverage against unbundled service providers.
For New Entrants and Emerging Players: Establish a beachhead in late-life UK asset acquisitions where decommissioning liability transfers create valuation arbitrage unavailable to incumbents with legacy obligations. Target electrification engineering services for marginal field clusters lacking in-house FEED capabilities. Position through shared infrastructure consortia to distribute cable costs across multiple license holders without bearing full development risk.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors subsea compression specialists with proven deployment records at Norwegian brownfield extensions. Long-term viability hinges on electrification service integration capabilities spanning power-from-shore and offshore wind hybridization. Watch Petroleum Safety Authority enforcement patterns as the inflection indicator for capital reallocation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Power-from-Shore Infrastructure Buildout | Grid connection agreements at Utsira and Kollsnes anchor electrification economics for platform clusters. |
| Subsea Compression Deployment | Equinor and Aker BP installations at Johan Sverdrup collapse capital thresholds for marginal tie-backs. |
| Digital Twin Integration | Virtual facility modeling at Clair Ridge enables predictive maintenance contracts that fragment integrated service agreements. |
| Shared Infrastructure Consortium Formation | UK operators distribute cable costs across license holders to compress front-end engineering schedules. |
| Late-Life Asset Acquisition | Harbour Energy and Ithaca Energy transfers capture decommissioning liability arbitrage from exiting majors. |
Research Methodology
Initial hypotheses were tested against primary input from subsea engineering directors, drilling procurement managers, regulatory compliance officers, and offshore logistics coordinators and refined through secondary validation against Norwegian Petroleum Safety Authority enforcement records, UK North Sea Transition Authority licensing databases, ECHA chemical registration filings, and operator capital expenditure disclosures. Bottom-up field development project tracking was triangulated with top-down basin production forecasts.
Demand-supply balance modeling across the projection horizon incorporated type, service type, technology, and end user segmentation dimensions with regional regulatory framework overlays. CAGRs were derived through regression analysis of historical sanctioning activity against electrification mandate timelines. Forecast inputs included platform decommissioning schedules and power-from-shore grid connection queue positions.
Stress conditions across nickel alloy price volatility, carbon pricing divergence scenarios, and subsea engineering labor availability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement consistency and supply chain lead time stability. Material shifts in Petroleum Safety Authority electrification deadline acceleration or REACH compliance timeline compression would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Middle East Natural Gas Market
Oil & Gas
Global Deep-Well Disposal Services Market
Oil & Gas
Russian Federation Oil and Gas Upstream Market
Oil & Gas
Italy Oil and Gas Downstream Market
Oil & Gas
Europe Seismic Survey Market
Oil & Gas
Mineral Oil and Mineral Spirit Market
Oil & Gas
Subsea Boosting Systems Market
Oil & Gas
Global LNG Liquefaction Terminals Market
Oil & Gas
Malaysia Oilfield Services Market
Oil & Gas
Marine Oil Water Separators Market
Oil & Gas
Tricone Bits Market
Oil & Gas
Middle East and Africa Drilling Market
Oil & Gas
Deepwater Hydrocarbons Exploration Market
Oil & Gas
Africa Oil and Gas Market
Oil & Gas
North America Directional Drilling Services Market
Oil & Gas
Global LNG Liquefaction Equipment Market