
 Well Test Market | 2026-2036
Well Test Market Size, Share, and Industry Trends Forecast 2026-2036
Well Test Market Analytics
Modular test package bundling is recalibrating how offshore operators evaluate service contracts. Schlumberger leverages integrated wireline and testing portfolios to anchor deepwater campaigns in West Africa and the Gulf of Mexico. Halliburton competes through geographic dominance in North American shale basins, while Baker Hughes differentiates via advanced downhole sensor technology leadership.
Well testing encompasses controlled flow measurement and pressure transient analysis performed on oil and gas wells to determine reservoir properties, flow rates, and formation damage, typically conducted using surface separation equipment rated for pressures exceeding 10,000 psi and temperatures above 300°F to evaluate commercial viability. Production testing services command the largest revenue share among service types due to their recurring nature throughout field life, while downhole sensors represent the fastest-expanding technology segment as operators prioritize real-time reservoir data over intermittent surface measurements. Exploration applications sustain premium pricing despite cyclical capital allocation, whereas reservoir characterization work generates the most intensive repeat-engagement patterns with service providers.
API standards govern wellhead and surface equipment specifications in the United States, while Brazil's ANP mandates specific test protocols for pre-salt field development, and Norway's PSA enforces stringent safety requirements for North Sea testing operations that elevate equipment certification costs. These regulatory frameworks shape procurement decisions by dictating minimum equipment ratings, data reporting frequencies, and environmental containment standards. Stakeholders must monitor evolving methane emission measurement requirements and digital data submission mandates that will determine competitive qualification for future national oil company tenders.
Market Dynamics
Real-time downhole monitoring packages are compressing test cycle durations and forcing surface equipment suppliers to integrate digital twin compatibility into API RP 14B wellhead specifications or risk disqualification from supermajor procurement tenders.
Growth Catalysts
- Pre-salt basin development:Petrobras and international consortia in Brazil commission extended-duration production testing campaigns that sustain premium service pricing.
- API RP 14B integration:Wellhead equipment standards now mandate digital twin compatibility, expanding upgrade demand across Gulf of Mexico offshore programs.
- Wireline-testing bundling:Integrated service portfolios anchor deepwater campaign commitments and extend contract tenures.
Market Restraints
- High-pressure alloy scarcity:Nickel-based superalloy supply concentrates in a limited supplier base, creating input cost volatility for 10,000+ psi rated separation equipment.
- North Sea certification costs:Norway's PSA safety requirements elevate equipment qualification expenses and extend vendor onboarding timelines.
- Intermittent surface measurement substitution:Traditional well testing faces displacement by permanent downhole gauge networks that reduce need for mobilized test packages.
Strategic Opportunities
- West Africa deepwater expansion:Underpenetrated offshore blocks off Angola and Nigeria offer white space for integrated testing and monitoring service deployment.
- Methane emission measurement mandates:Evolving regulatory requirements for fugitive emissions quantification during flow testing create new data service revenue streams.
- Sensor-software convergence:Downhole fiber-optic sensing combined with edge computing enables real-time reservoir characterization without surface facility constraints.
Industry Challenges
- Digital-legacy system integration:Supermajor operators require seamless data handoff between new real-time monitoring platforms and decades-old SCADA infrastructure.
- Specialized technician scarcity:Deepwater test package operations demand certified personnel fluent in both high-pressure surface equipment and downhole telemetry systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Well Test Market |
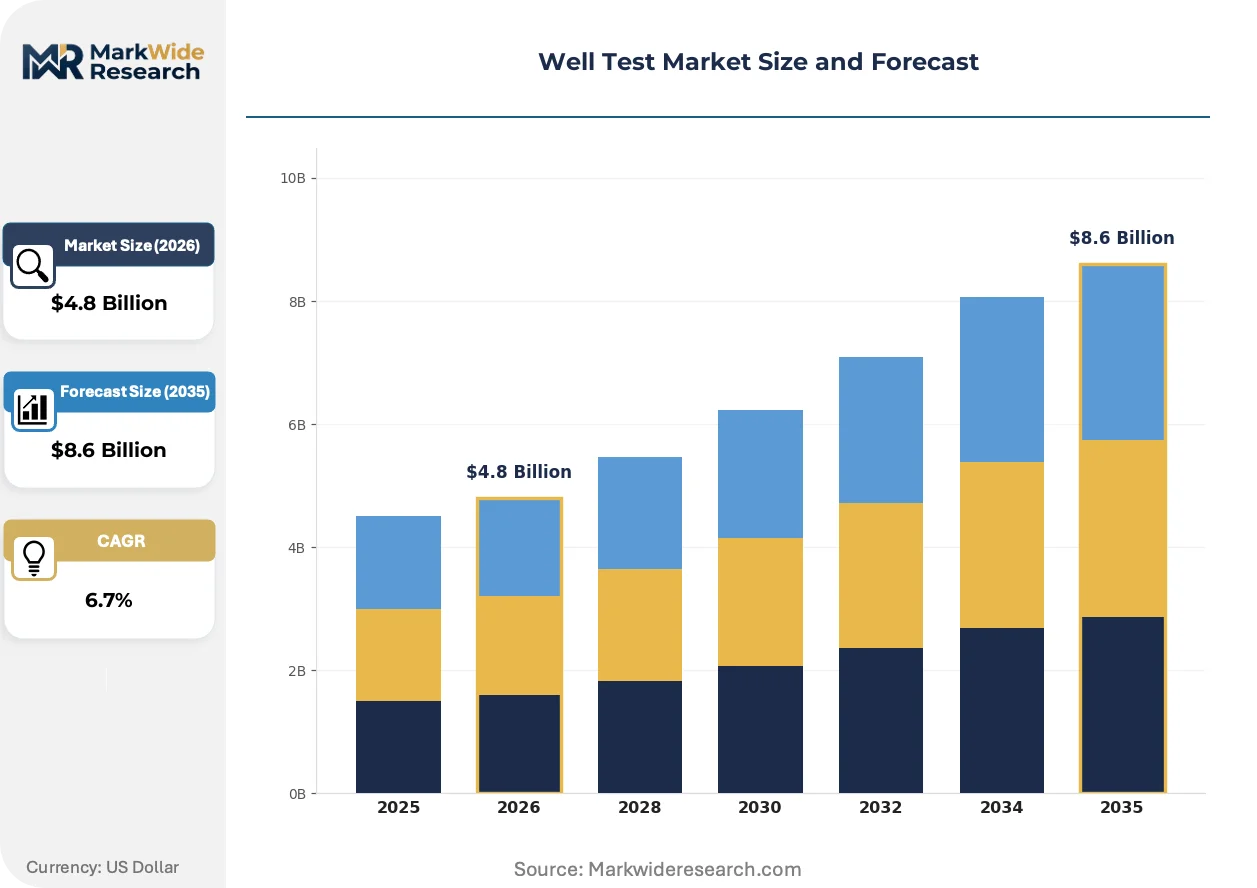
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Build-Up Testing, Drawdown Testing, Interference Testing, Production Testing Technology: Multi-Phase Flow Meters, Electro-Mechanical Equipment, Portable Test Units, Downhole Sensors End User: Oil & Gas Companies, Service Providers, Independent Operators, Government Agencies Application: Exploration, Production Optimization, Reservoir Characterization, Environmental Monitoring |
| Companies Covered | Schlumberger, Halliburton, EXPRO Group, Baker Hughes, Weatherford, TechnipFMC, TETRA Technologies, China Oilfield Services Limited, Oil States International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Well Test Market Evolving Landscape
Digital twin integration is rewriting equipment procurement specifications. Three interconnected developments are compressing traditional testing workflows and elevating data-centric service models.
Fiber-optic distributed temperature and pressure sensing is overtaking conventional electronic gauges in high-temperature reservoirs. Operators in Brazil's pre-salt basins deploy these systems at 300°F-plus conditions where electronics fail. The technology is overtaking wireline-conveyed measurements by eliminating mobilization delays and enabling continuous drawdown analysis.
Brazil's ANP mandates specific test protocols for pre-salt field development that exceed international baseline requirements. These rules force service providers to maintain dedicated certification for Brazilian operations. Pre-salt consortia absorb elevated compliance costs to secure development licenses, creating a regulated premium tier distinct from standard international service pricing.
Integrated service contracts now bundle wireline, testing, and monitoring under single-vendor accountability. Supermajors in the Gulf of Mexico consolidate procurement to reduce interface risk between discrete service phases. This consolidation rewards providers with full technology stacks and marginalizes specialized single-service vendors.
Well Test Market Segmentation
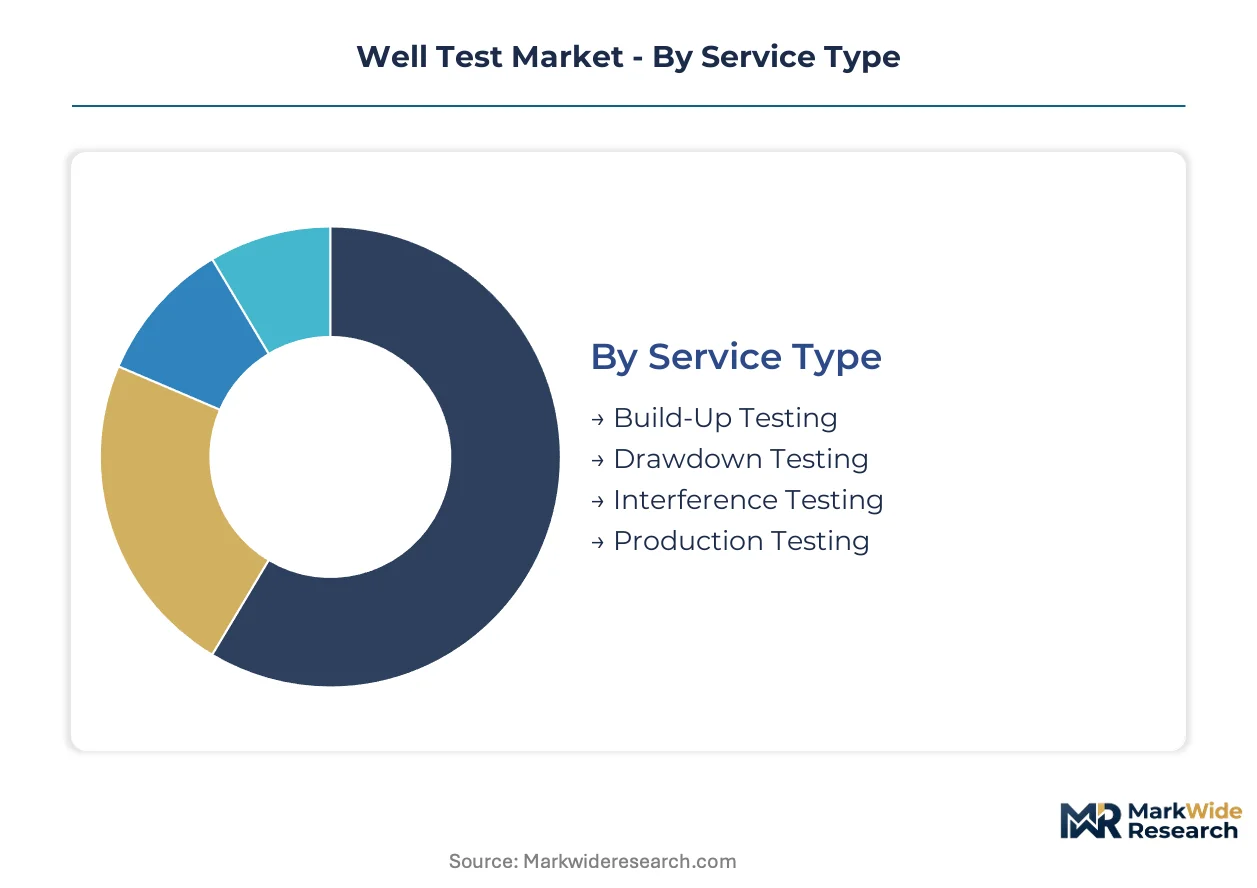
Well test procurement divides across four critical dimensions that shape vendor qualification and contract structures. Service type determines equipment mobilization frequency, while technology selection governs data resolution and real-time capability. End-user category dictates risk tolerance and contract tenure, and application context sets regulatory intensity and pricing premiums.
Service Type:
Upgrade cycles for surface separation packages and downhole tool strings rotate around field development phases, with operators replacing or expanding test portfolios as reservoir maturity shifts diagnostic priorities.
- Production Testing:Recurring flow measurement campaigns using surface separation equipment rated for 10,000+ psi and 300°F-plus conditions. Demand concentrates in Brazil's pre-salt basins where Petrobras commissions extended-duration campaigns that sustain premium pricing through field life.
- Build-Up Testing:Pressure transient analysis conducted after flow periods to determine permeability and skin damage. North American shale operators deploy these packages frequently during completion evaluation, driving repeat-engagement patterns with service providers.
- Drawdown Testing:Controlled production to assess deliverability and formation damage.
- Interference Testing:Multi-well pressure monitoring to define reservoir connectivity and boundary conditions.
Production Testing sits at the top of the volume ranking, with Downhole Sensors climbing the fastest.
Technology:
Cost tiers separate permanent installations from mobilized packages, with capital intensity and data continuity driving procurement trade-offs across offshore and onshore environments.
- Downhole Sensors:Fiber-optic distributed temperature and pressure systems operating beyond 300°F where electronics fail. Brazil's pre-salt consortia deploy these for continuous drawdown analysis, eliminating wireline mobilization delays while satisfying ANP protocol mandates.
- Multi-Phase Flow Meters:Real-time three-phase measurement without surface separation. Gulf of Mexico operators integrate these with digital twin platforms to compress test cycles and meet API RP 14B procurement specifications.
- Portable Test Units:Rapidly deployable packages for exploration and appraisal drilling.
- Electro-Mechanical Equipment:Conventional surface separation and control systems.
Downhole Sensors command the steepest expansion trajectory, while Electro-Mechanical Equipment retains the largest installed base.
End User:
Customer type determines contract structure, with integrated service bundling favored by capital-rich operators and single-service procurement persisting among cost-constrained independents.
- Oil & Gas Companies:Supermajors and national oil companies with multi-year framework agreements. These entities in the Gulf of Mexico consolidate wireline, testing, and monitoring under single-vendor accountability to reduce interface risk between discrete service phases.
- Service Providers:Subcontracted specialists executing testing programs on behalf of operators. West Africa deepwater expansion creates white space for integrated testing and monitoring deployment through these intermediaries.
- Independent Operators:Smaller entities with spot-market procurement and shorter contract tenures.
- Government Agencies:Regulatory bodies mandating test protocols for license compliance.
Oil & Gas Companies dominate contract value, with Service Providers expanding most quickly in underpenetrated offshore blocks.
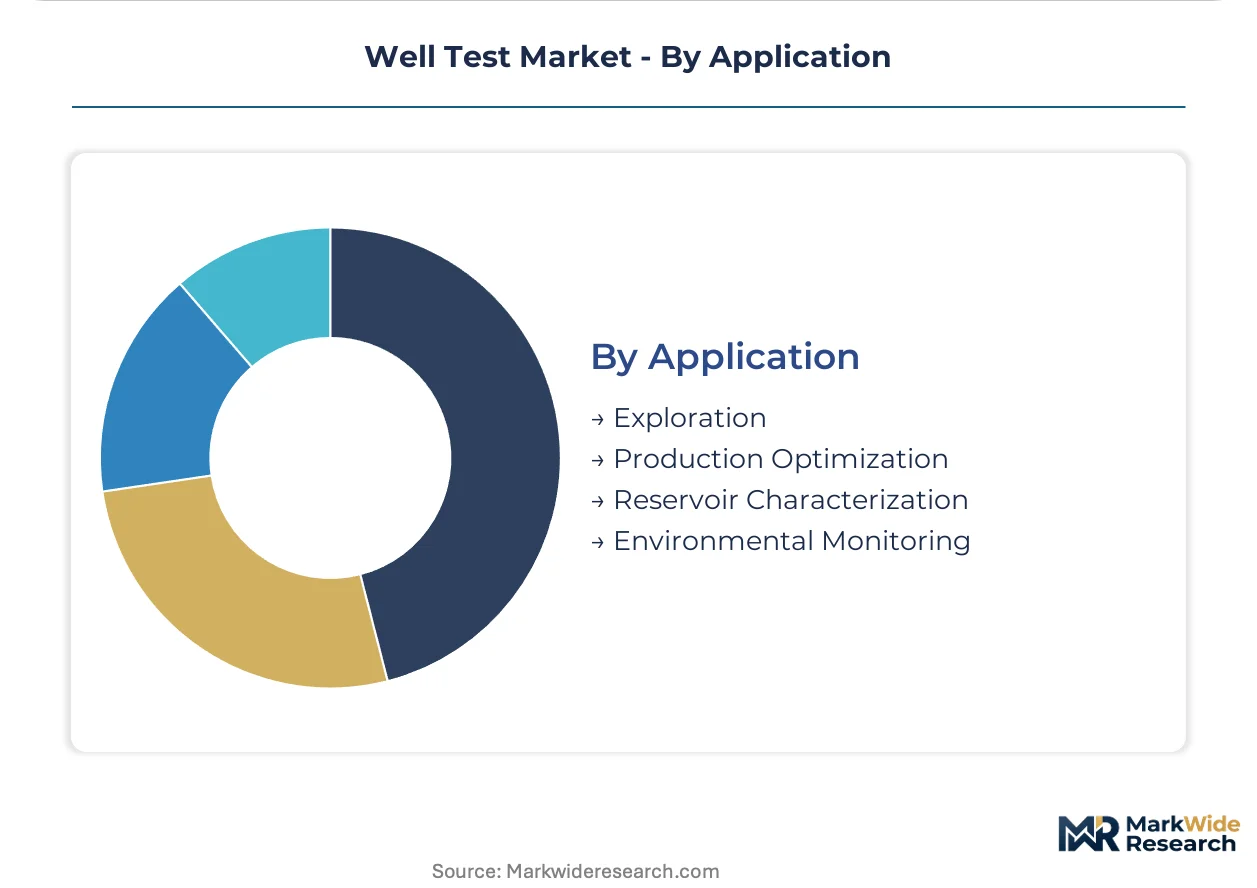
Application:
Application context governs regulatory intensity, with exploration sustaining premium pricing despite cyclical capital allocation and environmental monitoring emerging as a compliance-driven revenue stream.
- Reservoir Characterization:Intensive repeat-engagement work generating the most sustained service provider relationships. Norway's PSA safety requirements elevate equipment certification costs for these campaigns, extending vendor onboarding timelines but securing long-term commitments.
- Exploration:High-stakes appraisal testing with premium pricing. Pre-salt basin development in Brazil sustains this segment through ANP-mandated protocols that exceed international baseline requirements.
- Production Optimization:Ongoing field management to maximize recovery factors.
- Environmental Monitoring:Fugitive emissions quantification and containment verification.
Reservoir Characterization leads in repeat-engagement intensity, with Environmental Monitoring gaining share fastest on methane measurement mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Well testing technology first achieved commercial scale in the Gulf of Mexico during the 1970s offshore boom, establishing the technical templates now deployed across deepwater basins worldwide. The industry's geographic footprint now spans five critical national markets where reservoir complexity and regulatory stringency drive specialized service demand.
United States
Offshore exploration programs in the Gulf of Mexico are expanding adoption of real-time downhole monitoring packages. API RP 14B wellhead equipment standards now mandate digital twin compatibility, reshaping procurement criteria among supermajors operating federal waters. Houston anchors the largest concentration of testing service providers and equipment fabricators serving domestic and international markets.
Brazil
Petrobras and international consortia commission extended-duration production testing campaigns in pre-salt basins that sustain premium service pricing through field life. ANP mandates specific test protocols for pre-salt field development that exceed international baseline requirements, forcing dedicated certification for Brazilian operations. Rio de Janeiro hosts the primary service provider clusters supporting Campos and Santos basin development.
Norway
North Sea testing operations face stringent safety requirements from the country's national petroleum regulator that elevate equipment certification costs and extend vendor onboarding timelines. Reservoir characterization work generates the most intensive repeat-engagement patterns with service providers due to complex fractured carbonate formations. Stavanger and Bergen concentrate the specialist engineering workforce for subsea testing package deployment.
United Kingdom
Mature North Sea assets require ongoing production optimization testing to maximize recovery factors from depleting reservoirs. The country's offshore regulator enforces environmental containment standards that shape procurement decisions for surface separation equipment. Aberdeen maintains Europe's densest cluster of well testing specialists despite production decline in surrounding waters.
China
National oil companies are expanding deepwater exploration in the South China Sea, driving demand for high-pressure testing equipment rated beyond standard specifications. The country's national energy administration is implementing data submission mandates that will determine competitive qualification for future tenders. Shenzhen and Tianjin host the primary manufacturing bases for domestic testing package production.
Well Test Market Competitive Landscape
The competitive structure tilts toward integrated service conglomerates with full technology stacks. Three global oilfield service majors anchor procurement frameworks through bundled wireline-testing-monitoring portfolios, while regional specialists and national oilfield service companies occupy tier-two positions through geographic density or cost positioning. Strategic moves concentrate on integrated contract consolidation and sensor-software convergence rather than pure equipment supply.
Among the integrated service tier, Schlumberger, Halliburton, and Baker Hughes exemplify divergent competitive positioning. Schlumberger represents the full-stack archetype with combined wireline and testing portfolios anchoring deepwater campaigns. Halliburton occupies a position emphasizing North American shale basin dominance through geographic density. Baker Hughes exemplifies technology-led differentiation via advanced downhole sensor capabilities. These three entities sit within the supermajor procurement tier where single-vendor accountability reduces interface risk between discrete service phases.
| Leading Market Players |
|---|
| Schlumberger |
| Halliburton |
| EXPRO Group |
| Baker Hughes |
| Weatherford |
| TechnipFMC |
| TETRA Technologies |
| China Oilfield Services Limited |
| Oil States International |
| Others |
Value Network & Pricing Analysis
API RP 14B digital twin mandates from Gulf of Mexico supermajors are forcing equipment fabricators to absorb certification upgrade costs or cede procurement eligibility, compressing margins on standard-rated packages while widening spreads for digitally integrated offerings.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs well test procurement, with certification grade and real-time data capability as primary differentiation drivers. Premium tiers capture ANP-compliant Brazilian pre-salt packages and API RP 14B-certified Gulf of Mexico equipment, while economy tiers serve spot-market North American shale operators. Pricing pressure stems from nickel-based superalloy input volatility for 10,000+ psi rated separation equipment. Independent operators exhibit highest price sensitivity, whereas Petrobras and international consortia absorb elevated compliance costs for license security.
Supply Chain Analysis
Direct-to-operator channels handle supermajor framework agreements, with subcontractor networks serving tier-two service providers. Manufacturing concentrates in the United States, Brazil, and China, with Houston and Rio de Janeiro anchoring high-pressure equipment fabrication and Shenzhen hosting domestic Chinese package production. Supply chains draw from nickel-based superalloy suppliers concentrated in limited geographies, with synthetic diamond and fiber-optic sensing components as critical technology inputs. Single-source vulnerability in superalloy supply creates cost volatility exposure. Distribution runs through integrated service conglomerates with bundled wireline-testing-monitoring portfolios.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in sensor-software convergence and methane measurement data services, with digital twin integration requirements accelerating premium-tier demand while legacy equipment faces commoditization pressure.
For Market Incumbents: Extend integrated service bundling to lock in multi-year Gulf of Mexico framework agreements before Halliburton or Baker Hughes consolidate remaining uncommitted supermajor procurement. Deepen backward integration into fiber-optic sensing manufacturing to reduce dependency on external component suppliers facing allocation constraints. Defend against permanent downhole gauge substitution by embedding predictive analytics into real-time monitoring packages that justify recurring service fees over capital equipment sales. For New Entrants and Emerging Players: ANP pre-salt certification requirements in Brazil open a window for specialized compliance-focused service providers to capture subcontractor roles from integrated majors lacking dedicated Brazilian operational capacity. Target West Africa deepwater blocks off Angola and Nigeria where integrated testing and monitoring penetration remains limited and national oil companies seek vendor diversification. Lead with methane emission measurement data services as a differentiated entry point where regulatory tailwinds outpace incumbent capability deployment. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap sensor-software specialists possessing fiber-optic distributed sensing IP and edge computing reservoir characterization platforms. Long-term viability favors providers with captive certification in Brazil's ANP regime and API RP 14B digital twin integration capabilities rather than pure equipment fabricators. Watch for inflection in national oil company tender specifications requiring fugitive emissions quantification as a mandatory evaluation criterion.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Integration | API RP 14B compliance secures supermajor procurement eligibility in Gulf of Mexico federal waters. |
| Fiber-Optic Sensing Scale-Up | ANP pre-salt mandates in Brazil drive replacement of electronic gauges above 300°F reservoir conditions. |
| Methane Measurement Service Launch | Emerging regulatory requirements in Norway's PSA jurisdiction create new data revenue streams. |
| West Africa Deepwater Expansion | Underpenetrated Angolan and Nigerian offshore blocks offer first-mover integrated service positioning. |
| Backward Integration into Superalloy Supply | Captive nickel-based alloy sourcing mitigates input cost volatility for high-pressure separation equipment. |
Research Methodology
Direct dialogue with well test operations managers, procurement leads at national oil companies, subsea equipment engineers, and regulatory compliance officers anchored qualitative findings, cross-referenced against API RP 14B documentation, ANP pre-salt field development protocols, Norway PSA safety directives, and SEC filings from integrated oilfield service providers. Secondary sources included customs data on high-pressure equipment trade flows, offshore drilling contract databases, and patent filings for fiber-optic distributed sensing technologies. Bottom-up field deployment estimates and top-down energy service spending allocations were triangulated to validate market sizing.
Bottom-up modeling tracked equipment package deployments by pressure rating, temperature specification, and digital integration tier across the projection horizon. Top-down analysis calibrated service revenue against upstream capital expenditure patterns and exploratory drilling permit trends. Segmentation dimensions encompassed service type, technology category, end-user contract structure, and application regulatory intensity. CAGRs were derived from equipment replacement cycles, pre-salt field development timelines, and digital adoption curves in Gulf of Mexico deepwater programs.
Revisions become necessary when nickel-based superalloy supply disruptions, methane emission measurement mandate accelerations, or permanent downhole gauge substitution rates materially diverge from base assumptions. Forecasts reflect documented expectations regarding Petrobras pre-salt campaign continuity, API specification evolution timelines, and West Africa licensing round outcomes. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Russian Federation Oil and Gas Upstream Market
Oil & Gas
Global Fracking Fluids and Chemicals Market
Oil & Gas
Pipeline Integrity Market
Oil & Gas
Gold Mining Market
Oil & Gas
China Oil and Gas Market
Oil & Gas
Offshore Drilling Fluid Market
Oil & Gas
North America Wireline Logging Services Market
Oil & Gas
Oil & Gas Equipment MRO Market
Oil & Gas
Indonesia Oilfield Equipment Rental Services Market
Oil & Gas
India Oil and Gas Market
Oil & Gas
Latin America AI in Oil and Gas Market
Oil & Gas
Asphaltene Inhibitors Market
Oil & Gas
Chad Oil and Gas Upstream Market
Oil & Gas
United Kingdom LNG Market
Oil & Gas
Subsea Manifolds Market
Oil & Gas
Smart Pigging Market