
 Canada Oil and Gas Market | 2026-2036
Canada Oil and Gas Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Oil and Gas Market Analysis
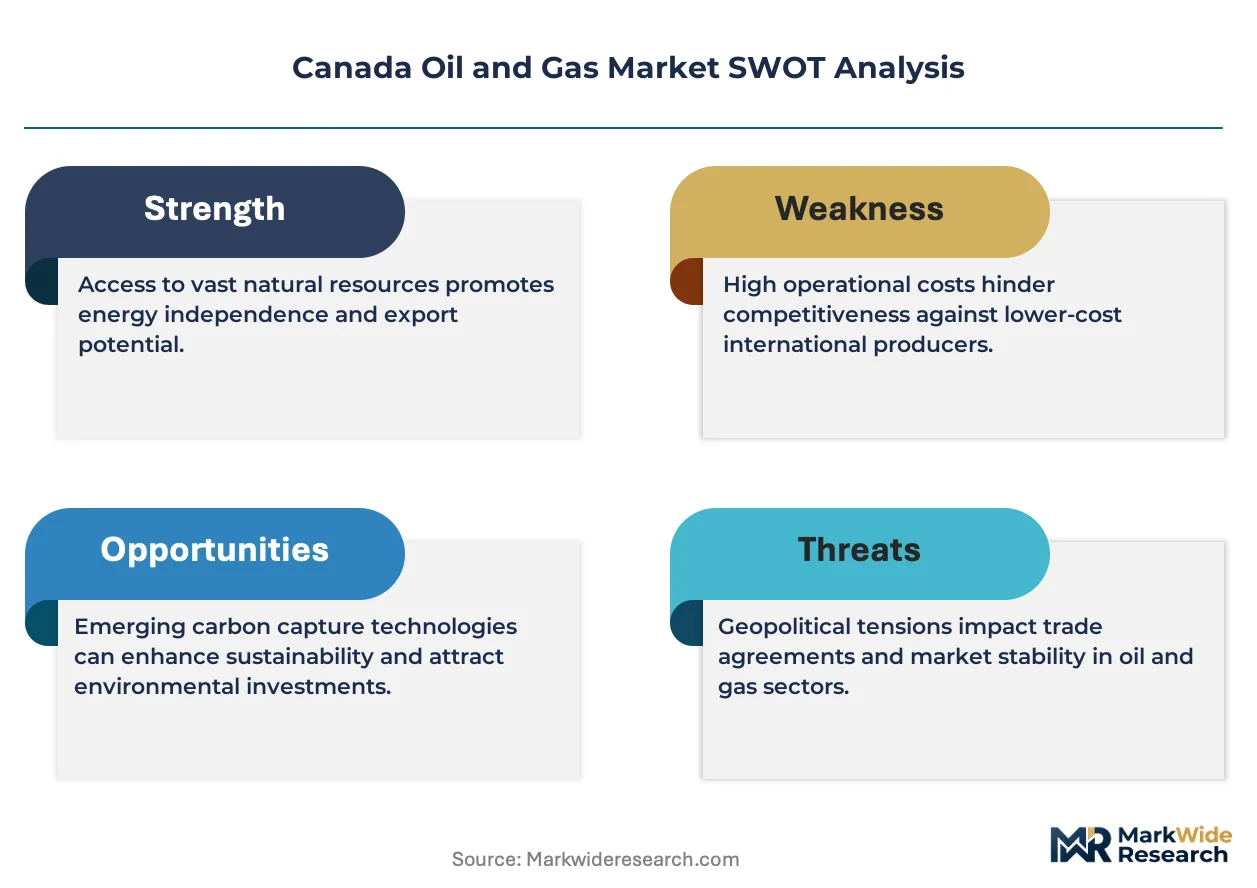
The federal methane regulations for the oil and gas sector is repositioning capital toward leak detection and repair technologies across Canadian production basins. Suncor Energy Inc. leverages its integrated refining and retail network to capture margin across the value chain. Canadian Natural Resources Ltd. anchors the thermal oil sands segment with extensive in-situ operations in northern Alberta. Enbridge Inc. controls critical pipeline infrastructure linking western supply to eastern refineries and U.S. export markets.
Canada oil and gas encompasses the exploration, production, processing, transportation, and refining of hydrocarbon resources including conventional crude, oil sands bitumen, and natural gas, with bitumen requiring steam-assisted gravity drainage or mining extraction to achieve flow characteristics suitable for pipeline transport and upgrading. The upstream segment dominates capital deployment through oil sands thermal projects and Montney shale gas development, while the midstream segment captures structural value from pipeline constraints and export capacity expansion. LNG export infrastructure under construction in British Columbia represents the fastest-growing application category, though downstream refining remains mature with limited greenfield capacity additions.
Health Canada and Environment and Climate Change Canada jointly administer emissions standards and health assessments affecting facility permitting and product specifications, while the Canada Energy Regulator governs interprovincial and international pipeline approvals that determine market access timelines. Provincial regulators including the Alberta Energy Regulator and British Columbia Oil and Gas Commission layer additional requirements for water use, seismic monitoring, and reclamation bonding that shape operating costs. Stakeholders must monitor the interplay between federal carbon pricing escalation and provincial royalty regime adjustments to determine long-term project economics and portfolio allocation priorities.
Market Dynamics
Alberta's oil sands corridor is driving capital allocation toward thermal production with integrated carbon capture, as federal methane regulations force rapid technology deployment across Canadian basins. The tension between provincial royalty optimization and federal emissions pricing creates divergent investment timelines.
Growth Catalysts
- Federal Methane Regulations:Mandatory leak detection and repair protocols are accelerating deployment of optical gas imaging and continuous monitoring systems across production facilities.
- Montney Shale Gas:Unconventional resource development in northeastern British Columbia and northwestern Alberta is expanding drilling programs and midstream compression infrastructure.
- LNG Export Infrastructure:Terminal construction on British Columbia's coast is opening new demand corridors for western Canadian natural gas into Asian markets.
Market Restraints
- Pipeline Capacity Constraints:Limited egress options from western supply basins create price differentials and force reliance on rail transport for incremental volumes.
- Carbon Pricing Escalation:Federal fuel charge and provincial output-based pricing systems compress operating margins for emissions-intensive thermal oil sands production.
- Capital Intensity of In-Situ Projects:Steam-assisted gravity drainage facilities require sustained multibillion-dollar commitments with decade-long payback horizons.
Strategic Opportunities
- Carbon Capture Integration:Federal investment tax credits and Alberta's TIER system create economic viability for large-scale sequestration hubs tied to oil sands operations.
- Small Modular Reactors:Nuclear energy applications for steam generation in thermal production offer pathway to near-zero emissions bitumen extraction.
- Petrochemical Feedstock Expansion:Alberta's propane dehydrogenation and polypropylene investments diversify value capture beyond combustion fuels.
Industry Challenges
- Geoscience Talent Pipeline:Retirement waves among experienced reservoir engineers and seismic interpreters constrain technical capacity for complex unconventional development.
- Indigenous Consultation Timelines:Prolonged duty-to-consult processes for pipeline routing and facility permitting extend project approval cycles unpredictably.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Oil and Gas Market |
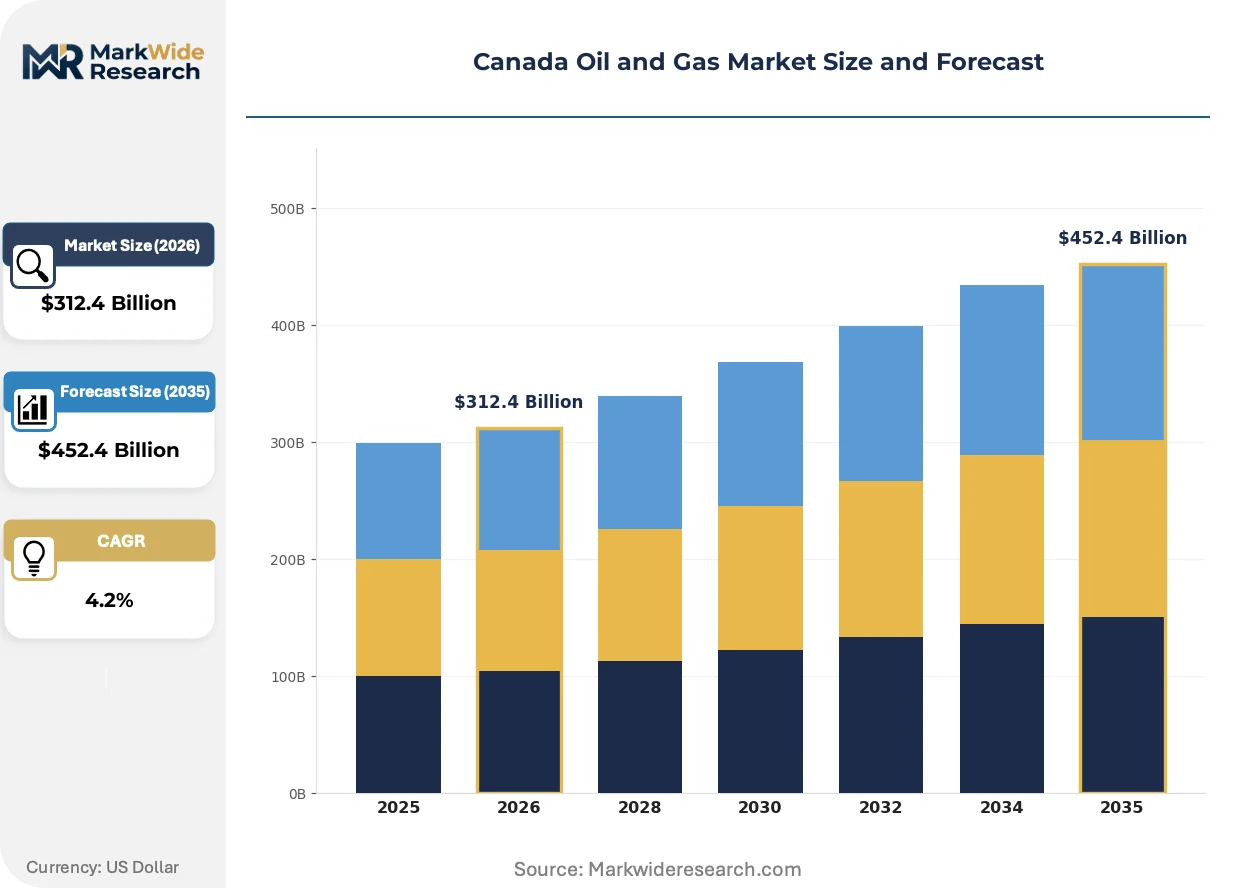
| Market Size in 2026 | $312.4 Billion |
| Market Size in 2035 | $452.4 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Upstream, Midstream, Downstream, Refining Application: Petroleum Production, Natural Gas Processing, Oil Sands, LNG Export Technology: Drilling, Hydraulic Fracturing, Enhanced Oil Recovery, Seismic Imaging End User: Utilities, Industrial, Transportation, Oilfield Services |
| Companies Covered | Cenovus Energy Inc., Suncor Energy Inc., Canadian Natural Resources Ltd., Imperial Oil Ltd., Enbridge Inc., Tourmaline Oil Corp., Whitecap Resources Inc., Pembina Pipeline Corp., Paramount Resources Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Oil and Gas Market Emerging Trajectories
Digitalization of subsurface characterization and surface operations is compressing decision cycles across Canadian oil and gas value chains. Three developments are restructuring competitive positioning.
Electrification of drilling rigs and hydraulic fracturing fleets is electrifying diesel-intensive wellsite operations. Producers in the Montney and Duvernay formations are contracting grid-powered or solar-battery hybrid equipment to reduce fuel costs and emissions intensity. This shift is compressing the operational cost structure for unconventional development while requiring transmission infrastructure upgrades in rural Alberta and British Columbia.
Canada's federal methane regulations are tightening measurement and reporting standards for fugitive emissions. The Canada Energy Regulator and provincial counterparts now mandate quarterly surveys with specified detection technologies. Upstream operators are responding by deploying aerial LiDAR and satellite monitoring across the oil sands and conventional basins, with capital reallocating toward predictive maintenance platforms.
Integrated majors are unbundling downstream logistics from production operations, creating standalone midstream entities. This restructuring separates commodity price exposure from fee-based transportation revenue, attracting institutional capital seeking yield stability. The pattern is most visible in Alberta's oil sands corridor, where pipeline and storage assets are being carved out into income-focused vehicles.
Canada Oil and Gas Market Segmentation
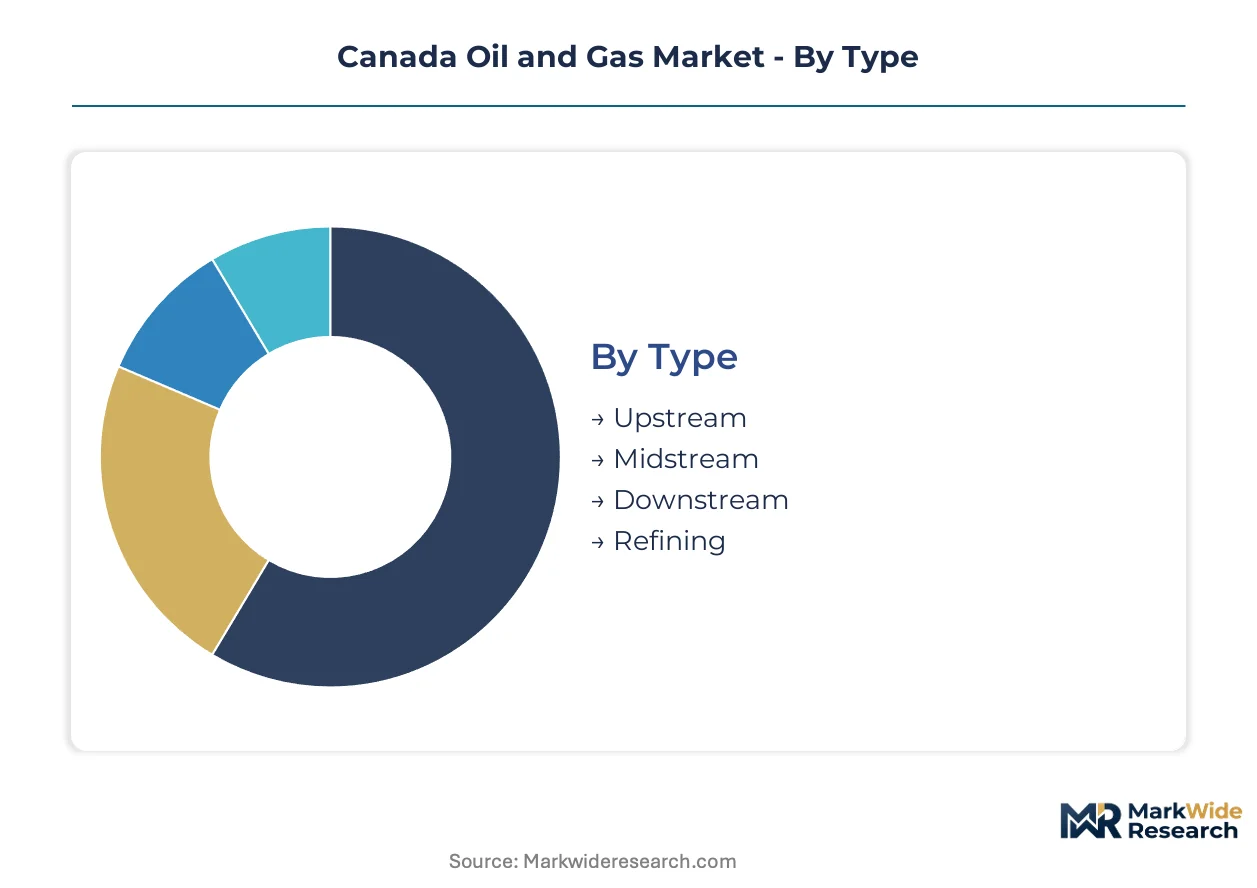
Segmentation of Canada's oil and gas market reveals how capital flows between standalone extraction operations and integrated value-chain systems. Each dimension—type, application, technology, and end user—exposes distinct margin structures and regulatory exposures that shape investment decisions across western Canadian basins.
Type:
Upstream segments operate as standalone profit centers with direct commodity exposure, while midstream and downstream functions embed into integrated corporate structures or spin out as fee-based entities.
- Upstream:Exploration and production activities span conventional crude, natural gas, and oil sands bitumen extraction. Alberta's oil sands corridor concentrates thermal in-situ development where steam-assisted gravity drainage dominates capital deployment amid federal methane compliance costs.
- Midstream:Pipeline transportation, storage terminals, and processing facilities bridge supply basins to market. Enbridge's Mainline system and Trans Mountain expansion illustrate how infrastructure constraints create structural value capture from western Canadian egress limitations.
- Downstream:Wholesale distribution and marketing of refined products and natural gas to end-use markets. This segment embeds into utility procurement networks across Ontario and Quebec where natural gas-fired power generation expands as transitional capacity.
- Refining:Conversion of crude oil into transportation fuels, heating oil, and petrochemical feedstocks. Strathcona and Sarnia facilities represent mature capacity with limited greenfield additions, forcing reliance on throughput optimization and carbon intensity reduction.
Upstream leads volumes today; midstream is gaining share fastest as asset unbundling accelerates.
Application:
Cost tier separation distinguishes capital-intensive thermal extraction from lower-barrier conventional production and processing activities.
- Petroleum Production:Conventional crude extraction from western Canadian sedimentary basins. Montney and Duvernay formations in Alberta and British Columbia attract drilling programs where electrified rigs compress operating costs.
- Natural Gas Processing:Treatment of raw gas to pipeline specifications including dehydration, compression, and liquids extraction. Northeastern British Columbia processing hubs expand to feed LNG export terminals under construction.
- Oil Sands:Bitumen extraction through mining or in-situ thermal methods requiring steam generation and water handling. Alberta's Athabasca region anchors thermal production where carbon capture integration determines project viability under federal pricing systems.
- LNG Export:Liquefaction of natural gas for marine transport to Asian markets. Kitimat terminal construction represents the steepest expansion trajectory as western Canadian gas seeks premium pricing outside North American markets.
Oil sands leads volumes today; LNG export is gaining share fastest.
Technology:
Technology maturity curves separate proven extraction methods from emerging digital and emissions-reduction systems.
- Drilling:Wellbore construction using rotary and directional techniques across conventional and unconventional reservoirs. Pad drilling in the Montney reduces surface footprint while accelerating well delivery timelines.
- Hydraulic Fracturing:Pressure-induced rock fracturing to enhance permeability in tight formations. Fleet electrification in Alberta and British Columbia cuts diesel consumption and aligns with provincial emissions regulations.
- Enhanced Oil Recovery:Injection of fluids or gases to mobilize residual hydrocarbons after primary production. Carbon dioxide flooding in Saskatchewan conventional fields leverages anthropogenic CO2 supply from industrial sources.
- Seismic Imaging:Subsurface characterization using reflection seismology for reservoir delineation. Machine learning interpretation compresses cycle times for Duvernay and Montney development decisions.
Drilling leads volumes today; seismic imaging is gaining share fastest.
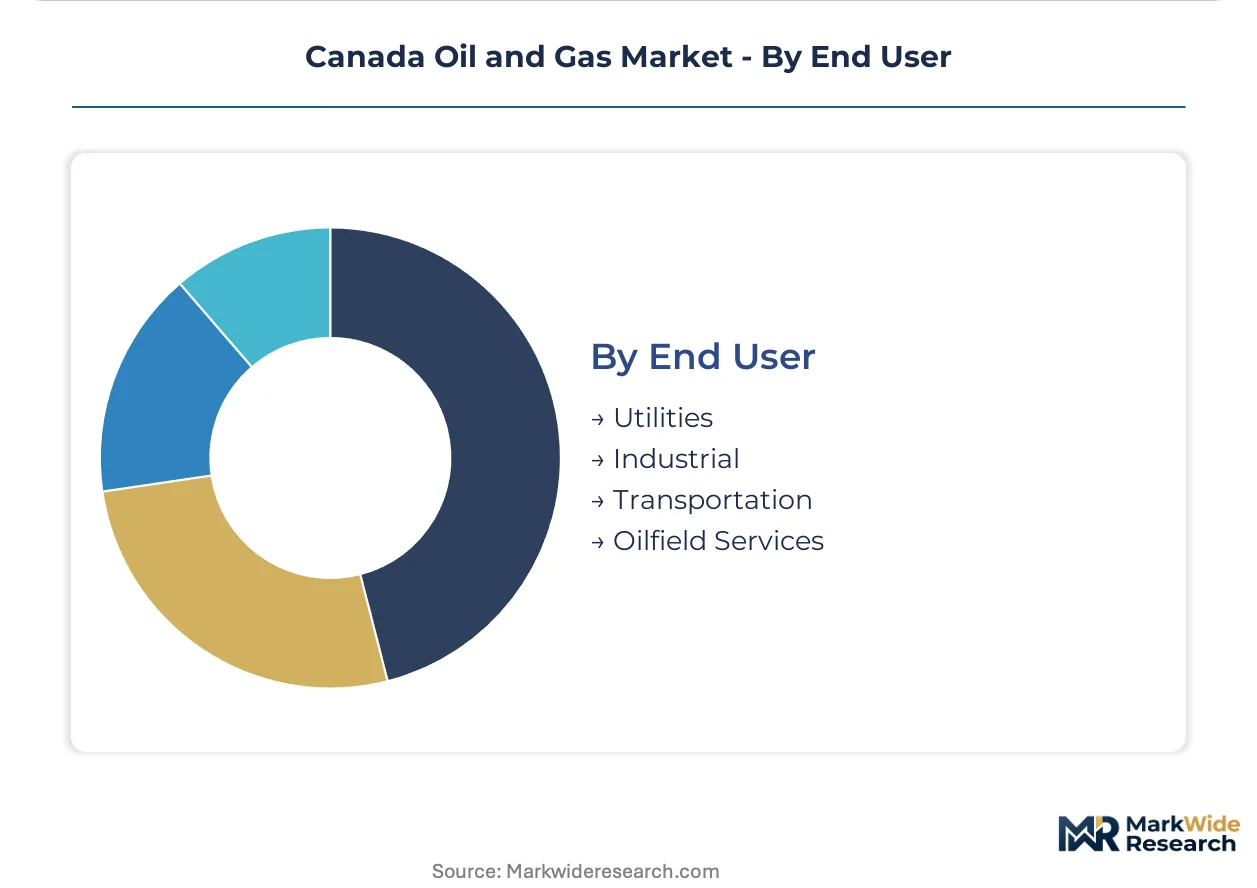
End User:
Customer type determines contract structures, with utilities offering long-term offtake stability against industrial spot-market exposure.
- Utilities:Electric power generators and natural gas distributors procuring fuel for generation and residential delivery. Ontario and Alberta utilities expand gas-fired capacity as coal retirement accelerates under federal regulations.
- Industrial:Manufacturing, mining, and petrochemical operations consuming fuel and feedstock. Alberta's propane dehydrogenation investments diversify demand beyond combustion into polypropylene production.
- Transportation:Fleet operators and marine bunkering consuming refined products and emerging alternative fuels. Rail transport fills pipeline capacity gaps for incremental oil sands volumes to U.S. refineries.
- Oilfield Services:Contractors supporting exploration, drilling, and completion activities. Pressure pumping and directional drilling specialists face margin compression as operator capital discipline extends cycle times.
Industrial leads volumes today; utilities are gaining share fastest as power sector decarbonization creates bridge-fuel demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Canadian oil and gas sector traces its modern origins to the 1947 Leduc discovery near Edmonton, which established Alberta as the dominant production basin and triggered federal-provincial jurisdictional frameworks that persist today.
Alberta
Thermal in-situ operations in the Athabasca oil sands corridor drive capital deployment, with steam-assisted gravity drainage facilities integrating carbon capture systems. The Alberta Energy Regulator administers water use permits and reclamation bonding requirements that shape operating costs. Calgary anchors corporate headquarters concentration while Fort McMurray hosts extraction operations where federal methane compliance accelerates leak detection technology adoption.
British Columbia
Montney shale gas development in the northeast Peace River region expands drilling programs and midstream compression infrastructure. The British Columbia Oil and Gas Commission layers seismic monitoring requirements and water management protocols on federal baseline standards. Kitimat hosts LNG export terminal construction that opens Asian demand corridors for western Canadian natural gas.
Ontario
Natural gas-fired power generation expansion proceeds as utilities retire coal capacity under federal clean electricity regulations. The Ontario Energy Board governs distribution rate applications and procurement frameworks affecting fuel demand. Sarnia's petrochemical corridor processes Alberta bitumen and Montney liquids into refined products and chemical feedstocks.
Saskatchewan
Enhanced oil recovery through carbon dioxide flooding mobilizes residual conventional crude in the Weyburn-Midale fields. The provincial Ministry of Energy and Resources oversees enhanced recovery incentive programs that leverage anthropogenic CO2 supply from industrial sources. Regina-based service companies support thermal and CO2 flood operations across the southeastern sedimentary basin.
Canada Oil and Gas Market Vendor Landscape
Capital-heavy integrated producers compete with asset-light exploration specialists for capital allocation in Canadian hydrocarbon basins. The market structure consolidates around three dominant archetypes: full-cycle majors controlling upstream-through-downstream value chains, pure-play upstream developers focused on single-basin growth, and fee-based midstream operators monetizing infrastructure bottlenecks. Strategic moves concentrate on carbon capture integration partnerships and midstream asset unbundling into income-focused vehicles.
Among Calgary-headquartered integrated operators, Canadian Natural Resources Ltd. and Suncor Energy Inc. exemplify the full-cycle archetype with thermal oil sands dominance and downstream refining exposure. Enbridge Inc. occupies a distinct position as infrastructure-focused entity controlling interprovincial pipeline corridors. Tourmaline Oil Corp. represents the pure-play natural gas developer archetype concentrated in Montney unconventional resource expansion.
| Leading Market Players |
|---|
| Cenovus Energy Inc. |
| Suncor Energy Inc. |
| Canadian Natural Resources Ltd. |
| Imperial Oil Ltd. |
| Enbridge Inc. |
| Tourmaline Oil Corp. |
| Whitecap Resources Inc. |
| Pembina Pipeline Corp. |
| Paramount Resources Ltd. |
| Others |
Supply Flow & Price Mechanics
Steam generation costs cascade through Alberta's thermal oil sands operations, compressing from natural gas input prices through SAGD facility operating margins to Western Canadian Select benchmark differentials against WTI. Federal carbon pricing escalation feeds directly into production economics, forcing operators to absorb costs or pass through to refiners with pipeline-constrained egress.
Pricing Analysis
Contract-based long-term offtake agreements dominate thermal oil sands and Montney gas sales, insulating producers from spot volatility while locking in basis differentials. Price differentiation rests on carbon intensity certification under Alberta's TIER system and methane compliance tier, with low-emission barrels commanding premium access to California LCFS markets. Pricing pressure stems from pipeline capacity constraints that force Western Canadian Select discounts wider when rail becomes marginal transport. Industrial buyers in Sarnia and Vancouver exhibit highest price sensitivity, while Asian LNG offtakers under 20-year contracts show least.
Supply Chain Analysis
Specialized drilling crews and SAGD facility operators concentrate in Calgary and Fort McMurray, with competition for reservoir engineers intensifying as retirement waves thin experienced ranks. Equipment manufacturing draws from the United States, Germany, and South Korea for high-pressure pumps, directional drilling systems, and modular processing units. Raw material dependencies include specialty steel alloys, proppant ceramics, and membrane filtration components. Supply chain risk centers on single-source vulnerability for subsea wellhead systems and long-lead compression equipment. Distribution runs through Enbridge's Mainline system and Trans Mountain pipeline to U.S. Midwest refineries and British Columbia tidewater.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Canada's oil and gas sector functions as a jurisdictional arbitrage between federal emissions pricing and provincial royalty optimization, with Alberta's TIER system offering cost relief unavailable under federal backstop rates in other provinces.
For Market Incumbents: Extend carbon capture integration partnerships to secure federal investment tax credits before credit phase-down accelerates. Consolidate midstream assets into standalone income vehicles to separate fee-based revenue from commodity exposure. Electrification of SAGD operations represents the critical lever against rising carbon costs, though grid transmission upgrades in northern Alberta lag deployment timelines. For New Entrants and Emerging Players: Direct-to-industrial sales platforms for low-carbon natural gas bypass traditional utility intermediaries and capture green-premium pricing from manufacturing buyers in Ontario and Quebec. White-space concentration sits with Montney liquids-rich windows where pad drilling density remains below optimal spacing. Indigenous partnership structures offer accelerated permitting pathways for pipeline lateral projects. For Investors and Strategic Acquirers: Consolidation pressure builds where subscale Montney operators face capital discipline from lenders wary of single-basin concentration. Long-term viability favors integrated majors with downstream refining exposure and carbon capture hub positioning. Watch for inflection in differential narrowing between Western Canadian Select and Maya crude, signaling egress constraint relief.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Capture Hub Development | Federal investment tax credits and Alberta TIER compliance create economic viability for oil sands sequestration clusters. |
| Midstream Asset Unbundling | Standalone pipeline entities attract institutional capital seeking yield stability separate from commodity volatility. |
| Montney Pad Density Optimization | Electrified rig fleets and machine-learned seismic interpretation compress well delivery timelines in northeastern British Columbia. |
| LNG Export Terminal Completion | Kitimat liquefaction capacity opens premium Asian pricing corridors for western Canadian natural gas producers. |
| Small Modular Reactor Pilot | Nuclear steam generation for SAGD operations offers pathway to near-zero emissions bitumen extraction in Athabasca. |
Methodological Framework
Coverage spans Alberta, British Columbia, Ontario, and Saskatchewan, with primary inputs from each province's regulatory and operating environment. Interviews incorporated reservoir engineers at thermal oil sands operators, Alberta Energy Regulator permitting officials, utility fuel procurement managers at Ontario power generators, and midstream commercial directors at pipeline entities. Secondary validation drew from Canada Energy Regulator pipeline filings, Alberta government royalty and production statistics, British Columbia Oil and Gas Commission water use disclosures, and Environment and Climate Change Canada emissions inventories. Bottom-up project-level economics triangulated against top-down provincial production forecasts.
Segmentation granularity modeled upstream, midstream, downstream, and refining functions separately, with technology splits for drilling, hydraulic fracturing, enhanced recovery, and seismic imaging. Application dimensions included petroleum production, natural gas processing, oil sands extraction, and LNG export. End-user categories captured utilities, industrial, transportation, and oilfield services procurement patterns. CAGRs derived from production decline curve analysis, capital expenditure schedules for sanctioned projects, and regulatory scenario modeling across federal carbon pricing trajectories. Forecast inputs incorporated methane compliance cost curves, LNG offtake contract structures, and pipeline capacity expansion timelines.
The model assumes a particular technology adoption path; alternative pathways for small modular reactor steam generation or electrified SAGD would alter the outlook for oil sands emissions intensity and operating cost structures. Forecasts embed assumptions regarding federal-provincial carbon pricing coordination, Indigenous consultation timelines for pipeline routing, and Asian LNG demand elasticity. Material deviation in carbon border adjustment implementation, TIER system amendments, or Trans Mountain throughput expansion warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Norway Oilfield Equipment Rental Services Market
Oil & Gas
Oil and Gas Well Conductor Installation Services Market
Oil & Gas
Modular Refinery Market
Oil & Gas
Nigeria Oil and Gas Midstream Market
Oil & Gas
Offshore Drilling Fluid Market
Oil & Gas
Asia-Pacific Oil Country Tubular Goods Market
Oil & Gas
Norway Oilfield Equipment Market
Oil & Gas
Subsea Flowlines Market
Oil & Gas
Sudan Oil and Gas Market
Oil & Gas
United States Onshore Drilling Fluid Market
Oil & Gas
Middle East Natural Gas Market
Oil & Gas
Global Deep-Well Disposal Services Market
Oil & Gas
Oilfield Market
Oil & Gas
Oil and Gas Industry Turbomachinery Market
Oil & Gas
Pipeline Integrity Market
Oil & Gas
Oil and Gas Gasket Market