
 Kuwait Oil and Gas Upstream Market | 2026-2036
Kuwait Oil and Gas Upstream Market Size, Share, and Industry Trends Forecast 2026-2036
Kuwait Oil and Gas Upstream Market Foresight
Integrated well services and long-term production maintenance contracts is rebalancing how upstream value gets captured in Kuwait. Kuwait Petroleum Corporation leverages its vertical control over the entire hydrocarbon chain from exploration through export. Schlumberger Limited sustains technology leadership in reservoir characterization and digital oilfield solutions across Kuwaiti concessions. Baker Hughes Co. competes through specialized drilling systems and artificial lift technologies tailored to mature field conditions.
Kuwait Oil and Gas Upstream encompasses exploration, drilling, and production activities targeting crude oil and natural gas reservoirs, utilizing seismic surveying, directional drilling, and artificial lift systems to extract hydrocarbons from onshore and offshore formations. Enhanced Oil Recovery leads technology deployment as mature fields require thermal and chemical injection methods to sustain plateau production rates. Horizontal Drilling occupies growing share in heavy oil redevelopment projects targeting the Lower Fars formation. National Oil Companies dominate end-user demand through KPC's centralized capital allocation and field development planning.
Kuwait's Ministry of Oil and the Environment Public Authority enforce flaring reduction mandates and environmental impact assessments that shape drilling permit timelines and production facility design standards. The Supreme Petroleum Council sets capacity targets that directly determine annual upstream capital budgets and foreign partnership terms. Stakeholders must monitor how KPC's strategic shift toward international offshore exploration alters domestic service procurement priorities and contractor qualification requirements.
Market Dynamics
Enhanced oil recovery deployment is compressing production economics across Kuwait's mature Burgan and Lower Fars formations, forcing capital reallocation toward thermal and chemical injection methods that sustain plateau rates in aging reservoirs.
Growth Catalysts
- Supreme Petroleum Council capacity mandates:KPC's centralized target-setting directs annual upstream capital budgets toward heavy oil redevelopment and offshore exploration blocks.
- Horizontal drilling penetration:Directional drilling systems unlock heavy oil reserves in the Lower Fars formation that vertical wells cannot economically access.
- Artificial lift modernization:Sucker rod and electric submersible pump upgrades extend well life across Burgan Field's mature production zones.
Market Restraints
- Specialized equipment import dependency:Directional drilling motors and high-pressure pumping units concentrate supply with US and European OEMs, exposing procurement to currency volatility and lead-time extension.
- Flaring reduction compliance costs:Kuwait Environment Public Authority mandates require gas capture infrastructure investment that extends project payback periods.
- Reservoir complexity escalation:Heavy oil viscosity and carbonate heterogeneity constrain recovery factors below light crude benchmarks.
Strategic Opportunities
- Offshore exploration licensing:KPC's strategic pivot toward international offshore blocks creates demand for subsea engineering and floating production expertise.
- Digital oilfield convergence:Real-time reservoir monitoring combined with predictive maintenance algorithms reduces unplanned downtime across gathering networks.
- Integrated service contracting:Long-term production maintenance agreements replace discrete well service awards, locking in decade-spanning revenue visibility.
Industry Challenges
- Enhanced recovery engineering talent scarcity:Thermal EOR design and chemical formulation expertise concentrates with a narrow cohort of specialists, constraining project staffing velocity.
- Legacy SCADA integration friction:New digital oilfield platforms must interface with decades-old control systems across Burgan's centralized production facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kuwait Oil and Gas Upstream Market |
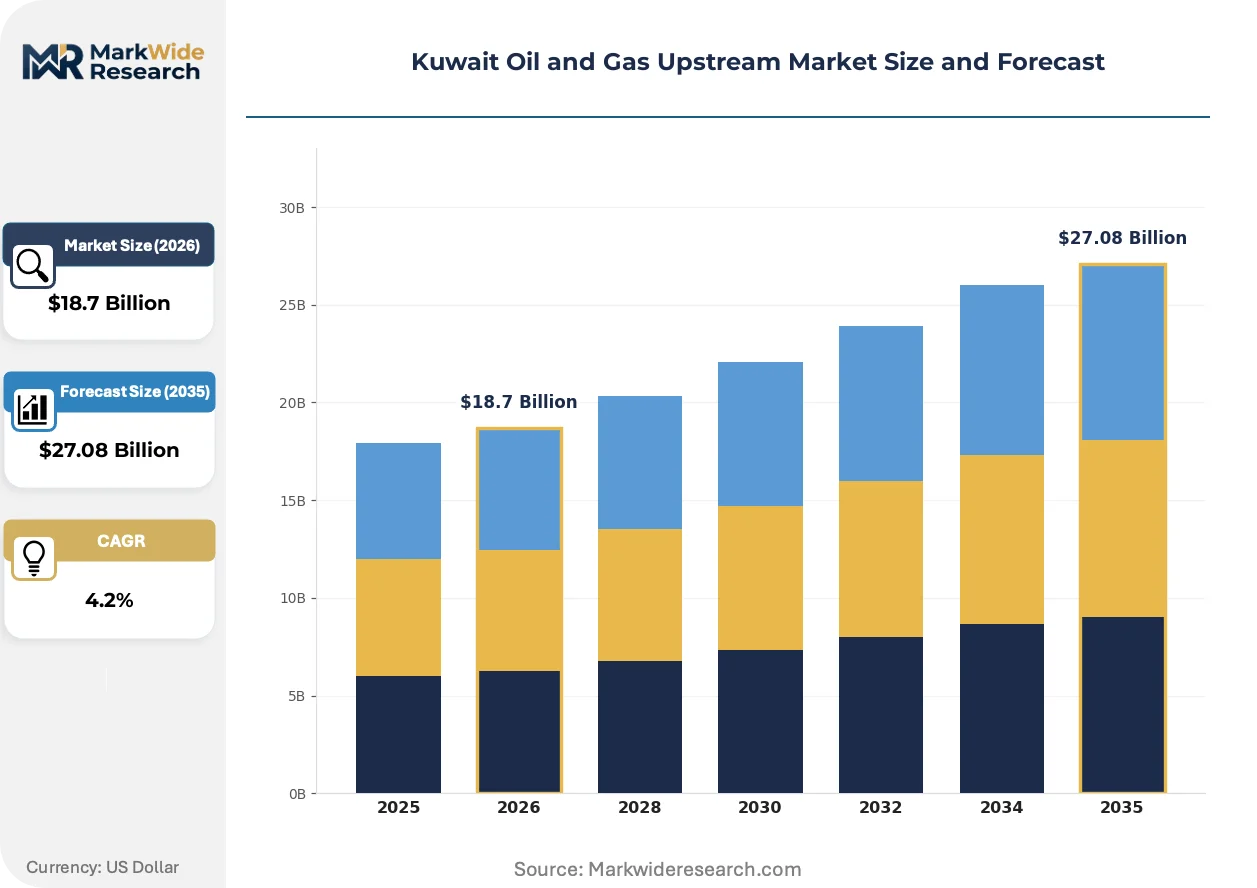
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $27.08 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Exploration, Drilling, Production, Well Services Technology: Seismic Surveying, Enhanced Oil Recovery, Hydraulic Fracturing, Horizontal Drilling End User: National Oil Companies, Independent Producers, Oilfield Service Companies, Engineering Firms Deployment: Fixed Platforms, Floating Production Storage and Offloading, Subsea Systems, Integrated Operations |
| Companies Covered | Kuwait Petroleum Corporation, Kuwait Energy PLC, Schlumberger Limited, Baker Hughes Co., Saudi Arabian Oil Co., Chevron Corporation, BP PLC, Petrofac Limited, Kuwait Gulf Oil Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kuwait Oil and Gas Upstream Market Shifts & Advancements
Technology deployment in Kuwait's upstream sector is pivoting from discrete tool adoption toward integrated systems that compress decision cycles between reservoir characterization and production optimization.
Modular skid-mounted pumping units is modularizing artificial lift deployment across Kuwait's heavy oil redevelopment projects. KPC's field operators are adopting these containerized systems to reduce rig-up time and enable rapid relocation between well pads. The technology is compressing capital intensity thresholds for marginal well economics.
Kuwait's Environment Public Authority flaring reduction mandates are tightening gas capture requirements across all new drilling permits. Operators must install vapor recovery units and closed-loop flare systems before production commencement. Heavy oil thermal projects face the steepest compliance cost escalation given their inherently higher gas-oil ratios.
Service contract unbundling is fragmenting procurement patterns that previously favored integrated drilling packages. KPC's subsidiary operators are now awarding reservoir characterization, directional drilling, and artificial lift as separate technical scopes. This shift is most pronounced in the Lower Fars heavy oil redevelopment where specialized thermal EOR contractors displace generalist drilling fleets.
Kuwait Oil and Gas Upstream Market Segmentation
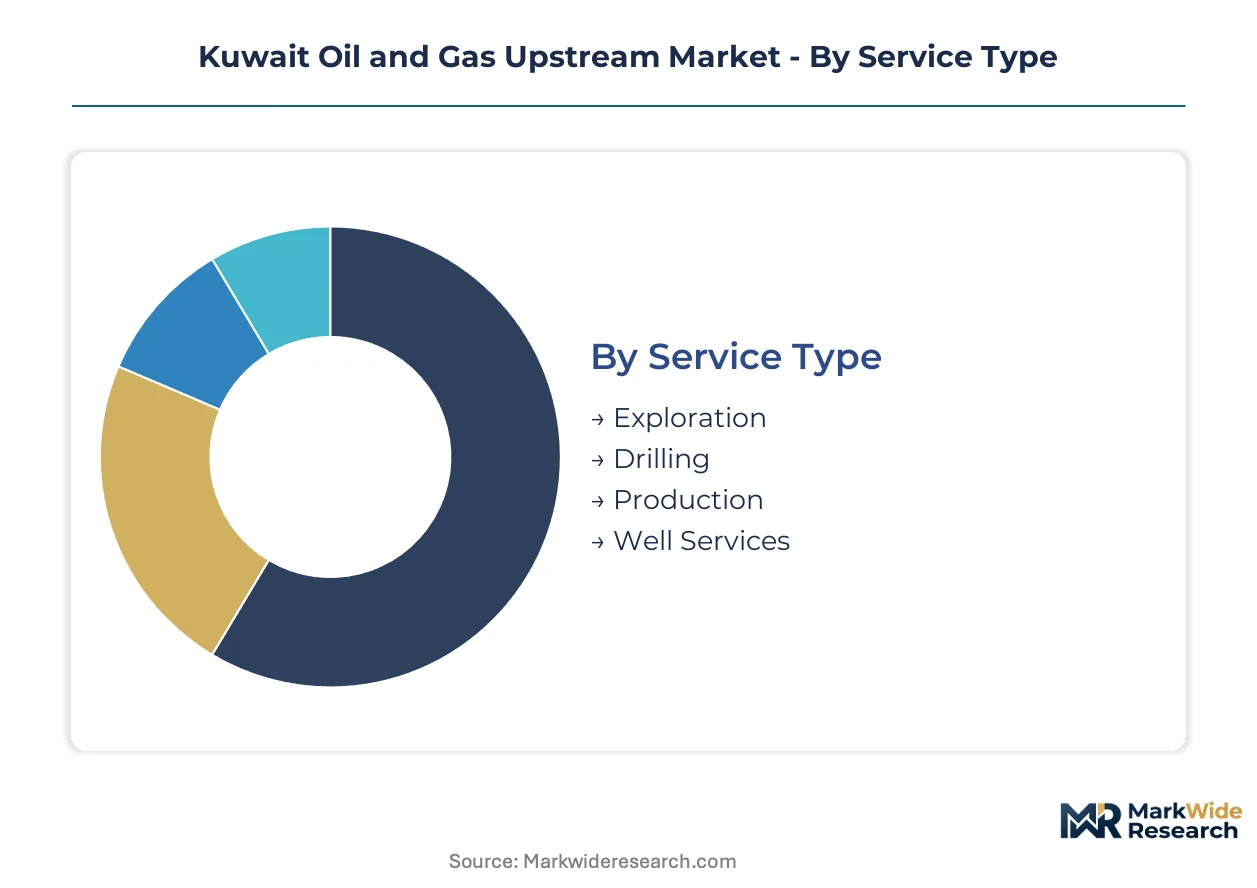
Kuwait's upstream procurement patterns diverge sharply across service tiers and technology maturity levels. Capital allocation decisions at KPC and its operating subsidiaries concentrate demand in distinct segments with diverging margin profiles and contract tenures.
Service Type:
Operator budget authority determines which service tier captures upstream spend.
- Production:Sustained plateau operations across Burgan Field and Lower Fars redevelopment anchor this segment. KOC's long-term production maintenance agreements favor integrated contractors capable of artificial lift optimization and surface facility management across mature well stock.
- Drilling:Directional drilling systems and rig mobilization dominate capital deployment in heavy oil zones where vertical well economics fail. Horizontal penetration rates in Lower Fars formations drive demand for specialized mud systems and bottom-hole assembly suppliers.
- Exploration:Seismic acquisition and wildcat drilling concentrate in KPC's emerging offshore frontier blocks where data scarcity elevates geophysical survey intensity.
- Well Services:Workover rigs and completion interventions address Burgan's aging well population with escalating frequency as reservoir pressure declines accelerate.
Volume sits with Production; growth tilts toward Drilling.
Technology:
Field maturity dictates technology selection across Kuwait's asset base.
- Enhanced Oil Recovery:Thermal and chemical injection methods sustain output from Burgan's mature carbonate reservoirs and Lower Fars heavy oil deposits. KOC's capacity targets depend on EOR deployment as natural decline rates steepen across legacy production zones.
- Horizontal Drilling:Extended-reach laterals unlock heavy oil reserves in Lower Fars formations where conventional vertical completions prove uneconomic. Directional drilling intensity is climbing fastest in heavy oil redevelopment budgets.
- Seismic Surveying:3D seismic acquisition supports exploration licensing rounds and reservoir characterization for EOR design in carbonate heterogeneity zones.
- Hydraulic Fracturing:Limited application in Kuwait's naturally fractured carbonate reservoirs contrasts with shale-dominated markets, constraining service provider specialization.
Enhanced Oil Recovery commands current spend; Horizontal Drilling is expanding most quickly.
End User:
Contracting structure determines which entity category captures service procurement.
- National Oil Companies:KPC and its operating subsidiaries KOC, KNPC, and KUFPEC centralize upstream investment decisions through Supreme Petroleum Council-mandated capacity targets. Their integrated field development planning dominates service demand aggregation.
- Oilfield Service Companies:Schlumberger, Baker Hughes, and Halliburton compete for integrated drilling and production maintenance contracts through technology partnerships and local content commitments.
- Independent Producers:Minimal presence in Kuwait's NOC-dominated upstream structure limits this segment to marginal farm-in opportunities on frontier blocks.
- Engineering Firms:FEED contractors and EPC specialists capture offshore project development work as KPC pivots toward international exploration.
National Oil Companies anchor procurement volume; Oilfield Service Companies face margin pressure from contract unbundling.
Deployment:
Asset location and water depth dictate infrastructure configuration.
- Fixed Platforms:Burgan Field's shallow-water legacy infrastructure and onshore gathering systems dominate Kuwait's current production base. Platform maintenance and brownfield upgrades absorb majority of deployment-related capital.
- Floating Production Storage and Offloading:KPC's strategic shift toward international offshore blocks elevates FPSO demand for deepwater developments beyond Kuwait's territorial waters.
- Subsea Systems:Tieback architecture and subsea processing units feature in frontier exploration planning where seabed conditions favor minimal surface footprint.
- Integrated Operations:Digital oilfield convergence and centralized control room architecture reduce staffing requirements across Burgan's distributed well pads.
Fixed Platforms retain volume dominance; Floating Production Storage and Offloading is gaining share fastest as KPC diversifies geographically.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
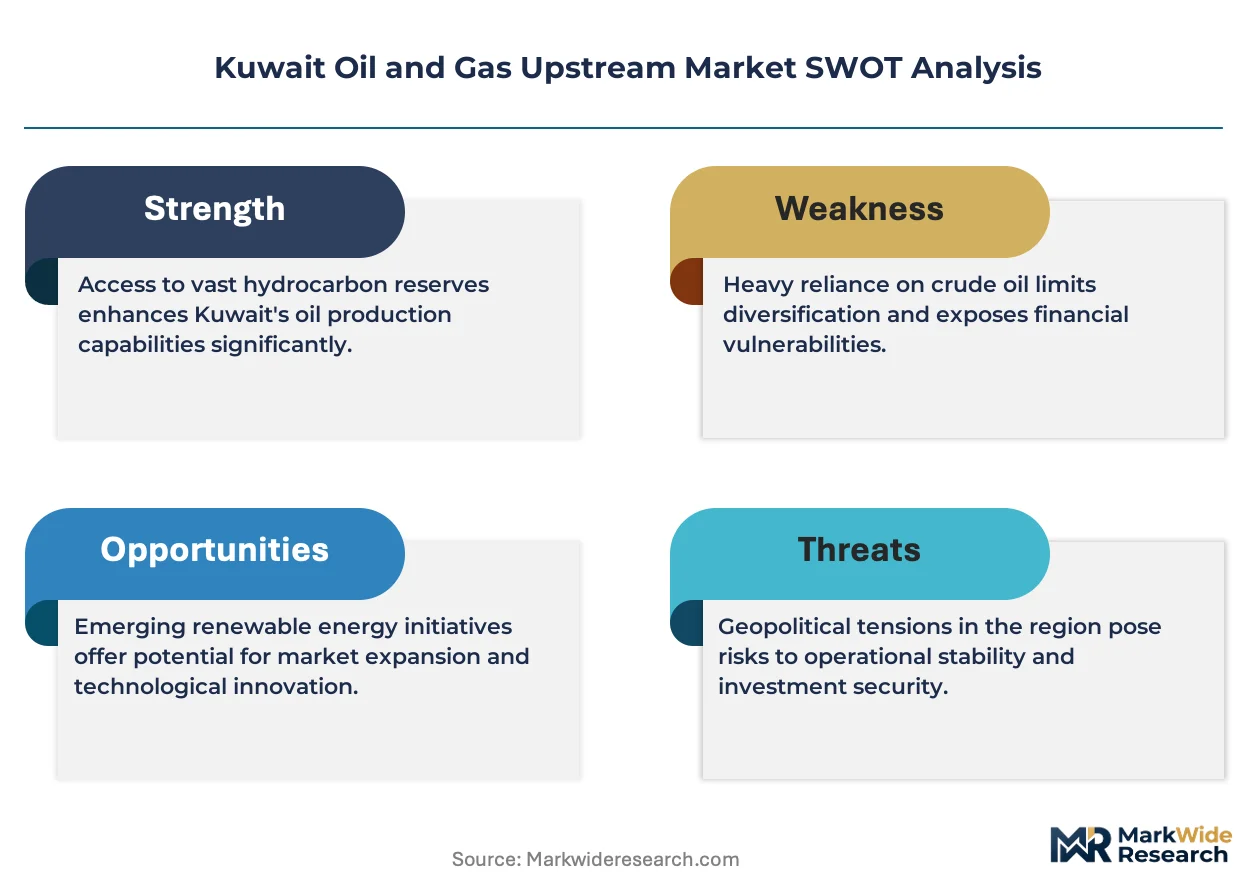
Kuwait's domestic production capacity outstrips local consumption by substantial margins, positioning the emirate as a net exporter with upstream investment decisions driven by export market requirements rather than internal energy security. The Supreme Petroleum Council's capacity mandates direct capital allocation across mature onshore redevelopment and frontier offshore exploration. Field development priorities concentrate in heavy oil zones and carbonate reservoir extensions where enhanced recovery techniques sustain plateau output.
United States
Permian Basin operators deploy horizontal drilling and hydraulic fracturing at scale unmatched elsewhere, with the EPA's methane emissions regulations tightening fugitive gas capture standards across drilling permits. Houston anchors the global oilfield services supply chain, with engineering firms clustering around specialized directional drilling and subsea technology development.
Saudi Arabia
Saudi Aramco's maximum sustained capacity targets drive demand for smart well completions and reservoir monitoring systems across Ghawar and Safaniya fields. The Ministry of Energy's gas expansion program mandates flare elimination timelines that accelerate gas processing infrastructure deployment. Dhahran's technology centers concentrate artificial lift optimization and digital oilfield integration expertise.
United Arab Emirates
ADNOC's production capacity expansion toward 5 million barrels per day elevates demand for enhanced oil recovery contracting and offshore platform engineering. The Supreme Petroleum Council's local content requirements reshape procurement patterns toward in-country value creation. Abu Dhabi's industrial zones host integrated drilling and production maintenance service hubs serving regional offshore developments.
Norway
Equinor's Johan Sverdrup and Northern Lights projects demonstrate subsea compression and carbon capture integration at commercial scale. The Norwegian Petroleum Directorate's emissions reduction targets accelerate electrification of offshore platforms and floating wind tie-ins. Stavanger's engineering cluster specializes in harsh-environment subsea systems and Arctic drilling technology.
Brazil
Petrobras' pre-salt development programs sustain demand for ultra-deepwater drilling rigs and subsea production systems beneath thick salt layers. ANP's local content regulations mandate domestic fabrication percentages for floating production units and subsea equipment. Rio de Janeiro's offshore engineering sector concentrates FPSO integration and subsea tieback expertise.
Kuwait Oil and Gas Upstream Market Competitive Landscape
Top-tier vendors anchor integrated service contracting, while specialized technology providers occupy niche positions in reservoir characterization and artificial lift systems. The market structure concentrates around national oil company procurement centralization through KPC and its operating subsidiaries. Three archetypes dominate: vertically integrated international service conglomerates, regional engineering specialists with heavy oil expertise, and technology licensors with proprietary enhanced recovery methods. Competitive dynamics center on long-term production maintenance agreement awards and partnership structures for frontier offshore blocks.
Within the integrated service tier, Schlumberger Limited and Baker Hughes Co. exemplify full-spectrum providers capable of bundling directional drilling, reservoir characterization, and artificial lift across Kuwaiti concessions. Kuwait Petroleum Corporation occupies a singular position as both demand aggregator and field operator, centralizing capital allocation through Supreme Petroleum Council-mandated capacity targets. Chevron Corporation represents the international oil company archetype participating through technical service agreements and heavy oil redevelopment partnerships.
| Leading Market Players |
|---|
| Kuwait Petroleum Corporation |
| Kuwait Energy PLC |
| Schlumberger Limited |
| Baker Hughes Co. |
| Saudi Arabian Oil Co. |
| Chevron Corporation |
| BP PLC |
| Petrofac Limited |
| Kuwait Gulf Oil Company |
| Others |
Supply & Pricing Matrix
Horizontal drilling penetration across Kuwait's Lower Fars heavy oil zones is compressing per-well economics while concentrating procurement leverage with directional drilling specialists and high-pressure pumping unit suppliers. This technology shift simultaneously elevates capital intensity thresholds and fragments vendor relationships as KPC's subsidiaries unbundle integrated service contracts into discrete technical scopes.
Pricing Analysis
Cost-down pressure on drilling services accelerates because KOC's contract unbundling fragments previously integrated packages into separately bid reservoir characterization, directional drilling, and artificial lift scopes. Project-based pricing dominates, with differentiation across premium-tier digital oilfield integration, standard-tier equipment supply, and economy-tier labor-only services. Price differentiation traces to technology sophistication and local content certification levels. Small regional contractors exhibit highest price sensitivity; integrated international vendors absorb margin compression through scale.
Supply Chain Analysis
Direct-to-operator channels handle KPC's centralized procurement demand, with specialized equipment flowing through Houston, Aberdeen, and Singapore engineering hubs. Directional drilling motors, high-pressure pumping units, and subsea processing components draw from US, European, and East Asian manufacturing concentrations. Single-source vulnerability concentrates in advanced downhole telemetry and thermal EOR chemical formulations. Distribution runs through long-term production maintenance agreements that lock in decade-spanning revenue visibility.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Kuwait's upstream service market is consolidating around technology leaders capable of delivering integrated digital oilfield solutions, as contract unbundling and procurement centralization squeeze mid-tier generalists without specialized heavy oil or subsea capabilities.
For Market Incumbents: To counter margin compression from KPC's contract unbundling, Schlumberger and Baker Hughes should deepen backward integration into modular skid-mounted pumping unit manufacturing and captive supply of high-pressure fracturing consumables. Securing long-term production maintenance agreements across Burgan Field's mature zones locks in revenue visibility that discrete well service awards cannot match.
For New Entrants and Emerging Players: Launch via specialized thermal EOR engineering partnerships targeting Kuwait's Lower Fars heavy oil redevelopment, where reservoir complexity and chemical formulation expertise create defendable positioning. White-space opportunity concentrates in digital oilfield integration services for legacy SCADA system upgrades and real-time reservoir monitoring platforms that interface with decades-old Burgan control infrastructure.
For Investors and Strategic Acquirers: Re-rating potential sits with heavy oil thermal EOR specialists given KPC's capacity mandates and natural decline acceleration across mature carbonate reservoirs. Acquisition targets should demonstrate proprietary chemical formulation IP and established Kuwait Environment Public Authority compliance track records. Watch KPC's offshore exploration licensing rounds as inflection indicators for subsea engineering demand migration beyond domestic territorial waters.
| Strategic Initiative | Industry Significance |
|---|---|
| Enhanced Oil Recovery Technology Licensing | Proprietary thermal and chemical injection methods differentiate bidders for KOC's long-term production maintenance agreements. |
| Digital Oilfield Platform Integration | Real-time reservoir monitoring capabilities reduce unplanned downtime across Burgan Field's centralized production facilities. |
| Modular Artificial Lift Manufacturing Scale-Up | Skid-mounted pumping units compress rig-up time and enable rapid relocation between Kuwait's heavy oil well pads. |
| Subsea Engineering Joint Venture | Floating production expertise positions partners for KPC's strategic pivot toward international offshore exploration blocks. |
| Local Content Certification Program | Supreme Petroleum Council procurement preferences favor contractors meeting in-country value creation thresholds. |
Research Methodology
Multi-period observation of drilling contract award patterns, EOR deployment rates, and KPC capital allocation cycles anchored the trend analysis, supplemented by interviews with reservoir engineers at Kuwait Oil Company, procurement leads at KPC subsidiaries, artificial lift specialists at Baker Hughes and Schlumberger, and thermal EOR contractors active in Lower Fars redevelopment. Secondary validation drew from Supreme Petroleum Council capacity mandate disclosures, Kuwait Environment Public Authority flaring compliance filings, and OPEC production data. Bottom-up well-count modeling and top-down expenditure triangulation cross-checked volume estimates.
Segment-weighting across service type, technology maturity, and deployment mode informed the analytical framework throughout the forecast period. Modeled dimensions included production maintenance versus drilling versus exploration spend, enhanced oil recovery versus horizontal drilling technology categories, and fixed platform versus floating production infrastructure configurations. CAGRs derived from elasticity analysis linking KPC capacity targets to required well intervention intensity and EOR injection volumes. Forecast inputs incorporated reservoir decline curve trajectories and heavy oil viscosity constraints on recovery factors.
Regulatory enforcement shifts, KPC strategic redirection toward international offshore blocks, and thermal EOR chemical supply disruptions are the dominant revision risks to upstream expenditure trajectories. Forecasts reflect documented assumptions regarding Supreme Petroleum Council mandate continuity and Burgan Field natural decline rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Downhole Tractor Market
Oil & Gas
Subsea Multiphase Flowmeter Market
Oil & Gas
Egypt Natural Gas Market
Oil & Gas
Subsea Well Access System Market
Oil & Gas
Sidetracking Market
Oil & Gas
Oriented Perforating System Market
Oil & Gas
Oil and Gas Processing Seals Market
Oil & Gas
Coal Mining Market
Oil & Gas
North America Perforating Gun Market
Oil & Gas
Netherlands LNG Bunkering Market
Oil & Gas
Thailand Oil and Gas Market
Oil & Gas
North America Directional Drilling Services Market
Oil & Gas
Digital Drilling Rigs Market
Oil & Gas
Oilfield Roller Chain Market
Oil & Gas
Uzbekistan Oil and Gas Market
Oil & Gas
Mexico Oil and Gas Downstream Market