
 Drilling Mud Desander and Desilter Market | 2026-2036
Drilling Mud Desander and Desilter Market Size, Share, and Industry Trends Forecast 2026-2036
Drilling Mud Desander and Desilter Market Analysis
Market Context with Strategic Players
Multi-source procurement for hydrocyclone cones and shaker screens is restructuring supply relationships across the solids control supply base. National Oilwell Varco leverages its integrated rig systems portfolio to bundle desander units with broader drilling packages. Derrick Corporation differentiates through proprietary screen technology that extends operating life in high-solids drilling environments. Kosun Machinery competes on manufacturing scale, anchoring cost-efficient production for Asian offshore contractors.
Technical Definition and Structural Segments
Drilling mud desanders and desilters are solids control devices that use hydrocyclone separation to remove sand-sized and silt-sized particles from drilling fluid, typically operating at 4-inch to 12-inch cone diameters with 15-75 psi inlet pressure to maintain fluid weight and rheology within API specifications. Hydrocyclones dominate product type revenue due to universal deployment across onshore and offshore rigs, while centrifuges capture premium margin pools where operators demand ultra-fine cuttings separation for synthetic-based mud systems. Within end users, oil and gas applications anchor volume demand, though mining and water well segments are expanding fastest as exploration moves into geologically complex formations requiring advanced solids control.
Regulatory Framework and Forward Outlook
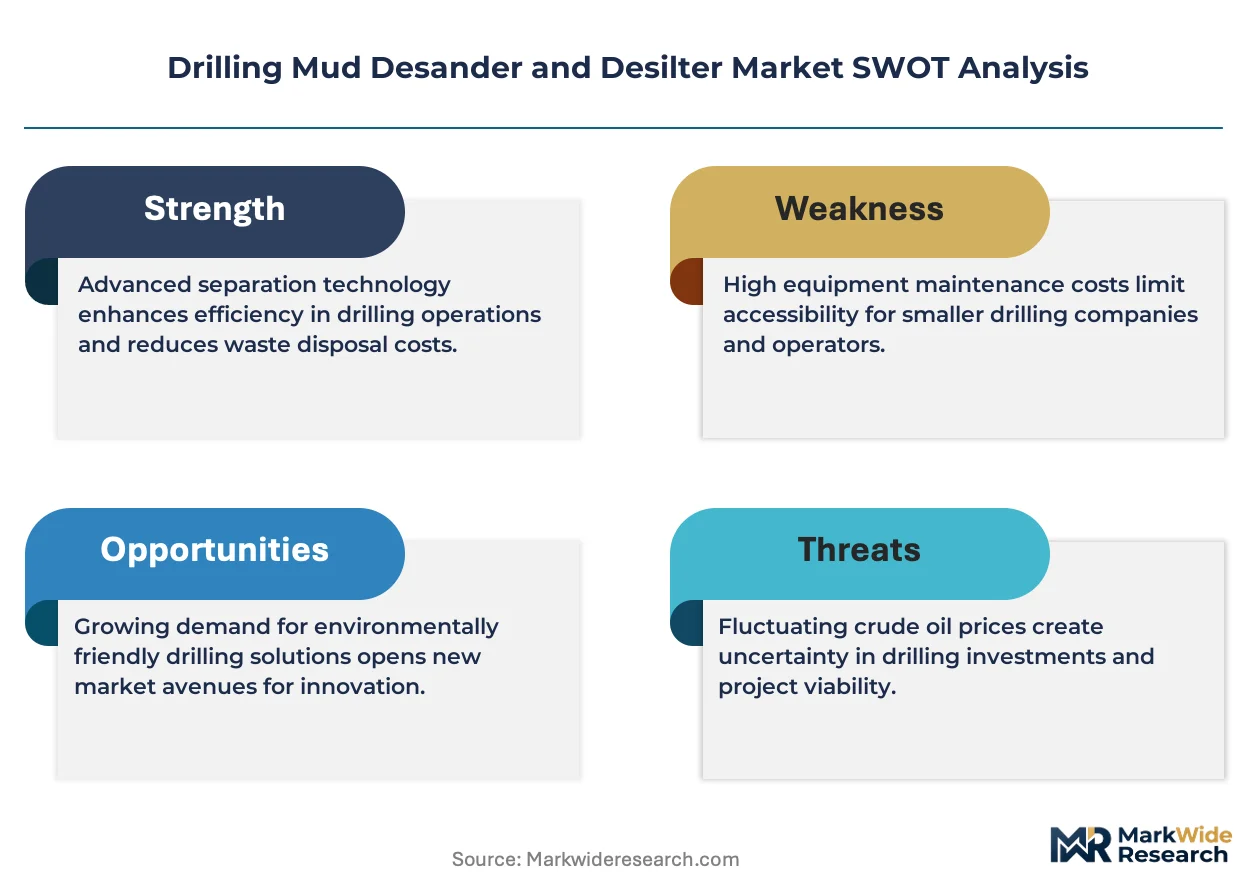
API standards govern equipment performance testing and classification, while EPA regulations in the United States and OSPAR guidelines in the North Sea constrain drilling waste discharge and compel closed-loop mud system adoption. BSEE well control rules and offshore safety directives from Norway's Petroleum Safety Authority shape capital allocation toward redundant solids control capacity. Stakeholders must monitor how evolving cuttings disposal regulations in multiple jurisdictions redefine the total cost of ownership for desander and desilter fleets.
Market Dynamics
Integrated solids control packages are compressing procurement cycles as offshore contractors in the Gulf of Mexico and North Sea consolidate vendor relationships around single-source hydrocyclone and shaker screen suppliers.
Growth Catalysts
- Pad drilling intensity:Permian Basin operators now run desander and desilter units at 40% higher utilization rates per rig, forcing faster replacement of cone assemblies and screen media.
- EPA closed-loop mandates:Stricter drilling waste discharge rules compel operators to install redundant solids control capacity, expanding the installed base of hydrocyclone units.
- API 13C specification tightening:New shaker performance testing protocols shorten equipment replacement cycles and elevate demand for certified cone assemblies.
Market Restraints
- Polyurethane cone price volatility:Raw material cost swings for hydrocyclone liners compress margin pools for replacement part suppliers serving onshore contractors.
- Asian manufacturing concentration:Over 60% of hydrocyclone cone production sits in eastern China, exposing procurement timelines to regional logistics disruptions.
- Centrifuge substitution in synthetic mud systems:Ultra-fine cuttings separation requirements in deepwater environments displace desilter arrays with high-speed centrifuge packages.
Strategic Opportunities
- Mining exploration expansion:Geologically complex copper and lithium formations in Chile and Australia require advanced solids control for diamond drilling operations.
- OSPAR guideline alignment:North Sea operators face 2027 deadlines for zero-discharge compliance, mandating closed-loop mud system retrofits across aging platform fleets.
- IoT-enabled predictive maintenance:Real-time cone wear monitoring converges with cloud analytics to unbundle service contracts from equipment sales.
Industry Challenges
- Hydrocyclone sizing expertise gap:Field engineers capable of optimizing cone diameter-to-pressure ratios for high-solids formations remain scarce in Permian and Bakken plays.
- API 13C certification timeline:Third-party testing bottlenecks delay new shaker screen launches by 8-14 months, freezing product development roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drilling Mud Desander and Desilter Market |
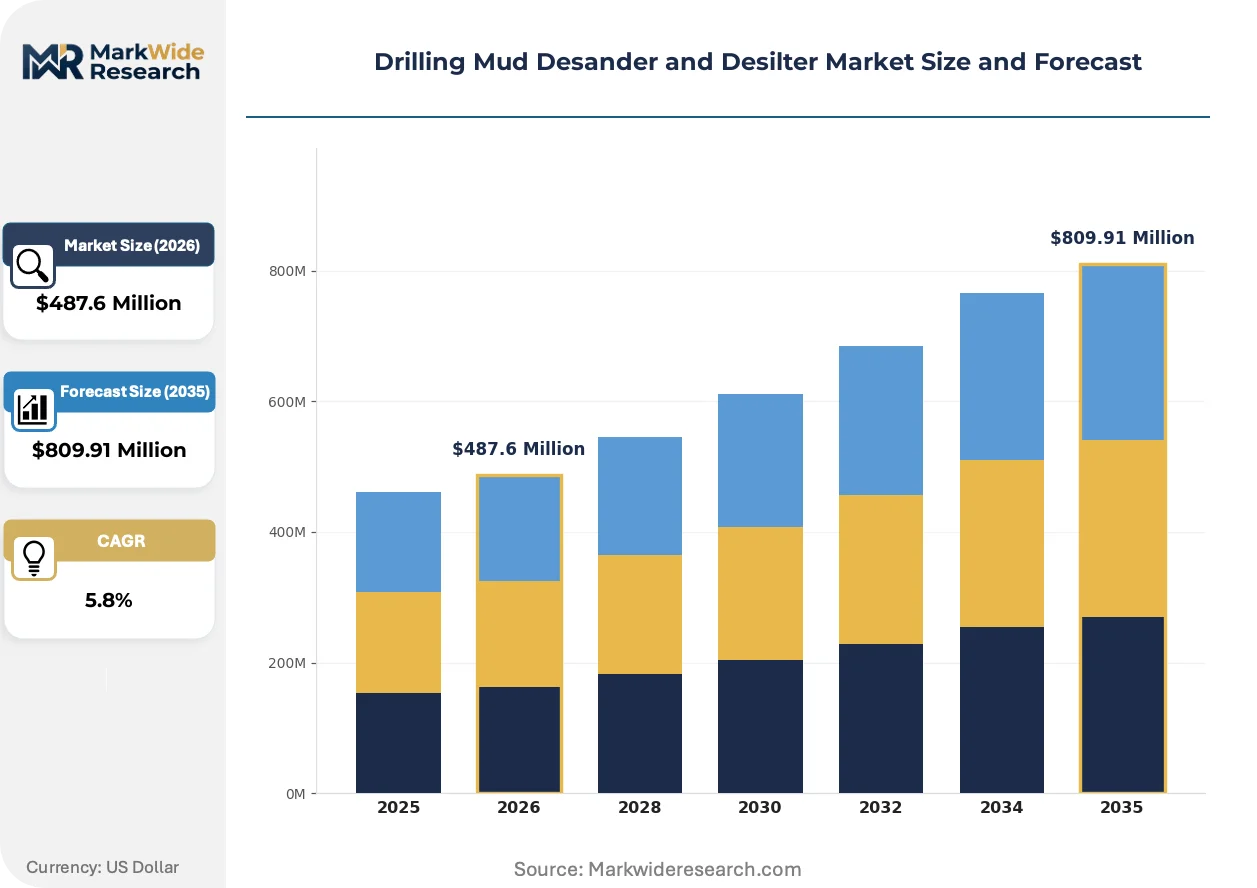
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $809.91 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrocyclones, Shakers, Centrifuges, Separators End User: Oil & Gas, Mining, Water Well, Construction Application: Drilling, Excavation, Waste Management, Industrial Processes Technology: Mechanical, Hydraulic, Pneumatic, Electro-mechanical |
| Companies Covered | National Oilwell Varco, Derrick Corporation, Schlumberger, Kosun Machinery, GN Solids Control, Halliburton, Weatherford International, XBSY, Baker Hughes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drilling Mud Desander and Desilter Market Emerging Trajectories
Electrification of rig power systems is reshaping solids control equipment design, with manufacturers adapting hydrocyclone pump drives and shaker motor configurations for variable frequency operation.
Variable frequency drive technology is electrifying desander and desilter pump systems, replacing fixed-speed centrifugal pumps with electronically controlled units. Offshore contractors in the North Sea and Gulf of Mexico are specifying VFD-equipped packages for 30% of new rig builds. This shift compresses energy consumption metrics and enables real-time flow rate adjustment without mechanical throttling.
EPA effluent limitation guidelines are tightening permissible drilling waste discharge volumes for coastal waters, forcing operators to treat cuttings on-site rather than transport to shore-based facilities. Onshore shale plays face parallel constraints from state-level groundwater protection rules. Synthetic-based mud systems in deepwater Brazil and West Africa now require secondary desilter stages to meet local environmental discharge permits.
Contracting models are fragmenting as national oil companies unbundle solids control services from integrated drilling contracts. Saudi Aramco and Petrobras now tender hydrocyclone maintenance separately from rig day rates, creating standalone service revenue pools. Independent operators in the Permian Basin favor rental-over-ownership structures for desander units, compressing capital deployment timelines and elevating aftermarket service intensity.
Drilling Mud Desander and Desilter Market Segmentation
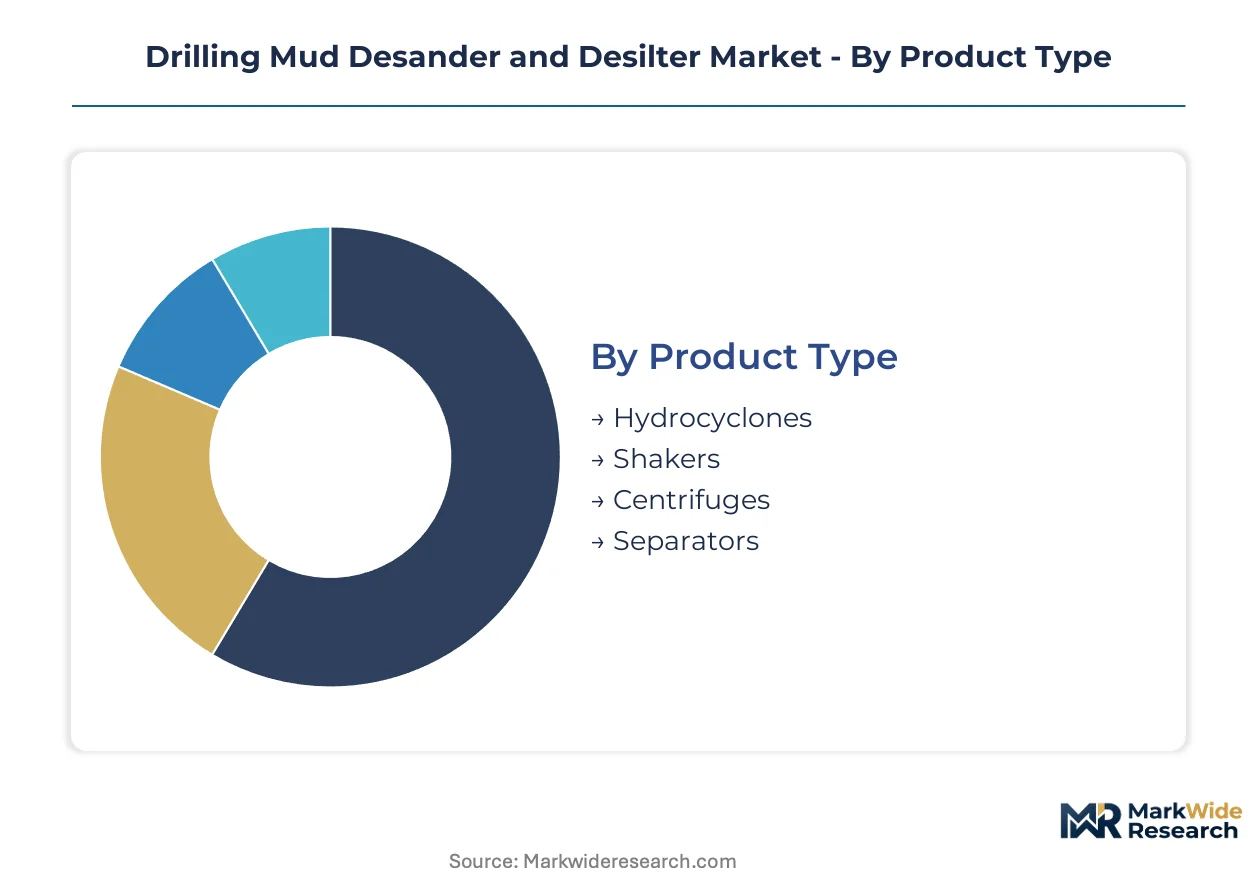
Segmentation in drilling mud desander and desilter markets reveals how equipment specifications diverge across operational environments. Understanding these splits allows manufacturers to align cone geometry, screen mesh ratings, and drive configurations with specific formation demands and regulatory constraints.
Product Type:
Hydrocyclones dominate unit volume while centrifuges command premium pricing in specialized applications.
- Hydrocyclones:Conical separation devices process drilling fluid through centrifugal force at 15-75 psi inlet pressure, removing sand and silt particles across 4-inch to 12-inch cone diameters. Demand concentrates in Permian Basin pad drilling operations where operators run units at elevated utilization rates per rig, forcing faster replacement cycles for cone assemblies.
- Centrifuges:High-speed rotational separators achieve ultra-fine cuttings removal for synthetic-based mud systems in deepwater environments. North Sea and Gulf of Mexico offshore contractors specify these units where OSPAR and EPA discharge rules mandate secondary solids control stages, capturing premium margins despite higher capital cost.
- Shakers:Vibrating screen systems provide primary solids control through mesh filtration.
- Separators:Integrated multi-stage units combine hydrocyclone and screening functions.
Mature deployment sits with hydrocyclones. Newer deployment is concentrated in centrifuges.
End User:
Application intensity varies sharply between established hydrocarbon extraction and emerging mineral exploration verticals.
- Oil & Gas:Conventional drilling operations across onshore shale plays and offshore basins anchor equipment demand through rig fleet expansion and replacement cycles. API 13C specification tightening shortens shaker screen replacement timelines, while pad drilling intensity in West Texas elevates per-rig desander utilization rates above historical norms.
- Mining:Diamond drilling and exploration in geologically complex copper and lithium formations drives adoption of portable solids control units. Chilean copper districts and Australian lithium provinces are expanding fastest as exploration moves into formations requiring advanced cuttings management for core recovery.
- Water Well:Geothermal and municipal drilling applications require compact, mobile separation equipment.
- Construction:Foundation drilling and tunnel boring projects utilize temporary mud systems with rental-heavy procurement models.
Established procurement patterns characterize oil and gas. Mining applications are gaining share fastest.
Application:
Operational phase determines equipment mobility requirements and redundancy specifications.
- Drilling:Primary solids control during active borehole operations consumes the majority of hydrocyclone and shaker deployment, with real-time fluid weight maintenance critical to wellbore stability.
- Excavation:Trenchless construction and horizontal directional drilling applications utilize compact, trailer-mounted desander units.
- Waste Management:Closed-loop mud system retrofits for zero-discharge compliance drive secondary processing equipment demand.
- Industrial Processes:Non-oilfield applications including tunnel slurry treatment and dredging operations adapt drilling solids control technology.
Continuous operation defines drilling applications. Waste management is climbing the fastest.
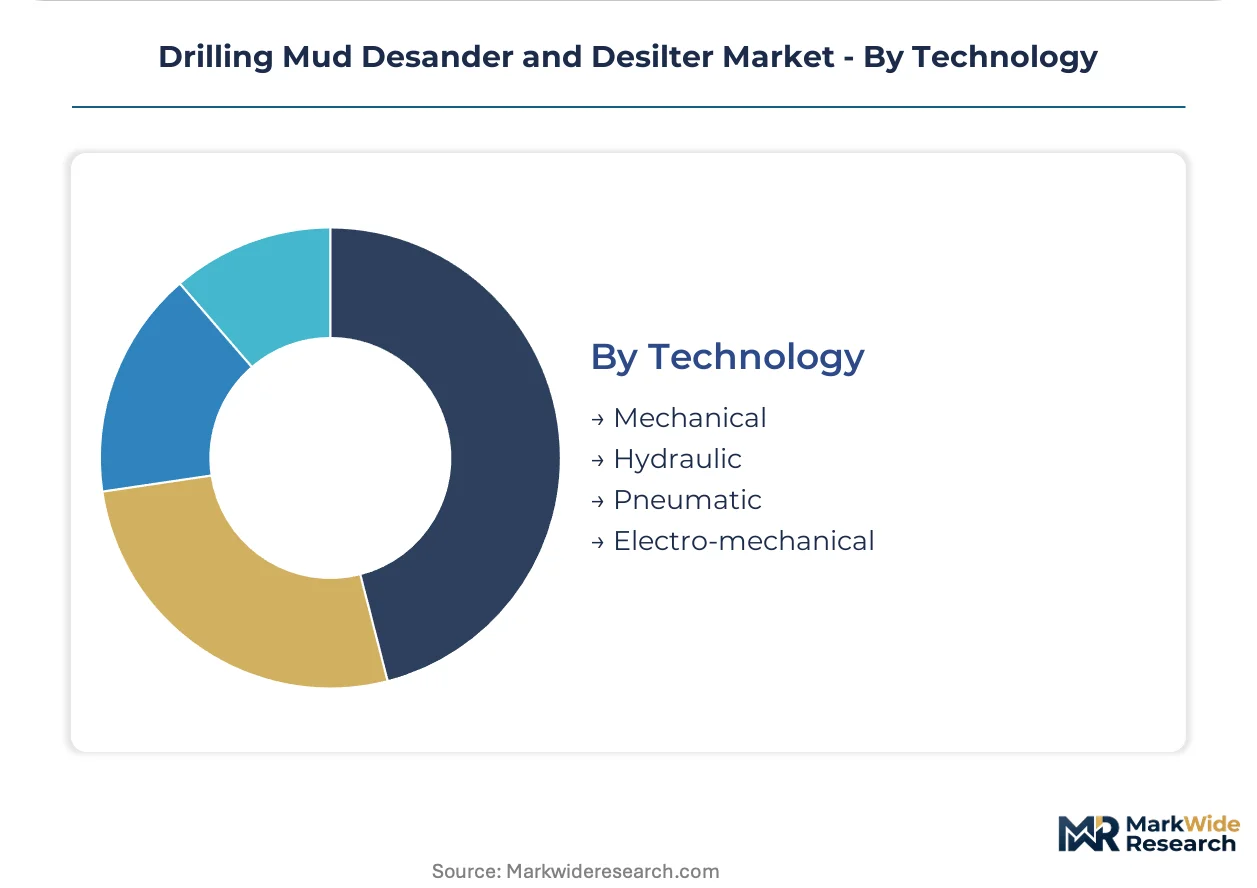
Technology:
Drive mechanism selection increasingly reflects electrification trends across rig power systems.
- Mechanical:Direct-drive configurations with fixed-speed pumps dominate legacy rig installations and rental fleets where capital constraints limit upgrade investment.
- Hydraulic:Fluid power systems deliver precise flow control for high-solids formations requiring variable cone pressure adjustment.
- Pneumatic:Compressed air drives suit hazardous environment deployments where electrical ignition risks constrain equipment selection.
- Electro-mechanical:Variable frequency drive integration enables real-time pump speed adjustment without mechanical throttling, with North Sea and Gulf of Mexico contractors specifying VFD-equipped packages for new rig builds to compress energy consumption metrics.
Conventional mechanical systems retain installed base dominance. Electro-mechanical configurations show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pad drilling intensity in West Texas concentrates hydrocyclone demand more densely than any other geography, while offshore contractors in the North Sea and Gulf of Mexico drive premium equipment specifications through regulatory pressure.
United States
Permian Basin operators run desander and desilter units at utilization rates 40% above historical baselines, forcing accelerated cone assembly replacement. EPA effluent limitation guidelines for coastal waters mandate closed-loop mud system adoption across Gulf of Mexico platforms. Houston anchors the domestic supply base, with fabrication clusters serving both onshore shale plays and offshore contractors.
China
Domestic shale gas development in Sichuan Basin expands procurement of compact solids control packages for mountainous terrain drilling. MEE regulations tighten drilling waste discharge standards for Yangtze River basin operations. Zhengzhou and Xi'an manufacturing clusters supply over 60% of global hydrocyclone cone production, exposing procurement timelines to regional logistics constraints.
Norway
North Sea platform retrofits for zero-discharge compliance drive secondary desilter stage installations ahead of 2027 OSPAR deadlines. Petroleum Safety Authority offshore safety directives shape capital allocation toward redundant solids control capacity. Stavanger and Bergen engineering centers specialize in high-specification equipment for harsh-environment drilling.
Brazil
Deepwater pre-salt development in the Santos Basin requires ultra-fine cuttings separation for synthetic-based mud systems. ANP environmental licensing mandates secondary solids control stages for subsea discharge permits. Rio de Janeiro and Macaé service hubs coordinate equipment logistics for floating production installations.
Saudi Arabia
Unconventional gas drilling in the Jafurah Basin expands demand for high-capacity desander arrays in tight gas formations. Saudi Aramco procurement unbundling creates standalone service contracts for hydrocyclone maintenance separate from rig day rates. Dhahran and Dammam industrial zones concentrate solids control equipment distribution for Middle East operations.
Drilling Mud Desander and Desilter Market Vendor Landscape
Strategic bundling dominates the current landscape as integrated rig systems providers consolidate procurement relationships around single-source hydrocyclone and shaker screen suppliers. The vendor base splits between diversified oilfield service conglomerates and specialized solids control fabricators. Three archetypes define competitive positioning: integrated systems bundlers, proprietary technology specialists, and manufacturing-scale cost leaders. Portfolio diversification and geographic expansion constitute the dominant competitive moves, with players extending screen media and cone replacement services into aftermarket revenue pools.
Among diversified oilfield service providers, National Oilwell Varco and Schlumberger exemplify the systems bundling archetype, anchoring desander units within broader drilling package offerings. Halliburton occupies a parallel position through integrated well construction portfolios. Derrick Corporation and Kosun Machinery represent contrasting specialization vectors—proprietary screen technology and manufacturing-scale production respectively—illustrating how technical differentiation and cost efficiency anchor alternative competitive positions.
| Leading Market Players |
|---|
| National Oilwell Varco |
| Derrick Corporation |
| Schlumberger |
| Kosun Machinery |
| GN Solids Control |
| Halliburton |
| Weatherford International |
| XBSY |
| Baker Hughes |
| Others |
Supply Flow & Price Mechanics
Captive production of polyurethane cone liners in eastern China anchors both supply security and margin structures for hydrocyclone assembly suppliers serving Permian Basin contractors. This backward integration into raw material processing concentrates pricing power with integrated manufacturers while exposing spot-market buyers to volatile input costs.
Pricing Analysis
Warranty bundling separates premium-tier suppliers from unbundled economy offerings in desander and desilter procurement. Three-tier pricing structure across premium, standard, and economy levels reflects API 13C certification status, after-sales service inclusion, and cone replacement interval guarantees. Cost compression in standard-tier equipment is intensifying because of polyurethane price volatility and Asian manufacturing competition. National oil companies exhibit lowest price sensitivity due to integrated drilling contract structures, while independent Permian operators drive rental-market price competition.
Supply Chain Analysis
Dual-sourcing requirements from Gulf of Mexico contractors mandate qualified secondary suppliers for hydrocyclone cones and shaker screens outside the primary China base. Manufacturing gravity centers on China, with secondary clusters in the United States and Norway serving regional offshore markets. Raw material flows draw from petroleum-derived polyurethane feedstocks, high-tensile steel for screen mesh, and engineered ceramics for wear-resistant cone liners. Single-source vulnerability concentrates in Zhengzhou-Xi'an logistics corridors. Distribution runs through Houston, Stavanger, and Rio de Janeiro service hubs coordinating rig-site delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
API 13C certification timelines and EPA closed-loop mandates are forcing consolidation among undifferentiated cone assembly suppliers without testing laboratory relationships.
For Market Incumbents: Hedge against centrifuge substitution in deepwater synthetic mud systems by acquiring secondary-stage separation technology or licensing high-speed rotational patents. Secure redundant cone manufacturing capacity outside eastern China to mitigate logistics disruption exposure. Prioritize certification laboratory partnerships to compress 8-14 month API 13C testing bottlenecks. For New Entrants and Emerging Players: Launch via rental-service models targeting Permian Basin independent operators seeking capital-light solids control deployment. Mining exploration in Chilean copper districts and Australian lithium provinces offers the most penetrable white-space, with portable desander units replacing temporary mud pit construction. Lead with IoT-enabled predictive maintenance contracts to unbundle service revenue from equipment sales. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated rig systems providers seeking hydrocyclone technology tuck-ins. Long-term viability favors specialists with captive polyurethane processing and API-certified testing capabilities. Watch for inflection in Saudi Aramco and Petrobras unbundling velocity, as standalone service contract proliferation signals aftermarket revenue pool expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyurethane Processing | Cone liner suppliers in China secure margin control against raw material volatility. |
| API 13C Certification Laboratory Partnership | Equipment manufacturers compress testing timelines to accelerate product launches. |
| IoT-Enabled Predictive Maintenance Platform | Service providers unbundle recurring revenue from capital equipment transactions. |
| Zero-Discharge System Retrofit Capacity | North Sea contractors meet OSPAR deadlines through secondary desilter installations. |
| Mining Exploration Portable Unit Development | Suppliers capture Chilean and Australian diamond drilling solids control demand. |
Methodological Framework
Independent corroboration across drilling contractor procurement directors, solids control equipment engineering leads, and aftermarket service managers underwrites the qualitative findings. Primary fieldwork involved structured interviews with rig fleet superintendents, API certification laboratory technicians, and polyurethane raw material procurement specialists. Secondary validation drew from API specification documents, EPA effluent limitation guidelines, OSPAR discharge reports, and customs trade data for hydrocyclone cone imports. Bottom-up equipment deployment counts triangulate against top-down rig fleet expansion projections.
Comparable historical replacement cycles across the 2018-2023 reference period anchor the projection methodology. The forecast framework models demand across product type, end-use vertical, operational application, and drive technology configuration. CAGRs derive from rig utilization intensity trends, regulatory compliance deadlines, and equipment replacement interval compression. Industry-specific inputs include Permian Basin pad drilling density metrics and North Sea platform age distribution for retrofit timing.
Regulatory enforcement variance, raw material price discontinuities, and offshore drilling contract cancellation waves are the dominant revision risks. Forecasts reflect documented assumptions regarding API specification adoption timelines and closed-loop mandate implementation schedules. A model refresh is warranted upon material change in EPA or OSPAR discharge rule stringency.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
United States Oil and Gas Upstream Market
Oil & Gas
Vietnam Oil and Gas Upstream Market
Oil & Gas
Qatar Oilfield Service Market
Oil & Gas
Oil Tank Rotating Stacker Market
Oil & Gas
Deepwater and Ultra-Deepwater Exploration and Production Market
Oil & Gas
Pumpjack Market
Oil & Gas
United Arab Emirates Oil and Gas Downstream Market
Oil & Gas
United Kingdom Oil and Gas Midstream Market
Oil & Gas
Hydraulic Workover Units Market
Oil & Gas
Iran Oil and Gas Market
Oil & Gas
Leak Detection for Oil & Gas Market
Oil & Gas
Oil and Gas Engineering Services Market
Oil & Gas
Coiled Tubing System Market
Oil & Gas
Russia Oil and Gas EPC Market
Oil & Gas
North America Frac Sand Market
Oil & Gas
Spacer Fluid Market