
 Middle East and Africa Drill Collar Market | 2026-2036
Middle East and Africa Drill Collar Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Drill Collar Market Insights
Capital-intensity divergence between integrated manufacturers and assembly-dependent suppliers is bifurcating competitive tiers in the Middle East and Africa drill collar landscape. Hunting PLC leverages captive steel forging capacity to sustain delivery reliability across West African offshore contracts. National Oilwell Varco anchors its position through vertical control over heat-treatment facilities in the Arabian Peninsula. Schlumberger differentiates via digital drilling integration that bundles collar telemetry with directional services.
Drill collars are thick-walled, heavy tubular steel components positioned directly above the drill bit to provide downward force and maintain tension on the drillstring, typically manufactured from AISI 4145H modified alloy steel through rotary forging and trepanning processes to achieve concentricity within 0.5 mm. The steel material segment dominates procurement volumes across Middle Eastern onshore fields where sour-gas resistance governs metallurgical selection. Premium product grades command expanding share in Nigerian and Angolan deepwater programs where extended-reach drilling imposes stricter fatigue specifications. The offshore installation category absorbs disproportionate capital allocation as operators in Mozambique's Rovuma Basin and Senegal's Sangomar field advance subsea development timelines.
API Specification 7-1 governs dimensional and material standards for drill collar manufacturing, while Nigeria's Nigerian Content Development and Monitoring Board enforces local assembly thresholds that reshape supplier entry pathways. Saudi Aramco's supplier qualification system and Abu Dhabi National Oil Company's in-country value requirements further segment market access by certification tier. Stakeholders must monitor how decarbonization commitments among national oil companies redirect procurement criteria toward low-emission manufacturing footprints and extended product lifecycle specifications.
Market Dynamics
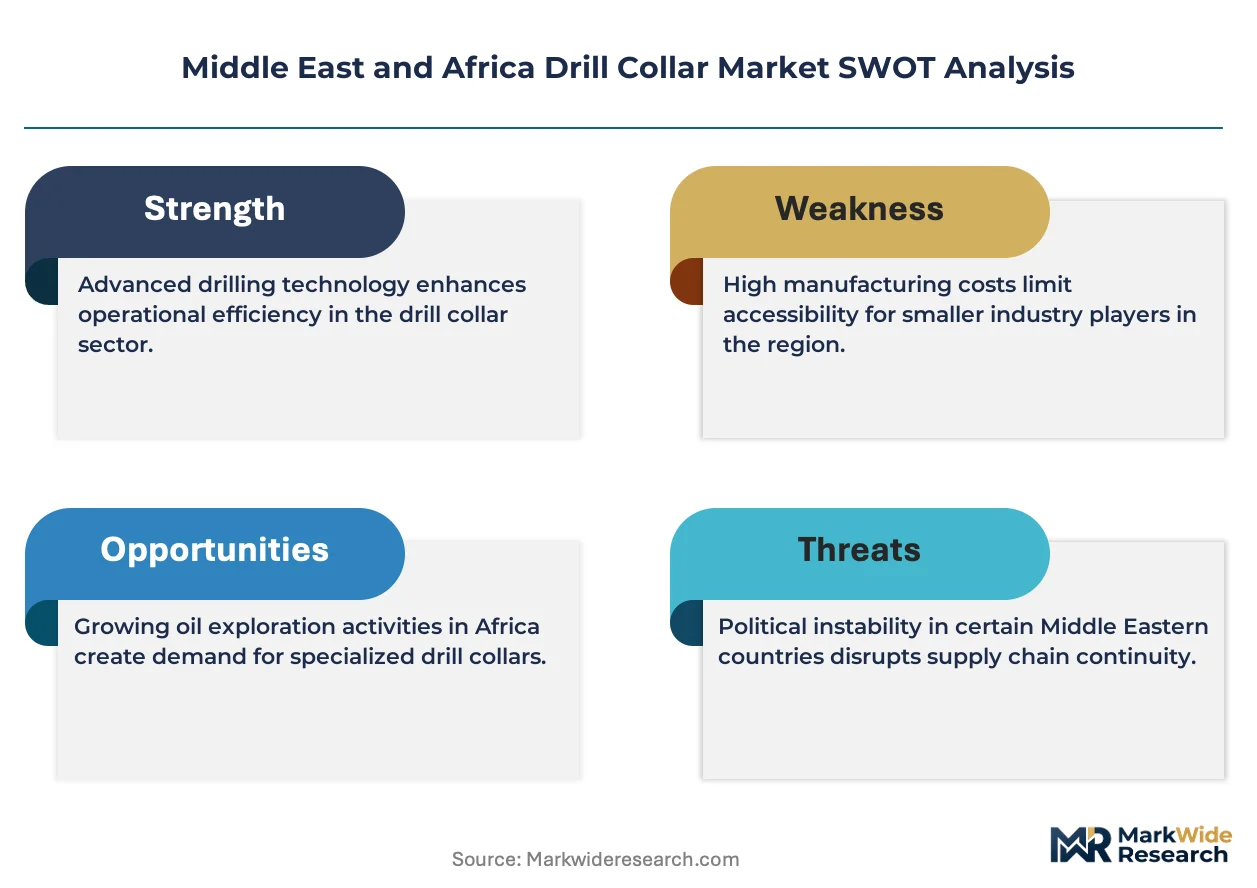
Deepwater exploration timelines in the Gulf of Guinea and Saudi Arabia's unconventional gas push are concentrating procurement around premium-grade AISI 4145H modified alloy steel collars, bifurcating supplier tiers by metallurgical certification and heat-treatment capability.
Growth Catalysts
- API Specification 7-1 upgrades:Revised dimensional and material standards are elevating entry barriers for non-certified manufacturers across Nigerian and Angolan offshore blocks.
- Extended-reach drilling fatigue specifications:Premium product grades are capturing share in Mozambique's Rovuma Basin subsea developments where well architecture demands superior torsional resistance.
- Saudi Aramco supplier qualification system:Tiered certification pathways are consolidating procurement toward integrated manufacturers with captive forging capacity.
Market Restraints
- Alloy steel price volatility:Chromium and molybdenum input cost swings are compressing margin predictability for assembly-dependent suppliers without long-term scrap hedging.
- Heat-treatment facility concentration:Limited regional capacity in the Arabian Peninsula creates delivery reliability exposure for non-integrated contractors.
- Non-magnetic collar substitution:Composite and titanium alternatives are displacing conventional steel in measurement-while-drilling applications requiring magnetic neutrality.
Strategic Opportunities
- Senegal Sangomar field development:First oil timelines are accelerating collar procurement for subsea installation categories with extended product lifecycle specifications.
- UAE deepwater exploration blocks:ADNOC in-country value requirements are creating qualification pathways for local assembly joint ventures.
- Digital drilling telemetry convergence:Bundled collar sensor integration with directional drilling services is opening service-revenue models beyond hardware supply.
Industry Challenges
- Rotary forging skill scarcity:Concentricity tolerances within 0.5 mm require specialized machinist training that outpaces regional vocational pipeline output.
- Nigerian Content Development and Monitoring Board compliance timelines:Local assembly thresholds are extending qualification cycles for foreign suppliers without established domestic partnerships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Drill Collar Market |
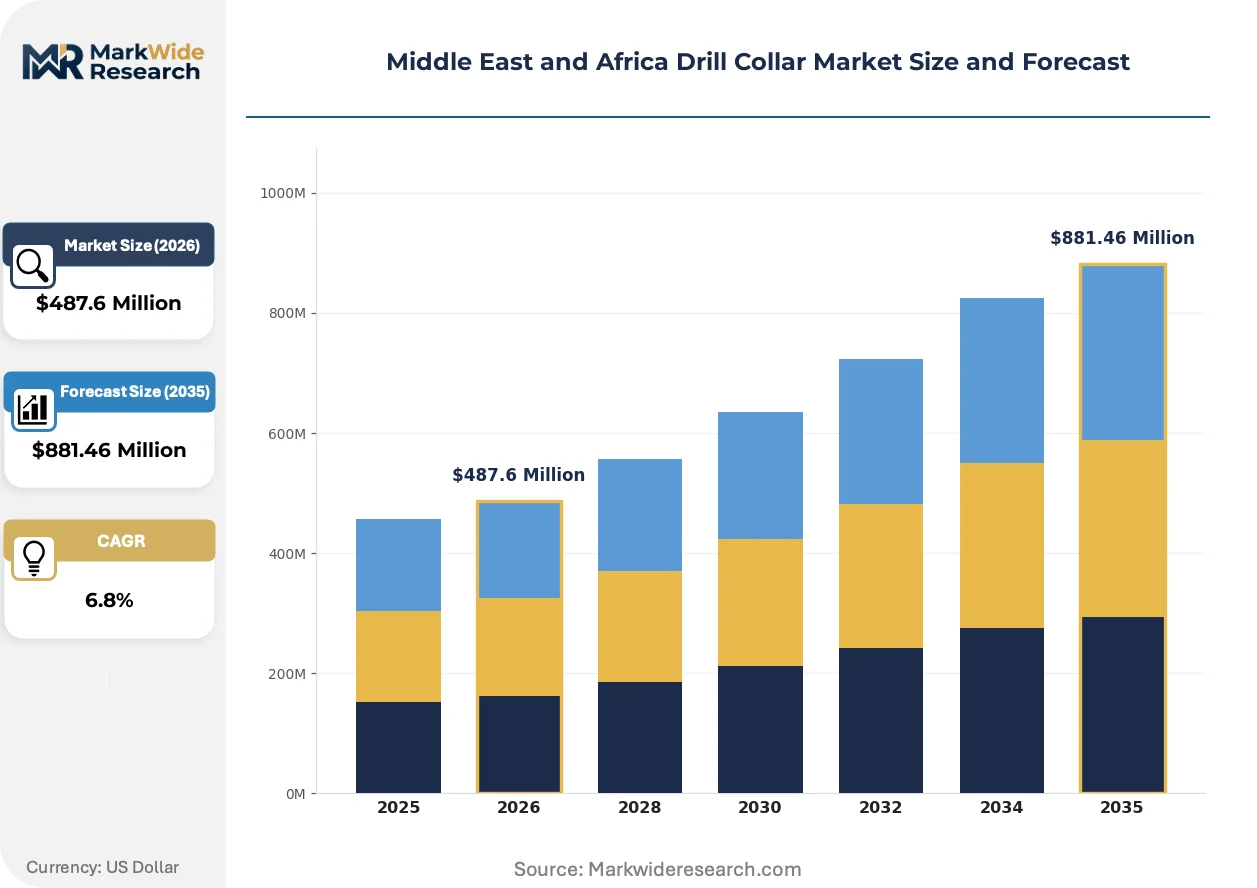
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heavyweight, Standard, Premium, Custom Material: Steel, Composite, Aluminum, Others Application: Oil & Gas, Mining, Geological Exploration, Environmental Installation Type: Onshore, Offshore, Subsea, Others |
| Companies Covered | Hunting PLC, National Oilwell Varco Inc., Schlumberger Limited, China Vigor Drilling Oil Tools and Equipment Co. Ltd, International Drilling Services Ltd, Schoeller-Bleckmann Oilfield Equipment AG, American Oilfield Tools Inc., Challenger International Inc., Zhong Yuan Special Steel Co. Ltd, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Drill Collar Market Trends and Innovations
Telemetry-enabled drill collars and sour-gas metallurgical advances are redefining procurement criteria across Middle Eastern and West African drilling programs, compressing traditional hardware margins while expanding service-attachment revenue pools.
Non-magnetic monel alloy collars are fragmenting the premium collar segment as measurement-while-drilling and logging-while-drilling adoption accelerates in directional wells. Abu Dhabi National Oil Company and Saudi Aramco are specifying these grades for high-temperature sour-gas horizons. The technology is fragmenting supplier tiers by separating magnetic-neutral capability from conventional forged steel production.
Nigeria's Nigerian Content Development and Monitoring Board local assembly mandates are restructuring supplier entry pathways. Foreign manufacturers must establish domestic partnerships or joint ventures to qualify for offshore drilling contracts. Angolan content requirements are following similar trajectory, compressing time-to-market for non-compliant entrants.
Integrated service contracting is displacing discrete hardware procurement in deepwater programs. Operators in Mozambique's Rovuma Basin and Senegal's Sangomar field are bundling collar supply with directional drilling and telemetry services. This model concentrates purchasing authority with integrated oilfield service providers rather than independent equipment distributors.
Middle East and Africa Drill Collar Market Segmentation
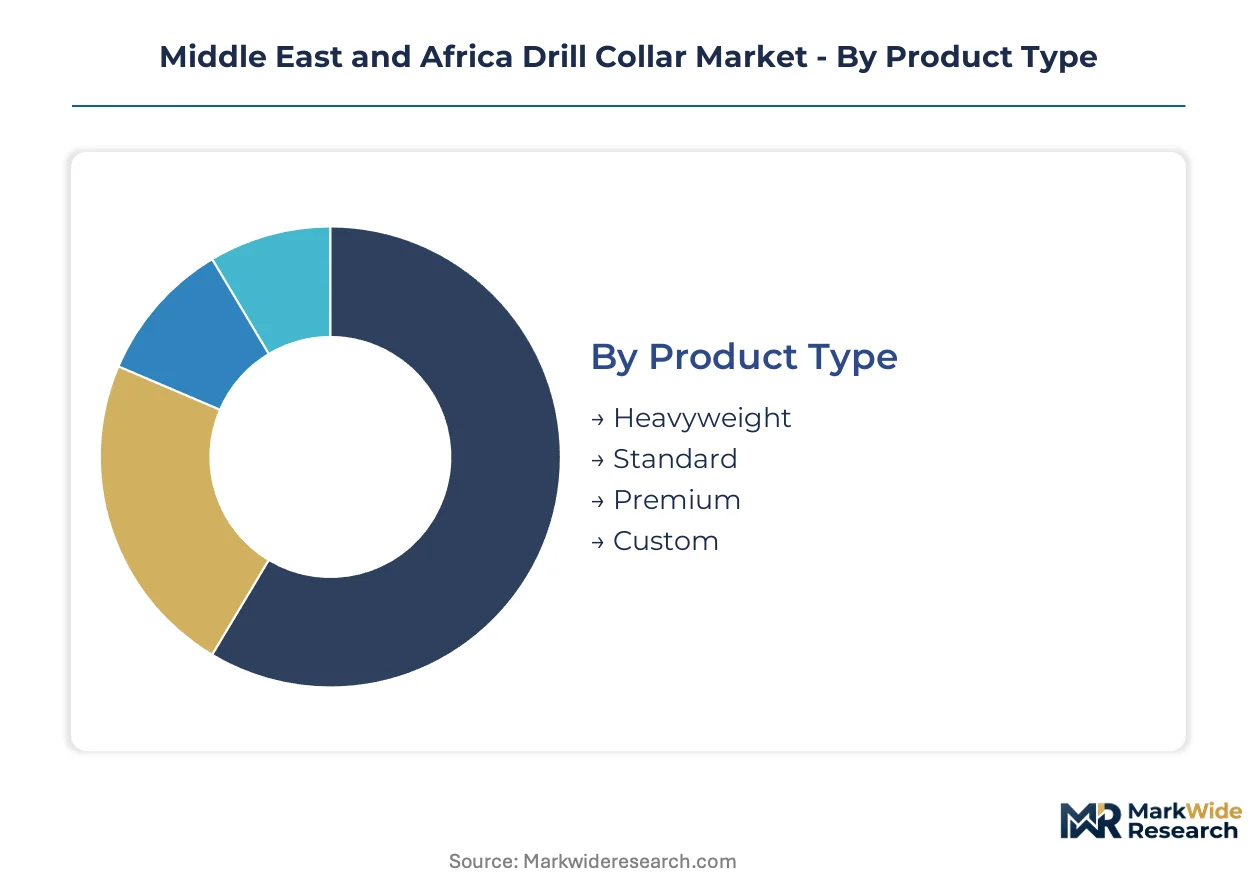
Drill collar procurement in the Middle East and Africa fragments across metallurgical grades, deployment environments, and regulatory compliance tiers. Understanding these segment boundaries clarifies where integrated manufacturers command premium positioning versus where assembly-dependent suppliers compete on cost.
Product Type:
Composite and titanium collar alternatives are exerting substitution pressure most acutely on lower-specification forged steel categories, forcing product-type strategists to defend differentiation through fatigue certification and telemetry integration.
- Premium:Manufactured from AISI 4145H modified alloy steel with enhanced heat-treatment protocols for sour-gas resistance. Demand concentrates in Saudi Aramco's unconventional gas developments and UAE deepwater exploration blocks where extended-reach drilling imposes strict torsional specifications.
- Standard:Conventional rotary-forged collars meeting baseline API Specification 7-1 dimensional tolerances. Procurement volumes remain anchored in Nigerian onshore fields where cost discipline outweighs performance premium requirements.
- Heavyweight:Thicker-walled configurations providing concentrated mass for vertical drilling applications. Nigerian Content Development and Monitoring Board local assembly mandates are reshaping supplier qualification pathways for this category.
- Custom:Application-specific geometries for non-standard well architectures. Angola's pre-salt development timelines are accelerating procurement of tailored collar configurations.
Premium collars retain volume leadership; Custom configurations hold the steepest expansion curve.
Material:
Cost tiering separates captive steel forgers from composite assemblers, with raw material hedging capability determining margin sustainability across volatile chromium and molybdenum cycles.
- Steel:Dominates procurement volumes through AISI 4145H modified alloy and non-magnetic monel variants. Saudi Aramco and Abu Dhabi National Oil Company specifications for high-temperature sour-gas horizons are fragmenting supplier tiers by metallurgical certification.
- Composite:Carbon-fiber reinforced polymers displacing conventional steel in measurement-while-drilling applications requiring magnetic neutrality. Mozambique's Rovuma Basin operators are specifying these grades for directional telemetry integration.
- Aluminum:Lightweight configurations for corrosive environments where mass reduction outweighs strength requirements. Senegal's Sangomar field development timelines are testing aluminum collar durability in subsea conditions.
- Others:Titanium and hybrid material experiments for extreme fatigue environments. Limited regional heat-treatment capacity constrains commercial scaling.
Steel retains volume leadership; Composite materials are climbing the fastest.
Application:
Customer type bifurcation concentrates purchasing authority with integrated oilfield service providers in deepwater programs versus independent equipment distributors in conventional onshore fields.
- Oil & Gas:Primary demand driver spanning exploration, development, and workover operations. Gulf of Guinea offshore programs and Saudi Arabia's unconventional gas push are concentrating procurement around premium-grade specifications.
- Mining:Geotechnical drilling for mineral resource delineation. South African platinum belt operations require collar configurations adapted to hard-rock penetration.
- Geological Exploration:Scientific and governmental survey programs. Budget constraints limit specification requirements to standard-grade offerings.
- Environmental:Groundwater monitoring and remediation drilling. Emerging regulatory frameworks for carbon capture storage are creating niche demand.
Oil & Gas retains volume leadership; Environmental applications are gaining share fastest.
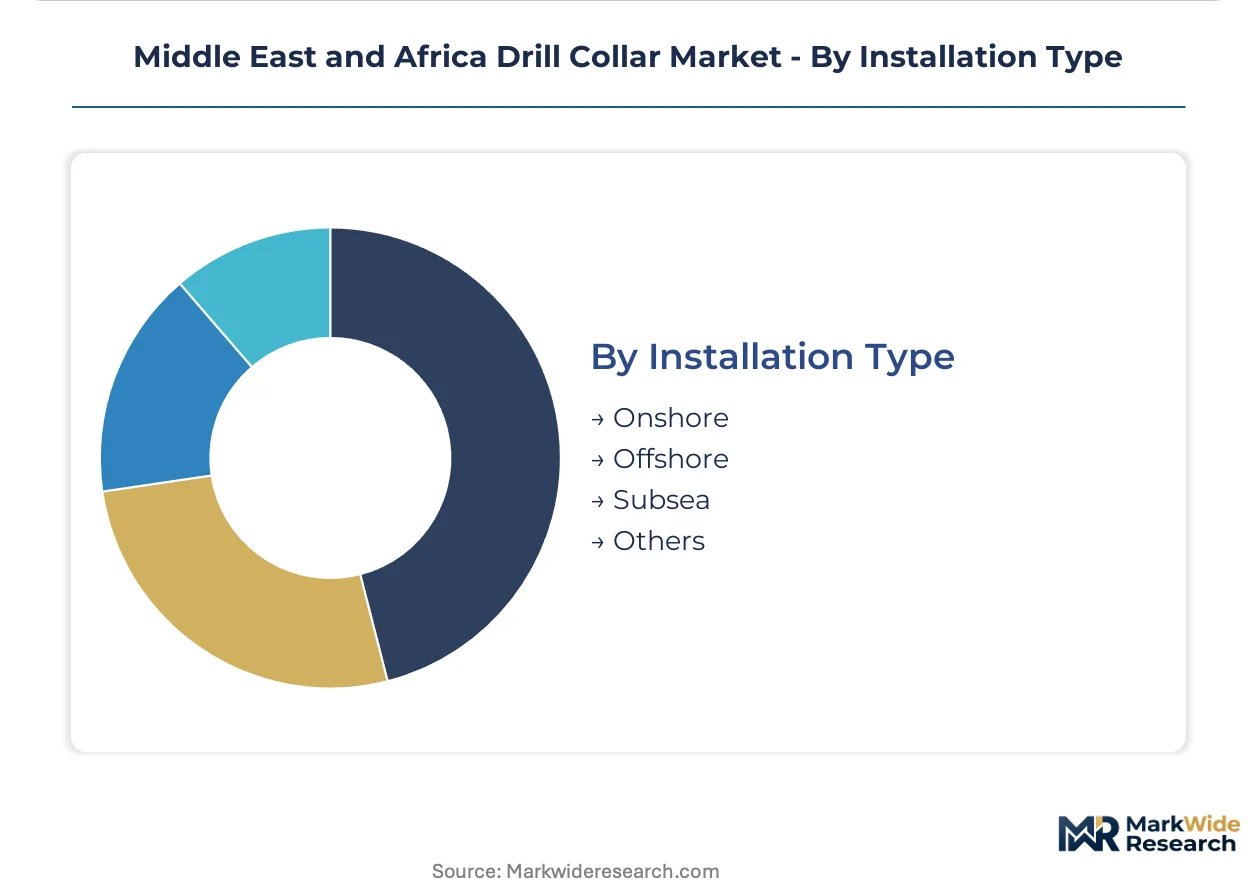
Installation Type:
Supply concentration in the Arabian Peninsula creates delivery reliability exposure for non-integrated contractors serving subsea and offshore categories.
- Offshore:Floating platform and jack-up rig deployments in the Gulf of Guinea. Nigerian and Angolan content requirements are restructuring supplier entry pathways through local assembly mandates.
- Subsea:Seabed wellhead connections requiring extended product lifecycle specifications. Mozambique's Rovuma Basin and Senegal's Sangomar field developments are accelerating capital allocation to this category.
- Onshore:Desert and conventional land drilling across Saudi Arabia and UAE. Sour-gas resistance governs metallurgical selection in high-temperature horizons.
- Others:Arctic-adapted and specialized environment configurations. Limited applicability across Middle Eastern and African climatic conditions.
Onshore retains volume leadership; Subsea installations show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement elasticity varies sharply across the Middle East and Africa. Saudi Arabian and UAE buyers prioritize metallurgical certification over unit cost, while Nigerian and Angolan operators face tighter capital constraints that amplify price sensitivity in standard-grade segments.
Saudi Arabia
Unconventional gas developments in the Jafurah Basin are driving demand for sour-gas-resistant premium collars. The Saudi Aramco supplier qualification system mandates tiered certification pathways that favor integrated manufacturers with captive forging capacity. Dammam's industrial corridor hosts the kingdom's densest concentration of heat-treatment facilities serving onshore drilling programs.
United Arab Emirates
ADNOC's deepwater exploration blocks offshore Abu Dhabi are accelerating procurement of extended-reach drilling configurations. The national oil company's in-country value requirements create qualification pathways for local assembly joint ventures. Jebel Ali's free zone infrastructure supports regional distribution hubs serving Gulf of Guinea contracts.
Nigeria
Offshore drilling programs in the Gulf of Guinea are concentrating procurement around API Specification 7-1 certified premium grades. The Nigerian Content Development and Monitoring Board enforces local assembly thresholds that reshape supplier entry pathways. Lagos and Port Harcourt anchor the domestic fabrication ecosystem for collar finishing operations.
Angola
Pre-salt development timelines are accelerating demand for custom collar geometries tailored to non-standard well architectures. Local content requirements are following Nigeria's trajectory, compressing time-to-market for non-compliant foreign entrants. Luanda's port infrastructure handles the bulk of subsea equipment importation for block operators.
Mozambique
Rovuma Basin subsea developments are absorbing disproportionate capital allocation for extended product lifecycle specifications. Integrated service contracting is displacing discrete hardware procurement as operators bundle collar supply with directional drilling services. Maputo serves as the logistical coordination point for offshore installation campaigns.
Middle East and Africa Drill Collar Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Middle East and Africa drill collar landscape. Integrated oilfield service providers with captive metallurgical capabilities command premium positioning in Saudi Aramco and ADNOC qualified supplier tiers, while assembly-dependent fabricators compete on delivery speed for Nigerian onshore contracts. The market structure bifurcates around forging capacity ownership versus third-party heat-treatment reliance. Strategic moves concentrate on backward integration into steel supply and joint venture formation to satisfy local content mandates.
Among European-anchored specialists, Hunting PLC and Schoeller-Bleckmann Oilfield Equipment AG exemplify the integrated manufacturing archetype with positions in premium-grade supplier tiers. National Oilwell Varco Inc. represents the diversified oilfield services model that bundles hardware with directional drilling capabilities. Schlumberger Limited anchors the digital-integrated tier where collar telemetry converges with subsurface service offerings. Chinese fabricators including Zhong Yuan Special Steel Co. Ltd occupy cost-competitive positions in standard-grade procurement channels.
| Leading Market Players |
|---|
| Hunting PLC |
| National Oilwell Varco Inc. |
| Schlumberger Limited |
| China Vigor Drilling Oil Tools and Equipment Co. Ltd |
| International Drilling Services Ltd |
| Schoeller-Bleckmann Oilfield Equipment AG |
| American Oilfield Tools Inc. |
| Challenger International Inc. |
| Zhong Yuan Special Steel Co. Ltd |
| Others |
Pricing and Supply Chain Analysis
Composite collar substitution for conventional steel in measurement-while-drilling applications is simultaneously redrawing procurement geography toward East Asian composite fabricators and compressing pricing power among Arabian Peninsula heat-treatment operators tethered to legacy forging economics. This displacement dynamic bifurcates supplier tiers by material capability while amplifying cost volatility for chromium and molybdenum-dependent steel forgers serving Nigerian onshore fields.
Pricing Analysis
After-market service contracts and telemetry-enabled collar maintenance drive lifetime value capture across Saudi Aramco and ADNOC supplier tiers. Three-tier pricing stratification separates API Specification 7-1 certified premium grades from standard rotary-forged offerings and lightweight composite alternatives. Cost compression in standard-grade channels intensifies as Chinese fabricators expand volume share through scrap-metal hedging advantages. Nigerian onshore operators exhibit acute price sensitivity, while UAE deepwater programs prioritize metallurgical certification over unit economics.
Supply Chain Analysis
Inventory lead times for premium AISI 4145H modified alloy steel collars extend disproportionately when heat-treatment capacity bottlenecks emerge across Saudi Arabia's Dammam industrial corridor. Supply concentrates in Saudi Arabia, China, and Austria for specialized forging inputs. Raw material flows draw from chromium mines in South Africa, molybdenum concentrates in Chile, and scrap steel recycling networks in Turkey. Single-source vulnerability concentrates around rotary forging equipment manufacturers in Germany and Japan. Distribution runs through Jebel Ali free zone hubs serving Gulf of Guinea contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa drill collar market sits at an early-cycle recovery phase driven by Gulf of Guinea offshore development timelines and Saudi unconventional gas capital deployment.
For Market Incumbents: Fortify captive heat-treatment capacity in the Arabian Peninsula to defend delivery reliability premiums against composite substitution threats. Deepen backward integration into specialty steel supply through long-term offtake agreements with Turkish scrap processors. Prioritize API Specification 7-1 certification maintenance as Nigerian Content Development and Monitoring Board mandates tighten qualification windows.
For New Entrants and Emerging Players: Anchor in Angolan pre-salt custom collar geometries where local content requirements have compressed incumbent response times. Target Senegal's Sangomar field subsea installation category through joint venture structures with domestic fabrication partners. Pursue integrated service contracting models that bundle hardware supply with directional drilling telemetry rather than discrete equipment distribution.
For Investors and Strategic Acquirers: The market sits at a capacity-constrained phase that favors integrated manufacturers with captive forging capability over assembly-dependent competitors. Long-term viability centers on metallurgical certification moats and regional heat-treatment infrastructure ownership. Monitor Saudi Aramco supplier qualification tier movements as inflection signals for procurement consolidation toward integrated service providers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Steel Supply | Captive scrap hedging insulates margin predictability against chromium and molybdenum volatility cycles. |
| Joint Venture Formation for Local Content Compliance | Nigerian and Angolan mandates require domestic assembly partnerships to qualify for offshore drilling contracts. |
| Telemetry-Enabled Collar Development | Sensor integration with directional drilling services opens recurring revenue streams beyond hardware margins. |
| Heat-Treatment Facility Expansion | Regional capacity addition in Saudi Arabia's Dammam corridor reduces delivery reliability exposure for West African contracts. |
| Non-Magnetic Monel Alloy Certification | ADNOC and Saudi Aramco sour-gas specifications fragment supplier tiers by magnetic-neutral capability. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of API specification documentation, national oil company procurement disclosures, and regional trade flow databases. Primary interviews engaged drilling engineers at Gulf of Guinea operators, procurement leads at Saudi Aramco qualified suppliers, heat-treatment facility managers in the Arabian Peninsula, and aftermarket service directors at integrated oilfield service providers. Secondary validation drew from customs records tracking alloy steel import flows, Nigerian Content Development and Monitoring Board compliance filings, and ADNOC in-country value requirement publications. Bottom-up volume estimates triangulate against top-down expenditure projections across the analysis window.
Segmentation dimensions modeled include metallurgical grade tier, installation environment, and regulatory compliance pathway across the projection horizon. Product-type splits capture premium, standard, heavyweight, and custom configurations. Material categories encompass steel, composite, aluminum, and experimental alloys. Application segmentation distinguishes oil and gas, mining, geological exploration, and environmental drilling. Geographic clusters reflect Saudi Arabia, UAE, Nigeria, Angola, and Mozambique procurement patterns. CAGRs derive from expenditure trajectory modeling and capacity utilization assumptions. Industry-specific inputs incorporate sour-gas resistance specifications and extended-reach drilling fatigue requirements.
Decision-makers should treat outputs as directional under assumptions of sustained Gulf of Guinea offshore development and stable API specification enforcement; material deviation in national oil company capital allocation or local content mandate intensity would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Malaysia Oil and Gas Pipeline Market
Oil & Gas
Underwater Monitoring System for Oil and Gas Market
Oil & Gas
Gabon Oil and Gas Market
Oil & Gas
Coiled Tubing System Market
Oil & Gas
United States Artificial Lift Systems Market
Oil & Gas
Large Scale LNG Terminal Market
Oil & Gas
Digital Oilfield Services Market
Oil & Gas
Ecuador Oil and Gas Midstream Market
Oil & Gas
Well Cementing Market
Oil & Gas
Underreamers Market
Oil & Gas
Oilfield Chemicals Market
Oil & Gas
Slickline Services Market
Oil & Gas
Netherlands LNG Bunkering Market
Oil & Gas
Gold Mining Market
Oil & Gas
South Korea Oil and Gas Market
Oil & Gas
Europe Coiled Tubing Market