
 Asia Pacific Oil Storage Tank Service Market | 2026-2036
Asia Pacific Oil Storage Tank Service Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Oil Storage Tank Service Market Analysis
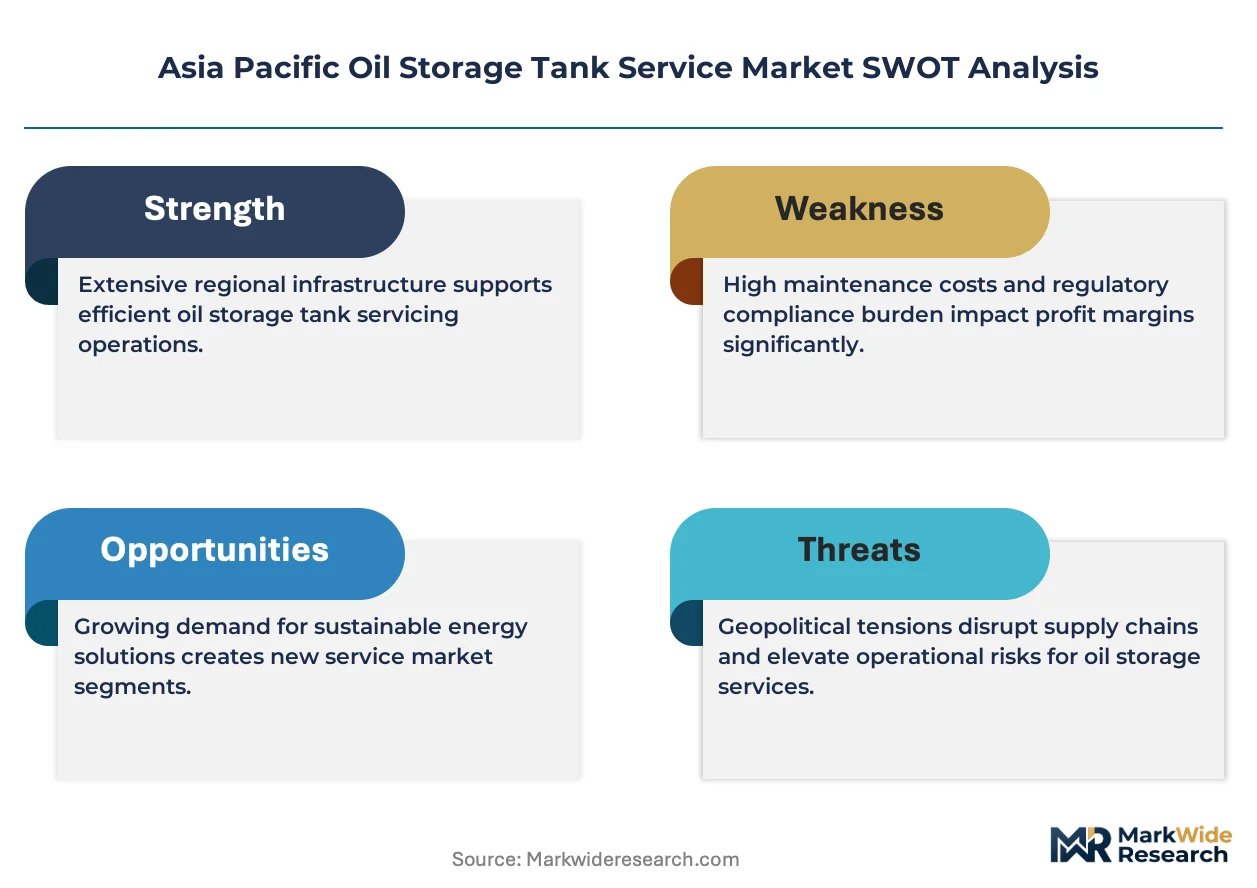
Aging certified welding specialists across Asia Pacific is unwinding maintenance backlogs at coastal terminals. Matrix Service leverages its integrated tank construction and repair capabilities across Australian LNG corridors. MISTRAS Group Inc. anchors its regional position through non-destructive testing technology leadership. Koninklijke Vopak N.V. dominates independent storage service contracts at key transshipment hubs.
Asia Pacific oil storage tank service encompasses inspection, cleaning, repair, and integrity management of above-ground and floating roof tanks built to API 650/653 standards, ensuring hydrocarbon containment and preventing environmental release across refining and terminal operations. Floating roof tank maintenance commands the largest service spend due to seal replacement cycles and rim fire detection mandates, while automated leak detection under technological application is expanding fastest as terminal operators retrofit legacy assets with real-time monitoring. Cleaning services for crude and product tanks retain stable margins tied to scheduled turnaround cycles at petrochemical plants.
India's CEA guidelines, Australia's EPA tank farm regulations, and Singapore's MPA terminal safety codes collectively mandate periodic integrity assessments and emission controls that sustain inspection demand. Japan's METI fire safety standards for petroleum storage further tighten compliance scope across the region. Stakeholders must weigh retrofit automation against conventional manual inspection economics as labor scarcity intensifies across coastal service corridors.
Market Dynamics
Automated corrosion monitoring systems are compressing inspection cycles across Asia Pacific terminals, forcing service providers to reconfigure workforce deployment models and pricing structures around predictive maintenance rather than scheduled downtime.
Growth Catalysts
- India's CEA Guidelines:State-run storage expansions and private terminal upgrades are accelerating mandatory integrity assessments across petroleum, aviation fuel, and strategic crude reserves.
- Seal Replacement Cycles:Floating roof tank maintenance commands sustained service spend as rim fire detection mandates tighten across Singapore's MPA terminal safety codes and Australia's EPA tank farm regulations.
- Automated Leak Detection:Terminal operators retrofit legacy assets with real-time monitoring, expanding fastest among technological applications as labor scarcity intensifies across coastal service corridors.
Market Restraints
- Certified Welding Specialist Scarcity:Aging technical workforce across Australia, Japan, and South Korea unwinds maintenance backlogs and extends project timelines at LNG corridors and refining hubs.
- Specialized Equipment Import Dependence:Non-destructive testing hardware and automated inspection robotics concentrate supply from European and North American manufacturers, exposing margins to currency volatility and shipping constraints.
- API 653 Recertification Complexity:Compliance scope expansion under Japan's METI fire safety standards and India's Petroleum and Natural Gas Regulatory Board mandates creates documentation bottlenecks for multi-site operators.
Strategic Opportunities
- Vietnam and Indonesia Storage Buildouts:Greenfield refinery and import terminal construction creates first-mover advantage for integrated construction-and-service contractors able to anchor long-term maintenance contracts.
- Drone-Based Ultrasonic Thickness Gauging:Convergence of unmanned aerial platforms with phased array inspection technology enables remote tank shell assessment without scaffolding, reducing confined-space entry requirements.
- Singapore Carbon Border Adjustments:Emission control mandates at transshipment hubs reward service providers offering vapor recovery upgrades and floating roof seal retrofits that demonstrate measurable methane reduction.
Industry Challenges
- Confined-Space Entry Certification Backlogs:Safety training pipeline constraints delay technician deployment for internal tank cleaning and repair operations, compressing turnaround windows at petrochemical plants.
- Legacy SCADA Integration Friction:Retrofitting real-time monitoring onto tanks with analog control architectures requires protocol bridging and cybersecurity hardening that extends commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Oil Storage Tank Service Market |
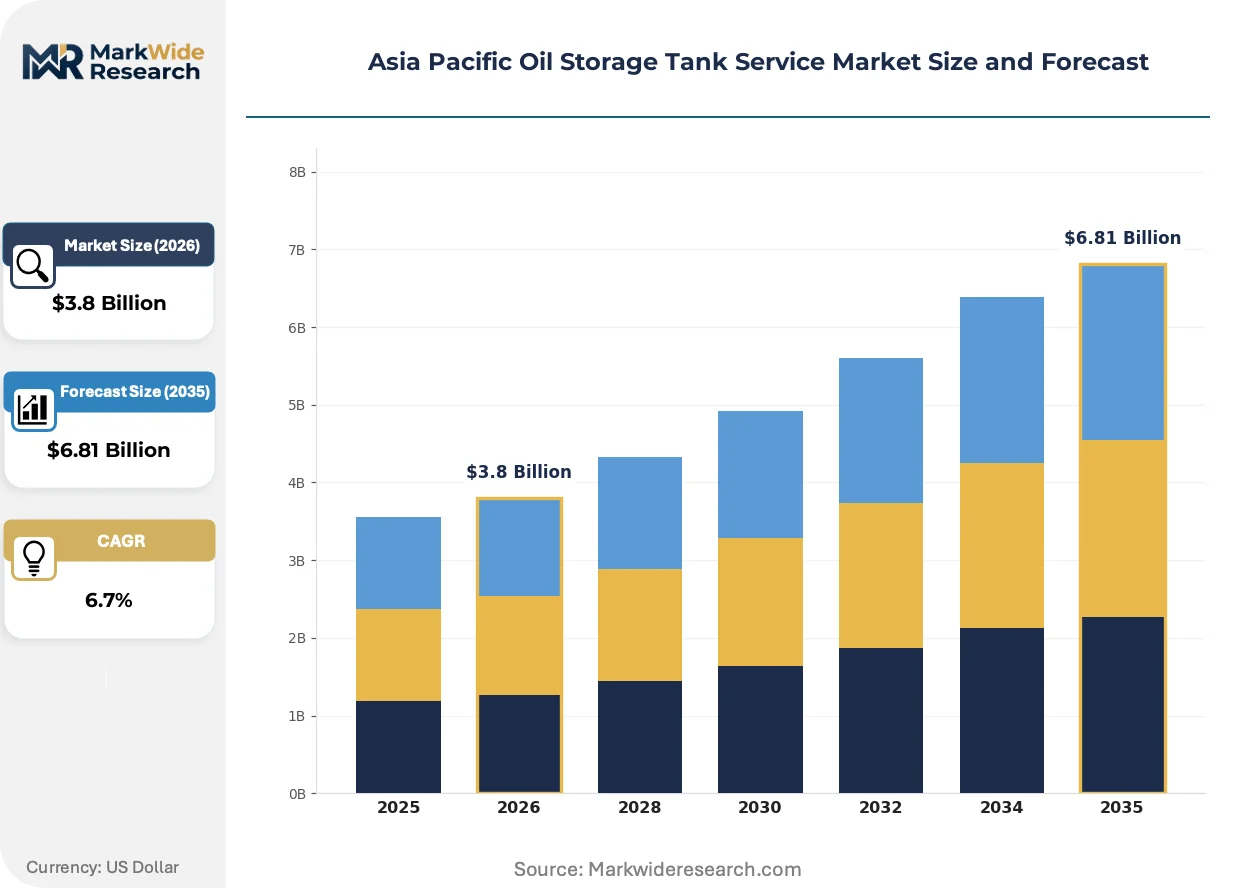
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Maintenance, Inspection, Repair, Cleaning End User: Refineries, Terminals, Petrochemical Plants, Storage Companies Tank Type: Above Ground, Underground, Floating Roof, Fixed Roof Technological Application: Automation, Monitoring, Safety Systems, Leak Detection |
| Companies Covered | Matrix Service, MISTRAS Group Inc., Koninklijke Vopak N.V., Gibson Energy Inc., Oiltanking GmbH, John Wood Group PLC, Veolia, Koch IP Holdings, LLC., McDermott International, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Oil Storage Tank Service Market Emerging Trajectories
Digital inspection workflows and autonomous monitoring hardware are displacing manual measurement regimes across Asia Pacific tank farms, redefining service provider capabilities and client contracting structures.
Phased array ultrasonic testing equipment is miniaturizing from cart-based systems to handheld units operable by single technicians. Mid-scale terminal operators across Thailand and Malaysia are adopting these units to reduce specialist crew sizes. The technology is miniaturizing inspection economics, enabling spot-check programs between full API 653 assessments.
Australia's EPA tank farm regulations now mandate continuous emission monitoring at facilities exceeding threshold storage volumes. This industrial consequence forces operators to integrate optical gas imaging with tank seal condition assessments. Floating roof tank service contracts in Queensland and Western Australia are expanding scope to include vapor recovery efficiency verification.
Long-term service agreements are displacing transactional repair procurement among integrated energy majors. Term contracting now covers predictive analytics, spare parts staging, and guaranteed response times rather than per-incident billing. This shift concentrates most visibly among Japanese trading house terminal portfolios and Indian Oil Corporation storage networks.
Asia Pacific Oil Storage Tank Service Market Segmentation
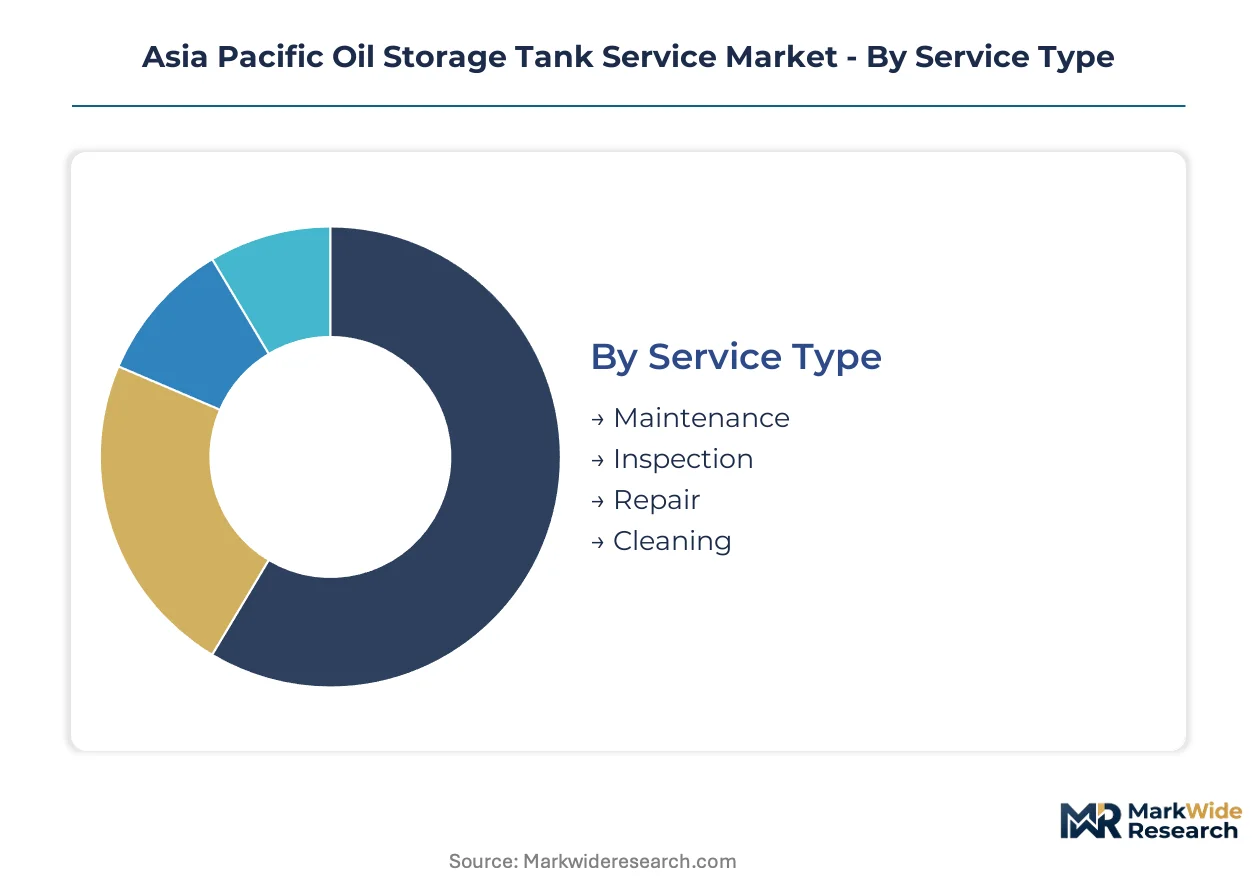
Service differentiation across the Asia Pacific oil storage tank service market determines procurement patterns, margin structures, and vendor selection criteria. Terminal operators segment requirements by operational criticality, regulatory exposure, and tank architecture complexity.
Service Type:
Inspection services face the strongest substitution pressure from automated corrosion monitoring systems, compressing traditional manual assessment cycles.
- Maintenance:Scheduled seal replacements, rim fire detection system upgrades, and structural reinforcement programs sustain recurring revenue at floating roof installations. India's state-run storage expansions and private terminal upgrades are accelerating preventive maintenance procurement across petroleum, aviation fuel, and strategic crude reserves.
- Inspection:API 653 compliance assessments, non-destructive testing campaigns, and integrity management audits form the regulatory backbone of service contracts. Australia's EPA tank farm regulations and Singapore's MPA terminal safety codes mandate periodic assessments that sustain inspection demand despite automation encroachment.
- Repair:Certified welding operations for shell plate replacement, roof reconstruction, and foundation remediation address integrity failures.
- Cleaning:Crude and product tank turnaround services retain stable margins tied to scheduled cycles at petrochemical plants.
Maintenance anchors the volume base while inspection gains share at the steepest rate as predictive analytics displace scheduled downtime.
End User:
Cost tier segmentation separates integrated majors with captive service capabilities from independent operators reliant on third-party contractors.
- Refineries:Complex turnaround schedules, hydrocracker unit proximity, and sulfur recovery integration demand specialized hot work protocols. Japanese refining hubs under METI fire safety standards maintain stringent contractor qualification requirements that limit vendor pools.
- Terminals:Transshipment volume throughput, multi-product segregation, and vapor recovery mandates define service scope. Singapore's carbon border adjustments reward providers offering floating roof seal retrofits that demonstrate measurable methane reduction.
- Petrochemical Plants:Polymer-grade product purity requirements drive cleaning specification intensity.
- Storage Companies:Independent tank farm operators prioritize unit-cost minimization over technical sophistication.
Terminals concentrate procurement volume while petrochemical plants expand service intensity fastest.
Tank Type:
Application-driven segmentation separates atmospheric storage from pressure-vessel architectures with divergent inspection protocols.
- Floating Roof:Rim seal assemblies, pontoon integrity, and rolling ladder mechanisms require specialized maintenance expertise. Seal replacement cycles command sustained service spend as rim fire detection mandates tighten across Australia's EPA regulations and Singapore's MPA codes.
- Above Ground:API 650 cylindrical welded structures dominate crude and product storage infrastructure. India's CEA guidelines and Petroleum and Natural Gas Regulatory Board mandates accelerate integrity assessments across state-run and private above-ground networks.
- Fixed Roof:Cone roof and dome roof configurations serve lower-volatility products with simpler maintenance regimes.
- Underground:Cavern storage and buried tank systems require confined-space entry certification and groundwater monitoring integration.
Floating roof installations anchor the revenue base while above-ground tanks expand most quickly amid India's storage buildout.
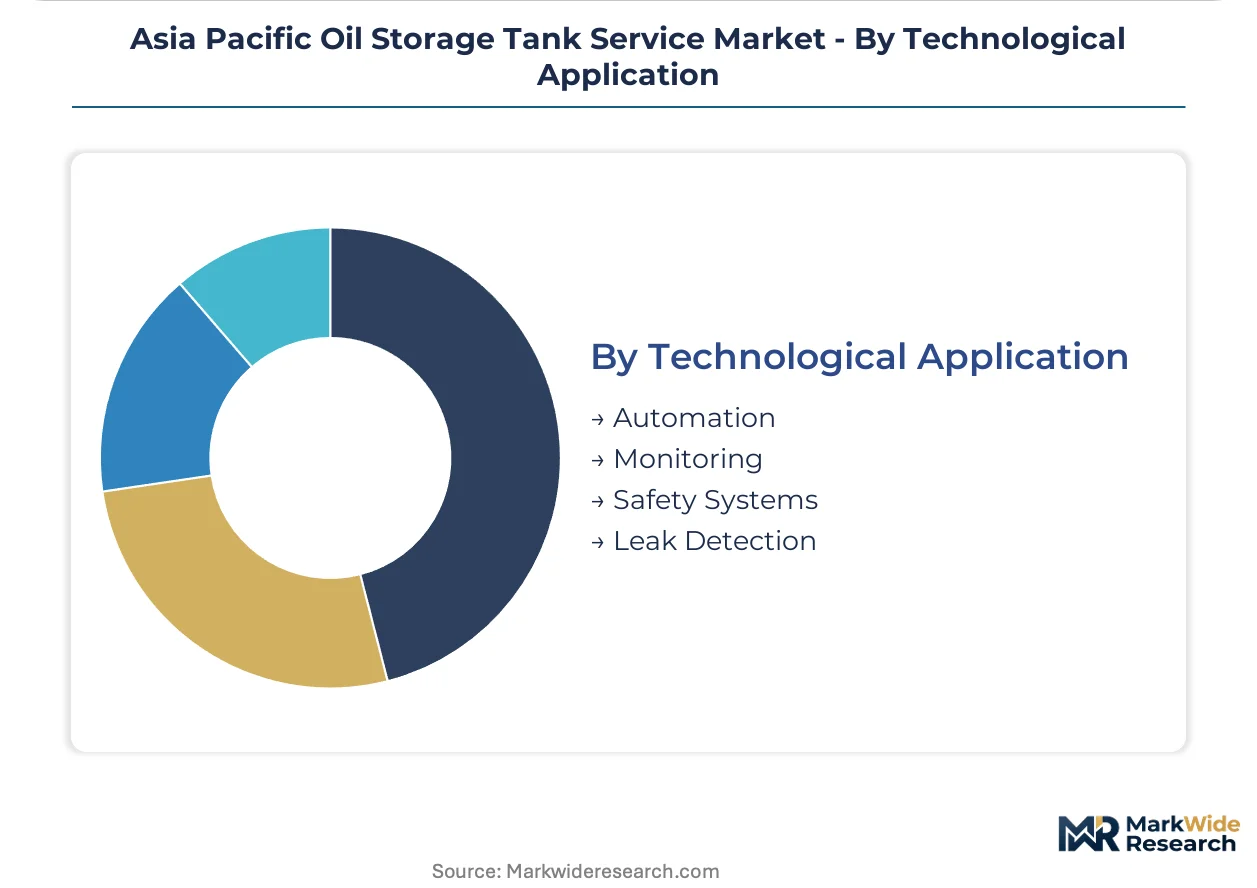
Technological Application:
Customer type segmentation separates retrofit automation demand from conventional manual service procurement.
- Automation:Robotic inspection platforms, drone-based ultrasonic thickness gauging, and autonomous cleaning systems reduce confined-space entry requirements. Phased array ultrasonic testing equipment miniaturization enables spot-check programs between full API 653 assessments across Thailand and Malaysia.
- Monitoring:Real-time corrosion sensors, structural health monitoring networks, and SCADA integration deliver predictive maintenance capabilities. Legacy SCADA integration friction extends commissioning timelines as terminal operators bridge analog control architectures.
- Safety Systems:Rim fire detection, overflow protection, and emergency venting upgrades address regulatory compliance.
- Leak Detection:Optical gas imaging, acoustic emission sensors, and vapor recovery efficiency verification expand contract scope. Australia's EPA now mandates continuous emission monitoring at facilities exceeding threshold storage volumes.
Monitoring commands the largest technology spend while leak detection climbs the fastest as emission controls tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's CEA guidelines anchor the dominant geography, mandating periodic integrity assessments across state-run petroleum reserves and private terminal networks. Terminal operators from Mumbai to Visakhapatnam accelerate procurement of inspection and maintenance services to meet compliance deadlines.
India
State-run storage expansions at Indian Oil Corporation facilities and private terminal upgrades at Reliance Industries sites drive service procurement acceleration. The Petroleum and Natural Gas Regulatory Board mandates API 653 recertification timelines that compress project schedules. Gujarat's Jamnagar refining corridor concentrates floating roof tank maintenance demand as seal replacement cycles intensify.
Australia
LNG export terminal operators along the Queensland coast expand automated corrosion monitoring deployments. The EPA tank farm regulations mandate continuous emission monitoring at facilities exceeding threshold storage volumes. Western Australia's Kwinana industrial zone anchors above-ground tank inspection demand as vapor recovery efficiency verification becomes contract standard.
Singapore
Carbon border adjustments at transshipment hubs reward service providers demonstrating measurable methane reduction through floating roof seal retrofits. The MPA terminal safety codes tighten rim fire detection mandates across Jurong Island storage clusters. Independent storage operators prioritize long-term service agreements covering predictive analytics and guaranteed response times.
Japan
METI fire safety standards for petroleum storage tighten compliance scope across refining and terminal operations. Aging certified welding specialists unwind maintenance backlogs at coastal facilities. The Chiba and Yokkaichi industrial corridors concentrate demand for non-destructive testing campaigns and structural reinforcement programs.
Vietnam
Greenfield refinery construction at Nghi Son and Long Son creates first-mover advantage for integrated construction-and-service contractors. National energy security programs accelerate strategic crude reserve buildouts. The Cai Mep-Thi Vai deepwater port zone attracts independent storage service contracts as import terminal capacity expands.
Asia Pacific Oil Storage Tank Service Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with the former commanding multi-site maintenance contracts and the latter dominating niche inspection technologies. The market structure rewards vertical capability breadth over pure-play scale, particularly among operators serving LNG corridors and refining hubs. Two strategic archetypes predominate: integrated tank construction-and-repair contractors and non-destructive testing technology specialists. Competitive moves concentrate on long-term service agreement anchoring and predictive maintenance platform deployment.
Within the integrated contractor tier, Matrix Service anchors positions across Australian LNG corridors through combined construction and repair capabilities. MISTRAS Group Inc. exemplifies the technology-specialist archetype, with its regional positioning tied to non-destructive testing equipment leadership. Koninklijke Vopak N.V. occupies a distinct position among independent storage operators, dominating service contracts at key transshipment hubs through terminal ownership integration.
| Leading Market Players |
|---|
| Matrix Service |
| MISTRAS Group Inc. |
| Koninklijke Vopak N.V. |
| Gibson Energy Inc. |
| Oiltanking GmbH |
| John Wood Group PLC |
| Veolia |
| Koch IP Holdings, LLC. |
| McDermott International |
| Others |
Supply Flow & Price Mechanics
India's CEA guidelines and Australia's EPA tank farm regulations simultaneously gate supplier qualification and stratify contract values across the Asia Pacific oil storage tank service market. Certified welding specialists command premium rates in Japan's METI-regulated corridors while automated inspection providers undercut manual service pricing in Southeast Asian greenfield terminals.
Pricing Analysis
Price spreads between Australian LNG corridor contracts and Indonesian import terminal services exceed forty percent at comparable specification levels. Three-tier pricing structure across API 653-certified specialists, regional inspection contractors, and unbundled cleaning providers reflects certification depth and response-time guarantees. Cost compression in standard-tier manual inspection is intensifying because phased array equipment miniaturization enables single-technician deployment. Independent storage operators exhibit highest price sensitivity; integrated majors prioritize guaranteed uptime over unit-cost minimization.
Supply Chain Analysis
Strategic stockpiling of non-destructive testing hardware dominates procurement strategy among Japanese and Australian terminal operators facing European and North American equipment lead times. Supply concentrates in Germany, the United States, and Japan for ultrasonic testing systems, robotic inspection platforms, and corrosion monitoring sensors. Specialized equipment import dependence exposes margins to currency volatility and shipping constraints through single-source vulnerability for automated inspection robotics. Distribution runs through authorized regional distributors with factory-trained technician networks rather than direct manufacturer relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia Pacific oil storage tank service market operates as a defensive-moat industry where regulatory certification entrenchment creates switching costs that lock terminal operators into incumbent relationships. API 653 compliance documentation and METI fire safety qualification histories accumulate as irreplaceable relationship assets.
For Market Incumbents: Fortify long-term service agreement anchoring by embedding predictive analytics platforms and spare parts staging into Indian Oil Corporation and Japanese trading house terminal portfolios. Automated corrosion monitoring systems threaten traditional inspection revenue streams; counter by acquiring drone-based ultrasonic thickness gauging capabilities to capture spot-check program expansion across Thailand and Malaysia.
For New Entrants and Emerging Players: Lead with integrated construction-and-service contracting at Vietnam's Nghi Son and Long Son greenfield refinery sites where first-mover positioning anchors decade-long maintenance relationships. Vietnam and Indonesia storage buildouts represent the most penetrable geography; enter through vapor recovery efficiency verification services that satisfy Singapore's carbon border adjustment requirements.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across automated leak detection technology deployment as terminal operators retrofit legacy assets with real-time monitoring infrastructure. Target acquisition profiles center on phased array equipment specialists with handheld unit distribution networks in Southeast Asia. The signal to watch is India's Petroleum and Natural Gas Regulatory Board mandate expansion beyond current API 653 recertification timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Long-Term Service Agreement Anchoring | Locks Indian Oil Corporation and Japanese trading houses into predictive maintenance platforms with guaranteed response commitments. |
| Drone-Based Ultrasonic Thickness Gauging Acquisition | Enables remote tank shell assessment without scaffolding, reducing confined-space entry requirements across Queensland terminals. |
| Vapor Recovery Efficiency Verification Capability | Captures Singapore carbon border adjustment rewards through measurable methane reduction demonstration at Jurong Island. |
| Certified Welding Specialist Pipeline Investment | Addresses aging workforce scarcity across Australia's LNG corridors and Japan's Chiba industrial zone. |
| Phased Array Equipment Miniaturization | Reduces crew sizes for mid-scale terminal operators in Thailand and Malaysia between full API 653 assessments. |
Methodological Framework
The analysis maps inspection services, maintenance programs, repair operations, and cleaning services, each validated through terminal operations managers, certified welding contractors, non-destructive testing equipment distributors, and regulatory compliance officers across India, Australia, Singapore, Japan, and Vietnam. Primary interviews with API 653 certified inspectors and secondary validation through Petroleum and Natural Gas Regulatory Board filings, Australian EPA enforcement records, Singapore MPA safety codes, and Japan METI technical standards enable bottom-up service volume estimation cross-checked against top-down terminal capacity expansion announcements.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include service type, end-user category, tank architecture, and technological application intensity. CAGRs derive from installed base expansion rates, regulatory mandate compliance timelines, and automation substitution curves. Forecast inputs incorporate India's state-run storage expansion schedules and Southeast Asian greenfield refinery construction pipelines without year-specific milestone assumptions.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement of India's CEA guidelines and Australia's EPA emission monitoring mandates would require recalibration. Forecasts reflect assumptions regarding certified workforce availability and equipment import supply chain stability. Revision becomes warranted when labor scarcity intensity or currency volatility crosses thresholds that alter automation adoption economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Middle-East Oil Country Tubular Goods (OCTG) Market
Oil & Gas
Romania Oil and Gas Market
Oil & Gas
Latin America Oilfield Chemicals Market
Oil & Gas
Kuwait Oil and Gas Market
Oil & Gas
Desalter Market
Oil & Gas
Canada Oil and Gas Pipeline Services Market
Oil & Gas
Pumpjack Market
Oil & Gas
Australia Oil and Gas Market
Oil & Gas
Drilling Bits Market
Oil & Gas
Well Cementing Market
Oil & Gas
Well Abandonment Services Market
Oil & Gas
Oil Tank Rotating Stacker Market
Oil & Gas
India Oil and Gas Market
Oil & Gas
Kuwait & Iraq Oilfield Chemicals Market
Oil & Gas
Intelligent Well Completion Market
Oil & Gas
Reservoir Analysis Market