
 Asia-Pacific Oil and Gas Storage Tank Market | 2026-2036
Asia-Pacific Oil and Gas Storage Tank Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Oil and Gas Storage Tank Market Outlook
Independent power producers and strategic petroleum reserve authorities are collapsing the traditional buyer mix once dominated by integrated oil majors. Koninklijke Vopak N.V. leverages its terminal network density across Singapore and Fujairah to anchor regional trading flows. McDermott International Ltd competes through offshore fabrication yards that sustain large-diameter spherical tank output. Toyo Kanetsu K.K. differentiates via cryogenic storage specialization for LNG import terminals.
Asia-Pacific oil and gas storage tanks are welded steel vessels designed to contain hydrocarbons at atmospheric or pressurized conditions, with wall thickness calibrated to API 650 and API 620 standards for seismic and wind loads. These structures buffer supply chain volatility, enable blending operations, and secure strategic reserves for energy-importing economies. Floating roof tanks dominate crude oil applications where vapor emission control determines regulatory compliance, while spherical tanks command premium margins in LNG and LPG service due to specialized fabrication requirements. Automated monitoring systems represent the fastest-growing technology segment as operators replace manual gauging to satisfy safety and environmental mandates.
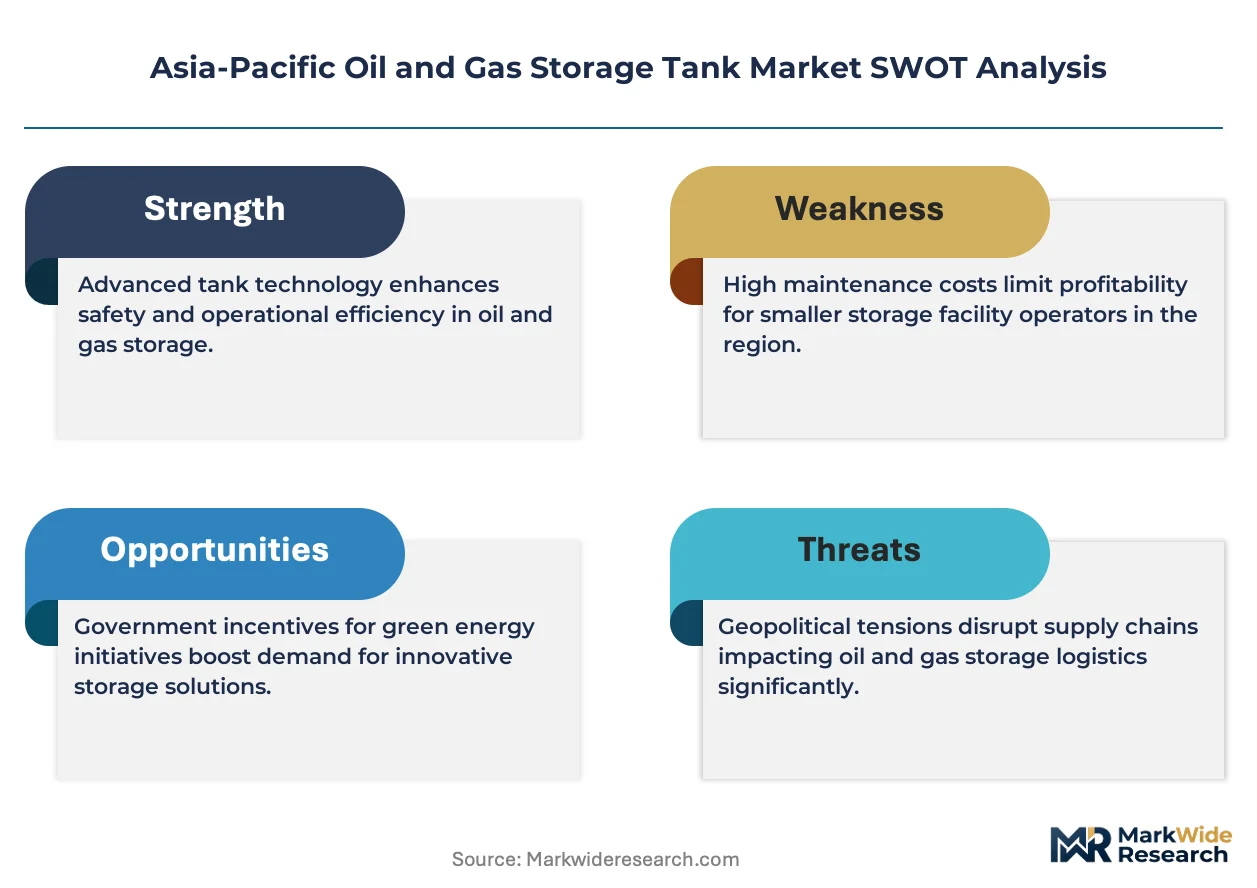
India's Petroleum and Natural Gas Regulatory Board enforces tank integrity management protocols that shape capital allocation toward corrosion-resistant materials and secondary containment. Japan's METI and METI-aligned JIS standards govern earthquake-resistant design, compelling manufacturers to validate base isolation and sloshing suppression features. Australia's state-level Work Health and Safety regulators impose atmospheric storage inspection cycles that sustain aftermarket retrofit demand. Stakeholders must weigh stranded asset risk against carbon border adjustments as hydrogen storage retrofits emerge as a contested long-term pivot.
Market Dynamics
India's Petroleum and Natural Gas Regulatory Board mandates double-bottom tank designs and corrosion-resistant materials, forcing capital reallocation across the Asia-Pacific region while seismic codes in Japan and Australia reshape engineering specifications.
Growth Catalysts
- Import dependence in Indonesia:Java-Bali corridor port-linked tank farms expand to buffer crude supply volatility for state refiners and independent power producers.
- API 650 and API 620 standards:Welded steel vessel specifications for seismic and wind loads drive replacement cycles across atmospheric and pressurized storage applications.
- Strategic petroleum reserve authorities:Government stockpiling programs in energy-importing economies sustain large-diameter tank demand outside traditional integrated oil major procurement.
Market Restraints
- Specialized spherical tank fabrication:LNG and LPG service requires premium-margin cryogenic construction that concentrates supply among limited offshore fabrication yards.
- Steel plate input volatility:Wall thickness calibration for seismic loads exposes project economics to commodity price swings in carbon steel and alloy materials.
- Carbon border adjustment exposure:Hydrogen storage retrofit timelines remain contested, creating stranded asset risk for conventional hydrocarbon tank investments.
Strategic Opportunities
- Vietnam and Philippines import terminals:Underpenetrated coastal storage infrastructure offers greenfield development potential for floating roof crude applications.
- Automated monitoring systems:Sensor networks replacing manual gauging satisfy safety mandates while opening aftermarket retrofit revenue across existing tank farms.
- Base isolation and sloshing suppression:METI-aligned JIS standards in Japan validate premium engineering exports to other earthquake-prone Asia-Pacific markets.
Industry Challenges
- Welding inspector certification timelines:API 650 and API 620 compliance requires qualified personnel that lag project award cycles across Southeast Asia.
- Legacy tank farm integration:Secondary containment retrofits for existing single-bottom structures demand operational downtime that conflicts with continuous supply commitments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Oil and Gas Storage Tank Market |
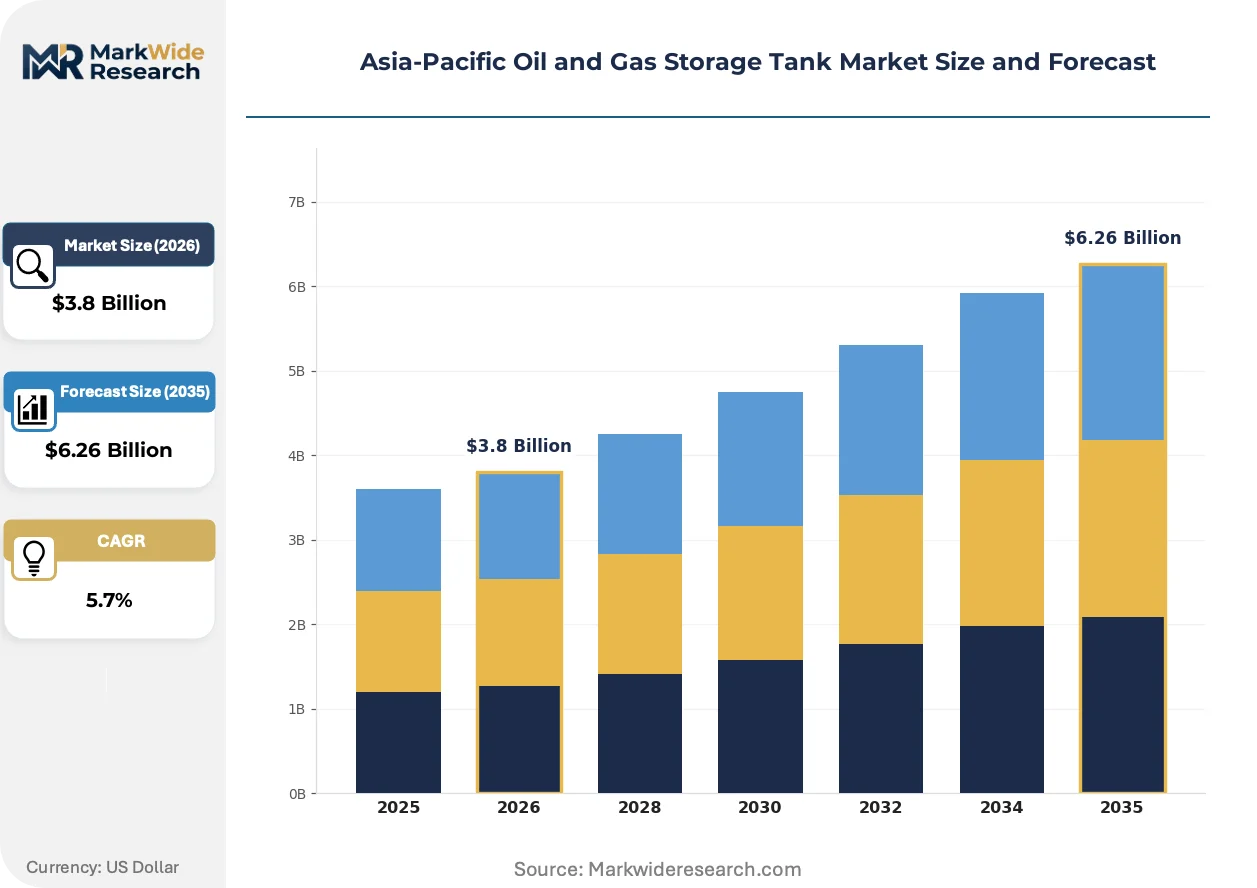
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Roof Tanks, Floating Roof Tanks, Spherical Tanks, Underground Tanks End User: Oil Refining, Natural Gas Processing, Chemical Manufacturing, Biofuels Production Installation: Above Ground, Below Ground, Offshore, Onshore Technology: Automated Systems, Manual Systems, Hybrid Systems, Monitoring Solutions |
| Companies Covered | CST Composites, Koninklijke Vopak N.V., McDermott International Ltd, TGE Gas Engineering GmbH, Oiltanking GmbH, Toyo Kanetsu K.K, Beltecno Corporation, Yachiyo Industries Co Ltd, DFC Pressure Vessel Manufacturer Co Ltd, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Oil and Gas Storage Tank Market Strategic Shifts
Sensor-driven automation and seismic engineering advances are compressing operational models across Asia-Pacific tank storage, while regulatory fragmentation between national petroleum boards and state safety agencies accelerates specification divergence.
Floating roof seal systems with vapor recovery integration are miniaturizing emission control hardware for crude oil applications. Refinery operators in Singapore and Fujairah adopt these compact designs to satisfy volatile organic compound mandates without full tank reconstruction. The technology is miniaturizing the capital barrier for regulatory compliance, enabling smaller terminal operators to achieve emission standards previously requiring greenfield investment.
METI's earthquake-resistant design protocols now govern base isolation validation for large-diameter tanks across Japan's industrial coast. The standard compels manufacturers to document sloshing suppression performance under simulated seismic loads, extending engineering certification cycles by months. LNG import terminals in Osaka Bay and Chiba Prefecture face the steepest compliance ramps, with project timelines stretching to accommodate third-party structural verification.
Independent power producers now contract directly with terminal operators, bypassing integrated oil majors that historically intermediated storage access. This disintermediation concentrates bargaining power among buyers with predictable offtake profiles, compressing pricing premiums for interruptible storage services. The shift is most visible in India's western coastal corridor, where state electricity boards secure dedicated tankage through long-term tolling arrangements.
Asia-Pacific Oil and Gas Storage Tank Market Segmentation
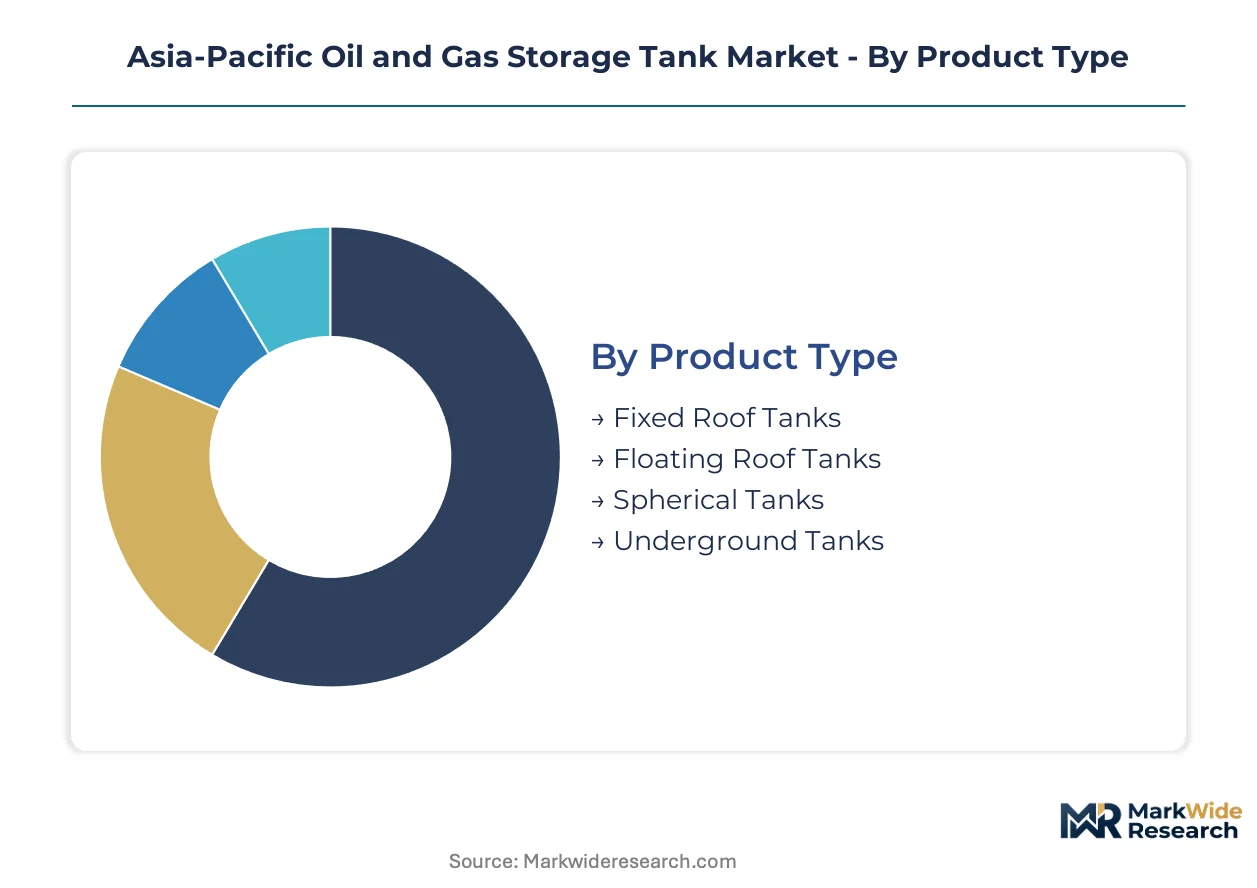
Storage tank procurement in Asia-Pacific fragments across four critical dimensions. Product geometry determines capital intensity and regulatory compliance pathways. End-user concentration in state-controlled refining and strategic reserves shapes contract structures and localization requirements.
Product Type:
Floating roof configurations command premium margins due to vapor emission control mandates across Singapore, Fujairah, and India's western coastal corridor. Spherical tanks extract the highest unit economics from LNG and LPG service where cryogenic fabrication expertise concentrates among Japanese and Korean yards.
- Floating Roof Tanks:These welded steel vessels feature pontoon or double-deck roofs that rise and fall with liquid levels, minimizing vapor space and volatile organic compound releases. India's Petroleum and Natural Gas Regulatory Board mandates these designs for crude storage above threshold capacities, driving replacement demand across Gujarat and Maharashtra refineries.
- Spherical Tanks:Pressure vessels fabricated from high-nickel alloy plates contain liquefied gases at cryogenic temperatures. Japan's Osaka Bay and Chiba Prefecture LNG import terminals sustain demand for METI-validated base isolation designs that command 40-60% fabrication premiums over atmospheric storage.
- Fixed Roof Tanks:Cone or dome-roof structures serve water-sensitive products and lower-volatility liquids where vapor recovery is secondary. These dominate chemical and biofuels applications across Southeast Asia due to lower capital barriers.
- Underground Tanks:Horizontal or vertical excavated installations buffer seismic risk and reduce land-use conflicts in Japan's dense industrial zones and Singapore's Jurong Island constraints.
The dominant share belongs to floating roof tanks, while spherical tanks are closing the gap fastest on LNG import terminal investments.
End User:
Application-driven cost tiers separate continuous-process refining from batch-mode chemical manufacturing. Strategic petroleum reserve authorities operate outside commercial pricing, distorting visible demand patterns.
- Oil Refining:Atmospheric and pressurized storage buffers crude supply volatility for state refiners across Indonesia's Java-Bali corridor and India's coastal processing hubs. India's double-bottom mandates and corrosion-resistant material standards reshape procurement specifications.
- Natural Gas Processing:Cryogenic spherical and bullet tanks handle condensate and NGL fractions at pressure. Australia's offshore gas developments and Vietnam's emerging import infrastructure sustain fabrication demand.
- Chemical Manufacturing:Fixed roof and specialized alloy tanks contain acids, solvents, and intermediates. Singapore's Jurong Island cluster and Thailand's Map Ta Phut industrial zone concentrate regional demand.
- Biofuels Production:Stainless steel and epoxy-lined tanks store ethanol and biodiesel blends. Indonesia's palm oil-derived biodiesel mandates and India's ethanol blending targets expand tank farm footprints.
Refining applications retain the largest installed base, though natural gas processing is expanding most quickly on LNG infrastructure commitments.
Installation:
Geography and seismic risk stratify engineering costs, with offshore fabrication carrying 2-3x onshore premiums due to marine logistics and platform integration.
- Above Ground:Vertical cylindrical tanks dominate crude and product storage across coastal tank farms. Japan's METI-aligned JIS standards and India's seismic zone classifications elevate foundation and anchoring costs.
- Below Ground:Excavated or mounded installations reduce visual impact and thermal exposure. These penetrate Japan's earthquake-prone industrial corridors and Singapore's land-constrained terminals.
- Offshore:Platform-integrated storage serves production facilities across Australia's Northwest Shelf and Malaysia's Sarawak waters. McDermott's fabrication yards and Korean shipbuilders compete for spherical and cylindrical contracts.
- Onshore:Conventional ground-level installation remains default for greenfield terminals in Vietnam and Philippines where infrastructure constraints are less severe.
Above ground installations hold the dominant position, while offshore configurations are gaining share fastest on deepwater gas development timelines.
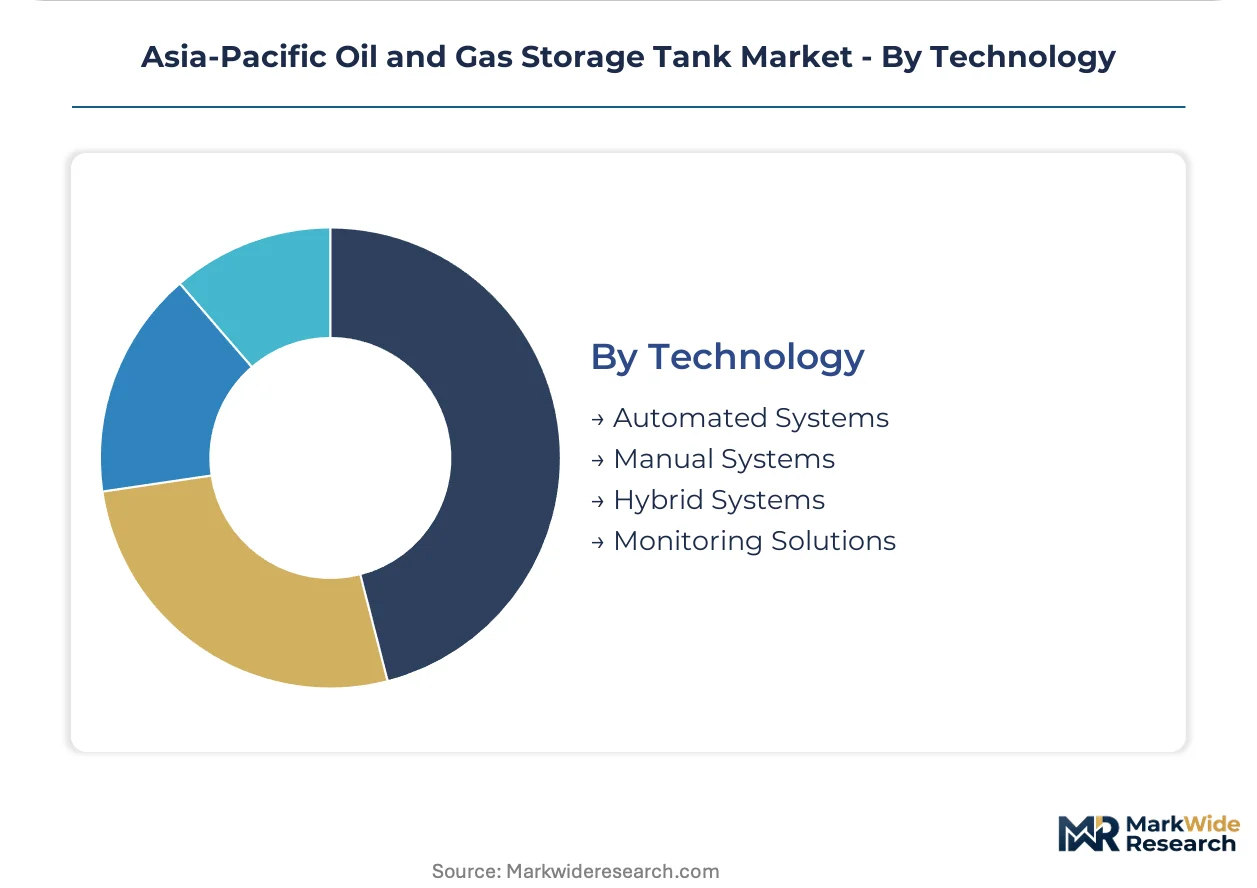
Technology:
Automation intensity separates safety-critical applications from cost-optimized legacy operations. Regulatory enforcement variance across national petroleum boards creates specification fragmentation.
- Automated Systems:Sensor networks, radar level gauges, and distributed control systems replace manual gauging. India's tank integrity protocols and Singapore's environmental mandates accelerate retrofit demand.
- Manual Systems:Dip tapes and sight glasses persist in smaller terminals and developing markets where capital constraints outweigh labor costs. These concentrate in Philippines and Vietnam secondary storage.
- Hybrid Systems:Partial automation with manual override capabilities bridges regulatory compliance and capital efficiency. These serve mid-scale independent power producers across India's western coastal corridor.
- Monitoring Solutions:Standalone leak detection, corrosion monitoring, and structural health diagnostics retrofit existing tank farms. Australia's Work Health and Safety inspection cycles sustain aftermarket revenue.
Automated systems command the leading share, with monitoring solutions climbing fastest on aging infrastructure integrity mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Terminal network density concentrates along Singapore's Jurong Island and Fujairah's coastal corridor, where tank farm operators leverage deepwater port access to anchor regional trading flows. India's Petroleum and Natural Gas Regulatory Board reshapes procurement specifications through double-bottom mandates and corrosion-resistant material standards. Japan's METI-aligned JIS standards govern earthquake-resistant design validation, extending engineering certification cycles for base isolation systems.
India
State refiners across Gujarat and Maharashtra expand crude storage to buffer supply volatility for processing hubs. The Petroleum and Natural Gas Regulatory Board enforces tank integrity protocols that force capital reallocation toward secondary containment and automated monitoring. The western coastal corridor concentrates demand as independent power producers secure dedicated tankage through long-term tolling arrangements with terminal operators.
Japan
LNG import terminals in Osaka Bay and Chiba Prefecture sustain demand for cryogenic spherical tanks with METI-validated seismic performance. METI's earthquake-resistant design protocols compel manufacturers to document sloshing suppression under simulated loads, stretching project timelines. Base isolation engineering for large-diameter tanks now exports to other earthquake-prone markets as a premium-validated capability.
Singapore
Jurong Island's land-constrained terminals drive adoption of compact floating roof seal systems with integrated vapor recovery. The port's trading hub status attracts independent power producers and strategic petroleum reserve authorities that bypass traditional integrated oil major intermediation. Terminal operators leverage network density to anchor regional flows between Middle Eastern crude suppliers and Southeast Asian refiners.
Indonesia
State refiners and independent power producers expand port-linked tank farms across the Java-Bali corridor to buffer import dependence. Growing crude supply volatility pushes capital allocation toward floating roof configurations that minimize vapor emissions. Java's northern coastal industrial zones concentrate greenfield development as domestic production declines accelerate import infrastructure commitments.
Australia
Offshore gas developments across the Northwest Shelf sustain demand for platform-integrated spherical and cylindrical storage. State-level Work Health and Safety regulators impose atmospheric storage inspection cycles that sustain aftermarket retrofit demand for aging tank farms. Western Australia's LNG export terminals and Queensland's emerging import infrastructure split procurement between cryogenic fabrication and conventional atmospheric applications.
Asia-Pacific Oil and Gas Storage Tank Market Competitive Environment
Concentration sits with terminal network operators and specialized fabrication yards that anchor regional supply chains. The vendor base stratifies across three tiers: multinational terminal operators leveraging geographic density, offshore fabrication specialists commanding premium margins in cryogenic applications, and regional steel fabricators competing on atmospheric storage cost efficiency. Dominant competitive moves include strategic partnerships between terminal operators and national oil companies, plus capacity expansion in earthquake-resistant engineering capabilities.
Among Dutch and German terminal operators, Koninklijke Vopak N.V. and Oiltanking GmbH exemplify network-density archetypes that leverage port-linked asset positions across Singapore and Fujairah. Japanese fabricators Toyo Kanetsu K.K. and Yachiyo Industries Co Ltd occupy specialist positions in cryogenic and seismic-engineered storage systems. McDermott International Ltd represents the offshore fabrication archetype with yards sustaining large-diameter spherical tank output for deepwater gas developments.
| Leading Market Players |
|---|
| CST Composites |
| Koninklijke Vopak N.V. |
| McDermott International Ltd |
| TGE Gas Engineering GmbH |
| Oiltanking GmbH |
| Toyo Kanetsu K.K |
| Beltecno Corporation |
| Yachiyo Industries Co Ltd |
| DFC Pressure Vessel Manufacturer Co Ltd |
| Others |
Value Chain & Pricing Dynamics
Large-diameter spherical tank fabrication capacity utilization above 85% across Japanese and Korean yards establishes price floors for cryogenic storage while compressing margins on atmospheric tank orders. Scale concentration in offshore fabrication creates asymmetric bargaining power where LNG import terminal developers absorb 40-60% premiums for METI-validated seismic engineering.
Pricing Analysis
India's Petroleum and Natural Gas Regulatory Board dictates the pricing tier structure through double-bottom mandates and corrosion-resistant material standards that stratify procurement across certification levels. Three-tier pricing structure across premium seismic-validated, standard API-compliant, and economy manual-system tiers reflects divergent engineering validation requirements. Cost compression in economy-tier atmospheric storage intensifies as regional steel fabricators compete on plate thickness optimization. Independent power producers exhibit highest price sensitivity due to predictable offtake profiles that commoditize interruptible storage services.
Supply Chain Analysis
Strait of Malacca transit underwrites carbon steel plate delivery schedules to Singapore and Fujairah terminal clusters, exposing project timelines to maritime congestion. Supply concentrates in Japan, South Korea, and China for high-nickel alloy plates, seismic base isolation systems, and automated monitoring sensors. Steel plate input volatility and qualified welding inspector scarcity constitute structural risks that extend fabrication lead times. Distribution runs through port-linked terminal operators who intermediate between fabrication yards and end-user refiners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified seismic engineering capability gaps separate premium-margin LNG terminal contractors from commoditized atmospheric storage fabricators, concentrating returns among METI-aligned validation holders.
For Market Incumbents: Shield terminal network positions by securing long-term tolling arrangements with India's state electricity boards before independent power producer consolidation accelerates. Expand backward integration into corrosion-resistant plate supply through captive partnerships with Korean mills. METI validation for base isolation systems represents the priority defensive moat against emerging Chinese fabrication entrants. For New Entrants and Emerging Players: Anchor in Vietnam and Philippines coastal storage infrastructure where greenfield floating roof demand outpaces established terminal operator coverage. Target automated monitoring retrofit contracts across Australia's aging tank farms as state Work Health and Safety inspection cycles intensify. Partner with regional EPC contractors to bypass incumbent fabrication yard queues. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among terminal operators with dedicated strategic petroleum reserve contracts and long-term tolling arrangements. Five-to-ten-year viability favors METI-validated seismic engineering specialists over undifferentiated atmospheric fabricators. Monitor hydrogen storage retrofit announcement velocity as stranded asset risk inflection signal for conventional hydrocarbon tank portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Seismic Engineering Certification Investment | METI-aligned JIS validation unlocks premium pricing for Osaka Bay LNG terminal contracts. |
| Automated Monitoring System Integration | Sensor network deployment satisfies India's Petroleum and Natural Gas Regulatory Board integrity mandates. |
| Corrosion-Resistant Material Backward Integration | Captive high-nickel alloy supply secures spherical tank margins against commodity volatility. |
| Long-Term Tolling Arrangement Expansion | Dedicated tankage contracts with India's western coastal power producers stabilize utilization. |
| Hydrogen Storage Retrofit Capability Development | Carbon border adjustment preparation positions terminal assets for fuel transition scenarios. |
Study Parameters
Desk research of customs trade databases, API standards documentation, and national petroleum board filings preceded structured interviews with EPC contractors, terminal operations managers, and refinery procurement leads. Primary fieldwork with Japanese and Korean fabrication yards, Singapore Jurong Island operators, and India's Petroleum and Natural Gas Regulatory Board officials anchored demand-side validation. Secondary sources included IEA storage capacity reports, METI technical bulletins, and project development databases. Bottom-up tank unit economics triangulated against top-down regional capacity projections.
Variance decomposition across product type, end-user concentration, installation geography, and technology automation intensity shaped the analytical framework. Modeled dimensions included floating roof versus spherical geometry, state refiner versus strategic reserve procurement, above-ground versus offshore configuration, and manual versus automated monitoring tiers. CAGRs derived from unit shipment trajectories and average selling price movements across the projection horizon. Forecast inputs incorporated steel plate price indices, seismic code amendment timelines, and LNG import terminal commitment pipelines.
Decision-makers should treat outputs as directional under stable regulatory enforcement and unaltered carbon border adjustment timelines; material deviation would warrant model refresh. Forecasts embed assumptions regarding welding inspector certification pipeline expansion and alloy plate supply continuity. Practitioners should keep alternative scenarios live as hydrogen storage retrofit adoption curves and METI validation requirement amendments evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Oil and Gas Midstream Market
Oil & Gas
Canada Oil and Gas Market
Oil & Gas
Clear Brine Fluids Market
Oil & Gas
Asia Pacific Upstream Oil and Gas Services Market
Oil & Gas
Oman Oil and Gas Upstream Market
Oil & Gas
Wellhead and Christmas Tree Special Parts Market
Oil & Gas
Trinidad and Tobago Oil and Gas Upstream Market
Oil & Gas
West Africa Oil and Gas Midstream Market
Oil & Gas
East Africa Oil and Gas Market
Oil & Gas
Ecuador Wireline Logging Services Market
Oil & Gas
Modular Refinery Market
Oil & Gas
United States Wireline Logging Services Market
Oil & Gas
Drilling Services Market
Oil & Gas
Algeria Oil and Gas Upstream Market
Oil & Gas
Process Simulation Software in Oil and Gas Market
Oil & Gas
Well Abandonment Services Market