
 Well Cementing Market | 2026-2036
Well Cementing Market Size, Share, and Industry Trends Forecast 2026-2036
Well Cementing Market Intelligence
Gulf of Mexico service capacity is repositioning toward ultradeepwater rig commitments. Halliburton leverages integrated well construction portfolios to anchor premium cementing contracts across North American shale basins. Schlumberger sustains technology leadership through automated cement placement systems that reduce nonproductive time. Baker Hughes Company competes on material science differentiation in sour-gas environments.
Well cementing comprises the placement of specialized Portland-based slurries into the annular space between casing and borehole wall, formulated with density modifiers, fluid-loss additives, and retarders to achieve compressive strengths exceeding 1,000 psi within 24 hours under downhole temperature and pressure conditions. Its primary purpose is zonal isolation, preventing fluid migration between formations and protecting casing integrity throughout the well lifecycle. Primary cementing commands the largest volume share as initial casing strings represent non-discretionary demand, while deepwater cementing captures disproportionate margin pools due to technical complexity and limited qualified service capacity. Foamed cementing is gaining application in low-fracture-gradient formations where conventional slurries risk lost circulation.
API Specification 10A, ISO 10426-1, and the EPA's Underground Injection Control regulations collectively govern product qualification, testing protocols, and environmental compliance across US onshore and offshore operations. These frameworks elevate barriers for unqualified suppliers and shift procurement criteria toward certified performance documentation. Stakeholders must monitor regulatory divergence between federal US standards and emerging state-level methane monitoring requirements that could reshape cement sheath integrity specifications.
Market Dynamics
Extended lateral drilling in the Permian Basin is compressing cementing cycle times and forcing operators to specify pre-mixed, high-performance slurries rather than field-blended formulations. This operational shift concentrates procurement power among integrated service providers capable of guaranteed placement performance.
Growth Catalysts
- Deepwater rig commitments:Brazil's pre-salt discoveries and West African frontier basins are expanding demand for high-pressure, high-temperature cementing systems.
- API Specification 10A tightening:The updated standard elevates qualification barriers for conventional suppliers and redirects procurement toward certified performance documentation.
- Foamed cementing technology:Low-fracture-gradient formations in mature North American shale plays are adopting nitrogen-stabilized slurries to prevent lost circulation events.
Market Restraints
- Proppant and specialty additive cost volatility:Silica flour and latex additives face supply concentration from limited domestic sources, squeezing margin predictability for regional blenders.
- Qualified deepwater service capacity:Gulf of Mexico ultradeepwater certification requirements restrict deployable assets to a handful of integrated providers.
- Geopolymer cement substitution:Experimental alkali-activated binders threaten Portland-based volume in carbon-intensive regulatory jurisdictions.
Strategic Opportunities
- Carbon capture and storage wellbores:EPA Underground Injection Control Class VI permitting is creating demand for ultra-low-permeability cement sheaths in saline aquifer formations.
- Automated cement placement systems:Real-time density and rheology monitoring is converging with predictive analytics to reduce nonproductive time in extended-reach laterals.
- Argentina Vaca Muerta development:Underdeveloped pressure pumping infrastructure creates white space for turnkey cementing contracts with guaranteed zonal isolation performance.
Industry Challenges
- HPHT cementing specialist shortage:Deepwater technical certification programs produce fewer qualified engineers than replacement demand requires.
- ISO 10426-1 compliance timeline:Extended laboratory qualification protocols delay new additive formulations by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Well Cementing Market |
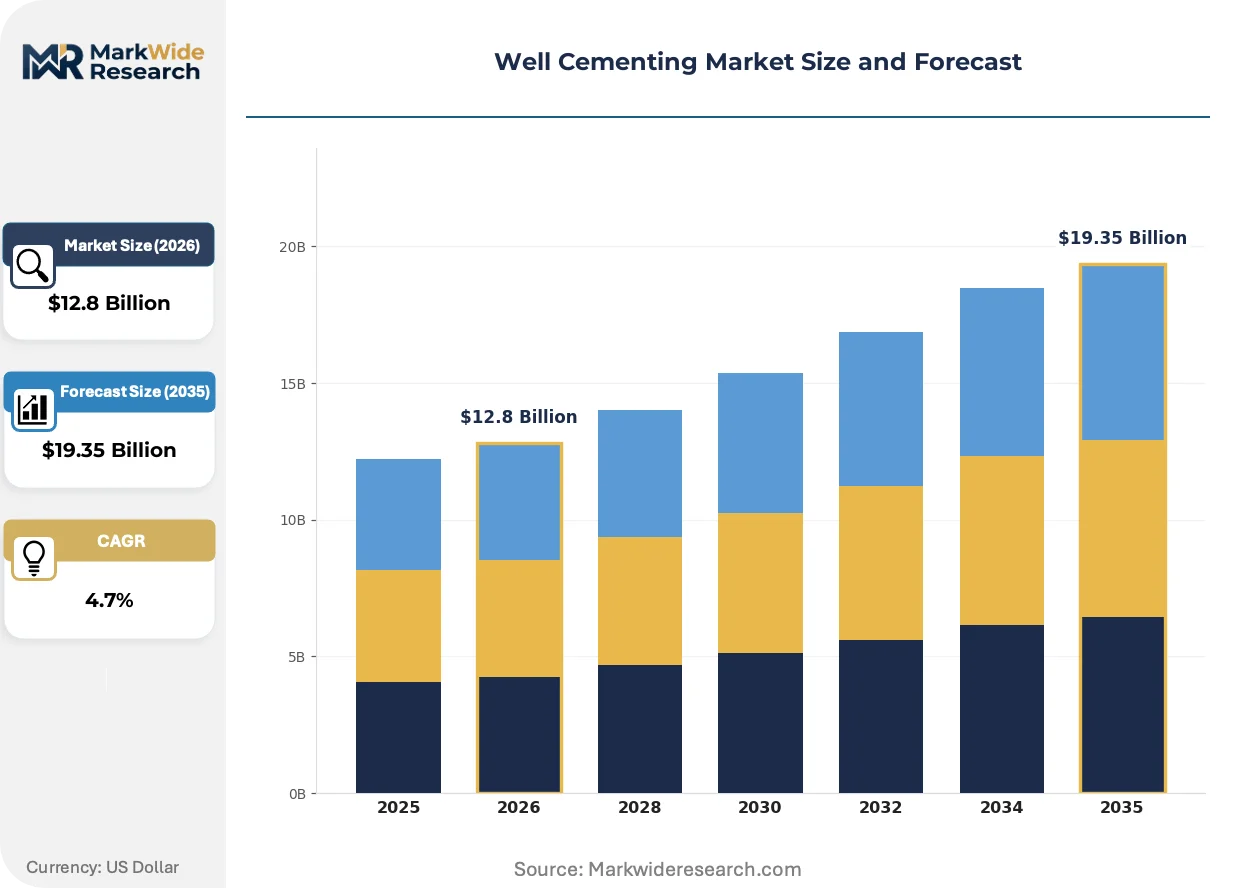
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $19.35 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Class A Cement, Class G Cement, Oil Well Cement, High-Temperature Cement, Light-Weight Cement Application: Primary Cementing, Remedial Cementing, Plug Cementing, Squeeze Cementing, Zonal Isolation Technology: Foamed Cementing, Accelerated Cementing, Lightweight Cementing, Deepwater Cementing, Lost Circulation Cementing End User: Oilfield Operators, Drilling Contractors, Well Service Companies, Exploration Firms, Production Companies |
| Companies Covered | Halliburton, Schlumberger, Baker Hughes Company, China Oilfield Services Limited, Weatherford, Trican Well Service Ltd., Calfrac Well Services Ltd., Sanjel Energy Services, Advanced Cementing Services Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Well Cementing Market Strategic Shifts & Innovations
Digital cementing design platforms are compressing the engineering-to-execution cycle and enabling real-time slurry optimization based on downhole telemetry. This technological layer is reshaping competitive advantage toward data-integrated service models.
Self-healing cement formulations containing microencapsulated polymers are unifying mechanical integrity and chemical resistance in a single sheath system. Operators in sour-gas environments are specifying these materials for critical casing strings. The technology is unifying previously separate remedial cementing budgets into primary cementing specifications.
EPA methane monitoring rules are tightening cement sheath integrity requirements for new well completions. The regulation forces operators to document annular gas migration potential before production startup. Shale basins with legacy cementing practices face the steepest compliance re-engineering costs.
Integrated service contracts are displacing discrete cementing procurement in North American shale plays. Operators bundle cementing with directional drilling and completions to transfer execution risk. The Permian Basin exhibits the most pronounced concentration of single-source well construction agreements.
Well Cementing Market Segmentation
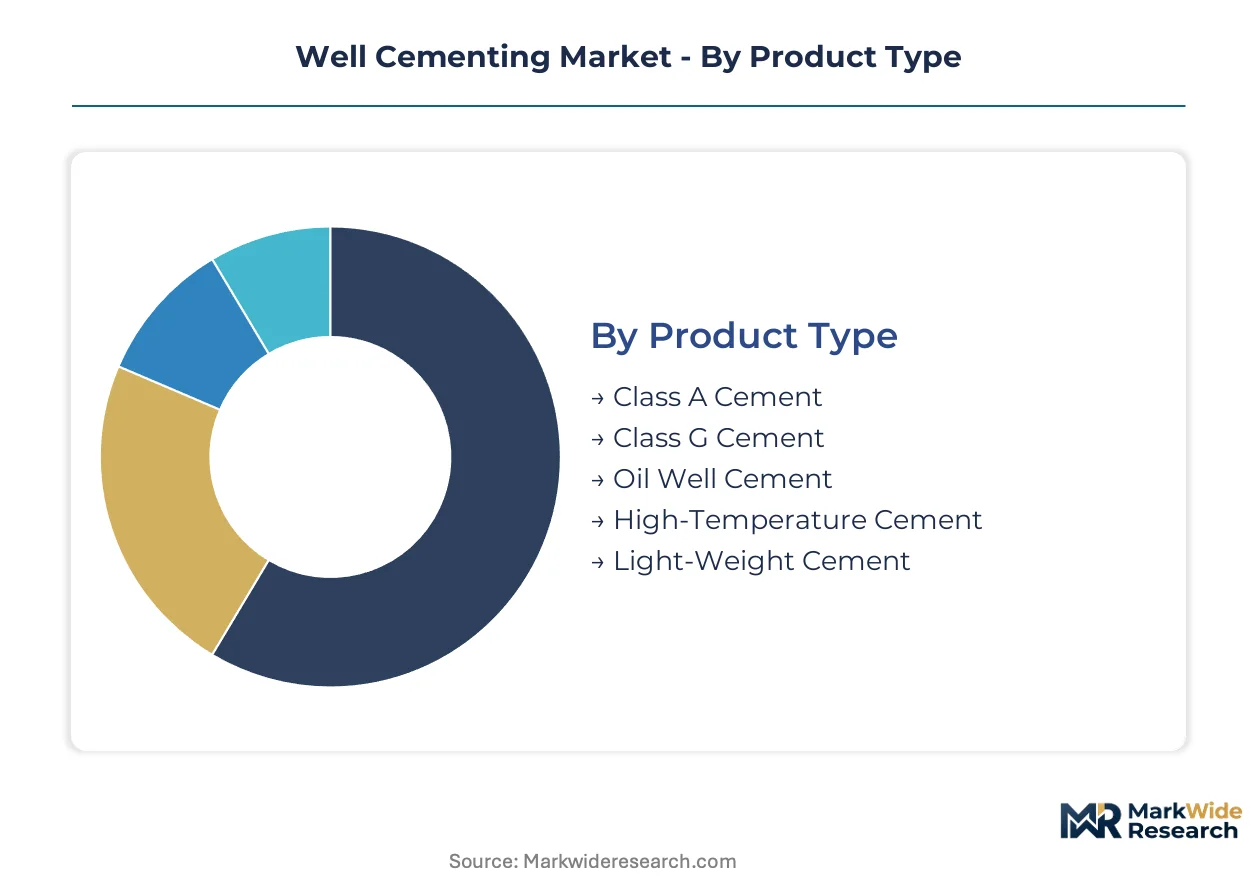
Well cementing procurement patterns diverge sharply between onshore shale basins and deepwater frontiers. Operators select product formulations and service technologies based on fracture gradient, temperature regime, and regulatory jurisdiction rather than price alone.
Product Type:
Buyers differentiate primarily by downhole temperature tolerance and compressive strength requirements rather than brand preference.
- Class G Cement:API-certified formulation delivers sulfate resistance and predictable thickening times across 8,000-12,000 foot vertical depths. Gulf of Mexico operators specify this grade for intermediate casing strings where temperature stability is non-negotiable.
- High-Temperature Cement:Silica-flour-enhanced blends maintain sheath integrity above 230°F in HPHT pre-salt formations. Brazil's deepwater discoveries are concentrating procurement of these specialty formulations where conventional Portland systems fail.
- Class A Cement:Standard construction-grade binder adapted for shallow surface casing with minimal additive loading.
- Oil Well Cement:API 10A-compliant base material requiring retarder modification for extended pumping times in extended-reach laterals.
- Light-Weight Cement:Bentonite or pozzolan-extended systems for low-fracture-gradient formations in mature Permian sub-basins.
Class G Cement leads volumes today; High-Temperature Cement is gaining share fastest.
Application:
Service intensity and margin structure vary dramatically between initial well construction and post-drilling intervention work.
- Primary Cementing:Initial annular placement during casing run represents non-discretionary demand with volume concentration in Permian multi-well pads. Extended lateral lengths are compressing job cycle times and forcing pre-mixed slurry specifications.
- Zonal Isolation:Precision placement across producing intervals demands real-time density monitoring and automated placement systems. West African frontier developments are specifying guaranteed isolation performance contracts with penalty clauses.
- Remedial Cementing:Squeeze and circulation repair of failed primary jobs carries premium pricing but irregular demand timing.
- Plug Cementing:Abandonment and temporary suspension applications governed by EPA Underground Injection Control integrity demonstrations.
- Squeeze Cementing:Targeted leak repair requiring pinpoint pressure control in depleted formations.
Primary Cementing commands the largest revenue pool; Zonal Isolation exhibits the steepest expansion trajectory.
Technology:
Technical sophistication determines service provider qualification tiers and contract exclusivity.
- Deepwater Cementing:HPHT placement systems with real-time pressure management and dual-gradient capability. Limited qualified vessel capacity in the Gulf of Mexico creates procurement bottlenecks for ultradeepwater rig commitments.
- Foamed Cementing:Nitrogen-stabilized slurries with densities below 12 ppg for formations where conventional systems risk lost circulation. North American shale operators are adopting this technology for depleted parent well offsets.
- Accelerated Cementing:Calcium chloride or seawater-blended systems for shallow water flow prevention in subsea conductor strings.
- Lightweight Cementing:Glass bead or ceramic microsphere systems for marginally pressured zones.
- Lost Circulation Cementing:Thixotropic and fibrous slurries for naturally fractured or vugular carbonate formations.
Deepwater Cementing anchors premium pricing; Foamed Cementing is climbing the fastest.
End User:
Procurement authority concentrates among integrated operators with in-house drilling engineering capabilities.
- Oilfield Operators:Supermajors and large independents with direct cementing specification authority and long-term service agreements. These buyers bundle cementing with directional drilling and completions to transfer execution risk.
- Drilling Contractors:Dayrate-based rig operators with limited cementing discretion beyond basic API compliance.
- Well Service Companies:Regional pressure pumping specialists subcontracted for remedial and plug cementing campaigns.
- Exploration Firms:Venture-backed wildcatters with sporadic demand and price-sensitive procurement.
- Production Companies:Late-life asset operators focused on workover and abandonment cementing.
Oilfield Operators dominate contract value; Well Service Companies are expanding fastest through integrated service bundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Deepwater cementing demand in Brazil outpaces onshore activity in Argentina, while Permian Basin operators compress cycle times faster than North Sea counterparts. Regulatory divergence between EPA Underground Injection Control and Brazil's ANP certification standards reshapes supplier qualification timelines across Atlantic basins.
United States
Permian Basin extended laterals drive pre-mixed slurry specifications, displacing field-blended formulations. EPA Underground Injection Control Class VI permitting tightens cement sheath integrity documentation for carbon storage wells. Houston anchors integrated service provider headquarters, concentrating procurement authority for Gulf of Mexico ultradeepwater contracts.
Brazil
Pre-salt discoveries below 2,000 meters water depth expand high-temperature cement procurement. ANP technical standards mandate dual-gradient placement system certification for Bacia de Santos operations. Macaé service vessel clusters face qualified capacity constraints as Petrobras accelerates rig commitments.
China
Tarim Basin HPHT exploration tightens product qualification under GB standards administered by SAMR. Sinopec and CNOOC bundle cementing with directional drilling in Sichuan shale gas developments. Tianjin port logistics clusters concentrate specialty additive import flows for Bohai Bay offshore programs.
Norway
North Sea electrification projects require ultra-low-permeability cement sheaths for subsea tiebacks. Petroleum Safety Authority Norway enforces stricter zonal isolation verification than UK HSE equivalents. Stavanger engineering centers anchor automated placement technology development for Johan Sverdrup phase expansions.
Saudi Arabia
Jafurah unconventional gas development creates demand for sour-gas-resistant cement systems. Saudi Aramco localizes procurement through IKTVA requirements, redirecting contracts toward in-Kingdom blenders. Dhahran technology centers pilot self-healing formulations for high-H2S carbonate reservoirs.
Well Cementing Market Key Industry Players
North American integrated service providers anchor the premium tier; Chinese state-affiliated operators hold volume-scale positions in Asia-Pacific. The vendor base stratifies across three archetypes: full-service well construction integrators, regional pressure pumping specialists, and state-owned oilfield service arms. Dominant competitive moves include backward integration into specialty additive manufacturing and technology licensing partnerships for automated placement systems.
Within the integrated service tier, Halliburton and Schlumberger exemplify providers bundling cementing with directional drilling and completions. Baker Hughes Company occupies a position emphasizing material science differentiation. Among Asia-Pacific state-affiliated operators, China Oilfield Services Limited represents the volume-scale archetype serving domestic unconventional and offshore programs.
| Leading Market Players |
|---|
| Halliburton |
| Schlumberger |
| Baker Hughes Company |
| China Oilfield Services Limited |
| Weatherford |
| Trican Well Service Ltd. |
| Calfrac Well Services Ltd. |
| Sanjel Energy Services |
| Advanced Cementing Services Incorporated |
| Others |
Cost & Logistics Intelligence
Pre-mixed high-performance slurry specifications from Permian Basin operators are compressing field-blending capacity and forcing regional blenders toward certified additive partnerships that elevate input costs and concentrate margin pools among integrated providers.
Pricing Analysis
Distributor margins on specialty additives vary sharply by certification tier. Three-tier pricing structure across API-certified premium, ISO-compliant standard, and non-certified economy levels separates deepwater-qualified systems from onshore commodity blends. Cost compression in standard-grade Portland formulations is intensifying because silica flour and latex additive supply concentrates from limited domestic sources. Exploration firms exhibit highest price sensitivity, while supermajors prioritize guaranteed placement performance over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with Chinese specialty additive manufacturing and domestic silica flour processing. Raw material flows draw from US Portland clinker production, Chinese retarder and fluid-loss polymer supply, and Middle Eastern barite sourcing. Tariff exposure on imported polymers threatens margin stability for regional blenders lacking captive chemical production. Distribution runs through Houston logistics clusters for Gulf of Mexico offshore programs and Midland basin transload terminals for Permian onshore demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA Underground Injection Control Class VI permitting for carbon storage wellbores is compounding demand for ultra-low-permeability cement systems and reshaping procurement criteria toward certified performance documentation.
For Market Incumbents: Deploy automated placement technology licensing to anchor premium service contracts. Integrate backward into specialty additive manufacturing to secure silica flour and latex supply chains against cost volatility. Geopolymer cement substitution in carbon-intensive jurisdictions threatens Portland-based volume; counter with self-healing formulation patents for sour-gas positioning. For New Entrants and Emerging Players: Foamed cementing systems for depleted parent well offsets offer the most penetrable technology wedge. Target Argentina Vaca Muerta where underdeveloped pressure pumping infrastructure creates white space for turnkey contracts. Lead with real-time density monitoring capabilities to differentiate from established field-blending operators. For Investors and Strategic Acquirers: Asymmetric upside sits with automated placement technology specialists holding HPHT certification. Long-term viability hinges on regulatory compounding through methane monitoring rules and carbon storage permitting. Watch EPA Class VI permit issuance velocity as inflection indicator for ultra-low-permeability cement sheath demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Additive Manufacturing | Captive silica flour production secures margin stability against supply concentration. |
| Automated Placement Technology Licensing | Schlumberger-type density monitoring systems reduce nonproductive time in extended laterals. |
| Self-Healing Formulation Patent Development | Microencapsulated polymer systems unify mechanical integrity for sour-gas carbonate reservoirs. |
| Carbon Storage Wellbore Certification Investment | EPA Class VI qualification opens saline aquifer cementing contracts with ultra-low-permeability specifications. |
| Argentina Vaca Muerta Turnkey Contracts | Guaranteed zonal isolation performance agreements capture white space in underdeveloped infrastructure. |
Research Approach
Multiple input streams — drilling engineering directors at supermajors, procurement leads at regional pressure pumping specialists, cementing operations managers at integrated service providers, and regulatory affairs officers — were reconciled against API Specification 10A compliance databases, EPA Underground Injection Control permit filings, ANP technical standard submissions, and customs trade records for specialty additive imports. Bottom-up well count and cement volume estimates across Brazil pre-salt, Permian Basin, and Gulf of Mexico ultradeepwater programs were cross-referenced with top-down service revenue allocations from SEC filings.
Historical rig commitment patterns and panel-based input from HPHT cementing engineers informed the projection framework across the analysis window. Segmentation dimensions modeled include product type by temperature tolerance, application by service intensity, technology by placement sophistication, and end user by procurement authority tier. CAGRs were derived from regression analysis against rig count trajectories and lateral length expansion curves, with adjustment for qualified deepwater service capacity constraints and ISO 10426-1 compliance timeline delays.
The model holds under stable regulatory enforcement of API and ISO standards; deviation in EPA methane monitoring rule stringency or accelerated geopolymer substitution mandates would shift volume and value distributions. Forecasts reflect documented assumptions regarding Brazil pre-salt rig commitment schedules and Permian Basin drilling efficiency gains. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
South and Central America Oil Country Tubular Goods (OCTG) Market
Oil & Gas
Oil and Gas Logistics Market
Oil & Gas
Crown Block Market
Oil & Gas
Europe Well Intervention Market
Oil & Gas
Europe Oilfield Services Market
Oil & Gas
Global Oilfield Stimulation Chemicals Market
Oil & Gas
GCC Natural Gas Market
Oil & Gas
North America Wireline Logging Services Market
Oil & Gas
India LNG Bunkering Market
Oil & Gas
Australia Oil and Gas Upstream Market
Oil & Gas
Asia-Pacific Digital Oilfield Market
Oil & Gas
Global Fracking Chemicals Market
Oil & Gas
US Oil and Gas Analytics Market
Oil & Gas
Casing and Cementation Hardware Market
Oil & Gas
Rigless Intervention Systems Sales Market
Oil & Gas
South America LNG Bunkering Market