
 North America Fracking Chemicals Market | 2026-2036
North America Fracking Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
North America Fracking Chemicals Market Analytics
Market Context
Petroleum engineering talent availability is collapsing across the Permian and Bakken basins, constraining deployment velocity for advanced chemical programs. Halliburton Company leverages its integrated service model to bundle chemical supply with pumping operations, capturing recurring offtake from majors and independents alike. BASF SE anchors its position through backward integration into acrylic acid and amine chemistry, securing feedstock cost advantages for friction reducer production. Dow Chemical Company competes via its Midland, Michigan R&D campus, where polymer scientists refine high-molecular-weight polyacrylamides for slickwater systems.
Technical Definition and Segment Structure
North America fracking chemicals comprise engineered fluid additives—biocides, friction reducers, surfactants, and gelling agents—blended into base fluids at concentrations typically ranging from 0.1 to 5.0 weight percent to modify rheology, reduce pipe friction, prevent microbial degradation, and stabilize proppant transport during hydraulic fracturing operations. Friction reducers command the largest product-type volume share, though gelling agents capture disproportionate margin pools in high-temperature, high-pressure applications exceeding 150 degrees Celsius bottom-hole static temperature. Among end users, service companies represent the fastest-growing procurement segment as independents outsource chemical selection and logistics to specialists rather than maintaining in-house formulation labs. Horizontal drilling applications consume the majority of chemical volumes, with multi-stage completions in the Delaware and Midland sub-basins requiring 50 to 100 percent more additive loading per wellbore than vertical equivalents.
Regulatory Framework and Outlook
The EPA administers underground injection control permits under the Safe Drinking Water Act, while state regulators including the Texas Railroad Commission and New Mexico Oil Conservation Division impose additional chemical disclosure mandates through FracFocus and state-specific reporting portals. OSHA's Process Safety Management standard and the Department of Transportation's hazardous materials shipping rules further govern handling, storage, and transportation of flammable and corrosive additives across state lines. Stakeholders must monitor evolving state-level groundwater protection statutes and EPA reconsideration of effluent limitation guidelines, as tightening discharge standards could force reformulation of biocide packages and accelerate substitution toward biodegradable surfactant chemistries.
Market Dynamics
Longer lateral completions in the Permian Basin are forcing chemical suppliers to reformulate friction reducers for higher shear tolerance, while EPA underground injection control rule updates are mandating biocide disclosure thresholds that reshape formulation economics.
Growth Catalysts
- Delaware Basin drilling intensity:Operators in this sub-basin now complete wells with 15,000-foot laterals, doubling additive loading per stage compared to legacy vertical designs.
- Texas Railroad Commission disclosure mandates:FracFocus reporting requirements have professionalized chemical sourcing, driving demand for pre-certified additive packages from specialist blenders.
- High-temperature gelling agent chemistry:Bottom-hole static temperatures exceeding 150 degrees Celsius in deep Wolfcamp zones require premium synthetic gel systems that command sustained margin premiums.
Market Restraints
- Acrylic acid feedstock volatility:Friction reducer producers face margin compression when propylene derivative costs spike, as polyacrylamide synthesis cannot absorb rapid input swings.
- Permian logistics concentration:Midland-anchored supply nodes create single-point vulnerability for just-in-time chemical delivery to multi-pad drilling programs.
- Biocide substitution limits:Glutaraldehyde alternatives lack equivalent broad-spectrum efficacy against sulfate-reducing bacteria in anoxic reservoir conditions.
Strategic Opportunities
- New Mexico Mancos-Gallup expansion:The San Juan Basin's reactivated oil window offers first-mover positioning for friction reducer suppliers ahead of infrastructure buildout.
- OSHA Process Safety Management alignment:Service companies bundling certified handling protocols with chemical supply capture recurring offtake from liability-conscious independents.
- Closed-loop blending systems:On-site modular units reduce transportation exposure and enable real-time viscosity adjustment based on formation response.
Industry Challenges
- Petroleum engineering talent scarcity:Field-specific expertise in rheology optimization and formation damage prevention has contracted across the Permian and Bakken, constraining deployment of advanced chemical programs.
- Multi-supplier integration complexity:Operators sourcing biocides, friction reducers, and surfactants from separate vendors face compatibility failures and non-productive time during stage transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Fracking Chemicals Market |
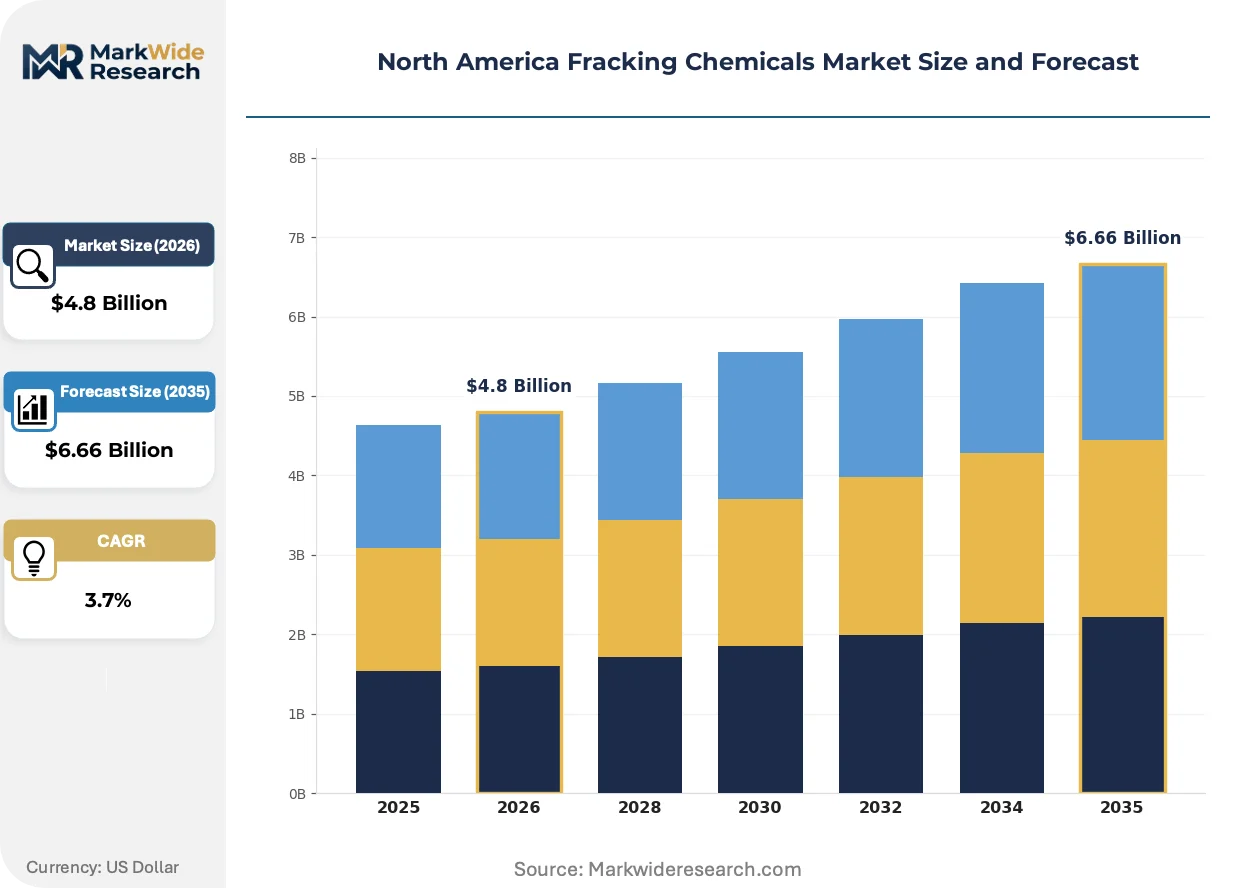
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biocides, Friction Reducers, Surfactants, Gelling Agents End User: Oil & Gas Operators, Service Companies, Energy Firms, Independents Application: Horizontal Drilling, Vertical Drilling, Enhanced Oil Recovery, Shale Gas Extraction Distribution Channel: Direct Sales, Online Sales, Distributors, Retailers |
| Companies Covered | Halliburton Company, BASF SE, Dow Chemical Company, Baker Hughes Incorporated, Solvay SA, CES Energy Solutions Corp, DuPont de Nemours Inc., Schlumberger Limited, Ecolab Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Fracking Chemicals Market Evolving Landscape
Formulation science is splitting between commodity slickwater systems and engineered high-performance packages, while regulatory disclosure requirements and operator procurement consolidation are rewiring competitive dynamics.
High-molecular-weight polyacrylamide friction reducer technology is bifurcating the product landscape. Standard anionic powders serve cost-sensitive Permian independents running 50-stage programs. Emulsion-based anionic copolymers with enhanced shear recovery capture share among majors drilling 80-plus stage laterals in the Delaware sub-basin. This split is compressing mid-tier suppliers lacking both commodity scale and specialty R&D depth.
EPA reconsideration of effluent limitation guidelines under the Clean Water Act is forcing biocide package reformulation. Discharge standards tightening for produced water recycling facilities are accelerating substitution toward biodegradable quaternary ammonium compounds. Delaware Basin operators with centralized water handling infrastructure face the steepest compliance timelines and are pre-qualifying alternative chemistries ahead of rule finalization.
Integrated service contracting is displacing discrete chemical procurement. Independents in the Midland sub-basin now delegate additive selection, logistics, and real-time blending to pumping service providers rather than maintaining in-house formulation laboratories. This consolidation concentrates purchasing power among four major service companies and marginalizes standalone chemical distributors lacking technical field support capabilities.
North America Fracking Chemicals Market Segmentation
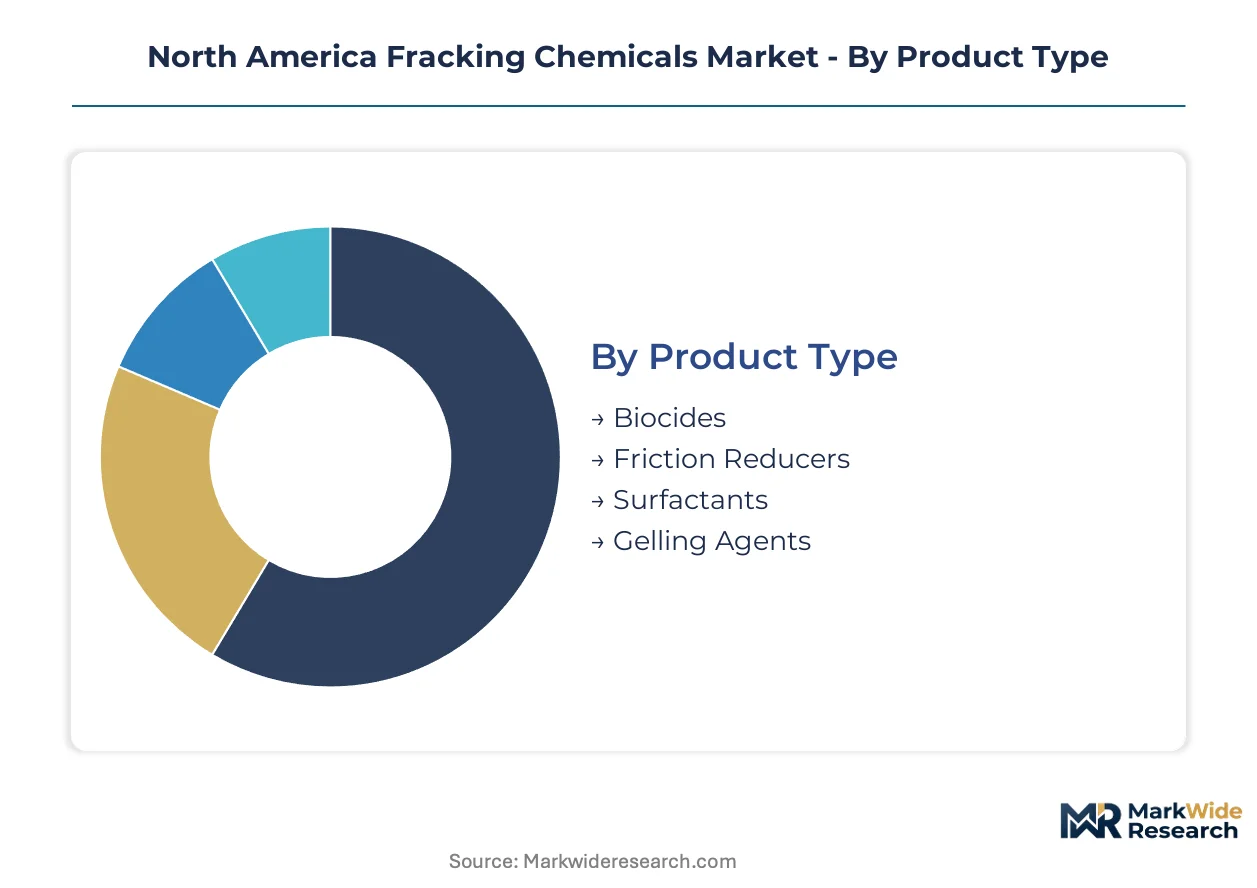
Fracking chemical procurement patterns diverge sharply across customer types and well geometries, with formulation requirements tightening most where lateral lengths extend and water recycling intensifies. Segment boundaries are blurring as integrated service providers bundle formerly discrete additive categories into single-source supply agreements.
Product Type:
Biocide packages face the most acute substitution pressure as EPA effluent rules and state discharge mandates force reformulation away from glutaraldehyde bases toward quaternary ammonium alternatives with narrower efficacy spectra.
- Friction Reducers:High-molecular-weight polyacrylamide polymers, delivered as dry powders or oil-based emulsions, slash pumping friction in high-rate slickwater designs. Demand concentrates in the Permian Basin's Delaware sub-basin, where 15,000-foot laterals and 80-plus stage completions impose shear-recovery specifications that commodity grades cannot satisfy. Acrylic acid feedstock volatility compresses margins for non-integrated producers during propylene derivative spikes.
- Gelling Agents:Synthetic polymer and guar-derived systems build viscosity for proppant suspension in crosslinked gel designs. Premium synthetic grades command sustained margin pools in deep Wolfcamp zones where bottom-hole static temperatures exceed 150 degrees Celsius and degrade conventional natural gum chemistry.
- Biocides:Broad-spectrum antimicrobial additives prevent sulfate-reducing bacteria proliferation in anoxic reservoir conditions and recycled water infrastructure. Glutaraldehyde alternatives struggle to match efficacy against biofilm formation in produced water handling systems.
- Surfactants:Non-ionic and anionic surface-active agents reduce interfacial tension for improved hydrocarbon recovery and cleanup. Biodegradable chemistries are gaining pre-qualification traction among Delaware Basin operators with centralized water recycling facilities facing tightened discharge timelines.
Friction reducers retain volume leadership; gelling agents hold the steepest expansion curve as high-temperature, high-pressure applications multiply.
End User:
Procurement authority is migrating fastest among entities lacking in-house formulation laboratories, with outsourcing economics reshaping vendor relationships across the cost tier spectrum.
- Service Companies:Pumping service providers now bundle chemical selection, logistics, and real-time blending into integrated service contracts. Halliburton and three other majors concentrate purchasing power through recurring offtake agreements that marginalize standalone distributors lacking technical field support capabilities.
- Independents:Small to mid-sized operators in the Midland sub-basin delegate additive procurement entirely to specialists rather than maintaining captive formulation labs. Liability-conscious independents pay premiums for OSHA Process Safety Management certified handling protocols bundled with chemical supply.
- Oil & Gas Operators:Majors and large independents with retained engineering capabilities specify proprietary formulations and maintain direct supplier relationships for critical additives. In-house rheology expertise constrains deployment velocity as petroleum engineering talent availability contracts across the Permian and Bakken.
- Energy Firms:Diversified energy companies with midstream and downstream integration pursue chemical supply security through backward integration into feedstock production or long-term offtake agreements with integrated chemical manufacturers.
Service companies capture procurement volume leadership; independents are climbing the fastest as outsourcing economics deepen.
Application:
Well geometry dictates additive loading intensity most directly, with lateral extension multiplying chemical consumption per wellbore while vertical drilling contracts as a share of total demand.
- Horizontal Drilling:Multi-stage completions in shale formations consume the majority of fracking chemical volumes, with 50 to 100 percent higher additive loading per wellbore than vertical equivalents. Delaware and Midland sub-basin programs drive specification escalation for shear-tolerant friction reducers and high-temperature gelling systems.
- Shale Gas Extraction:Dry gas and liquids-rich shale plays require tailored surfactant packages for flowback enhancement and clay stabilization. The Marcellus and Utica basins in the Appalachian region sustain demand for biocide-intensive formulations where produced water recycling infrastructure concentrates microbial contamination risk.
- Vertical Drilling:Conventional vertical completions retain niche demand for commodity-grade friction reducers and basic gelling agents in mature conventional fields. Chemical intensity per well remains substantially below horizontal equivalents, constraining supplier margin opportunity.
- Enhanced Oil Recovery:Chemical EOR applications including polymer flooding and surfactant-polymer drives represent a specialized demand pocket with distinct formulation requirements. Permian operators piloting tertiary recovery methods specify high-polymer-concentration systems with distinct rheology profiles from fracturing applications.
Horizontal drilling retains volume leadership; shale gas extraction is gaining share fastest as Appalachian infrastructure matures.
Distribution Channel:
Logistics configuration determines working capital requirements and technical service intensity, with direct relationships capturing the most sophisticated demand while distributor networks serve price-sensitive volume.
- Direct Sales:Manufacturer-to-operator relationships dominate premium additive categories requiring technical service support and real-time formulation adjustment. BASF and Dow Chemical leverage R&D campus proximity to major shale basins for specification development and customer co-engineering.
- Distributors:Regional chemical distributors serve cost-sensitive independents with standardized additive packages and consolidated procurement across multiple product categories. Midland-anchored supply nodes create single-point vulnerability for just-in-time delivery to multi-pad drilling programs.
- Online Sales:Digital procurement platforms capture commodity-grade additive demand from small operators with predictable, repetitive formulation requirements. Limited technical support capability constrains penetration in high-performance categories.
- Retailers:Limited retail presence serves marginal well workover and maintenance chemical demand through local supply houses. Volume concentration in major shale plays leaves peripheral geography underserved by dedicated distribution infrastructure.
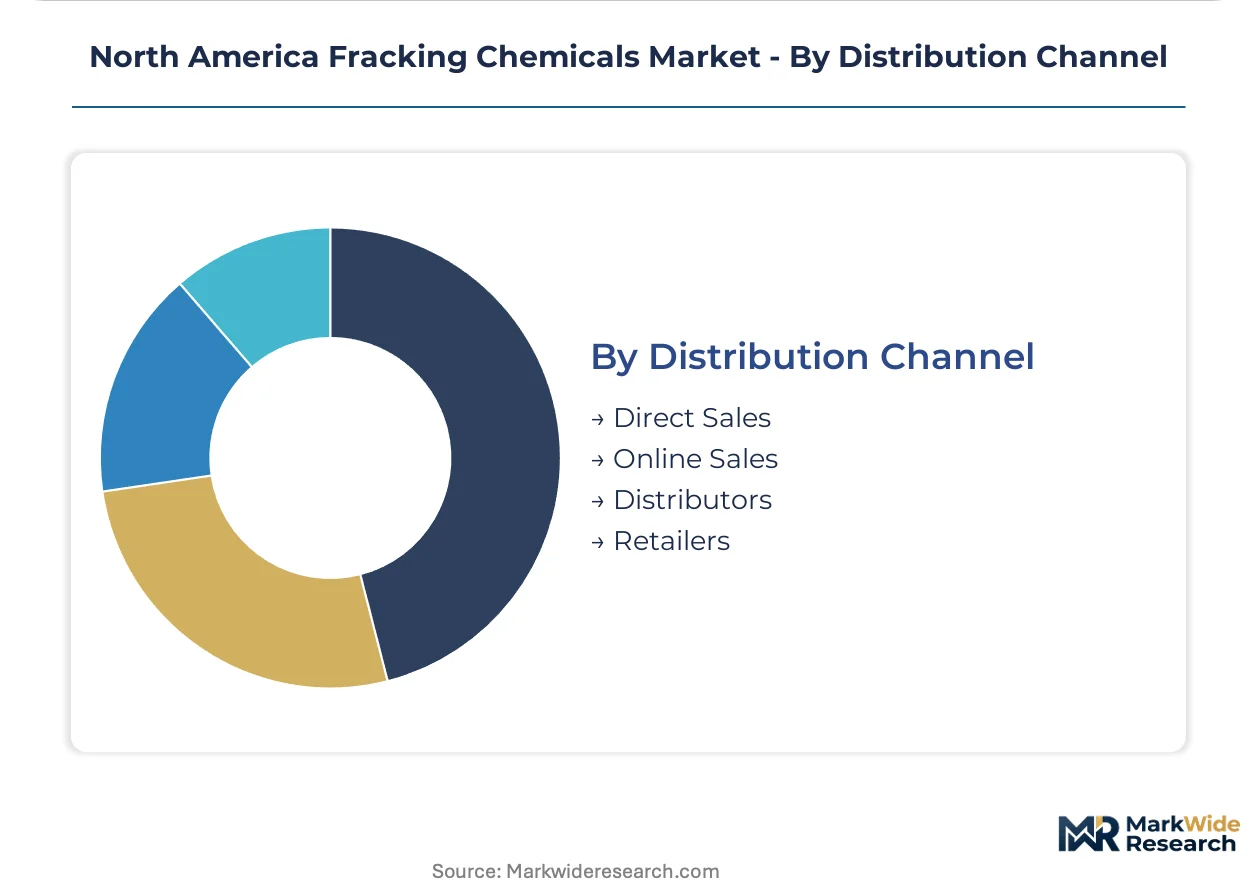
Direct sales retain volume leadership; distributor networks are expanding most quickly as procurement consolidation concentrates purchasing power among intermediaries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA underground injection control rules under the Safe Drinking Water Act anchor regulatory dynamics across the dominant United States shale basins, while Canadian provincial authorities and Mexican energy regulators impose parallel disclosure frameworks that shape cross-border chemical trade patterns.
United States
Permian Basin drilling intensity in Texas and New Mexico drives specialty chemical demand as 15,000-foot laterals multiply additive loading per stage. The Texas Railroad Commission mandates FracFocus disclosure thresholds that professionalize chemical sourcing. Midland-anchored supply clusters concentrate friction reducer production capacity for just-in-time delivery to multi-pad programs.
Canada
Montney and Duvernay shale operators in Alberta and British Columbia pursue longer lateral completions that strain conventional friction reducer shear tolerance. Health Canada and PMRA regulate biocide importation and environmental release under the Pest Control Products Act. Calgary-based service company headquarters coordinate chemical logistics across the Western Canadian Sedimentary Basin.
Mexico
Burgos Basin shale gas pilot programs generate nascent demand for imported friction reducer and gelling agent packages as national oil company drilling accelerates. The National Hydrocarbons Commission imposes chemical disclosure requirements modeled on US FracFocus protocols. Tampico and Reynosa logistics corridors handle cross-border chemical shipments from Texas supply nodes.
North America Fracking Chemicals Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the North America fracking chemicals market. The upper tier comprises diversified chemical manufacturers with captive feedstock positions and R&D campuses proximate to major shale basins. Specialist blenders and regional distributors occupy the lower tier, competing on logistics speed and pre-certified additive packages. Three strategic archetypes dominate: backward-integrated polymer producers, integrated oilfield service providers bundling chemicals with pumping operations, and independent formulation houses serving liability-conscious independents. Competitive moves concentrate on strategic partnerships for closed-loop blending systems and portfolio diversification into biodegradable surfactant chemistries ahead of tightened discharge standards.
Among integrated oilfield service providers, Halliburton Company exemplifies the bundling archetype that captures recurring offtake through combined chemical supply and pumping operations. BASF SE and Dow Chemical Company anchor the chemical manufacturer tier, representing backward-integrated positions into acrylic acid and amine feedstocks that secure cost advantages for friction reducer production. These three companies occupy positions that reflect the market's structural split between service-integrated and manufacturing-centric competitive vectors.
| Leading Market Players |
|---|
| Halliburton Company |
| BASF SE |
| Dow Chemical Company |
| Baker Hughes Incorporated |
| Solvay SA |
| CES Energy Solutions Corp |
| DuPont de Nemours Inc. |
| Schlumberger Limited |
| Ecolab Inc. |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements between Permian Basin operators and integrated chemical manufacturers lock in acrylic acid feedstock supply while freezing friction reducer pricing visibility across multi-year drilling programs. These contracts insulate buyers from propylene derivative volatility but expose suppliers to margin compression when input costs spike unexpectedly.
Pricing Analysis
Contract-based long-term offtake structures dominate friction reducer procurement, with three-tier pricing stratification across premium emulsion grades, standard dry powders, and economy bulk formulations. Price differentiation hinges on shear-recovery certification for 15,000-foot laterals and volume scale commitments from multi-pad operators. Cost compression in commodity friction reducers is intensifying because acrylic acid feedstock volatility compresses margins for non-integrated producers. Small independents in the Midland sub-basin exhibit highest price sensitivity, while majors drilling Delaware Basin deep Wolfcamp zones pay least attention to unit costs.
Supply Chain Analysis
Midland-anchored production clusters create single-point vulnerability for just-in-time chemical delivery to Texas and New Mexico drilling programs. Feedstock supply draws from Texas Gulf Coast propylene derivative production, Louisiana amine chemistry facilities, and Michigan polymer R&D campuses. Tariff exposure on Canadian guar imports for natural gelling agents compounds supply risk for cross-border formulation houses. Distribution runs through integrated service company logistics networks that bundle chemical supply with pumping operations, marginalizing standalone distributors lacking field technical support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America fracking chemicals market sits in early-stage cyclical recovery as Permian Basin drilling intensity rebounds from capital discipline lows and lateral completion lengths extend additive loading per wellbore.
For Market Incumbents: Shield margin pools in high-temperature gelling agents by deepening backward integration into captive amine chemistry production before propylene derivative volatility escalates. Fortify position against biodegradable surfactant substitution threats by pre-qualifying quaternary ammonium biocide alternatives ahead of EPA effluent rule finalization. Channel control through closed-loop blending system partnerships captures recurring offtake from liability-conscious independents outsourcing chemical logistics entirely. For New Entrants and Emerging Players: Technical field support gaps in the San Juan Basin's reactivated Mancos-Gallup oil window offer first-mover positioning before infrastructure buildout concentrates purchasing power among incumbent service companies. White-space targets include modular on-site blending units for real-time viscosity adjustment and certified handling protocol bundles for OSHA Process Safety Management compliance. The most penetrable segment remains small independents in peripheral basins lacking retained engineering capabilities. For Investors and Strategic Acquirers: Capital is best deployed toward backward-integrated polymer producers with captive acrylic acid positions and R&D campuses proximate to Permian and Bakken drilling activity. Long-term viability across the analysis window favors manufacturers with feedstock cost advantages and formulation expertise in high-temperature, high-pressure applications exceeding 150 degrees Celsius. The signal to watch as inflection indicator is Delaware Basin operator pre-qualification rates for biodegradable surfactant chemistries ahead of tightened discharge standards.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Acid | Captive propylene derivative supply secures friction reducer margin pools against feedstock volatility spikes. |
| Closed-Loop Blending System Deployment | On-site modular units reduce transportation exposure and enable real-time viscosity adjustment for Delaware Basin laterals. |
| Biodegradable Surfactant Pre-Qualification | Quaternary ammonium compound certification ahead of EPA effluent rules captures compliance-driven substitution demand. |
| High-Temperature Gelling Agent R&D Expansion | Synthetic polymer development for Wolfcamp zones exceeding 150 degrees Celsius commands sustained premium pricing. |
| OSHA Process Safety Management Certification | Certified handling protocol bundling captures recurring offtake from liability-conscious Midland sub-basin independents. |
Research Methodology
The analysis maps friction reducer, gelling agent, biocide, and surfactant sub-sectors, each validated through petroleum engineers at Permian and Bakken operators, procurement leads at pumping service companies, chemical plant managers in Texas and Louisiana, and distribution channel partners across the Western Canadian Sedimentary Basin. Primary interview insights combined with secondary validation from EPA underground injection control filings, Texas Railroad Commission FracFocus disclosures, SEC 10-K chemical segment reporting, and American Chemistry Council production data. Bottom-up well count and additive loading estimates triangulate against top-down chemical manufacturer revenue segmentation.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework models product type, end user procurement authority, well geometry application, and logistics configuration dimensions. CAGRs derive from stage count trajectories, lateral length extension curves, and additive concentration per foot assumptions. Industry-specific forecast inputs include Delaware Basin drilling permit filings and Permian water recycling infrastructure buildout rates.
Forecasts assume regulatory continuity in EPA underground injection control regimes and Texas Railroad Commission disclosure mandates; material policy shifts would require re-modeling biocide package economics and surfactant substitution timelines. Practitioners should keep alternative scenarios live as EPA effluent limitation guideline reconsideration and state-level groundwater protection statutes evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Cuttings Re-Injection Services Market
Oil & Gas
Kuwait Oilfield Services Market
Oil & Gas
Well Intervention Service Market
Oil & Gas
West Africa Oil and Gas Midstream Market
Oil & Gas
3D Printing in Oil and Gas Market
Oil & Gas
Oil and Gas Pipeline and Transportation Automation Market
Oil & Gas
GCC and North Africa Coiled Tubing Market
Oil & Gas
Global LNG Liquefaction Equipment Market
Oil & Gas
Expandable Liner Hanger System Market
Oil & Gas
Mobile Servicing Rig Market
Oil & Gas
Europe Oilfield Chemicals Market
Oil & Gas
Drilling Mud Desander and Desilter Market
Oil & Gas
Mineral Oil and Mineral Spirit Market
Oil & Gas
Oil and Gas Cloud Applications Market
Oil & Gas
Bunker Liners Market
Oil & Gas
Vacuum Gas Oil Market