
 Door Phone Market | 2026-2036
Door Phone Market Size, Share, and Industry Trends Forecast 2026-2036
Door Phone Market Intelligence
Commercial complex deployment is restructuring the door phone procurement landscape as facility operators prioritize networked security ecosystems over standalone analog units. Aiphone dominates Japan's high-rise intercom segment through stringent JIS standards compliance. Ubiquiti leverages cloud-managed architecture to compete in North American SMB installations. Godrej anchors India's price-sensitive residential market with localized manufacturing scale.
A door phone constitutes an entry-point communication device integrating audio, video, or dual-modal transmission for visitor verification and access control, typically operating across two-wire analog, IP/Ethernet, or wireless RF protocols with power-over-Ethernet capability enabling single-cable installation. IP-based systems capture expanding margin pools as property managers demand remote mobile access and building management system integration. Video transmission technology leads technology segmentation due to facial recognition integration and package delivery verification needs. Wired infrastructure sustains share in legacy building retrofits where wireless signal penetration faces structural constraints.
FCC Part 15 governs wireless door phone RF emissions in the United States, while CE marking and GDPR constrain European product design for data privacy and electromagnetic compatibility. China's GB standards and network access licenses from MIIT shape domestic manufacturing compliance for IP-connected units. Stakeholders must monitor evolving cybersecurity mandates for networked entry systems as regulatory bodies tighten firmware update requirements and encryption standards.
Market Dynamics
IP protocol migration is compressing analog door phone margins as property managers demand mobile-native access control and building management system interoperability across multi-tenant installations.
Growth Catalysts
- Smart building infrastructure mandates:China's GB standards for intelligent residential construction require video intercom integration in new high-rise developments, accelerating IP unit deployment.
- GDPR-driven security upgrades:European property operators replace legacy systems to meet data encryption and firmware audit requirements for visitor biometric capture.
- Package delivery verification:E-commerce logistics volume is rewriting entry-point communication priorities, with video door phones becoming essential for contactless handoff confirmation in Germany and South Korea.
Market Restraints
- Copper and semiconductor input volatility:Two-wire analog system manufacturing faces margin pressure from fluctuating commodity costs and chip allocation constraints.
- Wireless signal penetration limits:Reinforced concrete and metal framing in legacy high-rises in Japan and France block RF transmission, forcing expensive wired retrofits.
- CE marking timeline friction:Electromagnetic compatibility certification delays product launches by 4-8 months for IP-connected units seeking European market entry.
Strategic Opportunities
- India's affordable housing expansion:Government-subsidized residential construction creates volume demand for cost-optimized audio-visual entry systems with localized manufacturing scale.
- Healthcare facility access control:Hospital and aged-care complexes in Australia require HIPAA-aligned visitor management with audit trails, opening specialized vertical demand.
- PoE convergence with LED lighting infrastructure:Single-cable installation combining power-over-Ethernet door phones with smart building lighting networks reduces retrofit labor costs.
Industry Challenges
- Cybersecurity firmware maintenance:Network-connected units require continuous patch cycles that strain smaller OEM engineering resources and complicate long-term service contracts.
- Legacy analog integration complexity:Hybrid system deployments in renovated commercial buildings demand protocol bridges that increase installation cost and failure points.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Door Phone Market |
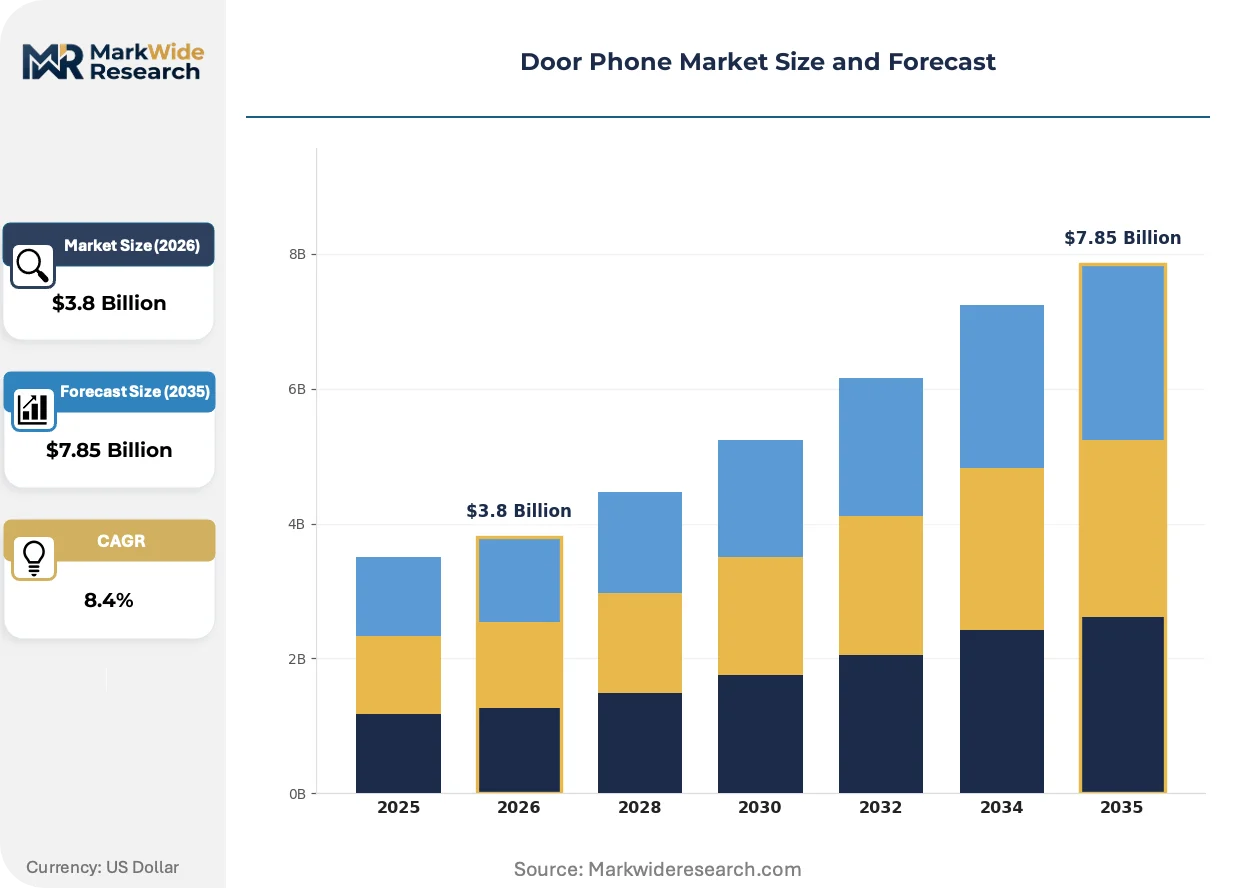
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.85 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wired, Wireless, IP-Based, Video Door Phones, Analog Technology: Voice Recognition, Audio Communication, Video Transmission, Network Integration, Remote Access Application: Residential Buildings, Commercial Complexes, Educational Institutions, Government Buildings, Hospitality Venues End User: Property Managers, Security Firms, Facility Operators, Maintenance Providers, Homeowners |
| Companies Covered | DNAKE, Ubiquiti, Akuvox, 2N, Verkada, Godrej, Aiphone, XTU, One Touch, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Door Phone Market Strategic Shifts & Innovations
Edge AI processing is eliminating cloud dependency for facial recognition, while regulatory fragmentation forces multi-certification strategies and buyer procurement consolidates around integrated security platform vendors.
On-device neural network inference is rewriting door phone architecture by enabling real-time visitor identification without latency-prone cloud roundtrips. Multi-tenant residential developers in South Korea specify NPU-embedded chipsets for GDPR-compliant local processing. This compression of compute to the edge is reducing bandwidth costs and enabling offline operation during network outages.
CE marking's expanded electromagnetic compatibility testing under RED 2014/53/EU is forcing hardware redesigns for IP units with Wi-Fi or cellular backhaul. Manufacturers serving France and Germany must validate coexistence with 5G C-band and LoRa networks. The certification burden falls heaviest on mid-tier suppliers lacking in-house EMC laboratories, consolidating procurement toward vertically integrated players.
Facility management outsourcing is consolidating door phone procurement through integrated security platform contracts rather than standalone hardware purchases. German and Dutch commercial real estate investment trusts now specify intercom functionality as a module within broader access control RFPs. This bundling compresses vendor margins while privileging suppliers with API-ready building management system integration.
Door Phone Market Segmentation
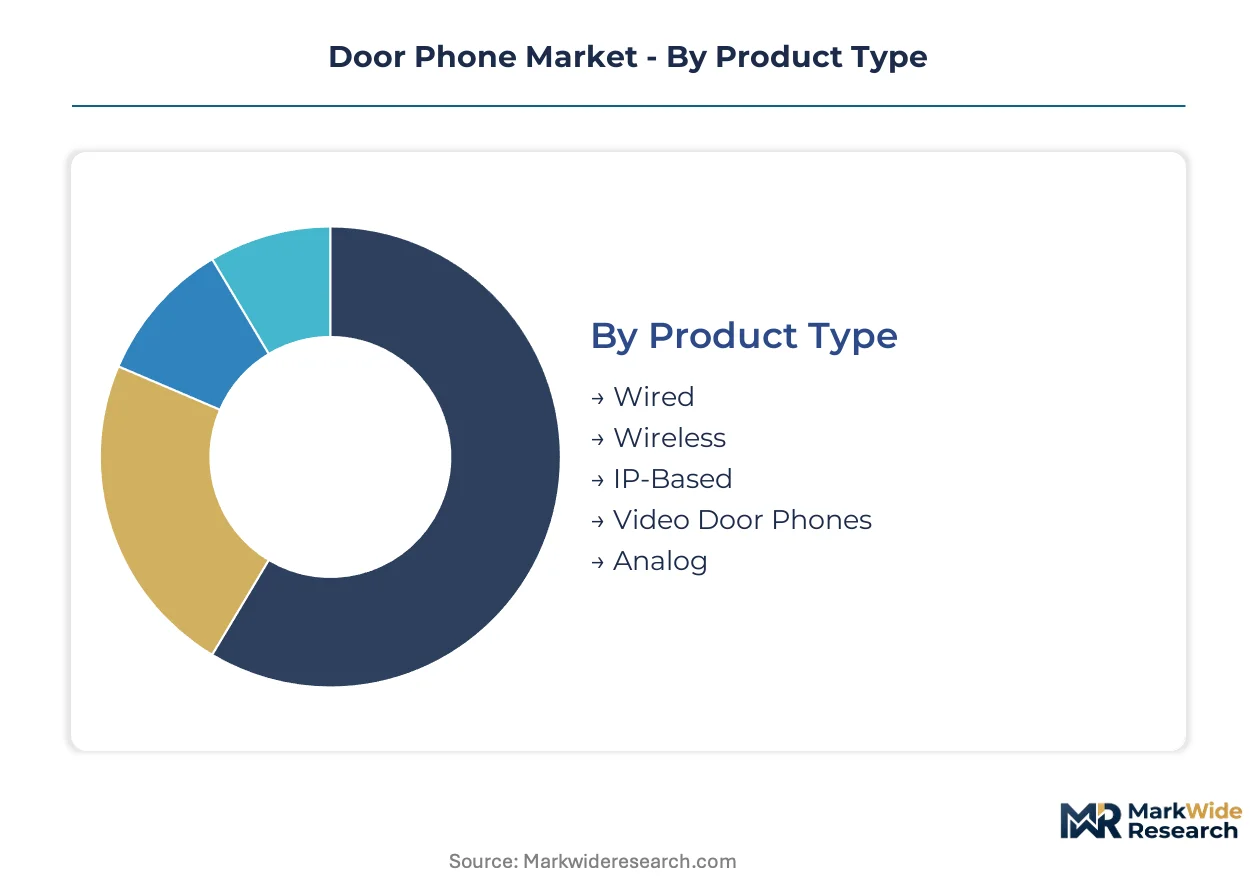
Door phone procurement patterns diverge sharply across installation environments, power infrastructure, and buyer sophistication. Segmentation reveals where margin pools concentrate and which technology transitions are compressing legacy revenue streams.
Product Type:
Supply concentration for chipsets and PoE components favors manufacturers with scale in IP and video assemblies over analog specialists.
- IP-Based:Ethernet-powered units with single-cable installation dominate new commercial construction in China, South Korea, and Germany. Building management system integration and mobile-native access control drive specification in multi-tenant developments.
- Video Door Phones:Camera-integrated systems with facial recognition capability capture expanding margin pools as e-commerce logistics volume rewrites entry-point priorities for package verification in Germany and South Korea.
- Wired:Two-wire analog infrastructure sustains share in legacy building retrofits where structural constraints block wireless signal penetration.
- Wireless:RF-based units serve residential applications with flexible installation requirements, though reinforced concrete limits deployment in Japan's high-rise stock.
- Analog:Legacy two-wire systems face margin compression as property managers migrate toward networked security ecosystems with remote management capability.
Today's leader: IP-Based. Tomorrow's challenger: Video Door Phones.
Technology:
Cost tier stratification separates premium edge-AI deployments from commodity audio installations.
- Video Transmission:Camera-enabled systems with real-time streaming and recording functionality lead technology segmentation. Facial recognition integration and package delivery verification requirements concentrate demand in commercial complexes and residential high-rises.
- Remote Access:Cloud-connected mobile applications enabling off-site visitor verification and door release command expanding most quickly. GDPR-compliant local processing with on-device neural networks displaces latency-prone cloud roundtrips in European deployments.
- Voice Recognition:Speaker-dependent authentication systems serve specialized access control scenarios in government and healthcare facilities.
- Audio Communication:Basic two-way voice intercom constitutes the lowest cost tier, dominant in price-sensitive residential retrofits.
- Network Integration:API-ready connectivity with building management systems and access control platforms increasingly specified in commercial real estate investment trust procurement.
Video Transmission commands current revenue. Remote Access gains specification fastest.
Application:
Volume concentration in residential automation contrasts with margin concentration in specialized commercial deployments.
- Commercial Complexes:Multi-tenant office and retail developments drive networked security ecosystem procurement. Facility operators prioritize building management system interoperability and centralized visitor audit trails over standalone hardware.
- Residential Buildings:High-rise apartment construction in China and India generates volume demand for cost-optimized audio-visual entry systems. Government-subsidized affordable housing programs in India create localized manufacturing scale opportunities.
- Educational Institutions:Campus-wide access control with emergency lockdown capability shapes specification for centralized intercom networks.
- Government Buildings:Security-cleared visitor management with biometric capture and audit compliance drives premium-tier procurement.
- Hospitality Venues:Guest experience integration with property management systems and concierge services differentiates supplier selection.
Commercial Complexes extract highest per-unit value. Residential Buildings deliver volume scale.
End User:
Customer type determines procurement channel and service contract structure.
- Property Managers:Multi-asset portfolio operators consolidate door phone procurement through integrated security platform contracts rather than standalone purchases. API-ready building management system integration privileges vertically integrated suppliers.
- Security Firms:Installation and monitoring service providers specify equipment with remote diagnostics capability to reduce truck-roll costs and enable predictive maintenance revenue streams.
- Facility Operators:In-house technical teams prioritize firmware update automation and cybersecurity patch management to reduce engineering resource strain.
- Maintenance Providers:Service contract specialists favor modular designs with field-replaceable components to minimize inventory complexity.
- Homeowners:Retail channel purchasers prioritize mobile application usability and DIY installation compatibility over enterprise-grade integration features.
Property Managers control enterprise specification. Homeowners drive consumer channel volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting production footprints as manufacturers seek jurisdictions with streamlined electromagnetic compatibility certification and lower compliance costs for IP-connected entry systems. China's MIIT network access licenses and India's localized manufacturing incentives are attracting assembly migration from European markets burdened by extended CE marking timelines.
China
Smart building infrastructure mandates under GB standards for intelligent residential construction are accelerating IP-based video door phone deployment in new high-rise developments. MIIT network access licenses constrain domestic manufacturing compliance for connected units, favoring established suppliers with regulatory navigation expertise. Shenzhen and Hangzhou industrial clusters concentrate chipset sourcing and final assembly for export-oriented production.
Germany
GDPR-driven security upgrades are compelling property operators to replace legacy systems with data-encryption-compliant visitor management infrastructure. CE marking requirements under RED 2014/53/EU enforce electromagnetic compatibility validation for Wi-Fi and cellular backhaul units, extending product launch timelines. Munich and Stuttgart engineering centers specialize in building management system integration for commercial real estate investment trusts.
United States
FCC Part 15 RF emissions governance shapes wireless door phone design for residential and SMB installations across multi-tenant developments. Cybersecurity mandates from CISA and state-level privacy regulations are tightening firmware update requirements for networked entry systems. Silicon Valley cloud-managed architecture providers compete with traditional security integrators in the North American market.
India
Government-subsidized affordable housing programs under the Pradhan Mantri Awas Yojana are generating volume demand for cost-optimized audio-visual entry systems. BIS certification requirements and PLI scheme incentives favor localized manufacturing scale over import-dependent supply chains. Maharashtra and Gujarat industrial corridors anchor assembly operations serving price-sensitive residential retrofit markets.
South Korea
Multi-tenant residential developers specify NPU-embedded chipsets for GDPR-compliant local facial recognition processing without cloud dependency. MFDS and national cybersecurity frameworks enforce encryption standards for biometric visitor capture systems. Seoul Capital Area technology clusters drive edge-AI integration in premium video intercom specifications for smart apartment complexes.
Door Phone Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with integrated security platform vendors consolidating procurement influence in commercial real estate while regional assemblers retain price-sensitive residential volume. The vendor base organizes into three tiers: vertically integrated players with in-house EMC laboratories, mid-scale specialists leveraging cloud-managed architectures, and regional fabricators dependent on localized manufacturing scale. Dominant competitive moves include API-ready building management system integration partnerships and backward integration into PoE component sourcing to defend margin position against commodity pressure.
Among Asia-Pacific headquartered suppliers, DNAKE, Akuvox, and Aiphone occupy distinct archetype positions within the competitive structure. DNAKE exemplifies the vertically integrated tier with regulatory navigation capabilities across multiple certification jurisdictions. Akuvox represents the cloud-native specialist segment targeting multi-tenant developments with mobile-native access control specifications. Aiphone anchors the premium-tier position in high-rise intercom markets where stringent JIS standards compliance creates certification barriers for non-domestic competitors.
| Leading Market Players |
|---|
| DNAKE |
| Ubiquiti |
| Akuvox |
| 2N |
| Verkada |
| Godrej |
| Aiphone |
| XTU |
| One Touch |
| Others |
Cost & Logistics Intelligence
Certification-grade bifurcation between CE-marked IP units and uncertified analog alternatives manifests in divergent margin structures and sourcing strategies across European and Asian supply bases. Premium-tier vendors absorb electromagnetic compatibility testing costs through captive laboratory investments, while commodity assemblers in India and China bypass European compliance to serve price-sensitive domestic retrofit markets with simplified two-wire architectures.
Pricing Analysis
Distributor margins in the 15-25% range separate factory-gate pricing from end-user project costs across commercial security integrators and residential electrical wholesalers. Three-tier pricing structure across premium, standard, and economy levels reflects chipset performance tiers, with NPU-embedded edge-AI units commanding substantial premiums over basic audio intercoms. Pricing pressure stems from semiconductor allocation constraints squeezing analog system manufacturers without volume leverage. Residential homeowners in India's affordable housing segment exhibit highest price sensitivity, while German commercial real estate investment trusts prioritize total cost of ownership over unit acquisition cost.
Supply Chain Analysis
Dual-sourcing requirements from European systems integrators mandate multi-supplier qualification for PoE chipsets and camera modules, fragmenting procurement across Taiwan, South Korea, and Chinese component vendors. Final assembly concentrates in Shenzhen, Hangzhou, and Dongguan industrial clusters feeding export markets, with Maharashtra and Gujarat corridors serving India's localized production mandates. Copper wire and CMOS image sensors constitute critical input dependencies. Single-source vulnerability in advanced neural processing units creates exposure for edge-AI product lines. Distribution runs through security integrators, electrical wholesalers, and direct OEM relationships with multi-tenant developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Door phone procurement has entered a late-cycle quality phase as facility managers replace standalone hardware with building management system-integrated platforms, privileging vendors with API-ready architectures and firmware maintenance capabilities over commodity assemblers.
For Market Incumbents: Anticipate margin compression from cloud-native entrants by deepening backward integration into PoE component sourcing and establishing captive EMC laboratories to compress CE marking timelines. Certification barriers under RED 2014/53/EU represent the critical defensive lever against mid-tier competitors lacking in-house electromagnetic compatibility validation infrastructure. For New Entrants and Emerging Players: Enter via India's government-subsidized affordable housing vertical, where localized manufacturing scale under PLI scheme incentives creates penetrable white space against import-dependent incumbents. Healthcare facility access control in Australia offers secondary entry opportunity through HIPAA-aligned visitor management specialization. Cloud-managed architecture with mobile-native access control provides differentiated go-to-market positioning against legacy analog integrators. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier suppliers lack capital to fund multi-certification strategies across CE marking, FCC Part 15, and MIIT network access regimes. Long-term viability favors vertically integrated players with regulatory navigation expertise spanning European, North American, and Asian compliance frameworks. Acquisition target archetype: regional specialists with established EMC laboratory infrastructure and building management system integration capabilities. The signal to watch is facility management outsourcing velocity, as integrated security platform contracts accelerate procurement consolidation toward bundled solution vendors.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-AI Chipset Integration | NPU-embedded architectures enable GDPR-compliant local facial recognition without cloud dependency in European deployments. |
| Building Management System API Development | Standardized connectivity protocols capture procurement preference from German and Dutch commercial real estate investment trusts. |
| CE Marking Captive Laboratory Investment | In-house electromagnetic compatibility validation compresses product launch timelines by 4-8 months for IP-connected units. |
| PoE Component Backward Integration | Upstream control over power-over-Ethernet chipsets defends margin position against commodity cost volatility. |
| India Localized Manufacturing Scale | Maharashtra and Gujarat assembly operations qualify for PLI scheme incentives serving price-sensitive residential retrofit demand. |
Research Approach
Coverage spans China, Germany, United States, India, and South Korea, with primary inputs from each market's regulatory and commercial stakeholders. The analytical approach combines structured interviews with multi-tenant developers, security systems integrators, facility management outsourcing firms, and building management system platform vendors with secondary validation from MIIT network access filings, FCC Part 15 equipment authorization databases, CE marking notifications under RED 2014/53/EU, and BIS certification records. Bottom-up unit shipment estimates triangulate against top-down construction spending allocations for intelligent residential and commercial building automation.
Rate-of-change decomposition separates volume growth from value migration across the projection horizon, modeling technology transition from analog to IP-based architectures, product type evolution from audio-only to video-integrated systems, and application shift from standalone residential installations to networked commercial security ecosystems. Segmentation dimensions include connectivity protocol, video capability tier, installation environment, and buyer sophistication level. CAGRs derive from regression analysis against construction permit data, smart building infrastructure mandate implementation timelines, and e-commerce logistics volume trajectories influencing package verification demand.
Inputs from regulatory filings, trade databases, and construction spending surveys were available through the study window; gaps in real-time OEM inventory positions and project-level procurement decisions introduce uncertainty bands around near-term shipment estimates. Forecasts reflect assumptions regarding GB standards enforcement continuity in China, GDPR audit intensity in Europe, and PLI scheme incentive stability in India. Deviation in semiconductor allocation priorities or cybersecurity firmware mandate acceleration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Cloud Security Software Market
Security Software
POS Security Market
Security Software
Patch and Remediation Software Market
Security Software
E Passport Market
Security Software
AI in Security Market
Security Software
Digital Credential Management Software Market
Security Software
Europe Enterprise Firewall Market
Security Software
Security Software for Consumers Market
Security Software
Global Automatic Number Plate Recognition (ANPR) System Market
Security Software
SSL Inspection Solution Market
Security Software
Privacy Management Software Market
Security Software
Public Key Infrastructure (PKI) Market
Security Software
Anti-Fraud Management System Market
Security Software
Banking Encryption Software Market
Security Software
Internet Filter Software Market
Security Software
Web Content Filtering Market